Power and Control Cable Market - Strategic Insights and Forecasts (2026-2031)
Power and Control Cable Market Share, Size & Growth By Type (Power Cable, Control Cable), Material (Copper, Aluminum, Others), Voltage (Low Voltage, Medium Voltage, High Voltage), End User (Residential, Commercial, Industrial), and Geography
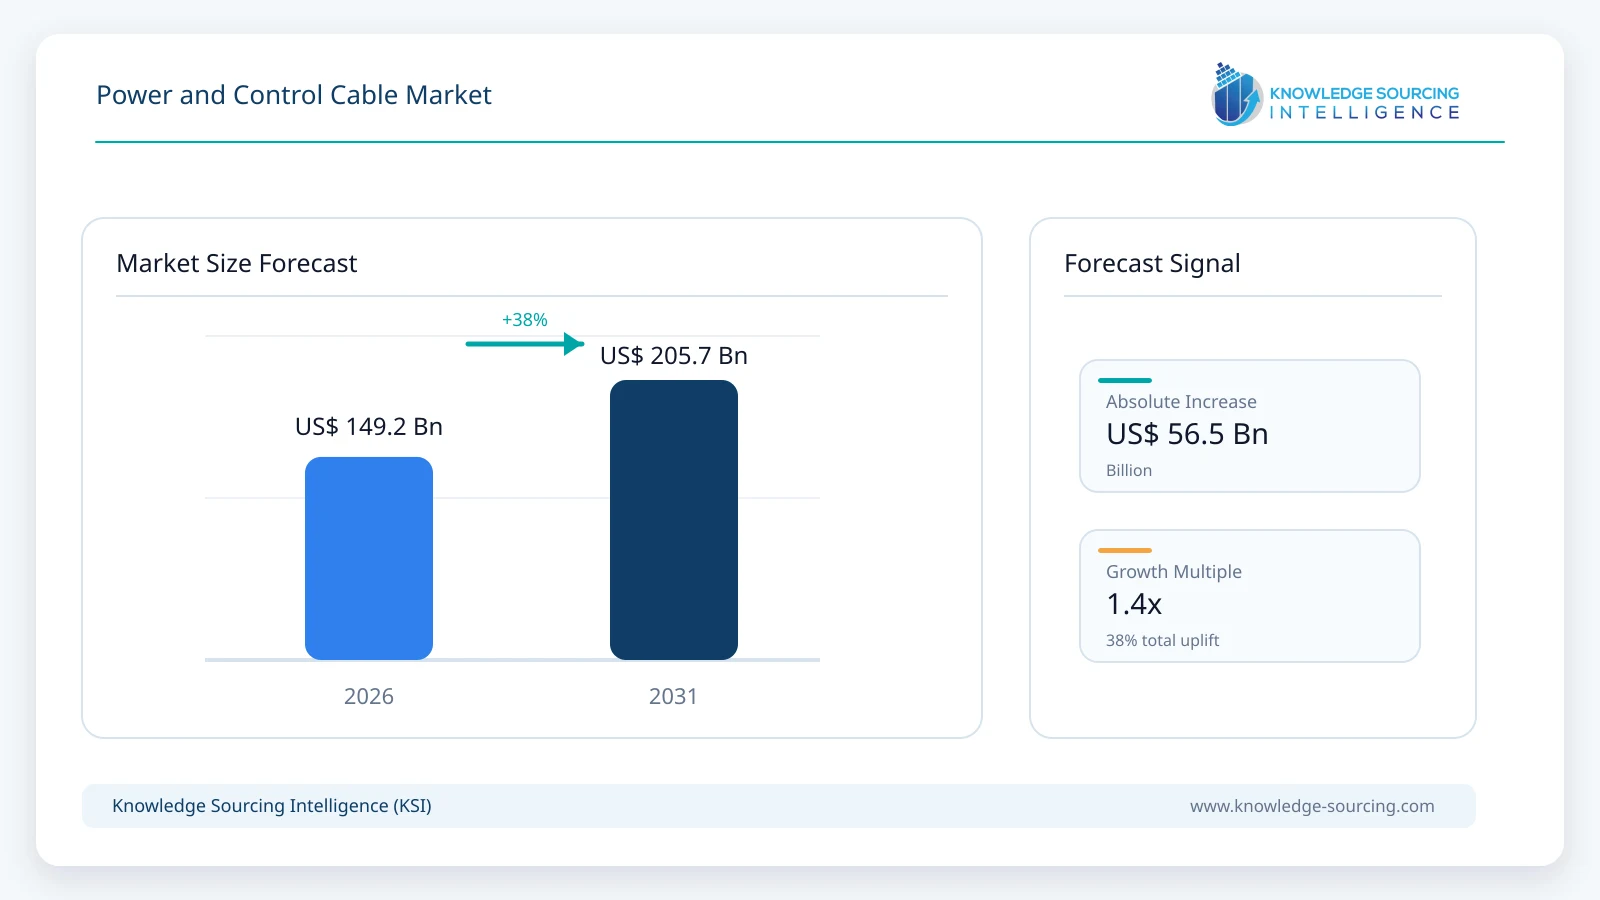
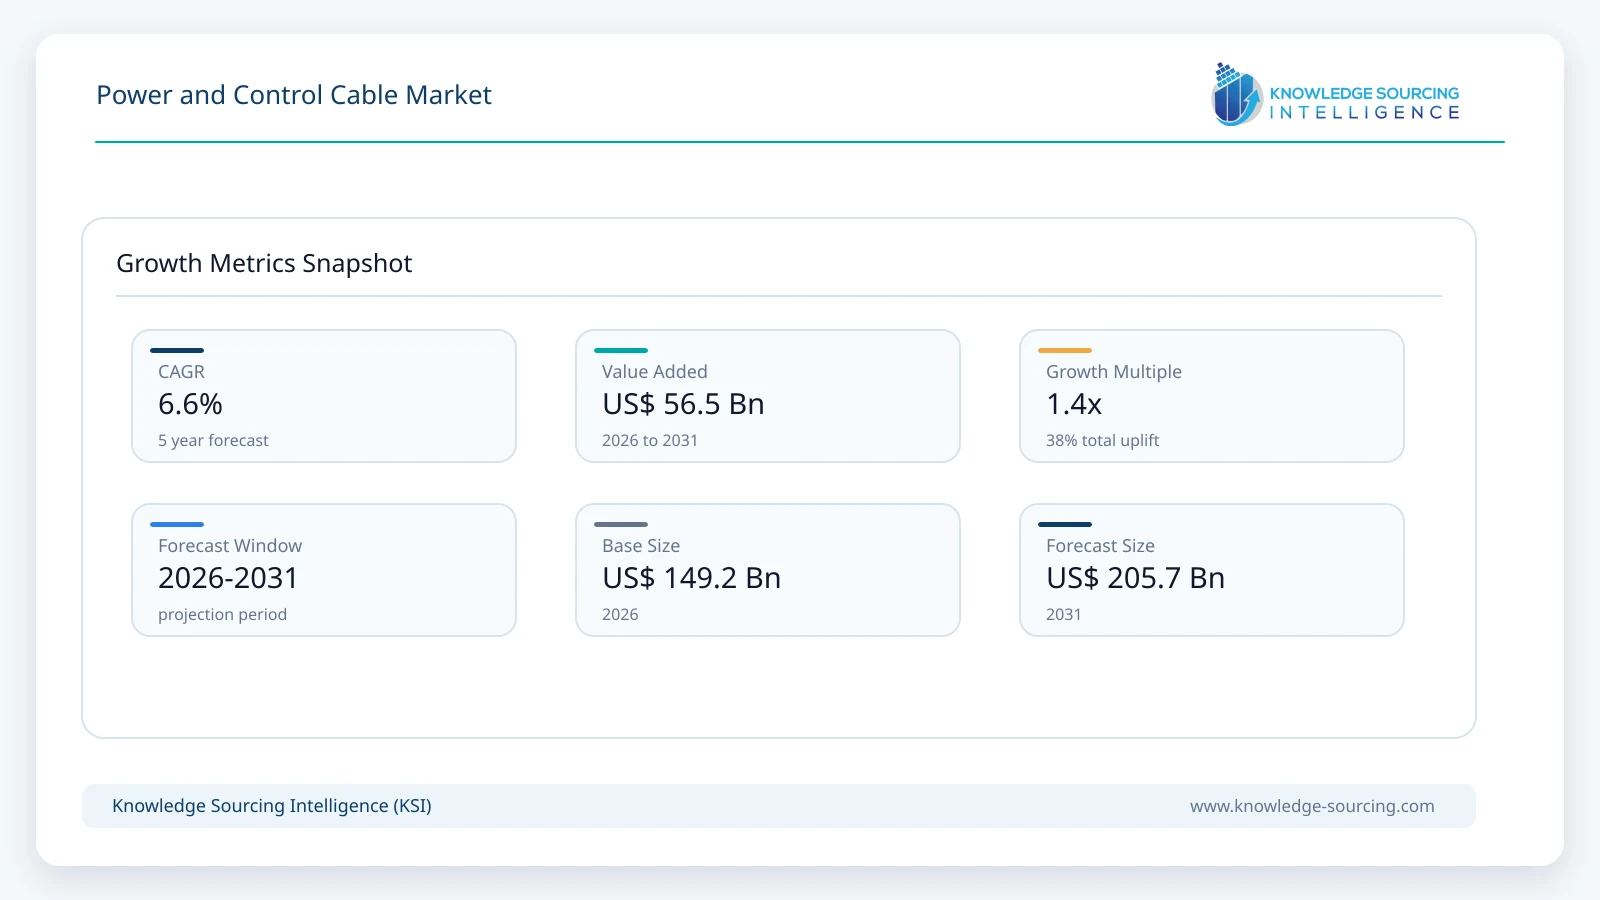
The global power and control cable market is forecast to grow from USD 149.20 billion in 2026 to USD 205.70 billion in 2031, representing a CAGR of 6.63% during the forecast period.
Highlights:
1
Power cables are estimated to account for approximately 82.0% of global power and control cable revenue in 2026, reflecting their use across building wiring, distribution networks, industrial facilities and transmission infrastructure.
2
Copper-based cables are estimated to represent approximately 63.0% of 2026 market revenue because of their conductivity, reliability and broad use across building, industrial and grid applications.
3
Low-voltage cables are estimated to account for approximately 50.0% of the market in 2026, supported by extensive use in buildings, industrial distribution, data centers, commercial infrastructure and equipment interconnections.
4
Industrial end users are estimated to contribute approximately 43.0% of 2026 market revenue, reflecting demand from manufacturing, process industries, data centers, utilities, mining, oil and gas and infrastructure projects.
5
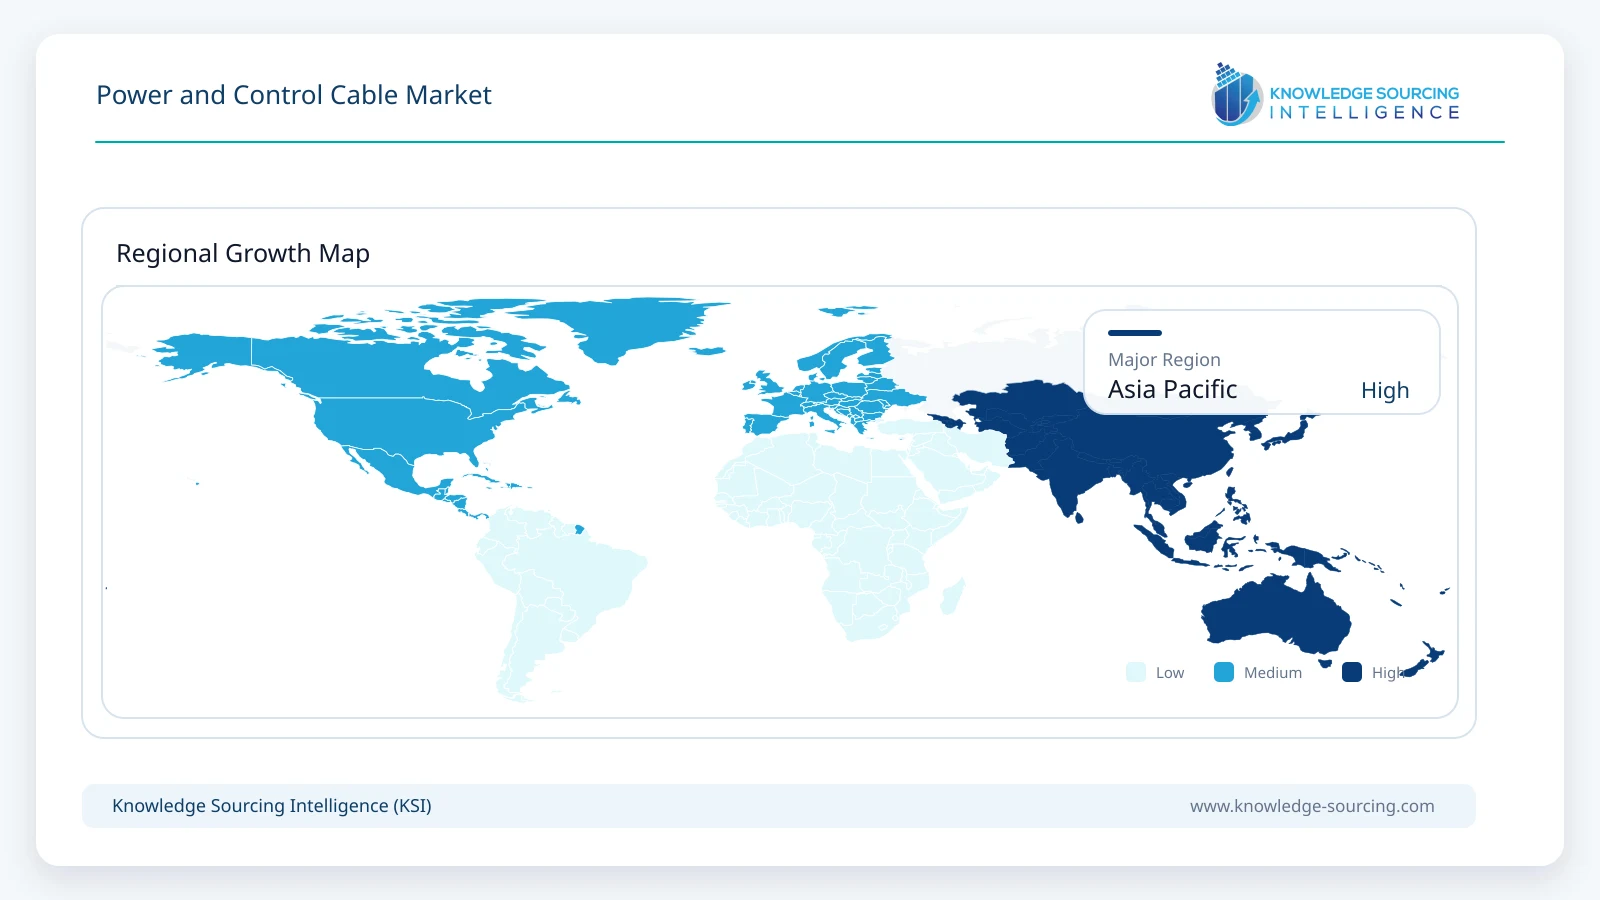
Asia Pacific is estimated to account for approximately 46.0% of global market revenue in 2026, supported by large construction, manufacturing, electrification and grid-investment programs across China, India, Southeast Asia and other regional economies.
6
Grid expansion, renewable integration, data-center power demand and electrification are increasing cable requirements while copper and aluminum price volatility is making conductor selection, procurement timing and material efficiency more important.
Market Overview
Power and control cables are fundamental electrical infrastructure products used to transmit electricity and control signals across buildings, industrial facilities, utility networks, renewable-energy projects, transport systems, data centers and other critical assets. The market spans low-voltage building and industrial cables, medium-voltage distribution products, high-voltage transmission systems and specialized control cables used for automation, instrumentation and equipment operation.
Demand is being reshaped by the global acceleration of electricity investment. The International Energy Agency estimates that annual grid investment needs to rise materially through 2030 as renewable generation, storage, electric vehicles, heat pumps and large electricity loads such as data centers increase pressure on existing transmission and distribution systems. This creates demand not only for new cable routes but also for reconductoring, distribution upgrades, interconnections and higher-capacity cable systems.
Cable demand is also becoming more technically differentiated. Grid projects require higher-voltage AC and DC systems, renewable projects need specialized export and inter-array cables, data centers require high-density power distribution, and industrial automation requires flexible and durable control cables. In buildings and public infrastructure, fire performance, low-smoke zero-halogen materials and certification requirements are becoming more important procurement criteria.
Supplier financial performance provides evidence of the current investment cycle. Prysmian reported EUR 19.65 billion in 2025 revenue and its Power Grid segment grew strongly in the first quarter of 2026. NKT has expanded medium-voltage manufacturing capacity and continues to secure large high-voltage project awards, while Nexans, Sumitomo Electric, LS Cable & System and other leading producers are investing in transmission and distribution capabilities.
Raw material economics remain central to the market. Copper and aluminum account for a substantial share of cable manufacturing cost, and fluctuations in metal prices can materially affect reported revenue and procurement decisions. Manufacturers therefore compete on conductor optimization, vertical integration, long-term metal sourcing, product engineering and the ability to meet project-specific safety and performance requirements.
Power and Control Cable Market Trends
Grid Expansion Moves Cable Supply Chains into Strategic Infrastructure
Electricity networks are becoming one of the most important sources of cable demand. The IEA estimates that current grid spending of roughly USD 400 billion per year needs to rise substantially by 2030, and 2026 investment is expected to approach USD 550 billion. New transmission lines, distribution upgrades and interconnectors translate directly into demand for conductors, underground cables, submarine cables, accessories and related installation capacity.
The result is a market in which manufacturing capacity and project execution are becoming strategic constraints. NKT completed an expansion of medium-voltage production in Denmark in 2026, while major producers are adding high-voltage and submarine cable capacity. Long project lead times and large order backlogs are supporting investment in new factories, cable-laying assets and supply agreements for copper and aluminum.
Data Centers Increase Demand for High-Density Power Distribution
Rapid data-center construction is creating demand for power cables across utility interconnections, substations, campus distribution, backup generation, building systems and rack-level infrastructure. The load density of AI-oriented facilities makes conductor capacity, fire performance and system reliability particularly important.
Prysmian reported growth in its Industrial & Construction business in North America during the first quarter of 2026, with data centers identified as a contributor. The company also announced the use of low-carbon aluminum cable in an Amazon data-center project, illustrating how material innovation and sustainability requirements are entering procurement decisions for high-load digital infrastructure.
Material Efficiency and Lower-Carbon Conductors Gain Importance
Copper remains the dominant conductor for many applications, but aluminum is increasingly attractive where weight and cost are important. Higher metal prices are encouraging cable manufacturers and customers to optimize conductor cross-sections, evaluate aluminum alternatives and use long-term supply arrangements to reduce price risk.
Sustainability is adding another dimension. Cable producers are increasing recycled content, reducing manufacturing emissions and developing lower-carbon conductor options. Procurement decisions for large infrastructure projects increasingly consider embedded carbon alongside electrical performance, safety and lifecycle reliability.
Market Segmentation by Type
Power Cable
Power cables are estimated at approximately USD 122.34 billion in 2026. The segment includes products used across low-, medium- and high-voltage electricity transmission and distribution, building power systems, industrial facilities, renewable generation, data centers and infrastructure projects.
The size of the segment reflects the breadth of applications. Low-voltage building and industrial cables represent high volumes, while medium- and high-voltage products contribute significant value through grid expansion and technically complex projects. Transmission systems also require specialized accessories, joints, terminations and installation capabilities that increase project value.
Power-cable demand is being reinforced by both new capacity and modernization. Advanced economies are upgrading aging networks, while emerging markets continue to add new lines, substations, industrial sites and buildings. Renewable-energy integration and data-center power requirements add further demand for cables capable of operating at higher loads and in challenging environments.
Market Segmentation by Material
Copper
Copper-based power and control cables are estimated at approximately USD 94.00 billion in 2026. Copper remains widely used because of its high conductivity, compact conductor size, mechanical reliability and broad acceptance across electrical codes and industrial specifications.
The material is particularly important in building wiring, industrial equipment, control systems, data centers and applications where space constraints or high current density make conductor efficiency valuable. Copper also remains important in many medium-voltage and specialized cable designs.
Price volatility is the principal commercial challenge. Manufacturers increasingly use hedging, metal-adjustment clauses and long-term procurement arrangements to manage exposure. High copper prices also create opportunities for aluminum in selected power applications, but substitution depends on installation space, connection design, safety standards and lifecycle requirements.
Market Segmentation by Voltage
Low Voltage
Low-voltage cables are estimated at approximately USD 74.60 billion in 2026. The segment serves buildings, commercial facilities, factories, data centers, machinery, transportation systems and local distribution applications, creating a very broad demand base.
Construction and industrial activity remain important demand drivers, but the segment is also benefiting from electrification inside existing facilities. EV charging, distributed solar, battery systems, automation, HVAC upgrades and data-center expansion all require additional low-voltage distribution and control infrastructure.
Safety requirements are becoming increasingly important. Fire-resistant, low-smoke and halogen-free constructions are gaining relevance in public buildings, transport infrastructure, data centers and high-occupancy facilities. This supports higher-value products and raises compliance requirements for manufacturers.
Market Segmentation by End User
Industrial
Industrial end users are estimated at approximately USD 64.16 billion in 2026. The segment includes manufacturing, oil and gas, mining, chemicals, data centers, utilities, transportation infrastructure and other facilities requiring both electrical power distribution and control connectivity.
Automation increases the importance of control cables that must carry signals reliably under vibration, repetitive motion, temperature variation and exposure to oils or chemicals. At the same time, industrial expansion requires low- and medium-voltage power cables for plant distribution, motors, switchgear, substations and process equipment.
Data centers are becoming an increasingly important industrial-like load category because of their high power density and reliability requirements. New facilities create cable demand from the utility connection through campus distribution and internal building systems, while backup power and cooling infrastructure add further electrical content.
Market Drivers
Expansion and Modernization of Electricity Grids
Electricity demand growth and renewable integration require utilities to expand transmission and distribution capacity. Grid bottlenecks are already delaying generation, storage and large-load projects in several regions, increasing policy pressure to accelerate network investment.
New lines, undergrounding, reconductoring and distribution upgrades all create cable demand. The IEA expects grid investment to rise substantially through 2030, supporting long-term procurement pipelines for low-, medium- and high-voltage cable systems.
Renewable Energy Integration and Interconnection
Solar, wind and storage projects require internal collection systems and connections to the wider power grid. Offshore wind and cross-border interconnection create particularly cable-intensive requirements because of submarine and high-voltage export systems.
The increasing scale and distance of renewable projects is driving demand for higher-voltage AC and DC cable technology, large conductor sizes and sophisticated installation services. This favors suppliers with strong engineering, testing and project-execution capability.
Data Center and Digital Infrastructure Construction
AI, cloud computing and digital services are driving construction of power-dense data centers. These facilities require substantial electrical infrastructure, including utility feeds, substations, distribution cables, backup-power systems and internal power routing.
Data-center growth therefore supports both utility-side cable demand and industrial/building cable demand. Reliability, fire performance and low-carbon materials are becoming increasingly important specifications for hyperscale customers.
Industrial Automation and Electrification
Factories are adding robotics, drives, sensors and automated material-handling systems that require both power and control connectivity. Electrification of process equipment can further increase load and the density of internal distribution systems.
Control cables benefit from requirements for flexibility, shielding, chemical resistance and reliable signal performance, while power cables support motors, switchgear and plant-wide distribution. This creates a combined demand opportunity within modern industrial facilities.
Urbanization and Building Infrastructure
Residential, commercial and public construction remains a large source of low-voltage cable demand. Urban development also requires distribution networks, transit infrastructure, water systems and other electrified assets.
Building codes and fire-safety requirements are raising product specifications in many markets. This supports demand for certified fire-resistant and low-smoke cable constructions, particularly in high-rise, public and mission-critical buildings.
Market Restraints
Copper and Aluminum Price Volatility
Conductor metals represent a substantial portion of cable manufacturing cost. Rapid changes in copper or aluminum prices can increase working-capital needs, alter project economics and create timing differences between procurement and customer pricing.
Manufacturers often use metal-adjustment mechanisms and hedging, but smaller suppliers and customers may still face margin pressure. Price volatility can also change the relative attractiveness of copper and aluminum designs.
Long Lead Times for High-Voltage Projects
High-voltage and submarine cable systems require specialized manufacturing assets, testing capability, engineering and installation vessels. Capacity is concentrated among a limited number of global suppliers, and large projects can reserve production years in advance.
These constraints can delay projects and increase procurement costs. Expansion of manufacturing capacity helps, but new facilities require significant capital and qualification time.
Fragmentation and Quality Variation in Low-Voltage Markets
Low-voltage cable markets contain many regional and local manufacturers. In price-sensitive markets, low-quality or non-compliant products can compete with certified products and create safety risks.
Stronger enforcement of standards and certification can improve market quality, but it also raises compliance costs. Established suppliers increasingly differentiate through fire performance, traceability, testing and brand reputation.
Permitting and Project Execution Delays
Cable demand tied to grid, renewable and infrastructure projects depends on permitting, financing and construction schedules. Transmission projects in particular can take many years to approve and build.
Delays can shift cable orders, create uneven factory loading and complicate working-capital planning. Large suppliers therefore rely on diversified project portfolios and framework agreements to manage execution risk.
Substitution and Design Optimization
Engineering changes can reduce cable intensity per project through higher-voltage systems, conductor optimization or alternative routing. Copper can also be replaced by aluminum in applications where weight and cost advantages outweigh space and connection constraints.
Such substitution does not eliminate cable demand, but it changes product mix and can pressure suppliers that are concentrated in one conductor material or voltage class.
Regional Outlook
Asia Pacific
Asia Pacific is estimated at approximately USD 68.63 billion in 2026. The region combines the world’s largest manufacturing base with major urban construction, renewable deployment, data-center investment and transmission and distribution expansion.
China remains the largest single cable manufacturing and consumption market, while India is investing heavily in renewable integration and transmission capacity. The Central Electricity Authority has outlined substantial transmission investment requirements through 2032, and grid constraints are already influencing the pace of renewable development.
Regional demand is also supported by Southeast Asian industrialization, new data centers and expanding utility networks. Asia Pacific contains a large number of global and regional cable producers, which increases price competition but also supports localized supply for infrastructure projects.
Competitive Landscape
The market includes diversified global cable groups, high-voltage specialists and large regional producers. Prysmian, Nexans, NKT, Sumitomo Electric, Furukawa Electric and LS Cable & System compete in technically advanced transmission and distribution applications, while Southwire, Polycab India, KEI Industries, Elsewedy Electric, Riyadh Cables and other regional leaders maintain strong positions in building, industrial and utility cables.
Scale matters because conductor procurement, manufacturing utilization and global project execution can materially affect profitability. High-voltage cable suppliers also require specialized factories, testing facilities and installation capabilities that create substantial barriers to entry. In lower-voltage markets, competition is broader and distribution reach, certification and cost efficiency become more important.
Technology differentiation is increasing around HVDC systems, submarine cables, fire performance, flexible industrial cables, monitoring, digital traceability and lower-carbon materials. Long-term customer relationships with utilities, EPC contractors, industrial operators and distributors remain critical because cable products are frequently specified years before project completion.
Recent Developments
September 2026: Prysmian and Rio Tinto announced the use of low-carbon ELYSIS aluminum in electrical cables contracted for an Amazon data center in Ohio, demonstrating growing interest in reducing embedded carbon in high-load electrical infrastructure.
August 2026: NKT qualified a 525 kV HVDC subsea power cable system for continuous operation at a conductor temperature of up to 90 degrees Celsius, enabling higher transmission capability or material optimization in future projects.
August 2026: Nexans announced qualification of a 525 kV HVDC cable system for installation at a water depth of 3,000 meters as part of the Great Sea Interconnector, extending the technical envelope for deepwater subsea transmission.
June 2026: NKT completed the expansion of its medium-voltage power cable production facility in Asnaes, Denmark, increasing capacity to serve grid upgrades, renewable-energy integration and electrification demand in Europe.
March 2026: NKT signed its largest single project order for the Eastern Green Link 3 HVDC cable system in the United Kingdom, reinforcing the scale of investment required for grid expansion and renewable integration.
Market Outlook
The power and control cable market is expected to remain supported by a multi-year electricity investment cycle through 2031. Grid expansion, renewable interconnection, data-center construction, industrial automation and urban infrastructure are creating demand across voltage classes and conductor materials.
Growth is likely to remain strongest in applications where electrical load, project complexity or safety requirements are increasing faster than general construction activity. Medium- and high-voltage grid systems, data-center power infrastructure and specialized industrial cables are therefore expected to attract significant supplier investment.
At the same time, the market remains exposed to metal-price volatility and project timing. Manufacturers that combine scale, conductor sourcing, technical certification, manufacturing capacity and project execution are positioned to capture the largest infrastructure programs, while regional suppliers will continue to compete strongly in low-voltage building and industrial applications.
Power and Control Cable Market Scope
Report Metric
Details
Total Market Size in 2026
USD 149.20 billion
Total Market Size in 2031
USD 205.70 billion
Forecast Unit
Billion
Growth Rate
6.63%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Type, Material, Voltage, End User, Geography
Companies
Prysmian S.p.A.
Nexans S.A.
NKT A/S
Sumitomo Electric Industries Ltd.
Furukawa Electric Co. Ltd.
LS Cable & System Ltd.
Market Segmentation
By Type
Power Cable
Control Cable
By Material
Copper
Aluminum
Others
By Voltage
Low Voltage
Medium Voltage
High Voltage
By End User
Residential
Commercial
Industrial
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Major Market Opportunities
3.4. Segment and Regional Summary
3.5. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion and Modernization of Electricity Grids
4.1.2. Renewable Energy Integration and Interconnection
4.1.3. Data Center and Digital Infrastructure Construction
4.1.4. Industrial Automation and Electrification
4.1.5. Urbanization and Building Infrastructure
4.2. Market Restraints
4.2.1. Copper and Aluminum Price Volatility
4.2.2. Long Lead Times for High-Voltage Projects
4.2.3. Fragmentation and Quality Variation in Low-Voltage Markets
4.2.4. Permitting and Project Execution Delays
4.2.5. Substitution and Design Optimization
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Technology and Material Trends
5. POWER AND CONTROL CABLE MARKET BY TYPE
5.1. Introduction
5.2. Power Cable
5.3. Control Cable
6. POWER AND CONTROL CABLE MARKET BY MATERIAL
6.1. Introduction
6.2. Copper
6.3. Aluminum
6.4. Others
7. POWER AND CONTROL CABLE MARKET BY VOLTAGE
7.1. Introduction
7.2. Low Voltage
7.3. Medium Voltage
7.4. High Voltage
8. POWER AND CONTROL CABLE MARKET BY END USER
8.1. Introduction
8.2. Residential
8.3. Commercial
8.4. Industrial
9. POWER AND CONTROL CABLE MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Taiwan
9.6.6. Indonesia
9.6.7. Thailand
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Product and Technology Positioning
10.3. Manufacturing Capacity and Supply Chain
10.4. Mergers, Acquisitions, Agreements and Partnerships