
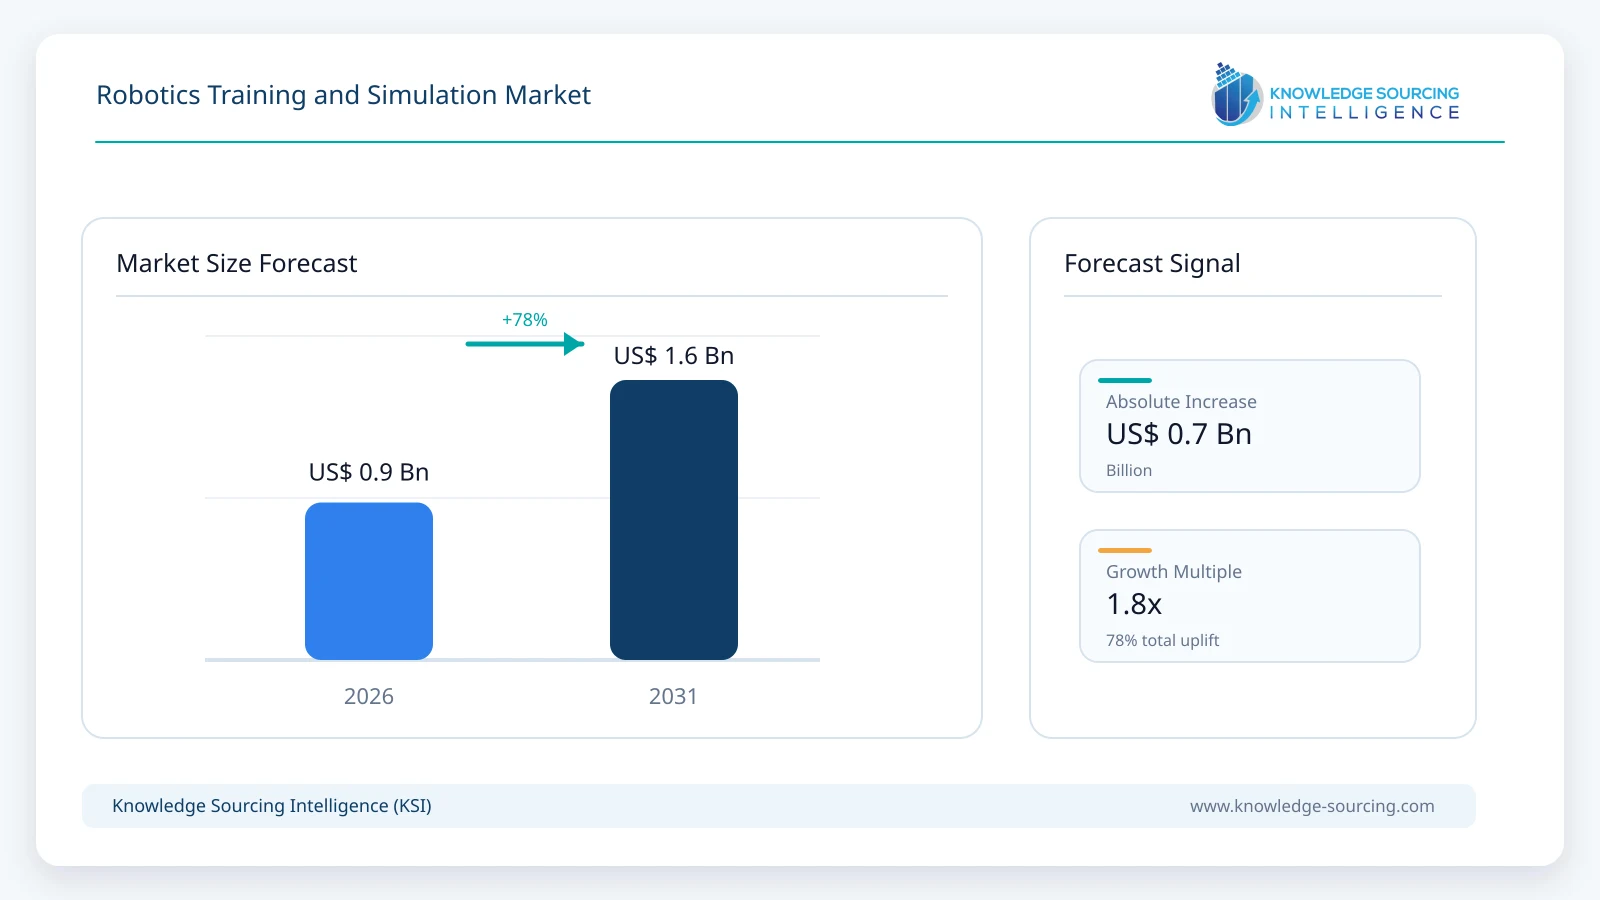
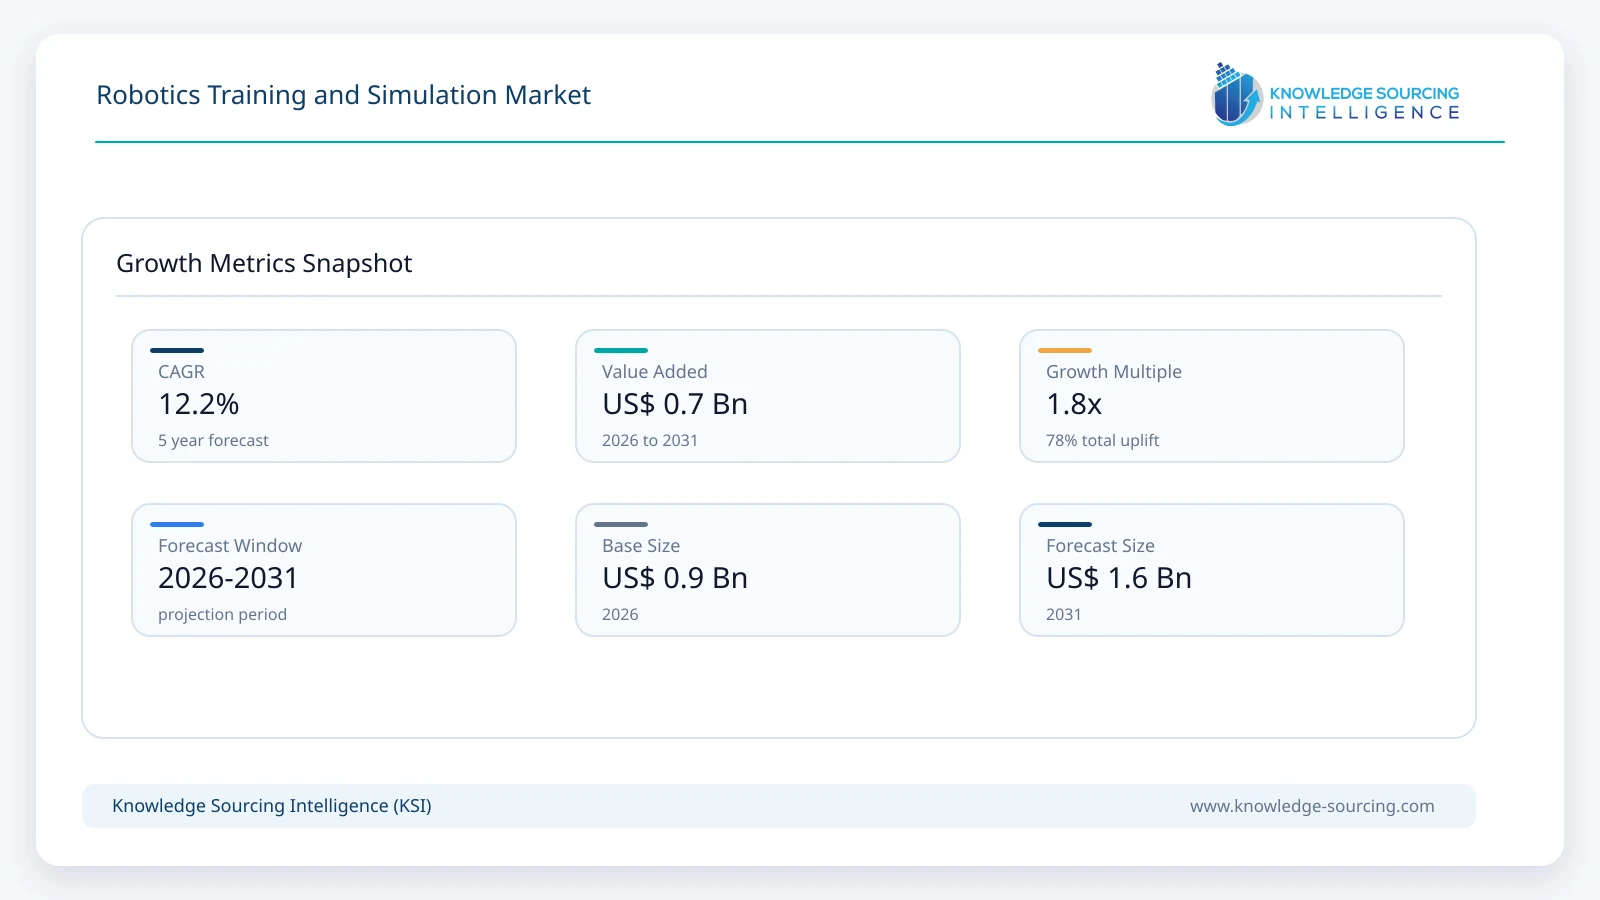
The Robotics Training and Simulation Market is set to reach USD 1.60 billion in 2031, growing at a CAGR of 12.2% between 2026 and 2031, from USD 0.90 billion in 2026.
Highlights:
- 1Software accounts for approximately 48% of market value in 2026, led by offline programming, robot-cell simulation, digital twins and AI training environments.
- 2Industrial robots account for approximately 63% of market demand by robot type in 2026, reflecting the scale of the global installed industrial robot base.
- 3Virtual testing and modelling represent approximately 44% of application revenue in 2026, ahead of standalone workforce training.
- 4Manufacturing companies account for approximately 35% of end-user demand in 2026, excluding automotive as a separately measured end-user segment.
- 5Asia Pacific accounts for approximately 36% of global market value in 2026, supported by its dominant share of industrial robot installations and installed stock.
Robotics training and simulation includes software, hardware and services used to design, program, test, train and validate robotic systems before or alongside physical deployment. The commercial scope includes industrial robot offline programming, virtual commissioning, digital twins, robotics-specific simulation engines, synthetic-data environments, reinforcement-learning workflows, operator and maintenance training and surgical robot simulation. General-purpose visualization software is included only where it directly supports robotics applications, while the value of the physical robot itself is excluded.
The underlying robotics installed base provides a substantial demand foundation. The International Federation of Robotics reported 542,076 new industrial robot installations in 2024 and an operational stock of 4,663,773 industrial robots, up 8.9% year on year. Electronics accounted for 128,899 new installations and automotive for 126,088. Asia represented 74% of global new deployments, with China alone accounting for 295,000 installations.
Training also represents a measurable commercial activity rather than a purely bundled service. ABB’s U.S. robotics training schedule lists instructor-led five-day courses at USD 3,100 per participant, while dedicated five-day classes can cost USD 17,500. ABB’s Austrian RobotStudio course is priced at EUR 1,960 per participant and includes a six-month Premium RobotStudio licence. These prices illustrate why training, application engineering and simulation services form a meaningful recurring value pool alongside software licences.
Simulation is increasingly moving into the engineering workflow itself. ABB RobotStudio, FANUC ROBOGUIDE, KUKA.Sim and Visual Components allow users to program, test and optimize robotic cells without occupying production equipment. FANUC describes ROBOGUIDE V10 as providing reach analysis, cycle-time validation, VR playback and digital-twin simulation before installation, while Visual Components supports offline programming across 22 robot brands and more than 40 controllers.
Market Trends
• Physical AI Is Expanding Simulation Beyond Conventional Robot Programming
Simulation is becoming a training environment for AI models rather than only a digital representation of mechanical motion. NVIDIA Isaac Sim supports physically based robot simulation, synthetic-data generation and integration with Isaac Lab for reinforcement learning. The software itself is now available for internal development without a conventional per-seat licence, meaning its direct software value should not be treated as equivalent to paid industrial simulation software; commercial value instead arises through enterprise support, GPU infrastructure, integration, cloud compute and related development services.
ABB strengthened this direction in March 2026 by integrating NVIDIA Omniverse technologies with RobotStudio. RobotStudio HyperReality is designed to combine industrial robot behaviour with photorealistic and physics-accurate environments for synthetic-data generation and physical-AI training. ABB states that applicable deployments can reduce engineering and production costs by up to 40% and shorten time-to-market by up to 50%.
• Virtual Commissioning Is Becoming Part of Mainstream Industrial Automation
Robot simulation is increasingly used before equipment reaches the factory floor. Engineers can examine robot reach, collisions, tooling, cycle times and sequencing before installation and can modify programs while production equipment remains in operation. FANUC’s ROBOGUIDE, ABB RobotStudio and KUKA.Sim all support this workflow, reducing the amount of physical trial-and-error needed during commissioning. FANUC further integrated ROBOGUIDE with NVIDIA Isaac Sim in 2026 so robot motion generated using FANUC control algorithms can be reproduced inside a photorealistic virtual factory.
Commercial simulation providers are also extending beyond individual robot brands. Visual Components provides offline programming across multiple manufacturers, allowing manufacturers and integrators operating mixed robot fleets to use a common virtual environment rather than maintaining separate programming workflows for every brand.
• Simulation and Real-World Demonstration Data Are Being Combined
AI-enabled robots require more diverse training than fixed industrial motion sequences. Universal Robots and Scale AI launched the UR AI Trainer in March 2026 to collect synchronized robot motion, force and vision data using production-grade Universal Robots systems. The approach allows models to learn from real human demonstrations while simulation provides additional scenarios and accelerated iteration.
AWS is similarly providing infrastructure for large-scale robot reinforcement learning. Its NVIDIA Isaac Lab workflows allow multiple simulated robots to train in parallel using GPU infrastructure, enabling robot developers to compress very large numbers of training interactions into substantially shorter development cycles.
• Surgical Robot Simulation Remains a High-Value Specialist Market
Healthcare creates a separate training requirement because clinicians must develop proficiency without exposing patients to unnecessary learning risk. Intuitive Surgical’s SimNow platform has recorded more than 3.3 million initiated simulation exercises, with more than 45 skills exercises and more than 35 procedure modules. The company had an installed base of 11,106 da Vinci systems at the end of 2025, up 12% year on year.
Hospitals use simulation for surgeon onboarding, credentialing, procedure training, technology adoption and skills maintenance. This makes healthcare smaller in absolute robotics volume than industrial manufacturing but materially more training-intensive per installed system.
Market Drivers
• A Large and Expanding Installed Robot Base
The global operational stock of industrial robots reached 4.66 million units in 2024 and continued to expand as more than half a million new systems were installed annually. Professional service robot sales separately exceeded 199,000 units in 2024, while almost 16,700 medical robots were sold. Every new deployment can create demand for programming, validation, operator preparation, maintenance training or AI model development.
• Training and Commissioning Have Direct Economic Value
Robotic equipment is productive only when engineers and operators can program, commission and maintain it effectively. Public ABB pricing shows multi-day instructor-led courses costing thousands of dollars per participant, demonstrating that workforce readiness is an identifiable revenue category rather than an incidental activity.
Offline programming creates a second economic benefit by reducing production downtime. Engineers can prepare and test new programs virtually while a robot remains in production, making simulation especially valuable in automotive, electronics and other high-utilization manufacturing environments.
• Physical AI Requires Far More Virtual Training
Traditional industrial robots operate in structured environments using deterministic programming. Humanoids, autonomous robots and AI-enabled manipulators must respond to changing objects, people and surroundings. These systems require substantially more training scenarios than conventional robots.
AWS documents Isaac Lab workflows where thousands of robot instances can run in parallel on GPU infrastructure, turning what could require months of physical interaction into much shorter simulated training cycles. This expands the commercial market from software licences and workforce instruction toward GPU compute, cloud infrastructure, synthetic data, integration and AI-engineering services.
Market Restraints
• Open-Source Software Limits Direct Licence Monetization
One important restraint is that several important robot-simulation tools are available free or open source. NVIDIA Isaac Sim is available for internal commercial R&D without per-user licence fees, while many robotics research environments also build on ROS, Gazebo and other open frameworks.
The commercial opportunity therefore depends increasingly on enterprise-grade engineering tools, support, cloud infrastructure, proprietary robot controllers, integration services and high-value training rather than assuming every simulator user generates licence revenue.
• Simulation Cannot Fully Replace Physical Validation
Robot performance depends on friction, tolerances, payload behaviour, sensor noise, contact forces and other real-world variables that cannot always be represented perfectly. Simulation therefore reduces physical testing but does not eliminate it.
This is why the market is moving toward simulation-to-real workflows. Universal Robots combines physical demonstrations with AI training, FANUC connects ROBOGUIDE with Isaac Sim, and Siemens explicitly discusses combining simulation with real-world robot testing rather than relying on virtual environments alone.
Segment Analysis
• By Component: Software
Software accounts for approximately 48% of global market value in 2026 and remains the largest component. The segment includes robot offline-programming licences, digital-twin platforms, virtual commissioning applications, physics-based simulation, robot-learning environments and specialist surgical simulation software.
The share reflects strong commercial activity around paid platforms such as RobotStudio Premium, ROBOGUIDE, KUKA.Sim, Visual Components, DELMIA and MATLAB/Simulink robotics tools. MathWorks’ Robotics System Toolbox, for example, supports industrial robot modelling, collision checking, path planning, Unreal Engine simulation and Gazebo co-simulation.
The revenue model must nevertheless distinguish between software adoption and software revenue. NVIDIA Isaac Sim is open source for internal R&D and Omniverse became freely available for development and production use in May 2026. Consequently, the market counts commercial compute, support, integration and derived robotics solutions rather than assigning artificial licence revenue to free software.
• By Robot Type: Industrial Robots
Industrial robots account for approximately 63% of market demand in 2026, supported by an operational global stock approaching 4.7 million units by the end of 2024. These systems require programming, integration, operator instruction, maintenance training and periodic reconfiguration throughout their working lives.
The segment also contains the most mature commercial simulation ecosystems. ABB, FANUC and KUKA each offer dedicated simulation and training environments, while multi-brand platforms such as Visual Components address integrators and factories operating heterogeneous robot fleets. Service robots, autonomous mobile robots and humanoids represent smaller installed bases but are expected to generate faster simulation growth because their behaviour relies more heavily on perception, AI models and variable-environment testing.
• By Application: Virtual Testing and Modelling
Virtual testing and modelling represent approximately 44% of market value in 2026 and form the largest application group. Activities include cell layout, collision detection, path planning, reachability, cycle-time analysis, virtual commissioning, perception testing, synthetic-data generation and reinforcement-learning validation.
The economic case is strongest where physical testing would stop production or require expensive prototypes. Visual Components reports customer applications where robot programming time has been materially reduced by moving programming off the production floor, while FANUC positions ROBOGUIDE specifically around proving workcell performance before installation.
• By End-User: Manufacturing Companies
Manufacturing companies account for approximately 35% of global market value in 2026, excluding automotive as a separate category. Electronics, metalworking, machinery, pharmaceuticals, food processing and other discrete manufacturing industries increasingly use robots for handling, assembly, welding, packaging and inspection.
IFR recorded 128,899 robot installations in electronics during 2024, slightly exceeding automotive installations. Metal and machinery also represented a significant share of global deployments. This supports a broader manufacturing training and simulation market beyond automotive factories alone.
Regional Outlook
• Asia Pacific
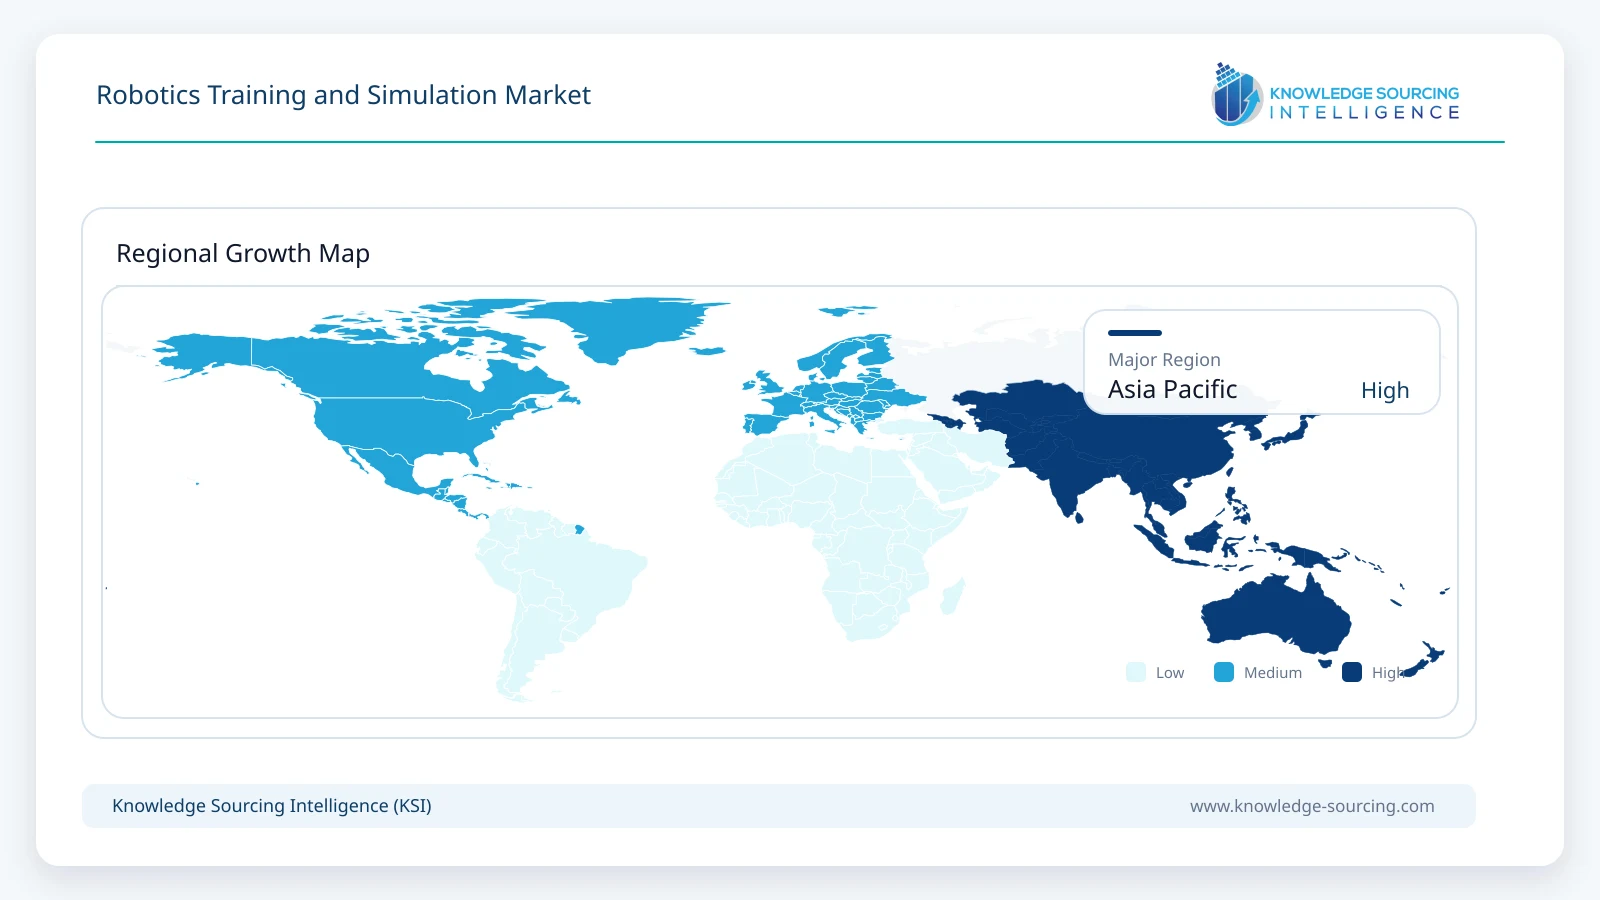
Asia Pacific accounts for approximately 36% of global market value in 2026 and represents the largest regional market. This is more consistent with the underlying robot deployment structure than assigning market leadership to North America. Asia accounted for 74% of industrial robot installations in 2024, while China alone represented 54% of global deployments. China also held 43.5% of the global operational industrial robot stock, with Japan and South Korea adding another 18.1%.
North America remains disproportionately important in physical-AI development, surgical robotics and cloud-based simulation and therefore has a higher simulation spend per robot than installation volumes alone would suggest. Europe similarly benefits from strong industrial automation software, automotive engineering and major robotics suppliers.
The geographic estimate therefore weights both installed robot activity and the higher software, engineering and training intensity found in North America and Europe rather than simply allocating the market according to robot unit volumes.
Competitive Landscape
The market includes robot manufacturers with proprietary simulation environments, independent engineering-software vendors, specialist surgical simulation providers and physical-AI infrastructure companies.
ABB Robotics participates through RobotStudio and its expanding HyperReality environment. As of September 2026, ABB has signed an agreement to sell its Robotics division to SoftBank Group for USD 5.375 billion, but ABB continued to describe completion as targeted for the second half of 2026 in its latest published financial updates, so the business should not yet be described as SoftBank-owned.
FANUC provides ROBOGUIDE and is integrating the platform with NVIDIA Isaac Sim. KUKA provides KUKA.Sim, iiQWorks.Sim and global robotics training through KUKA College. Visual Components provides multi-brand manufacturing simulation and offline robot programming.
NVIDIA is strategically important through Isaac Sim, Isaac Lab and Omniverse, although its open-source and free-use structure means its role should not be interpreted as direct robotics simulation software revenue alone. Siemens, Dassault Systèmes and MathWorks participate through digital twins, manufacturing simulation and robotics engineering software.
Intuitive Surgical provides a specialist surgical-robotics simulation ecosystem through SimNow, while Universal Robots / Teradyne Robotics is expanding from conventional cobot training into AI model-training infrastructure.
Recent Developments
July 2026: FANUC America detailed ROBOGUIDE V10’s 64-bit architecture, VR playback and digital-twin functionality for validating robotic workcells before installation.
May 2026: FANUC strengthened integration between ROBOGUIDE and NVIDIA Isaac Sim for virtual commissioning, physics-based simulation and physical-AI development.
March 2026: ABB Robotics announced integration of NVIDIA Omniverse technologies with RobotStudio and introduced RobotStudio HyperReality.
March 2026: Universal Robots and Scale AI launched the UR AI Trainer for synchronized collection of robot motion, force and vision data.
January 2026: AWS published GPU-accelerated NVIDIA Isaac Lab workflows enabling scalable reinforcement-learning training for robotic assets.
2026: Intuitive continued expanding SimNow 2 as a proficiency-based training environment across its da Vinci ecosystem.
Market Outlook
The robotics training and simulation market is forecast to increase from USD 0.90 billion in 2026 to USD 1.60 billion in 2031, representing a CAGR of 12.2%. The forecast is supported by different growth paths across the market rather than a uniform CAGR applied to every segment.
Industrial robot simulation and training remain the largest revenue pool and grow with installed automation, factory reconfiguration and offline programming. Surgical simulation expands with robotic procedure volumes and installed surgical systems. Autonomous robots and service robots require more extensive perception and scenario testing, while humanoid and physical-AI development produces the fastest growth from a small base because reinforcement learning and synthetic-data generation require substantially greater simulation intensity.
Software remains the largest component, but services retain a substantial share because robotics training, integration and commissioning are technically demanding. Asia Pacific leads the market in 2026 through the scale of its robot installed base, while North America retains an outsized role in AI training, cloud simulation and surgical robotics.
Robotics Training and Simulation Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.90 billion |
| Total Market Size in 2031 | USD 1.60 billion |
| Forecast Unit | Billion |
| Growth Rate | 12.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Robot Type, Component, Application, End-User Industry, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Robot Type
Industrial Robots
Surgical Robots
Autonomous Mobile and Vehicle Robots
Service Robots
Humanoid Robots
Others
By Component
Software
Hardware
Services
By Application
Virtual Testing and Modelling
Training
Education
Research and Development
Robotic Maintenance
Others
By End-User Industry
Manufacturing Companies
Automotive Industry
Healthcare Providers
Aerospace and Defense Organizations
Educational and Research Institutions
Logistics and Warehousing
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
South Korea
India
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Revenue Inclusion and Exclusion Criteria
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Expansion of the Global Robot Installed Base
3.1.2. Economic Value of Offline Programming and Virtual Commissioning
3.1.3. Growth of Physical AI and Robot-Learning Workloads
3.2. Market Restraints
3.2.1. Open-Source Simulation and Direct Software Monetization
3.2.2. Simulation-to-Real Validation Requirements
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Standards, Safety and Validation Environment
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Digital Twins and Virtual Commissioning
4.2. Physics-Based Robot Simulation
4.3. Synthetic Data Generation
4.4. Reinforcement and Imitation Learning
4.5. Virtual and Augmented Reality Training
4.6. Cloud-Based Robot Simulation
5. ROBOTICS TRAINING AND SIMULATION MARKET BY ROBOT TYPE
5.1. Introduction
5.2. Industrial Robots
5.3. Surgical Robots
5.4. Autonomous Mobile and Vehicle Robots
5.5. Service Robots
5.6. Humanoid Robots
5.7. Others
6. ROBOTICS TRAINING AND SIMULATION MARKET BY COMPONENT
6.1. Introduction
6.2. Software
6.3. Hardware
6.4. Services
7. ROBOTICS TRAINING AND SIMULATION MARKET BY APPLICATION
7.1. Introduction
7.2. Virtual Testing and Modelling
7.3. Training
7.4. Education
7.5. Research and Development
7.6. Robotic Maintenance
7.7. Others
8. ROBOTICS TRAINING AND SIMULATION MARKET BY END-USER INDUSTRY
8.1. Introduction
8.2. Manufacturing Companies
8.3. Automotive Industry
8.4. Healthcare Providers
8.5. Aerospace and Defense Organizations
8.6. Educational and Research Institutions
8.7. Logistics and Warehousing
8.8. Others
9. ROBOTICS TRAINING AND SIMULATION MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. South Korea
9.5.4. India
9.5.5. Taiwan
9.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Industrial Robot Simulation Platforms
10.3. Multi-Brand Offline Programming Platforms
10.4. Physical-AI and Robot-Learning Platforms
10.5. Surgical Robotics Simulation
10.6. Training and Services Capabilities
10.7. Partnerships and Product Development
10.8. Competitive Dashboard
11. COMPANY PROFILES
11.1. ABB Robotics
11.2. FANUC Corporation
11.3. KUKA AG
11.4. NVIDIA Corporation
11.5. Siemens AG
11.6. Dassault Systèmes SE
11.7. The MathWorks, Inc.
11.8. Visual Components Oy
11.9. Intuitive Surgical, Inc.
11.10. Universal Robots A/S
12. APPENDIX
12.1. Market Definition and Revenue Boundary
12.2. Currency and Conversion Assumptions
12.3. Base Year and Forecast Period
12.4. Market Estimation Approach
12.5. Primary and Secondary Research Framework
12.6. Segment Reconciliation
12.7. Data Triangulation and Validation
12.8. Abbreviations





Frequently asked questions
What is the projected market size and growth rate for the Robotics Training and Simulation Market between 2026 and 2031?
The Robotics Training and Simulation Market is projected to grow from USD 0.90 billion in 2026 to USD 1.60 billion by 2031. This expansion represents a robust Compound Annual Growth Rate (CAGR) of 12.2% over the forecast period, indicating significant market growth.
Which technology segment is the largest contributor to the Robotics Training and Simulation Market, and what drives its value?
Software is the leading technology segment, accounting for approximately 48% of the market value in 2026. This dominance is primarily driven by solutions for offline programming, robot-cell simulation, digital twins, and AI training environments, which are critical for advanced robotics applications.
What types of robots and end-user industries are key demand drivers within the Robotics Training and Simulation Market?
Industrial robots represent approximately 63% of the market demand by robot type in 2026, reflecting the extensive global installed industrial robot base. Among end-users, manufacturing companies contribute significantly, accounting for approximately 35% of demand in 2026, excluding the automotive sector.
Which geographical region holds the largest market share in the Robotics Training and Simulation Market, and what factors contribute to this?
Asia Pacific accounts for approximately 36% of the global market value in 2026, making it the dominant region. This substantial share is supported by its leading position in industrial robot installations and operational stock, with Asia representing 74% of global new deployments in 2024.
What are the primary applications driving revenue in the Robotics Training and Simulation Market, and how is the market's future outlook evolving?
Virtual testing and modelling represent approximately 44% of application revenue in 2026, surpassing standalone workforce training. The market's future outlook points towards simulation increasingly integrating into the core engineering workflow, leveraging digital twins, synthetic-data environments, and reinforcement-learning workflows.
What types of commercial offerings and services are prevalent in the Robotics Training and Simulation Market?
The Robotics Training and Simulation Market encompasses a range of commercial offerings, including instructor-led courses, dedicated five-day classes, and software licenses such as ABB’s RobotStudio Premium. These training, application engineering, and simulation services form a meaningful recurring value pool alongside software licenses, indicating a diverse service landscape.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Robotics Training and Simulation Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/robotics-training-and-simulation-market