
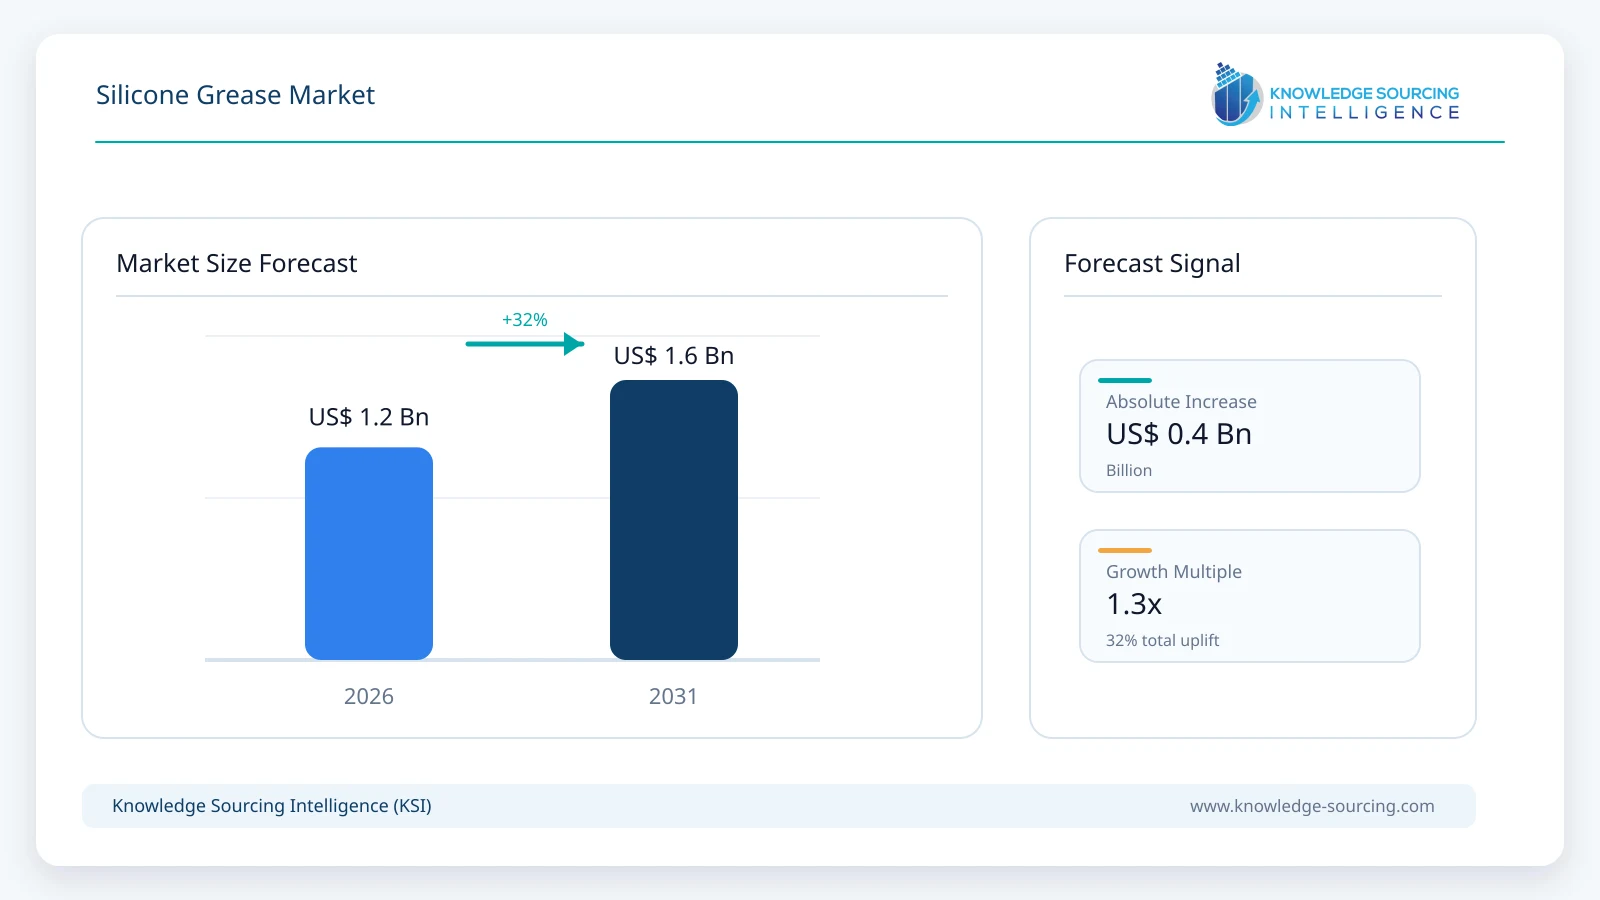
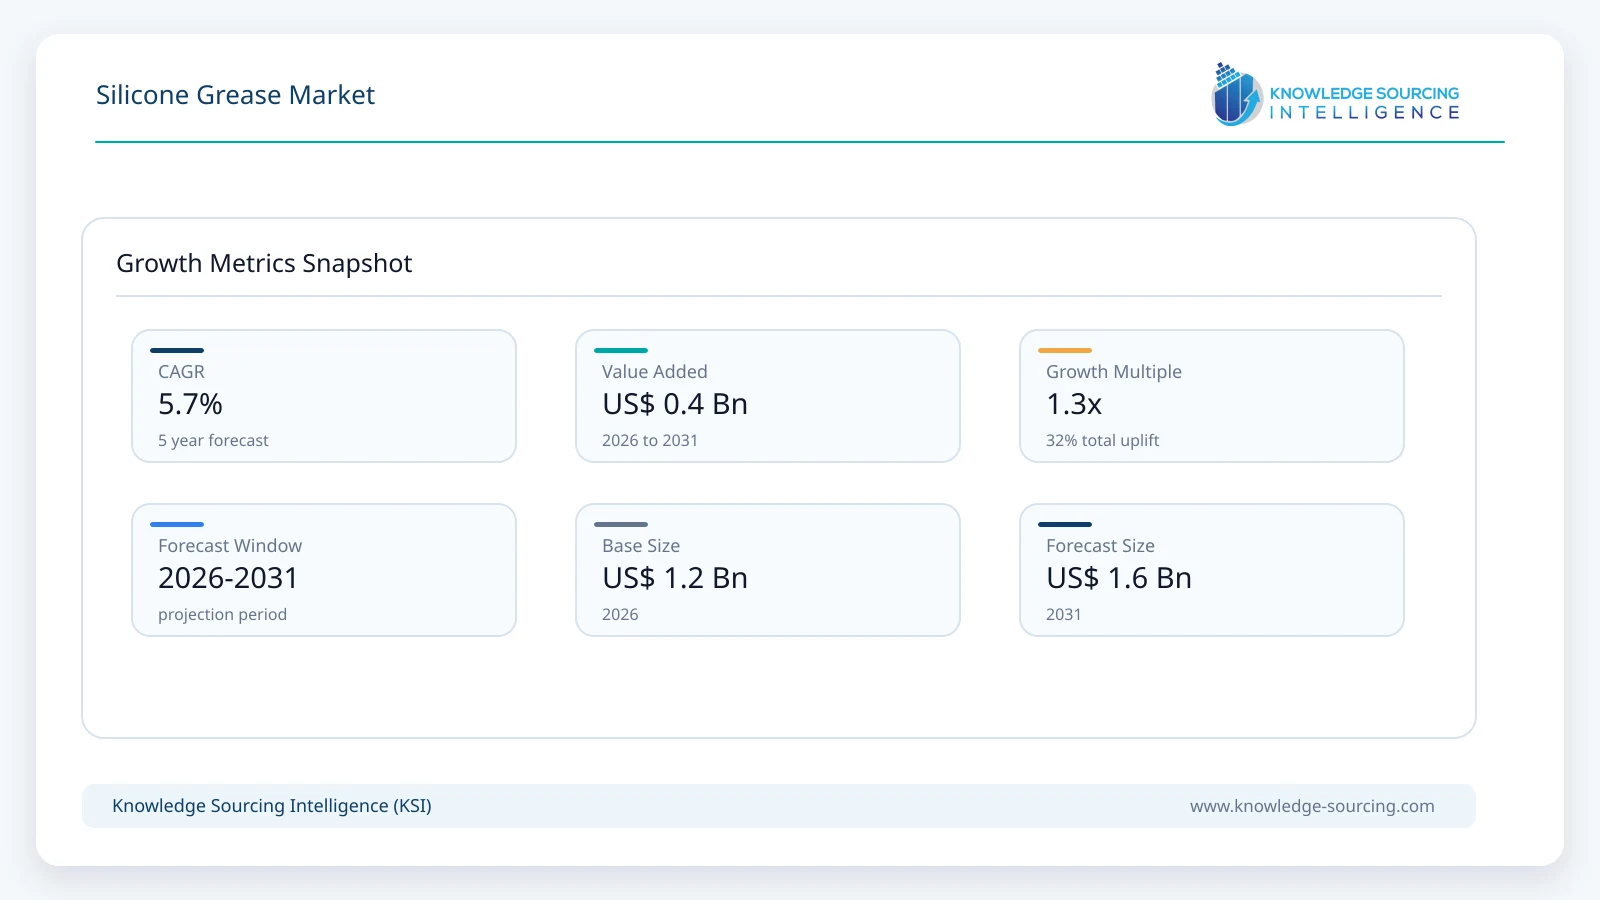
The Silicone Grease Market is projected to grow from USD 1.232 billion in 2026 to USD 1.622 billion by 2031, registering a 5.66% CAGR during the forecast period.
Highlights:
- 1General-purpose lubricating and sealing silicone grease accounts for approximately 38% of global market value in 2026, supported by broad use across seals, valves, plastics, elastomers and industrial equipment.
- 2Silica-based formulations represent approximately 58% of market value in 2026, reflecting the established use of fumed and other silica thickeners with silicone fluids.
- 3Automotive applications account for approximately 30% of market value in 2026 as silicone grease is used in connectors, control cables, plastic mechanisms, seals and temperature-sensitive components.
- 4Asia Pacific accounts for approximately 43% of global silicone grease market value in 2026 due to its concentration of automotive, semiconductor, electronics and industrial manufacturing.
- 5Thermally conductive silicone grease is projected to record the strongest product-level growth at approximately 8.2% annually through 2031 as power density increases across electronics and computing systems.
Report Overview
The silicone grease market is experiencing steady growth, supported by the expanding use of silicone-based lubricants across electrical, automotive, industrial, and specialized applications. Silicone greases generally combine silicone-based fluids with inorganic, soap-based or specialty thickeners to provide lubrication, sealing, dielectric protection or thermal transfer across applications where mineral-oil greases may experience oxidation, material incompatibility or excessive viscosity change. DuPont notes that silicone lubricants provide low friction together with strong resistance to oxidation and moisture and can be formulated for low-temperature applications approaching -73°C, while commercial silicone greases are used across electrical equipment, automotive components, plastic and rubber interfaces, valves, seals and industrial equipment.
The market includes general-purpose lubricating and sealing silicone greases, dielectric and electrical compounds, thermally conductive silicone greases, water- and food-compatible formulations and other specialist products. The product structure is broader than conventional two-category classifications because commercially available silicone greases use multiple formulation strategies and serve substantially different functional requirements. DuPont’s current portfolio includes silicone grease thickened with lithium soap as well as lithium-complex formulations, while Super Lube markets separate silicone dielectric, vacuum, food-grade and general lubricating greases.
Silicone grease occupies a specialist position within the broader lubricants industry because its primary advantage is not extreme mechanical load capacity but stability across temperature, electrical and environmental conditions that can challenge conventional lubricants. Silicone-based formulations are particularly compatible with many plastics and elastomers and can retain useful performance across wide temperature ranges. DuPont’s MOLYKOTE G-5042 automotive silicone grease, for example, operates between approximately -50°C and 170°C and is designed for metal-to-plastic and plastic-to-plastic interfaces, while MOLYKOTE G-5008 dielectric grease retains dielectric characteristics even following extended exposure above 200°C. This combination of temperature stability, water resistance and material compatibility supports applications ranging from automotive connectors and window mechanisms to O-rings, valves, industrial controls, laboratory equipment and household appliances.
Electronics and thermal management are creating a higher-value growth area within the market. Momentive’s SILCOOL thermal grease portfolio provides products with thermal conductivity ranging from approximately 3.3 W/m·K to 7 W/m·K for ICT applications, including servers and communications equipment, where low thermal resistance and long-term stability are critical. Semiconductor industry expansion reinforces this demand: worldwide semiconductor sales increased 25.6% in 2025 to USD 791.7 billion, while SEMI expects semiconductor manufacturing equipment sales to reach USD 165.9 billion in 2026, up 23.2% year over year.
Market Trends
Thermal Grease Performance Is Increasing With Electronics Power Density
Thermally conductive silicone grease is becoming more technically differentiated as AI computing, semiconductor equipment, telecommunications and power electronics generate higher heat loads within increasingly compact assemblies. Momentive markets silicone thermal greases specifically for server CPUs, ICT equipment and wireless infrastructure, where higher chipset density increases the need for low thermal resistance. Parker Chomerics expanded this category in 2026 with a four-product THERM-A-GREASE family providing thermal conductivity from 1.5 W/m·K to 7.0 W/m·K and thin minimum bond lines for electronic assemblies. Dow similarly launched a silicone-based thermal material in May 2026 with conductivity around 12 W/m·K for optical modules, dense electronics and high-speed data applications. Although gel and grease formats differ in rheology, these developments indicate the direction of the thermal-interface segment toward greater conductivity, lower bleed and automated dispensing as electronics power density increases.
Automotive Electrification Is Increasing Electrical Protection Requirements
Modern vehicles contain increasing numbers of electrical connectors, actuators, sensors and electronically controlled mechanisms, creating additional applications for dielectric and water-resistant silicone compounds. DuPont’s automotive lubrication guide lists silicone-based solutions for spark-plug boots, ignition switches, wiring and harness connections, overrunning clutches and low-temperature mechanisms, demonstrating that silicone grease demand extends well beyond conventional bearing lubrication. The underlying automotive manufacturing base remains substantial and is again growing: OICA reported global vehicle production of 96.4 million units in 2025, up 3.9%, with Asia Pacific producing approximately 59.2 million vehicles and accounting for more than 61% of global output. China alone produced 34.53 million vehicles, including 16.63 million new-energy vehicles, which increased 29%. Electrification increases the number and importance of moisture-sensitive connectors and control systems, supporting greater use of dielectric and sealing formulations per vehicle.
PFAS-Free and Application-Specific Formulations Are Increasing
Manufacturers are redesigning specialty greases to respond to regulatory and customer requirements surrounding fluorinated materials while preserving the temperature and friction characteristics required by demanding applications. FUCHS introduced NYEMED 7312 in 2025 as a non-PFAS, silica-thickened silicone damping grease for medical devices, targeting applications where controlled motion, biocompatibility and documentation are important. DuPont’s MOLYKOTE PG-21 silicone grease is similarly marketed without intentionally added PTFE or PFAS and provides a service temperature range from -50°C to 190°C for plastic/plastic and plastic/metal interfaces. These developments indicate that formulation design is becoming more application-specific. Medical equipment, semiconductors, electronics, automotive systems and food machinery increasingly require different combinations of dielectric behaviour, cleanability, thermal conductivity, material compatibility, low bleed and regulatory compliance rather than one universal silicone grease formulation.
Market Drivers
Expansion of Electronics and Semiconductor Manufacturing
Electronics provides one of the strongest incremental demand drivers because greater computing performance increases requirements for both thermal management and precision lubrication within manufacturing equipment. Global semiconductor sales reached USD 791.7 billion in 2025, rising 25.6%, while logic semiconductor sales increased 39.9% to USD 301.9 billion and memory sales increased 34.8% to USD 223.1 billion. Semiconductor-equipment investment is accelerating simultaneously. SEMI expects global semiconductor manufacturing equipment sales to reach USD 165.9 billion in 2026, up 23.2%, and approximately USD 229.5 billion by 2028 as AI, advanced memory and leading-edge logic drive capacity investment. Silicone greases benefit through two channels: thermal-interface materials dissipate heat from high-power electronic components, while specialty lubricants are used within manufacturing equipment requiring low particle generation, stable lubrication and long maintenance intervals. DuPont highlighted MOLYKOTE specialty lubricants specifically for advanced semiconductor manufacturing equipment at CSEAC 2026.
Higher Automotive Production and Increasing Electrical Content per Vehicle
Automotive applications remain the largest individual end-use category because silicone greases are used across mechanical and electrical systems where plastics, elastomers, moisture and changing temperatures make conventional lubricants less suitable. Global vehicle production increased from 92.7 million units in 2024 to 96.4 million units in 2025, while global sales approached 100 million vehicles. Asia Pacific accounted for over 61% of output, and China’s new-energy vehicle production increased 29% to 16.63 million units. Electrified vehicles add connectors, electronic controllers, high-voltage systems, sensors and motor-driven actuators, increasing opportunities for dielectric protection and compatible lubrication. MOLYKOTE’s automotive portfolio includes silicone products for wiring connections, spark-plug boots, ignition systems, control cables, plastic gears and overrunning clutches, illustrating the breadth of applications. The driver is therefore not only vehicle production growth but increasing electrical and polymer content per vehicle.
Demand for Reliable Lubrication Across Plastics, Elastomers and Wet Environments
Silicone grease is widely used where compatibility with plastic and elastomer components is as important as friction reduction. Super Lube’s compatibility data show strong compatibility across numerous polymers including ABS, polycarbonate, polyethylene, polypropylene and many elastomer types, while its silicone formulations are used for O-rings, seals, food equipment and electrical insulation. Clearco similarly markets silicone grease for O-rings, valves, seals, electrical applications, aerospace, food processing and oil and gas because of its hydrophobic characteristics, dielectric strength and stability. These properties sustain demand in equipment exposed to water, cleaning chemicals, temperature cycling or mixed polymer-metal interfaces, including beverage-processing equipment, plumbing systems, appliances and industrial automation. Growth is therefore linked to the expanding use of engineered plastics and elastomers in modern equipment as much as to traditional lubricant consumption.
Market Restraints
Alternative Thermal and Synthetic Lubricants Compete in High-Performance Applications
Silicone grease does not provide the optimum performance for every lubrication or thermal-management application. PAO, PFPE, ester-based and other synthetic greases can provide better load carrying, hydrocarbon compatibility or lower migration in specific environments, while thermal-management designers can choose pads, gels, phase-change materials and gap fillers instead of silicone grease. Henkel’s industrial thermal-management portfolio, for example, includes pads, liquid gap fillers, phase-change materials and silicone-free alternatives for applications where outgassing or silicone contamination is undesirable. Semiconductor, optical and electronics manufacturers can be particularly sensitive to siloxane migration and contamination, forcing suppliers to reduce oil bleed or offer silicone-free alternatives. This means strong electronics growth does not translate directly into equivalent silicone grease growth, because competing interface materials can capture part of the available thermal-management expenditure.
Specialty Formulations Require Application-Specific Qualification
Silicone greases are frequently used in systems where material compatibility, electrical behaviour, food-contact requirements or long service life must be validated before commercial adoption. Food-processing applications may require NSF H1 registration, while potable-water and oxygen-service applications can require separate certifications and compatibility testing. Super Lube’s silicone grease is NSF H1 registered for incidental food contact, while WEICON markets silicone grease for valves, seals and fittings with food and potable-water related approvals and a service range extending to approximately 200°C. Automotive and electronics suppliers similarly require validation against plastics, rubber materials, connector designs and production dispensing processes. These qualification requirements support high-value specialized products but lengthen replacement cycles because manufacturers are reluctant to change a validated grease once component reliability has been demonstrated.
Silicone Grease Market Segment Analysis
By Product Type
General-Purpose Lubricating and Sealing Silicone Grease
General-purpose lubricating and sealing silicone grease remains the largest product category and is projected to reach approximately USD 572 million by 2031. The segment grows more slowly than thermal and dielectric products at around 4.1% annually because it already has extensive penetration across O-rings, valves, seals, plastic mechanisms, appliances and maintenance applications. Silicone grease’s hydrophobic nature and relatively stable viscosity make it particularly useful where equipment experiences moisture or where plastics and elastomers require long-term lubrication without substantial swelling or degradation. DuPont, Super Lube, Clearco and WEICON all maintain products aimed at these applications, illustrating their continuing commercial importance. Thermally conductive grease grows considerably faster and approaches USD 402 million by 2031 as semiconductor, server, telecom and power-electronics applications increase, but its smaller 2026 base prevents it from overtaking general-purpose products during the forecast period.
By Thickener Type
Silica-Based Formulations
Silica-based silicone greases retain the largest thickener position and are projected to reach approximately USD 943 million by 2031. Silica provides a stable three-dimensional structure within silicone fluids and is widely used where chemical inertness, thermal stability and controlled consistency are important. The category includes both conventional general-purpose silicone compounds and technically advanced damping, electrical and specialty formulations. FUCHS’ NYEMED 7312 medical-device grease uses a silica-thickened silicone system, while Clearco’s PDMS-based compounds illustrate the continuing use of inorganic thickener systems in industrial sealing and lubrication. Lithium soap and lithium-complex silicone greases form a smaller but meaningful category and are particularly relevant to dynamic automotive and industrial lubrication. DuPont’s G-5042 uses a lithium thickener and its PG-21 product uses lithium complex, demonstrating why a two-way silica/PTFE classification does not adequately represent commercially available formulations.
By Application
Automotive
Automotive remains the largest application and is projected to reach approximately USD 481 million by 2031, representing growth of around 5.4% annually from 2026. Silicone grease is used in electrical connectors, ignition components, cables, plastic gears, window mechanisms, seals and actuators because the material combines dielectric properties with compatibility across rubber and plastic components. DuPont’s automotive guidance identifies silicone products for spark-plug boots, wiring harness connections, overrunning clutches and low-temperature mechanisms, while G-5042 is designed for long-term lubrication across metal/plastic and plastic/plastic interfaces from -50°C to 170°C. Electrical and electronics applications grow faster at approximately 8.0% annually and reach about USD 453 million by 2031, narrowing the gap with automotive as high-density computing, semiconductor manufacturing and advanced electrical equipment increase requirements for dielectric and thermal grease.
Regional Outlook
Asia Pacific
Asia Pacific remains both the largest and fastest-growing regional silicone grease market. The region is projected to reach approximately USD 729 million by 2031, representing growth of around 6.6% annually from 2026. Its position is supported by concentration across nearly every major demand industry.
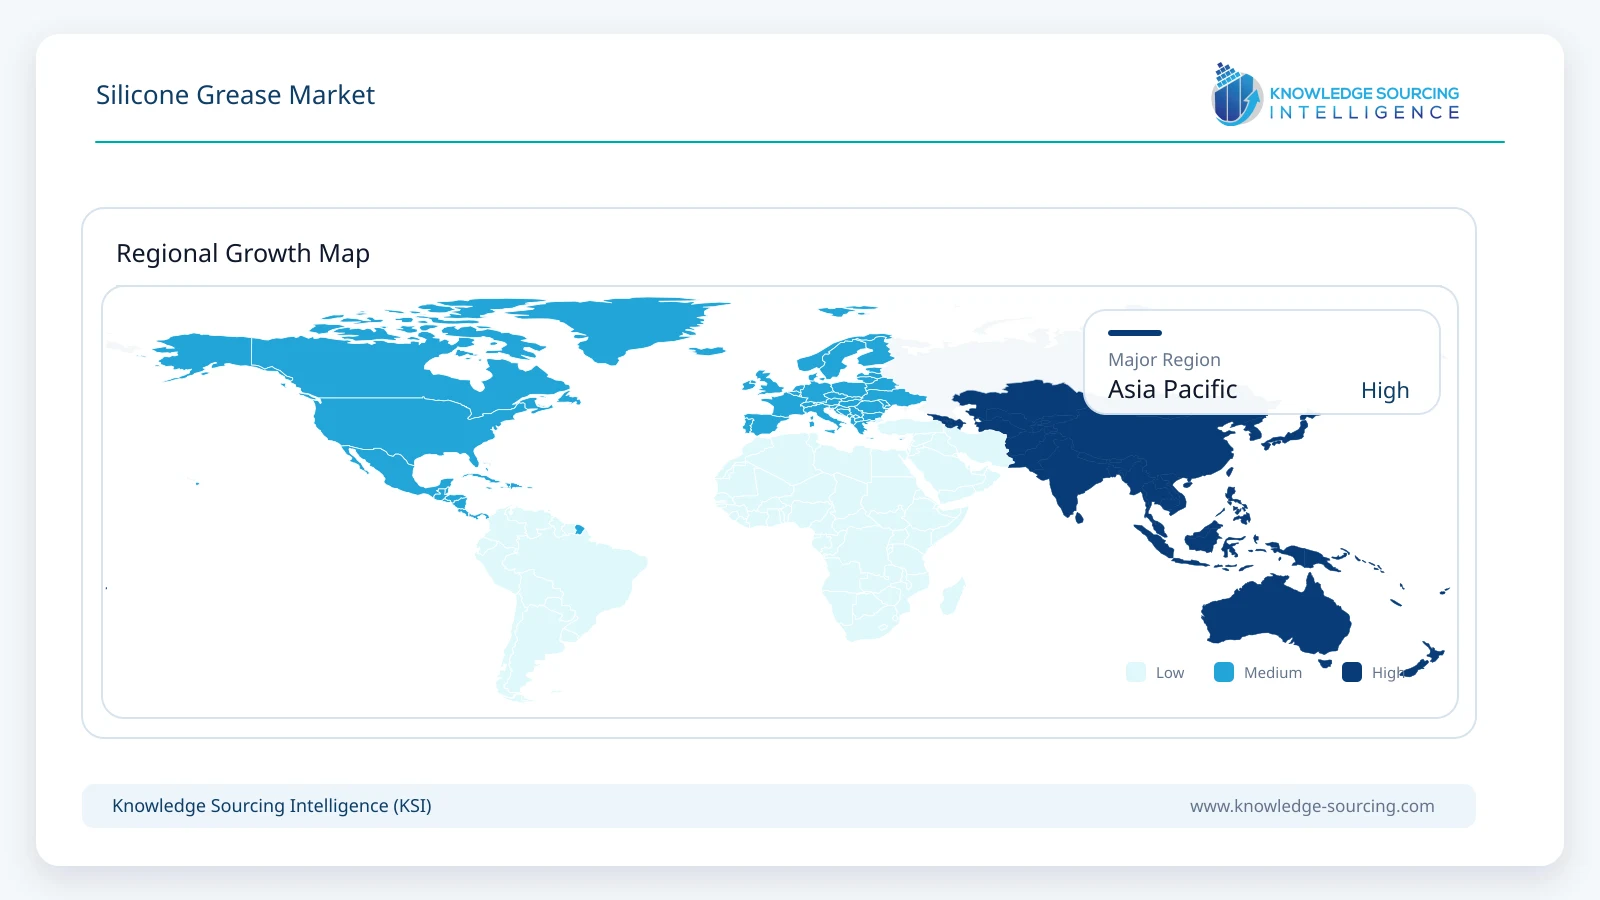
Asia Pacific produced approximately 59.2 million motor vehicles in 2025, more than 61% of global output, with China alone manufacturing 34.53 million units. The region also dominates semiconductor equipment investment: China, Taiwan and South Korea together represented 79% of worldwide semiconductor equipment spending in 2025, while China accounted for USD 49.3 billion. This combination supports demand for automotive dielectric greases, electronics thermal-interface materials, semiconductor-equipment lubricants and industrial sealing compounds. Japan additionally hosts major silicone technology suppliers such as Shin-Etsu and Momentive operations, while China and Southeast Asia continue expanding electronics and industrial production capacity.
Competitive Environment and Analysis
The silicone grease market combines large global silicone and specialty-chemical suppliers with lubricant specialists and application-focused thermal-management companies. DuPont’s MOLYKOTE portfolio covers automotive, industrial, electrical, semiconductor and food-processing lubrication, while Dow participates strongly in silicone thermal-management materials. Momentive and Shin-Etsu maintain significant electronics-oriented silicone portfolios, including thermally conductive grease and gel products, while Wacker has broad silicone-material capabilities. FUCHS participates through specialty Nye lubricant technologies, including medical-device silicone greases, and Parker Hannifin’s Chomerics division competes directly in high-performance thermal greases for electronic applications. Super Lube, Clearco and WEICON maintain broad industrial and maintenance-oriented portfolios covering O-rings, food machinery, electrical systems and sealing applications.
Competition is increasingly application-specific. High-volume general-purpose suppliers compete primarily on reliability, certifications, distribution and price, while electronics and semiconductor products compete on thermal conductivity, bond-line thickness, oil bleed, outgassing and dispensing behaviour. Automotive suppliers require extensive material compatibility and lifetime testing, while food, water and medical applications place greater emphasis on certification and documentation. This specialization limits direct substitution across product categories and allows smaller technical suppliers to maintain positions alongside global silicone producers.
Market Share Analysis
The market remains fragmented because silicone grease represents only one portion of the broader silicone, lubricant and thermal-interface portfolios of most major suppliers. DuPont maintains one of the broadest specialist grease portfolios through MOLYKOTE and has long-established positions across automotive and industrial applications, while Momentive and Shin-Etsu are particularly visible in thermal-management products. Dow benefits from substantial silicone-material expertise and is expanding high-conductivity electronics solutions, while FUCHS and Parker compete through more specialized lubricant and thermal-interface technologies. Regional and industrial suppliers including Super Lube, Clearco, WEICON and CHT maintain meaningful positions in general-purpose, food-grade, electrical and sealing applications.
Market share is consequently determined by application rather than total company size alone. Semiconductor and high-performance electronics customers prioritize thermal performance and contamination control, automotive suppliers value material compatibility and qualification history, and industrial users place greater emphasis on service temperature, water resistance and availability. Supplier concentration is therefore higher within individual technical niches than across the global silicone grease market as a whole.
Recent Developments
August 2026: DuPont showcased MOLYKOTE specialty lubricants at CSEAC 2026 in China alongside materials designed for advanced semiconductor manufacturing equipment.
May 2026: Dow launched DOWSIL TC-3120 Thermal Gel with approximately 12 W/m·K conductivity for optical modules, high-speed data equipment and dense electronics, demonstrating continued investment in high-performance silicone thermal interfaces.
2026: Parker Chomerics expanded its thermal-interface portfolio with four new silicone-based THERM-A-GREASE formulations providing thermal conductivity between approximately 1.5 and 7.0 W/m·K.
March 2026: MOLYKOTE G-5133M was highlighted as a PTFE- and intentionally added PFAS-free silicone grease capable of operating from approximately -73°C to 220°C across bearings, actuators, conveyors and valves.
November 2025: Shin-Etsu presented thermal-interface gap fillers and gel-grease technologies at PLASTIC JAPAN, reflecting continued development of silicone-based thermal-management materials.
July 2025: FUCHS introduced NYEMED 7312, a non-PFAS, silica-thickened silicone damping grease for medical-device applications.
Market Outlook
The global silicone grease market is forecast to increase from USD 1.166 billion in 2025 to USD 1.622 billion in 2031 at a CAGR of 5.66%. General-purpose lubrication and sealing remain the largest product category because silicone grease continues to provide a practical solution across O-rings, valves, plastics, elastomers and industrial equipment where water resistance and temperature stability are required. Automotive remains the largest application through 2031, supported by a global production base approaching 100 million vehicles annually and increasing electrical content in newer vehicle platforms. The market nevertheless becomes progressively more technically weighted toward dielectric and thermally conductive products as electronics, semiconductor manufacturing, AI computing infrastructure and electrified equipment expand.
Thermally conductive grease records the strongest product growth through the forecast period, while electrical and electronics applications grow faster than automotive and approach a similar market value by 2031. Silica-based formulations remain the leading thickener system, although lithium soap and lithium-complex formulations maintain important positions in dynamic automotive and industrial lubrication. Asia Pacific remains the largest and fastest-growing regional market because it combines more than 60% of global vehicle production with the majority of semiconductor-equipment investment and a substantial electronics manufacturing base. Competitive advantage through 2031 increasingly depends on application-specific formulation, reduced bleed and contamination, compatibility with plastics and elastomers, regulatory certification and the ability to maintain performance across wider thermal and electrical operating conditions.
Silicone Grease Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.232 billion |
| Total Market Size in 2031 | USD 1.622 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.66% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Thickener Type, Application, Geography |
| Companies |
|
Market Segmentation
BY PRODUCT TYPE
General-Purpose Lubricating and Sealing Silicone Grease
Dielectric and Electrical Silicone Grease
Thermally Conductive Silicone Grease
Food- and Water-Compatible Silicone Grease
Others
BY THICKENER TYPE
Silica-Based
Lithium Soap and Lithium Complex
PTFE and Fluorinated Systems
Others
BY APPLICATION
Automotive
Electrical and Electronics
Industrial Manufacturing
Oil, Gas and Chemical Processing
Food, Water and Sanitary Equipment
Others
BY GEOGRAPHY
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Market Estimation
2.4. Segment Modelling
2.5. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Silicone Grease Market Size, 2025-2031
3.3. Product Type Outlook
3.4. Thickener Type Outlook
3.5. Application Outlook
3.6. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Electronics and Semiconductor Manufacturing
4.1.2. Higher Automotive Production and Electrical Content per Vehicle
4.1.3. Demand for Reliable Lubrication Across Plastics, Elastomers and Wet Environments
4.2. Market Restraints
4.2.1. Competition from Alternative Thermal and Synthetic Lubricants
4.2.2. Application-Specific Qualification Requirements
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Regulatory and Certification Environment
5. TECHNOLOGICAL OUTLOOK
5.1. High-Conductivity Thermal Greases
5.2. Low-Bleed and Low-Outgassing Formulations
5.3. PFAS-Free Specialty Greases
5.4. Automated Dispensing and Thin Bond-Line Technologies
5.5. Dielectric and Connector Protection
6. SILICONE GREASE MARKET BY PRODUCT TYPE
6.1. Introduction
6.2. General-Purpose Lubricating and Sealing Silicone Grease
6.3. Dielectric and Electrical Silicone Grease
6.4. Thermally Conductive Silicone Grease
6.5. Food- and Water-Compatible Silicone Grease
6.6. Others
7. SILICONE GREASE MARKET BY THICKENER TYPE
7.1. Introduction
7.2. Silica-Based
7.3. Lithium Soap and Lithium Complex
7.4. PTFE and Fluorinated Systems
7.5. Others
8. SILICONE GREASE MARKET BY APPLICATION
8.1. Introduction
8.2. Automotive
8.3. Electrical and Electronics
8.4. Industrial Manufacturing
8.5. Oil, Gas and Chemical Processing
8.6. Food, Water and Sanitary Equipment
8.7. Others
9. SILICONE GREASE MARKET BY GEOGRAPHY
9.1. North America
9.1.1. USA
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. France
9.3.3. United Kingdom
9.3.4. Spain
9.3.5. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. India
9.5.4. South Korea
9.5.5. Taiwan
9.5.6. Thailand
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. DuPont de Nemours, Inc. / MOLYKOTE
11.2. Dow Inc.
11.3. Momentive Performance Materials Inc.
11.4. Shin-Etsu Chemical Co., Ltd.
11.5. Wacker Chemie AG
11.6. FUCHS SE / Nye Lubricants
11.7. Parker Hannifin Corporation / Chomerics
11.8. CHT Group
11.9. Avantor, Inc. / NuSil
11.10. Synco Chemical Corporation / Super Lube
11.11. Clearco Products Co., Inc.
11.12. WEICON GmbH & Co. KG
11.13. CRC Industries
11.14. Henkel AG & Co. KGaA
11.15. Shenzhen Tensan Co., Ltd.
12. APPENDIX
Navigate
Trusted by the world's leading organizations











