
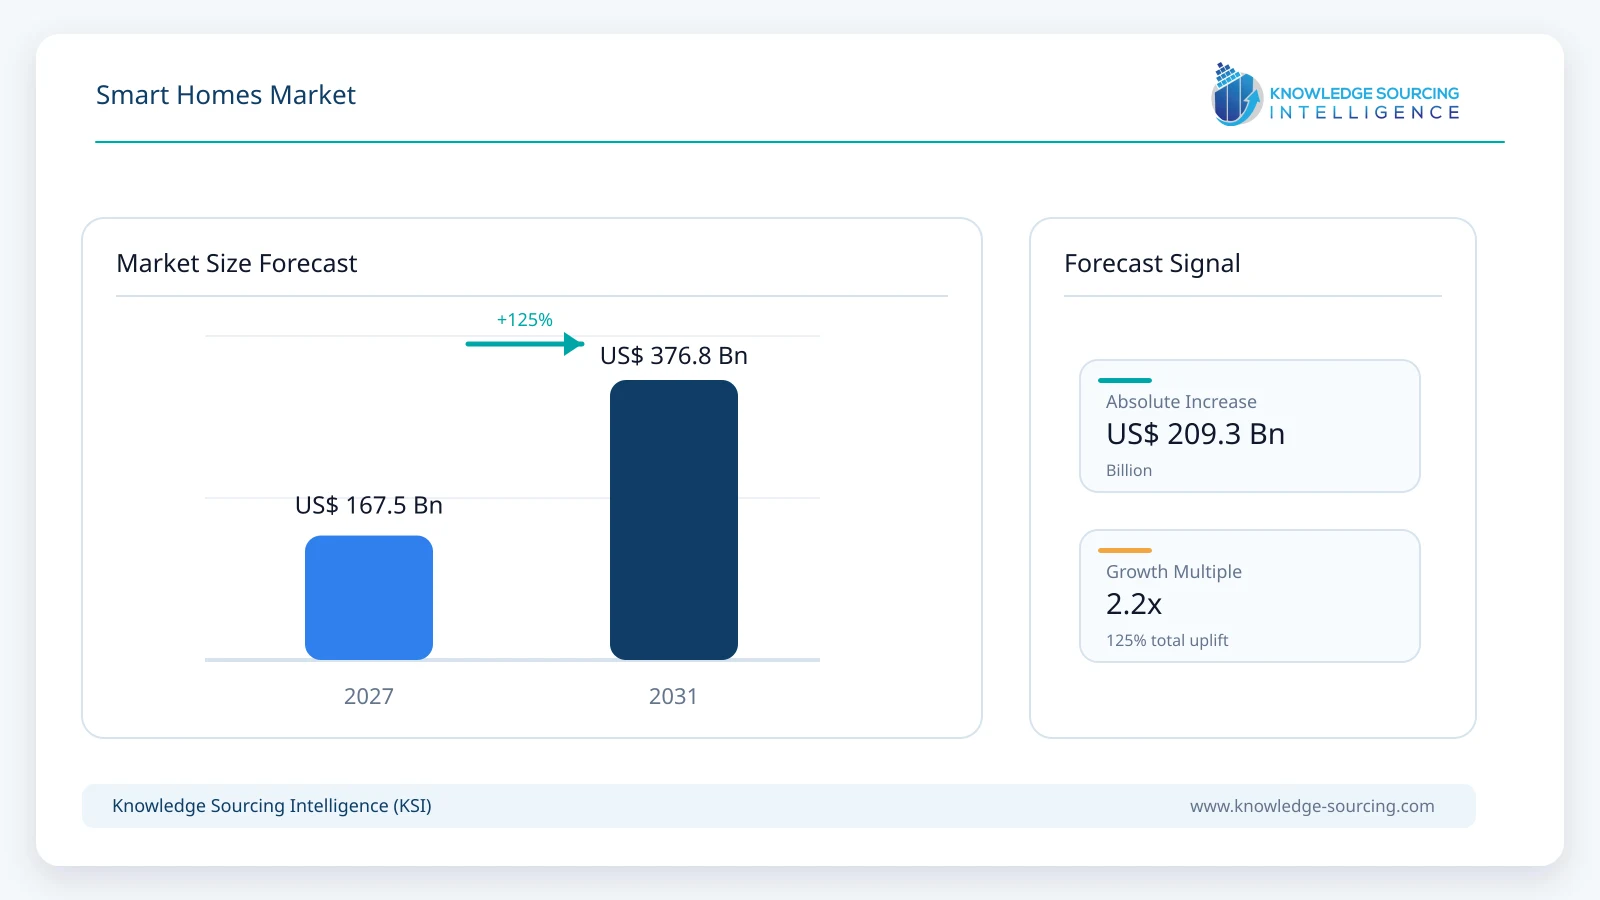
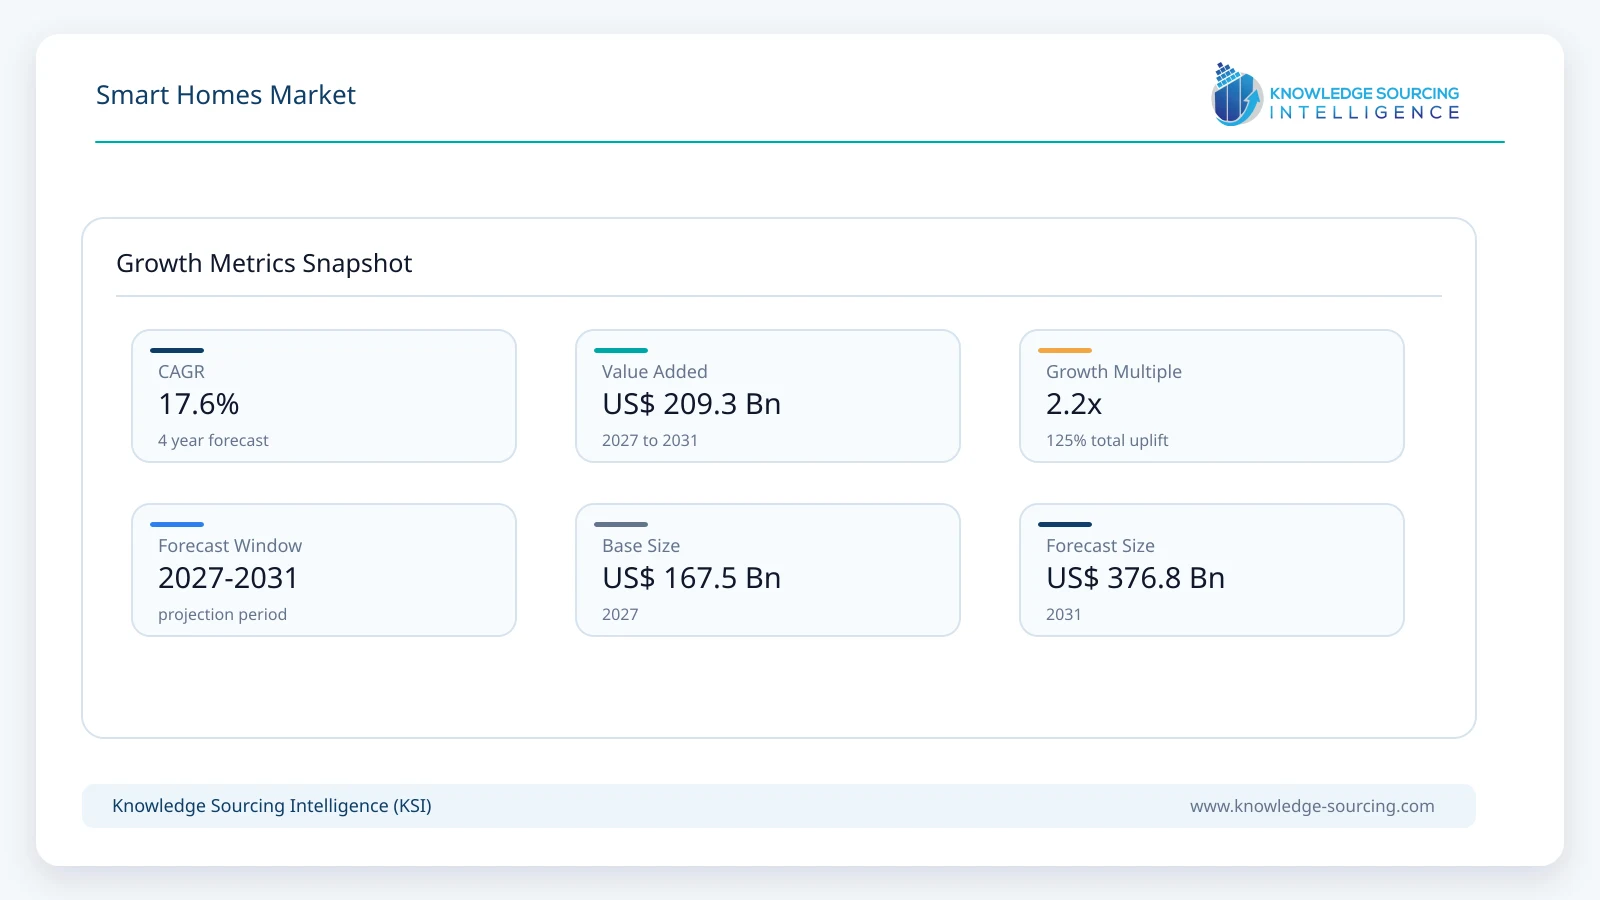
Global Smart Homes Market is forecast to grow at a CAGR of 17.6%, reaching USD 376.8 billion in 2031 from USD 167.5 billion in 2026.
Highlights:
- 1Growing adoption of connected home ecosystems is shifting demand toward interoperable and software-enabled smart home platforms.
- 2Energy management, security, and home automation remain the primary purchasing priorities across residential deployments.
- 3Matter-based interoperability is reducing ecosystem fragmentation and influencing product development across device manufacturers.
- 4Service providers are expanding installation and integration capabilities as buyers increasingly prefer turnkey smart home solutions.
- 5AI-enabled automation, predictive device management, and cloud connectivity are reshaping product differentiation and customer retention.
Demand is supported by several structural factors. Rising electricity costs are encouraging homeowners to adopt intelligent energy management systems capable of monitoring consumption and automating appliance schedules. Insurance providers in several markets increasingly recognize connected security systems as risk-reduction tools, while ageing populations are creating demand for remote health monitoring and assisted living technologies. These purchasing drivers have expanded the addressable customer base beyond technology enthusiasts to include mainstream homeowners, residential developers, landlords, and property management firms.
Value creation within the market extends across device manufacturers, semiconductor suppliers, software developers, cloud platform providers, telecommunications companies, installers, and managed service providers. Hardware remains an important revenue contributor, yet recurring income from software subscriptions, cloud services, maintenance, cybersecurity updates, and device management continues to increase. Suppliers are therefore expanding ecosystem capabilities rather than competing solely on hardware pricing.
Competition is increasingly shaped by ecosystem integration instead of individual product performance. Major technology companies continue to strengthen voice assistants, cloud platforms, artificial intelligence capabilities, and developer ecosystems to improve customer retention. At the same time, building automation specialists are extending their residential offerings by combining energy management, security, lighting, and climate control into unified home platforms that address both consumer convenience and operational efficiency.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Matter ecosystem | More than 775 certified device types (2025) | Broader interoperability reduces compatibility concerns and encourages wider smart home adoption. |
Connected devices | Billions of IoT devices remain in active global deployment (ITU and industry standards bodies) | Expanding connected infrastructure supports long-term demand for integrated residential automation. |
Global electricity efficiency focus | Governments continue strengthening residential energy-efficiency initiatives (IEA) | Higher household energy management demand supports intelligent lighting, HVAC, and energy management systems. |
AI-enabled consumer devices | Major technology vendors continue integrating on-device and cloud AI across consumer ecosystems (company disclosures, 2025-2026) | AI-driven automation is becoming an important product differentiation factor. |
Matter ecosystem members | Hundreds of companies participate in the Connectivity Standards Alliance | Industry-wide collaboration lowers interoperability barriers and expands compatible product portfolios. |
Key indicator: Matter certification continues expanding across hundreds of manufacturers and device categories.
Commercial meaning: Improved interoperability reduces ecosystem fragmentation, simplifying purchasing decisions for residential buyers.
Market Drivers
Expansion of interoperable smart home ecosystems through Matter standard
Compatibility has historically limited smart home adoption because consumers often had to commit to a single technology ecosystem. The Connectivity Standards Alliance has addressed this challenge through the Matter standard, which enables certified devices from multiple manufacturers to communicate using common protocols. Official CSA updates show continued expansion of certified products and participating manufacturers. Amazon, Google, Apple, Samsung, Schneider Electric, LG Electronics, and other ecosystem participants continue integrating Matter compatibility into their product portfolios. Reduced compatibility risk improves consumer confidence, shortens purchase evaluation cycles, and encourages multi-device deployments instead of isolated product purchases.
Residential energy management is becoming a primary investment priority
Electricity price volatility and national energy-efficiency policies are changing household purchasing priorities. Rather than installing individual smart devices for convenience, homeowners increasingly seek integrated systems capable of monitoring electricity consumption, scheduling appliance operation, optimizing HVAC performance, and supporting distributed energy resources such as rooftop solar and battery storage. The International Energy Agency continues to identify digital energy management as an important contributor to building efficiency improvements. Schneider Electric, Siemens, Honeywell, and other building technology providers have expanded residential energy management offerings that combine connected sensors, automation software, and intelligent control systems. These investments reflect growing customer demand for measurable reductions in household operating costs rather than simple automation features.
Growing demand for residential security and remote property monitoring
Security remains one of the strongest commercial justifications for smart home investment. Consumers increasingly purchase integrated surveillance cameras, smart locks, motion sensors, and video doorbells that allow continuous remote monitoring through mobile applications. Amazon, Google, Samsung, LG Electronics, and Honeywell continue expanding connected security portfolios while improving cloud storage, AI-enabled video analytics, and notification capabilities. Insurance incentives in selected markets, together with rising consumer awareness of home security risks, support replacement of conventional alarm systems with connected security platforms that deliver continuous monitoring, remote access, and software-based feature updates throughout the product lifecycle.
Artificial intelligence is increasing platform value rather than hardware complexity
Artificial intelligence is changing how smart homes operate by enabling predictive automation instead of simple rule-based control. Device manufacturers increasingly integrate AI into lighting, entertainment systems, climate control, appliances, and home assistants to learn occupant behavior and optimize system performance. Google, Samsung, Apple, Amazon, and LG Electronics have expanded AI functionality across consumer electronics ecosystems through both cloud-based and on-device processing. This improves customer retention because users gain more value from expanding within the same ecosystem rather than purchasing unrelated devices from competing vendors. AI also creates opportunities for premium software subscriptions, predictive maintenance services, and personalized home automation experiences.
Market Restraints and Challenges
Cybersecurity requirements continue increasing deployment complexity
Every connected device expands the potential attack surface within residential networks. Manufacturers therefore face rising costs associated with secure software development, encryption, authentication, vulnerability testing, and long-term firmware support. Regulatory agencies across multiple jurisdictions continue strengthening cybersecurity expectations for connected consumer products. Major technology vendors have increased investment in secure device management and software updates, while consumers increasingly evaluate vendors based on their ability to provide ongoing security support throughout the product lifecycle. Smaller manufacturers often face higher compliance costs because maintaining long-term security updates requires continuous engineering resources beyond initial product development.
Ecosystem fragmentation remains despite improving interoperability
Although Matter has improved cross-platform compatibility, legacy devices, proprietary communication protocols, and vendor-specific software features continue creating integration challenges. Many existing residential installations still combine products using Zigbee, Z-Wave, Wi-Fi, Bluetooth, Thread, and proprietary standards, making complete interoperability difficult. Consumers upgrading older systems frequently encounter compatibility limitations that increase installation costs and complicate purchasing decisions. System integrators therefore remain essential for larger residential projects where multiple communication technologies must operate together without affecting performance or security.
Professional installation requirements increase ownership costs
Basic connected devices are often suitable for self-installation, but integrated smart homes involving lighting controls, HVAC automation, energy management, surveillance, access control, and distributed networking generally require professional design and installation. Labour shortages affecting qualified electricians, automation specialists, and network technicians can extend project timelines and increase deployment costs, particularly in premium residential developments. Service providers continue expanding installation, integration, and managed support offerings to address these challenges, yet installation expenses remain an important purchasing consideration for consumers evaluating comprehensive home automation projects.
Long product lifecycles complicate software maintenance and customer expectations
Residential automation systems typically remain operational for many years, while software platforms evolve much more rapidly. Manufacturers must therefore provide firmware updates, cloud compatibility, cybersecurity patches, and application support long after hardware has been sold. Company disclosures from major technology providers consistently highlight continued investment in software engineering, cloud infrastructure, and ecosystem maintenance. These ongoing obligations increase lifecycle costs and place additional pressure on manufacturers that compete primarily through low-cost hardware rather than recurring software and service revenues.
Major Segment Analysis
Smart Security and Surveillance
Smart Security and Surveillance represents one of the most commercially important product categories because it addresses a clearly measurable household requirement: protecting residential property while enabling continuous remote monitoring. Demand extends across homeowners, apartment residents, residential developers, landlords, and property management companies. Purchasing decisions increasingly emphasize real-time mobile access, high-definition video quality, artificial intelligence-enabled event detection, encrypted cloud storage, and compatibility with broader smart home ecosystems rather than individual device specifications.
The segment is also benefiting from ecosystem integration. Video doorbells, smart locks, cameras, motion detectors, and alarm systems increasingly operate through unified mobile applications alongside lighting, voice assistants, and home automation platforms. Amazon, Google, Honeywell, Samsung Electronics, LG Electronics, and Apple continue expanding software capabilities that improve user experience and encourage customers to remain within a single ecosystem. Despite growing demand, privacy concerns, cybersecurity obligations, and subscription costs remain important evaluation factors for buyers. Vendors therefore compete through software reliability, cloud services, device interoperability, and long-term security support as much as through hardware innovation.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Mature connected-home adoption, broadband availability, ecosystem expansion | Privacy expectations and cybersecurity compliance |
Europe | Energy-efficiency rules, smart building initiatives, residential renovation | Data protection requirements and fragmented housing stock |
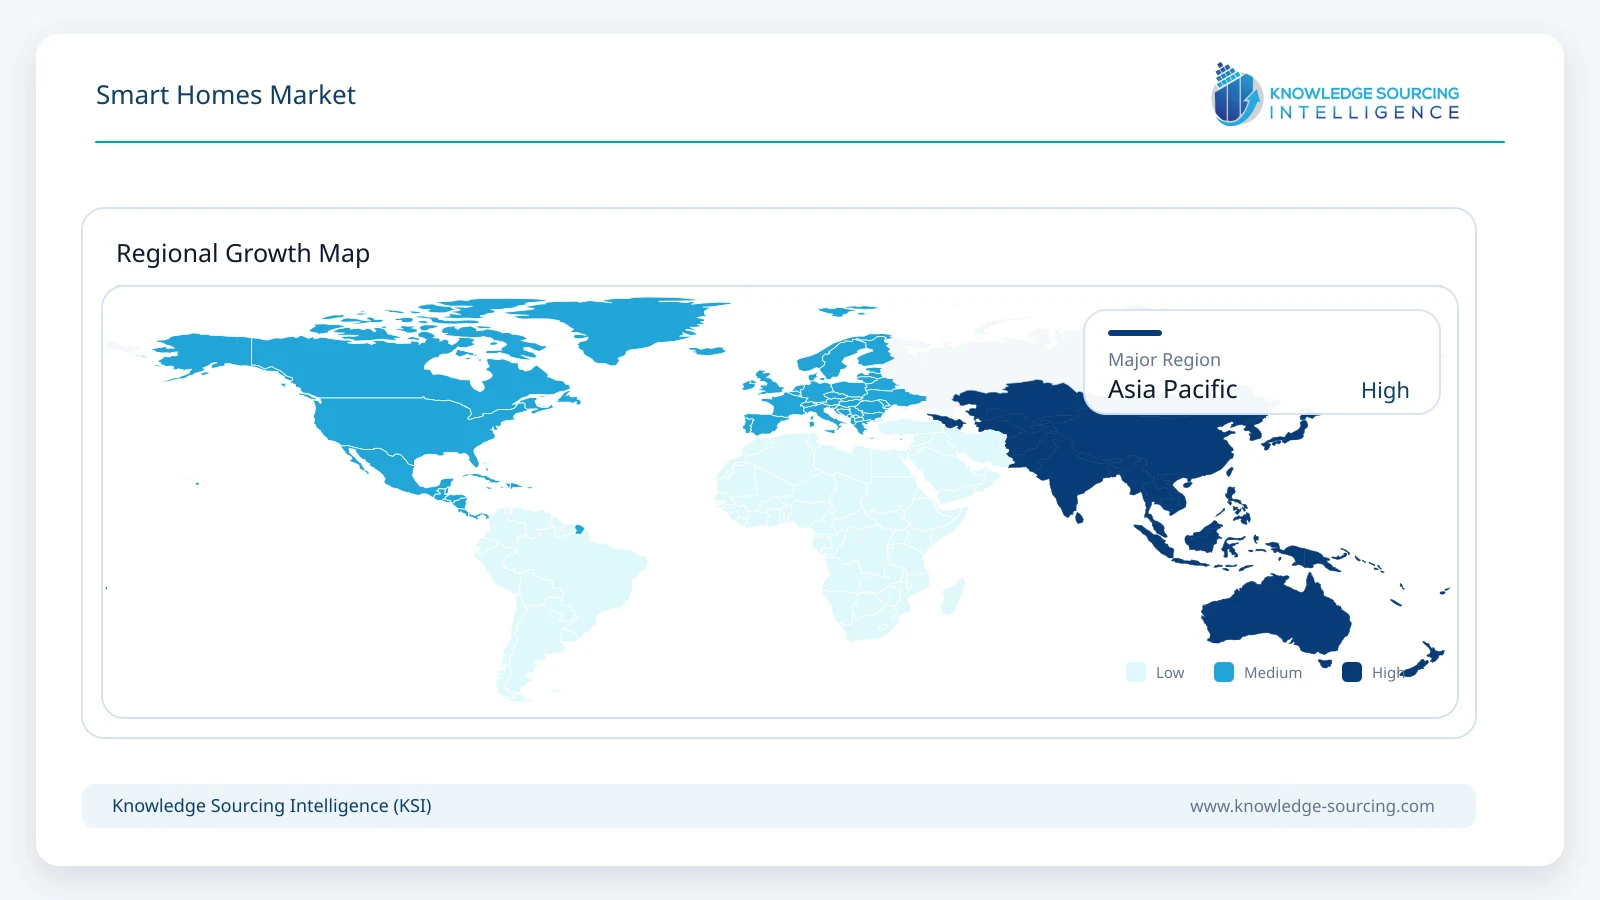
Asia Pacific | Urban housing growth, expanding broadband, consumer electronics manufacturing | Wide income differences and interoperability challenges |
Middle East and Africa | Smart city investment and premium residential developments | Limited adoption outside higher-income urban markets |
North America
North America continues to represent one of the most mature smart home markets because of high broadband penetration, widespread smartphone ownership, and early adoption of connected consumer technologies. The United States accounts for most regional demand, supported by established technology ecosystems from Amazon, Apple, Google, Honeywell, and Crestron Electronics. Residential buyers increasingly prioritize integrated security, voice control, intelligent climate management, and energy optimization rather than standalone connected devices. Utilities in several states also encourage demand for connected thermostats and energy management systems through efficiency programmes and demand-response initiatives.
Europe
European demand is closely linked to building efficiency, decarbonization objectives, and residential renovation programmes. European Union energy-performance policies continue encouraging deployment of intelligent heating, lighting, and building management technologies that reduce household energy consumption. Germany, the United Kingdom, and France remain commercially important markets because of relatively high digital connectivity and consumer willingness to invest in energy-saving technologies. Data protection requirements under the General Data Protection Regulation (GDPR) also influence product design, cloud storage practices, and cybersecurity investments across suppliers serving European customers.
Asia Pacific
Asia Pacific combines expanding consumer demand with one of the world's largest electronics manufacturing bases. China, Japan, South Korea, and India account for much of regional activity through domestic production, rising household connectivity, expanding broadband infrastructure, and growing middle-income populations. Samsung Electronics, LG Electronics, and several regional manufacturers continue strengthening AI-enabled consumer ecosystems while governments promote digital infrastructure and energy-efficient buildings. Rapid urban residential construction also creates opportunities for developers to incorporate connected lighting, access control, surveillance, and energy management during new housing projects rather than through later retrofits.
Middle East and Africa
Demand across the Middle East and Africa remains concentrated in premium residential developments, smart city initiatives, and high-income urban markets. Countries including the United Arab Emirates, Saudi Arabia, and Israel continue investing in digital infrastructure and intelligent building technologies that support connected residential environments. Outside these markets, adoption remains constrained by affordability, uneven broadband access, and limited availability of specialized installation services. Suppliers therefore focus on premium developments, integrated residential communities, and projects where building automation forms part of wider digital infrastructure investments.
Competitive Landscape
Competition within the global smart homes market is technology-led but increasingly ecosystem-driven. Consumer technology companies compete by expanding software platforms, artificial intelligence capabilities, cloud services, and cross-device compatibility, while traditional building automation companies differentiate through integrated energy management, security, and building control solutions. Switching costs increase as households accumulate compatible devices within a single ecosystem, encouraging suppliers to strengthen long-term customer retention through software updates, subscription services, and platform expansion.
Amazon.com, Google LLC, Apple Inc., Samsung Electronics, and LG Electronics continue investing in AI-enabled consumer ecosystems that combine smart speakers, entertainment systems, appliances, security devices, and cloud services. Siemens AG, Schneider Electric, Crestron Electronics, and Lutron Electronics focus on integrated residential automation, lighting controls, energy optimization, and professional installation networks. Competition increasingly depends on interoperability, cybersecurity, software reliability, installation support, and ecosystem breadth rather than hardware pricing alone. Participation in Matter certification also reflects an industry-wide effort to reduce compatibility barriers while maintaining platform differentiation through software and value-added services.
Recent Developments
September 2026: Aqara showcased its new Smart Lighting Series at IFA 2026, expanding Matter-compatible lighting across indoor and outdoor applications while strengthening interoperability across major smart-home platforms.
September 2026: tado° launched Smart Thermostat X (2nd gen), featuring Matter and Thread compatibility, rechargeable battery operation, AI-assisted heating optimisation, and support for boilers, heat pumps, and underfloor heating.
September 2026: UGREEN debuted its HomeAgent-based AIoT ecosystem at IFA 2026, combining local AI, smart-home coordination, cameras, smart speakers, and connected devices for more intelligent residential automation.
June 2026: Google launched the Google Home Speaker, its first speaker built for Gemini for Home, enabling more natural conversations and multi-step interactions for controlling connected smart-home devices.
April 2026: Samsung expanded SmartThings integration with 25 IKEA Matter-over-Thread devices, including smart bulbs, plugs, sensors, and controls, enabling broader interoperability across connected-home ecosystems.
Regulatory and Policy Environment
Residential smart home deployment is increasingly influenced by cybersecurity rules, energy-efficiency regulations, wireless communication standards, and consumer data protection requirements rather than product-specific legislation alone. Governments across North America, Europe, and Asia continue strengthening digital security expectations for connected consumer products, requiring manufacturers to improve software maintenance, vulnerability management, and secure authentication throughout product lifecycles.
Energy policy is also affecting purchasing behaviour. Building efficiency programmes, demand-response initiatives, and national decarbonization objectives encourage adoption of intelligent lighting, HVAC controls, and energy management systems that reduce electricity consumption. The European Union continues to support smarter building operation through energy performance legislation, while utilities in several countries provide incentives for connected energy management technologies that improve grid flexibility.
Industry standards are becoming equally important. The Matter interoperability standard, developed through the Connectivity Standards Alliance, provides a common communication framework that reduces compatibility barriers across manufacturers. Broader adoption of standardized communication protocols lowers integration complexity for installers while improving long-term product compatibility for consumers. Compliance with these standards increasingly influences procurement decisions, product development priorities, and ecosystem partnerships across the industry.
Outlook and Strategic Implications
The market outlook through 2031 will depend less on the number of connected devices entering households and more on the value generated through integrated ecosystems. Buyers increasingly expect lighting, security, entertainment, climate control, healthcare monitoring, and energy management to function as coordinated services rather than separate products. Artificial intelligence, cloud computing, and standardized interoperability are therefore expected to become stronger competitive differentiators than incremental hardware improvements.
Several strategic implications are emerging:
Manufacturers will continue expanding software capabilities, AI functions, and cybersecurity investments to increase recurring revenue and customer retention.
Installation and integration providers are expected to benefit from growing demand for professionally managed residential automation projects.
Utilities and energy service providers are likely to strengthen partnerships with smart home technology vendors to improve residential energy efficiency and demand-side management.
Residential developers are increasingly incorporating connected infrastructure during construction, reducing retrofit costs and improving long-term property value.
Technology providers that support open standards, long-term software maintenance, and cross-platform compatibility are likely to strengthen their competitive position as buyers prioritize ecosystem flexibility over standalone device features.
The competitive environment is expected to remain dynamic throughout the forecast period. Companies capable of combining secure software platforms, reliable interoperability, energy optimization, and comprehensive service support will be better positioned to capture value as residential automation evolves into a fully integrated digital home ecosystem.
Smart Homes Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 167.5 billion |
| Total Market Size in 2031 | USD 376.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 17.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Products, Services, Geography |
| Companies |
|
Market Segmentation
By Products
- Smart Security and Surveillance
- Smart Lighting and Electrical Devices
- Smart Access Control
- Smart HVAC and Climate Control
- Smart Home Appliances
- Smart Energy Management
- Smart Entertainment and Media Devices
- Smart Window Coverings
- Smart Home Hubs, Controllers, and Gateways
- Others
By Services
- Installation and Integration
- Consulting and Design
- Maintenance and Support
- Monitoring and Subscription Services
- Managed Services
By Geography
- North America
- USA
- Canada
- Others
- South America
- Brazil
- Argentina
- Others
- Europe
- Germany
- United Kingdom
- France
- Others
- Middle East and Africa
- Israel
- UAE
- Saudi Arabia
- Others
- Asia Pacific
- China
- South Korea
- Japan
- India
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Currency
1.5. Assumptions
1.6. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Sources
2.3. Data Collection and Validation
2.4. Market Estimation and Forecasting
3. EXECUTIVE SUMMARY
4. MARKET DYNAMICS
4.1. Market Segmentation
4.2. Market Drivers
4.3. Market Restraints
4.4. Market Opportunities
4.5. Porter’s Five Forces Analysis
4.5.1. Bargaining Power of Suppliers
4.5.2. Bargaining Power of Buyers
4.5.3. Threat of New Entrants
4.5.4. Threat of Substitutes
4.5.5. Competitive Rivalry
4.6. Market Life Cycle Analysis – Regional Snapshot
4.7. Market Attractiveness
5. GLOBAL SMART HOMES MARKET BY PRODUCTS
5.1. Smart Security and Surveillance
5.2. Smart Lighting and Electrical Devices
5.3. Smart Access Control
5.4. Smart HVAC and Climate Control
5.5. Smart Home Appliances
5.6. Smart Energy Management
5.7. Smart Entertainment and Media Devices
5.8. Smart Window Coverings
5.9. Smart Home Hubs, Controllers, and Gateways
5.10. Others
6. GLOBAL SMART HOMES MARKET BY SERVICES
6.1. Installation and Integration
6.2. Consulting and Design
6.3. Maintenance and Support
6.4. Monitoring and Subscription Services
6.5. Managed Services
7. GLOBAL SMART HOMES MARKET BY GEOGRAPHY
7.1. North America
7.1.1. USA
7.1.2. Canada
7.1.3. Others
7.2. South America
7.2.1. Brazil
7.2.2. Argentina
7.2.3. Others
7.3. Europe
7.3.1. Germany
7.3.2. United Kingdom
7.3.3. France
7.3.4. Others
7.4. Middle East and Africa
7.4.1. Israel
7.4.2. UAE
7.4.3. Saudi Arabia
7.4.4. Others
7.5. Asia Pacific
7.5.1. China
7.5.2. South Korea
7.5.3. Japan
7.5.4. India
7.5.5. Others
8. COMPETITIVE INTELLIGENCE
8.1. Company Benchmarking and Analysis
8.2. Recent Investment and Deals
8.3. Strategies of Key Players
9. COMPANY PROFILES
9.1. Siemens AG
9.2. Resideo Technologies, Inc.
9.3. Lutron Electronics Co., Inc.
9.4. Amazon.com, Inc.
9.5. Google LLC
9.6. Schneider Electric SE
9.7. Apple Inc.
9.8. Crestron Electronics, Inc.
9.9. Samsung Electronics Co., Ltd.
9.10. LG Electronics Inc.
Navigate
Trusted by the world's leading organizations











