
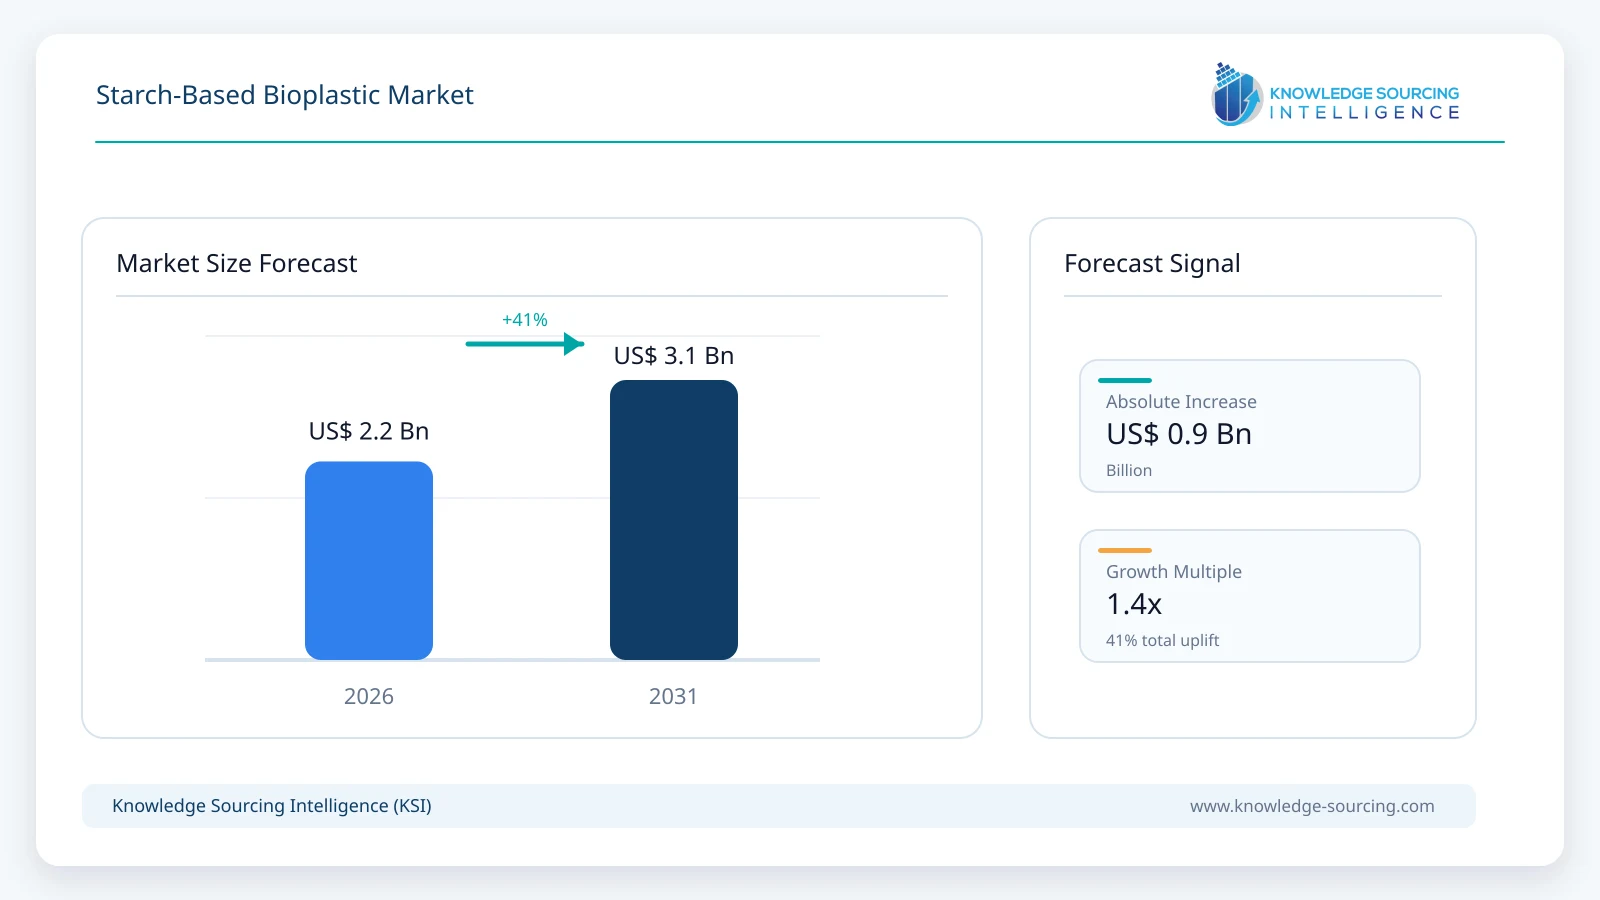
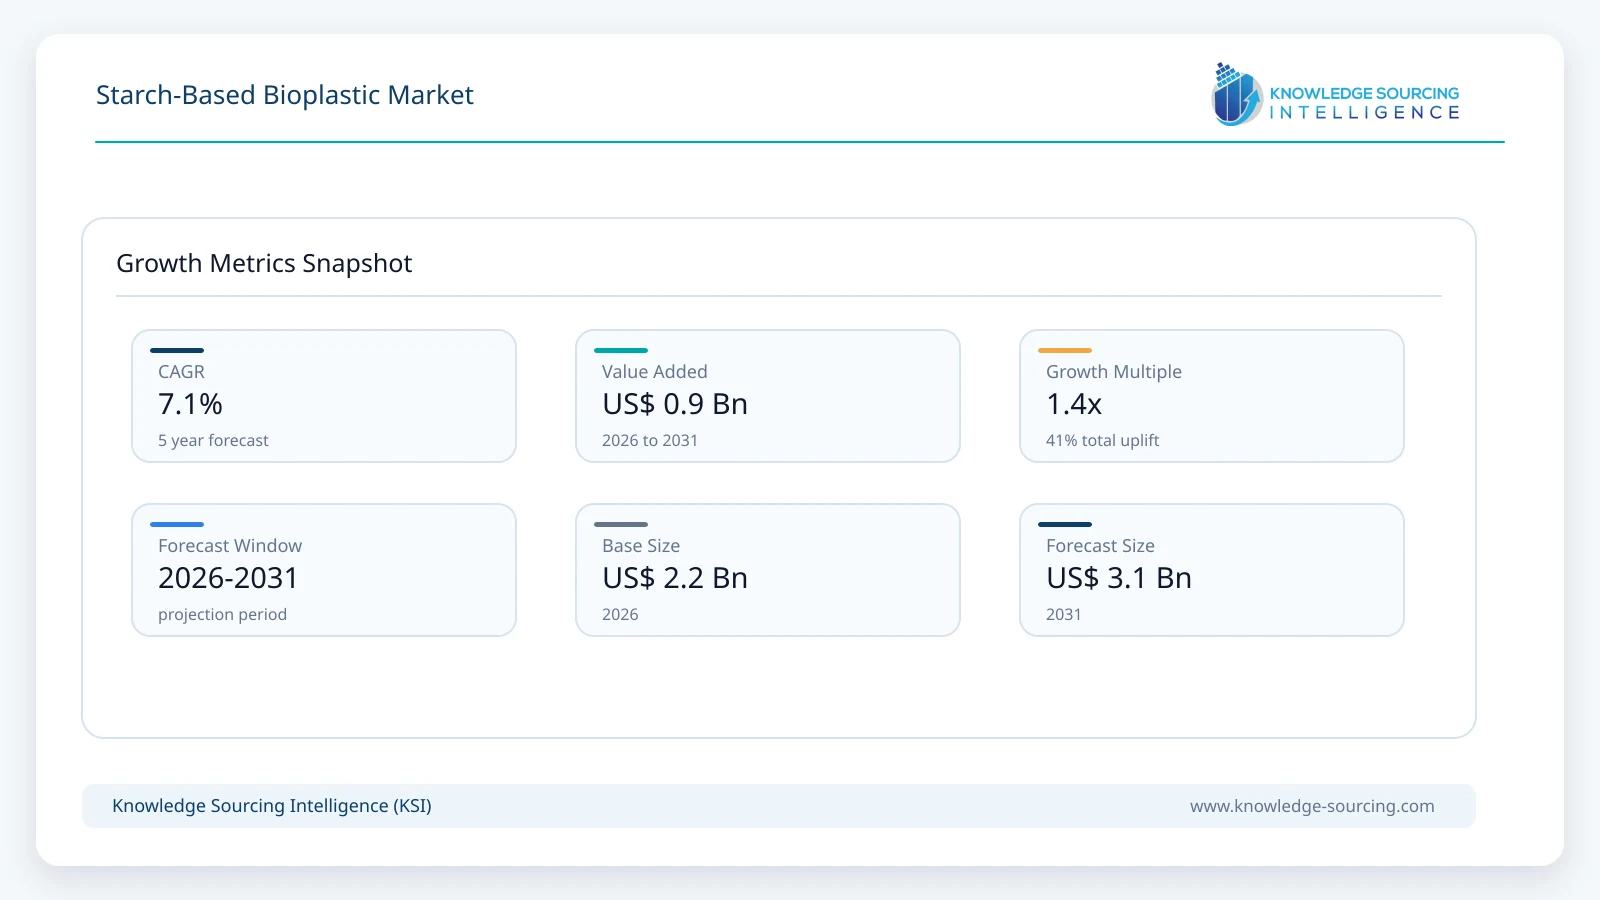
The global starch-based bioplastic market is forecast to grow from USD 2.17 billion in 2026 to USD 3.06 billion by 2031, representing a CAGR of approximately 7.1% during the forecast period.
Highlights:
- 1Starch-polyester blends account for approximately 68% of global market value in 2026, supported by their use in flexible films, compostable bags and higher-performance packaging.
- 2Corn-based starch accounts for approximately 44% of market value in 2026, reflecting established industrial availability in North America, China and other large agricultural markets.
- 3Packaging accounts for approximately 56% of global demand in 2026, led by flexible films, organic-waste bags, produce bags and specialty food packaging.
- 4Food and beverage accounts for approximately 43% of end-user demand in 2026, supported by compostable service formats and starch-based barrier packaging.
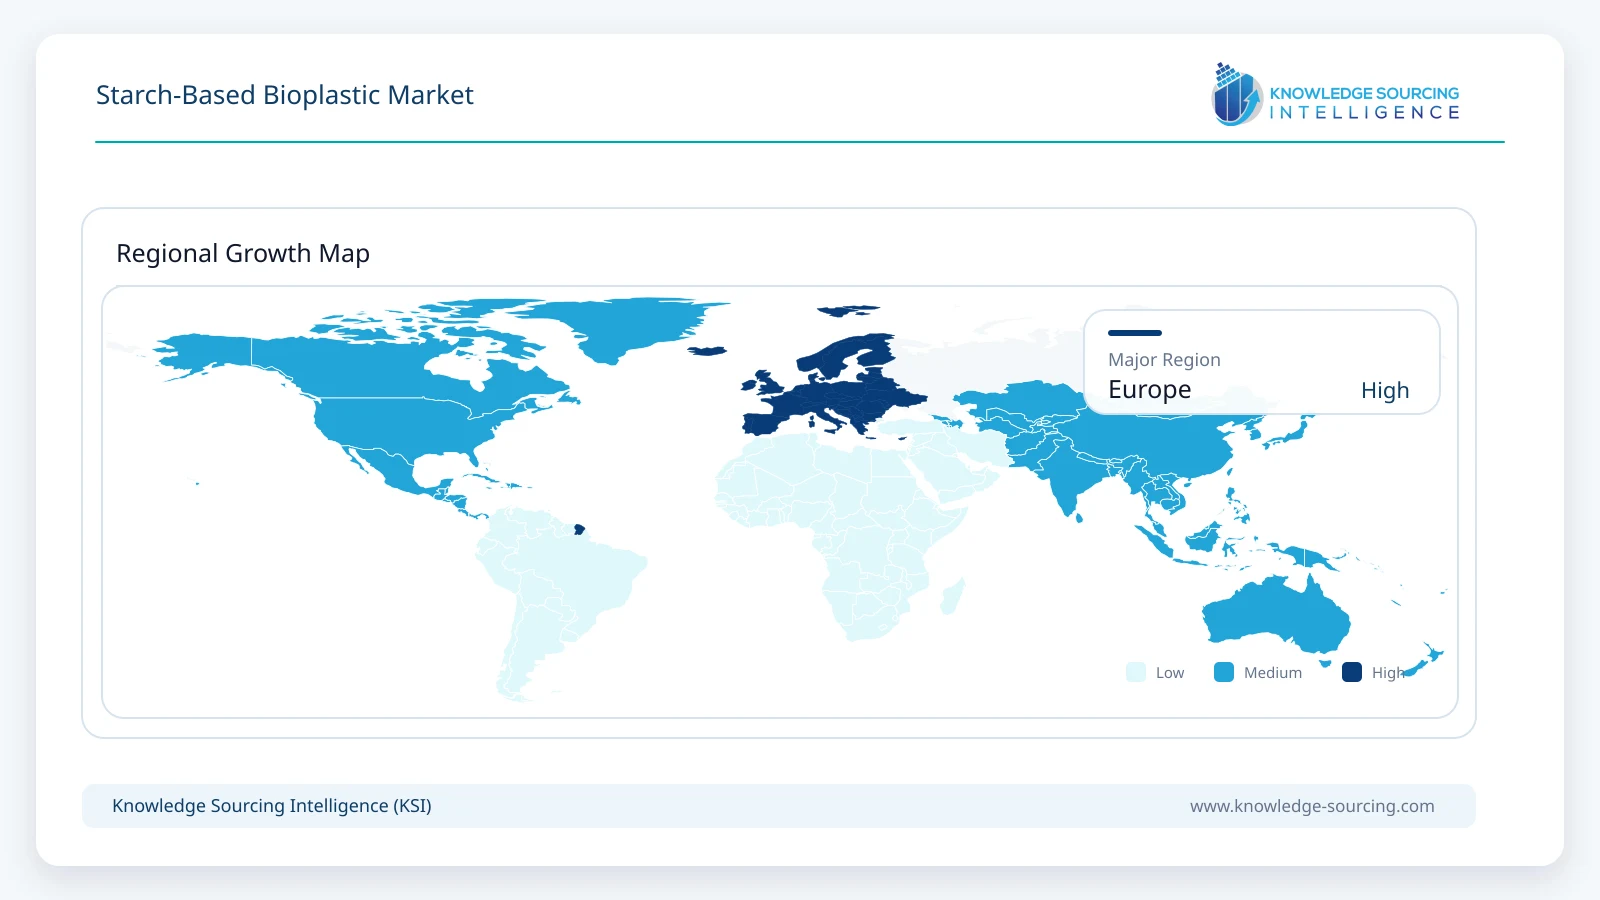
- 5Europe accounts for approximately 35% of global market value in 2026, supported by established composting systems, certified material suppliers and application-specific regulation.
The starch-based bioplastic demand is strongest where compostability or biological end-of-life routes offer a practical advantage over conventional plastics. Organic-waste bags, produce bags, selected food-service formats and agricultural mulch films are established applications because they can be collected with food or crop residues, or biodegrade in soil where certified for that use. Flexible packaging is also broadening beyond basic bags as suppliers improve barrier performance, printability, sealing and compatibility with standard converting equipment.
Government regulations are deciding the application choice rather than creating a blanket requirement for bio-based plastics. The EU Packaging and Packaging Waste Regulation became applicable from August 2026 and restricts mandatory compostability to selected formats while requiring most other packaging, including biodegradable plastic packaging, to be designed for material recycling. This favors starch-based materials where compostability is functionally justified and places greater pressure on suppliers to match resin design with the actual waste-management route.
Market Trends
Starch-Polyester Blends Consolidate Their Position
Starch is increasingly used as part of engineered compounds rather than as a standalone resin. Novamont's MATER-BI, AGRANA's AGENACOMP, BIOTEC's BIOPLAST grades and FKuR's Ceroflex illustrate the commercial shift toward blends that combine starch with biodegradable polymers to improve film strength, flexibility and processability. The result is a broader application range across shopping and produce bags, food-contact films, organic-waste liners and agricultural mulch. The strongest products are those that can run on conventional blown-film or extrusion equipment while maintaining certified compostability at the required thickness.
Barrier Packaging Broadens the Addressable Market
Starch-based materials are moving beyond simple carrier bags into barrier structures for dry food, fresh food and specialty packaging. Kuraray's PLANTIC portfolio uses a high-amylose starch-derived barrier layer in mono-material and laminated formats, while its 2026 Interpack portfolio introduced PLANTIC EP in pellet form for paper and flexible packaging applications. This expands the role of starch from bulk renewable filler to a functional barrier material, particularly where oxygen or aroma protection is needed alongside renewable content or compostability.
Home-Compostable Grades Gain Commercial Relevance
Suppliers are widening home-compostable portfolios for markets where industrial composting access is limited or where national rules favor certified home-compostable formats. AGRANA's AGENACOMP and several BIOTEC BIOPLAST grades are positioned around home-compostable films, while FKuR markets Ceroflex for certified home-compostable bags and produce films. This segment remains more technically demanding than industrial compostability because decomposition must occur under less controlled conditions, making thickness, material formulation and certification central to product differentiation.
Agricultural Applications Become More Specialized
Soil-biodegradable mulch films, plant clips and related agricultural products remain one of the clearest use cases for starch-based bioplastics because retrieval of conventional plastic films can be costly and incomplete. Novamont has extended MATER-BI into certified soil-biodegradable mulch and horticultural products, while AGRANA markets starch-based materials for mulch-film applications. Growth is tied to certification and agronomic performance rather than broad substitution of all agricultural plastics, which keeps the segment commercially focused on applications where removal and contamination costs are material.
Market Drivers
Organic-Waste Collection Supports Certified Compostable Films
Municipal and commercial food-waste collection creates a recurring market for compostable bags that can enter organics-processing streams with their contents. Novamont's MATER-BI is widely used in this application through BioBag and other converters, while BIOTEC and FKuR offer starch-based film grades designed for waste bags and liners. Demand is strongest where local collection rules explicitly permit certified compostable bags and where composting or anaerobic-digestion facilities can process them without disrupting the waste stream.
Food Packaging Seeks Higher Renewable Content Without Losing Performance
Food and beverage companies are under pressure to reduce fossil-material use while maintaining shelf life, sealing performance and compatibility with existing packaging lines. Starch-based compounds can raise renewable content while biodegradable polyesters provide the mechanical properties needed for commercial use. Kuraray's starch-derived PLANTIC barrier materials, AGRANA's AGENACOMP compounds and BIOTEC's film grades demonstrate how suppliers are targeting higher-value packaging rather than relying only on commodity disposable items.
Agriculture Provides a Practical End-of-Life Use Case
Conventional mulch films can leave plastic residues when collection is incomplete, particularly after long crop cycles or on large fields. Certified soil-biodegradable alternatives reduce the need for film recovery in selected applications and allow growers to incorporate the material into soil according to product instructions. This creates demand for formulations that maintain mechanical integrity during the crop cycle but meet recognized biodegradation standards after use.
Market Restraints and Challenges
Moisture Sensitivity Restricts Some Applications
Starch-rich materials remain more sensitive to water and humidity than many conventional polymers. Suppliers address the issue through polyester blending, multilayer structures, coatings and starch modification, but these steps add formulation complexity and can reduce the proportion of renewable content. Applications involving long shelf life, liquid contact or demanding tropical logistics therefore require more engineered structures than basic thermoplastic starch can provide.
End-of-Life Infrastructure Remains Uneven
Certified compostability does not guarantee that a product will reach a composting facility. Many markets lack separate bio-waste collection, industrial composting capacity or clear acceptance rules for compostable plastics. This limits the environmental and commercial value proposition for products designed primarily around organic recycling. The mismatch is especially important for packaging, where regulators increasingly require materials to be designed around the waste-management system that actually exists rather than around a theoretical disposal route.
Competing Biopolymers Capture New Capacity Investment
Starch blends remain an established biodegradable-material category, but much of the new global bioplastics capacity through 2030 is being directed toward PLA, PHA and selected bio-based durable polymers. Starch-based suppliers therefore compete not only with fossil plastics but also with other bio-based and biodegradable materials that may offer better heat resistance, transparency, stiffness or barrier performance in specific applications. This keeps starch-based market growth steady rather than allowing it to track the fastest-growing parts of the broader bioplastics industry.
Starch-Based Bioplastic Segment Analysis
By Starch Type
Corn-Based
Corn-based starch is expected to generate approximately USD 1.29 billion by 2031. Its position is supported by large industrial starch supply chains in North America, China and other agricultural regions, as well as established use in film compounds and biodegradable bag applications. Corn starch is widely available at industrial scale and can be processed into thermoplastic starch or used as the renewable fraction of biodegradable polymer blends. Potato, cassava and other starch sources remain important where regional feedstock economics, non-GMO positioning, transparency or specific processing properties provide an advantage.
By Bioplastic Type
Starch-Polyester Blends
Starch-polyester blends are forecast to generate approximately USD 2.11 billion by 2031, retaining the largest material-type position. Their commercial advantage comes from combining renewable starch content with the mechanical strength and moisture resistance of biodegradable polyesters. The category supports thin films, shopping and produce bags, organic-waste liners, food-service products and selected agricultural applications. Product development is increasingly focused on higher starch content without sacrificing processability or film performance, particularly for converters seeking to use existing extrusion equipment.
By Application
Packaging
Packaging is expected to account for approximately USD 1.75 billion by 2031. Flexible films remain the largest use area, but growth is spreading into barrier layers, paper coatings, thermoformed structures and specialty food-contact formats. The segment benefits from high volumes and visible sustainability targets, yet it is also subject to the strictest scrutiny around recyclability and disposal. Starch-based packaging is therefore best positioned in applications where compostability, renewable content or high-barrier functionality provides a defined commercial benefit rather than as a universal replacement for conventional packaging polymers.
By End-User
Food and Beverage
Food and beverage applications are forecast to generate approximately USD 1.34 billion by 2031. Demand spans produce bags, dry-food packaging, coffee and tea formats, service ware, food-waste liners and selected fresh-food barrier structures. The segment benefits from close alignment with organic-waste collection because food-contaminated packaging can be difficult to recycle mechanically. At the same time, food-contact compliance, moisture resistance and shelf-life requirements raise the technical threshold for suppliers, favoring companies with established certification and conversion support.
Major Region
Europe
Europe is expected to generate approximately USD 1.04 billion by 2031. The region has a mature supplier base that includes Novamont, BIOTEC, AGRANA and FKuR, along with established compostability standards and significant organic-waste collection infrastructure.
Regulation is becoming more selective under the PPWR, which favors compostable materials in applications where they provide a clear waste-management benefit rather than across all packaging categories. This should support steady demand in bio-waste bags, selected food-service formats and agricultural films while increasing pressure on suppliers to demonstrate correct end-of-life positioning.
Major Country
China
China is forecast to approach USD 460 million by 2031, supported by large packaging, e-commerce, food-service and agricultural markets together with a broad domestic plastics-conversion base. The country also has significant corn and other starch feedstock availability, which supports local compounding economics. Demand growth will depend on how local restrictions on conventional single-use plastics are implemented across provinces and municipalities, while domestic biodegradable-polymer capacity gives converters several material options beyond starch blends.
Competitive Environment and Analysis
The starch-based bioplastic market is more specialized than the broader bioplastics industry. The strongest participants are companies with proprietary starch-processing know-how, biodegradable-polymer compounding capability, certification portfolios and established relationships with film and packaging converters. Novamont remains a leading reference through MATER-BI, which combines technologies based on starches, vegetable oils and other components across bags, packaging, organic-waste collection and agriculture. AGRANA participates from the starch side through AMITROPLAST thermoplastic starch and AGENACOMP compounds, while BIOTEC operates a broad BIOPLAST portfolio with installed capacity of approximately 60,000 tonnes per year.
Kuraray participates through Plantic Technologies, whose PLANTIC portfolio uses high-amylose starch in barrier films and sheet structures. FKuR's Ceroflex provides another direct starch-based offering for compostable films and bags, while Cardia Bioplastics sells thermoplastic-starch compounds and biohybrid resins based on starch-polymer blends. Biome Bioplastics maintains starch-containing flexible-film grades, and Rodenburg Biopolymers remains associated with starch-based compounds for packaging and related applications.
The company set is narrower than in generic bioplastics because many large polymer producers focus on PLA, PBAT, PHA or bio-based durable polymers rather than starch-based systems. Competitive advantage therefore depends on starch formulation, compatibility with biodegradable polyesters, film-processing support, certification and the ability to match product design with the correct end-of-life route. Suppliers that can offer both high renewable content and practical converting performance are better positioned than companies competing only on feedstock origin.
Recent Developments
August 2026: Regulation (EU) 2025/40 on packaging and packaging waste became applicable across the EU, tightening the distinction between packaging designed for recycling and the limited formats where compostability is specifically required or permitted.
May 2026: Kuraray highlighted PLANTIC EP, a thermoplastic starch-based biodegradable and compostable biopolymer in pellet form, at Interpack 2026 for paper and flexible packaging applications.
2026: AGRANA expanded its current AGENACOMP portfolio across F30, F40, F50 and F51 grades, targeting flexible packaging and mulch-film applications with higher renewable-content options.
2026: BIOTEC continued commercial expansion of its BIOPLAST starch-based portfolio across industrial- and home-compostable flexible-film grades, supported by installed production capacity of approximately 60,000 tonnes per year.
January 2026: Novamont repositioned the MATER-BI brand around compostable materials, organic-waste management and application-specific circular-economy uses as the product family entered its fourth decade.
Market Outlook
The market through 2031 should remain concentrated in applications where starch provides a clear commercial function rather than serving only as a renewable feedstock. Flexible bags, organic-waste liners, food packaging, barrier structures and agricultural films will continue to account for most incremental demand because these applications can justify starch-based formulations through compostability, renewable content, cost management or specific barrier performance.
Regulatory direction will become more selective. European rules increasingly distinguish between packaging that should be recycled and products where compostability supports bio-waste collection or another defined end-of-life route. This will reduce the value of generic "biodegradable" positioning and increase demand for application-specific certification, labeling and disposal guidance. Suppliers with product portfolios covering industrial composting, home composting and soil biodegradation will have an advantage where local infrastructure differs.
Starch blends are unlikely to capture the fastest growth within the broader bioplastics industry because substantial new capacity is moving into PLA, PHA and other polymers. Their position should nevertheless remain durable because they combine mature starch-processing economics with established film applications and can be formulated across a wide range of renewable-content levels. Product development will continue to focus on thinner films, better moisture and barrier performance, higher starch loading and easier processing on conventional equipment.
Starch-Based Bioplastic Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.17 billion |
| Total Market Size in 2031 | USD 3.06 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 7.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Starch Type, Bioplastic Type, Application, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Starch Type
Corn-Based
Potato-Based
Cassava-Based
Rice-Based
Others
By Bioplastic Type
Thermoplastic Starch (TPS)
Starch-Polyester Blends
Starch-Based Barrier Materials and Other Compounds
By Application
Packaging
Service Ware
Agriculture and Horticulture
Others
By End-User
Food and Beverage
Agriculture
Cosmetics and Personal Care
Pharmaceuticals and Healthcare
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Taiwan
Australia
Others
Table of Contents
. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Currency
2.6. Assumptions
2.7. Base and Forecast Years Timeline
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Analyst View
4. TECHNOLOGICAL OUTLOOK
4.1. High-Starch Polymer Blends
4.2. Barrier and Multilayer Structures
4.3. Home-Compostable Film Grades
4.4. Soil-Biodegradable Agricultural Films
5. STARCH-BASED BIOPLASTIC MARKET BY STARCH TYPE
5.1. Introduction
5.2. Corn-Based
5.3. Potato-Based
5.4. Cassava-Based
5.5. Rice-Based
5.6. Others
6. STARCH-BASED BIOPLASTIC MARKET BY BIOPLASTIC TYPE
6.1. Introduction
6.2. Thermoplastic Starch (TPS)
6.3. Starch-Polyester Blends
6.4. Starch-Based Barrier Materials and Other Compounds
7. STARCH-BASED BIOPLASTIC MARKET BY APPLICATION
7.1. Introduction
7.2. Packaging
7.3. Service Ware
7.4. Agriculture and Horticulture
7.5. Others
8. STARCH-BASED BIOPLASTIC MARKET BY END-USER
8.1. Introduction
8.2. Food and Beverage
8.3. Agriculture
8.4. Cosmetics and Personal Care
8.5. Pharmaceuticals and Healthcare
8.6. Others
9. STARCH-BASED BIOPLASTIC MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. Israel
9.5.4. South Africa
9.5.5. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Taiwan
9.6.8. Australia
9.6.9. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Novamont S.p.A. / Versalis (Eni)
11.2. AGRANA Stärke GmbH
11.3. BIOTEC GmbH & Co. KG
11.4. Biome Bioplastics Limited
11.5. Kuraray Co., Ltd. / Plantic Technologies Limited
11.6. FKuR Kunststoff GmbH
11.7. Cardia Bioplastics
11.8. Rodenburg Biopolymers B.V.
11.9. Green Dot Bioplastics, Inc.
11.10. EnviGren Biotech India Pvt. Ltd.
11.11. BioBag International / Novamont Group
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected growth rate for the Starch-Based Bioplastic Market?
The Starch-Based Bioplastic Market is forecast to grow at a 7.1% CAGR from 2026-2031.
What is the estimated market size for starch-based bioplastics by 2031?
The Starch-Based Bioplastic Market is projected to reach USD 3.06 billion by 2031.
Which material blend dominates the Starch-Based Bioplastic Market?
Starch-polyester blends account for 68% of market value in 2026.
What is the leading application segment for starch-based bioplastics?
Packaging accounts for 56% of global demand in 2026.
Which geographic region holds the largest market share?
Europe accounts for 35% of global market value in 2026.
What are the primary drivers for starch-based bioplastic demand?
Compostability and government regulations are key demand drivers.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Starch-Based Bioplastic Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/starch-based-bioplastic-market