
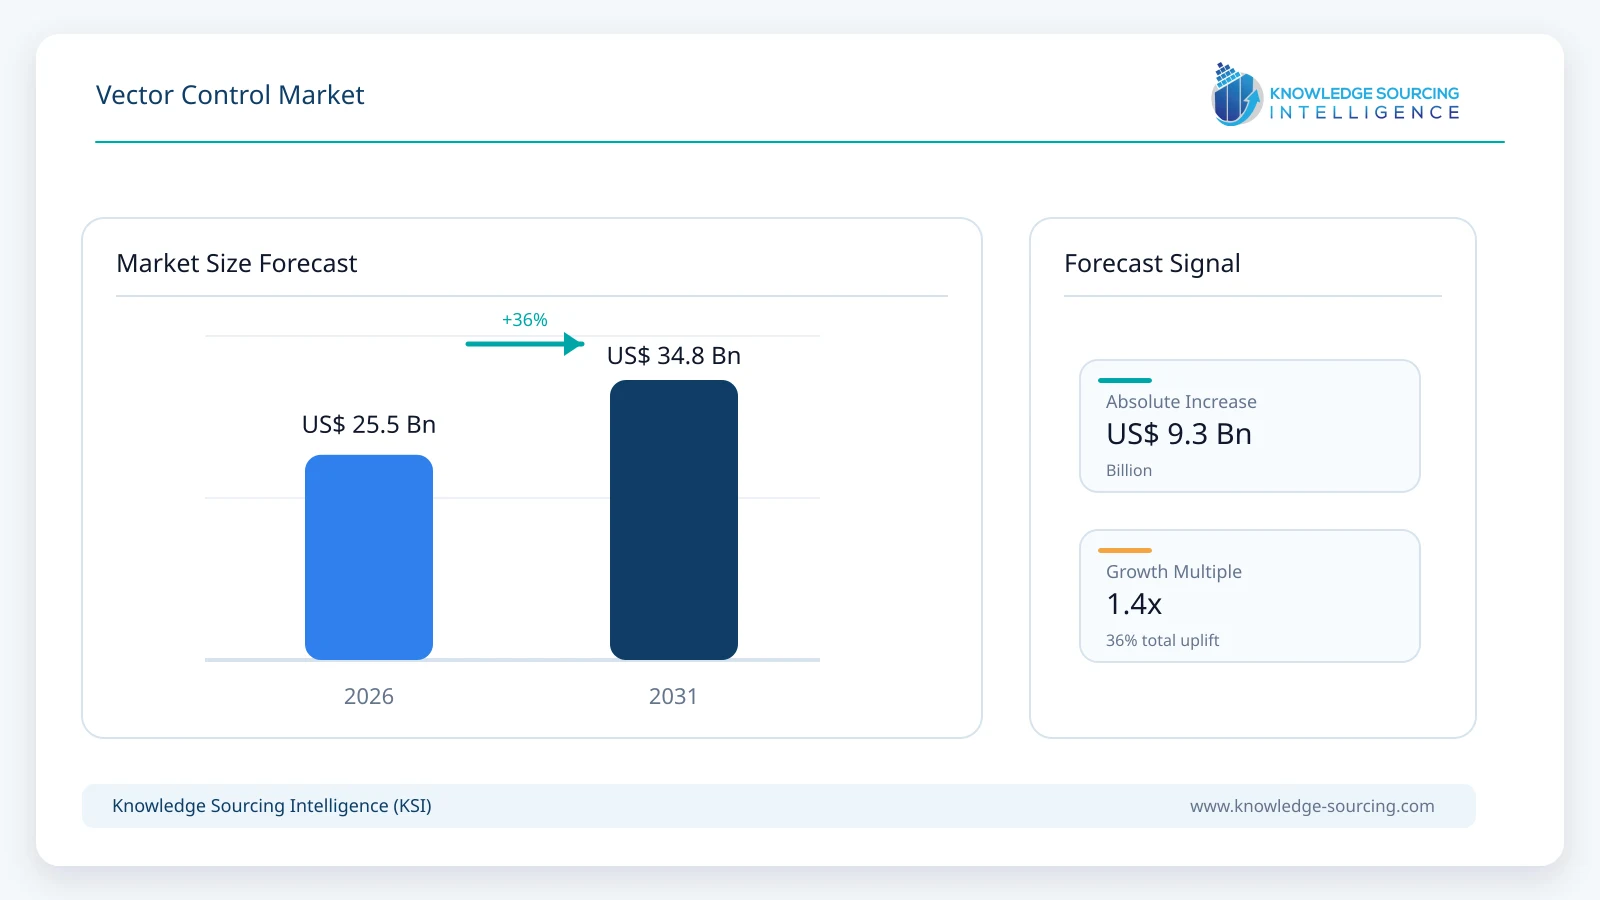
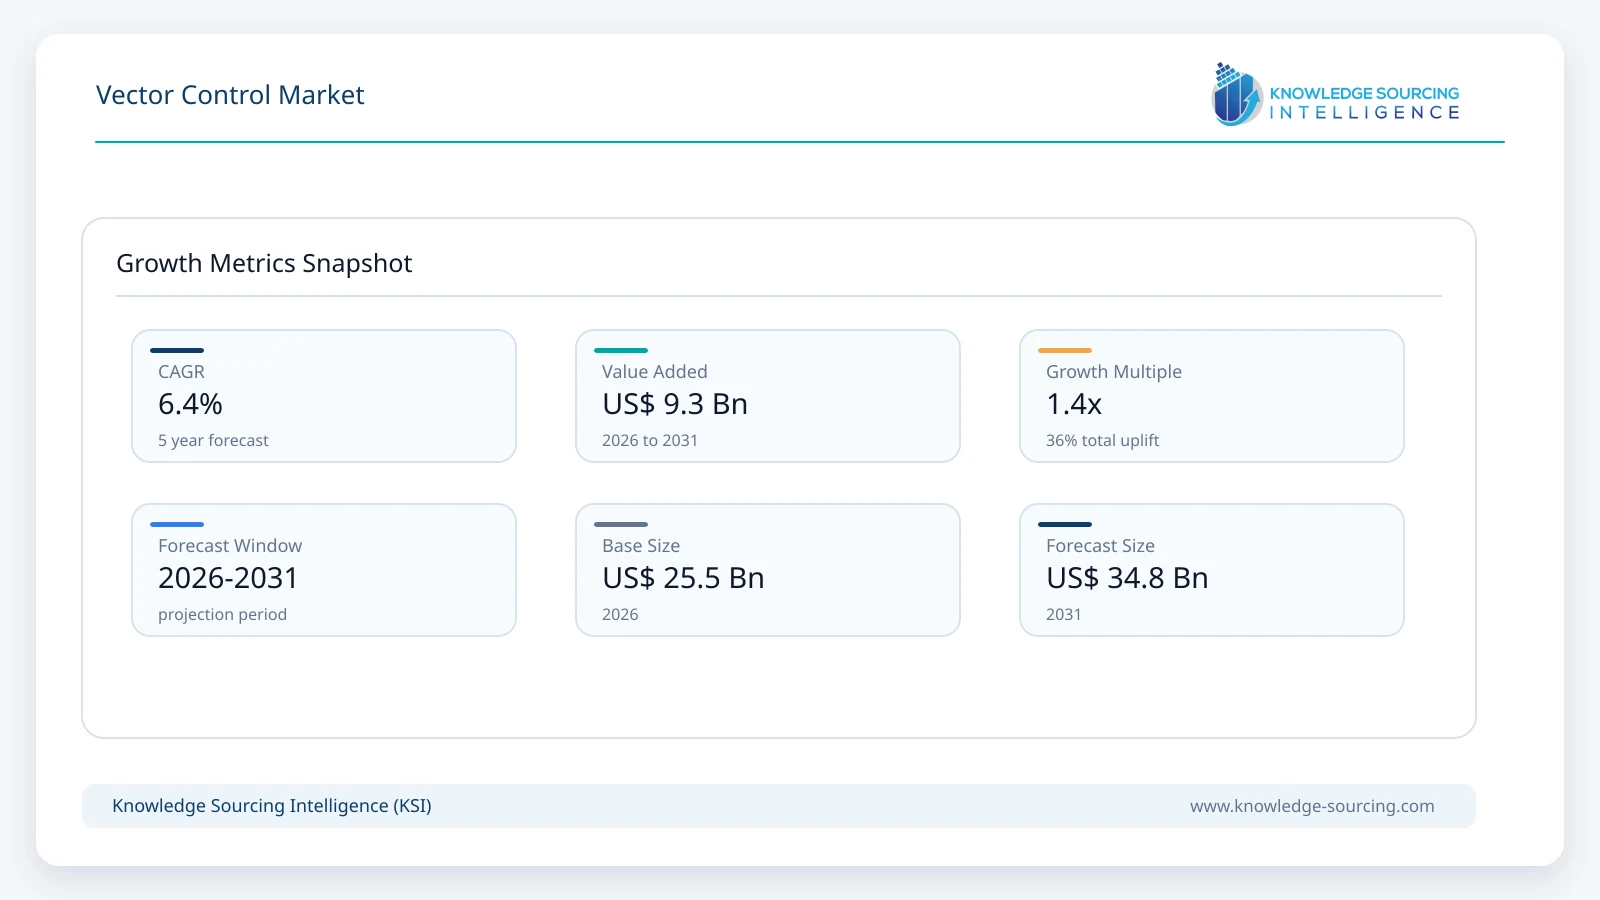
The vector control market is estimated at USD 25.50 billion in 2026 and is forecast to reach approximately USD 34.80 billion in 2031, representing a CAGR of 6.4% during the forecast period.
Highlights:
- 1Mosquito and other insect control remains the largest vector-management demand pool globally.
- 2Chemical control remains essential, while resistance management increases demand for diversified intervention portfolios.
- 3Public-health procurement is shifting toward dual-active nets, larvicides and integrated mosquito-management programs.
- 4Biological, behavioural and surveillance-led approaches are expanding alongside conventional insecticide-based vector control.
- 5Africa and Asia remain central to malaria and dengue programs, while North America leads commercial spending.
Vector Control Market Trends
Resistance Management Reshapes Product Selection
Vector-control programs are increasingly designed around rotation and combination rather than reliance on a single insecticide class. WHO continues to update resistance-monitoring methods, while suppliers are expanding dual-active nets, alternative larvicides, biological controls and new modes of action. This is changing procurement from a product-only decision into a portfolio decision based on local species, resistance profiles, breeding habitats and operational constraints.
Next-Generation Mosquito Nets Gain Strategic Importance
Insecticide-treated nets remain a central malaria intervention, but the mix is changing. Pyrethroid-only nets are increasingly supplemented by products using synergists or a second active ingredient. Vestergaard began Nigerian production of PermaNet Dual in September 2026 with planned annual capacity of 10 million nets, illustrating the shift toward regional manufacturing of newer dual-active technologies and shorter public-health supply chains.
Integrated and Behaviour-Based Approaches Expand
The market is also broadening beyond conventional spraying. Envu has expanded behaviour-based mosquito management through In2Care technology, while biological larvicides, insect-growth regulators, source reduction and targeted surveillance are increasingly combined with adulticides. These approaches are particularly relevant where resistance, environmental sensitivity or hidden breeding habitats reduce the effectiveness of repeated chemical treatment.
Vector Control Market Segment Analysis
By Vector Type
Insects
Insects represent the leading vector category because mosquitoes, ticks, flies and fleas account for a large portion of disease-control activity and recurring public-health intervention. Mosquito management is particularly important due to malaria, dengue, chikungunya, Zika and West Nile transmission. Demand spans insecticide-treated nets, indoor residual spraying, larvicides, adulticides, repellents, traps, surveillance and professional field services. The segment is also receiving a disproportionate share of innovation because insecticide resistance and changing vector geography require new active ingredients and integrated control strategies.
By Method of Control
Chemical Control
Chemical control remains the largest method because insecticides, larvicides, rodenticides and related formulations can be deployed quickly across outbreak response, routine public-health programs and commercial pest-management settings. Chemical tools are especially important when immediate population suppression is required. However, purchasing decisions increasingly incorporate resistance management, non-target effects and environmental requirements, encouraging rotation of active ingredients and combination with biological, physical and environmental methods rather than repeated use of a single chemistry.
By End User
Government and Public Health
Government and public-health programs form the most strategically important end-user group because large-scale malaria, dengue and urban mosquito-control programs require coordinated procurement, surveillance and field deployment. Ministries of health, municipal agencies and vector-control districts purchase nets, larvicides, space sprays, indoor residual-spray products, equipment and outsourced services. Procurement patterns can be cyclical and funding-dependent, but disease outbreaks, resistance monitoring and national elimination programs generate recurring demand that is difficult to substitute with household purchasing alone.
By Geography
North America
North America represents a major commercial market because of established mosquito-abatement districts, professional pest-management networks, rodent-control spending and widespread use of surveillance and contracted services.
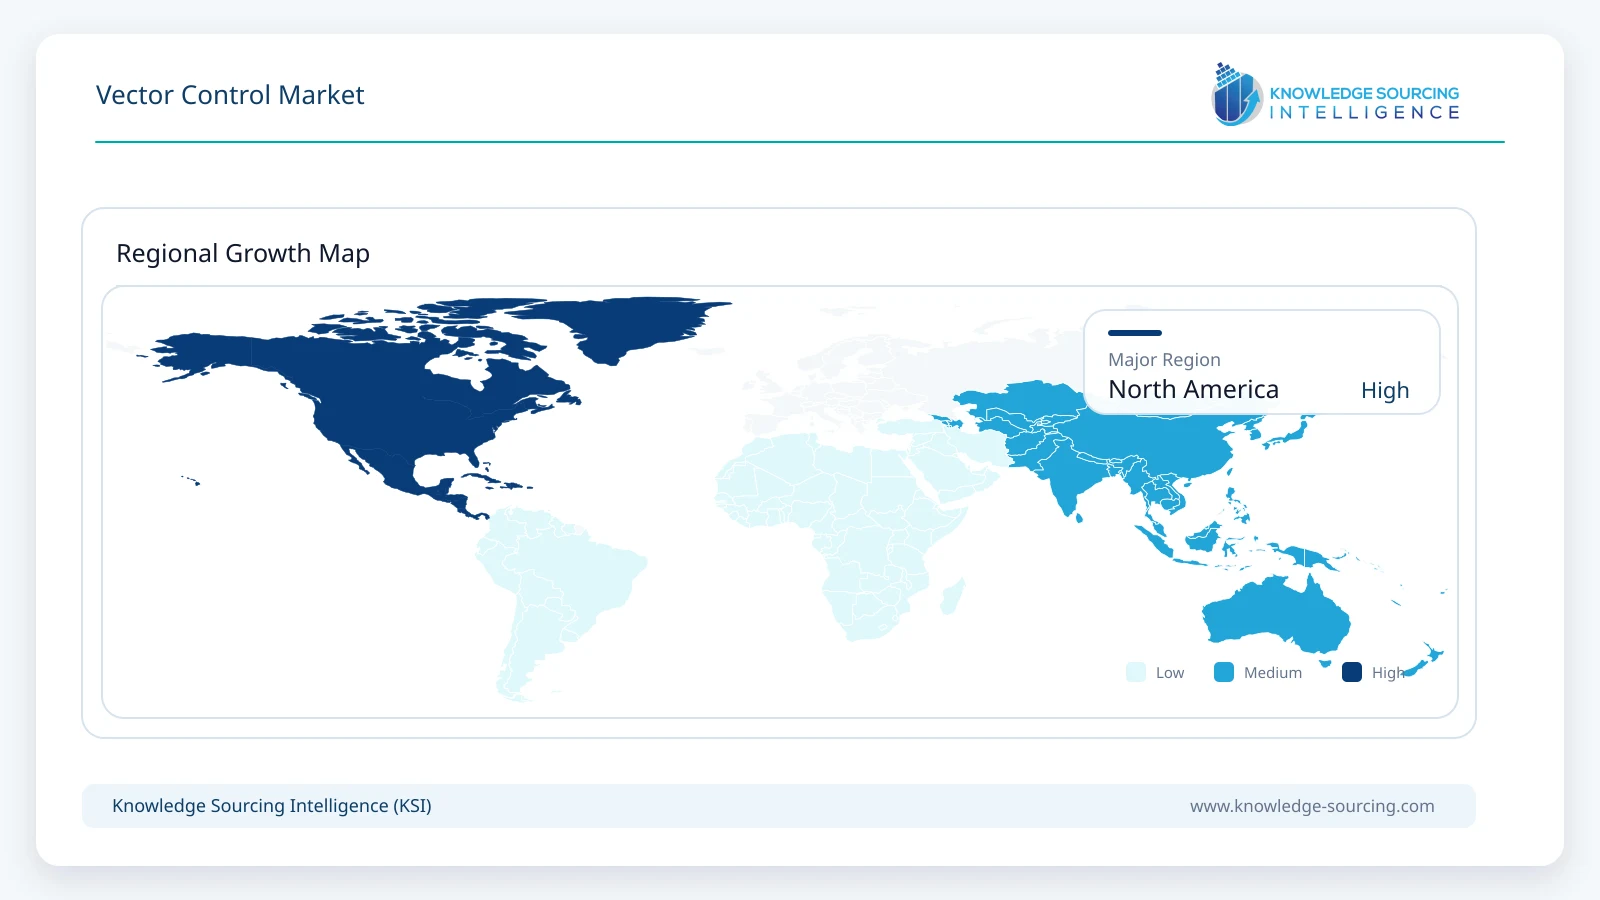
The region combines mature chemical-control demand with rapid uptake of connected monitoring and integrated pest-management tools. Africa carries the highest malaria-related public-health burden, while Asia Pacific combines dense urban populations with substantial dengue and mosquito-management needs, making both regions critical to long-term unit demand and innovation deployment.
Market Drivers
Persistent malaria, dengue and other vector-borne disease burdens sustaining prevention and outbreak-response spending.
Climate and urbanization effects extending vector seasons and creating new surveillance and treatment requirements.
Insecticide resistance increasing demand for new active ingredients and integrated resistance-management strategies.
Government and municipal investment in mosquito, rodent and urban sanitation programs.
Technology adoption in traps, monitoring, geospatial targeting and data-assisted field operations.
Market Restraints
Dependence on public-health budgets, donor funding and tender cycles in disease-endemic markets.
Regulatory restrictions and environmental scrutiny affecting registration and use of chemical active ingredients.
Resistance reducing the useful life of established insecticides and increasing program complexity.
Fragmented local execution and limited surveillance capacity in some high-burden markets.
Operational cost and training requirements associated with integrated and technology-enabled control programs.
Competitive Environment
Competition spans manufacturers of insecticides and vector-control products, insecticide-treated-net suppliers, specialist mosquito-control companies, rodent-control manufacturers and professional pest-management service providers. Envu, BASF, Sumitomo Chemical, Mitsui Chemicals Crop & Life Solutions, Vestergaard, Clarke, Central Life Sciences and Valent BioSciences participate directly in mosquito or public-health vector-control technologies. Bell Laboratories is a specialist in rodent control, while Rentokil Initial, Rollins, Ecolab, Anticimex and Arrow Exterminators provide recurring professional pest and vector-management services. Competitive advantage increasingly depends on regulatory approvals, resistance-management capability, field support, application technology and breadth of integrated solutions.
Recent Developments
September 2026: Vestergaard began manufacturing PermaNet Dual dual-active insecticide-treated mosquito nets in Nigeria, with planned annual capacity of 10 million nets.
August 2026: Envu Malaysia signed a five-year framework with Malaysia's Institute for Medical Research to evaluate vector-control solutions and address insecticide resistance.
July 2026: Envu introduced Barcelo Liquid Film in Brazil, adding a silicone-based physical-action larvicide for Aedes aegypti control.
June 2026: WHO issued updated information for insecticide-resistance monitoring, reinforcing the importance of standardized resistance surveillance.
June 2026: WHO provided an update on its assessment of Wolbachia population replacement for Aedes-borne disease control, with guideline development continuing.
Market Outlook
The vector control market should expand steadily through 2031 as disease-prevention programs become more data-driven and intervention portfolios become more diversified. Chemical products will remain essential, but future value growth will increasingly come from resistance-management solutions, dual-active nets, biological and behavioural approaches, improved monitoring and integrated service delivery. Suppliers that combine proven efficacy with regulatory support, field training and locally adaptable implementation models are positioned to capture a larger share of public-health and professional demand.
Vector Control Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 25.50 billion |
| Total Market Size in 2031 | USD 34.80 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Vector Type, Method of Control, End User, Geography |
| Companies |
|
Market Segmentation
By Vector Type
Insects
Rodents
Other Disease Vectors
By Method of Control
Chemical
Biological
Physical and Mechanical
Environmental Management and Source Reduction
By End User
Government and Public Health
Commercial and Industrial
Residential
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Others
Europe
Germany
France
United Kingdom
Italy
Others
Middle East and Africa
South Africa
Nigeria
Saudi Arabia
Others
Asia Pacific
China
India
Japan
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Scope
1.3. Currency and Assumptions
2. RESEARCH METHODOLOGY
2.1. Secondary Research
2.2. Company and Product Validation
2.3. Market Estimation and Triangulation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Insecticide Resistance and Regulation
4.4. Technology and Sustainability Trends
5. VECTOR CONTROL MARKET BY VECTOR TYPE
5.1. Insects
5.2. Rodents
5.3. Other Disease Vectors
6. VECTOR CONTROL MARKET BY METHOD OF CONTROL
6.1. Chemical
6.2. Biological
6.3. Physical and Mechanical
6.4. Environmental Management and Source Reduction
7. VECTOR CONTROL MARKET BY END USER
7.1. Government and Public Health
7.2. Commercial and Industrial
7.3. Residential
8. VECTOR CONTROL MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Others
8.3. Europe
8.3.1. Germany
8.3.2. France
8.3.3. United Kingdom
8.3.4. Italy
8.3.5. Others
8.4. Middle East and Africa
8.4.1. South Africa
8.4.2. Nigeria
8.4.3. Saudi Arabia
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. India
8.5.3. Japan
8.5.4. Southeast Asia
8.5.5. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Product and Service Positioning
9.2. Resistance-Management Strategies
9.3. Recent Developments and Partnerships
10. COMPANY PROFILES
10.1. Envu
10.2. BASF SE
10.3. Sumitomo Chemical Co., Ltd.
10.4. Mitsui Chemicals Crop & Life Solutions, Inc.
10.5. Vestergaard Sarl
10.6. Clarke
10.7. Central Life Sciences
10.8. Valent BioSciences LLC
10.9. Bell Laboratories, Inc.
10.10. Rentokil Initial plc
10.11. Rollins, Inc.
10.12. Ecolab Inc.
10.13. Anticimex Group
10.14. Arrow Exterminators, Inc.
10.15. PelGar International Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Abbreviations
Navigate
Trusted by the world's leading organizations











