
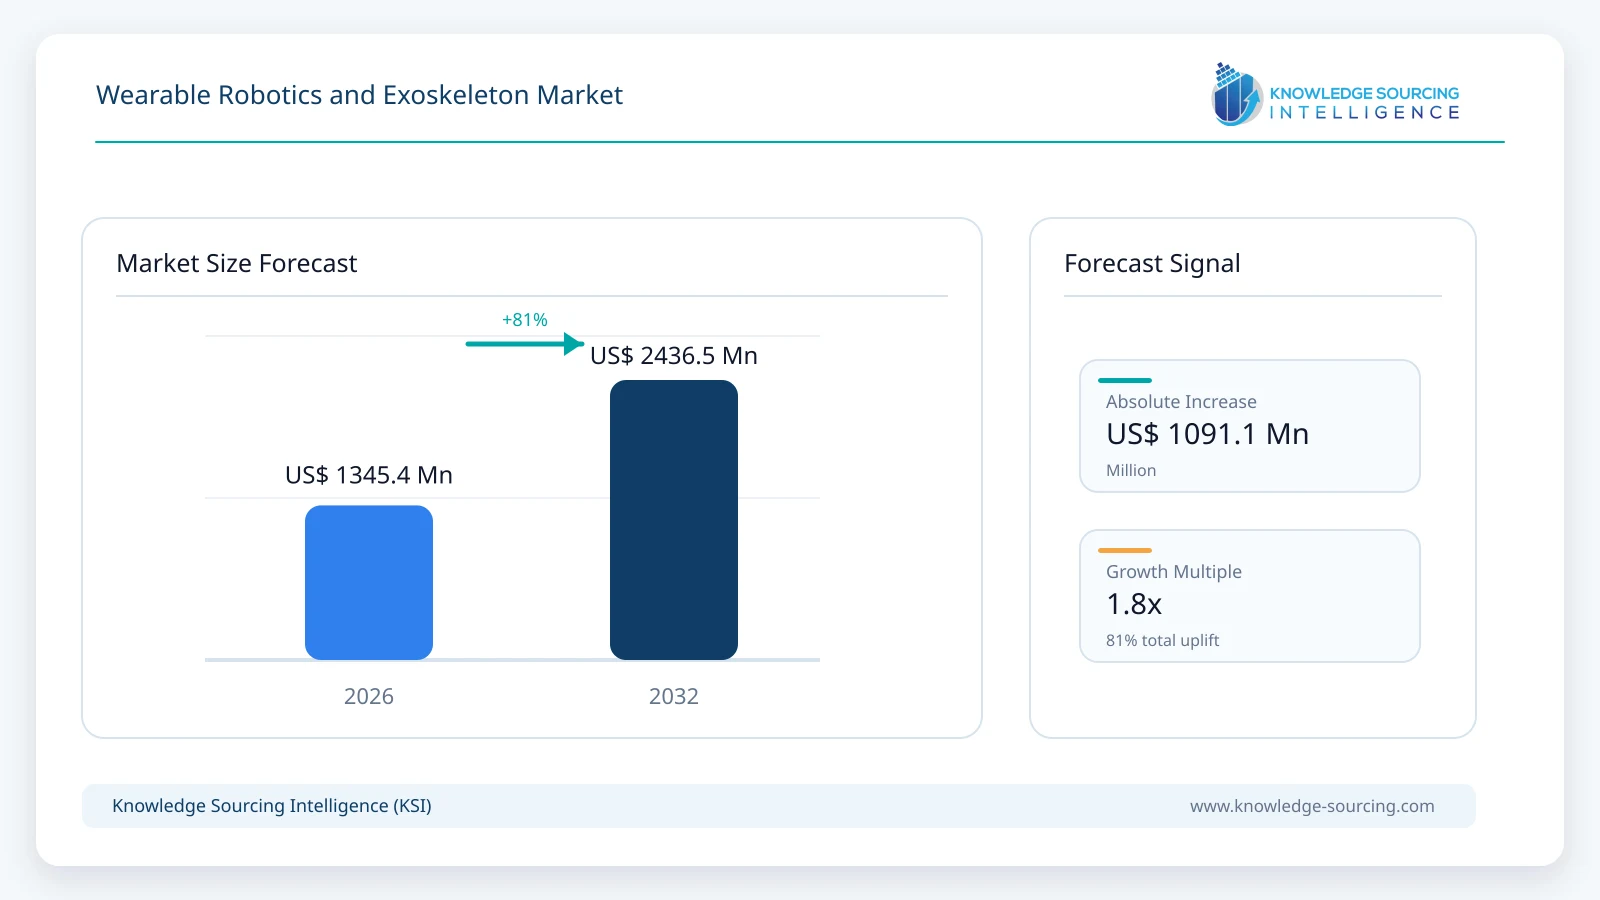
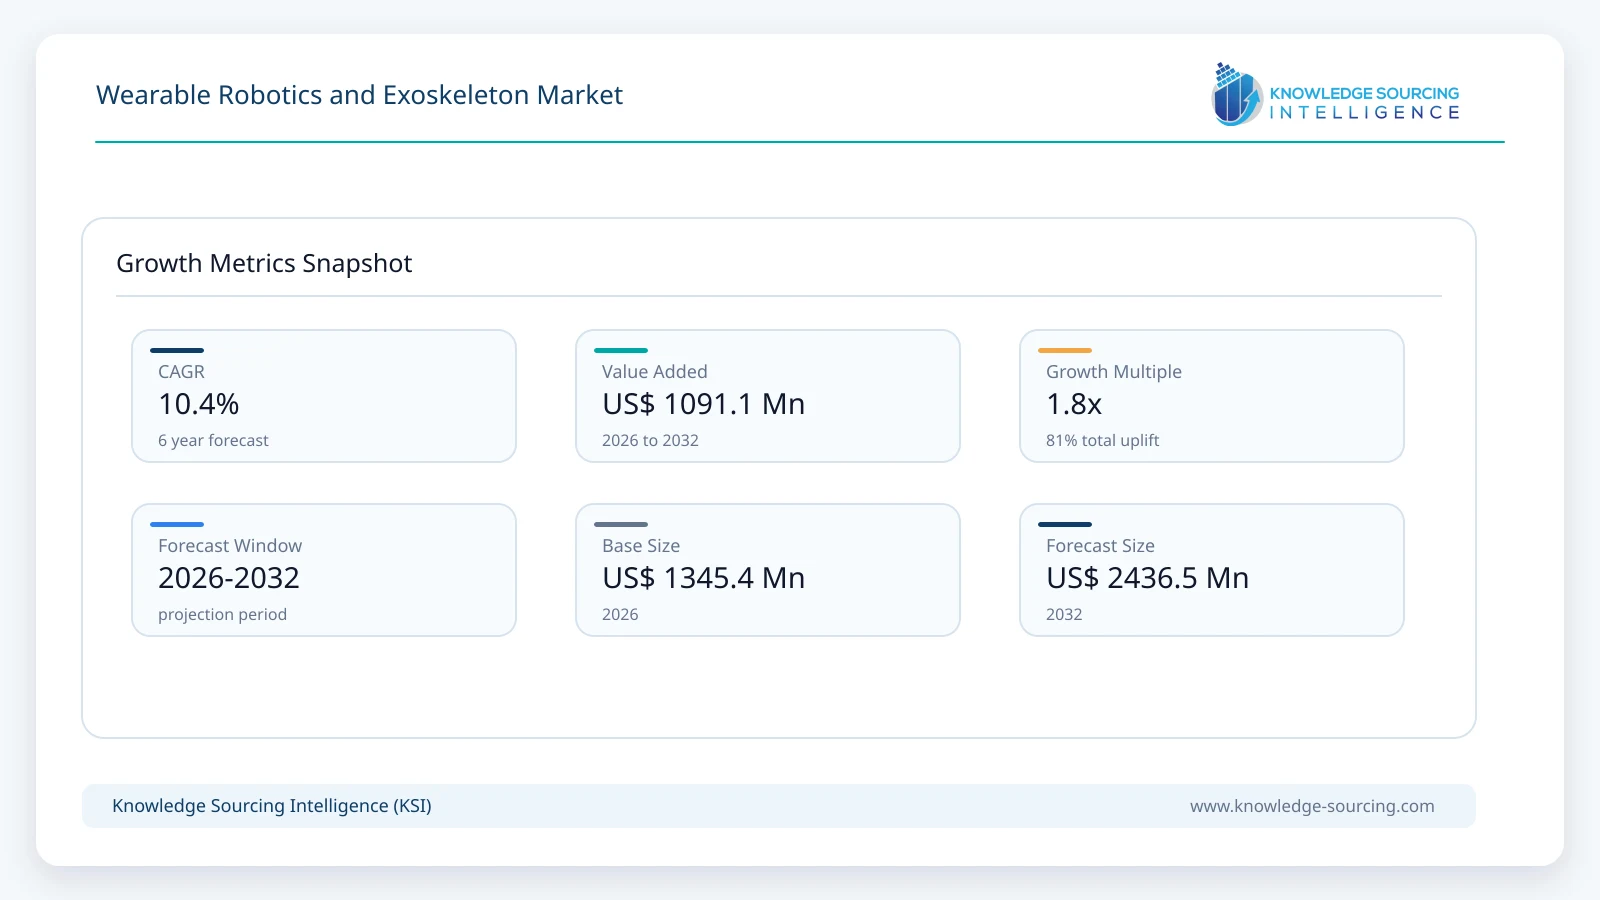
The wearable robotics and exoskeleton market is estimated at USD 1,345.4 million in 2026 and is forecast to reach USD 2,436.5 million in 2032, representing a 10.4% CAGR during the forecast period.
Highlights:
- 1Mechatronic prosthetics are estimated to represent 65.6% of 2026 market revenue, reflecting the established commercial base of sensor-controlled knees, adaptive feet and myoelectric upper limbs.
- 2Personal mobility exoskeletons are forecast to grow at approximately 14.1% CAGR during 2026–2032, subject to reimbursement, fitting and service capacity.
- 3Robotic orthoses are projected to exceed US$288.57 million in 2032, with growth linked to active limb assistance and specialized clinical distribution.
- 4Industrial exoskeleton demand depends on task-level economics, employee acceptance and ergonomic validation, with repeat procurement dependent on successful workplace trials.
- 5The October 2026 change in Ekso ownership and continued investment in mechatronic prosthetics are reshaping the competitive supplier landscape.
Commercially, this is a wider market than rehabilitation and industrial exoskeletons alone. Microprocessor-controlled prosthetic knees, myoelectric hands and adaptive prosthetic ankles connect human movement to embedded sensors, algorithms and controlled mechanical response. Their purchasers include prosthetic clinics, distributors, public reimbursement systems and private insurers, not only hospitals and manufacturing companies. These differences shape product pricing, regulatory requirements and replacement cycles.
Mechatronic prosthetics account for the largest share of revenue, supported by established clinical purchasing channels and higher-value intelligent components. Exoskeletons and robotic orthoses serve different patient, industrial and consumer needs, with distinct pricing and replacement cycles. Conventional artificial limbs, standard braces and standalone monitoring wearables are outside the product scope, as are clinical fitting fees unrelated to device supply.
Market Definition and Commercial Boundaries
Wearable robotics connects a physical device to a person's movement or intended movement. Rigid and soft exoskeletons can assist gait, lifting or repetitive work. Robotic orthoses support weakened biological limbs, while robotic prostheses replace missing limbs with controllable electromechanical or mechatronic functions. Advanced microprocessor-controlled knees use sensor-regulated resistance to respond to different walking conditions, while powered hands and ankles use active actuation for additional functional assistance.
Commercial applications include rehabilitation exoskeletons worn by patients, personal walking systems, occupational support equipment, consumer assistive suits, robotic orthoses, myoelectric hands and microprocessor-controlled lower-limb prosthetics. Conventional passive joints, cosmetic prostheses, fixed braces, non-wearable rehabilitation robots and general-purpose activity trackers fall outside this category because they do not provide the relevant adaptive or assistive functions.
The industry spans both device manufacturing and clinical service delivery. A fitted prosthetic limb can combine a mechatronic knee or foot with a socket, adapters, fitting appointments and aftercare. Device manufacturers generate revenue from intelligent components, while clinicians and service providers earn separate income from evaluation, customization and support. These distinct revenue streams influence the value captured by each participant in the supply chain.
Market Dynamics
Reimbursement and clinical access influence high-value device adoption
The commercial constraint in robotic prosthetics is frequently access to coverage rather than a lack of technical capability. Microprocessor-controlled joints are sold into a clinical pathway that requires patient evaluation, prescription, functional classification, fitting and adjustments. A manufacturer's ability to demonstrate controlled stance, safer terrain negotiation or reliable hand function matters only when clinicians and payers can establish medical necessity and supported use.
Ottobock's 2025 results identify newer microprocessor-controlled knees and the C-Brace neuro-orthosis among its growth contributors. Expanded reimbursement for selected knee and orthotic products reinforces the importance of national coverage rules. Embla Medical likewise reports demand for advanced prosthetics and neuro-orthotics. Competition increasingly centers on clinically demonstrated function and reimbursement access, alongside the established ability to supply and service devices through specialist networks.
U.S. HCPCS reimbursement allowances illustrate the economic stakes for premium robotic prosthetics. Payments to a clinic or provider can cover a wider set of benefits than the manufacturer-supplied component. Funding policies, clinical evidence, replacement eligibility and service arrangements consequently influence the affordability and uptake of similar technologies across countries.
Human-machine interfaces raise the value of mechatronic prosthetics
The product opportunity extends beyond the mechanical strength of a joint. Sensors, adaptive microprocessor control, muscle-signal capture and pattern-recognition systems increasingly determine how a prosthetic or orthotic device performs during irregular movement. These technologies can reduce the need for repeated manual settings and increase the number of conditions in which the same component functions usefully.
For manufacturers, that shifts competition toward reliability, control performance, firmware support, clinician tooling and the ability to integrate with standard fittings. It also creates longer development and certification cycles. Purchasing authorities must weigh the incremental functional benefit against component pricing, eligibility restrictions, maintenance burden and replacement policies. A technically advanced device may therefore command a higher selling price without achieving the same market penetration in every geography.
Ottobock's 2026 investment in human-machine interface technology and its planned acquisition of Fesia Technology illustrate interest in neural interfaces and active assistance. Suppliers able to integrate controllers, wearable hardware and clinician-facing software can differentiate through more responsive movement support, easier adjustment and ongoing functional upgrades.
Industrial exoskeletons face a pilot-to-deployment bottleneck
Passive occupational supports and powered industrial suits promise mechanical load assistance, but scaling them requires evidence for the specific workplace task. A shoulder-support frame tested during overhead installation may perform differently during materials handling or an entire variable-length shift. Worker comfort, fit, interference with protective equipment, sanitation and storage can determine whether a pilot becomes a purchase order.
Ottobock's 2025 market assessment describes occupational exoskeletons as an emerging category, substantially smaller than established prosthetics. Industrial suppliers therefore face a more challenging conversion path from demonstration projects to repeat fleet orders. Passive shoulder and back supports compete on comfort and task compatibility, while powered systems face additional maintenance, charging and cost requirements.
The October 2026 expansion of SUITX by Ottobock into Würth branches in Germany and other European markets illustrates a route to wider adoption. Local demonstrations reduce the cost of trial and help companies select support equipment for defined tasks. Distribution alone does not confirm injury reduction or guarantee volume purchases; procurement still depends on the measured suitability of each task.
Consumer exosuits introduce a distinct low-price growth path
Retail mobility assistance offers a different commercial pathway from prescribed clinical devices. Consumer exosuits combine relatively compact actuators, batteries and support structures to assist walking and recreational activities. Their addressable customer base may exceed that of highly specialized rehabilitation equipment, but realized selling prices are far lower and device upgrade cycles remain uncertain.
Manufacturers compete on comfort, weight, motor output, battery endurance, serviceability and usable assistance under real walking conditions. Consumer devices sell at materially lower price points than hospital gait systems, making shipment growth more important to revenue expansion. As competition increases, pricing pressure, warranty expenses and returns may offset some gains from wider adoption.
Segment Analysis
By Product Family: Mechatronic Prosthetics
Mechatronic prosthetics are the largest commercial category under the broader wearable robotics definition. The segment includes microprocessor-controlled knee systems, myoelectric and bionic hands, and qualifying powered or adaptive ankle and foot units. Its current revenue base reflects established prosthetics manufacturing, clinical distribution and reimbursed component purchasing rather than only experimental robotics installations.
High component values and supervised clinical purchasing distinguish mechatronic prosthetics from consumer wearables. A microprocessor knee typically passes through specialized suppliers, certified prosthetists and a payer before reaching the patient. Control systems and safety features can improve functional performance, but training requirements, repair access and refitting costs influence the purchasing decision and manufacturers' ability to sustain premium pricing.
The microprocessor-controlled knee segment is estimated at US$540.00 million in 2026. Its value reflects the combination of premium intelligent joint systems and established prosthetic-care channels. Reimbursement policies strongly influence device access, while manufacturers compete on stability control, terrain adaptation, service intervals and compatibility with standard fittings. Delays in authorization or limited prosthetist capacity can constrain sales even when clinical demand is present.
A distinct competitive effect arises from widening reimbursement eligibility. Ottobock has linked commercial growth in North America to access to selected microprocessor-controlled prosthetic knees and the C-Brace orthosis. When more patient groups qualify, annual placements can grow without an equivalent increase in the total number of amputees. Nevertheless, achieving the forecast requires trained clinicians and sustained payer funding. The effect is not automatic simply because a new product is commercially available.
Manufacturers differ in where they capture value. Ottobock and Embla Medical offer broad portfolios of prosthetic components, while Open Bionics focuses on advanced upper-limb devices. Blatchford and other specialist suppliers compete on gait technology and fitting compatibility. This product diversity creates distinct paths to growth, from replacement sales through established clinics to new prescriptions for higher-function devices.
Myoelectric hands and sensor-controlled feet have opportunities to outpace conventional component replacement in selected applications. However, lower-cost mechanical alternatives, maintenance requirements and payer documentation still limit substitution. Premium knee systems benefit more directly from reimbursement expansion, while hand and foot products depend heavily on functional differentiation, fitting expertise and patient affordability.
By Product Family: Robotic Orthoses
Robotic orthoses support movement in an existing limb rather than replace it. Products include mechatronic knee-ankle-foot systems, powered arm braces and active hand-assistance devices. Their commercialization depends on clinical outcomes, prescribed use, fitting complexity and access to specialist rehabilitation networks. Myomo's reported 2025 revenue illustrates a commercial market for powered upper-limb assistance, alongside smaller specialized product categories.
Mechatronic lower-limb orthoses are estimated to generate US$64.80 million in 2026. These devices typically address patients retaining a biological limb but requiring active joint support. Their clinical pathway differs from personal walking exoskeletons, while motorized hand-assistance devices address upper-limb rehabilitation and functional activities where active grasp support is required.
By Product Family: Exoskeletons and Exosuits
Wearable exoskeletons comprise clinical gait-assistance systems, personal mobility devices, workplace assistive frames, consumer powered suits and specialized research equipment. The family is projected to reach US$581.78 million by 2032. Clinical systems remain expensive, low-volume purchases, while workplace and consumer systems involve lower prices and potentially broader distribution.
Personal mobility exoskeletons have a distinct prescription and service model. Wandercraft's U.S. launch of Eve extends self-balancing systems from supervised rehabilitation toward home use for eligible users. Patient evaluation, fitting, training and coverage continue to govern conversion from product interest to sales. Industrial systems should be evaluated through measured ergonomic improvement and site-level purchasing decisions, while recreational units are influenced by battery endurance, retail pricing and device acceptance.
By Customer and Use Case
Healthcare is the primary outlet for robotic prosthetics, orthoses and rehabilitation exoskeletons. Industrial purchasers prioritize repetitive handling and ergonomic applications, while consumers focus on walking support and outdoor use. Military and research institutions remain smaller specialist buyers. Each customer group evaluates the technology differently, from clinical function and reimbursement to task productivity, comfort and durability.
Geographic Outlook
North America: Reimbursement and clinical networks support premium products
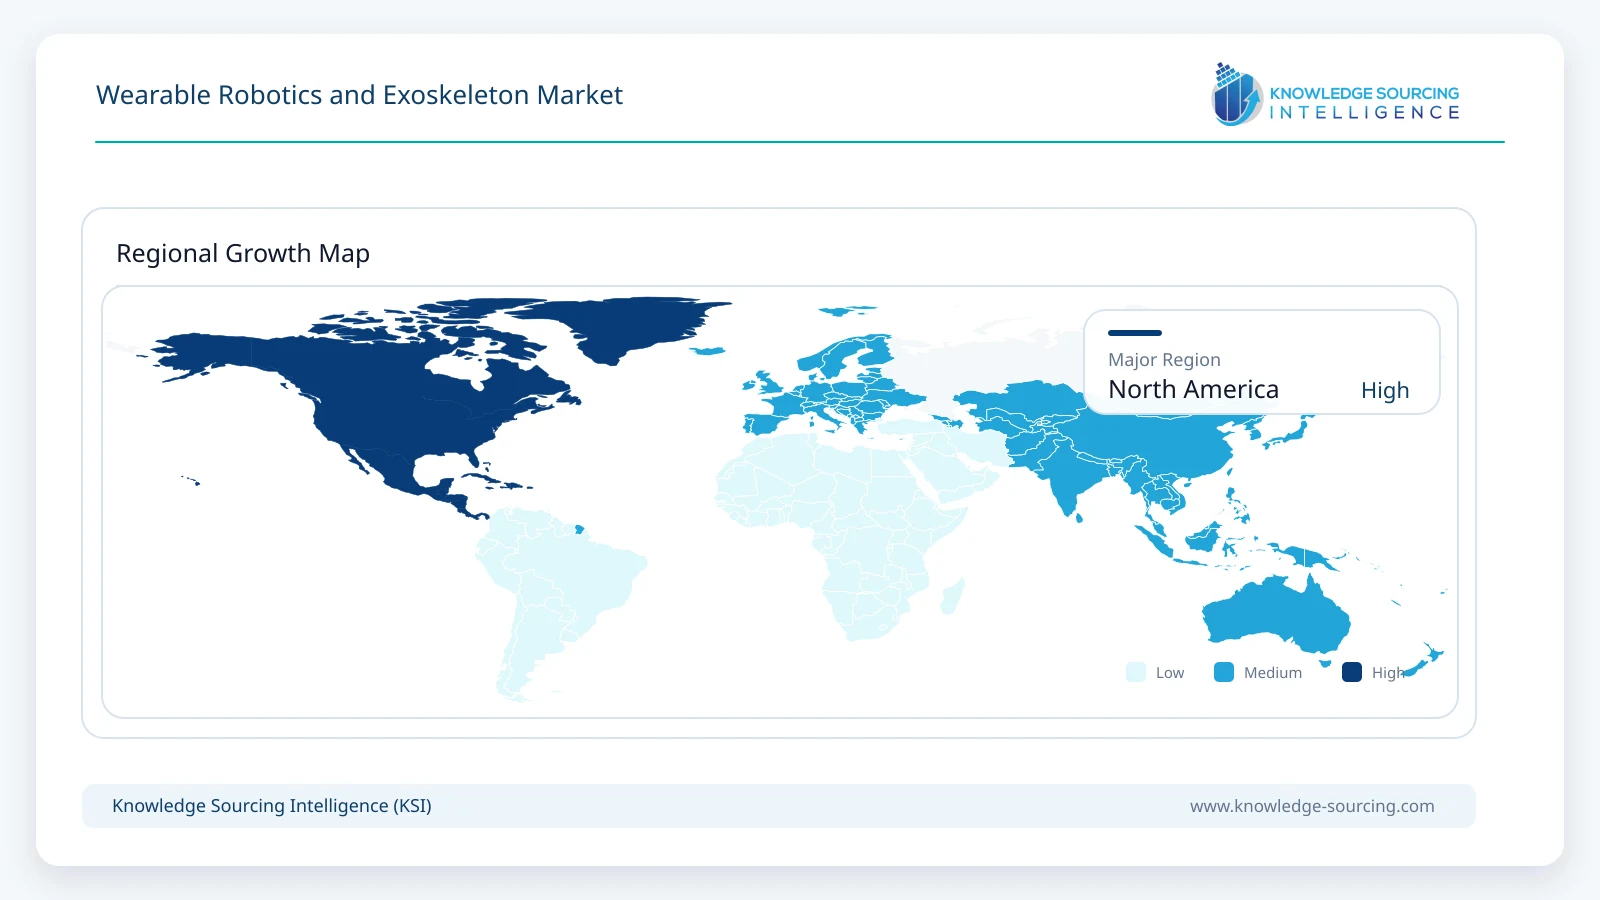
North America represents an estimated 35.3% of 2026 revenue. The region combines established prosthetic and orthotic clinics, specialist insurers, major manufacturers and identifiable coding frameworks. These strengths support adoption of advanced medical components, although eligibility rules, prior authorization and fitting capacity can delay uptake. The announced Hanger–Numotion combination could reshape referral networks and procurement relationships across rehabilitation and mobility services.
Europe: Supplier depth and industrial adoption channels
Europe combines major mechatronic prosthetic suppliers, rehabilitation innovators and occupational assistive-device manufacturers. Germany and France are significant through Ottobock, Wandercraft and established distribution networks. Medical demand is shaped by national reimbursement systems and specialized clinical access, while industrial sales require task-specific workplace trials. These distinct purchasing pathways influence deployment timing across the region.
Asia Pacific: Component manufacturing and consumer-unit growth
Asia Pacific is estimated to generate US$353.59 million in 2026. Japan and South Korea have medical robotics ecosystems, while China is relevant for component manufacturing, rehabilitation equipment and affordable powered wearables. Growth in lower-priced consumer exosuits may lift shipment volumes faster than market revenue, whereas premium prosthetic systems remain dependent on specialist clinical channels and reimbursement access.
Competitive Landscape
The expanded market includes prosthetics specialists, robotic orthosis developers and exoskeleton manufacturers. Ottobock, Embla Medical, Blatchford and Open Bionics are relevant to advanced limb technology. Myomo, CYBERDYNE and specialist orthosis suppliers compete in powered limb assistance. Wandercraft, Lifeward, German Bionic, SUITX by Ottobock, Auxivo, DynaWear and Hypershell participate in medical, industrial or consumer exoskeletons.
The October 2026 restructuring of Ekso's businesses separated medical and industrial product portfolios. Wandercraft acquired the medical exoskeleton operations, while DynaWear acquired the former EksoWorks industrial assets. The transactions may affect product roadmaps, distributor relationships and competitive positioning across rehabilitation and occupational assistance.
Recent Developments
02 October 2026: SUITX by Ottobock expanded its industrial exoskeleton distribution collaboration with Würth across European skilled-trades markets.
01 October 2026: Wandercraft acquired Ekso Bionics' medical exoskeleton business, while EksoWorks industrial assets moved separately to DynaWear.
17 September 2026: Wandercraft launched its FDA-cleared Eve personal self-balancing exoskeleton commercially in the United States.
13 August 2026: Ottobock reported H1 growth in prosthetics and neuro-orthotics, alongside investment in human-machine interfaces and Fesia Technology.
Wearable Robotics and Exoskeleton Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1,345.4 million |
| Total Market Size in 2032 | USD 2,436.5 million |
| Forecast Unit | Million |
| Growth Rate | 10.4% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Product Family, End User, Technology, Geography |
| Companies |
|
Market Segmentation
By Product Family
Mechatronic Prosthetics
Microprocessor-Controlled Knees
Bionic and Myoelectric Hands and Arms
Sensor-Controlled and Powered Ankles/Feet
Robotic Orthoses
Mechatronic Lower-Limb Orthoses
Powered Upper-Limb Orthoses
Active Robotic Hand Assistance
Exoskeletons and Exosuits
Clinical Rehabilitation Exoskeletons
Personal Mobility Exoskeletons
Passive Industrial Exoskeletons
Powered Industrial Exoskeletons
Consumer and Outdoor Assistance
Defence and Research
By End User
Healthcare and Prosthetic Care
Industrial and Logistics
Consumer and Recreation
Defence and Research
By Technology
Sensor-Controlled Mechatronic Systems
Motor-Actuated Wearable Robotics
Passive Assistive Exoskeletons
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
Others
Asia Pacific
China
Japan
South Korea
India
Others
Table of Contents
1. INTRODUCTION
1.1. Research Scope and Definitions
1.2. Methodology and Data Sources
1.3. Market Scope and Revenue Definitions
1.4. Base Year and Forecast Period, 2026–2032
2. EXECUTIVE SUMMARY
2.1. Global Market Estimates and Forecast
2.2. Product-Family Demand and Commercial Findings
2.3. Regional and Competitive Insights
3. MARKET DYNAMICS
3.1. Growth Drivers
3.2. Market Restraints
3.3. Regulatory and Reimbursement Frameworks
3.4. Clinical Fitting and Distribution Economics
3.5. Industry Value Chain
3.6. Porter’s Five Forces Analysis
4. TECHNOLOGY LANDSCAPE
4.1. Sensor-Controlled and Motor-Actuated Mobility
4.2. Myoelectric Control and Adaptive Biomechanics
4.3. Soft Exosuits and Rigid Exoskeletons
4.4. Safety, Battery Systems and Human-Machine Interfaces
5. WEARABLE ROBOTICS AND EXOSKELETON MARKET BY PRODUCT FAMILY
5.1. Mechatronic Prosthetics
5.1.1. Microprocessor-Controlled Knees
5.1.2. Bionic and Myoelectric Hands and Arms
5.1.3. Sensor-Controlled and Powered Ankles/Feet
5.2. Robotic Orthoses
5.2.1. Mechatronic Lower-Limb Orthoses
5.2.2. Powered Upper-Limb Orthoses
5.2.3. Active Robotic Hand Assistance
5.3. Exoskeletons and Exosuits
5.3.1. Clinical Rehabilitation Exoskeletons
5.3.2. Personal Mobility Exoskeletons
5.3.3. Passive Industrial Exoskeletons
5.3.4. Powered Industrial Exoskeletons
5.3.5. Consumer and Outdoor Assistance
5.3.6. Defence and Research
6. MARKET BY END USER
6.1. Healthcare and Prosthetic Care
6.2. Industrial and Logistics
6.3. Consumer and Recreation
6.4. Defence and Research
7. MARKET BY TECHNOLOGY
7.1. Sensor-Controlled Mechatronic Systems
7.2. Motor-Actuated Wearable Robotics
7.3. Passive Assistive Exoskeletons
8. MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. France
8.3.3. United Kingdom
8.3.4. Italy
8.3.5. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. United Arab Emirates
8.4.3. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. Japan
8.5.3. South Korea
8.5.4. India
8.5.5. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Competitive Dashboard
9.2. Product Capability and End-User Mapping
9.3. Pricing, Fitting and Distribution Models
9.4. Mergers, Partnerships and Product Launches
10. COMPANY PROFILES
10.1. Ottobock SE & Co. KGaA (including SUITX)
10.2. Embla Medical (Össur)
10.3. Blatchford
10.4. Open Bionics
10.5. Steeper Group
10.6. Myomo, Inc.
10.7. Wandercraft (including Ekso Medical)
10.8. Lifeward Ltd. (ReWalk)
10.9. CYBERDYNE Inc.
10.10. German Bionic
10.11. Auxivo AG
10.12. DynaWear Tech (including former EksoWorks)
10.13. Hypershell
10.14. Fourier Intelligence
10.15. B-Temia Inc.
11. APPENDIX
11.1. Currency and Market Definitions
11.2. Research Methodology
11.3. Glossary and Abbreviations
11.4. Primary Sources
Navigate
Trusted by the world's leading organizations











