
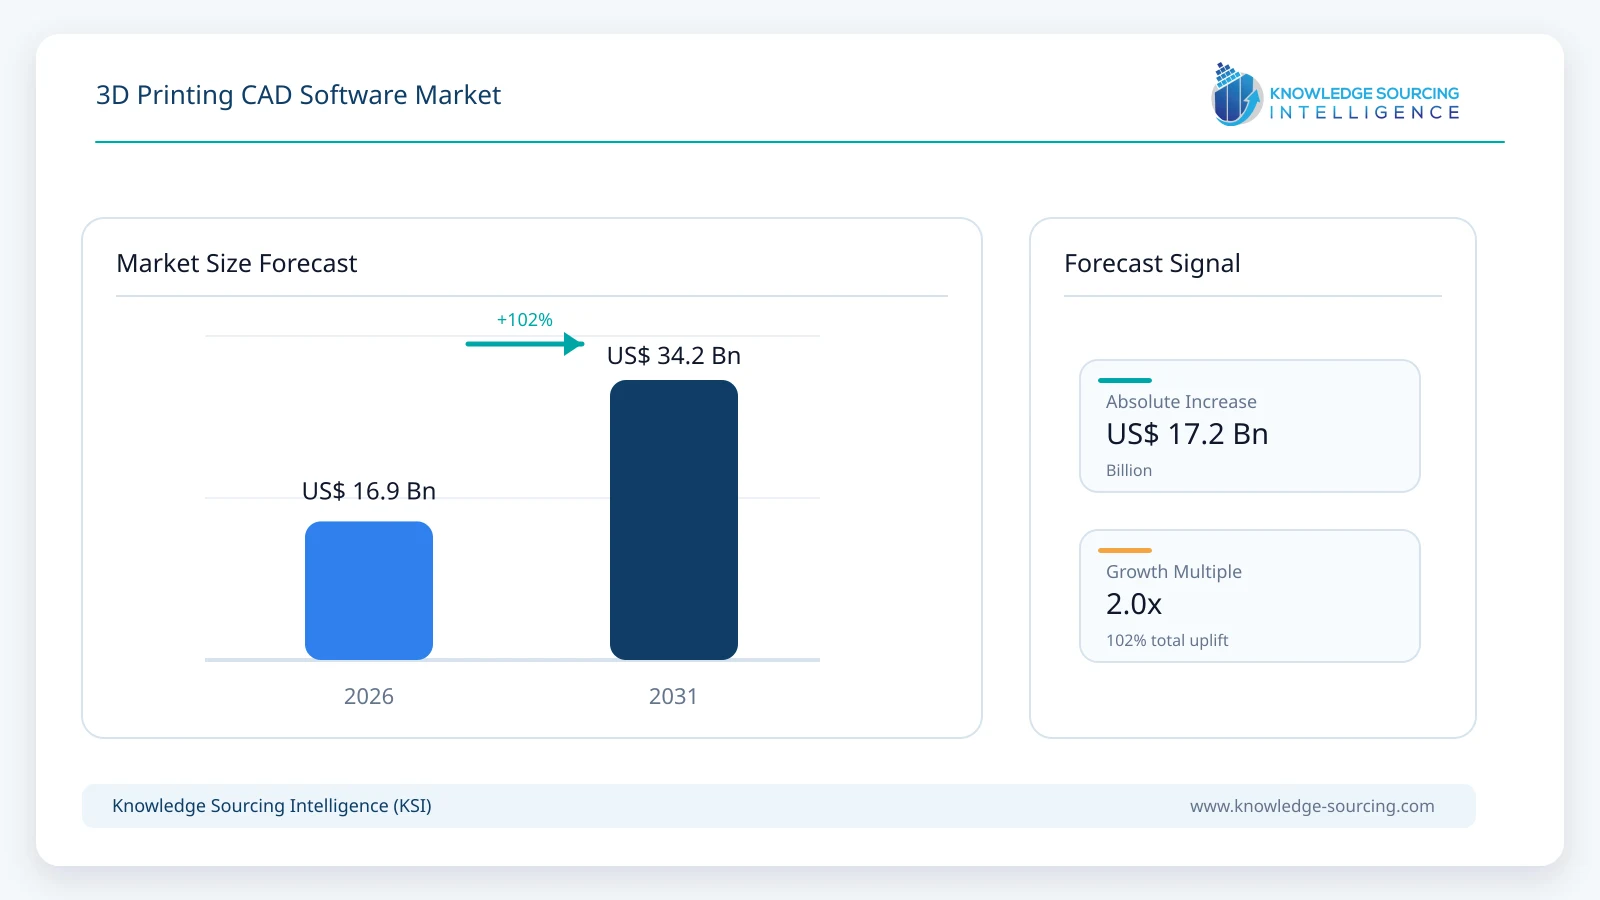
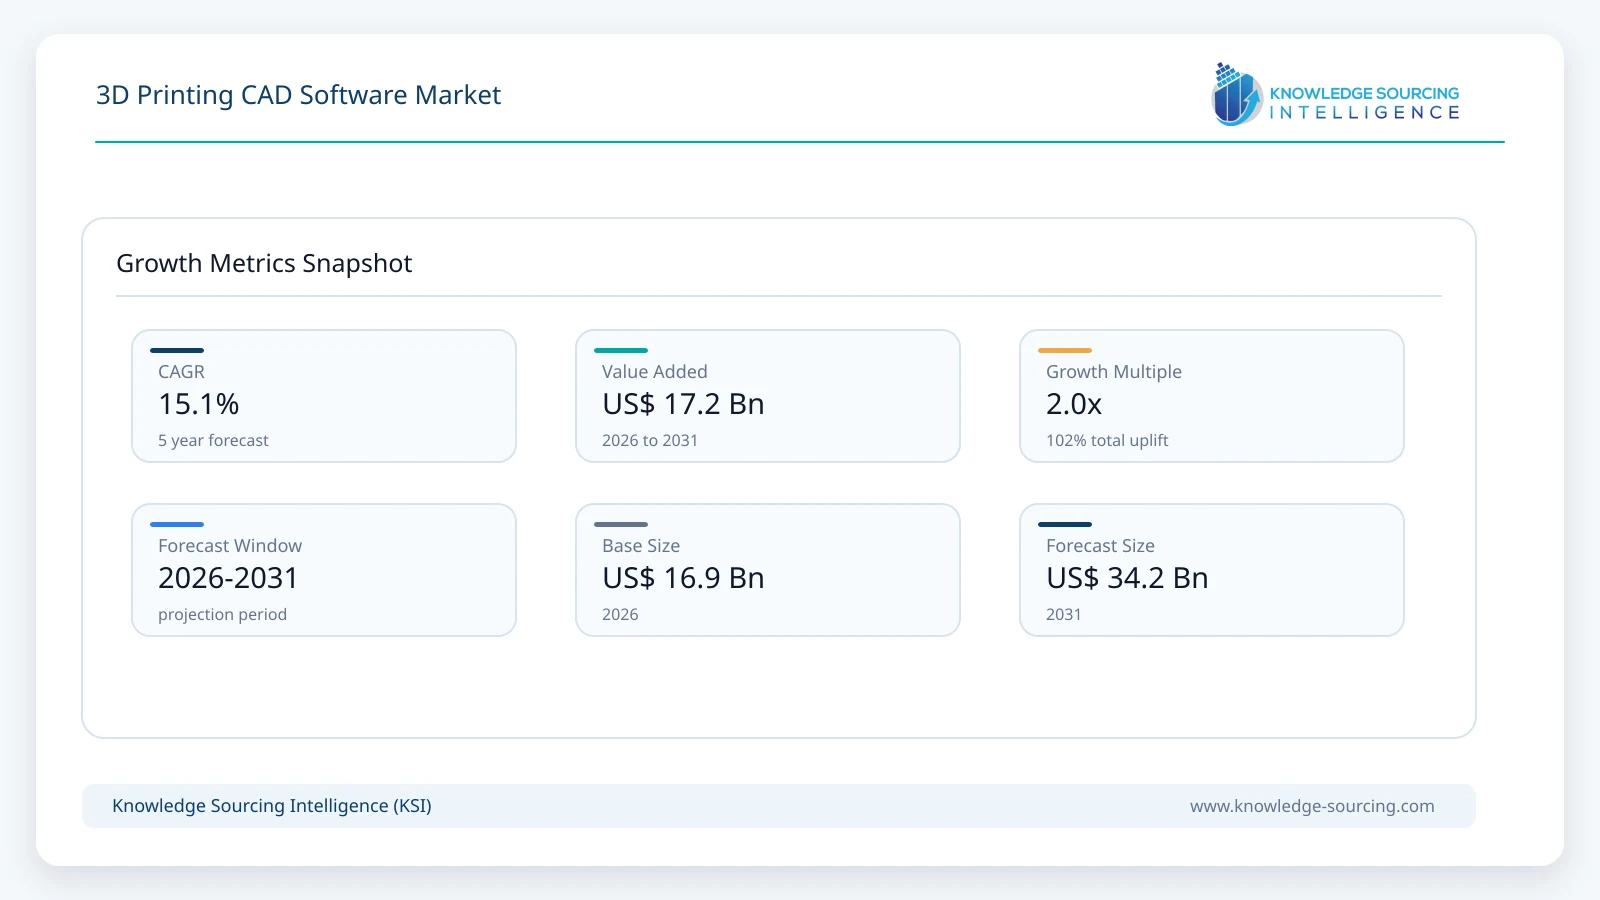
The global 3D Printing CAD Software Market is expected to expand at a CAGR of approximately 15.1%, reaching an estimated market size of USD 34.16 billion in 2031 from USD 16.91 billion in 2026.
Highlights:
- 1Broad CAD platforms compete with specialized additive-design tools as industrial users seek lattice modeling, revision control, manufacturability checks and downstream file compatibility.
- 2Automotive, aerospace and healthcare buyers require printable geometries that can be reviewed against engineering, material and process constraints, not only visually inspected.
- 3Cloud access is increasingly associated with design collaboration, managed revisions and distributed engineering teams, while locally managed installations remain important for controlled programs.
- 4Implicit and lattice modeling address complex internal structures whose data volumes and editing requirements challenge conventional CAD workflows.
- 5Interoperability is becoming more important as engineering models pass into specialist preparation tools; the 3MF specification received ISO/IEC recognition in 2025.
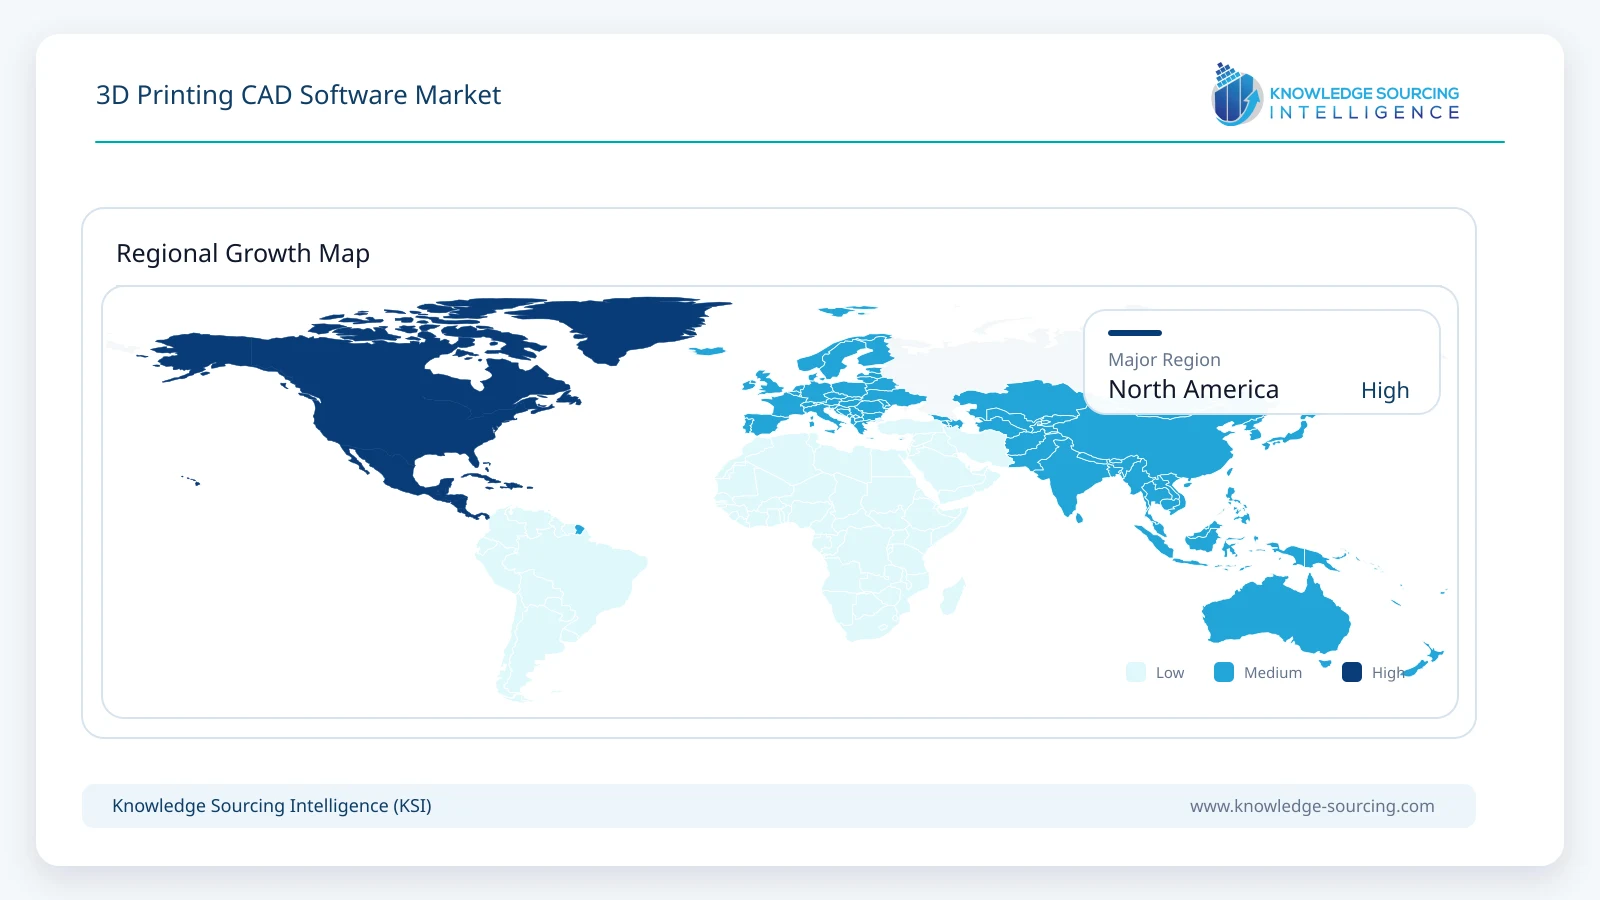
- 6North America offers an established engineering-software customer base, while Asia Pacific benefits from expanding manufacturing design capabilities and additive-manufacturing activity.
3D printing CAD software enables designers and engineers to construct, modify, and validate digital objects intended for additive manufacturing. Parametric solid modeling, direct modeling, surface design, topology optimization, and lattice generation support different levels of design complexity. The same digital model may be used to evaluate fit, strength, part consolidation and producibility before it is transferred into a manufacturing-preparation environment. For industrial buyers, the most valuable capability is not simply the ability to export an STL file, but to preserve accurate geometry, revisions and manufacturing intent across successive engineering decisions.
The commercial customer base extends from industrial product developers and automotive engineering teams to aerospace contractors, medical-device manufacturers and architectural specialists. Autodesk Fusion, Dassault Systèmes SOLIDWORKS and 3DEXPERIENCE, Siemens Designcenter and PTC Onshape supply broad engineering platforms; nTop and other specialists address geometries that are difficult to construct with conventional boundary-representation modeling. Subscription access, enterprise administration, data interoperability and workflow integration affect software spending alongside the underlying design capabilities.
Market Overview
Industrial additive manufacturing imposes geometric rules that differ from those used in machining and molding. Engineers must consider build orientation, wall thickness, access for support removal, minimum features, surface finish, and anisotropic mechanical behavior. Software platforms that expose these constraints during design can reduce late-stage geometry repairs and unnecessary printing iterations. In regulated products, traceable revisions and verified design inputs are as important as the flexibility to construct complicated shapes.
Siemens identifies lattice generation, manufacturability checks, and direct handling of convergent geometry as core design-for-additive-manufacturing capabilities in Designcenter. Dassault Systèmes supports additive-oriented lattice and implicit design within its 3DEXPERIENCE ecosystem, while Autodesk connects modeling with additive setup and manufacturing workspaces in Fusion. Specialized platforms such as nTop concentrate on reusable computational design workflows and the translation of dense cellular structures into formats that other design and production systems can process.
Software procurement now involves more than the engineering workstation. Industrial customers evaluate named-user and floating licenses, cloud-data controls, PLM interfaces, access for external suppliers, advanced optimization modules, and support for printer-specific preparation applications. A vendor that integrates the complete design-to-production process may capture a larger software budget, but interoperability with an existing CAD estate often matters more than replacing the entire design environment. This combination supports competition between established platform vendors and focused specialists.
Market Trends
Implicit Geometry and Lattice Workflows Move Into Production Design
Lightweight aerospace parts, porous medical implants and heat-transfer structures require geometric detail that can overwhelm conventional solid-modeling workflows. Implicit representations and computational lattices give engineers a practical way to define repeating internal architecture through rules rather than manually modeling thousands of individual elements. Siemens' Designcenter additive workflow and nTop's implicit modeling illustrate how geometry representation has become a competitive product feature rather than a peripheral export option.
Manufacturers still need the complex geometry to survive downstream revision, simulation, and build preparation. nTop promotes an implicit interchange format to transfer such designs without excessively large mesh files; Materialise provides CAD-and-mesh preparation workflows to process designs for printing. Suppliers that preserve editable design intent while supporting reliable manufacturing translation are better positioned for recurring enterprise adoption than isolated geometry generators.
Cloud CAD Is Being Bought as a Collaboration and Governance System
Distributed engineering teams increasingly review digital parts alongside suppliers, contract manufacturers and qualification personnel. PTC's browser-native Onshape combines CAD with product-data management, while Autodesk Fusion links design work to collaborative data services. Buyers value controlled access, revision histories and simultaneous engineering because a printing-ready shape must remain associated with its approved design and manufacturing settings.
Cloud deployment does not remove the need for security review or local engineering performance. Defense contractors, healthcare-device businesses and enterprises with restricted design information may insist on private governance, export-control screening and controlled supplier access. This creates a mixed procurement environment in which cloud-native subscriptions compete with on-premises CAD, hybrid services and enterprise-hosted architectures rather than replacing them uniformly.
Design and Manufacturing Preparation Are Converging
Traditional production workflows pass CAD geometry into separate applications for mesh repair, orientation, support design and slicing. Each handoff creates opportunities for conversion loss, broken references and repeated engineering decisions. Autodesk's July 2026 Fusion release added additive sub-nest arrangement and slice-area analysis, while Materialise Magics 30 introduced support for implicit geometries and additional design preparation controls. These changes shorten the distance between design engineering and machine execution.
The purchasing effect is selective rather than universal. Production users may pay for integrated software extensions that remove repeated manual steps, but established factories still retain specialist preparation tools where printer fleets, materials or validation requirements demand them. CAD suppliers therefore compete through connected data and workspaces, while independent vendors defend value with cross-machine workflows and detailed manufacturing expertise.
Interoperable Manufacturing Data Is Gaining Strategic Value
AM production involves more information than a triangulated surface: unit scale, color, materials, identifiers, and sometimes lattice or toolpath instructions must move consistently between applications. Recognition of 3MF under ISO/IEC 25422:2025 strengthens a standards-based alternative to workflows that rely almost exclusively on STL. Design teams can evaluate the format as part of a controlled exchange between CAD, collaboration, preparation, and printing tools.
The commercial benefit depends on actual implementation, not the publication of a standard alone. CAD applications and machine software vary in the extensions and metadata they support, so customers must test exchange of specific attributes before qualification. Vendors able to demonstrate reliable transfers across several design and manufacturing systems can lower switching friction and improve their chances of being selected for multi-site deployments.
Segment Analysis
By End User: Automotive
Automotive engineering is a significant source of paid 3D modeling demand because OEMs and Tier 1 suppliers use additive methods to make functional prototypes, development fixtures, assembly aids, and selected performance parts. Complex castings or joined assemblies can sometimes be redesigned as fewer pieces, but printable geometry still needs controlled tolerances, repeatable material properties, and production planning. Siemens Designcenter and Autodesk Fusion connect familiar engineering models to design-for-additive checks and manufacturing workflows, reducing the effort required to test successive component variants.
Automotive purchasing is driven by shared vehicle-platform engineering and strict supplier interfaces rather than printer ownership alone. A design change must remain traceable through prototype review, dimensional inspection, and eventual manufacturing release; this favors established CAD platforms with reliable version history. The sector represents approximately 23% of the estimated 2026 end-user market value, although the proportion is expected to moderate slightly as specialized aerospace and healthcare applications gain importance.
By Deployment: Cloud
Cloud-based CAD is a substantial and expanding deployment category because product teams need shared model access, centrally managed revisions and controlled collaboration across suppliers and manufacturing sites. PTC Onshape integrates CAD and product-data management in a browser-native architecture, while Autodesk Fusion combines engineering tools with connected project data. Cloud solutions account for an estimated 54% of deployment value in 2026, with increasing importance as professional subscriptions replace fragmented local software administration.
The leading cloud platforms are increasingly evaluated as engineering governance systems, not simply remote substitutes for desktop modeling. Browser-based review, controlled release history and centrally administered permissions help suppliers work from approved geometry and identify design changes before production. On-premises software remains important for restricted projects and exceptionally complex data environments, creating demand for hybrid connectivity and security features within an otherwise growing cloud market.
Cloud purchasing is expected to gain share through 2031 as multi-location design teams adopt subscriptions and expand access beyond specialist workstations. Software developers still need to provide dependable geometry handling, export options and interfaces with plant-floor preparation software, since remote collaboration alone cannot establish the manufacturability of a printed component.
Market Drivers
Complex Geometries Require More Capable Design Tools
Additive manufacturing makes internal channels, porous structures, and consolidated assemblies practical, but these features are difficult to maintain with basic mechanical CAD. Designcenter's lattice tools and nTop's implicit workflows show why specialist functionality carries commercial value. Engineering groups adopting metal printing or advanced polymer processes often need higher software tiers or complementary design modules to create manufacturable geometries.
Additional design complexity also increases the importance of simulation and revision control. A valid structure must meet loading, clearance, thermal, and inspection requirements throughout development, creating continuing demand for qualified design applications rather than a one-time modeling purchase.
Connected Engineering Workflows Reduce Repeat Work
Disconnected CAD, mesh-repair and build-preparation processes can force engineers to reconstruct surfaces or reapply design changes at multiple stages. Autodesk Fusion and Materialise Magics demonstrate competing ways to reduce that friction through integrated capabilities and more reliable CAD imports. For customers running repeated development iterations, avoided data repair and engineering time can justify additional software licensing.
Purchasing decisions increasingly involve engineering management and manufacturing operations together. Companies assessing subscriptions are likely to prioritize model continuity, managed libraries and effective transfers into production systems where those factors reduce time spent on non-productive work.
Medical Device Customization Raises Design and Documentation Needs
Additively manufactured implants, dental devices and surgical guides often require patient- or application-specific geometry. The US FDA identifies these as actual medical applications and provides technical guidance covering design and manufacturing considerations. Software must support precise geometry, reviewable changes and production-ready files within documented quality procedures.
Patient-specific development introduces more design variants and documented approvals than conventional standardized devices. Hospitals and medical manufacturers therefore need reliable model revision, geometry validation and manufacturability controls, supporting recurring demand for professional CAD and specialist engineering applications rather than occasional visualization tools.
Subscription Platforms Make Advanced CAD More Accessible
A small product developer may prefer a monthly or annual subscription over a large upfront workstation-software commitment. Cloud-native and connected CAD platforms can provide access to collaborative modeling, standard updates and shared model libraries without the infrastructure required for a traditional enterprise rollout. PTC's Onshape and Autodesk's Fusion exemplify that access model.
Accessibility supports a larger addressable user population, but it does not mean every registered account generates enterprise-level revenue. Growth depends on converting occasional design activity into recurring paid use, expanding capability tiers and retaining customers as their printed products move from prototypes into more controlled production programs.
File Standards Improve Multi-Vendor Manufacturing Integration
A manufacturer using different CAD packages and printers needs geometry and material information to travel through several software environments. ISO/IEC 25422:2025 recognition of 3MF gives vendors and users a consistent framework for data exchange. The 3MF Consortium also maintains an application-compatibility matrix, making support for the core format and individual extensions visible.
Manufacturers remain responsible for validating file transfer in their own processes. Nevertheless, standardized exchanges can reduce avoidable translation work and make it easier to retain established CAD tools when adopting additional printers or specialist preparation software.
Market Restraints
Enterprise CAD Qualification and Migration Costs
Changing a primary CAD environment affects templates, libraries, automated scripts, PLM connections, design histories and supplier collaboration. Aerospace and automotive buyers may have years of approved engineering practice built around a particular platform. A newer design application can offer strong additive functions without being a realistic replacement for an established multi-site system.
Suppliers must therefore support interoperability and incremental deployment while proving that feature improvements justify retraining and validation. Procurement complexity can favor extensions to incumbent software and slow migration to competing systems even where new technical capabilities are attractive.
Engineering Talent and Design-for-Additive Skills
Generating a printable model requires process understanding beyond ordinary shape construction. Engineers need to account for unsupported overhangs, minimum wall dimensions, trapped powder, distortion, part orientation, and post-processing access. Advanced lattice or generative tools may increase design freedom while introducing new analytical skill requirements.
A shortage of staff able to interpret simulations and manufacturing constraints can limit utilization of high-end CAD licenses. Buyers may defer specialized modules until training, application support and internal design standards reach a level where the additional features create repeatable production benefits.
Software Interoperability Remains Incomplete
A valid CAD export can still lose parameters, metadata or complex lattice detail when it passes through another application's mesh or preparation process. Materialise's continuing CAD import updates and nTop's focus on implicit interchange demonstrate that data transfer remains an active engineering problem. The 3MF standard improves the framework, but implementation of extensions differs between software vendors.
Companies using several additive technologies must conduct process-specific exchange tests rather than assume a common filename guarantees equivalent manufacturing results. Repair effort and integration projects can offset part of the productivity gain from software modernization.
Security and Intellectual-Property Requirements Constrain Cloud Adoption
Cloud CAD can make supplier collaboration easier, but product geometry may contain proprietary designs, defense-controlled information, or sensitive patient-related data. Customers must evaluate access rights, data residency, identity controls, export restrictions, and the contractual responsibilities of software vendors. These requirements are particularly visible in aerospace, defense, and medical-device engineering.
Organizations with restricted data environments may require on-premises installations, private configurations or limited sharing even when cloud-native functionality is desirable. Vendors unable to satisfy such controls can face lengthy sales cycles or exclusion from specific customer programs.
Additive Economics Limit Demand for Specialized Features
Many industrial components are still produced more economically through conventional subtractive or formative manufacturing, particularly at large production volumes. A CAD function that enables complex lattices creates limited value if a customer cannot qualify an economically viable printing process or material. Software investment therefore follows the business case for actual end-use printing and advanced prototyping.
Engineering firms may retain basic modeling seats and purchase specialized design tools only for selected production programs. A limited number of qualified parts, poor machine utilization or expensive post-processing can postpone premium software purchases even when the design technology is capable of producing more sophisticated geometry.
Regional Outlook
North America
North America represents approximately 34% of the global market value in 2026. The United States combines large aerospace and medical-device engineering sectors with mature software procurement and established additive-manufacturing programs. Autodesk and PTC provide widely used design environments, while independent computational-design specialists address advanced lattice and optimization requirements. Customers increasingly assess CAD alongside software governance, manufacturing qualification and intellectual-property protection.
Production-grade adoption depends on more than a favorable design-tool ecosystem. Defense and healthcare customers must control technical data and verify manufacturing outputs, which supports both enterprise platforms and specialist integration services. Canadian and Mexican engineering operations also participate through cross-border product development and manufacturing supply chains.
Asia Pacific
Asia Pacific is the fastest-growing major region, with its share moving from approximately 30% in 2026 toward 35% in 2031. China, Japan, South Korea and India contain expanding industrial design, electronics, automotive and manufacturing communities capable of adopting professional CAD and additive methods. Demand ranges from rapid product development to production tooling and selected end-use components. Global software suppliers compete with local engineering practices and procurement preferences across very different industrial structures.
Cloud collaboration is useful for regional suppliers working with multinational customers, but software budgets, digital skills and data-governance requirements vary substantially by country. Companies that combine strong modeling, localized support and interoperability with installed manufacturing software are positioned to benefit as additive applications become more demanding.
Competitive Landscape
3D printing CAD software competition has two overlapping layers. Broad mechanical-design platforms, including Autodesk, Dassault Systèmes, Siemens and PTC, sell robust geometry construction, assemblies, engineering data management and manufacturing interfaces. Specialized firms such as nTop focus on computational workflows and complex additive geometries. Customers often purchase both categories because a high-end lattice design may still need to exchange data with an incumbent enterprise CAD and PLM system.
Materialise competes closer to the transition from design into additive preparation, where CAD handling, mesh editing and printability are commercial priorities. Trimble, Robert McNeel & Associates and Shapr3D address different professional and smaller-team design workflows that can lead to printed prototypes or specialty products. Vendors compete on application fit, workflow automation, licensing flexibility, compatible file formats and the cost of training engineers.
Enterprise buyers increasingly compare vendors on geometry fidelity, design revision control, compatibility with existing engineering software and qualification support. Providers that can maintain model integrity from computational design into an established production workflow can earn recurring subscriptions even when the customer's primary CAD platform does not change.
Recent Developments
September 2026: Autodesk introduced product manufacturing information authoring in Fusion's Design workspace, helping retain dimensions and manufacturing instructions alongside CAD models as parts move toward production.
July 2026: PTC launched Onshape Labs as an early-access initiative for emerging AI capabilities in its cloud-native CAD/PDM platform; it was an opt-in development program, not evidence of universal deployment.
July 2026: Autodesk released a Fusion update adding additive sub-nest arrangement, slice-area analysis for powder-bed processes and additional volumetric-lattice controls, strengthening the design-to-build workflow.
June 2026: Siemens consolidated the NX CAD identity under Designcenter, bringing its cloud and on-premises engineering offerings into a common design portfolio; this was a portfolio update, not a newly disclosed additive-manufacturing deployment.
June 2026: Materialise released Magics 30 with support generation for implicit geometry and new lattice-related capabilities, strengthening complex-geometry preparation for additive printing.
July 2025: The 3MF Consortium announced recognition of 3MF as ISO/IEC 25422:2025, improving the standards foundation for cross-vendor exchange of additive-manufacturing model information.
Market Outlook
CAD suppliers will have to support increasingly complicated geometries without forcing customers to abandon established product-development data. Implicit models, lattice optimization and manufacturability analysis are likely to move deeper into the engineering workflow, but production users will continue to require editable geometry, controlled revisions and reliable translation into downstream tools. Those requirements favor vendors that connect design capability with actual qualification and manufacturing practice.
Cloud platforms can gain adoption through supplier collaboration and simplified administration, while on-premises and hybrid models remain relevant for restricted engineering programs. Competitive differentiation is likely to shift toward traceable design-to-production workflows and defensible productivity benefits rather than the number of available modeling commands.
Longer-term software procurement will depend on whether additive projects mature into repeatable production in each end market. Advanced engineering functionality is more likely to command durable subscription spending when it supports qualified printed parts, reduces design rework and integrates with the tools that manufacturers already use.
3D Printing CAD Software Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 16.91 billion |
| Total Market Size in 2031 | USD 34.16 billion |
| Forecast Unit | Billion |
| Growth Rate | 15.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | End-user, Deployment, Geography |
| Companies |
|
Market Segmentation
By End-user
Healthcare
Automotive
Aerospace and Defense
Construction
Others
By Deployment
Cloud
On-Premises
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Size and Growth, 2026-2031
1.3. End-User and Deployment Outlook
1.4. Regional Opportunity Summary
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Complex Geometries Require More Capable Design Tools
3.1.2. Connected Engineering Workflows Reduce Repeat Work
3.1.3. Medical Device Customization Raises Design and Documentation Needs
3.1.4. Subscription Platforms Make Advanced CAD More Accessible
3.1.5. File Standards Improve Multi-Vendor Manufacturing Integration
3.2. Market Restraints
3.2.1. Enterprise CAD Qualification and Migration Costs
3.2.2. Engineering Talent and Design-for-Additive Skills
3.2.3. Software Interoperability Remains Incomplete
3.2.4. Security and Intellectual-Property Requirements Constrain Cloud Adoption
3.2.5. Additive Economics Limit Demand for Specialized Features
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Parametric and Direct CAD Modeling
4.2. Lattice, Implicit and Generative Geometry
4.3. Design-for-Additive-Manufacturing Validation
4.4. CAD-to-Print Interoperability and 3MF
4.5. Cloud-Native CAD and PDM
4.6. Design-to-Manufacturing Integration
5. 3D PRINTING CAD SOFTWARE MARKET BY END-USER
5.1. Introduction
5.2. Healthcare
5.3. Automotive
5.4. Aerospace and Defense
5.5. Construction
5.6. Others
6. 3D PRINTING CAD SOFTWARE MARKET BY DEPLOYMENT
6.1. Introduction
6.2. Cloud
6.3. On-Premises
7. 3D PRINTING CAD SOFTWARE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Autodesk, Inc.
9.2. Dassault Systèmes SE
9.3. Siemens AG
9.4. PTC Inc.
9.5. Hexagon AB
9.6. nTop, Inc.
9.7. Materialise NV
9.8. Trimble Inc.
9.9. Robert McNeel & Associates
9.10. Shapr3D Zrt.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











