
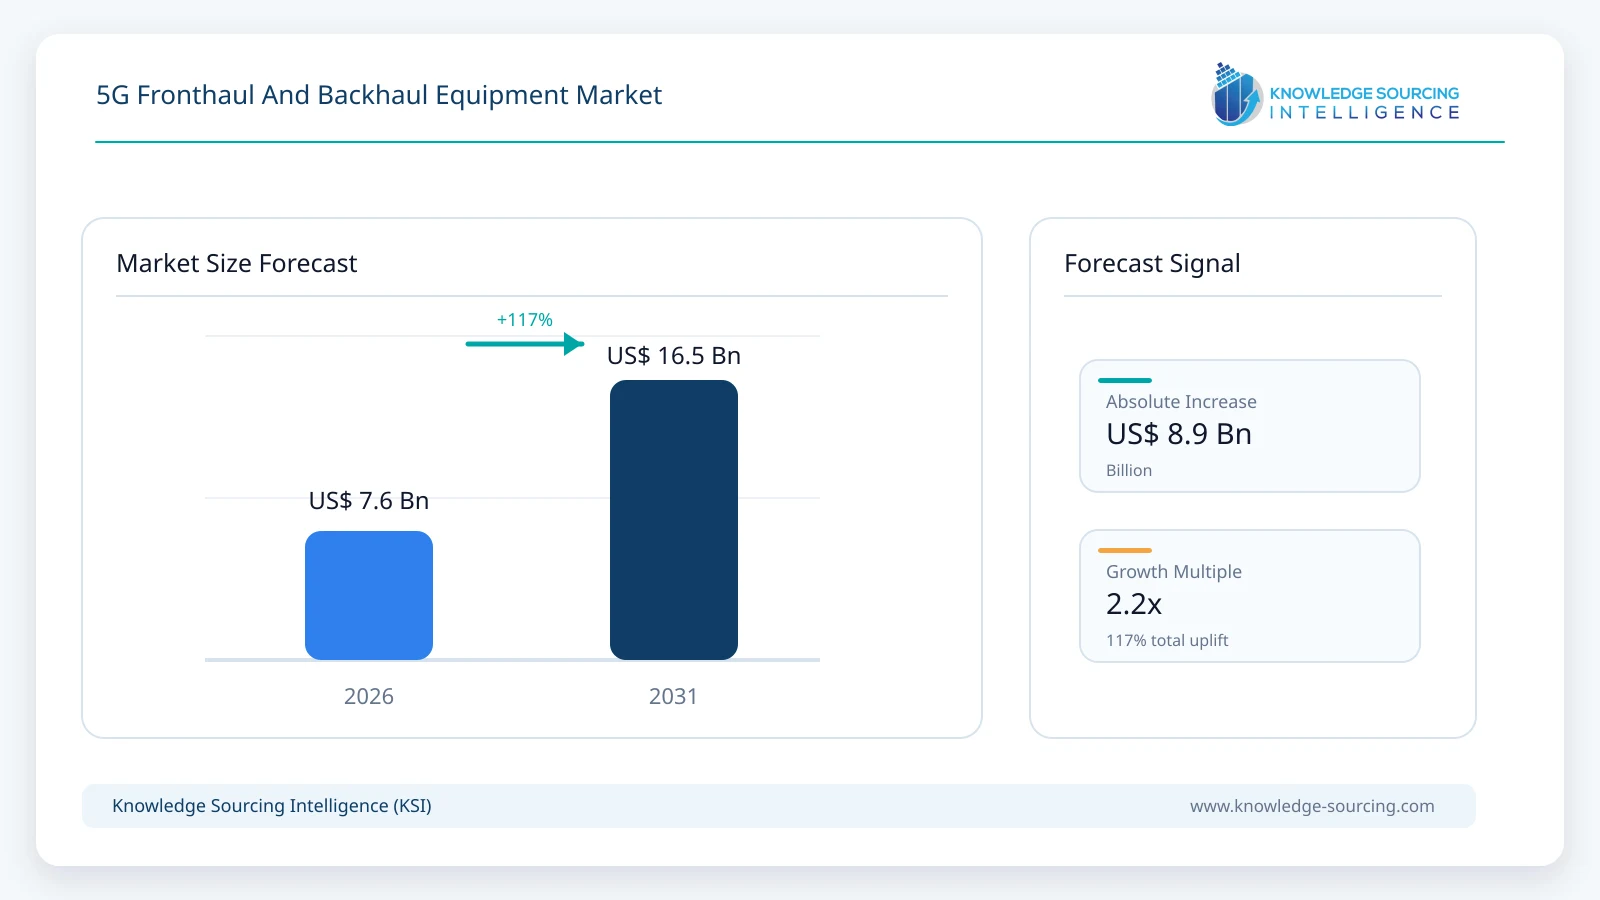
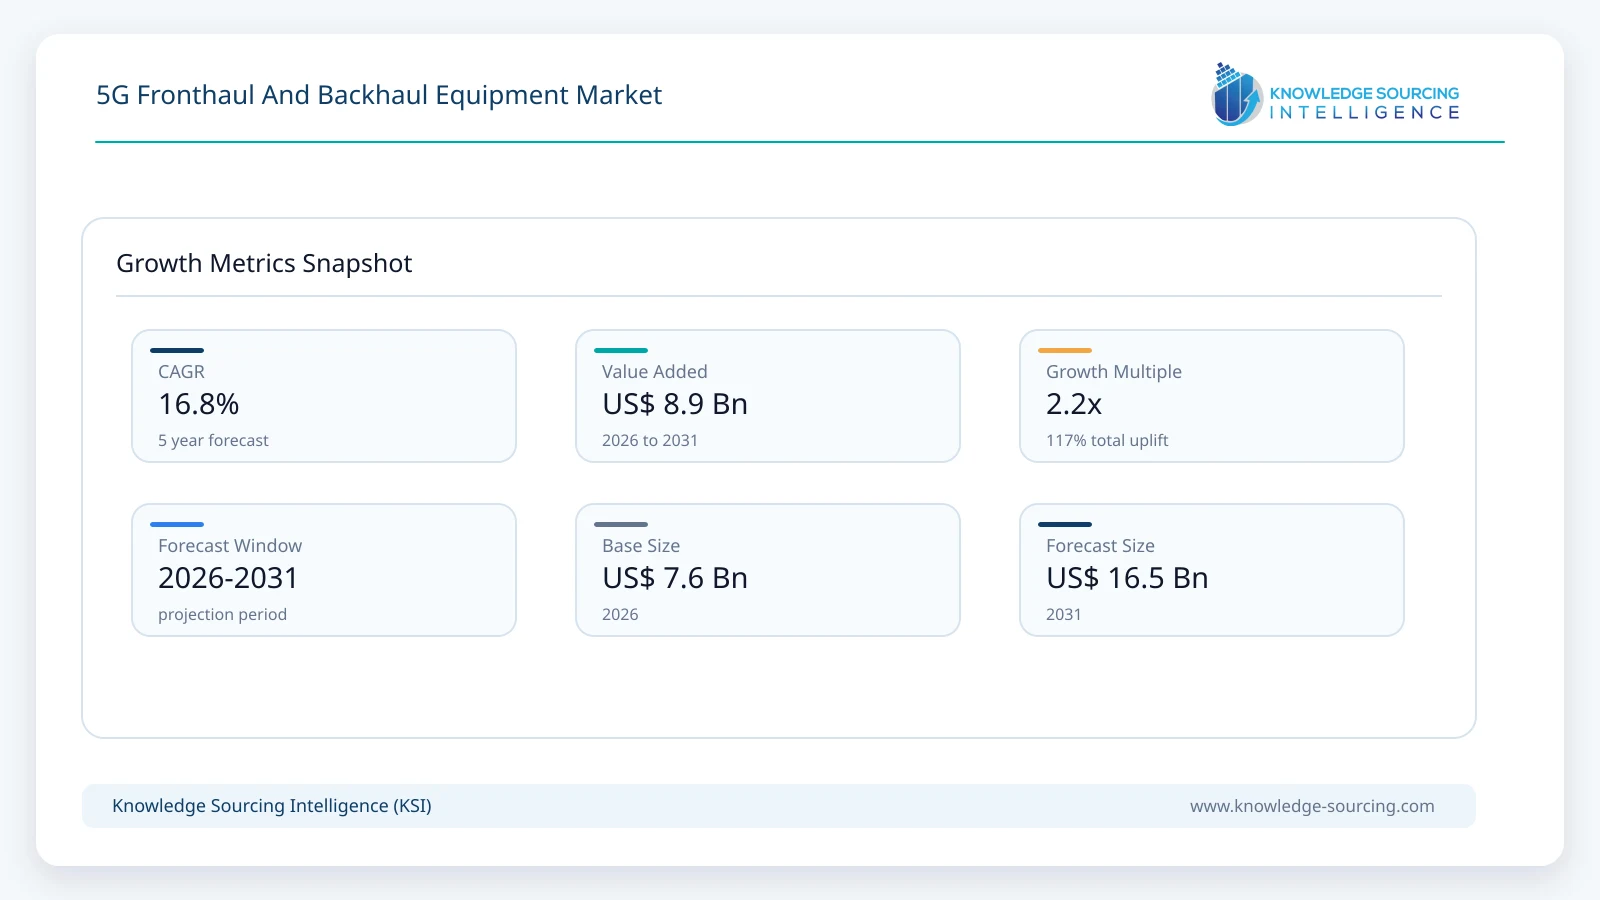
The Global 5G Fronthaul and Backhaul Equipment market is forecast to grow at a CAGR of 16.8%, reaching USD 16.5 billion in 2031 from USD 7.6 billion in 2026.
Highlights:
- 1Fronthaul equipment accounts for approximately 38% of global market value in 2026, with its position strengthening as C-RAN, Open RAN and cloud RAN deployments increase.
- 2Wireless transport represents approximately 39% of market value in 2026, supported by microwave, E-band and multi-band deployments where fiber is unavailable or uneconomic.
- 3Asia Pacific accounts for approximately 40% of global market value in 2026, supported by large installed 5G networks and continued investment across China, India, Japan and South Korea.
- 4Global 5G subscriptions reached approximately 3.1 billion during the first quarter of 2026 and are forecast to reach 6.4 billion by 2031.
- 5Global mobile data traffic is forecast to reach approximately 328 EB per month by 2031, compared with 146 EB per month in 2025.
The market includes transport equipment deployed between 5G radio units, distributed or centralized processing locations, aggregation networks, and mobile cores. Fronthaul connects radio units or remote radio heads with distributed or centralized baseband functions, while backhaul carries aggregated RAN traffic toward the core network. The market includes optical transport systems, WDM and OTN equipment, packet and IP transport platforms, PON-based systems, microwave and millimeter-wave radios, synchronization equipment and directly associated transport-network management capabilities.
The revised forecast is materially below KSI's previous 37.7% growth assumption. The earlier 2026 market base was broadly plausible, but extending that value to USD 36.77 billion by 2031 overstated the likely equipment cycle. Dell'Oro expects current 5G deployment to support approximately two more years of growth in point-to-point microwave transmission before mobile-backhaul demand moderates ahead of the next major radio cycle. At the same time, Ericsson forecasts 5G subscriptions to increase to 6.4 billion by 2031 and total mobile data traffic to reach approximately 328 EB per month, indicating that transport investment continues even where basic coverage is already established.
Modern transport networks are also becoming more converged. Rather than constructing entirely separate networks for fronthaul, midhaul and backhaul, operators increasingly use packet, optical, PON and microwave infrastructure within common mobile-anyhaul architectures. Nokia describes this evolution as a combination of IP, optical, xPON and microwave technologies capable of supporting distributed, centralized and cloud RAN configurations while meeting latency, synchronization and capacity requirements.
Market Trends
Open Fronthaul Is Increasing Transport Requirements
RAN disaggregation separates radio units from distributed and centralized processing functions, increasing the importance of standardized transport between these elements. Open RAN architectures use standardized fronthaul interfaces such as the O-RAN 7.2x split, while packet-based eCPRI improves bandwidth efficiency compared with traditional CPRI implementations. These changes support demand for Ethernet-based fronthaul switches, active and passive WDM, packet-optical platforms, timing equipment and high-capacity optical links capable of maintaining strict latency and synchronization requirements.
The commercial importance of fronthaul is therefore increasing faster than the overall installed backhaul base. Operators adopting centralized processing can reduce duplication of baseband resources and improve resource utilization, but these benefits depend on sufficiently capable transport. Fronthaul investment is consequently concentrated where fiber availability, network density and RAN architecture justify centralization, rather than becoming universal across every radio site.
Fronthaul, Midhaul and Backhaul Are Converging
Operators increasingly seek to use one transport architecture across multiple RAN interfaces and network generations rather than operate separate overlays. Nokia's mobile-transport portfolio supports combinations of IP, optical, xPON and microwave technologies and describes the move toward mobile anyhaul, in which fronthaul, midhaul and backhaul are managed through a common programmable transport fabric.
This convergence is commercially important because 4G and 5G networks coexist for many years. Transport systems therefore need to support legacy CPRI traffic, packet-based eCPRI, Ethernet, F1 interfaces and conventional backhaul simultaneously. Operators can increase utilization of existing fiber and aggregation assets instead of replacing transport infrastructure every time the RAN architecture changes. Investment consequently shifts toward scalable packet-optical platforms with high-precision timing, service assurance and software-defined control rather than single-purpose transport appliances.
Microwave and E-Band Remain Important Alongside Fiber
Fiber provides extremely high long-term capacity, but deployment economics depend heavily on the availability of ducts, existing fiber routes and civil infrastructure near each radio site. In locations where new fiber construction requires extensive trenching or rights-of-way, high-capacity microwave and E-band systems can provide a significantly faster deployment route.
The technology is also evolving beyond traditional lower-capacity microwave links. E-band radios support multi-gigabit transport, while multi-band systems combine high-capacity millimeter-wave spectrum with lower-frequency microwave links to improve availability. In May 2026, Cellnex began deploying Ericsson's MINI-LINK 6356 high-power E-band radio together with Ericsson's Transport Automation Controller, demonstrating the continued role of wireless transport in European 5G modernization.
Market Drivers
Continued Growth in Mobile Data Traffic
Transport-capacity requirements continue increasing even after initial 5G coverage is established. Ericsson forecasts mobile data traffic to rise from 146 EB per month in 2025 to 328 EB per month in 2031, while the share of traffic carried over 5G increases substantially during the same period.
Higher traffic per radio site requires operators to upgrade links from lower-capacity Ethernet and microwave connections toward 10G, 25G, 100G and higher interfaces depending on network location. Fixed Wireless Access adds further sustained traffic because home broadband usage generates substantially greater data volumes than conventional smartphone connectivity. These trends support continuing investment in optical transport, packet routing, microwave capacity and aggregation systems even where the number of physical macro sites grows more slowly.
5G Standalone and Network Slicing Increase Transport Complexity
5G Standalone allows operators to offer differentiated connectivity, network slicing and service-specific performance characteristics that depend on coordinated behavior across radio, transport and core networks. Ericsson reported that commercial differentiated-connectivity offerings based on 5G SA network slicing increased from 65 to 84 within six months by mid-2026.
Transport networks therefore need to provide appropriate capacity, latency, synchronization, and resilience for different service classes instead of functioning solely as undifferentiated bandwidth pipes. Packet-optical transport platforms increasingly incorporate programmable service-level control and network automation to support these requirements. This raises the value of transport software and synchronization capabilities alongside physical equipment.
Emerging Markets Continue to Expand 5G Networks
Although major developed markets have completed much of their initial 5G radio rollout, large subscriber markets continue to add coverage and capacity. India had approximately 430 million 5G subscriptions at the end of 2025 and is forecast to exceed 1.1 billion by 2031.
Southeast Asia, Africa and Latin America also remain earlier in their deployment cycles. These markets often have less extensive fiber at radio sites, creating additional demand for microwave and multi-band wireless transport. The combination of new coverage, rising smartphone data consumption and FWA deployment therefore extends the 5G transport-equipment cycle beyond markets where nationwide coverage is already mature.
Market Restraints
Initial 5G Infrastructure Deployment Is Maturing in Major Markets
The strongest period of greenfield 5G infrastructure deployment has already passed in China, South Korea, North America and several other markets. Investment increasingly shifts from building entirely new transport links toward increasing capacity on existing infrastructure, replacing selected equipment and introducing cloud or Open RAN architectures.
Dell'Oro's July 2026 outlook expects 5G rollout to support another two years of point-to-point microwave growth before mobile-backhaul equipment demand begins to weaken ahead of the future 6G investment cycle. This limits the likelihood of sustaining the previous KSI forecast's exceptionally high growth rate through 2031, particularly in conventional backhaul equipment.
Transport Technology Economics Vary by Site
No single transport technology provides the lowest-cost solution across every 5G deployment. Fiber is attractive where existing infrastructure is accessible, but new construction can involve substantial civil-work costs and long deployment timelines. Microwave can be deployed much faster but depends on spectrum, propagation characteristics and line-of-sight conditions. E-band provides high capacity but is typically suited to shorter link distances.
Operators therefore use different combinations of direct fiber, WDM, PON, packet transport, microwave and millimeter wave according to site requirements. This reduces the likelihood that any individual technology captures all incremental market growth and makes equipment demand dependent on local network architecture rather than a uniform global migration.
Segment Analysis
By Equipment: Fronthaul
Fronthaul equipment is projected to reach approximately USD 6.85 billion by 2031, supported by the growing separation of radio units from distributed and centralized processing functions. Cloud RAN, centralized RAN and Open RAN increase the amount of traffic that must move between RAN components while introducing stringent latency, timing and synchronization requirements. Nokia's transport architecture supports CPRI, eCPRI, Ethernet and packetized fronthaul over converged optical infrastructure, reflecting the industry's move toward common transport networks capable of supporting several generations and functional splits simultaneously.
Fronthaul deployment remains concentrated in locations where centralizing processing provides sufficient economic or operational benefits. Dense urban networks, shared RAN infrastructure and operators pursuing cloud-native RAN architectures provide the strongest commercial opportunities. Direct fiber remains important, but wavelength multiplexing and packet-based transport improve fiber efficiency where multiple radio sectors or sites need to connect to common processing locations. The segment consequently grows faster than conventional backhaul through 2031 while remaining smaller in absolute installed-market value.
By Type: Wireless
Wireless transport equipment is projected to reach approximately USD 6.9 billion by 2031, supported by continued microwave modernization, E-band adoption and 5G expansion in areas where extending fiber is costly or operationally difficult. Modern wireless backhaul increasingly combines traditional microwave spectrum with E-band links to achieve higher capacity while retaining the availability needed for carrier-grade mobile networks. Ericsson's MINI-LINK portfolio and similar systems from Ceragon, Aviat Networks and other specialist suppliers illustrate this evolution from conventional microwave toward multi-gigabit packet transport.
The segment is particularly important in rural networks, emerging markets and tower locations where civil works would make fiber deployment uneconomic. Wireless systems can also provide temporary or rapid-deployment capacity while operators await fiber construction. Fiber continues to expand and remains preferable for many high-density, long-life sites, but this does not eliminate wireless transport. Instead, the market increasingly develops around a hybrid architecture in which fiber carries the largest aggregation loads while microwave and E-band extend high-capacity connectivity to individual radio sites.
By Geography: Asia Pacific
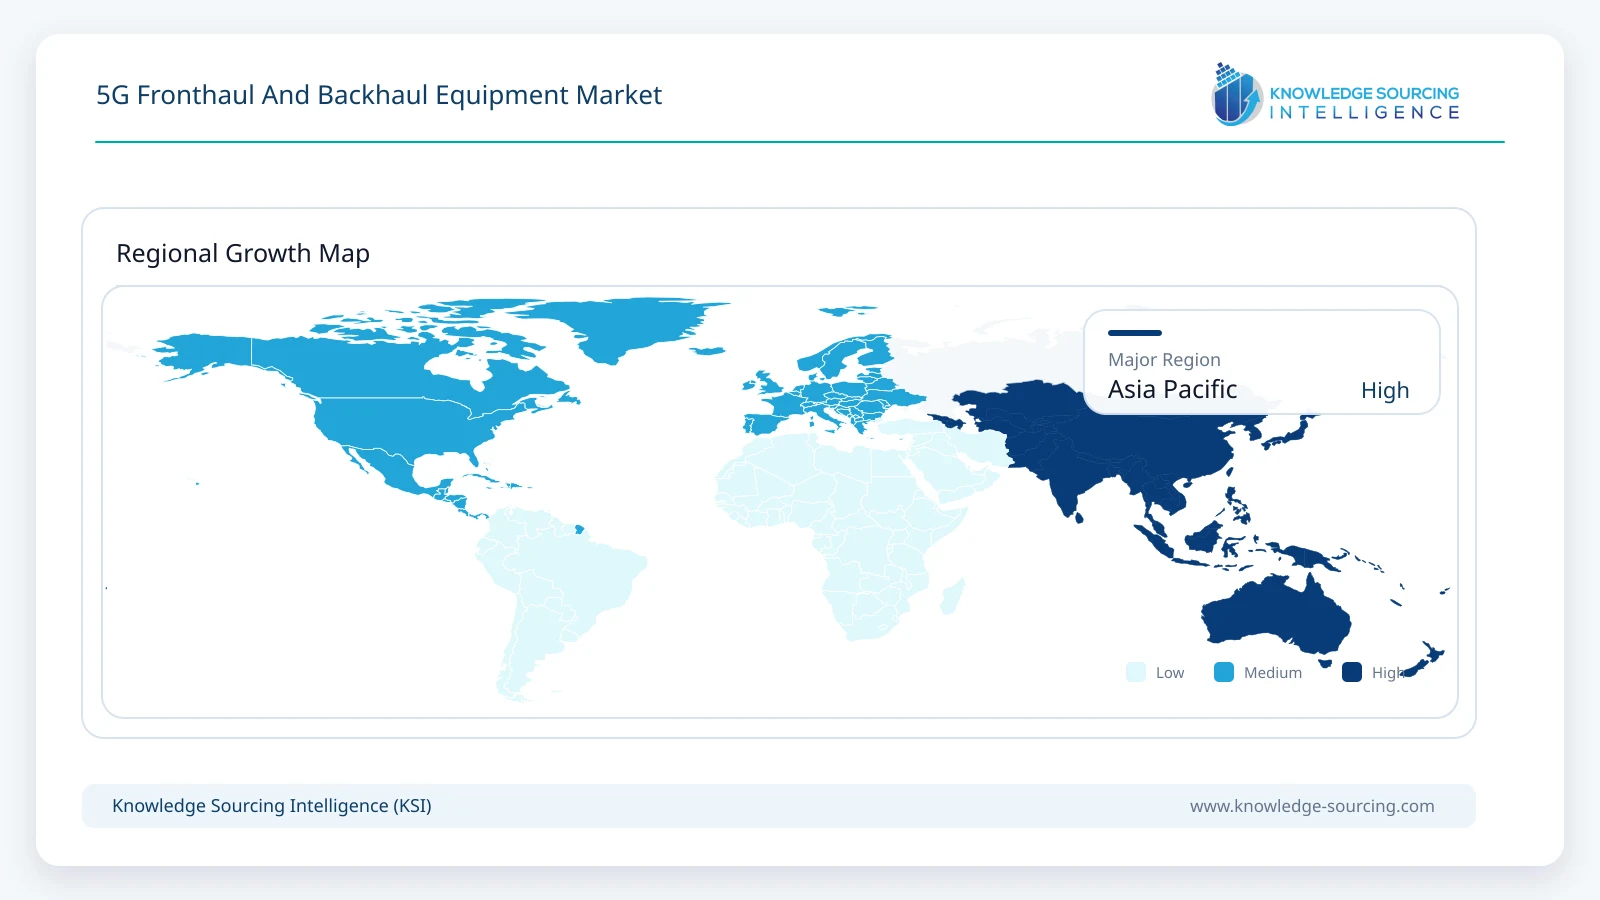
Asia Pacific is projected to reach approximately USD 6.65 billion by 2031, remaining the largest regional market. China provides the world's largest installed 5G infrastructure base, while India continues to add both subscribers and network capacity at considerable scale. Ericsson expects India's 5G subscriber base to exceed 1.1 billion by 2031, while Japan and South Korea increasingly focus on 5G-Advanced, capacity enhancement and modernization of existing networks.
The regional market therefore combines different investment cycles rather than following one common pattern. Mature networks increasingly require optical upgrades, higher-capacity aggregation and new fronthaul for cloud RAN, while later-stage markets continue building new backhaul links. Southeast Asian operators provide further demand as 5G coverage expands and mobile traffic increases. Asia Pacific's large installed radio base and continuing subscriber growth consequently support demand across optical, packet and wireless transport systems through 2031.
Competitive Environment and Analysis
The 5G fronthaul and backhaul equipment market includes integrated telecom-equipment manufacturers, optical-networking vendors, IP-routing suppliers and specialist microwave companies. Ericsson and Nokia maintain broad transport portfolios combining packet networking, microwave and optical technologies. Huawei and ZTE participate across RAN, IP and optical transport, while Cisco and Juniper have stronger positions in packet and routing infrastructure. Ciena, ADTRAN and related optical specialists address high-capacity access and aggregation requirements, while Ceragon, Aviat Networks and SIAE Microelettronica maintain significant specialization in microwave and millimeter-wave transport.
Competitive differentiation extends beyond headline bandwidth. Operators evaluate synchronization performance, latency, spectrum efficiency, automation, energy consumption, interoperability, hardware footprint and support for converged 4G/5G transport. Nokia's Optical Anyhaul platform, for example, combines WDM, packet transport, synchronization and software-defined management for fronthaul and backhaul use cases. Ericsson's Cellnex deployment similarly combines E-band radio equipment with transport automation rather than treating radio and management software as separate procurement decisions.
Recent Developments
July 2026: Dell'Oro Group forecast approximately two further years of growth in point-to-point microwave transmission equipment, supported primarily by continuing 5G deployment.
May 2026: Cellnex became the lead customer for Ericsson's MINI-LINK 6356 high-power E-band radio and began deployment in Poland alongside Ericsson's Transport Automation Controller.
June 2026: Ericsson's Mobility Report indicated that global 5G subscriptions had risen to around 3.1 billion during the first quarter of 2026 and forecast 6.4 billion subscriptions by the end of 2031.
2026: O-RAN technical development continued to strengthen Open Fronthaul interoperability and conformance requirements as operators move toward larger-scale multi-vendor RAN deployments.
2026: Mobile-transport vendors continued integrating IP, optical, microwave and software-defined automation into common anyhaul architectures capable of supporting fronthaul, midhaul and backhaul on shared infrastructure.
Market Outlook
The global 5G fronthaul and backhaul equipment market is undergoing significant expansion, driven by traffic growth, 5G Standalone, fixed wireless access, RAN disaggregation, and transport modernization. These factors are increasingly shaping network investment beyond nationwide first-time 5G deployment.
Fronthaul becomes more important as operators centralize or cloudify RAN processing, while conventional backhaul continues to account for the larger installed requirement. Fiber and optical transport gain capacity share at high-density sites, but wireless transport remains essential where fiber construction is expensive, slow or operationally impractical.
Asia Pacific remains the largest regional opportunity because it combines enormous installed 5G networks with markets still expanding coverage and subscriber penetration. North America and Europe increasingly focus on capacity upgrades, 5G SA and architectural modernization, while Africa, Latin America and parts of Southeast Asia provide a longer runway for new transport links.
The market therefore remains structurally attractive through 2031, but the investment cycle supports a mid-to-high-teens growth rate rather than the previously published 37.7% CAGR.
5G Fronthaul And Backhaul Equipment Market Scope:
Report Metric Details Total Market Size in 2026 USD 7.6 billion Total Market Size in 2031 USD 16.5 billion Forecast Unit Billion Growth Rate 16.8% Study Period 2021 to 2031 Historical Data 2021 to 2024 Base Year 2025 Forecast Period 2026 – 2031 Segmentation Equipment, Type, Geography Companies
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Huawei Technologies Co. Ltd.
- ZTE Corporation
- Samsung Electronics Co. Ltd.
- Cisco Systems Inc.
- Juniper Networks Inc.
- Ciena Corporation
Market Segmentation
By Equipment
Fronthaul
Fiber Direct Connection
Passive WDM
Active WDM / OTN / SPN
eCPRI / Ethernet Fronthaul
Wireless Fronthaul
Backhaul
IP RAN
PON
OTN
WDM
Microwave and Millimeter Wave
Others
By Type
Fixed
Wireless
By Geography
North America
United States
Canada
Others
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Market Estimation
2.4. Segment Modelling
2.5. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. 5G Fronthaul and Backhaul Equipment Market Size, 2026-2031
3.3. Equipment Outlook
3.4. Type Outlook
3.5. Regional Outlook
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Continued Growth in Mobile Data Traffic
4.1.2. 5G Standalone and Network Slicing
4.1.3. Emerging-Market 5G Network Expansion
4.2. Market Restraints
4.2.1. Maturing Initial 5G Infrastructure Cycle
4.2.2. Transport Technology Economics
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Open RAN and Cloud RAN Transport Outlook
4.7. Fiber and Microwave Deployment Economics
5. 5G FRONTHAUL AND BACKHAUL EQUIPMENT MARKET BY EQUIPMENT
5.1. Fronthaul
5.1.1. Fiber Direct Connection
5.1.2. Passive WDM
5.1.3. Active WDM / OTN / SPN
5.1.4. eCPRI / Ethernet Fronthaul
5.1.5. Wireless Fronthaul
5.2. Backhaul
5.2.1. IP RAN
5.2.2. PON
5.2.3. OTN
5.2.4. WDM
5.2.5. Microwave and Millimeter Wave
5.2.6. Others
6. 5G FRONTHAUL AND BACKHAUL EQUIPMENT MARKET BY TYPE
6.1. Fixed
6.2. Wireless
7. 5G FRONTHAUL AND BACKHAUL EQUIPMENT MARKET BY GEOGRAPHY
7.1. North America
7.1.1. United States
7.1.2. Canada
7.1.3. Others
7.2. South America
7.2.1. Brazil
7.2.2. Argentina
7.2.3. Others
7.3. Europe
7.3.1. United Kingdom
7.3.2. Germany
7.3.3. France
7.3.4. Italy
7.3.5. Spain
7.3.6. Others
7.4. Middle East and Africa
7.4.1. Saudi Arabia
7.4.2. UAE
7.4.3. South Africa
7.4.4. Others
7.5. Asia Pacific
7.5.1. China
7.5.2. Japan
7.5.3. India
7.5.4. South Korea
7.5.5. Australia
7.5.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Telefonaktiebolaget LM Ericsson
9.2. Nokia Corporation
9.3. Huawei Technologies Co., Ltd.
9.4. ZTE Corporation
9.5. Samsung Electronics Co., Ltd.
9.6. Cisco Systems, Inc.
9.7. Juniper Networks, Inc.
9.8. Ciena Corporation
9.9. NEC Corporation
9.10. Fujitsu Limited
9.11. Ceragon Networks Ltd.
9.12. Aviat Networks, Inc.
9.13. SIAE Microelettronica S.p.A.
9.14. ADTRAN Holdings, Inc.
9.15. Ekinops S.A.
9.16. Tejas Networks Limited
9.17. Ribbon Communications Inc.
9.18. FiberHome Telecommunication Technologies Co., Ltd.
10. APPENDIX
Navigate
Trusted by the world's leading organizations











