
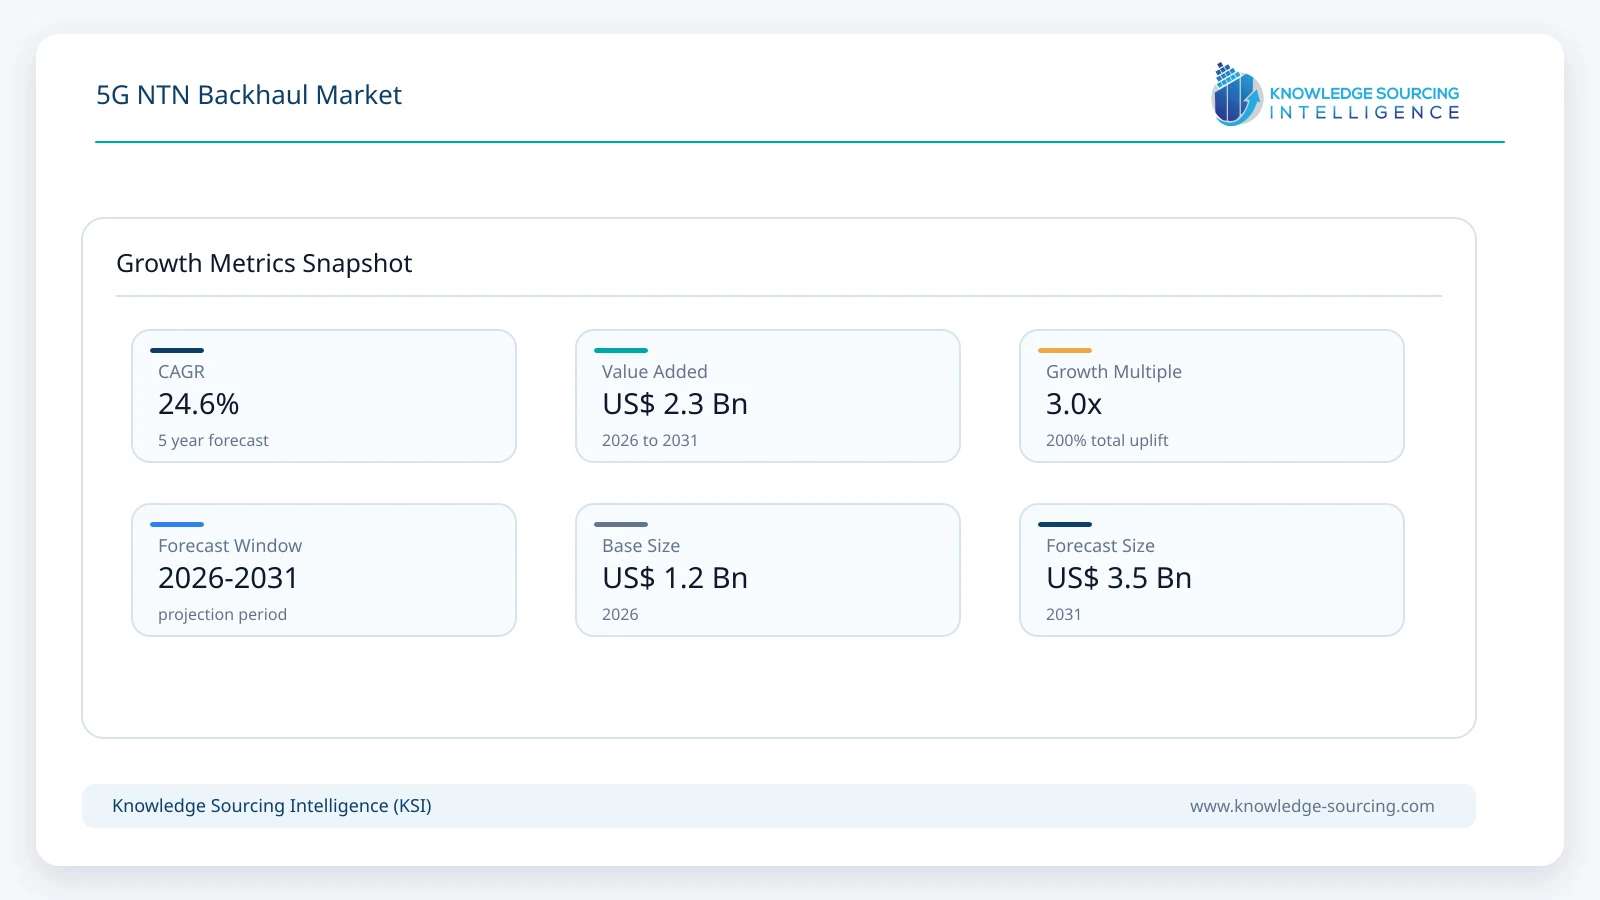
The 5G NTN Backhaul Market is projected to grow at a CAGR of 24.6% over the forecast period, reaching USD 3.48 billion by 2031 from USD 1.16 billion in 2026.
Highlights:
- 1LEO satellite systems account for an estimated 54.0% of market revenue in 2026, supported by lower latency, expanding constellation capacity and increased mobile-operator interest in satellite-connected cell sites.
- 2Public mobile networks represent approximately 69.0% of market demand in 2026, as telecom operators use NTN backhaul primarily to extend coverage and add resilience to terrestrial networks.
- 3North America accounts for an estimated 30.0% of global market revenue in 2026, supported by extensive commercial satellite infrastructure and a large ecosystem of LEO, GEO and satellite-network technology providers.
- 4satellite-backhaul partnership announcements are increasingGSA reported in August 2026 that , as operators use satellite transport both to improve network resilience and to connect terrestrial towers in locations where fiber deployment is uneconomic.
- 51 Gbps download and 400 Mbps uploadVodafone and Amazon Leo announced a commercial program in March 2026 to connect remote 4G and 5G base stations across Europe and subsequently Africa, with satellite backhaul supporting up to .
- 6multi-orbit, software-defined and increasingly 3GPP-aligned architecturesCommercial development is shifting from proprietary satellite transport toward that can integrate more directly with terrestrial 5G networks.
- 7Network resilience, private 5G and temporary communications are emerging as important demand pools alongside conventional rural mobile coverage.
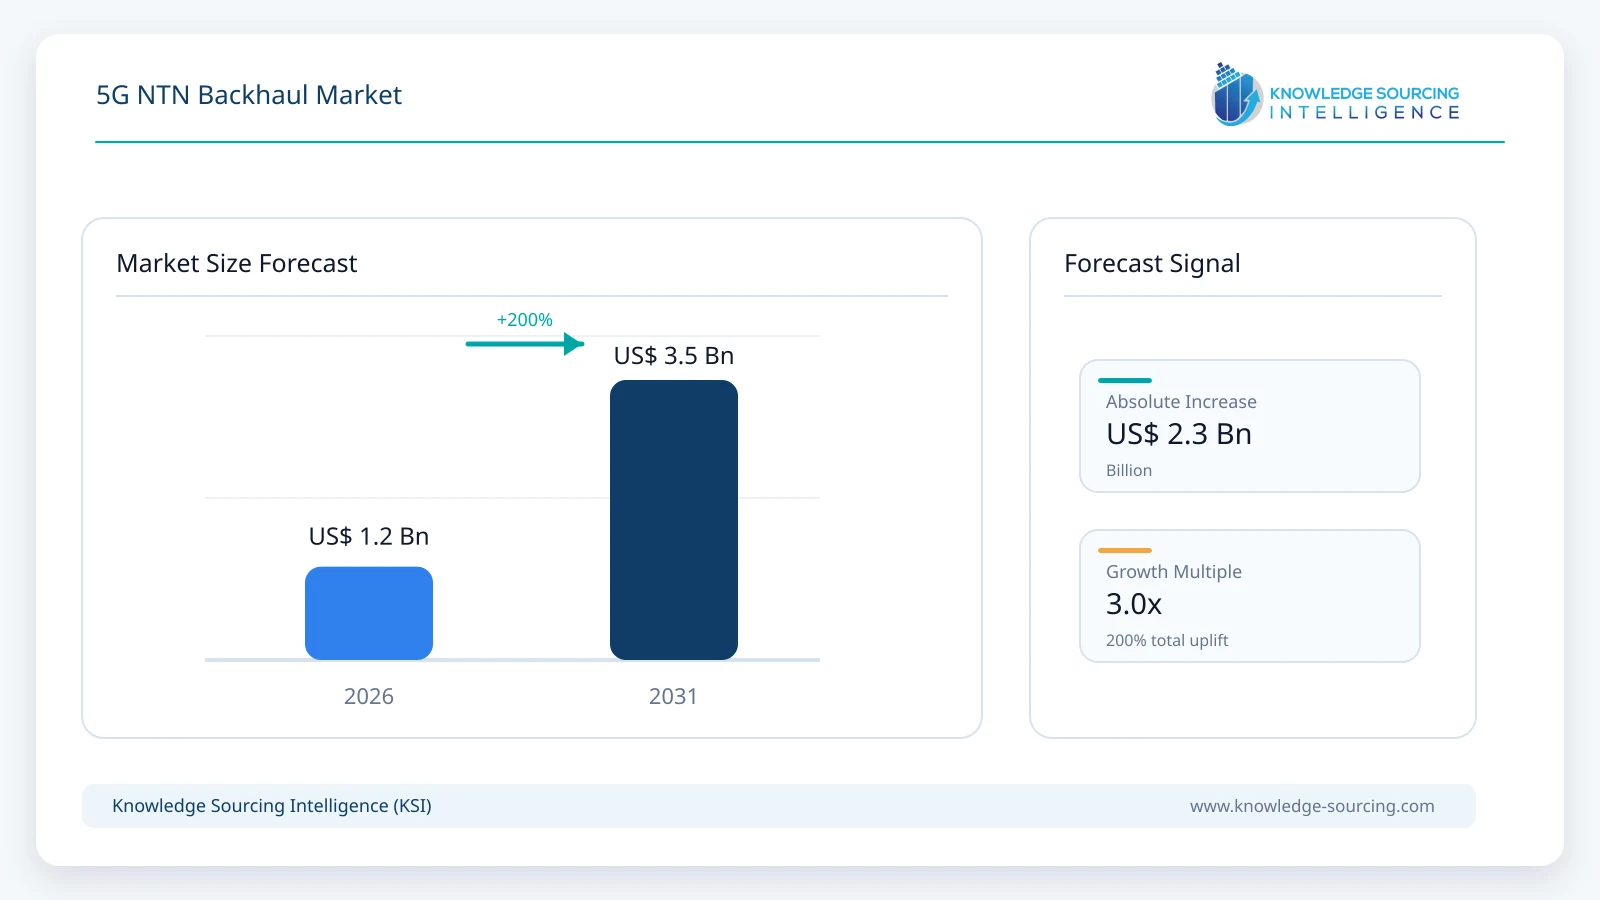
Growth is being supported by commercial low-Earth-orbit satellite capacity, integration of satellite links with mobile core networks, increasing use of non-terrestrial connectivity for rural cell sites, resilience requirements, and the gradual commercialization of standards-based 5G NTN infrastructure.
5G NTN backhaul provides connectivity between terrestrial radio sites or private-network infrastructure and the wider mobile core through satellite or other non-terrestrial platforms. The technology is particularly relevant where fiber, microwave or other terrestrial transport is unavailable, slow to deploy or economically unattractive. It can also provide secondary network paths where resilience is more important than minimizing transport cost.
The market includes satellite and non-terrestrial backhaul equipment, ground infrastructure, terminals, gateways, network-management systems and associated connectivity services used to transport traffic from 5G cellular or private-network sites. It includes LEO, MEO and GEO satellite systems and selected high-altitude platform applications. Direct-to-device satellite connectivity in which a satellite communicates directly with an end-user handset without a terrestrial 5G cell site is excluded from the backhaul market.
Market Overview
Satellite backhaul has been used in mobile networks for many years, particularly in islands, mountainous regions, remote communities and areas where terrestrial transmission infrastructure is uneconomic. The emergence of 5G and new LEO satellite constellations is changing the performance and commercial profile of this market. Traditional GEO backhaul remains useful where wide coverage and predictable capacity are required, but LEO systems offer substantially lower latency and are increasingly capable of supporting broadband-intensive 4G and 5G cell sites.
The 5G NTN backhaul opportunity should be distinguished from the wider 5G NTN market. Direct-to-device satellite connectivity, satellite IoT terminals and consumer satellite broadband can all use NTN technology but do not necessarily carry traffic from terrestrial 5G base stations to a mobile core. Backhaul is narrower and is driven principally by telecom transport economics, network reach and resilience.
Commercial evidence increasingly supports this use case. Vodafone and Amazon Leo agreed in March 2026 to connect geographically dispersed mobile base stations in Europe and Africa using LEO satellite transport. Vodafone specifically identified the ability to deploy mobile sites without constructing long fiber or fixed-wireless backhaul links and to provide alternative connectivity if terrestrial transmission infrastructure is interrupted.
GSA’s August 2026 tracking of NTN partnerships similarly found increasing satellite-backhaul activity as operators attempt both to expand terrestrial mobile coverage and improve resilience. Community and enterprise broadband represented 38% of tracked satellite-operator and telecom-operator partnerships, while satellite backhaul was identified as a growing category.
A second change is occurring at the technology layer. Satellite networking platforms are increasingly being developed around 3GPP-compatible NTN architecture rather than remaining entirely separate proprietary transport environments. Gilat demonstrated end-to-end 3GPP-compliant 5G NTN connectivity using a GEO satellite in February 2026, validating standardized 5G NTN services across existing satellite infrastructure.
The combination of expanding satellite capacity, lower latency, standards convergence and greater automation supports a stronger growth profile after 2027 as commercially available LEO constellations increase capacity and operators gain experience integrating satellite transport into their terrestrial networks.
Market Drivers
LEO satellite networks are improving the economics of remote 5G backhaul
Remote cell sites traditionally rely on microwave links, fiber where available, or GEO satellite transport. LEO constellations introduce another option with materially lower orbital latency and increasingly large available capacity. This improves the suitability of satellite backhaul for broadband-intensive 5G traffic rather than restricting satellite transport primarily to low-capacity rural cellular sites.
Vodafone’s Amazon Leo agreement is a particularly important commercial indicator. The operator intends to use satellite links to connect mobile base stations directly with its core telecom infrastructure in Germany and other European markets before expanding the model across Africa through Vodacom. The first sites are expected to be connected during 2026.
LEO consequently expands its share of the NTN backhaul market through 2031 as constellation capacity increases and operator procurement moves beyond trials.
Extending mobile coverage without building terrestrial transport infrastructure
The business case for NTN backhaul is strongest where the economics of the access network and transport network differ. An operator may be able to justify a rural radio site based on subscriber coverage, public-service obligations or government support but still face an uneconomic fiber connection stretching tens or hundreds of kilometers.
Satellite transport removes much of this distance dependency. Once a suitable satellite terminal is installed, a mobile site can be connected without constructing continuous physical infrastructure between the site and the operator’s terrestrial network.
This is particularly relevant across rural Africa, mountainous Asia Pacific markets, islands and remote regions of North and South America. Mobile-network expansion can therefore create NTN backhaul demand even where satellite communication is not used for direct consumer access.
Network resilience is becoming a separate commercial requirement
Satellite transport is increasingly being procured as a secondary path even where terrestrial backhaul already exists. Fiber cuts, floods, wildfires, earthquakes and infrastructure failures can isolate mobile sites or entire regions when networks depend on one terrestrial transport route.
Vodafone explicitly identifies resilience as a reason for its Amazon Leo deployment, including the ability to preserve critical online services when fiber links are damaged. SES similarly markets satellite-enabled cellular connectivity for emergency restoration, temporary capacity and cell-site protection.
This broadens the market beyond permanent rural sites. Urban networks, public-safety systems, critical infrastructure and disaster-recovery networks can maintain satellite capacity primarily as an alternate transport path.
3GPP integration is reducing the separation between satellite and mobile networks
Historically, satellite backhaul was integrated with mobile infrastructure largely as an external IP transmission service. 5G NTN standards are enabling satellite systems to interact more directly with the mobile-network architecture.
Gilat’s February 2026 demonstration validated 3GPP-compliant end-to-end 5G NTN over GEO infrastructure using standardized VSAT and hub technologies. Effnet also signed an agreement in May 2026 with a major satellite operator to evaluate and deploy its 5G NTN platform, including architectures where gNB functionality can be hosted on satellite payloads.
Standards alignment can reduce integration complexity, widen the supplier ecosystem and allow telecom operators to manage terrestrial and satellite resources within increasingly common network frameworks.
Private 5G creates additional backhaul demand outside national mobile networks
Mining sites, oil and gas facilities, ports, utilities, agricultural operations and remote industrial facilities increasingly use private LTE or 5G networks for local connectivity. Many such locations also lack reliable terrestrial backhaul.
Satellite can connect the local private network to remote applications, cloud infrastructure or centralized operational systems without requiring long-distance fiber construction. The economics are particularly attractive where private cellular connectivity supports high-value industrial operations rather than low-ARPU consumer broadband.
Private and enterprise networks therefore become one of the fastest-growing demand categories through 2031, even though public telecom operators remain the largest buyers.
Market Restraints and Challenges
Fiber and microwave remain more economical where terrestrial infrastructure already exists
Satellite backhaul is not a universal replacement for terrestrial transport. High-capacity fiber generally provides lower marginal bandwidth costs, very low latency and predictable performance once deployed. Microwave and millimeter-wave links can also provide attractive economics where line-of-sight paths are available.
NTN backhaul is therefore most competitive where geography, time to deployment, redundancy requirements or low site density weaken the economics of terrestrial infrastructure. In dense urban markets, satellite transport generally remains a secondary or resilience option rather than the primary backhaul layer.
Satellite capacity and terminal economics remain material
LEO economics are improving, but mobile sites can require sustained throughput and service-level commitments rather than intermittent consumer traffic. Operators need sufficient satellite capacity, ground gateways, terminals and network-management infrastructure to guarantee acceptable performance.
High-performance electronically steered antennas and multi-orbit terminals remain more expensive than many conventional terrestrial backhaul interfaces. Equipment prices need to decline further for satellite transport to become economically attractive across a substantially larger number of low-revenue cell sites.
Ku- and Ka-band links require careful availability planning
High-frequency satellite bands provide substantial bandwidth but can experience attenuation during heavy precipitation. This is particularly relevant to tropical markets that simultaneously contain many of the remote communities where satellite backhaul has a strong economic case.
Operators may need adaptive coding, larger link margins, redundant paths or multi-orbit connectivity to maintain required service availability. This can increase total system cost relative to headline terminal and capacity pricing.
Direct-to-device satellite systems can reduce some ultra-remote backhaul requirements
Direct-to-device satellite connectivity represents both an expansion of the broader NTN ecosystem and a potential substitute for conventional cell-site backhaul in very low-density areas. If a satellite system can connect standard or lightly modified mobile devices directly, an operator may not need to construct a terrestrial base station in locations with extremely limited traffic.
This effect is unlikely to eliminate NTN backhaul because terrestrial radio sites provide much higher local capacity. However, D2D can reduce the business case for constructing low-utilization towers in the most remote locations and may concentrate backhaul investment on sites with sufficient demand to justify terrestrial RAN infrastructure.
Regulatory and spectrum coordination remain complex
Satellite systems cross national borders while terrestrial mobile networks operate within country-specific spectrum and licensing frameworks. Gateway licensing, landing rights, frequency coordination, satellite authorizations and telecom regulations can therefore affect deployment timing.
The growth of hybrid terrestrial and non-terrestrial networks requires increasing cooperation between mobile regulators, satellite regulators and international standards bodies. Regulatory differences are likely to remain an important determinant of how quickly commercial deployments scale across individual countries.
Major Segment Analysis
By Orbital Platform
LEO represents the largest platform category and is projected to grow at approximately 30.1% annually through 2031. The segment benefits from lower latency, growing constellation capacity and operator demand for broadband-class cell-site transport. Amazon Leo, Eutelsat’s OneWeb network, Starlink and future LEO systems increasingly position telecommunications backhaul as an enterprise use case rather than focusing solely on consumer satellite broadband.
GEO retains an important role because existing satellites provide extensive coverage, mature ground infrastructure and predictable availability. Gilat’s successful 2026 5G NTN demonstration over GEO infrastructure demonstrates that standards-based 5G integration does not depend exclusively on LEO systems. GEO grows considerably more slowly, however, as lower-latency applications favor LEO and multi-orbit designs.
MEO remains smaller but benefits from high-throughput networks including SES O3b mPOWER. SES continues adding satellites and is preparing its next-generation meoSphere architecture for operation around 2030, increasing available medium-Earth-orbit capacity.
High-altitude platforms and UAS-based backhaul remain an early-stage category but offer potential for rapidly deployable localized coverage where conventional satellites or fixed infrastructure are unsuitable.
By Backhaul Role
Primary cell-site backhaul remains the largest commercial role, particularly for permanent rural and remote mobile sites. Satellite transport substitutes directly for fiber or microwave where terrestrial infrastructure cannot be economically extended.
Hybrid and overflow backhaul is becoming more relevant as software-defined networks allow traffic to be distributed between terrestrial and satellite links according to capacity requirements and service conditions. This model can reduce dependence on a single transport technology and allow satellite bandwidth to be activated as traffic increases.
Resilience and backup applications grow quickly as telecom operators, governments and critical-infrastructure providers place greater value on maintaining connectivity during physical network disruption.
Temporary and deployable backhaul addresses disaster recovery, seasonal demand, public events, defense, construction and other situations where a mobile network needs to be established more quickly than permanent terrestrial transport can be built.
By Network Type
Public mobile networks remain the largest customer category through 2031. Telecom operators use NTN backhaul to extend national networks, meet rural-coverage objectives and improve resilience. The segment is projected to exceed USD 2.12 billion by 2031, although its overall market share gradually decreases as other applications expand.
Private and enterprise 5G represents the fastest-growing major customer category, at approximately 32.0% annually. Mining, energy, logistics, agriculture and remote industrial facilities can combine local private cellular coverage with satellite transport to central systems.
Government and public-safety networks also grow above the market average because transport redundancy and rapid deployment can justify the higher cost of satellite connectivity.
Regional Analysis
North America remains the largest market in 2026, supported by extensive satellite infrastructure, multiple LEO constellation operators and a developed ecosystem of ground-equipment and mobile-network technology suppliers. The United States hosts companies including Amazon Leo, SpaceX, Viasat, EchoStar/Hughes and numerous satellite-network technology providers.
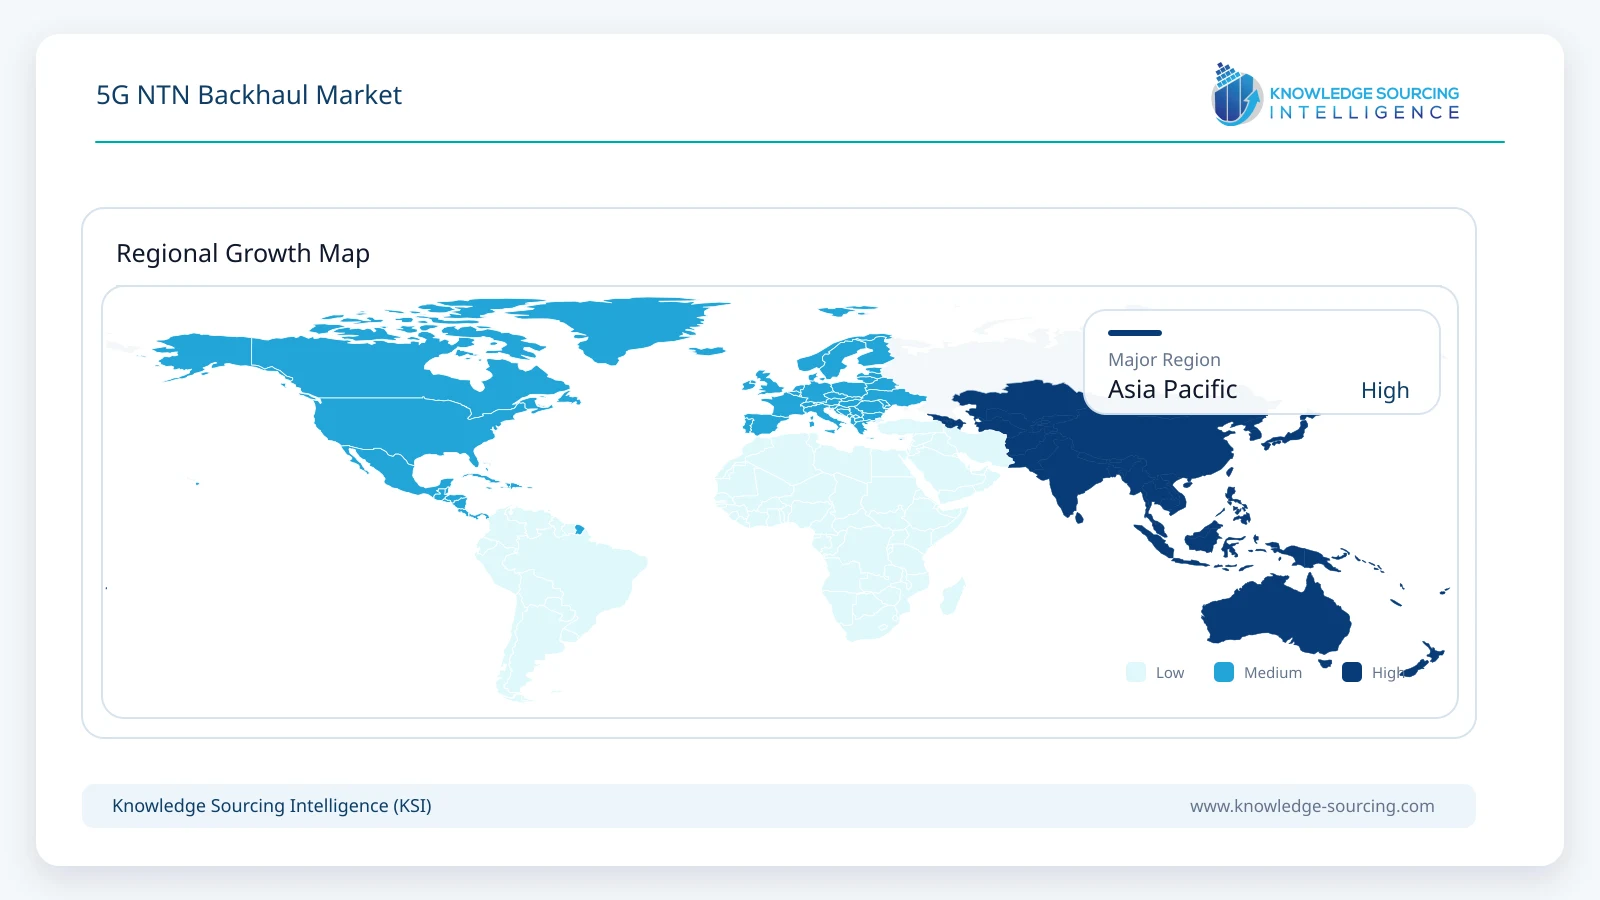
Asia Pacific is projected to record the strongest growth among the major regions, at approximately 28.3% annually through 2031, and becomes increasingly important to global demand. Large rural populations, island geographies and expanding 5G infrastructure create a significant backhaul opportunity across India, Indonesia, the Philippines, Japan, Australia and other markets.
Europe benefits from expanding multi-orbit capacity and public investment in integrated terrestrial-satellite infrastructure. The IRIS² program moved further into its implementation phase in August 2026, with Eutelsat’s LEO architecture incorporating beamforming and 5G NTN technologies as part of Europe’s sovereign connectivity infrastructure.
The Middle East and Africa provide another strong growth area. Large geographic distances, uneven fiber availability and continued mobile-network expansion create favorable satellite-backhaul economics. Vodafone’s planned Amazon Leo rollout through Vodacom directly targets this opportunity across African markets.
South America remains smaller in revenue but has substantial use cases across the Amazon, mining regions, offshore energy operations and isolated communities where terrestrial transport is difficult to deploy.
Technology Outlook
Multi-Orbit and Software-Defined Backhaul
Future NTN backhaul increasingly combines GEO, MEO and LEO capacity rather than requiring operators to commit to one orbital architecture. Software-defined networking can route traffic according to latency, capacity, availability and cost requirements.
Multi-orbit operation becomes particularly valuable where satellite backhaul is used for both primary connectivity and resilience because traffic can migrate between networks as conditions change.
3GPP-Compliant NTN Ground Infrastructure
Standardized 5G NTN gateways, gNB functions and network integration represent one of the most important technology transitions. Gilat’s GEO demonstration and Effnet’s operational satellite project show that vendors are moving standardized NTN functions from laboratories toward commercial infrastructure.
The longer-term effect is likely to be a reduction in the distinction between a conventional satellite transport network and a telecom-native NTN infrastructure layer.
Electronically Steered Antennas and Dynamic Beamforming
Electronically steered terminals can track moving LEO satellites without mechanically repositioning a conventional dish, making them increasingly important to LEO and multi-orbit deployments. At the satellite layer, dynamic beamforming allows capacity to be directed toward changing traffic demand.
IRIS², for example, is being designed around beamforming antennas and multi-orbit connectivity, while OQ Technology received ESA support during 2026 for development of high-capacity multi-beam phased-array technology.
Recent Developments
August 2026: Eutelsat announced completion of the first major IRIS² program review, allowing Europe’s sovereign multi-orbit connectivity infrastructure to move toward full industrial implementation. The architecture combines beamforming, LEO capacity and 5G NTN technology, supporting future integration of terrestrial and satellite communications.
May 2026: Effnet signed a strategic agreement with a major satellite operator to evaluate and deploy its standards-based 5G NTN platform in an operational satellite environment. The technology supports regenerative architectures in which 5G gNB functionality can be hosted directly on the satellite payload.
March 2026: Vodafone and Amazon Leo announced an agreement to use LEO satellite backhaul for remote 4G and 5G mobile base stations across Europe and subsequently Africa through Vodacom. The service is designed to provide up to 1 Gbps downstream and 400 Mbps upstream and to support both coverage expansion and network resilience.
March 2026: GSMA Foundry and the European Space Agency announced access to up to EUR 100 million in new funding for AI-enabled NTN, direct-to-device, 5G/6G test hubs and future satellite-terrestrial convergence projects.
February 2026: Gilat demonstrated end-to-end 3GPP-compliant 5G NTN connectivity over a GEO satellite, validating standardized VSAT and hub technology for integration between satellite and terrestrial mobile infrastructure.
Competitive Landscape
The competitive environment combines satellite-network operators, satellite ground-system suppliers, mobile-network vendors and software companies. Amazon Leo, Eutelsat, SES, SpaceX, Telesat and Viasat provide or are developing the space-based capacity used for satellite-enabled telecom transport.
Gilat, Hughes Network Systems, ST Engineering iDirect, Comtech and Kratos provide ground infrastructure, gateways, modems, terminals and network-management technologies. Gilat has positioned cellular backhaul as one of its commercial satellite applications and is developing its SkyEdge platform toward standardized 5G NTN compatibility. Its July 2026 orders exceeding USD 20 million for SkyEdge multi-orbit systems illustrate continued investment by satellite operators in ground-network infrastructure.
Ericsson, Nokia, Huawei, ZTE and Mavenir occupy a different part of the ecosystem through mobile RAN, core-network and NTN integration. Their role becomes increasingly important as satellite connectivity is integrated directly into 3GPP mobile architectures.
Gatehouse Satcom, Effnet, SatixFy and OQ Technology provide specialized NTN software, modem, payload and protocol capabilities. Competition is consequently based not only on satellite capacity but on the ability to integrate orbital resources, gateways, telecom protocols and network-management software into a reliable end-to-end backhaul service.
Analyst View
The strongest commercial case for NTN backhaul is not replacing fiber in locations where fiber already performs economically. The opportunity lies where terrestrial network economics break down or where relying on a single terrestrial route creates unacceptable operational risk. Rural cell sites, islands, remote industrial facilities, emergency networks and geographically isolated infrastructure therefore remain the most attractive deployment environments.
LEO changes the addressable market because lower latency and greater aggregate capacity allow satellite transport to support much more demanding mobile traffic than conventional narrowband rural backhaul. The significance of operator programs such as Vodafone-Amazon Leo is that they treat satellite connectivity as part of mainstream network planning rather than an exceptional solution for a handful of isolated sites.
The market is also moving toward hybrid architecture. Satellite transport increasingly works alongside fiber, microwave and other terrestrial technologies rather than replacing them outright. Network software can choose among available paths according to congestion, outage conditions, application requirements and cost. This makes resilience and augmentation increasingly important revenue opportunities.
Standardization may ultimately have a greater structural impact than the satellites themselves. As 3GPP NTN functions move into ground systems and satellite payloads, telecom operators can manage satellite connectivity more like another network domain. This lowers the architectural barrier between mobile and satellite industries and expands the potential supplier and application ecosystem.
Direct-to-device connectivity should be watched carefully because it competes with satellite backhaul at the very edge of the coverage map. In locations with almost no traffic, connecting devices directly from space may be more rational than constructing terrestrial radio infrastructure. Backhaul remains more attractive where operators need local capacity, conventional mobile coverage, private-network functionality or connectivity for many users concentrated around a site.
For suppliers, the highest-value position increasingly lies in interoperability rather than a single component. Multi-orbit support, standards-based integration, automated routing, electronically steered terminals and service-level management determine whether NTN can operate as a dependable transport layer within commercial 5G networks.
5G NTN Backhaul Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.16 billion |
| Total Market Size in 2031 | USD 3.48 billion |
| Forecast Unit | Billion |
| Growth Rate | 24.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Orbital Platform, Backhaul Role, Network Type, Geography |
| Companies |
|
Market Segmentation
By Orbital Platform
· Low Earth Orbit (LEO) Satellites
· Medium Earth Orbit (MEO) Satellites
· Geostationary Earth Orbit (GEO) Satellites
· High-Altitude Platform Systems & UAS
By Backhaul Role
· Primary Cell-Site Backhaul
· Hybrid & Capacity-Augmentation Backhaul
· Resilience & Backup Backhaul
· Temporary & Deployable Backhaul
By Network Type
· Public Mobile Networks
· Private & Enterprise 5G Networks
· Government & Public-Safety Networks
By Geography
North America
· United States
· Canada
· Mexico
South America
· Brazil
· Argentina
· Others
Europe
· United Kingdom
· Germany
· France
· Italy
· Spain
· Others
Middle East and Africa
· Saudi Arabia
· UAE
· South Africa
· Nigeria
· Others
Asia Pacific
· China
· India
· Japan
· South Korea
· Indonesia
· Philippines
· Australia
· Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Scope Exclusions
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. Satellite Capacity and Mobile Backhaul Economics
3.5. Terrestrial vs. NTN Backhaul Comparison
3.6. Regulatory and Spectrum Environment
3.7. 3GPP NTN Standardization
3.8. Porter’s Five Forces Analysis
3.9. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. Multi-Orbit and Software-Defined Backhaul
4.2. 3GPP-Compliant NTN Ground Infrastructure
4.3. Electronically Steered Antennas and Dynamic Beamforming
5. 5G NTN BACKHAUL MARKET BY ORBITAL PLATFORM
5.1. Introduction
5.2. Low Earth Orbit Satellites
5.3. Medium Earth Orbit Satellites
5.4. Geostationary Earth Orbit Satellites
5.5. High-Altitude Platform Systems & UAS
6. 5G NTN BACKHAUL MARKET BY BACKHAUL ROLE
6.1. Introduction
6.2. Primary Cell-Site Backhaul
6.3. Hybrid & Capacity-Augmentation Backhaul
6.4. Resilience & Backup Backhaul
6.5. Temporary & Deployable Backhaul
7. 5G NTN BACKHAUL MARKET BY NETWORK TYPE
7.1. Introduction
7.2. Public Mobile Networks
7.3. Private & Enterprise 5G Networks
7.4. Government & Public-Safety Networks
8. 5G NTN BACKHAUL MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. United Kingdom
8.3.2. Germany
8.3.3. France
8.3.4. Italy
8.3.5. Spain
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. South Africa
8.4.4. Nigeria
8.4.5. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. India
8.5.3. Japan
8.5.4. South Korea
8.5.5. Indonesia
8.5.6. Philippines
8.5.7. Australia
8.5.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Competitive Positioning
9.2. LEO, MEO and GEO Capability Benchmarking
9.3. Ground Infrastructure and Terminal Analysis
9.4. 3GPP NTN Integration Capability
9.5. Multi-Orbit and Network-Management Analysis
9.6. Strategic Partnerships and Developments
9.7. Competitive Dashboard
10. COMPANY PROFILES
10.1. Amazon Leo
10.2. Eutelsat
10.3. SES S.A.
10.4. SpaceX
10.5. Telesat Corporation
10.6. Viasat, Inc.
10.7. Gilat Satellite Networks Ltd.
10.8. Hughes Network Systems, LLC
10.9. ST Engineering iDirect
10.10. Comtech Telecommunications Corp.
10.11. Ericsson
10.12. Nokia Corporation
10.13. Huawei Technologies Co., Ltd.
10.14. ZTE Corporation
10.15. Mavenir Systems, Inc.
10.16. Gatehouse Satcom A/S
10.17. Effnet AB
10.18. SatixFy Communications Ltd.
10.19. OQ Technology
10.20. Kratos Defense & Security Solutions, Inc.
11. ANALYST VIEW
12. APPENDIX
12.1. Research Methodology
12.2. Market Estimation and Assumptions
12.3. Scope and Double-Counting Controls
12.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











