
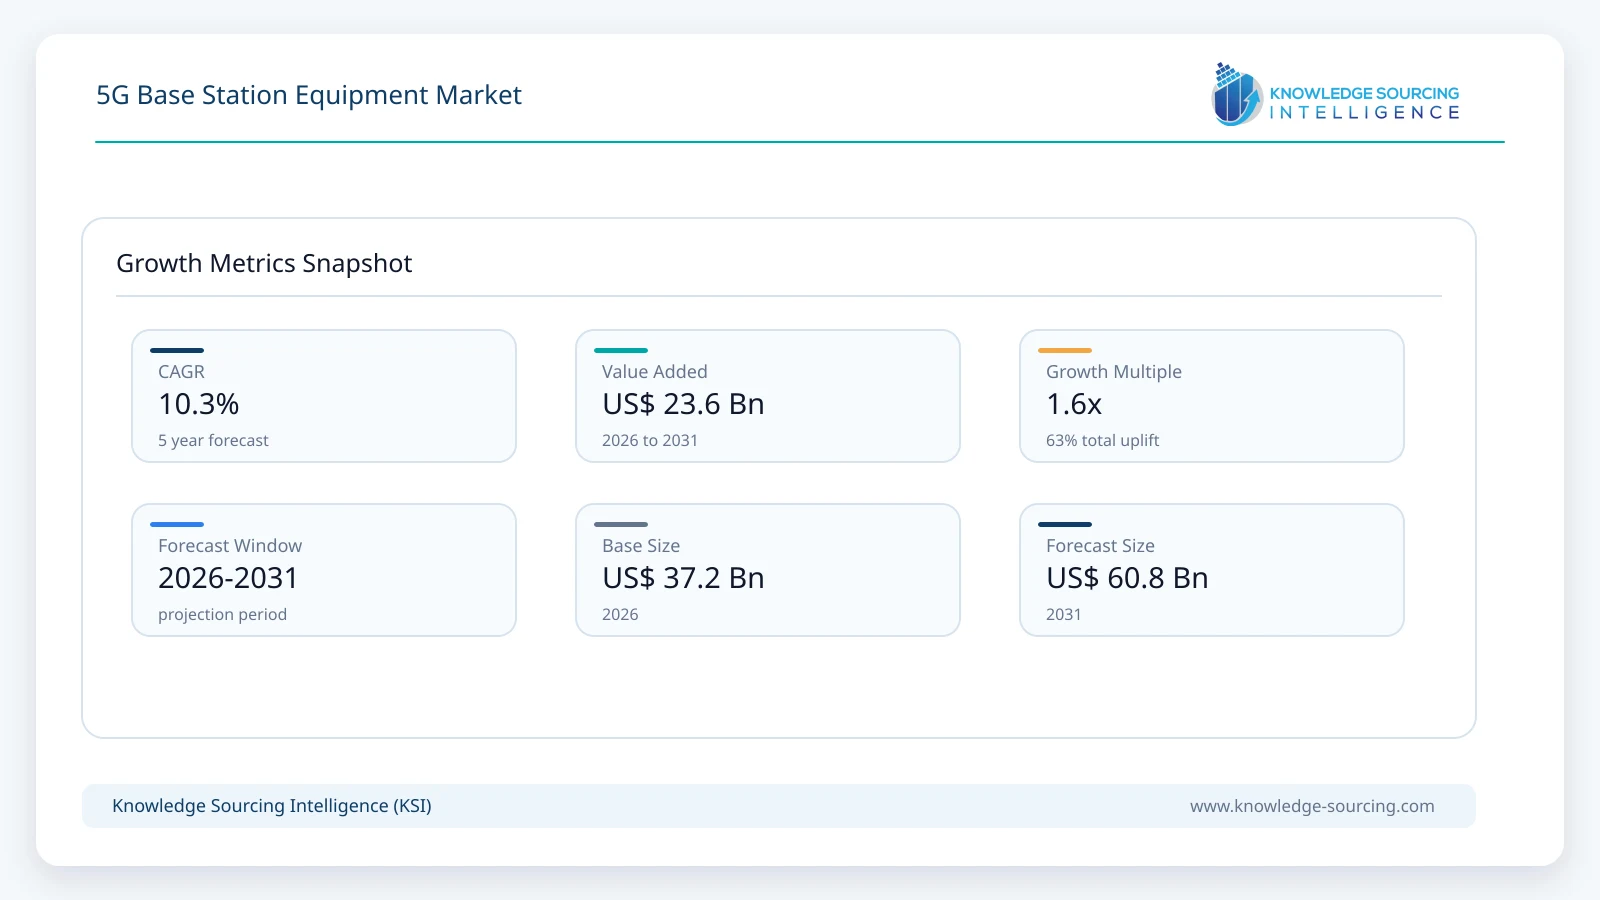
The 5G Base Station Equipment market is forecast to grow at a CAGR of 10.3%, reaching USD 60.8 billion in 2031 from USD 37.2 billion in 2026.
Highlights:
- 1Macrocell base stations account for an estimated 68.0% of global market revenue in 2026reflecting the continued importance of wide-area public mobile infrastructure.
- 2Macro radio and antenna-integrated radio equipment represents approximately 52.0% of market revenue in 2026making the radio layer the largest equipment category.
- 3Mid-band equipment accounts for approximately 75.0% of 2026 revenuesupported by widespread deployment of C-band and comparable spectrum for 5G capacity.
- 4Asia Pacific represents approximately 55.0% of global revenue in 2026led by China, India, Japan and South Korea.
- 5India’s 5G BTS count increased from 140,623 in March 2023 to 562,971 by June 30, 2026, demonstrating that major physical-network expansion is still occurring outside the most mature 5G markets.
- 65G Standalone deployment remains at an earlier stage than 5G radio coverage, with more than 90 operators having launched SA compared with approximately 390 commercial 5G operators globally.
- 7Equipment development is shifting toward lighter radios, more efficient power amplifiers, virtualized baseband, Open RAN compatibility and AI-enabled RAN compute.
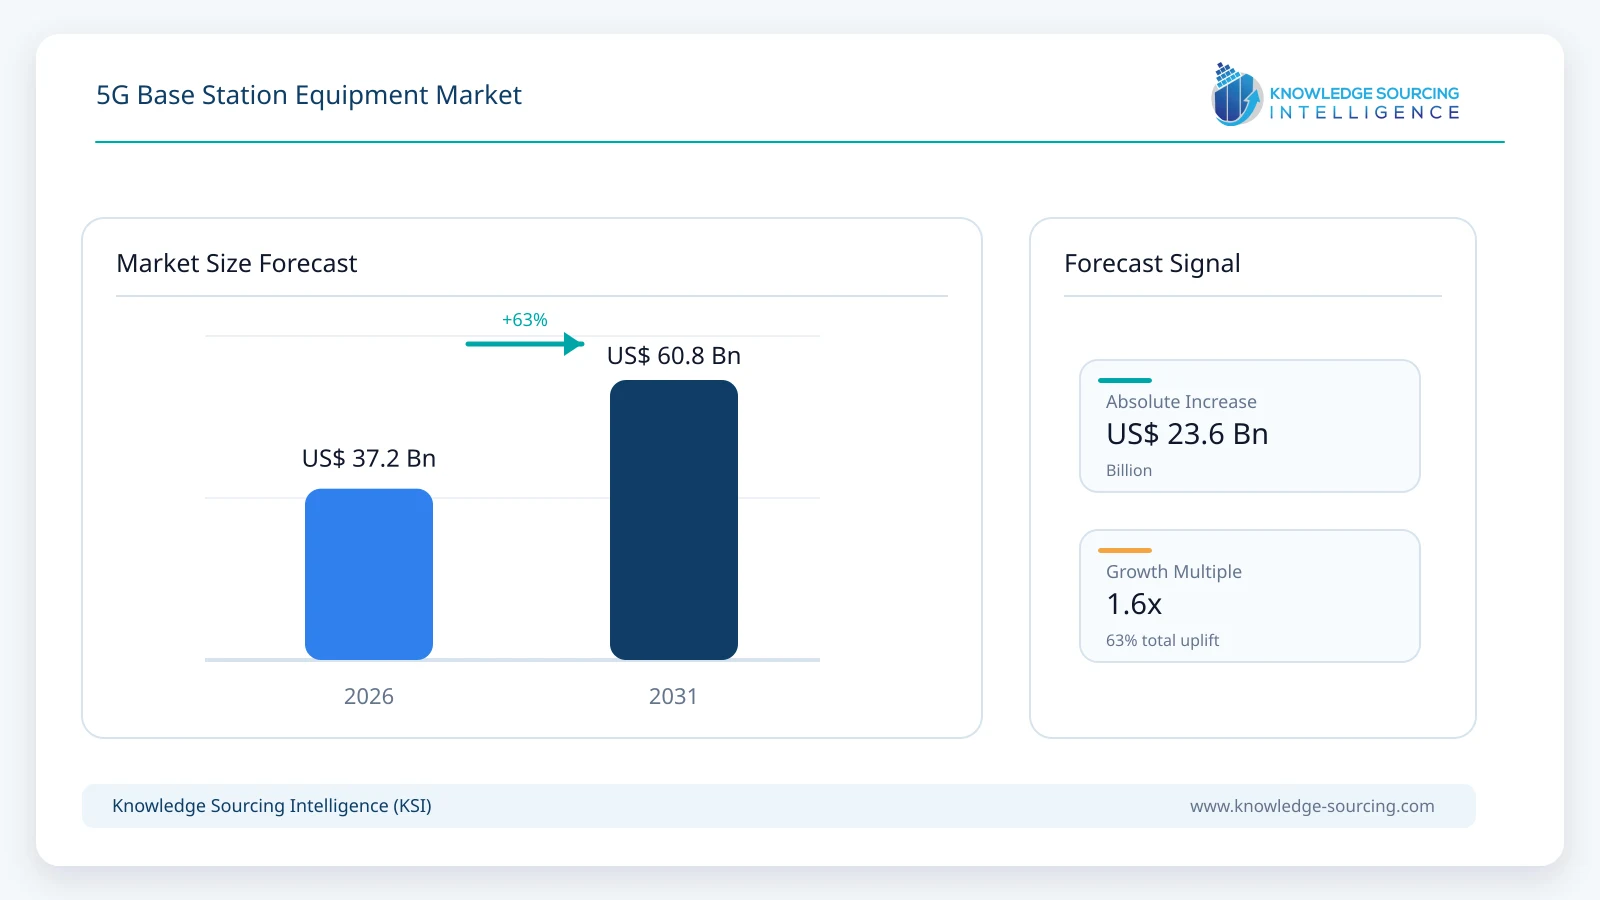
Growth is being supported by continued network expansion in markets such as India and parts of Southeast Asia, replacement and modernization of first-generation 5G radio equipment, wider 5G Standalone adoption, small-cell densification, private 5G deployments and the transition toward Cloud RAN, Open RAN and AI-enabled radio architectures.
5G base station equipment comprises the radio and compute hardware used to establish and operate the radio access network between mobile devices and the wider telecom network. The market includes macro radio equipment, antenna-integrated radio systems, baseband and RAN compute platforms, integrated small-cell systems and associated power and site-support equipment. The scope excludes passive tower infrastructure, standalone fronthaul and backhaul equipment, mobile-core equipment and customer-premises devices.
The market is progressing beyond the initial phase in which growth was primarily determined by how quickly operators could establish nationwide 5G coverage. Equipment procurement increasingly reflects network capacity, spectrum utilization, energy efficiency, cloudification and the ability to upgrade existing sites toward 5G-Advanced. Ericsson estimates that global 5G subscriptions were close to 3.3 billion in mid-2026 and will reach 6.4 billion by 2031, while 5G’s share of mobile traffic continues to increase.
Market Overview
The base station is the principal physical layer through which mobile operators convert spectrum holdings into usable coverage and capacity. In a conventional macro network, the base station comprises radio units, antenna systems and baseband processing. Modern 5G systems increasingly integrate the antenna and radio in an Active Antenna Unit while separating other baseband functions into centralized, distributed or cloud-based compute environments.
The market therefore needs to be viewed as more than the number of new towers built each year. Existing sites can generate substantial equipment expenditure when operators add new spectrum bands, replace older radios, introduce Massive MIMO, increase baseband processing capacity or migrate to more software-defined architectures. This becomes particularly important as early 5G markets move from coverage construction toward capacity and modernization.
China remains the world’s largest individual 5G equipment ecosystem. KSI’s current country model places the Chinese market at USD 14.7 billion in 2026 and USD 23.9 billion in 2031, reflecting both the enormous installed base and continued 5G-Advanced investment. The United States represents another large market, with KSI estimating USD 6.6 billion in 2026 and USD 9.1 billion by 2031.
These markets are nevertheless at different stages. China’s national rollout is mature relative to India, while U.S. demand increasingly centers on mid-band capacity, Open RAN, virtualized RAN and replacement of earlier hardware. Germany combines modernization with vendor-diversification requirements. India is still adding large numbers of 5G BTSs and expanding coverage and capacity simultaneously.
The result is a global market in which unit additions grow more slowly than during the first 5G deployment wave, but equipment value continues rising through higher-performance radios, additional spectrum layers, small cells, enterprise systems and more sophisticated baseband compute.
Market Drivers
Continued traffic growth requires capacity expansion even where 5G coverage is already extensive
Population coverage does not indicate whether a 5G network has sufficient capacity. Mobile traffic continues rising as video quality improves, fixed wireless expands, and AI-enabled applications increase uplink and downlink requirements.
Ericsson reports that 5G carried approximately 48% of global mobile data traffic at the end of 2025 and expects the share to reach 85% by 2031. Global 5G subscriptions are forecast to increase to 6.4 billion over the same period.
Operators therefore continue upgrading existing sites after basic 5G coverage has been achieved. Additional mid-band radios, Massive MIMO systems and higher-capacity baseband platforms can increase sector capacity without requiring a new tower. This creates recurring equipment expenditure across mature mobile markets.
India remains a major physical deployment opportunity
India represents one of the clearest examples of continuing large-scale base-station expansion. The country increased its 5G BTS count from 140,623 in March 2023 to 562,971 by June 30, 2026, while 5G services became available in 99.9% of districts.
Ericsson expects India’s 5G subscriptions to exceed 1.1 billion by 2031. Increasing subscriber density, mobile data traffic and fixed wireless usage should require continued radio and baseband investment even after national coverage is established.
This gives India a different growth profile from China. Chinese procurement increasingly emphasizes modernization and 5G-Advanced, while India’s market still combines new site deployment, capacity expansion and additional spectrum utilization.
Smaller and lighter radio equipment improves site economics
Physical constraints remain important in radio-network deployment. Towers and rooftops already carry several generations and spectrum bands, and every additional radio can increase wind loading, installation cost and site energy consumption.
Equipment suppliers are responding by reducing weight and integrating more functionality into individual units. NEC announced on January 23, 2026 that its new Sub-6 GHz Massive MIMO Radio Unit would reduce weight by approximately 33% to 16 kg or less and normal operating power consumption by around 42% compared with its current model. NEC also expects the new RU to extend supported fronthaul distance when used with its vRAN platform.
Ericsson’s February 2026 radio portfolio similarly includes compact high-bandwidth radios such as AIR 3267, which supports 600 MHz instantaneous bandwidth in a 13 kg unit.
The commercial benefit is broader than the equipment price itself. Lower weight can reduce structural upgrades and installation labor, while improved energy efficiency reduces recurring operating expenditure.
Standalone, Cloud RAN and virtualized RAN are changing baseband procurement
The radio unit remains physical hardware, but baseband processing is becoming increasingly software-defined. Operators can separate centralized and distributed functions and run portions of the RAN on cloud infrastructure rather than dedicated proprietary appliances.
Samsung announced on January 13, 2026 that it had completed a commercial call using its vRAN solution with Intel Xeon 6 on a Tier-1 U.S. operator’s live network, demonstrating that general-purpose and accelerated computing platforms are moving deeper into commercial RAN deployment.
Nokia’s July 2026 AI-native RAN announcement extends this transition further. The company introduced GPU-powered baseband options including an AirScale capacity plug-in unit, standalone AI-RAN node and cloud-native alternatives.
Under the KSI model, baseband and RAN compute equipment grows at approximately 12.9% annually through 2031, faster than conventional macro-radio equipment.
Private 5G creates a second buyer group outside national operators
Most base station equipment continues to be purchased by national telecom operators, but private networks create a separate market for factories, ports, mines, utilities, defense facilities and campuses.
Private systems generally use fewer sites, but they frequently require compact radios, integrated small cells and localized baseband platforms designed for easier deployment and management. Their procurement decisions are also less dependent on national mobile-coverage economics.
The private and enterprise base-station segment is projected to grow at approximately 20.8% annually through 2031, materially faster than public-operator equipment demand, although it remains much smaller in absolute value.
AI-RAN is creating a new compute layer within the base station
Artificial intelligence is moving from centralized network management into the RAN itself. Ericsson’s February 2026 equipment portfolio incorporates neural-network accelerators into Massive MIMO radios, allowing some AI inference to occur directly within radio hardware.
Nokia announced its commercial AI-native RAN platform on July 15, 2026, incorporating accelerated computing into AirScale and standalone AI-RAN nodes. The company positions the architecture as a method of improving spectral efficiency while creating infrastructure capable of running both radio and AI workloads.
This changes the long-term equipment mix. Base station value increasingly reflects processing capability and software upgradeability rather than only transmit power, antenna count and supported bands.
Market Restraints and Challenges
China is transitioning from rollout to modernization
China continues to generate very large base-station equipment demand, but the nature of procurement is changing. The market already contains several million 5G sites, which reduces the need for the extraordinary rate of first-time macro deployment seen earlier in the decade.
Future expenditure increasingly comes from capacity upgrades, 5G-Advanced radios, AI-enabled RAN, equipment replacement and enterprise deployments. These categories can still generate substantial revenue but generally create a more gradual equipment cycle than greenfield nationwide rollout.
This maturation is one reason global market growth increasingly depends on India, emerging markets, small cells, private networks and replacement cycles rather than simply extrapolating early Chinese deployment rates.
Better equipment can reduce the number of units required
A modern base station can support more bandwidth, process more traffic and serve more users than earlier-generation equipment. Multiband radios can replace several single-band systems, while more powerful baseband platforms can consolidate processing.
This improves operator economics but moderates equipment-unit growth. Market value therefore does not rise in direct proportion to mobile traffic or subscriber counts.
The same dynamic applies to AI-enabled RAN. Software and accelerated compute can extract more performance from existing spectrum and sites, potentially delaying some physical expansion.
Power consumption remains a major operating constraint
Radio equipment represents a substantial portion of mobile-network electricity consumption, particularly where Massive MIMO systems are deployed at scale. Energy cost therefore affects procurement decisions alongside capacity.
NEC stated in January 2026 that the power-amplifier module in a radio unit can account for approximately 75% of total RU power consumption and developed a new high-efficiency module specifically to reduce this burden.
Vendors increasingly compete on watts per unit of capacity, sleep-mode behavior and the ability to shut down unused resources dynamically. Equipment that increases throughput but materially raises site energy consumption faces a weaker commercial case.
Open RAN increases integration requirements
Open interfaces allow operators to source radios, baseband software and management systems from multiple vendors, potentially increasing competition and reducing lock-in.
However, disaggregation transfers more responsibility for testing, interoperability and lifecycle management to operators or systems integrators. Multi-vendor architectures can require additional engineering resources before achieving the same operational maturity as vertically integrated RAN systems.
This slows adoption in some networks even where operators support Open RAN strategically.
6G planning will influence late-period purchasing
The first commercial 6G services are expected around 2030 in leading markets. Operators procuring equipment near the end of the forecast period will therefore place increasing value on hardware that can evolve toward 6G through software, accelerated computing or common radio platforms.
This does not eliminate 5G equipment investment. Much of the physical infrastructure deployed during 2026–2031 will remain operational well into the next decade. However, upgradeability becomes an increasingly important purchasing criterion.
Major Segment Analysis
By Base Station Type
Macrocell base stations account for approximately 68.0% of market revenue in 2026 because nationwide mobile networks continue to rely on macro sites for coverage and high-capacity urban service.
Macro equipment revenue grows more slowly than the overall market and is projected to reach approximately USD 36.5 billion by 2031. Mature markets increasingly upgrade existing sites rather than constructing large numbers of new ones.
Small cells grow faster, at approximately 15.4% annually through 2031, as operators densify capacity in cities, transport hubs, stadiums and enterprise locations. Their share rises from around 20% in 2026 to approximately 25% in 2031.
Indoor and enterprise base stations record similarly strong growth. Private 5G, industrial connectivity and indoor coverage requirements increase demand for compact integrated systems that can be deployed without conventional macro-site infrastructure.
By Equipment Category
Macro radio and AAU equipment remains the largest equipment category, representing approximately 52.0% of market revenue in 2026. Radios continue to absorb the largest portion of physical RAN investment because spectrum additions and Massive MIMO require substantial RF hardware.
Its share gradually declines as compute becomes more important.
Baseband and RAN compute increases from approximately USD 9.3 billion in 2026 to USD 17.0 billion by 2031, representing around 12.9% annual growth. Cloud RAN, virtualized RAN and AI-RAN increase processing requirements while allowing operators to select more flexible hardware platforms.
Integrated small-cell systems reach approximately USD 7.3 billion by 2031, supported by enterprise, indoor and densification deployments.
Power systems and supporting equipment grow more slowly as vendors improve equipment efficiency and consolidate site hardware.
By Frequency Band
Mid-band remains the dominant equipment category, accounting for approximately 75.0% of market revenue in 2026. Spectrum around 2.5 GHz, C-band and 3.5 GHz provides the strongest balance between coverage and capacity and continues to support the majority of high-value Massive MIMO deployment.
Low-band equipment retains a stable role in wide-area coverage, especially in rural networks and indoor coverage layers.
High-band and mmWave equipment is projected to grow at approximately 16.3% annually through 2031 from a smaller base. Its strongest applications remain dense urban hotspots, private networks, venues and selected fixed-wireless deployments rather than nationwide macro coverage.
By End User
Mobile network operators account for approximately 89.0% of equipment revenue in 2026, but their share gradually declines as enterprise and government deployments grow.
Private and enterprise network equipment is projected to reach approximately USD 6.7 billion by 2031, supported by manufacturing, ports, energy, mining, transportation and large campus environments.
Government, defense and public-safety networks remain smaller but grow above the overall market rate as dedicated secure 5G systems become more common.
Regional Analysis
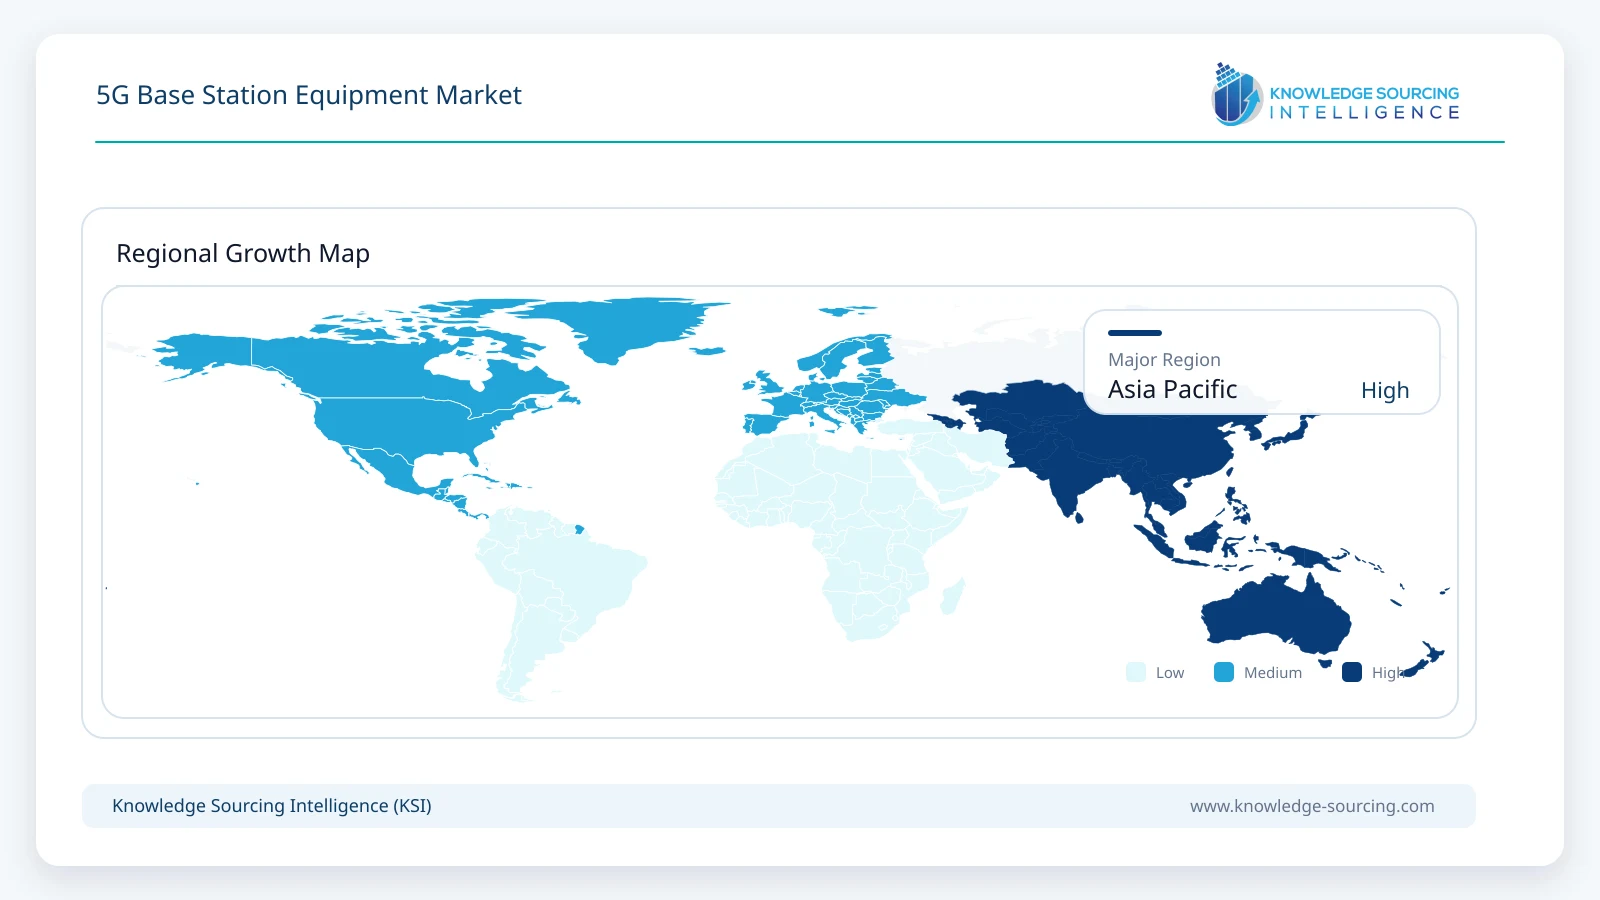
Asia Pacific accounts for approximately 55.0% of global revenue in 2026 and remains the largest region through 2031. China dominates the installed equipment base, while India contributes an increasing proportion of incremental deployment.
Japan and South Korea remain advanced markets where spending is increasingly related to Open RAN, virtualized RAN, 5G-Advanced and equipment modernization. NEC’s January 2026 new radio development and Samsung’s continued vRAN activity demonstrate the region’s focus on software-defined and energy-efficient base-station architecture.
North America remains a high-value equipment market. Operators continue investing in mid-band capacity, FWA support, virtualized RAN and Open RAN while gradually shifting from coverage-driven spending toward modernization.
Europe grows somewhat faster than North America because several countries combine 5G modernization with vendor-replacement and diversification programs. Nokia’s March 31, 2026 agreement with Virgin Media O2 includes Massive MIMO radios, future-ready baseband and next-generation radio platforms, illustrating that mature European networks still require substantial physical equipment refresh.
The Middle East and Africa record the fastest regional percentage growth in the KSI model. Gulf operators continue deploying advanced 5G and 5G-Advanced infrastructure, while several African countries remain in earlier stages of 5G rollout.
South America also expands above the global average as Brazil and other major markets increase 5G capacity and coverage.
Technology Outlook
AI-Ready Radios and AI-RAN Compute
Base-station equipment is increasingly being designed to execute AI functions locally. Ericsson is incorporating neural-network accelerators into Massive MIMO radios, while Nokia is introducing GPU-powered RAN compute options.
This moves intelligence closer to the air interface and allows operators to optimize beamforming, coverage, capacity and energy use with lower latency.
Cloud RAN and Open Baseband Architecture
Baseband processing is shifting from proprietary hardware toward virtualized and cloud-native software running across dedicated accelerators, general-purpose processors and increasingly GPUs.
Open interfaces allow radios and compute platforms from different vendors to operate together, although integration remains technically demanding.
The architectural shift increases the importance of software upgradeability and compute performance in base-station procurement.
Energy-Efficient Multiband Radios
Radio equipment is moving toward fewer physical units supporting more spectrum. Nokia’s Doksuri portfolio, launched on March 1, 2026, is designed around increased energy efficiency, simplified deployment and AI-ready 5G operation.
Multiband and integrated radios can reduce tower loading and site power while allowing operators to modernize several frequency layers simultaneously.
Recent Developments
July 15, 2026: Nokia announced its commercial AI-native RAN platform, including a GPU-powered AirScale capacity expansion unit, standalone AI-RAN node and cloud-native compute options. The platform is designed to support 4G, 5G and future network evolution while introducing accelerated AI processing directly into RAN infrastructure.
March 31, 2026: Nokia announced a major multi-year 5G RAN deployment and modernization agreement with Virgin Media O2 in the United Kingdom. The equipment package includes Nokia AirScale RAN, Massive MIMO radios, future-ready baseband and next-generation energy-efficient radio platforms.
March 5, 2026: Ericsson announced an agreement with Dialog Axiata to deploy 5G RAN equipment in Sri Lanka, including AIR 3219 Massive MIMO antenna-integrated radios for 3.5 GHz deployment and 5G-Advanced RAN software.
March 1, 2026: Nokia launched its Doksuri Remote Radio Head portfolio, designed to improve energy efficiency, capacity and deployment simplicity in 5G networks. The products form part of Nokia’s AirScale RAN portfolio.
February 17, 2026: Ericsson launched ten new AI-ready radios, including new TDD and FDD Massive MIMO equipment, multiband radios and products incorporating neural-network accelerators for local AI inference.
January 23, 2026: NEC announced development of a new Sub-6 GHz 5G Massive MIMO Radio Unit scheduled for commercial release during fiscal 2026. NEC reported improvements in throughput, equipment weight and energy consumption compared with its previous-generation unit.
Competitive Landscape
Huawei, Ericsson, Nokia, ZTE and Samsung remain the principal global RAN equipment suppliers. Their scale, operator relationships and ability to integrate radios, baseband, software and management systems create significant barriers to entry for complete nationwide deployments.
Huawei remains particularly strong across China and several emerging markets and competes through integrated Massive MIMO, baseband and 5G-Advanced portfolios. ZTE maintains a similarly strong domestic position in China while expanding AI-enabled RAN and specialized enterprise solutions internationally.
Ericsson’s competitive strategy increasingly combines compact radio hardware with proprietary silicon and AI-enhanced RAN software. Its February 2026 portfolio illustrates this integration through neural-network accelerators embedded directly in new Massive MIMO radios.
Nokia competes through AirScale, Habrok Massive MIMO, Doksuri radios, anyRAN and an expanding AI-RAN architecture. Its equipment strategy allows operators to retain purpose-built AirScale infrastructure while gradually introducing cloud and accelerated-compute options.
Samsung has developed a strong position in virtualized RAN and Open RAN, particularly in the United States, South Korea, Japan and selected European networks. Its January 2026 live-network vRAN milestone demonstrates the continued shift from dedicated baseband hardware toward commercial compute platforms.
NEC and Fujitsu remain important challengers in Open RAN and virtualized RAN. NEC has shipped more than 50,000 Massive MIMO units since 2020 and continues developing lighter, more efficient Open RAN-compatible radios.
Mavenir, Parallel Wireless and Rakuten Symphony compete more heavily through disaggregated and software-centric RAN architectures, while Airspan, Baicells, Comba Telecom, Tejas Networks, Viettel High Tech and VVDN address small cells, enterprise networks, regional operators and Open RAN radio opportunities.
The market remains concentrated at the national macro-network level but considerably more fragmented in small cells, private 5G and Open RAN. Competitive advantage increasingly depends on the combination of radio efficiency, compute flexibility, energy performance, open-interface compatibility and software upgradeability.
Analyst View
The 5G base-station market is no longer driven primarily by whether a country has launched 5G. The commercial question is increasingly what kind of equipment operators need after initial coverage has been established.
China illustrates this change most clearly. Its scale still makes it the largest national equipment market, but incremental spending increasingly comes from 5G-Advanced, capacity, replacement and AI-enabled RAN rather than first-time nationwide construction. India remains more physically expansion-driven, creating a different equipment opportunity even though both markets are within Asia Pacific.
The equipment mix is also shifting. Radio hardware remains the largest value pool, but baseband and RAN compute grow faster because virtualization and AI increase the processing requirement behind each radio site. The traditional distinction between a base station and a distributed computing platform is consequently becoming less clear.
Small cells and private networks add another growth layer. Macro networks remain dominant, but enterprises and neutral hosts increasingly purchase compact base-station systems for factories, campuses and dense indoor environments. These deployments create opportunities for suppliers that cannot realistically compete for entire national macro networks.
Energy efficiency will remain a central procurement criterion. Operators need greater capacity without allowing site electricity consumption and tower loading to grow at the same rate. Lighter radios, multiband consolidation and more efficient power amplifiers therefore have direct economic value beyond environmental positioning.
The strongest incremental opportunities through 2031 are concentrated in baseband and RAN compute, small cells, private 5G systems, high-band equipment, energy-efficient multiband radios, and AI/Open RAN architectures, while conventional macro equipment remains the largest but slower-growing revenue pool.
5G Base Station Equipment Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 37.2 billion |
| Total Market Size in 2031 | USD 60.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Base Station Type, Equipment Category, Frequency Band, End User |
| Companies |
|
Market Segmentation
By Base Station Type
· Macrocell Base Stations
· Small Cell Base Stations
· Indoor & Enterprise Base Stations
By Equipment Category
· Macro Radio & Antenna-Integrated Radio Equipment
· Baseband & RAN Compute
· Integrated Small-Cell Systems
· Power Systems & Supporting Equipment
By Frequency Band
· Low-Band
· Mid-Band
· High-Band / mmWave
By End User
· Mobile Network Operators
· Private & Enterprise Network Operators
· Government, Defense & Public-Safety Networks
By Geography
North America
· United States
· Canada
· Mexico
South America
· Brazil
· Argentina
· Others
Europe
· United Kingdom
· Germany
· France
· Italy
· Spain
· Others
Middle East and Africa
· Saudi Arabia
· UAE
· South Africa
· Nigeria
· Others
Asia Pacific
· China
· India
· Japan
· South Korea
· Indonesia
· Thailand
· Taiwan
· Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Scope Exclusions
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. Global 5G Deployment and Subscription Outlook
3.5. Radio Capacity and Spectrum Expansion
3.6. Site Power, Weight and Deployment Economics
3.7. Open RAN and Vendor Diversification
3.8. Private 5G Infrastructure Opportunity
3.9. Porter’s Five Forces Analysis
3.10. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. AI-Ready Radios and AI-RAN Compute
4.2. Cloud RAN and Open Baseband Architecture
4.3. Energy-Efficient Multiband Radios
5. 5G BASE STATION EQUIPMENT MARKET BY BASE STATION TYPE
5.1. Introduction
5.2. Macrocell Base Stations
5.3. Small Cell Base Stations
5.4. Indoor & Enterprise Base Stations
6. 5G BASE STATION EQUIPMENT MARKET BY EQUIPMENT CATEGORY
6.1. Introduction
6.2. Macro Radio & Antenna-Integrated Radio Equipment
6.3. Baseband & RAN Compute
6.4. Integrated Small-Cell Systems
6.5. Power Systems & Supporting Equipment
7. 5G BASE STATION EQUIPMENT MARKET BY FREQUENCY BAND
7.1. Introduction
7.2. Low-Band
7.3. Mid-Band
7.4. High-Band / mmWave
8. 5G BASE STATION EQUIPMENT MARKET BY END USER
8.1. Introduction
8.2. Mobile Network Operators
8.3. Private & Enterprise Network Operators
8.4. Government, Defense & Public-Safety Networks
9. 5G BASE STATION EQUIPMENT MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. United Kingdom
9.3.2. Germany
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Nigeria
9.4.5. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. South Korea
9.5.5. Indonesia
9.5.6. Thailand
9.5.7. Taiwan
9.5.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Competitive Positioning
10.2. Macro Radio & Massive MIMO Capability
10.3. Baseband & RAN Compute Capability
10.4. Small Cell & Enterprise Equipment
10.5. Cloud RAN, vRAN & Open RAN Readiness
10.6. Equipment Weight, Power & Energy Efficiency
10.7. Strategic Developments
10.8. Competitive Dashboard
11. COMPANY PROFILES
11.1. Huawei Technologies Co., Ltd.
11.2. Ericsson
11.3. Nokia Corporation
11.4. ZTE Corporation
11.5. Samsung Electronics Co., Ltd.
11.6. NEC Corporation
11.7. Fujitsu Limited
11.8. Mavenir Systems, Inc.
11.9. Airspan Networks Holdings Inc.
11.10. Comba Telecom Systems Holdings Limited
11.11. Baicells Technologies Co., Ltd.
11.12. Tejas Networks Limited
11.13. Parallel Wireless, Inc.
11.14. Rakuten Symphony
11.15. Viettel High Tech
11.16. VVDN Technologies
12. ANALYST VIEW
13. APPENDIX
13.1. Research Methodology
13.2. Market Estimation and Assumptions
13.3. Scope and Double-Counting Controls
13.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











