
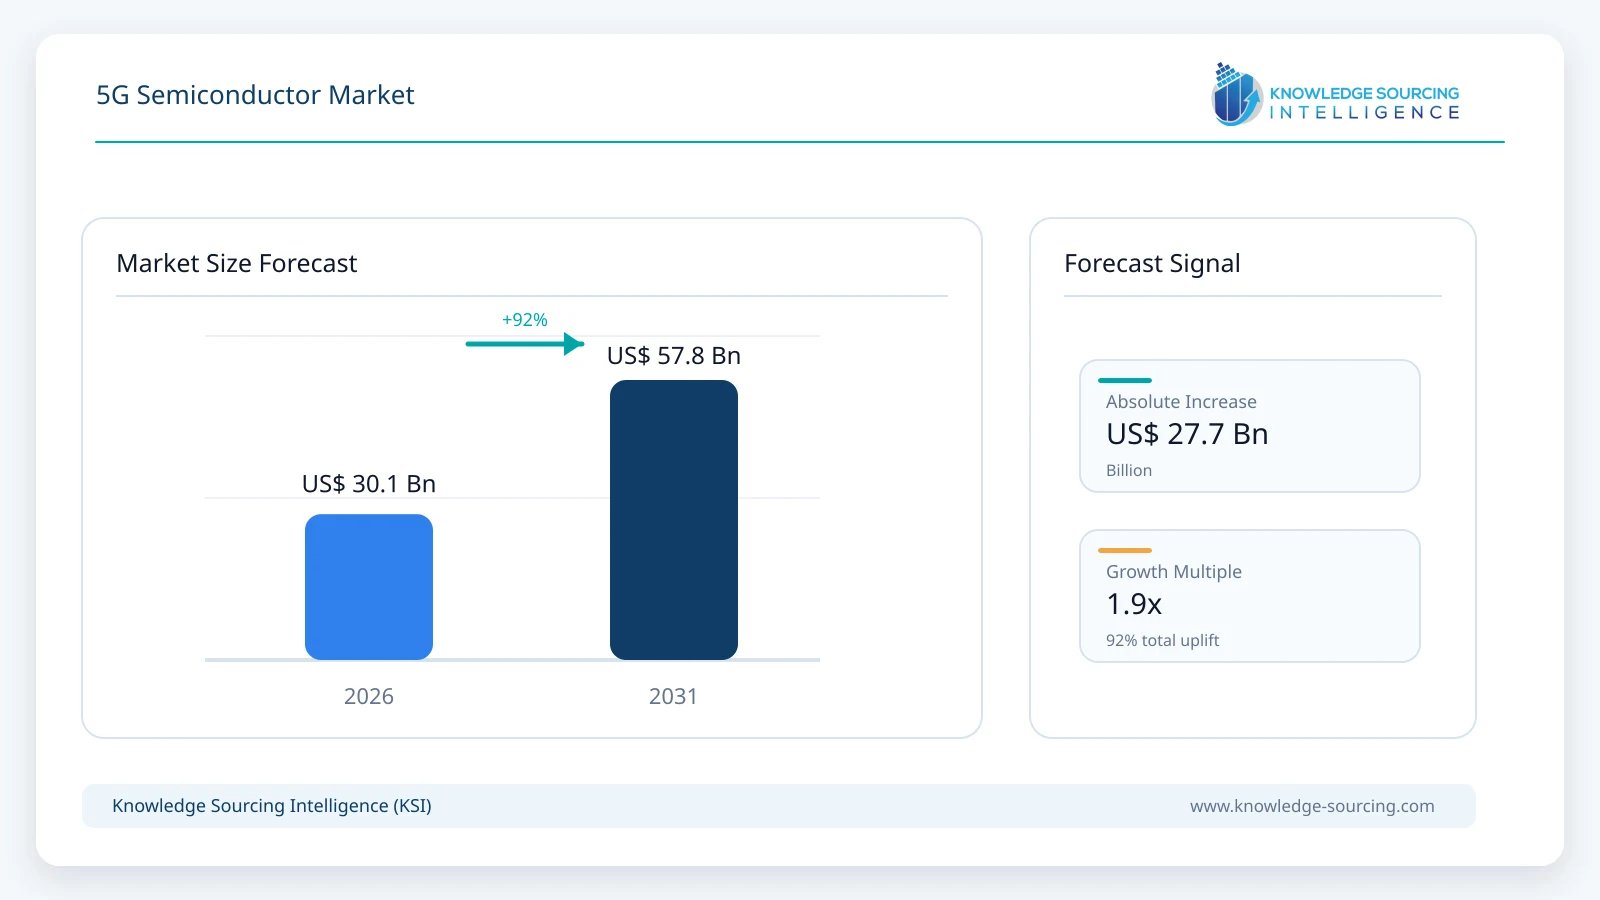
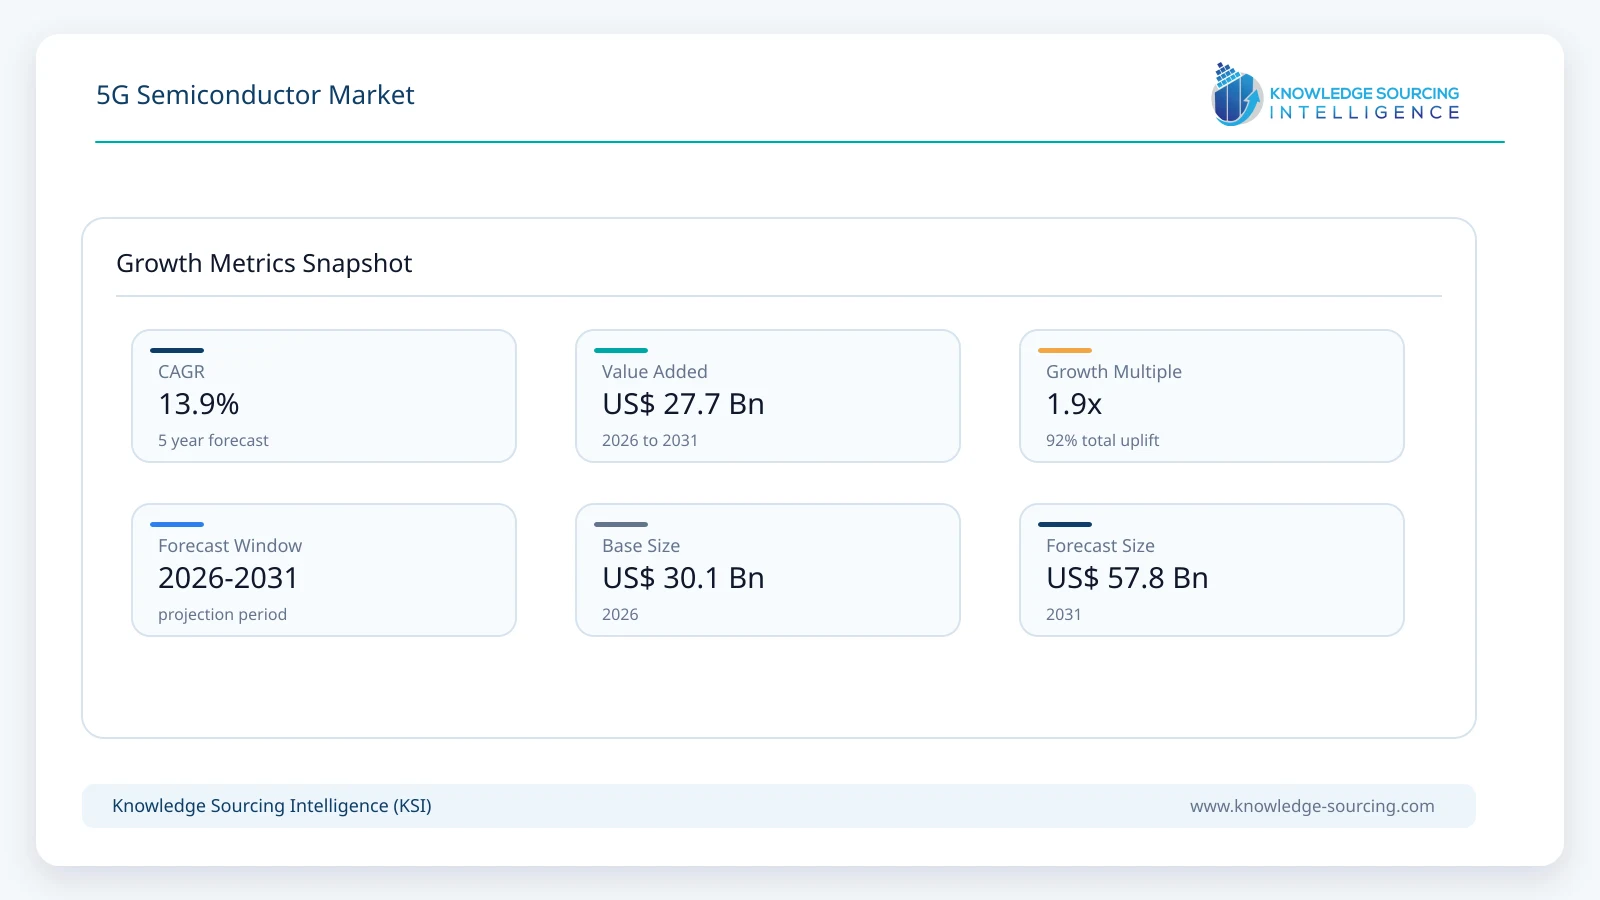
The 5G Semiconductor Market is forecast to grow at a CAGR of 13.9%, increasing from USD 30.1 billion in 2026 to USD 57.8 billion by 2031.
Highlights:
- 1Modem, baseband and cellular SoCs account for approximately 47.0% of the market in 2026, remaining the largest semiconductor function as 5G expands across smartphones, FWA, automotive and IoT.
- 2Smartphones and consumer devices represent approximately 62.0% of 2026 revenue, although infrastructure and connected-device applications capture a larger share of incremental growth.
- 3RAN and base-station processors and accelerators are the fastest-growing major semiconductor function at approximately 19.8% annually through 2031, supported by Cloud RAN, Open RAN and AI-RAN.
- 4mmWave-capable and multi-band semiconductor content grows at approximately 18.1% annually through 2031, driven by higher RF complexity and selected high-capacity applications.
- 5Asia Pacific accounts for approximately 58.0% of 2026 revenue, reflecting the region’s concentration of semiconductor, smartphone, module and telecom-equipment manufacturing.
Growth is supported by continuing migration of connected devices toward 5G, expansion of 5G standalone networks, commercialization of 5G-Advanced, increasing semiconductor content in radio-access infrastructure, RedCap adoption and the integration of AI acceleration into modem, RF and RAN processing architectures.
The market covers semiconductor content directly enabling 5G connectivity and radio-network operation, including cellular modem and baseband processors, RF front-end components, RAN and base-station processors and accelerators, and supporting power-management, timing and connectivity ICs. Integrated application processors are included only where identifiable semiconductor value is attributable to integrated cellular connectivity. General-purpose compute, memory and storage products without a direct 5G function are excluded.
The semiconductor requirement is becoming broader as 5G progresses from basic connectivity toward 5G-Advanced. Qualcomm’s X105, announced in March 2026, combines a Release 19-ready modem architecture with integrated AI processing, expanded carrier aggregation, NR-NTN and a new RF transceiver. MediaTek is following a similar direction with its M90 platform, while infrastructure vendors are increasingly combining dedicated baseband acceleration with general-purpose and AI-oriented compute.
5G semiconductor demand extends across both connected devices and network infrastructure. At the device level, a complete platform requires modem and baseband processing, RF transceivers, filters, switches, power amplifiers, antenna-management components and supporting power circuitry. Infrastructure requires a different mix of radio transceivers, baseband processors, accelerators, network processors and timing components. These markets are increasingly connected because the transition toward 5G-Advanced raises processing and RF requirements at both ends of the radio link.
The market is also moving beyond the initial smartphone-led deployment phase. Ericsson reported 3.1 billion global 5G subscriptions during the first quarter of 2026 and expects the total to reach 6.4 billion by 2031. More than 90 operators had commercially launched 5G Standalone networks, leaving substantial room for migration from NSA toward a more advanced 5G architecture.
Semiconductor value increasingly depends on capability rather than unit volume alone. New modem platforms support more carrier combinations, higher uplink performance, integrated satellite connectivity and AI-assisted operation. RF front ends become more complex as devices support additional bands, while network infrastructure is shifting toward programmable and accelerated processing. The result is a market in which smartphones remain the largest revenue pool but no longer account for the majority of incremental opportunity.
Market Drivers
5G-Advanced is increasing semiconductor functionality per device
5G-Advanced creates an upgrade cycle even in markets where smartphone unit growth is relatively modest. Qualcomm’s X105 5G Modem-RF, announced on March 2, 2026, is designed around a Release 19-ready architecture and introduces integrated NR-NTN, a fifth-generation dedicated 5G AI processor and broader spectrum aggregation. Qualcomm positions the platform across smartphones, FWA, automotive, PCs, XR and industrial IoT rather than limiting it to premium handsets.
The commercial implication extends into the RF front end. Supporting more frequency combinations, transmit paths and antenna configurations increases requirements for filters, switches, power amplification and tuning components. 5G-Advanced therefore raises semiconductor content even when the overall number of end devices grows more slowly than during the first 5G adoption cycle.
Cloud RAN and AI-RAN are expanding the infrastructure semiconductor opportunity
RAN architecture is becoming more compute intensive as operators separate software from proprietary baseband appliances and introduce AI into radio-network operation. Intel is positioning Xeon 6 SoC as a common platform across RAN, network core and edge workloads and demonstrated Cloud RAN and AI inference operating on common processor infrastructure at MWC Barcelona 2026.
Marvell follows a more specialized architecture through OCTEON Fusion baseband and network-processing products, while its March 2026 partnership with NVIDIA connects Marvell semiconductor technology with NVIDIA’s AI-RAN ecosystem.
The transition does not eliminate dedicated telecom silicon. Instead, it creates heterogeneous RAN compute combining CPUs, specialized accelerators, network processors and increasingly GPUs. This raises the value of semiconductor content associated with each advanced RAN deployment.
RF complexity continues rising as more bands are combined
The RF front end remains strategically important because every additional cellular band or transmit path requires physical RF functionality. Qorvo’s current infrastructure portfolio addresses Massive MIMO, macro base stations, small cells and backhaul, while its integrated module strategy combines several RF functions to reduce design complexity.
The same challenge exists in mobile devices. Supporting low-band coverage, several mid-band carriers and selected mmWave frequencies can require a large collection of filtering and amplification components even when much of the baseband processing has been consolidated into one SoC.
This means greater semiconductor integration does not eliminate the RF opportunity. It instead shifts competitive advantage toward suppliers capable of providing highly integrated modules that meet stringent size, efficiency and coexistence requirements.
RedCap broadens 5G semiconductor demand beyond high-performance devices
Conventional 5G semiconductor platforms were initially optimized for smartphones and broadband devices that could justify high modem complexity. RedCap creates a reduced-capability tier for automotive, industrial and IoT applications that require the longevity and network architecture of 5G but not multi-gigabit performance.
Qualcomm introduced the A10 5G Modem-RF on January 5, 2026 as its first automotive RedCap modem. The Release 17 platform supports both RedCap and LTE and is designed to reduce complexity, cost and power consumption for connected vehicles.
This expands the semiconductor opportunity into devices that otherwise could remain on LTE for much of the forecast period and creates a wider performance ladder between LPWA connectivity and flagship 5G.
Uplink-intensive applications increase modem and network-processing requirements
Mobile networks have historically been optimized primarily around downlink traffic, but video creation, cloud interaction, industrial applications and AI services are increasing uplink requirements. The semiconductor impact extends from handset transmit architecture through radio processing and network compute.
MediaTek and Samsung demonstrated this direction on June 3, 2026 by completing a 3Tx five-layer uplink configuration using MediaTek’s M90 modem and Samsung vRAN and radio infrastructure. The test combined n66 and dual n77 carriers and achieved 670 Mbps uplink throughput.
More sophisticated uplink operation increases requirements for modem scheduling, RF transmission paths, carrier aggregation and base-station processing, strengthening semiconductor value across both the device and network sides of the market.
Market Restraints and Challenges
Smartphone maturity limits growth in the largest application
Smartphones remain the largest semiconductor application, but overall handset volumes are substantially more mature than during the first decade of smartphone adoption. The market therefore depends increasingly on semiconductor content per device rather than rapid expansion in device units.
Greater RF complexity, AI processing and 5G-Advanced capability support additional value, but component integration and pricing pressure offset part of this increase. This makes smartphones a large but comparatively slower-growing segment and shifts a greater proportion of incremental opportunity toward infrastructure, FWA, automotive and industrial applications.
Semiconductor integration can reduce discrete component opportunities
Greater integration improves size, efficiency and system cost but can reduce the number of standalone components required in each device. Functions that previously required separate modem, transceiver, positioning and processing chips can increasingly be consolidated into fewer packages.
This favors suppliers controlling broader system architectures while creating pressure on vendors dependent on a narrow discrete component category. RF technologies retain greater specialization because filters, power amplifiers and antenna-related functions cannot always be consolidated onto the same advanced digital process used for baseband compute.
Advanced semiconductor development requires increasing capital and engineering resources
High-performance modem and network processors increasingly require advanced process technology, complex physical design and substantial software investment. Development costs rise as vendors integrate more processing, AI, positioning and radio functionality into each platform.
This creates high barriers to entry in modem and baseband silicon and encourages consolidation around suppliers capable of supporting multiyear standards development and large customer programs. Specialist RF and infrastructure semiconductor companies can compete through differentiated architectures, but building a complete global modem ecosystem remains particularly capital-intensive.
mmWave remains geographically selective
mmWave-capable semiconductor content is growing rapidly, but mmWave itself remains concentrated in selected devices, FWA deployments, venues and high-capacity infrastructure. Most global 5G traffic continues to rely primarily on Sub-6 GHz spectrum.
Suppliers therefore need to support increasingly advanced mmWave architectures without assuming universal deployment. The strongest business cases remain where very high capacity or localized coverage offsets shorter propagation range and greater equipment complexity.
Major Segment Analysis
Modem, Baseband & Cellular SoCs: Largest Semiconductor Function
Modem and baseband platforms remain the central semiconductor layer because virtually every 5G device requires connectivity processing regardless of its end application. The category is projected to reach approximately USD 24.84 billion by 2031, supported by wider 5G penetration, 5G-Advanced upgrades, RedCap and increasing integration of AI and NTN functions.
Growth is slower than RAN processing because smartphone modem penetration is already high in many major markets. Competitive differentiation increasingly centers on power efficiency, carrier aggregation, uplink capability, AI integration and the ability to support a wider range of device categories from one architecture.
RAN & Base-Station Processors and Accelerators: Fastest-Growing Function
RAN processing is moving toward a more heterogeneous architecture as traditional purpose-built baseband equipment coexists with virtualized RAN, Open RAN and AI-accelerated systems. The segment is projected to reach approximately USD 10.40 billion by 2031, giving it the strongest growth profile among the principal semiconductor functions.
Marvell, Intel, NVIDIA, AMD and other compute suppliers are increasingly competing alongside traditional telecom semiconductor platforms. The opportunity extends beyond replacing proprietary baseband hardware because operators are beginning to evaluate infrastructure capable of supporting radio processing and AI workloads within the same distributed compute environment.
Smartphones & Consumer Devices: Largest Application
Smartphones remain the largest application but are projected to grow at approximately 10.0% annually through 2031, below the overall semiconductor market. Increasing 5G penetration in lower price tiers and migration toward 5G-Advanced support continued growth, while mature global handset volumes constrain the expansion rate.
The segment nevertheless remains strategically important because advanced smartphone architectures drive modem, RF-front-end and process-technology development that later migrates into FWA, automotive, PCs and IoT.
FWA, Routers & IoT: Faster-Growing Device Opportunity
FWA, routers and IoT represent one of the strongest device-side growth pools as 5G expands beyond smartphones. The segment is projected to exceed USD 10 billion by 2031, supported by residential FWA, enterprise gateways, RedCap and industrial connectivity.
The semiconductor mix differs substantially by application. High-performance FWA equipment requires advanced modem-RF systems and substantial processing, while RedCap enables lower-cost industrial and IoT platforms with reduced bandwidth and power requirements. This allows semiconductor vendors to serve a much broader performance range than during the first stage of 5G deployment.
mmWave-Capable & Multi-Band Semiconductors: Fastest-Growing Radio Segment
mmWave-capable semiconductor revenue is projected to reach approximately USD 17.33 billion by 2031. The segment benefits from greater semiconductor value per device because beamforming, additional RF paths and high-frequency operation require more sophisticated radio components than conventional Sub-6 GHz-only designs.
Growth remains concentrated in premium devices, FWA, dense venues and selected infrastructure. The segment therefore increases materially in value without becoming the dominant global radio architecture.
Regional Analysis
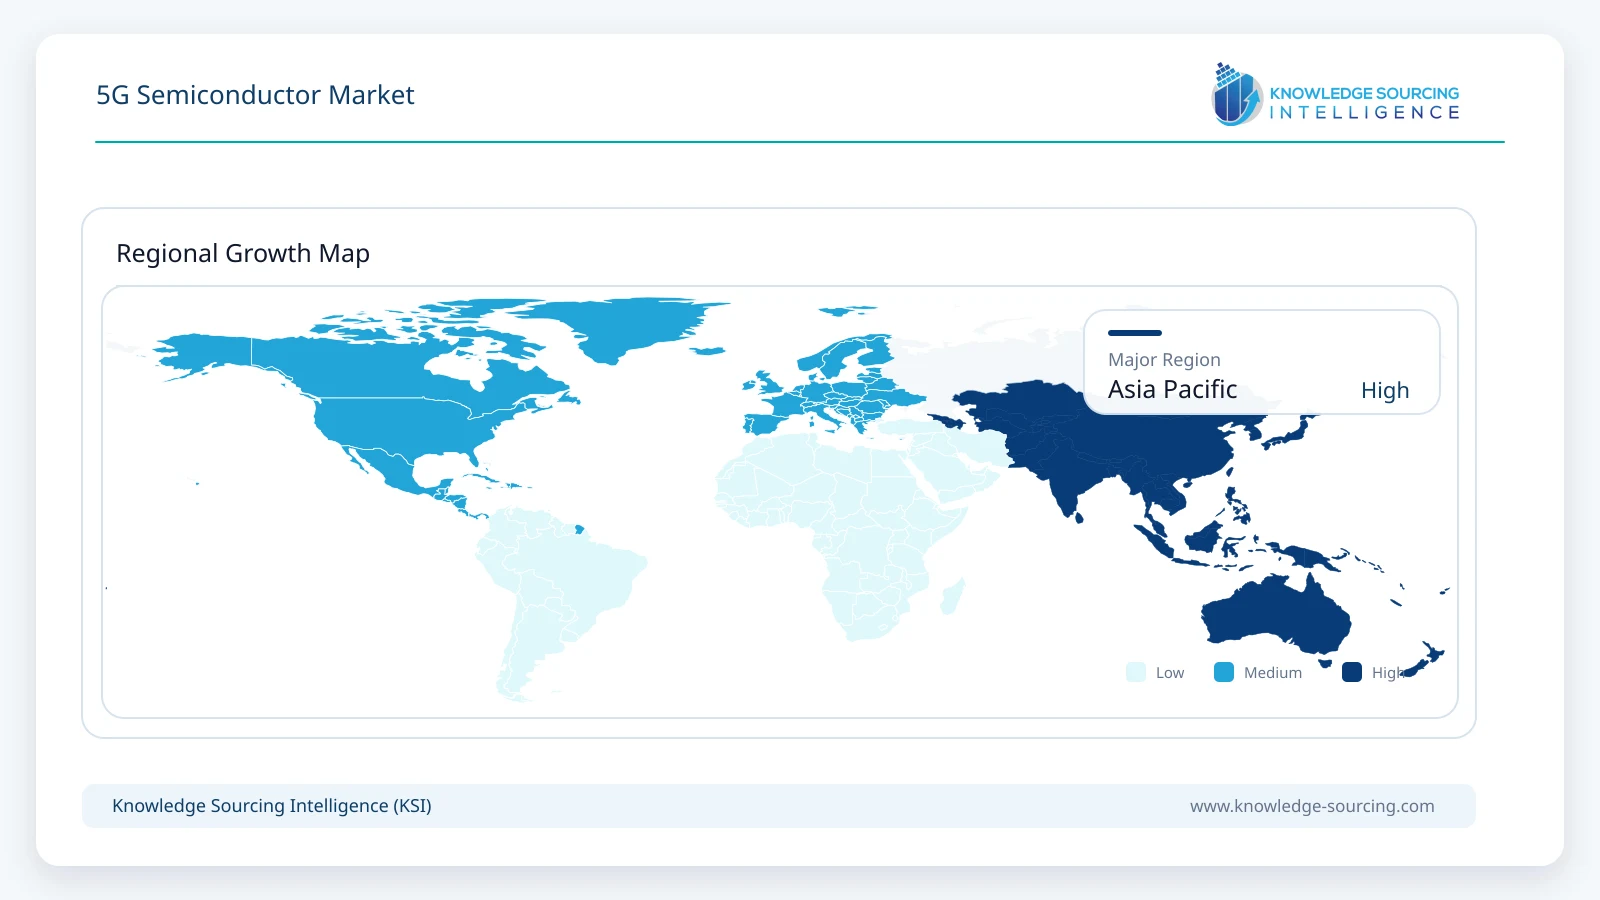
Asia Pacific remains the largest regional market because it combines enormous end-device demand with concentration of semiconductor fabrication, packaging, module manufacturing and telecom-equipment production. China is central to smartphone, network-equipment and IoT demand, Taiwan remains critical to semiconductor manufacturing, South Korea combines device and semiconductor production, and Japan retains significant RF and specialist-component capabilities.
Regional revenue is projected to approach USD 35 billion by 2031, while Asia Pacific maintains roughly three-fifths of the global market. North America remains strategically important through semiconductor design leadership in modem, RF, infrastructure compute and AI acceleration, while Europe contributes demand through industrial, automotive and telecom applications. Middle East and Africa remain smaller but expand as 5G deployment moves into more markets.
Technology Outlook
AI-Integrated Modem-RF Platforms
AI is increasingly becoming part of the connectivity subsystem rather than remaining confined to the application processor. Qualcomm’s X105 includes a dedicated 5G AI processor designed to optimize modem behaviour according to network and application conditions.
The integration of AI directly into modem operation can improve radio selection, efficiency and traffic optimization and represents an additional source of semiconductor value within advanced connectivity platforms.
AI-RAN and Heterogeneous Baseband Compute
Future RAN architectures increasingly combine general-purpose processors, telecom accelerators and AI-oriented compute. Intel’s Xeon approach emphasizes convergence on common compute, while Marvell and NVIDIA represent a model combining specialized silicon with accelerated AI infrastructure.
The commercial opportunity therefore shifts from one dominant processor architecture toward a heterogeneous RAN compute stack optimized for performance per watt and programmability.
Integrated Terrestrial and Non-Terrestrial Connectivity
NR-NTN support is increasingly being integrated directly into mainstream modem architectures. Qualcomm’s X105 includes integrated satellite support alongside terrestrial 5G, positioning NTN as part of the broader cellular connectivity platform rather than a completely separate modem category.
This increases requirements across modem processing, RF design, positioning and power management and creates additional value in premium mobile, automotive and industrial platforms.
Recent Developments
June 2026: MediaTek and Samsung completed the industry’s first 3Tx five-layer 5G uplink test using MediaTek’s M90 modem and Samsung vRAN, Massive MIMO and macro-radio infrastructure. The configuration combined n66 and dual n77 carriers and achieved 670 Mbps uplink throughput.
March 2026: NVIDIA and Marvell announced a strategic semiconductor partnership connecting Marvell custom silicon and networking technologies with the NVIDIA AI-RAN ecosystem, extending collaboration into next-generation 5G and 6G infrastructure.
March 2026: Qualcomm introduced the X105 5G Modem-RF, its first Release 19-ready modem-RF architecture, incorporating integrated NR-NTN and a fifth-generation 5G AI processor.
January 2026: Qualcomm introduced the A10 5G Modem-RF, its first automotive 5G RedCap modem, targeting lower-complexity and lower-power migration from LTE toward 5G connectivity.
Competitive Landscape
Qualcomm holds a central position in 5G semiconductor architecture through its modem-RF systems, RF front-end portfolio and platforms addressing smartphones, FWA, automotive and IoT. Its competitive direction is increasingly centered on integration of modem processing, AI, RF, positioning and terrestrial/non-terrestrial connectivity within common system architectures.
MediaTek provides the principal alternative high-volume modem platform across smartphones and connected devices. The M90 extends the company’s position into advanced carrier aggregation, uplink performance, AI-assisted connectivity and future 5G-Advanced device platforms.
Broadcom, Qorvo, Skyworks and Murata remain significant RF participants. Qorvo’s current portfolio spans mobile front-end modules and infrastructure products for macro base stations, Massive MIMO and small cells, reflecting the continuing importance of specialist RF technology even as digital semiconductor functions consolidate.
Marvell is positioned strongly in infrastructure semiconductor processing through baseband and network-processing technologies, while Intel competes through general-purpose network and edge compute. NVIDIA is becoming increasingly relevant as AI-RAN brings accelerated computing into telecom infrastructure.
Analog Devices maintains a strong position in highly integrated radio transceivers for base-station equipment, while AMD provides adaptive computing and acceleration technologies used across communications infrastructure. NXP, Texas Instruments, Renesas and Infineon participate across power, timing, control and supporting semiconductor functions.
Competition therefore differs by layer. Modem suppliers compete on standards readiness, power efficiency and integration; RF vendors compete on filtering, amplification and module complexity; infrastructure suppliers increasingly compete on performance per watt, programmability and the ability to combine conventional telecom workloads with AI processing.
Analyst View
The 5G semiconductor market is moving from a connectivity-adoption cycle toward a semiconductor-content cycle. The first phase depended heavily on the number of smartphones moving from LTE to 5G. The next phase depends more on what each connected device and base station needs to do once 5G becomes standard.
This favors semiconductor categories where complexity is still increasing materially. RAN processing is one of the clearest examples because network architecture is shifting toward Cloud RAN, Open RAN and AI-RAN rather than simply replicating traditional baseband systems. RF remains similarly important because additional bands and aggregation combinations continue increasing the amount of radio functionality required even when device volumes are mature.
RedCap expands the market in a different direction by lowering the semiconductor threshold for adopting 5G. Automotive, industrial and IoT applications can move onto 5G SA without requiring the complete modem-RF capability of a premium smartphone.
Smartphones will remain the largest revenue pool, but the most attractive incremental opportunities increasingly sit in RAN acceleration, FWA and IoT, RedCap, mmWave and AI-integrated modem-RF platforms. The competitive advantage shifts toward semiconductor suppliers able to combine performance, power efficiency and software programmability rather than simply deliver higher theoretical peak speeds.
5G Semiconductor Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 30.1 billion |
| Total Market Size in 2031 | USD 57.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 13.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Semiconductor Function, Application, Radio Capability, Geography |
| Companies |
|
Market Segmentation
By Semiconductor Function
Modem, Baseband & Cellular SoCs
RF Front-End Semiconductors
RAN & Base-Station Processors and Accelerators
Power Management, Timing & Supporting ICs
By Application
Smartphones & Consumer Devices
FWA, Routers & IoT
5G Network Infrastructure
Automotive & Industrial 5G
By Radio Capability
Sub-6 GHz-Focused
mmWave-Capable & Multi-Band
By Geography
North America
South America
Europe
Middle East and Africa
Asia Pacific
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Scope Exclusions
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. Global 5G Device and Subscription Outlook
3.5. 5G Standalone and 5G-Advanced Adoption
3.6. RF Front-End Complexity
3.7. Semiconductor Integration and Process Technology
3.8. Cloud RAN, Open RAN and AI-RAN Semiconductor Requirements
3.9. Porter’s Five Forces Analysis
3.10. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. AI-Integrated Modem-RF Platforms
4.2. AI-RAN and Heterogeneous Baseband Compute
4.3. Integrated Terrestrial and Non-Terrestrial Connectivity
5. 5G SEMICONDUCTOR MARKET BY SEMICONDUCTOR FUNCTION
5.1. Introduction
5.2. Modem, Baseband & Cellular SoCs
5.3. RF Front-End Semiconductors
5.4. RAN & Base-Station Processors and Accelerators
5.5. Power Management, Timing & Supporting ICs
6. 5G SEMICONDUCTOR MARKET BY APPLICATION
6.1. Introduction
6.2. Smartphones & Consumer Devices
6.3. FWA, Routers & IoT
6.4. 5G Network Infrastructure
6.5. Automotive & Industrial 5G
7. 5G SEMICONDUCTOR MARKET BY RADIO CAPABILITY
7.1. Introduction
7.2. Sub-6 GHz-Focused
7.3. mmWave-Capable & Multi-Band
8. 5G SEMICONDUCTOR MARKET BY GEOGRAPHY
8.1. North America
8.2. South America
8.3. Europe
8.4. Middle East and Africa
8.5. Asia Pacific
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Competitive Positioning
9.2. Modem & Baseband Platform Benchmarking
9.3. RF Front-End Capability
9.4. RAN Processing and Acceleration
9.5. 5G-Advanced & Release 18/19 Readiness
9.6. RedCap, NTN & mmWave Capability
9.7. AI Integration and Power Efficiency
9.8. Strategic Developments
9.9. Competitive Dashboard
10. COMPANY PROFILES
10.1. Qualcomm Technologies, Inc.
10.2. MediaTek Inc.
10.3. Samsung Electronics Co., Ltd.
10.4. Broadcom Inc.
10.5. Qorvo, Inc.
10.6. Skyworks Solutions, Inc.
10.7. Murata Manufacturing Co., Ltd.
10.8. Marvell Technology, Inc.
10.9. Intel Corporation
10.10. Advanced Micro Devices, Inc.
10.11. Analog Devices, Inc.
10.12. NXP Semiconductors N.V.
10.13. Texas Instruments Incorporated
10.14. Renesas Electronics Corporation
10.15. Infineon Technologies AG
11. ANALYST VIEW
12. APPENDIX
12.1. Research Methodology
12.2. Market Estimation and Assumptions
12.3. Scope and Double-Counting Controls
12.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











