
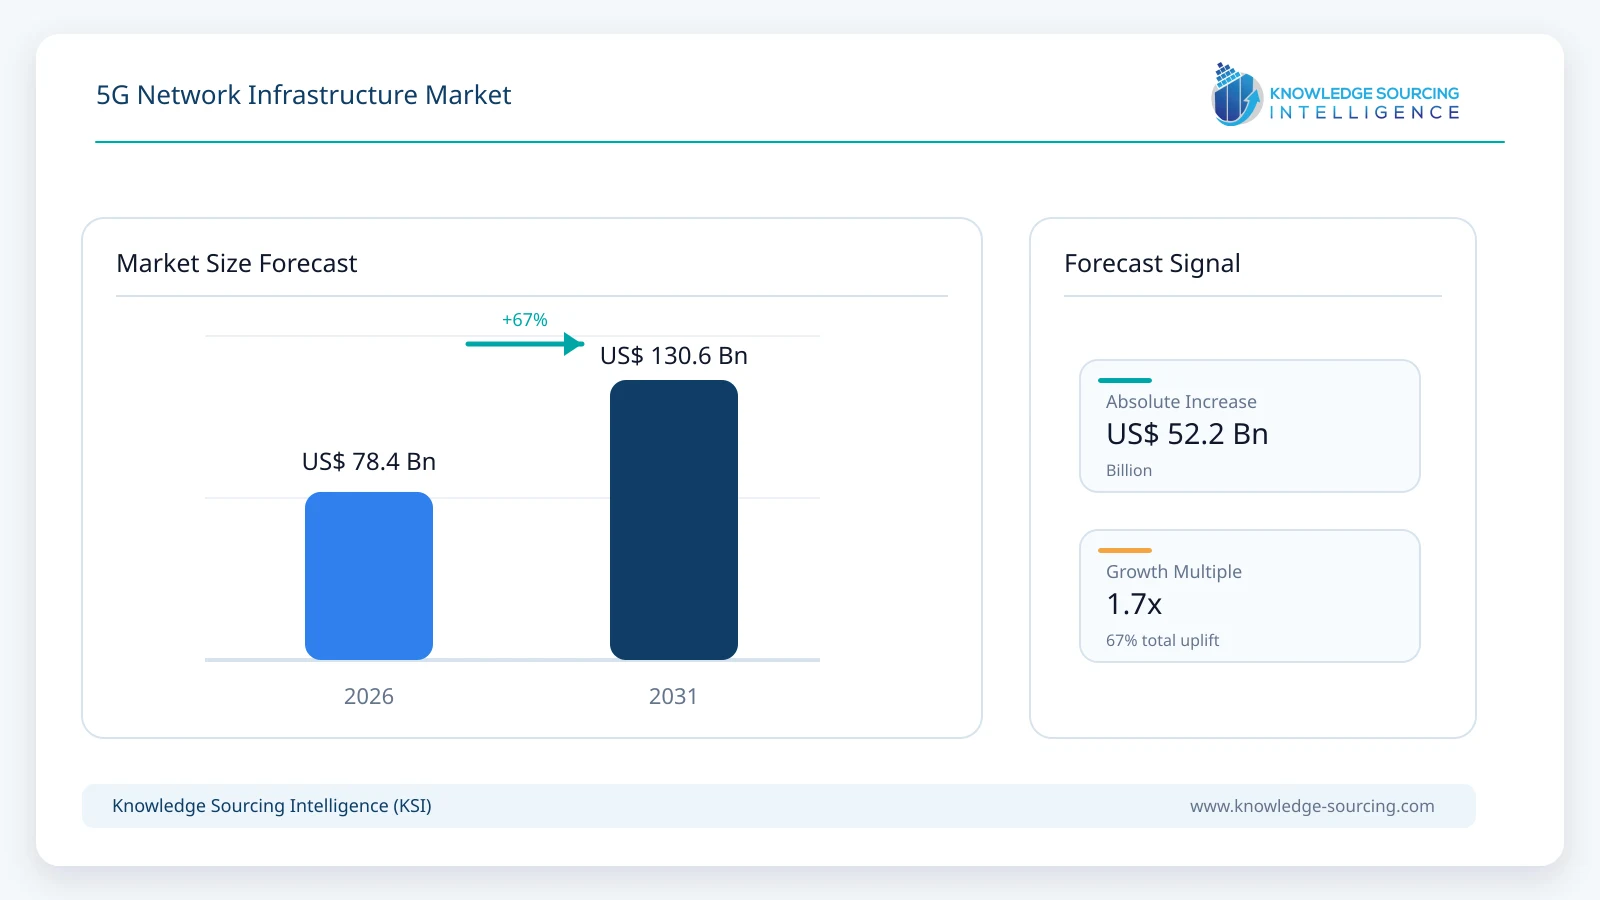
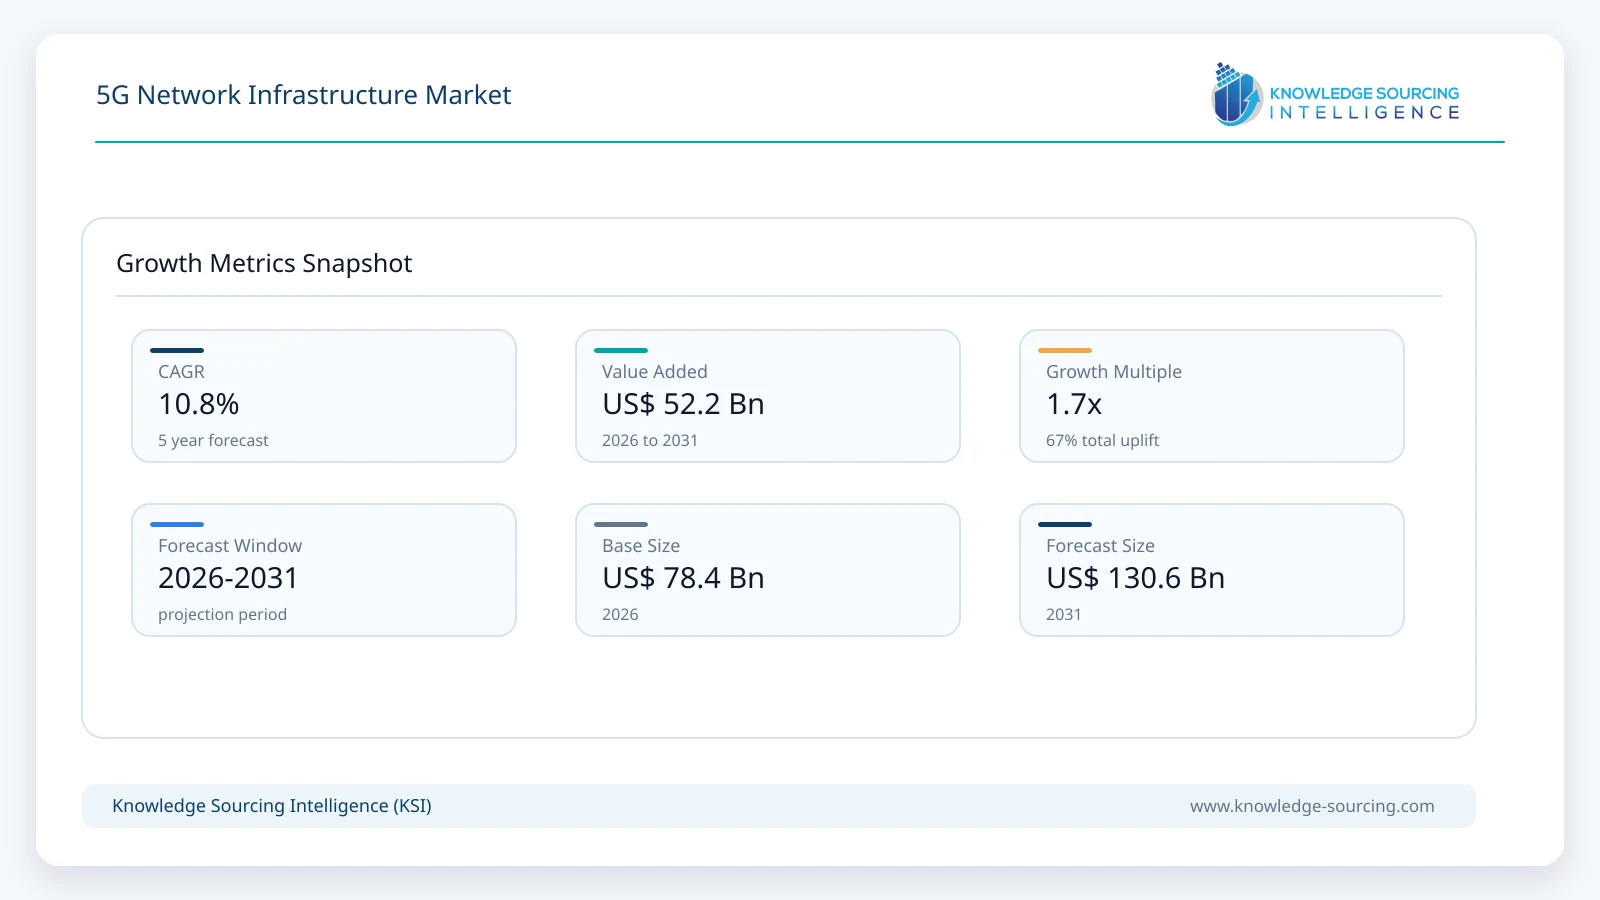
The 5G network infrastructure market is projected to grow at a CAGR of 10.8% over the forecast period, increasing from USD 78.4 billion in 2026 to USD 130.6 billion by 2031.
Highlights:
- 1Radio Access Network infrastructure accounts for an estimated 54.1% of global market revenue in 2026, reflecting the continued scale of Massive MIMO, macro-radio, baseband, small-cell and radio-modernization spending.
- 2Asia Pacific represents approximately 61.8% of market revenue in 2026, primarily because China remains the world’s largest installed 5G infrastructure base while India continues rapid network expansion.
- 324.3% annually through 2031Public carrier networks remain the principal deployment model, but private 5G infrastructure is forecast to expand at approximately , materially faster than conventional nationwide carrier infrastructure.
- 490 service providers have commercially launched 5G Standalone networksMore than , compared with approximately 390 operators offering 5G services overall.
- 53.1 billion during Q1 2026Global 5G subscriptions passed and are forecast to reach 6.4 billion by 2031. 5G carried approximately 48% of global mobile data traffic at the end of 2025 and is expected to handle 85% by 2031.
- 65.15 million 5G base stations by July 2026China reached , while India reached 562,971 5G BTSs by June 2026, illustrating the very different scale of physical infrastructure deployment across the two fastest-growing Asian ecosystems.
- 75G Standalone, 5G-Advanced, private 5G, AI-RAN, automated network operations and additional mid-band capacityInfrastructure spending is shifting from initial 5G coverage toward .
The market covers the infrastructure required to provide commercial and private 5G connectivity, including radio access network equipment, 5G core networks, transport and backhaul infrastructure, edge infrastructure and network-management and orchestration systems. The scope includes public carrier networks, private 5G systems and shared or hybrid deployment architectures. It excludes mobile devices, FWA customer-premises equipment, passive cell-tower assets where no network equipment is included, and standalone semiconductor revenue.
China has already constructed more than five million 5G base stations and is transitioning toward 5G-Advanced upgrades, while India remains in a stronger capacity-expansion phase and markets including the United States are increasing investment in Standalone cores, Open RAN, private 5G and AI-enabled network infrastructure.
Market Overview
The global 5G network infrastructure market is moving from a coverage-led rollout cycle into a more differentiated investment phase. During the early commercial years of 5G, operator capital expenditure concentrated heavily on radio deployment, spectrum activation and achieving national population coverage. By 2026, this pattern has changed. China, South Korea, North America and several Gulf markets have mature 5G coverage, while India has completed one of the fastest nationwide deployments globally. Infrastructure requirements increasingly arise from capacity expansion, Standalone core migration, network slicing, private wireless, software automation and preparation for 5G-Advanced rather than simply adding first-generation 5G radios.
This transition explains why the previous 15.4% global forecast is no longer appropriate. China’s current KSI country model places its infrastructure market at USD 32.4 billion in 2026 and USD 39.8 billion in 2031, reflecting only 4.2% annual growth as the country’s physical network matures. India, by comparison, is estimated at USD 5.2 billion in 2026 and USD 17.1 billion in 2031 as capacity, enterprise applications and Standalone infrastructure expand. The U.S. model similarly shows considerably faster growth than China. A credible global forecast therefore needs to aggregate markets at different stages rather than apply a single high-growth rate to the existing worldwide base.
Subscriber and traffic trends nevertheless provide a strong underlying investment case. Ericsson estimates that global 5G subscriptions reached 3.1 billion during Q1 2026 and will increase to 6.4 billion by 2031. More importantly for infrastructure suppliers, 5G’s share of mobile data traffic is expected to rise from 48% at the end of 2025 to approximately 85% by 2031. Networks therefore need to support substantially more traffic even where headline coverage statistics change relatively little.
The architecture of spending is also broadening. RAN remains the largest component, but 5G Core, transport, edge systems and software-defined network management are gaining relative importance. Operators that initially deployed 5G through Non-Standalone architecture increasingly need cloud-native Standalone cores if they want to commercialize network slicing, differentiated quality of service, network APIs and enterprise connectivity. Ericsson identified 84 commercial differentiated-connectivity offerings based on 5G SA network slicing by mid-2026, up from 65 only six months earlier.
Market Drivers
5G Standalone migration is creating a second infrastructure investment cycle
The transition from Non-Standalone to Standalone 5G requires more than a software label change. SA networks use cloud-native 5G core architecture and enable capabilities such as network slicing, more advanced policy control, API exposure and differentiated connectivity without dependence on legacy 4G core infrastructure. More than 90 operators have now launched 5G SA, but that remains a minority of the roughly 390 operators that have launched commercial 5G overall, leaving substantial migration potential through 2031.
Commercial deployment activity confirms that this transition is active rather than theoretical. Wind Tre switched on Italy’s first 5G Standalone network with Ericsson in January 2026, while Three Sweden and Telekom Slovenije also deployed Ericsson-powered SA networks. These projects require cloud-native core infrastructure together with compatible RAN, orchestration and transport systems.
Increasing mobile traffic requires additional capacity after coverage is complete
Population coverage is a poor proxy for network completion. A network can technically cover a city while still requiring additional radio capacity, spectrum layers and backhaul as customer traffic rises. Ericsson forecasts 5G to carry approximately 85% of mobile data traffic by 2031, meaning operators need to expand capacity on infrastructure that may already provide nominal coverage.
Virgin Media O2’s 2026 UK network-modernization program illustrates this shift. The operator is deploying additional Massive MIMO and multiband radio infrastructure, exploiting newly acquired mid-band spectrum and preparing its network for broader 5G SA and 5G-Advanced capabilities. Ericsson and Nokia both secured substantial parts of the operator’s modernization program rather than a conventional first-time 5G rollout.
India remains in a stronger physical infrastructure expansion phase
India differs from more mature 5G markets because its network continues to expand rapidly while subscriber and data usage also rise. The number of 5G BTSs increased from 140,623 in March 2023 to 562,971 by June 30, 2026, with 5G available across 99.9% of districts. Government policy additionally supports domestic telecom-equipment manufacturing and indigenous 5G core development.
India’s infrastructure spending increasingly moves beyond geographic rollout toward densification, fixed wireless access, additional spectrum utilization and enterprise connectivity. Ericsson expects Indian 5G subscriptions to exceed 1.1 billion by 2031, providing one of the world’s largest future traffic bases.
Private 5G is creating an infrastructure market outside conventional MNO networks
Manufacturers, utilities, ports, mining operators, logistics companies and large campuses increasingly deploy dedicated private cellular networks where deterministic coverage, mobility or security requirements cannot be met economically through conventional enterprise Wi-Fi alone. Private 5G requires its own radios, core software, edge infrastructure and network management but often operates at a much smaller scale than national carrier networks.
Commercial models are becoming more repeatable. Ericsson and Verizon Business expanded private 5G availability internationally in June 2026, while NTT DATA and Ericsson established a multi-year partnership intended to provide managed private 5G integrated with edge and physical AI capabilities.
The KSI model therefore projects private 5G infrastructure expenditure to increase from approximately USD 7.1 billion in 2026 to nearly USD 20.9 billion by 2031. This growth does not imply private networks replacing carrier infrastructure. Instead, they create an additional infrastructure layer within industrial facilities and enterprise campuses.
5G-Advanced is extending the commercial life of the 5G investment cycle
5G-Advanced introduces improvements in carrier aggregation, uplink performance, network intelligence, RedCap connectivity, energy efficiency and service differentiation. China is already progressing beyond basic 5G deployment into large-scale 5G-A commercialization, while Huawei introduced a 5G-Advanced mobile backhaul architecture in February 2026 designed around 10GE/25GE site connectivity and programmable SRv6 transport.
This transition supports additional investment across RAN, transport and automation without requiring an entirely new network generation. It also provides a bridge between conventional 5G infrastructure and 6G commercialization expected around 2030.
Market Restraints and Challenges
China’s enormous installed network reduces incremental global growth
China remains the largest individual 5G infrastructure market, but its growth profile is structurally changing. The country reached 5.15 million 5G base stations by July 2026, with networks covering all towns and more than 95% of administrative villages. The incremental need for millions of additional conventional coverage sites is therefore lower than during the initial rollout.
Future spending increasingly shifts toward 5G-A, industrial applications and network modernization. This remains commercially significant, but it grows more slowly than the original nationwide build and consequently reduces the sustainable CAGR of the global market.
Operators still need clearer monetization from Standalone infrastructure
5G SA allows differentiated connectivity, network slicing and enterprise services, but technical capability does not automatically create revenue. Ericsson’s 2026 study of telecom executives found that roughly 70% had not yet begun implementing many of the technologies they considered critical to future growth, despite strong confidence in the opportunity.
Operators may therefore phase infrastructure investments where there is no clear commercial path to monetizing new network capabilities. Network vendors increasingly need to demonstrate operational savings or measurable new service revenue rather than selling infrastructure primarily on peak performance.
Vendor restrictions fragment global procurement
5G infrastructure has become strategically sensitive because mobile networks form part of national critical infrastructure. Restrictions on specific vendors and national supply-chain requirements have fragmented what was once a more globally uniform procurement market. Operators may need to replace existing equipment, maintain multiple vendor stacks or select higher-cost alternatives according to security and policy requirements.
This fragmentation creates opportunities for Ericsson, Nokia, Samsung, NEC, Mavenir and Open RAN vendors in selected markets but can also increase integration complexity and slow investment decisions.
Open and cloud RAN increase integration responsibility
Open RAN and virtualized RAN architectures allow operators to separate hardware, software and radio components, potentially increasing supplier choice. However, disaggregation can transfer a larger integration burden to the operator or systems integrator. Achieving equivalent performance, synchronization and lifecycle management across multivendor systems can be difficult, particularly in large nationwide networks.
Ericsson and Nokia’s March 2026 decision to make their automation applications more compatible across each other’s SMO ecosystems illustrates the industry’s recognition that interoperability needs to extend beyond standardized radio interfaces into operational software.
Approaching 6G affects late-period capital planning
3GPP’s current schedule places 6G specifications within Release 21, spanning 2027–2028, with first commercial systems expected around 2030. Operators investing in infrastructure during 2029–2031 will increasingly assess whether assets can support both advanced 5G and later 6G evolution.
This does not make 5G infrastructure obsolete. Fiber transport, cloud-native cores, edge sites, automation platforms and much of the physical RAN architecture will remain relevant. However, it can slow investment in equipment with limited upgrade paths.
Major Segment Analysis
By Component
Radio Access Network remains the largest infrastructure category, accounting for an estimated 54.1% of global market revenue in 2026. Massive MIMO radios, baseband systems, small cells and radio modernization continue to absorb substantial operator investment, particularly in India, emerging markets and capacity-constrained urban networks.
RAN’s share gradually declines through 2031 as the market shifts toward software and distributed computing. 5G Core infrastructure grows faster as operators migrate to Standalone architecture, while transport systems require higher-capacity links to support dense RAN and edge deployments.
Network management and orchestration is projected to record approximately 18.3% CAGR through 2031, making it one of the fastest-growing component groups. Ericsson’s June 2026 expansion of its Intelligent Automation Platform from RAN into core networks and Nokia’s agentic autonomous-network portfolio demonstrate how operational software is becoming a larger part of network investment.
Edge infrastructure also records above-market growth and is projected to reach approximately USD 14.37 billion by 2031, supported by private networks, low-latency enterprise applications and increasingly distributed AI workloads.
By Spectrum Band
Mid-band spectrum remains the principal radio-infrastructure layer because it provides the best compromise between coverage and capacity. The 2.5 GHz, 3.3–3.8 GHz and similar bands support a substantial portion of current Massive MIMO deployment and remain central to operator capacity strategies through 2031.
Low-band infrastructure remains necessary for rural and wide-area coverage but offers less capacity. mmWave grows faster from a smaller base and is increasingly used for dense urban hotspots, fixed wireless and selected enterprise applications rather than as the principal nationwide radio layer.
By Deployment Type
Public carrier networks remain the largest category throughout the forecast period because nationwide mobile operators control most spectrum and infrastructure investment. However, their share falls gradually as private 5G and hybrid networks expand.
Private 5G is the fastest-growing major deployment model. Industrial operators increasingly require connectivity designed around production environments rather than consumer mobile broadband. Manufacturing, ports, mining and logistics provide the strongest commercial use cases because the economic value of automation and machine connectivity can justify dedicated infrastructure.
By Deployment Mode
Non-Standalone infrastructure remains significant in 2026 because a large number of global 5G networks still rely on 4G core infrastructure. This balance changes substantially during the forecast period.
The KSI model estimates that Standalone-related infrastructure increases to approximately 69% of deployment-mode revenue by 2031 as operators introduce cloud-native 5G cores, network slicing and programmable quality-of-service capabilities.
By End User
Telecom operators remain the principal buyer through 2031. However, manufacturing and industrial automation increase their contribution as private 5G deployments move from pilots toward production environments. Transportation, ports, utilities, public safety and government networks provide additional specialized demand.
Regional Analysis
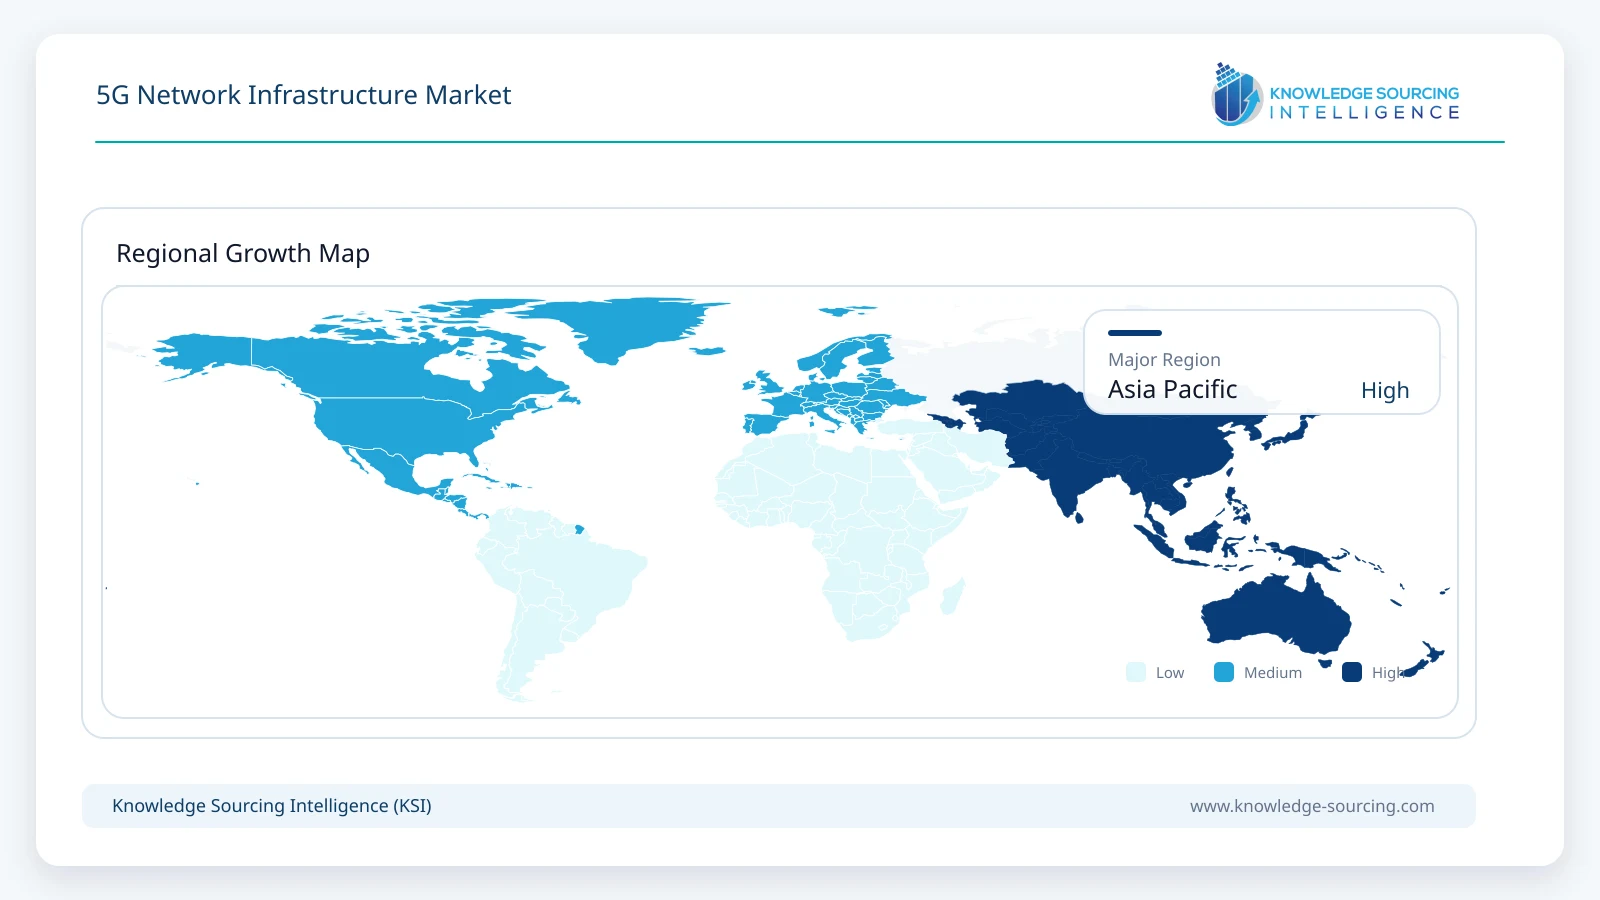
Asia Pacific accounts for approximately 61.8% of global revenue in 2026, reflecting the extraordinary scale of China’s installed infrastructure together with continued investment in India, Japan and South Korea. The region’s share gradually declines through 2031 as China’s growth moderates and North America, the Middle East and selected emerging markets increase investment.
China remains the world’s largest single market but transitions from base-station rollout toward 5G-A, industrial connectivity, automation and higher-capacity transport. India provides the strongest large-country expansion opportunity and is expected to increase materially in the global infrastructure mix through 2031.
North America grows considerably faster than its 2026 base because U.S. spending increasingly shifts toward mid-band densification, Open RAN, 5G SA, private networks and network modernization. AT&T and Ericsson’s 2026 deployment of new 600 MHz dual-band radios and continued Open RAN modernization illustrates ongoing infrastructure investment beyond initial 5G launch.
Europe has broad 5G coverage but remains behind leading Asian markets in SA deployment. Multi-year modernization programs at Virgin Media O2, Wind Tre and other operators indicate that infrastructure spending is increasingly linked to core migration, additional spectrum and network automation rather than first-time coverage.
The Middle East remains an important high-investment market because Saudi Arabia, the UAE and other Gulf countries are using 5G and 5G-Advanced as components of national digital strategies. Latin America grows through continued 5G rollout in Brazil, Mexico and additional markets, although spectrum economics and operator capital constraints can slow the pace of physical deployment.
Technology Outlook
AI-Native RAN and Autonomous Networks
AI is moving from an external optimization tool toward part of the underlying network architecture. Nokia launched what it describes as its first commercial AI-native RAN platform in July 2026, combining Nokia anyRAN software with NVIDIA’s Aerial AI-RAN platform. The architecture is intended to improve spectral efficiency while enabling shared infrastructure for radio and AI workloads.
Cloud-Native Standalone Core and Network Slicing
5G SA is the architectural foundation for programmable connectivity. Operators increasingly deploy cloud-native cores alongside slicing, policy control and API exposure. The commercial significance is visible in the increase to 84 differentiated-connectivity offerings based on SA slicing by mid-2026.
5G-Advanced RAN and Transport
5G-Advanced extends the existing infrastructure cycle through wider carrier aggregation, enhanced uplink, AI-driven network management and higher-capacity transport. The technology allows operators to extract additional capability from existing spectrum and sites without waiting for 6G.
Recent Developments
July 2026: Nokia launched its commercial AI-native RAN platform, combining Nokia anyRAN software with NVIDIA Aerial AI-RAN infrastructure. The platform is intended to provide a migration path toward AI-native mobile networks while maintaining compatibility with Open RAN architectures.
June 2026: Ericsson expanded its Intelligent Automation Platform into 5G Core, creating a unified automation framework spanning RAN and core infrastructure and introducing core-specific automation applications.
June 2026: Nokia and Indosat Ooredoo Hutchison announced a nationwide network-modernization agreement in Indonesia involving low- and mid-band 5G RAN deployment and preparation for AI-RAN capabilities.
March 2026: Virgin Media O2 selected Ericsson and Nokia for major multi-year UK RAN modernization programs. Both agreements include advanced Massive MIMO and radio infrastructure, with the network evolving toward broader 5G SA, automation and 5G-Advanced capabilities.
March 2026: Ericsson and Nokia announced cooperation to improve interoperability between their respective Service Management and Orchestration and rApp ecosystems, supporting multivendor automation across purpose-built, Cloud RAN and Open RAN networks.
January 2026: Wind Tre and Ericsson switched on Italy’s first commercial 5G Standalone mobile network, using Ericsson’s cloud-native 5G Core and enabling network slicing and enterprise connectivity services.
Competitive Landscape
Huawei, Ericsson, Nokia, ZTE and Samsung remain the principal global suppliers of end-to-end or large-scale 5G RAN infrastructure. Huawei and ZTE hold particularly strong positions in China and several emerging markets, while Ericsson and Nokia have extensive positions across North America and Europe. Samsung Networks maintains an important role in the United States, South Korea, Japan and selected international Open RAN deployments.
The competitive environment is widening as infrastructure becomes more software-defined. Mavenir, Parallel Wireless, NEC and Fujitsu compete through Open RAN, virtualized RAN and private-network solutions. Rakuten Symphony provides cloud-native telecom infrastructure and automation derived from Rakuten Mobile’s network architecture.
Cisco, Hewlett Packard Enterprise, Oracle and Red Hat participate increasingly through core, transport, telco-cloud and orchestration layers rather than conventional macro radios. Ciena and Ribbon Communications provide high-capacity transport systems, while Comba Telecom and FiberHome retain important positions in radio, indoor coverage and optical infrastructure.
Analyst View
The global 5G infrastructure market remains attractive, but it should no longer be forecast as though every major country is still in the initial rollout phase. China’s enormous installed network fundamentally changes the global growth profile. With more than five million base stations already deployed, incremental spending increasingly shifts toward upgrades and software rather than maintaining the extraordinary physical rollout rates of the early 5G period.
India provides the strongest counterweight to this maturation. Its installed BTS count continues to rise rapidly, while subscriber adoption and fixed wireless usage increase traffic requirements. The U.S. and Europe provide another growth mechanism through SA cores, Open RAN, network modernization and private wireless rather than very large increases in national base-station counts.
The architecture of the market is therefore becoming more important than the headline number of sites. RAN remains the largest revenue pool, but core networks, edge infrastructure and orchestration software grow faster. By 2031, operators are purchasing a materially more programmable and software-intensive infrastructure stack than they were during the first commercial 5G deployments.
Private 5G also becomes strategically important despite remaining much smaller than public carrier networks. Industrial enterprises are beginning to procure cellular infrastructure directly or through managed-service providers, creating an additional demand base that is less dependent on consumer mobile ARPU.
The KSI expects the Chinese market to mature over the forecast period as the industry approaches early 6G commercialization, while faster-growing infrastructure categories such as private 5G, SA Core, edge infrastructure, AI-RAN, and network automation continue expanding well above the overall market rate.
5G Network Infrastructure Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 78.4 billion |
| Total Market Size in 2031 | USD 130.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Spectrum Band, Deployment Type, Deployment Mode |
| Companies |
|
Market Segmentation
By Component
· Radio Access Network
· 5G Core Network
· Transport & Backhaul Network
· Edge Infrastructure
· Network Management & Orchestration
· Others
By Spectrum Band
· Low-Band
· Mid-Band
· High-Band / mmWave
By Deployment Type
· Public Carrier Networks
· Private 5G Networks
· Shared Infrastructure
· Hybrid Networks
By Deployment Mode
· Standalone
· Non-Standalone
By End User
· Telecom Operators
· Manufacturing & Industrial Automation
· Transportation & Logistics
· Energy & Utilities
· Healthcare
· Public Sector
· Other Enterprises
By Geography
North America
· United States
· Canada
· Mexico
South America
· Brazil
· Argentina
· Others
Europe
· United Kingdom
· Germany
· France
· Italy
· Spain
· Others
Middle East and Africa
· Saudi Arabia
· UAE
· South Africa
· Others
Asia Pacific
· China
· India
· Japan
· South Korea
· Indonesia
· Thailand
· Taiwan
· Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Scope Exclusions
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. 5G Subscription and Traffic Outlook
3.5. Spectrum and Network Densification Analysis
3.6. Public vs. Private 5G Infrastructure Economics
3.7. Regulatory and Supply-Chain Environment
3.8. Porter’s Five Forces Analysis
3.9. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. AI-Native RAN and Autonomous Networks
4.2. Cloud-Native Standalone Core and Network Slicing
4.3. 5G-Advanced RAN and Transport
5. 5G NETWORK INFRASTRUCTURE MARKET BY COMPONENT
5.1. Introduction
5.2. Radio Access Network
5.3. 5G Core Network
5.4. Transport & Backhaul Network
5.5. Edge Infrastructure
5.6. Network Management & Orchestration
5.7. Others
6. 5G NETWORK INFRASTRUCTURE MARKET BY SPECTRUM BAND
6.1. Introduction
6.2. Low-Band
6.3. Mid-Band
6.4. High-Band / mmWave
7. 5G NETWORK INFRASTRUCTURE MARKET BY DEPLOYMENT TYPE
7.1. Public Carrier Networks
7.2. Private 5G Networks
7.3. Shared Infrastructure
7.4. Hybrid Networks
8. 5G NETWORK INFRASTRUCTURE MARKET BY DEPLOYMENT MODE
8.1. Standalone
8.2. Non-Standalone
9. 5G NETWORK INFRASTRUCTURE MARKET BY END USER
9.1. Telecom Operators
9.2. Manufacturing & Industrial Automation
9.3. Transportation & Logistics
9.4. Energy & Utilities
9.5. Healthcare
9.6. Public Sector
9.7. Other Enterprises
10. 5G NETWORK INFRASTRUCTURE MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.1.3. Mexico
10.2. South America
10.2.1. Brazil
10.2.2. Argentina
10.2.3. Others
10.3. Europe
10.3.1. United Kingdom
10.3.2. Germany
10.3.3. France
10.3.4. Italy
10.3.5. Spain
10.3.6. Others
10.4. Middle East and Africa
10.4.1. Saudi Arabia
10.4.2. UAE
10.4.3. South Africa
10.4.4. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. India
10.5.3. Japan
10.5.4. South Korea
10.5.5. Indonesia
10.5.6. Thailand
10.5.7. Taiwan
10.5.8. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Competitive Positioning
11.2. RAN and Core Capability Benchmarking
11.3. Open RAN, Cloud RAN and AI-RAN Analysis
11.4. Market Share Analysis
11.5. Strategic Partnerships and Developments
11.6. Competitive Dashboard
12. COMPANY PROFILES
12.1. Huawei Technologies Co., Ltd.
12.2. Telefonaktiebolaget LM Ericsson
12.3. Nokia Corporation
12.4. ZTE Corporation
12.5. Samsung Electronics Co., Ltd.
12.6. Mavenir Systems, Inc.
12.7. NEC Corporation
12.8. Fujitsu Limited
12.9. Rakuten Symphony
12.10. Parallel Wireless, Inc.
12.11. Comba Telecom Systems Holdings Limited
12.12. FiberHome Telecommunication Technologies Co., Ltd.
12.13. Cisco Systems, Inc.
12.14. Hewlett Packard Enterprise
12.15. Oracle Corporation
12.16. Ciena Corporation
12.17. Ribbon Communications Inc.
12.18. Airspan Networks Holdings Inc.
12.19. Red Hat, Inc.
12.20. Dell Technologies Inc.
13. ANALYST VIEW
14. APPENDIX
14.1. Research Methodology
14.2. Market Estimation and Assumptions
14.3. Scope and Double-Counting Controls
14.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











