
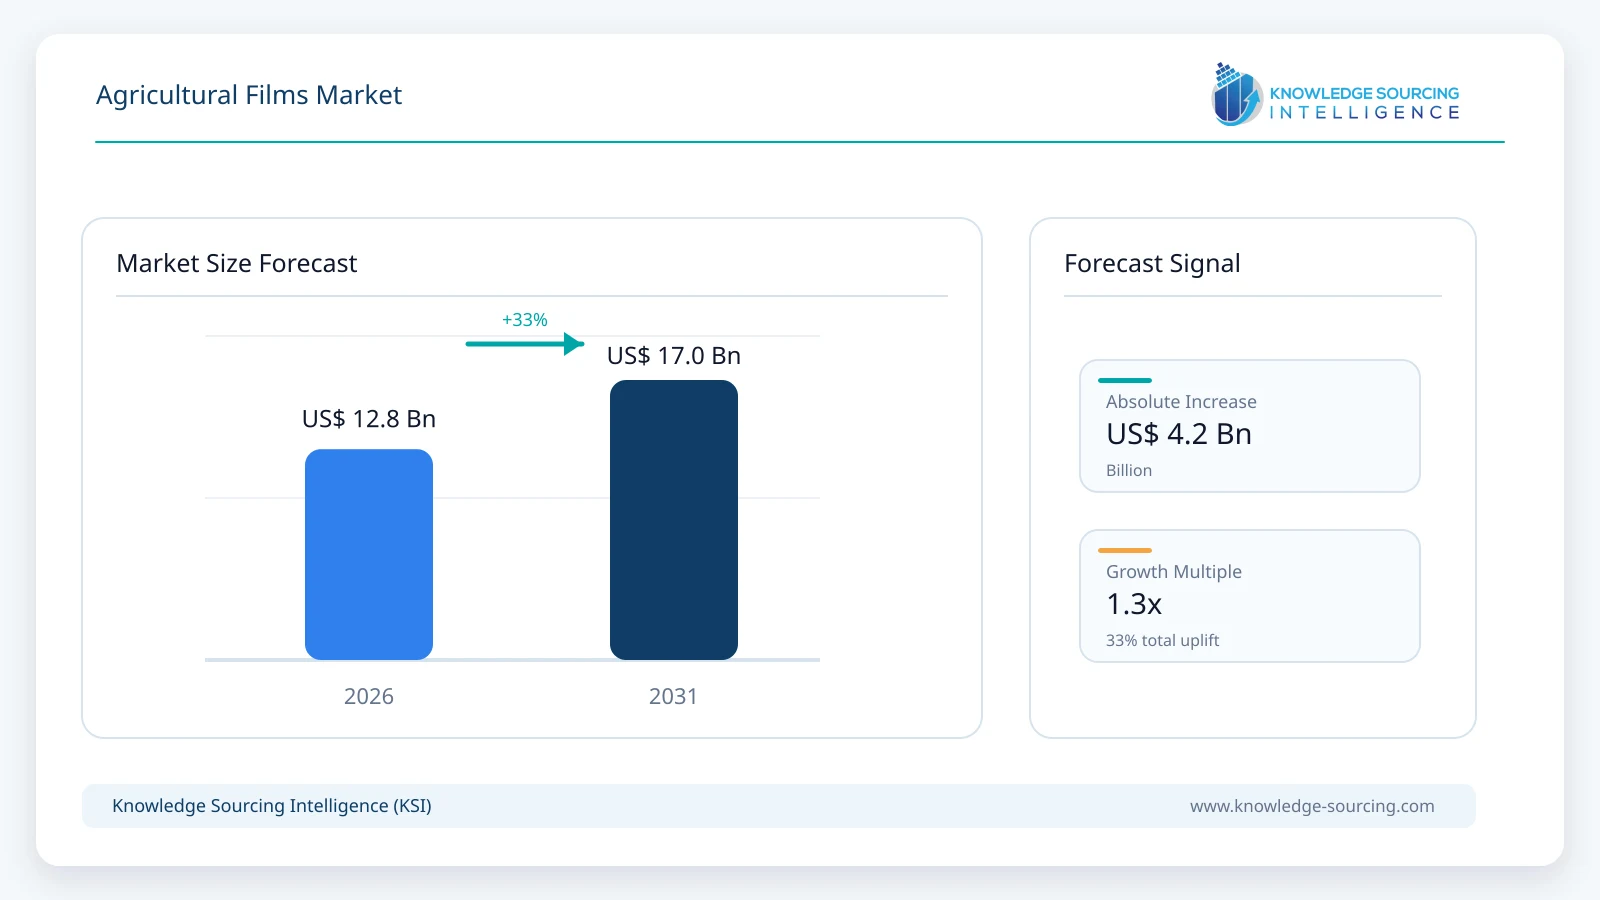
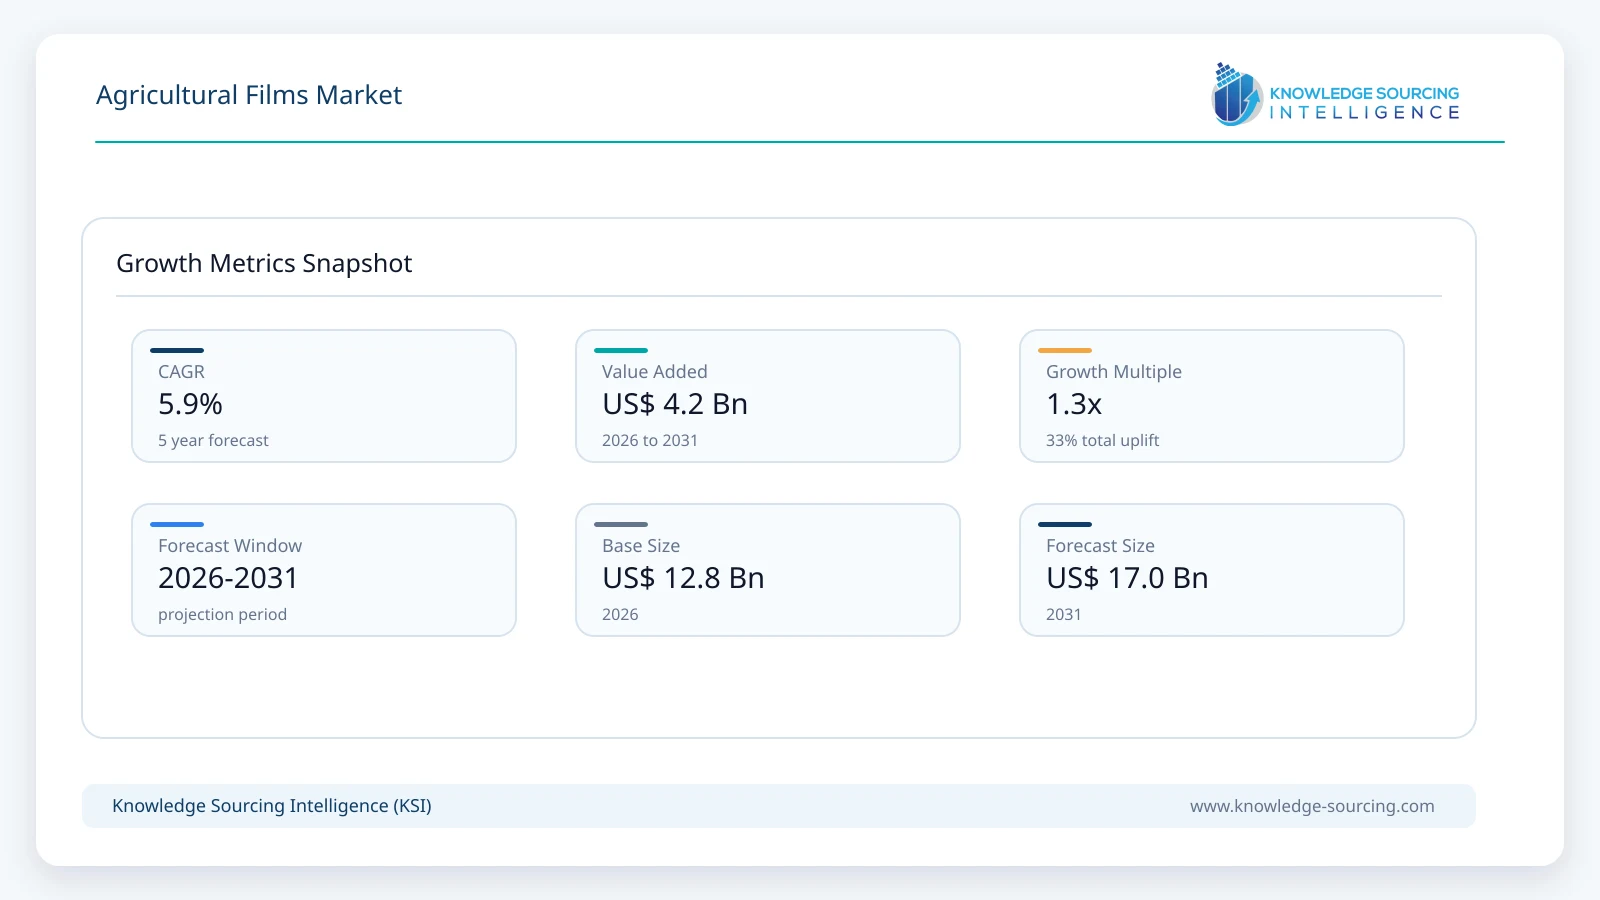
The Agricultural Films Market is expected to increase from approximately USD 12.8 billion in 2026 to USD 17.0 billion by 2031, representing an annual growth rate of about 5.9% over the five-year period.
Highlights:
- 1LDPE remains the largest named polymer family because it combines flexible processing, transparency and broad use in greenhouse coverings and farm films.
- 2Greenhouse films represent the largest application market, with mulching also contributing significant demand across open-field vegetables and fruit cultivation.
- 3Coextruded films with engineered UV performance, optical control and puncture strength are displacing undifferentiated specifications in demanding applications.
- 4Collection costs and contamination determine whether recycled content is commercially practical; silage wrap offers a clearer mechanical-recycling route than thin, soil-contaminated mulch.
- 5Soil-biodegradable mulch solutions face a different certification and price structure from conventional polyethylene, limiting direct substitution.
- 6Asia Pacific leads global demand; horticultural investment and water scarcity create particularly strong growth opportunities in Middle East and Africa.
This report covers film products sold for crop cultivation, protected horticulture and forage storage, including greenhouse covers, silage films and mulch films. The type classification follows the predominant polymer family in the film: low-density polyethylene (LDPE), high-density polyethylene (HDPE), linear low-density polyethylene (LLDPE), and other materials. The last category includes qualified biodegradable formulations and specialty polymer systems. Multilayer structures are attributed to one predominant type rather than counted separately under every polymer present.
Purchases are generated by farms, commercial growers, contract wrapping operators and horticultural distributors. The market excludes greenhouse frames, irrigation hardware, nets, tarpaulins unrelated to agriculture, crop protection chemicals and the separate turnover of upstream polymers already incorporated into converted films. Resins from BASF or other material suppliers influence film specifications and margin, but resin sales cannot be added to the invoiced film market a second time. Geography tracks the intended end market rather than the location of the polymer plant.
Market Overview
A greenhouse film can remain exposed to sunlight, sprayed chemicals and repeated seasonal temperature changes for several years. Its commercial performance depends on how the resin blend manages ultraviolet radiation, incoming photosynthetically active light and surface condensation over that service life. INDEVCO, for example, specifies tailored greenhouse covers with optical and UV-stabilization choices for different crops and climates. Film makers must therefore supply verified life expectancy and consistent optical behavior, not merely a competitive price per kilogram.
Silage uses a shorter but less forgiving operating window. Forage quality deteriorates when punctures, poor adhesion or deficient oxygen barriers expose stored crops to air. RKW has emphasized multilayer constructions and reduced handling in its Polydress silage range, while Amcor’s Silotite and Baletite products illustrate the move toward coordinated bale-binding and wrapping methods. The practical cost calculation includes wrapping time, dry-matter loss and the proportion of film that can be recovered after use. These operational considerations support a premium for dependable converted films even where raw-material prices are volatile.
Agricultural-film demand also attracts policy scrutiny because the waste stream is difficult to collect. The FAO estimated that plant and animal production used 12.5 million tonnes of plastic products in 2019, a figure that includes many items other than films. Removal and recycling are generally more manageable for bale wrap and robust greenhouse sheets than for thin mulch contaminated with soil. European biodegradation criteria and material certification consequently influence purchasing, but they do not amount to a global ban on polyethylene films. Regional cropping systems and disposal infrastructure remain decisive.
Market Trends
Optical Engineering Replaces Simple Thickness Comparisons
Productivity claims for greenhouse coverings are increasingly tied to light diffusion, heat retention and anti-drip performance. Highly transparent covers are not optimal for every crop: diffused light may improve distribution within a canopy, while thermal additives help manage overnight losses in colder production regions. A grower may accept a costlier film if fewer condensation droplets, better uniformity or an extended replacement interval offset the initial outlay. INDEVCO’s climate-specific greenhouse specifications demonstrate how converters compete on a combination of resin chemistry and local agronomic requirements.
The consequences for film suppliers are technical and commercial. Optical properties must survive weathering and exposure to agrochemicals; otherwise a favorable installation test may have little value after two growing seasons. Specialized coextrusion and formulation support make greenhouse film harder to substitute than standard sheet products. This places performance testing and distributor agronomy knowledge near the center of competitive differentiation.
Recovered Polyethylene Is Finding a Route Back into Forage Films
Bale wrapping produces a comparatively concentrated used-film stream, particularly where contractors or producer associations collect material at scale. Trioworld offers Loop bale wrap incorporating a minimum of 30% post-consumer recycled plastic from agricultural film. Its process is built around a controlled waste input because inconsistent recyclate can affect tack, stretchability and barrier performance. Coveris and Groupe Barbier also market silage-related products that use recycled content or integrate recovery-oriented design.
The economics are less convincing for thin mulch films containing large quantities of soil and vegetation. Washing, sorting and drying can absorb the value of the recovered polymer. Distinguishing the two waste streams matters: a circularity claim demonstrated in bale wrap should not be extrapolated to every agricultural film. Certification and traceability are becoming more important to buyers that want to substantiate recycled-content claims without accepting higher forage losses.
Certified Biodegradable Mulch Is Developing a Distinct Value Proposition
BASF’s ecovio M2351 is certified to EN 17033, while Novamont reported conformity of a MATER-BI mulch film with the relevant EU fertilising-product framework in November 2025. The two approaches address the cost and environmental burden of extracting low-gauge film after harvest. They compete where weed suppression and moisture conservation must be reconciled with the expense of collection, not in every application occupied by LDPE or LLDPE.
Certification is only part of the purchase decision. Growers must consider soil conditions, cultivation cycles, film functionality during the crop season and total applied cost. Materials meeting a biodegradation criterion can command higher initial prices and still be economical where labor for film retrieval is scarce. Conversely, long-lived greenhouse covers and recoverable silage film generally call for reuse or recycling rather than incorporation into soil.
Silage System Design Is Moving Beyond Standalone Film Rolls
Mechanized wrapping makes reel change frequency, consistent stretch and bale density visible expenses during peak harvest. Amcor’s Silotite Film&Film proposition pairs Baletite binding film with outer wrapping to improve barrel coverage and avoid an incompatible net layer in the recovered waste stream. RKW’s Polydress TWISTA integrates a vacuum film and silage cover for one-step deployment over clamp silos. Both examples concern the handling system around the film, not simply additive packages in the polymer.
These system improvements are meaningful where large forage volumes leave little time for repeated manual adjustments. Reliability during installation protects the feed inventory and reduces contractor downtime. Suppliers able to demonstrate fewer handling steps or lower waste rates can defend their position even during periods when customers scrutinize film prices closely.
Segment Analysis
By Type: Low-density Polyethylene
LDPE holds the leading position among the named film polymer types because its flexibility, transparency and established processing behavior suit many greenhouse and agricultural covering applications. Its role is especially evident in long-life coverings and flexible sheet products, where converters can adapt a familiar resin platform to local crop conditions. Manufacturers commonly modify the film using multilayer structures, ultraviolet stabilizers and optical additives; the finished product may also contain LLDPE or other components. The classification used here assigns a hybrid film to its principal resin, avoiding the false assumption that the polymer families are always used separately.
Growth is likely to be slower than that of some specialty structures as growers demand thinner yet stronger films. LLDPE has a particularly important role in stretch and puncture-resistant formulations, while HDPE contributes to applications requiring different stiffness and strength characteristics. Biodegradable materials sit within Other Types when they are not predominantly one of the specified polyethylene families. The relative mix will depend on resin pricing, local agronomic practice and environmental requirements.
By Application: Greenhouse
Greenhouse coverings are the largest application by value, as protected cultivation requires engineered films over substantial roof and sidewall areas. The film must transmit or diffuse useful light, withstand repeated climate and chemical exposure and remain serviceable through multiple crop cycles. In horticultural clusters, the financial consequence of replacing an underperforming cover can exceed the original film bill, favoring experienced suppliers with local test data and stable distribution.
Mulching ranks close behind, especially across open-field fruit and vegetable production where films limit weed pressure and moisture loss. Silage demand is shaped instead by livestock output, weather patterns and forage preservation methods. These applications do not share a uniform renewal cycle. Greenhouse covers may last years, thin mulch films can be replaced each crop, and silage wrap is purchased as the harvested forage is stored.
Market Drivers
Growth in Protected Horticulture
Greenhouse operators require coverings that allow close control of heat, light and moisture while limiting exposure to damaging weather. Expanding protected cultivation increases installed film area and demand for climate-specific grades rather than uniform general-purpose sheeting. The film is only a fraction of a greenhouse investment, but failure during the growing season can be costly. This creates demand for durable, tested products with documented service life. Supplier access to local horticultural distributors and crop-specific installation practices is particularly important in markets where operators are moving from low-cost tunnels to professional protected-growing structures.
Water and Weed Management in Field Crops
Vegetable and fruit growers use mulch to suppress competing weeds and reduce moisture evaporation from cultivated soil. The benefit becomes commercially important where irrigation water is expensive, rainfall is irregular or labor for repeated weed control is scarce. Film selection still varies by crop, soil temperature and harvest practice; black, reflective and biodegradable variants are not interchangeable. Demand therefore emerges from agronomic requirements rather than a simple increase in plastic use. Suppliers offering application guidance and appropriate gauge selection are better placed to protect volumes against competition from the cheapest film rolls.
Protection of High-Value Forage
A punctured silage bale can compromise feed quality long after the wrapping contractor leaves the field. Livestock operations consequently evaluate adhesion, gas barrier, mechanical strength and ultraviolet stability together. Multilayer silage films and film-based binding systems can reduce exposure to oxygen while making handling more predictable during harvest. RKW and Amcor compete in this performance-oriented portion of the market. The effect is most visible in dairy and intensive livestock systems, where the cost of feed losses and replacement fodder can outweigh a modest premium for dependable wrapping material.
Higher Film Productivity Through Coextrusion
Multilayer extrusion lets manufacturers place different mechanical and functional properties in separate portions of a film. A strong core may be combined with surfaces optimized for tack, light transmission or resistance to weathering, depending on the application. Thickness reduction is valuable only when puncture resistance, barrier integrity and operating life are preserved. Process control, resin compounding and quality testing therefore create commercial advantages for converters with advanced machinery. Customers gain fewer reel changes or a longer replacement interval, while suppliers may lower polymer consumption per usable hectare or bale without degrading field performance.
Targeted Support for Recoverable and Biodegradable Systems
Collection schemes for silage plastic and technical standards for soil-biodegradable mulch offer different routes to lower environmental burdens. Trioworld's bale-wrap products incorporating agricultural post-consumer material demonstrate that recovered polymer can return to a demanding film application when the feedstock is controlled. In Europe, the amended fertilising-product framework sets criteria for certain biodegradable mulch films. Neither approach automatically reduces cost, but both create opportunities where disposal expense, procurement requirements or environmental compliance are material to the buyer. Verified performance and certification support adoption more effectively than unqualified claims of sustainability.
Market Restraints
Uncertain Polyethylene and Additive Costs
Margins at film converters respond to changes in polyethylene prices, energy and freight. Many agricultural customers order seasonally and compare prices with locally available alternatives, limiting suppliers' ability to pass through short-term increases. Premium additives for ultraviolet resistance, anti-fog behavior or light diffusion further raise the cost of sophisticated grades. A film producer holding stock for peak installation periods can be exposed to unfavorable movements before orders are delivered. Local manufacturing and procurement flexibility help, but do not eliminate the effect of resin volatility on profitability and investment decisions.
Contaminated Waste and Weak Collection Infrastructure
Used mulch is often mixed with earth, roots and moisture. The resulting collection and washing expense can exceed the value of the recovered polymer, especially where film is thin and farms are dispersed. Forage wrapping is easier to aggregate, but recycling still depends on sorting, local take-back programs and access to suitable processors. Without those conditions, films advertised as recyclable may be buried, burned or discarded. The absence of dependable recovery systems increases pressure on the industry and can discourage growers from using products that leave a difficult waste stream after harvest.
Trade-Offs Between Thin Gauge and Field Reliability
Lowering film thickness reduces polymer consumption and transport weight, but excessive down-gauging increases tearing or premature failure. In silage, punctures admit oxygen; in greenhouses, damaged sheets can alter temperature, moisture and light conditions for a crop. These consequences are far more expensive than the material saved on an individual roll. Producers need to validate mechanical strength under realistic installation, wind and agrochemical exposure. Small farms may lack the equipment and training needed to install thin high-performance film consistently, limiting the practical addressable market for aggressive downgauging.
Cost and Application Limits of Biodegradable Alternatives
Certified soil-biodegradable films can eliminate a film-removal step, but they may carry higher initial prices than conventional polyethylene. They also need to retain their function for the intended crop cycle and degrade in the relevant environmental conditions afterward. Growers must understand that EN 17033 certification and other regulatory conformity statements have defined test scopes; they do not make every film suitable for every climate or application. Longer-lived greenhouse covers and silage films cannot simply adopt a mulch formulation. Adoption will therefore remain selective where the full economics and technical conditions are favorable.
Fragmented Farming Practices and Distribution
Agricultural-film specifications are strongly localized. Sun intensity, growing season, crop mix, harvesting methods and film collection obligations differ markedly between regions. A grade proven in one horticultural cluster may require reformulation or different stabilization elsewhere. Smallholder customers often buy through distributors that prioritize price, immediate availability and familiarity over specialized technical advantages. This fragmentation raises the cost of field trials, inventory and customer support. Suppliers without dependable regional channels may struggle to convert technical products into recurring volumes even when laboratory test results are strong.
Regional Outlook
Asia Pacific
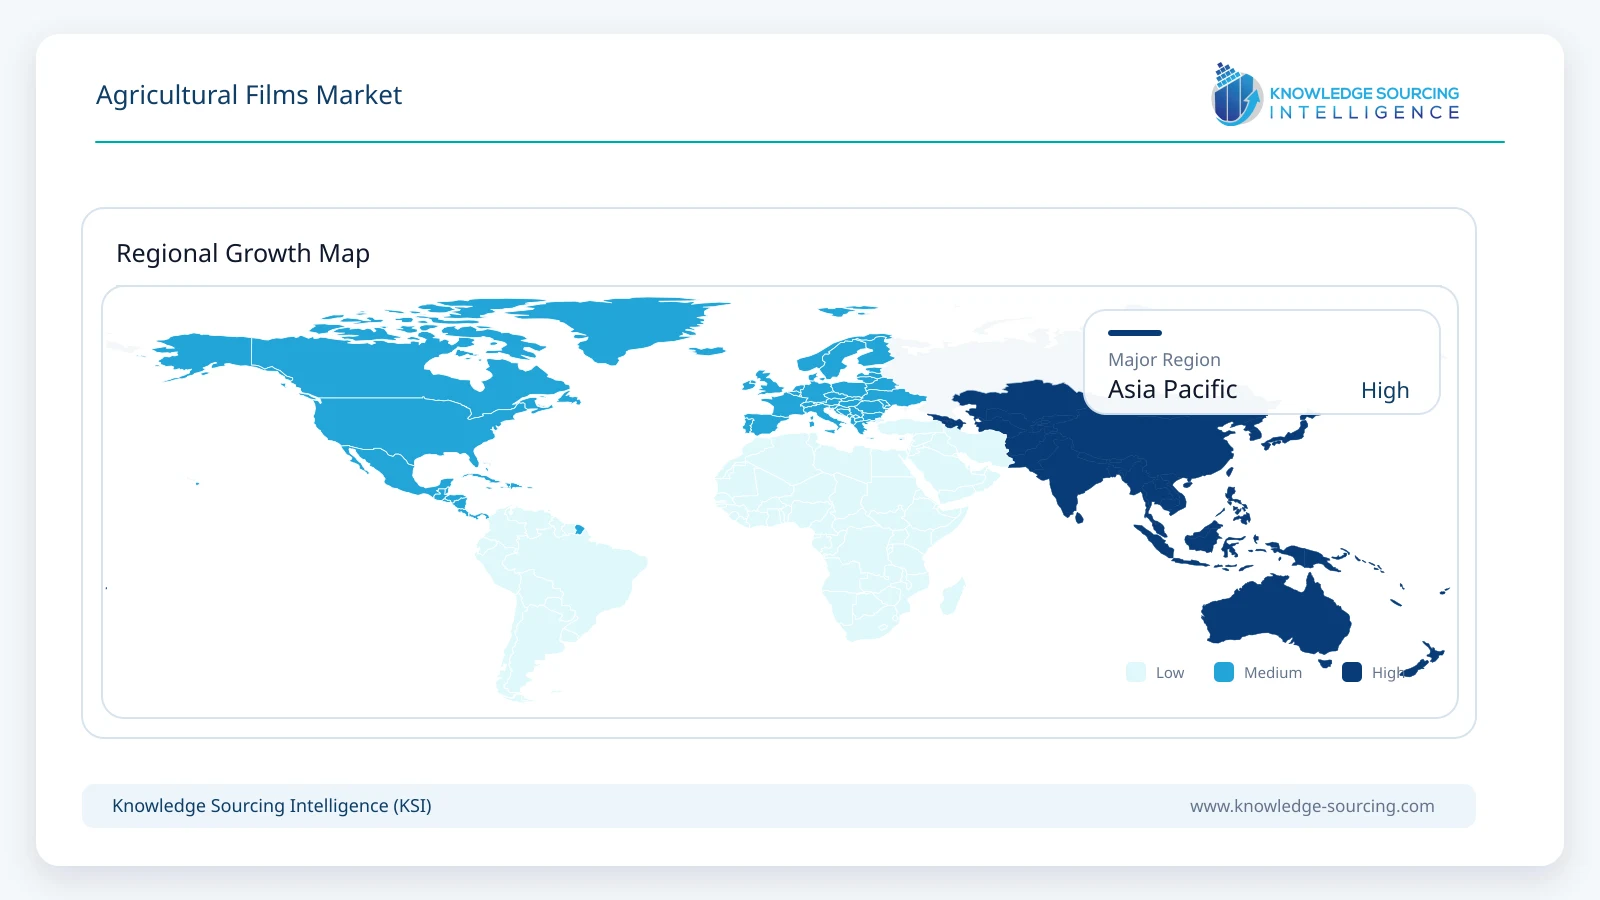
Asia Pacific holds the leading regional position, supported by large-scale plasticulture in China and India alongside advanced protected-growing economies. Demand differs considerably within the region. Vegetable cultivation and mulching support frequent purchases of relatively thin films, whereas technically advanced greenhouse operations require optical and long-life coverings. Large-scale use does not guarantee equivalent supplier margins: fragmented distribution and strong price competition can favor local converters. Purchasers in high-value horticulture are more likely to justify optical additives, documented UV resistance and durable multilayer structures.
China and India are substantial demand centers, although their crop mixes and levels of protected cultivation differ. International companies face competition from domestic film extruders capable of meeting local specifications. Regional growth will be determined as much by farm investment, crop economics and water availability as by underlying agricultural production. Recovery systems remain uneven, particularly for used mulch.
Middle East and Africa
Middle East and Africa offers the fastest relative growth opportunity, albeit from a considerably smaller base. In water-constrained horticultural markets, greenhouse film is purchased as part of a managed production environment rather than a stand-alone sheet. Operators need reliable thermal and optical properties under intense irradiation, dust and large day-night temperature changes. A premium film can be justified when it supports crop yields or reduces unscheduled replacement, although high project capital costs and imported material prices complicate purchasing.
Saudi Arabia, the United Arab Emirates and other regional protected-cultivation markets provide identifiable opportunities, while extensive agricultural systems elsewhere follow different film economics. Competition depends on local installation partners, distribution quality and proven resistance to demanding field conditions. Protected horticulture should gradually lift regional demand, although investment cycles and imported equipment costs may create considerable year-to-year variation.
Competitive Landscape
The market includes globally scaled film converters and locally strong agricultural specialists. RKW and Trioworld are notable in forage conservation; Coveris and Groupe Barbier offer silage-related protection, while PLASTIKA KRITIS, Ginegar and INDEVCO compete in protected cultivation. Amcor now carries the former Berry Global agricultural-film offerings following the companies’ April 2025 combination. Reporting Berry as an unrelated competitor would double-count the corporate footprint. Similarly, the historic Trioplast name has been superseded by Trioworld, although its agricultural brands remain familiar to distributors.
Resin providers must be distinguished from converted-film suppliers. BASF develops film-specific additives and ecovio compounds; Novamont, owned by Versalis, supplies MATER-BI biodegradable materials and corresponding mulch solutions. Their technical influence is substantial, particularly where certification shapes product selection, but it does not mean their upstream polymer revenue can be included in film-converter turnover. Competitive success is determined by product suitability, consistency from reel to reel, agricultural field support, local capacity and credible treatment of used film.
Geographic coverage creates another dividing line. A manufacturer that sells a qualified long-life greenhouse film into a horticultural cluster benefits from recurring distributor relationships, installation expertise and warranty confidence. Bale-wrap suppliers, by contrast, must serve time-critical harvest windows and machinery-specific wrapping needs. Producers targeting low-cost commodity film face weaker differentiation and greater exposure to resin prices. These distinct buying conditions make global share comparisons difficult without a consistently defined underlying revenue base.
Recent Developments
July 2026: Trioworld secured RecyClass recycled-content certification for three stretch-film products at its Ajax plant in Canada, strengthening verified circular-film expertise across the wider business.
April 2026: Trioworld published its 2025 sustainability report, describing advances in material circularity and operations across its film portfolio, which includes agriculture and horticulture products.
November 2025: Novamont announced EU fertilising-product conformity for a MATER-BI soil-biodegradable mulch film under Regulation 2019/1009 and Delegated Regulation 2024/2787.
May 2025: Trioworld opened a high-performance recycled-content stretch-film line in Apeldoorn, Netherlands, extending the organization-wide film-processing and recycled-polymer capabilities.
April 2025: Amcor completed its combination with Berry Global, consolidating agricultural film brands including Silotite within the Amcor group.
February 2025: BASF expanded its compostable horticultural component range and identified its EN 17033-certified ecovio M2351 mulch-film compound as an existing agricultural application.
Market Outlook
Agricultural films will remain an established component of intensive crop and forage production, but demand is likely to shift toward products whose value can be demonstrated in field performance. The most attractive greenhouse grades will be supported by evidence of optical behavior and replacement life; silage systems will be judged on handling time, puncture resistance and feed conservation. These criteria support specialist film converters and credible agricultural distribution networks, while limiting differentiation for suppliers competing only through polyethylene price.
End-of-life requirements will produce more than one technology pathway. Clean, collected forage films are suitable candidates for mechanical recycling and incorporation of recovered polymer. Thin mulch often presents weaker recycling economics and a more relevant role for certified biodegradable materials where agronomic conditions permit. Suppliers that can match the appropriate solution to crop, service life and waste infrastructure should be better positioned than companies promoting a universal replacement material. The pace of adoption will remain regionally uneven, with Asia Pacific driving scale and protected cultivation supporting faster growth in selected water-stressed markets.
Agricultural Films Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 12.8 billion |
| Total Market Size in 2031 | USD 17.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Low-Density Polyethylene
High-Density Polyethylene
Linear Low-Density Polyethylene
Other Types
By Application
Silage
Greenhouse
Mulching
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. AGRICULTURAL FILMS MARKET BY TYPE
5.1. Introduction
5.2. Low-density polyethylene
5.3. High-density polyethylene
5.4. Linear low-density polyethylene
5.5. Other Types
6. AGRICULTURAL FILMS MARKET BY APPLICATION
6.1. Introduction
6.2. Silage
6.3. Greenhouse
6.4. Mulching
6.5. Others
7. AGRICULTURAL FILMS MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. RKW Group
9.2. Trioworld Group
9.3. Amcor plc
9.4. Coveris
9.5. Groupe Barbier
9.6. Armando Alvarez Group
9.7. PLASTIKA KRITIS S.A.
9.8. Ab Rani Plast Oy
9.9. Ginegar Plastic Products Ltd.
9.10. INDEVCO Group
9.11. BASF SE
9.12. Novamont S.p.A.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for the Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size for agricultural films by 2031?
The Agricultural Films Market is projected to reach USD 17.0 billion by 2031.
What is the estimated CAGR for the Agricultural Films Market (2026-2031)?
The Agricultural Films Market is expected to grow at approximately 5.9% CAGR.
Which polymer type dominates the Agricultural Films Market?
LDPE remains the largest named polymer family.
What is the largest application segment for agricultural films?
Greenhouse films represent the largest application market.
Which region leads global demand for agricultural films?
Asia Pacific leads global demand.
Which regions present strong growth opportunities?
Middle East and Africa show strong growth opportunities.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Agricultural Films Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/agricultural-films-market