
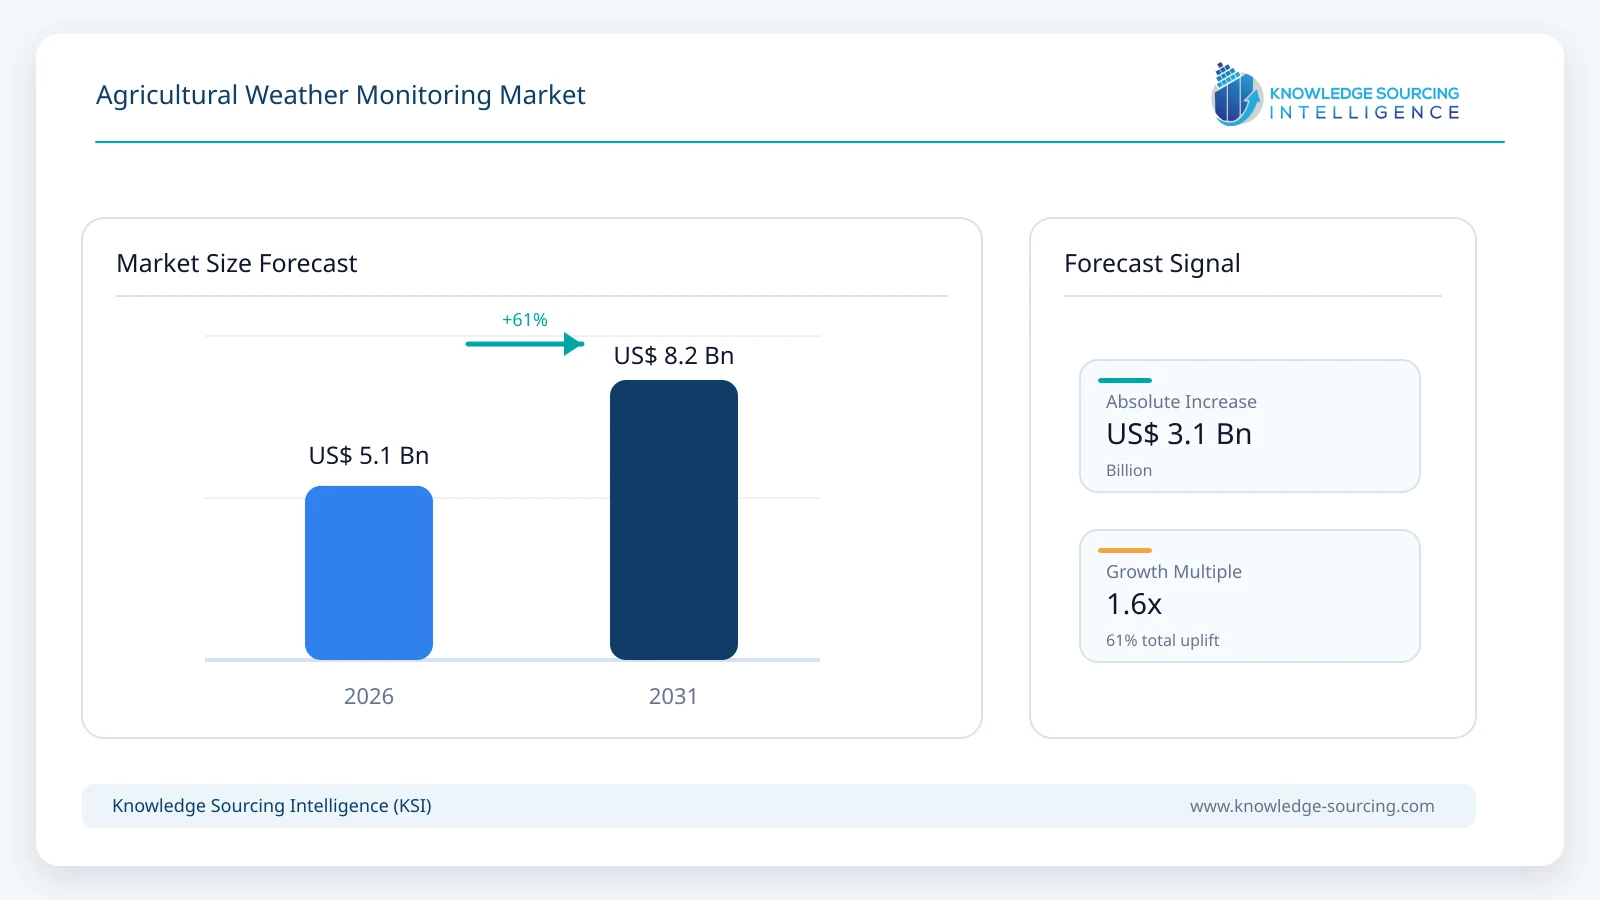
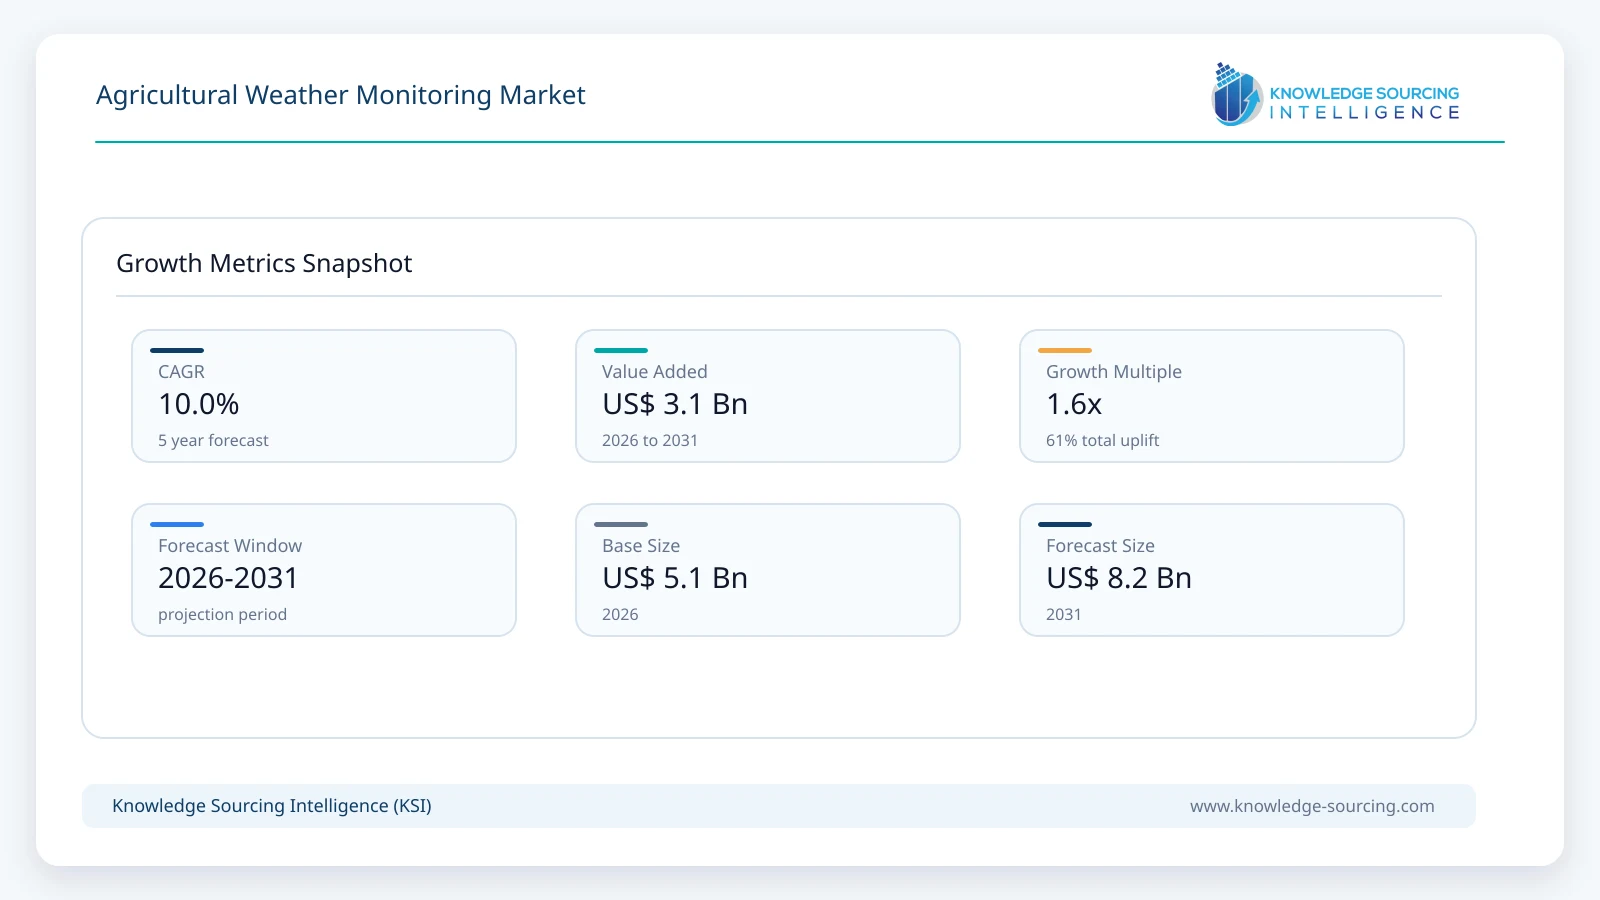
The global agricultural weather monitoring market is estimated at USD 5.1 billion in 2026 and is projected to reach USD 8.2 billion by 2031, growing at a CAGR of approximately 10.0% during the forecast period.
Highlights:
- 1Soil moisture and temperature monitoring account for approximately 32% of global market value in 2026.
- 2Hardware generates about USD 3.16 billion of agricultural weather monitoring revenue in 2026.
- 3Irrigation-management applications are projected to grow at approximately 11.7% annually through 2031.
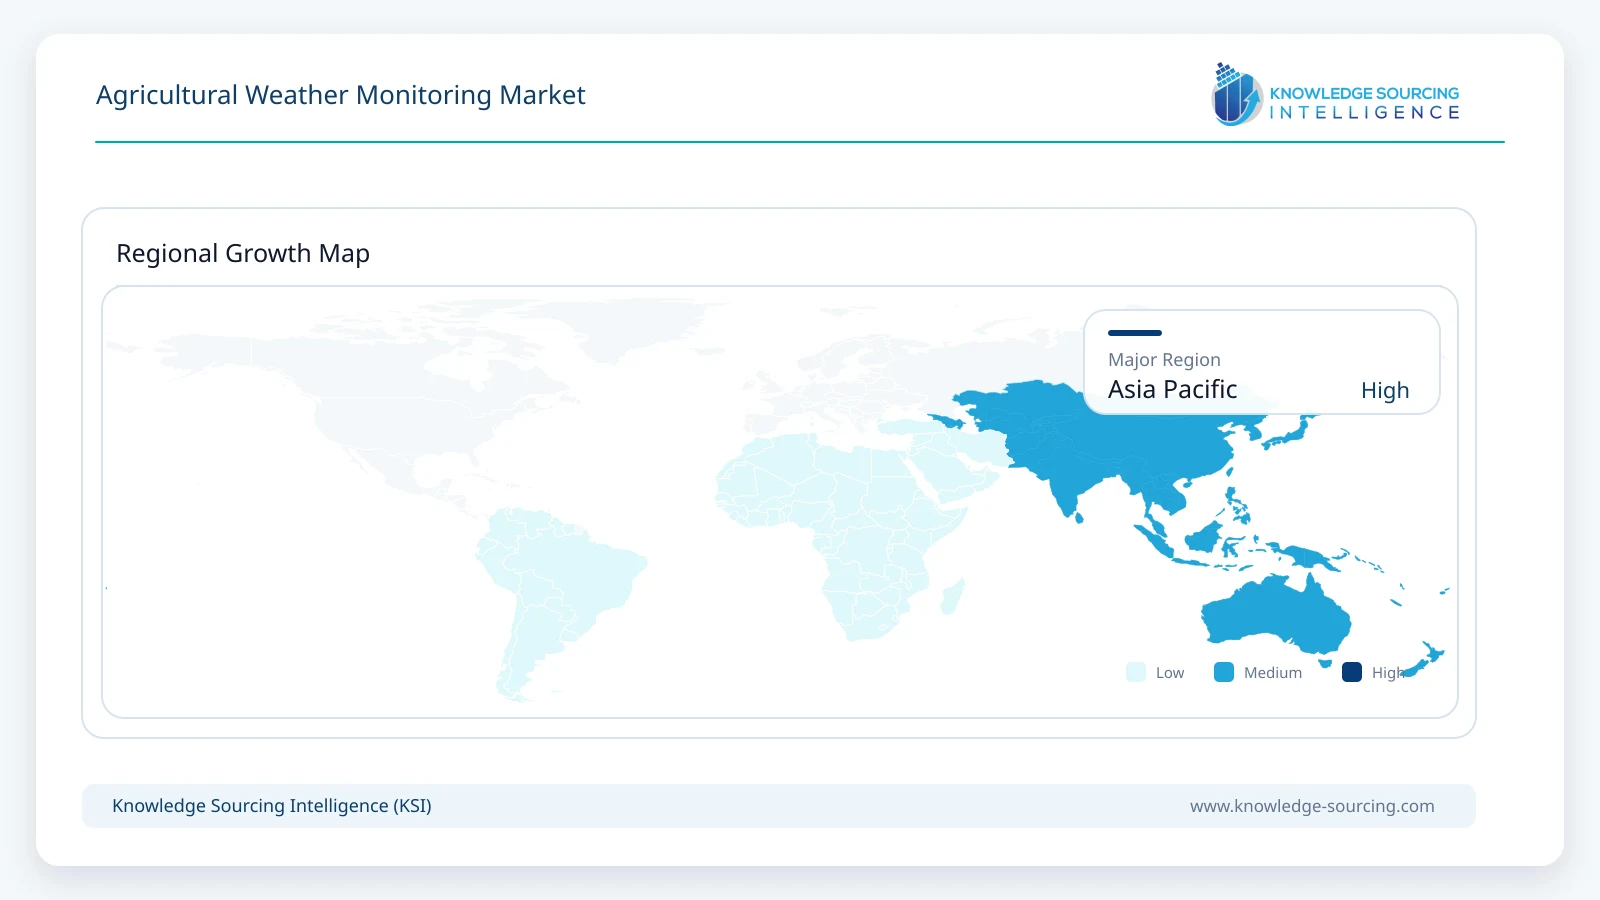
- 4Asia Pacific represents roughly 34% of global agricultural weather monitoring value in 2026.
- 5Connected weather stations are increasingly integrated with crop, irrigation and disease-management decision tools.
- 6Satellite soil-moisture data are expanding the monitoring layer beyond individual field weather stations.
Agricultural weather monitoring systems collect farm-specific environmental data including rainfall, air temperature, humidity, wind, solar radiation, leaf wetness and soil moisture or temperature. These measurements support operational decisions that are sensitive to local conditions, including when to irrigate, spray, protect against frost, harvest and schedule field work. Modern systems usually combine in-field sensors with cellular, Wi-Fi or low-power wireless connectivity and cloud-based visualization. The market therefore includes weather-station hardware, auxiliary soil and crop sensors, gateways, software and analytics subscriptions, and related installation or support services.
Product design is moving toward lower-maintenance, integrated systems. METER Group's ATMOS 41 Gen 2 packages 12 weather variables into a compact station, Campbell Scientific supports configurable research-grade agricultural weather networks, and Davis EnviroMonitor can connect a broad range of third-party sensors through field nodes. Pessl's METOS platform links station data with forecasts, disease models and satellite information, while Arable and xFarm combine field weather observations with crop-water and agronomic decision support. These architectures increase the economic value of weather monitoring because the measured variable is connected directly to an operational action.
Market Trends
Weather stations are becoming part of broader crop-intelligence platforms
The fastest change in the market is the integration of weather monitoring with soil, irrigation, crop-development and disease-risk data. Arable Mark 3 combines meteorological measurements with crop imagery, evapotranspiration, plant stress and optional soil or irrigation sensing. Davis EnviroMonitor places weather, soil moisture, frost, pest and irrigation information within one agricultural monitoring environment, while xFarm links xSense weather measurements with irrigation and crop-protection modules. Pessl Instruments follows a similar model through FieldClimate, which combines field measurements with weather forecasts, disease models and satellite services. This reduces the importance of the weather station as an isolated hardware purchase and increases recurring software and analytics revenue.
Satellite observations are being fused with ground measurements
Satellite-derived soil moisture, crop condition and rainfall information are becoming more useful alongside ground weather stations. NASA's NISAR mission entered science operations after its July 2025 launch and released provisional data during 2026; its soil-moisture products are designed to provide high-resolution measurements over much of the globe. NASA and USDA already use assimilated satellite soil-moisture observations to improve agricultural monitoring in areas where ground precipitation networks are sparse. Satellite products do not replace field stations because local rainfall, leaf wetness, wind and crop microclimates still require ground measurement, but they extend coverage and help agricultural networks identify spatial variability between monitored sites.
Market Drivers
Irrigation efficiency and weather variability are increasing demand for field-level measurements
Farm irrigation decisions depend on highly localized rainfall, evapotranspiration, temperature and root-zone moisture conditions. General weather forecasts can identify regional patterns, but they often do not capture the microclimate differences that determine whether an individual block requires irrigation. Davis, WiseConn, xFarm, Arable and METOS all connect weather observations with soil or irrigation information for this reason. As water availability becomes more constrained and pumping costs rise, growers have a stronger financial incentive to measure conditions before irrigating. This supports adoption in vineyards, orchards, specialty crops and irrigated field crops where the cost of overwatering or water stress can materially affect yield and quality.
Disease, frost and spray-risk models are converting weather data into direct farm decisions
Weather monitoring creates more value when measurements trigger an action. Leaf wetness, humidity and temperature can feed disease-risk models, wind data can identify safer spraying windows, and wet-bulb or minimum-temperature measurements support frost protection. Campbell Scientific agricultural systems are used for disease modeling and pesticide timing, Davis Mobilize includes frost and pest-management functions, and METOS combines field weather data with disease models and spray-window tools. This shift from observation toward decision support raises willingness to pay for software, alerts and agronomic subscriptions because the system can reduce crop losses, unnecessary applications and labor rather than simply record environmental conditions.
Market Restraint
Sensor maintenance, connectivity and uncertain farm-level returns can limit deployment density
Weather monitoring networks still face practical adoption barriers. Sensors require correct siting, calibration, cleaning and periodic maintenance, while cellular or wireless connectivity can be unreliable in remote agricultural areas. Poor installation can produce misleading rainfall, wind or temperature data, undermining confidence in the entire platform. Smaller farms may also struggle to justify multiple stations where crop value is low or weather risk is limited. Vendors are addressing these barriers through solar power, all-in-one sensors, low-maintenance designs and integrated telemetry, but the economics of dense field-level monitoring remain strongest in high-value crops, irrigated operations and large farms where one better-timed decision can offset the system cost.
Agricultural Weather Monitoring Market Segment Analysis
By Technology
Soil Moisture and Temperature
Soil moisture and temperature monitoring is projected to reach approximately USD 2.79 billion by 2031. The segment is commercially important because weather observations become more actionable when growers can see how rainfall and irrigation affect water availability in the root zone. Soil data support irrigation scheduling, detect overwatering or water stress and help interpret evapotranspiration estimates. Most major agricultural monitoring platforms therefore connect weather stations with soil probes rather than treating the two systems separately. The segment also benefits from greater sensor durability and wireless connectivity, allowing multiple depths or zones to be monitored across one farm.
By Component
Hardware
Hardware is projected to account for approximately 56% of market value by 2031. Weather stations, rain gauges, anemometers, temperature and humidity probes, soil sensors, solar-radiation sensors, gateways and data loggers remain the largest part of the installed system cost. Hardware share declines gradually as software subscriptions, agronomic models, APIs and analytics expand faster, but physical measurement remains essential because local weather and soil conditions cannot be inferred reliably from regional forecasts alone. Suppliers that combine durable sensors with cloud connectivity are therefore positioned to participate in both equipment and recurring software revenue.
By Application
Irrigation Management
Irrigation management is projected to generate approximately USD 3.20 billion in market revenue by 2031. This application combines weather, rainfall, evapotranspiration and soil-moisture data to determine when and how much water should be applied. The economic case is strongest where water, energy or labor costs are high and in crops where short periods of water stress can reduce quality. WiseConn directly integrates weather-station data into automated irrigation scheduling, while Davis, xFarm, METOS and Arable provide related crop-water tools. Crop protection and disease management represent another large application because humidity, leaf wetness, wind and temperature strongly influence spray timing and pathogen risk.
By Geography
Asia Pacific
Asia Pacific is projected to expand at approximately 11.2% annually between 2026 and 2031. The region combines very large agricultural areas with growing use of precision irrigation, protected cultivation and digital farm-management systems. China, India, Japan, Australia and Southeast Asia present different adoption patterns, but localized weather and soil monitoring are increasingly relevant in high-value horticulture, irrigated crops and commercial plantations.
Government and research networks also support deployment by creating regional weather data infrastructure. North America remains a mature high-value market with strong use of precision agriculture, while Europe benefits from intensive horticulture, vineyards and regulatory pressure to improve water and pesticide efficiency.
Competitive Environment
The market includes agricultural technology specialists, environmental-instrumentation companies and digital farm-platform providers. Pessl Instruments, Davis Instruments, Arable, Campbell Scientific and METER Group compete directly in field weather and environmental measurement, while xFarm Technologies, WiseConn and CropX integrate weather data within broader farm-management or irrigation platforms. Vaisala, AEM and OTT HydroMet contribute professional meteorological sensing and network capabilities, and companies such as Spectrum Technologies, Delta-T Devices, Sencrop and Aeron Systems address farm-scale monitoring niches.
Competitive advantage depends on sensor reliability, installation simplicity, connectivity, battery or solar performance, cloud software and the ability to turn measurements into decisions. Open sensor architectures can be attractive to large farms and research networks because users can combine weather stations with third-party soil, flow or crop sensors. Platforms with disease models, irrigation scheduling, mobile alerts and API integration can generate recurring software revenue and improve customer retention. The market is therefore moving toward connected ecosystems rather than one-time sales of standalone weather instruments.
Recent Developments
July 2026: Pessl Instruments and 1NCE announced connectivity collaboration to support METOS smart-farming deployments across international markets.
July 2026: Pessl Instruments and Environet integrated METOS weather-station data into the OneSoil platform for combined field monitoring and agronomic analysis.
July 2026: NASA released provisional NISAR data products, expanding access to radar observations that support crop and soil-moisture monitoring.
March 2026: Davis Instruments highlighted expanded EnviroMonitor sensor flexibility for farmers, combining weather stations, field nodes and third-party sensors within one cloud-connected system.
2026: METER Group continued commercial deployment of the ATMOS 41 Gen 2 all-in-one weather station for crop-weather and distributed environmental monitoring.
Agricultural Weather Monitoring Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.1 billion |
| Total Market Size in 2031 | USD 8.2 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Component , Application, Geography |
| Companies |
|
Market Segmentation
By Technology
Rain Gauge
Wind Speed
Wind Direction
Air Temperature and Humidity
Soil Moisture and Temperature
Solar Radiation and Evapotranspiration
Others
By Component
Hardware
Software and Analytics
Services
By Application
Irrigation Management
Crop Protection and Disease Management
Frost and Heat-Risk Management
Harvest and Field Operations
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
France
Germany
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Indonesia
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Irrigation Efficiency and Weather Variability Are Increasing Demand for Field-Level Measurements
3.1.2. Disease, Frost and Spray-Risk Models Are Converting Weather Data into Direct Farm Decisions
3.2. Market Restraint
3.2.1. Sensor Maintenance, Connectivity and Uncertain Farm-Level Returns Can Limit Deployment Density
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Connected Automatic Weather Stations
4.2. Soil and Crop Sensor Integration
4.3. Satellite and Ground-Data Fusion
4.4. AI and Agronomic Decision Models
5. AGRICULTURAL WEATHER MONITORING MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Rain Gauge
5.3. Wind Speed
5.4. Wind Direction
5.5. Air Temperature and Humidity
5.6. Soil Moisture and Temperature
5.7. Solar Radiation and Evapotranspiration
5.8. Others
6. AGRICULTURAL WEATHER MONITORING MARKET BY COMPONENT
6.1. Introduction
6.2. Hardware
6.3. Software and Analytics
6.4. Services
7. AGRICULTURAL WEATHER MONITORING MARKET BY APPLICATION
7.1. Introduction
7.2. Irrigation Management
7.3. Crop Protection and Disease Management
7.4. Frost and Heat-Risk Management
7.5. Harvest and Field Operations
7.6. Others
8. AGRICULTURAL WEATHER MONITORING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. France
8.4.3. Germany
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Israel
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. India
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Thailand
8.6.7. Indonesia
8.6.8. Australia
8.6.9. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Pessl Instruments GmbH
10.2. Davis Instruments
10.3. Arable Labs, Inc.
10.4. Campbell Scientific, Inc.
10.5. METER Group, Inc.
10.6. Vaisala Oyj
10.7. AEM
10.8. OTT HydroMet
10.9. xFarm Technologies
10.10. WiseConn
10.11. CropX Technologies
10.12. Spectrum Technologies, Inc.
10.13. Delta-T Devices Ltd.
10.14. Sencrop / ISAGRI
10.15. Aeron Systems Pvt. Ltd.
10.16. Climavision
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











