
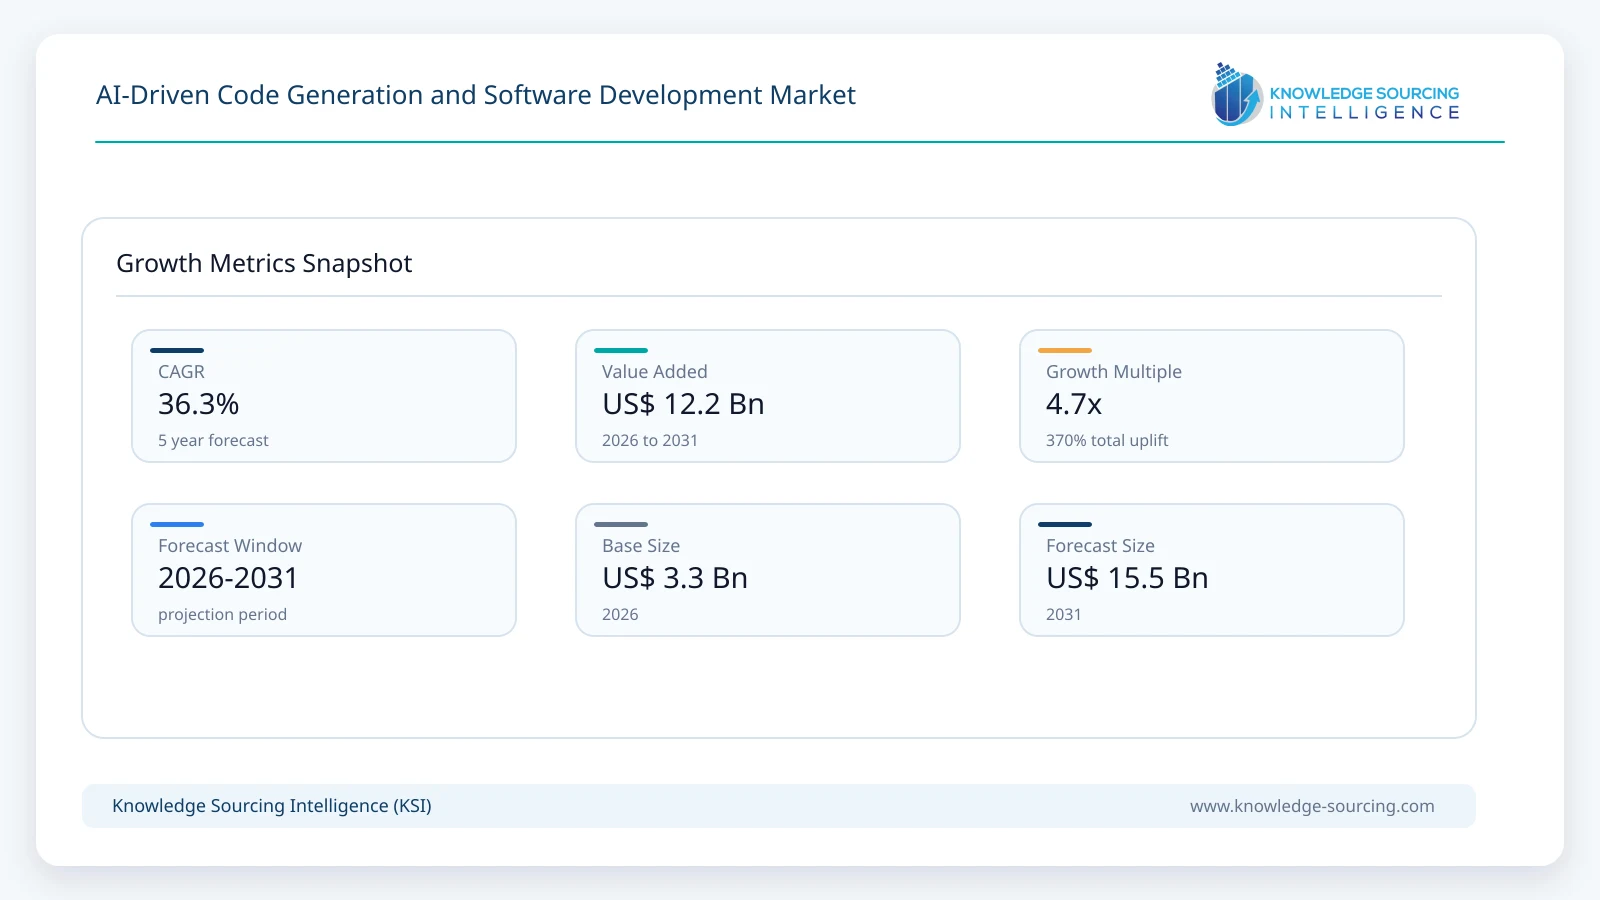
The global AI-Driven Code Generation and Software Development Market is expected to expand at approximately 36.3% annually, reaching USD 15.50 billion in 2031 from USD 3.30 billion in 2026.
Highlights:
- 1AI agents represent an estimated 20% of 2026 market value, with stronger growth expected as firms purchase supervised repository-level execution.
- 2Code generation accounts for an estimated 43% of 2026 spending under the application classification, although testing and review functions are gaining budget.
- 3Enterprise procurement increasingly tests whether coding agents respect repository permissions, approval workflows and software supply-chain policies.
- 4Consumption-based pricing is changing cost comparisons as a long-running code agent can use substantially more inference than an editor suggestion.
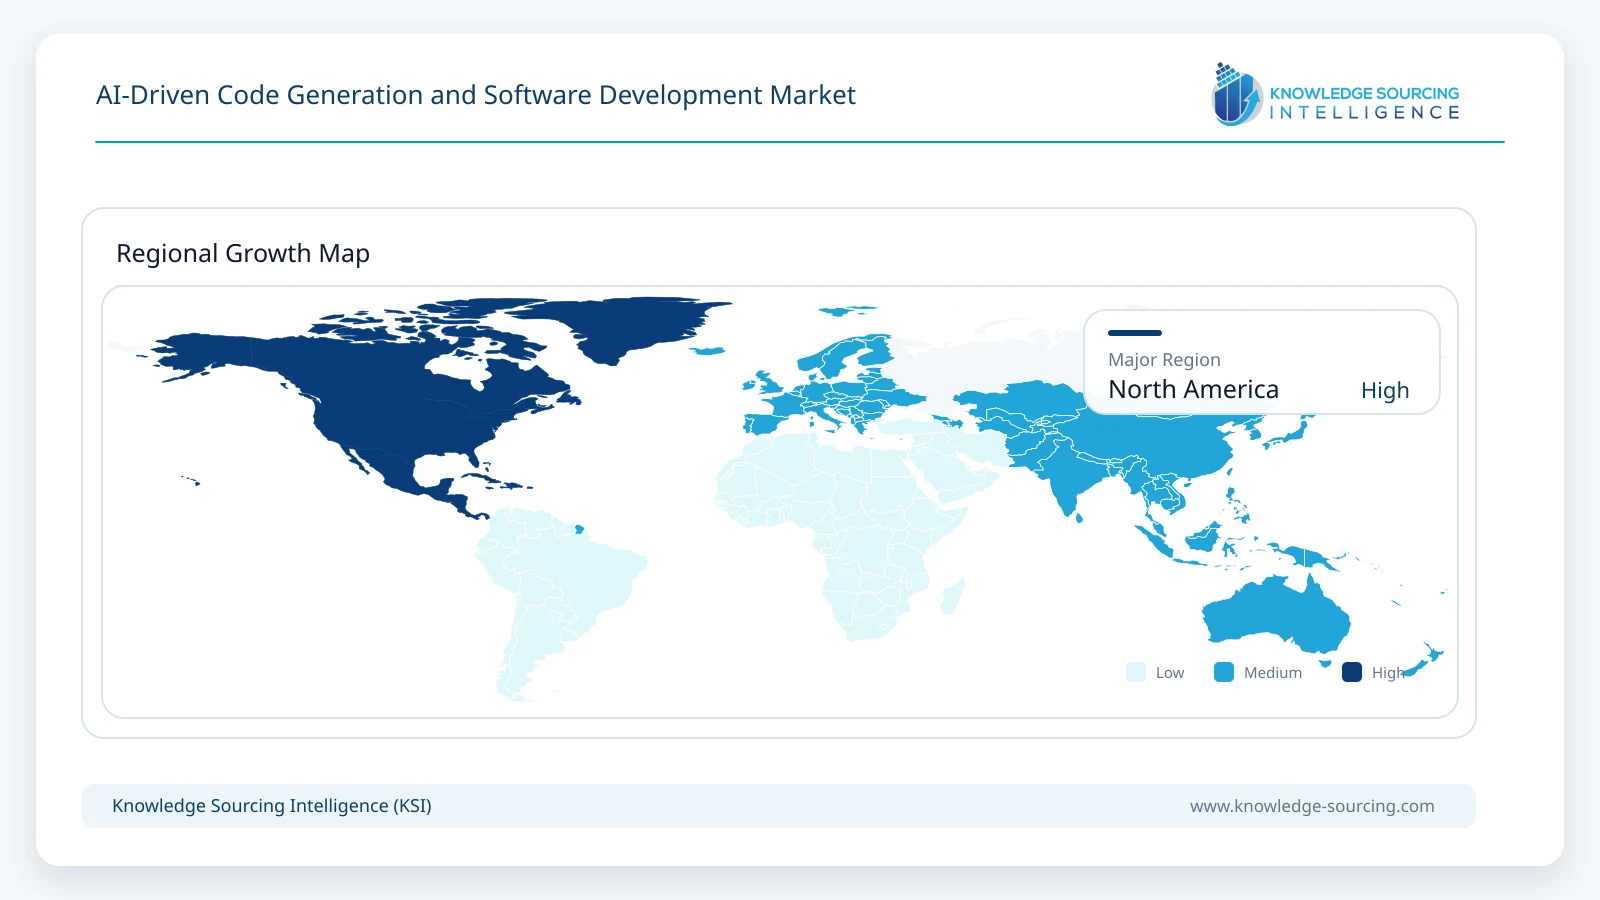
- 5North America has the largest current commercial buying base, while Asia Pacific is expected to increase its revenue contribution through 2031.
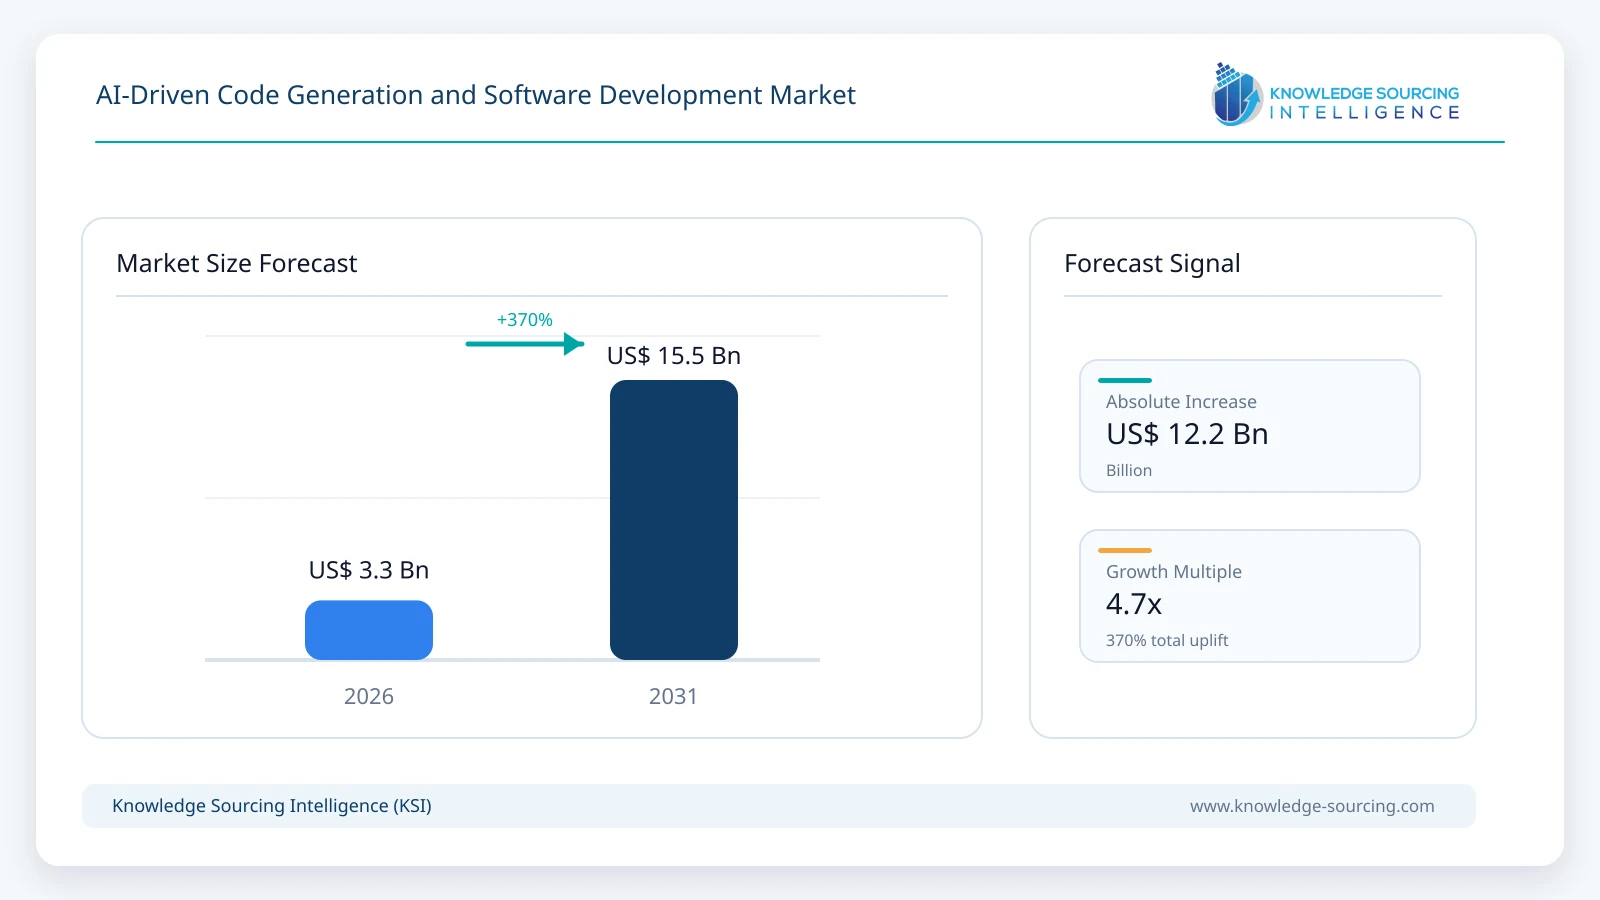
AI-driven code generation and software development products are commercial assistants and engineering agents used to write, transform, explain, test and maintain software. Procurement may take the form of developer subscriptions, enterprise licenses or separately billed coding-agent and model usage. The offering is distinct from the sale of general-purpose cloud infrastructure, a conventional IDE license or a software consulting project in which AI happens to be used internally.
Products differ in where they operate. Some offer inline code completion inside an editor; others take repository-level assignments, modify files within a controlled environment and submit work for approval. Access to build systems, internal documentation, source repositories and test results can be more consequential than a small improvement in public coding benchmarks. Security teams must specify what data enters a model context and which actions an autonomous agent may execute.
Market Overview
Microsoft reported 50 million GitHub Copilot users in July 2026 and noted both growing enterprise participation and significant consumption revenue following a billing change. This is an important indication of developer-tool reach but should not be read as 50 million paying coding seats. OpenAI separately reported more than five million weekly Codex users in June, including nondevelopers. Adoption data therefore support the case for a large prospective buying population without defining the value of paid software-development tools.
Buyers can choose a platform-linked assistant, a model developer's coding agent or a specialist IDE. These options carry different responsibilities: a model vendor may provide inference and an agent harness, while a developer-platform vendor manages repository permissions, workflow presentation and review history. Organizations routinely use multiple offerings during evaluation, but sustained paid usage depends on whether each product fills a distinct engineering need.
Market Trends
Repository agents move from code suggestion to accountable delivery
GitHub expanded Copilot cloud agent in April 2026 so teams can request an implementation plan, allow work on a branch and inspect the diff before asking for a pull request. That separation between preparation and acceptance fits existing software engineering controls more closely than an assistant that simply outputs a patch in chat. An agent that cannot run the project's actual tests or understand the branch policy may create additional review work despite producing plausible code.
Longer-running tasks also change infrastructure requirements. Agents need constrained terminals, temporary credentials, dependency access and traceable tool execution. These features create higher-value enterprise tiers but demand more engineering support from suppliers; adoption is not a mechanical conversion of every existing code-completion user into an autonomous-agent purchaser.
Billing follows inference consumed, not just seats provisioned
GitHub activated AI Credit-based billing across Copilot plans on 1 June 2026, giving customers a more direct link between model use and invoices. A small developer team running occasional completions may have predictable monthly costs, whereas a centralized agent service handling difficult issues can accumulate retries, long context windows and repeated test cycles. The price of a subscription therefore explains only part of the actual engineering cost.
Large buyers are beginning to negotiate budgets, utilization controls and workload-specific model selection alongside user entitlements. Premium pricing is easier to sustain where vendors demonstrate accepted patches and reduced rework. Charging for generated tokens without corresponding measures of engineering outcomes can weaken renewals when agent usage rises faster than deployable code.
Codebase context becomes a purchasable capability
A code model trained on public languages may still misunderstand an enterprise's deployment conventions, service relationships or migration history. Retrieval-augmented tools address part of that gap by finding relevant specifications, issues and repository files at execution time. Their practical value depends on permissions, freshness and the accuracy of document-to-code relationships; retrieving an outdated runbook can make a confident agent less useful than an ordinary developer search.
Google's Managed Agents release in May 2026 placed code execution in a controlled cloud sandbox, while newer model and agent products increasingly support project-specific instructions. These capabilities increase interest in enterprise subscriptions where integration and governance are included. They also preserve space for specialized vendors that understand the surrounding toolchain even when the underlying language model is purchased elsewhere.
Verification capacity becomes the limit on agent throughput
A coding agent can produce a working-looking pull request more quickly than a reviewer can establish its correctness. Generated database migrations, authentication changes and dependency upgrades expose risks that ordinary unit tests often miss. GitHub's 2026 support for code referencing and Anthropic's security-oriented coding tools show vendors extending the review surface, though neither removes the need for human approval on material changes.
Software leaders are therefore comparing escaped defects, reopened pull requests and time spent on supervision with gross lines of code produced. Buyers with well-maintained tests and explicit ownership rules can delegate more work; organizations without those controls often need to invest in engineering hygiene before procuring higher agent volumes.
Segment Analysis
By Technology: AI Agents
Multi-step coding agents are the fastest-changing product group in this market's technology taxonomy. An agent interprets an issue, gathers context, edits files and may run tests inside a permitted environment. Its commercial importance is not that it uses a different foundation model from a conversational assistant; rather, the customer pays for a managed execution workflow with longer task duration and additional governance. AI-agent-associated revenue is expected to approach USD 5.89 billion by 2031 under the market forecast.
The segment's implied annual growth is approximately 54.9% during 2026–2031, reflecting the movement from limited paid agents toward routine supervised tasks. Reliability and permission controls will determine how much revenue moves into these products. The categories of generative AI, LLMs, agents and RAG often operate together technically; a contract is assigned to one primary capability only for consistent market classification.
By Application: Code Generation
Enterprise developers use code generation for application scaffolding, API implementation, feature conversion and modernization of older software. The category remains prominent because new features consume substantial engineering time and generated code can be reviewed against an existing requirement. GitHub Copilot, Cursor, JetBrains and Codex reach this demand through different combinations of editor assistance and delegated repository work. Productivity depends heavily on project context, however; fast output that requires extensive correction does not create equivalent value.
Code-generation-related spending is expected to reach approximately USD 5.74 billion by 2031, an implied 32.2% CAGR from its 2026 position. Its percentage contribution moderates as teams pay separately for debugging, review and DevOps operations. Enterprise procurement is likely to favor vendors able to produce testable diffs and to respect architectural constraints, not those maximizing the amount of generated source code.
By End-User: IT & Telecommunication
IT service companies, cloud operators and telecommunications technology teams manage large and continuously changing software estates. Their developers frequently maintain APIs, customer platforms, operational tooling and infrastructure code, which makes AI assistance commercially applicable beyond greenfield product development. The sector is estimated to represent USD 6.82 billion of attributable purchasing in 2031, despite slower percentage growth than some smaller regulated verticals.
Central engineering teams also face complex authentication rules, internal code dependencies and service reliability obligations. Large suppliers can spread the cost of agent integration across many users, while telecommunications operators must validate changes that may affect live networks. Vendors able to connect models with build pipelines and established change records have an advantage over generic developer chat interfaces.
Market Drivers
Large engineering backlogs and modernization requirements
Enterprises must maintain legacy systems while adding customer features, cloud integrations and security changes. Engineering capacity cannot be expanded immediately for each new requirement. AI-assisted modification and code generation make a viable purchase when they shorten a measurable delivery stage without increasing later rework. The spending mechanism is particularly visible in organizations with documented code ownership and mature automated tests.
Larger contracts are likely to reflect controlled expansion from pilots into multiple repositories and teams. The expected reduction in routine implementation effort can justify additional agent usage, but only when review time and defect rates are measured alongside speed.
Mainstream developer engagement with coding assistants
Microsoft reported 50 million GitHub Copilot users in its July 2026 earnings call, indicating that these interfaces have reached far beyond a niche of early adopters. The figure is a user metric, not a paid-seat or coding-revenue measure. Nevertheless, it reduces the initial training barrier for enterprises considering governed deployment and provides a broad base from which paid advanced capabilities can be adopted.
Organizations with existing identity, repository and license management arrangements can make purchasing decisions faster than firms building governance from scratch. Supplier growth increasingly depends on converting familiar developer workflows into measurable paid enterprise usage.
Agent integration with CI/CD and software delivery systems
An agent that opens a reviewed change within an established development pipeline has a clearer commercial role than one that produces text outside the workflow. Build execution, test evidence, issue linking and version control reduce manual transfer of generated output. GitHub and OpenAI have expanded agent integration surfaces during 2026, allowing organizations to delegate constrained work without abandoning normal code review.
These integrations support recurring usage fees and enterprise administration products. Their value is greatest when tool permissions and exception handling are explicit, since a failed automated task should return evidence for diagnosis rather than silently close a development ticket.
Paid demand for security and code quality validation
Software buyers face increasing costs from insecure dependencies, misconfigured permissions and faulty code changes. AI can help identify likely vulnerabilities or create initial tests, but it can also generate an error that passes a superficial review. This creates a purchasing case for deeper review, test-generation and remediation tools sold around the principal coding assistant.
The effect is not a universal uplift to every subscription. Customers will demand evidence of reduced escaped defects and lower manual triage rather than accept claims about the quantity of scans performed. Vendors with transparent findings and human-review controls are more credible in critical applications.
Expansion of enterprise deployment and model choice
Organizations that restrict proprietary source code cannot evaluate a coding tool solely on model quality. Data handling, regional processing, configurable retention and private repository access determine whether the product is even eligible for procurement. More suppliers now offer enterprise administrative controls and model-routing options to address these constraints.
The resulting market includes contracts for governed multi-model access as well as specialist on-premise or isolated environments. Integration work can increase purchase value, but support and inference costs must remain proportionate to engineering outcomes.
Market Restraints
Defect propagation and unreliable autonomous changes
A plausible patch can compile while violating an unstated product requirement, mishandling an exception or changing a database schema incorrectly. Multi-file agents may compound the problem by making several coordinated but mistaken edits. Enterprises cannot eliminate review simply because coding benchmarks improve, especially for production releases with hard uptime and security constraints.
Verification cost rises with agent task volume when test suites are weak. Such organizations may limit usage to drafts and supervised code completion until they have dependable regression coverage and ownership rules.
Source confidentiality and intellectual-property exposure
Source repositories contain proprietary architecture, credentials and third-party licensed components. Sending unrestricted context to an external model can conflict with contractual and internal security requirements. Code referencing helps developers inspect possible reuse, but it does not substitute for a licensing policy or guarantee that generated output has a clear provenance.
Legal review, security evaluation and regional storage requirements can delay procurement. Vendors may need to provide private execution, retention controls and evidence of limited tool access before regulated customers expand beyond pilots.
Variable inference costs and difficult unit economics
A long agent run can repeatedly query a model while inspecting a repository, running tests and recovering from failure. Consumption billing makes those costs visible, but monthly invoices remain sensitive to task complexity and unsuccessful attempts. Customers using several overlapping coding products also risk paying multiple times for capabilities that are not fully adopted.
A supplier may win a trial through low seat prices yet lose renewal negotiations if spending per accepted change proves unpredictable. Enterprises are likely to impose quotas and require usage analytics, restraining premium adoption where value evidence is weak.
Legacy code and fragmented engineering knowledge
Older applications often lack current specifications, maintainable build scripts or reliable test coverage. AI agents need the very context that such systems fail to document, and retrieval over outdated material can lead to persistent wrong assumptions. Integrations across different source-control, ticketing and CI systems also become expensive when teams have divergent working practices.
Implementation effort may exceed the cost of licensing the assistant. Firms with complex estates often progress repository by repository, which moderates the pace at which pilot use becomes a company-wide paid contract.
Governance requirements for self-directed tool execution
An agent with write access to production infrastructure, dependency registries or deployment scripts can cause operational damage if given excessive authority. Least-privilege credentials, approval gates, action logging and rollback are therefore necessary parts of deployment. The availability of an autonomous feature in a product does not establish that a customer has approved it for live use.
Security review and change-control responsibilities remain with the organization. This limits fully unattended automation and places a premium on systems that make every proposed change easy for engineers to understand and reverse.
Regional Outlook
North America
North America is estimated to account for 42% of global AI-assisted software development spending in 2026, reflecting large enterprise software budgets and the commercial presence of major development platform vendors. Microsoft, GitHub, OpenAI, Anthropic and numerous specialist companies sell into mature software engineering teams with established repository governance and cloud procurement. The United States provides most regional spending, though cross-border developer teams complicate any direct comparison of user location with billed revenue.
The regional market is projected at approximately USD 5.58 billion by 2031, an implied 32.1% CAGR. Expansion depends on moving beyond individual developer access into enterprise-wide policies, reliable agent execution and chargeback mechanisms. North America's share moderates as adoption broadens in Asian software and technology-service organizations.
Asia Pacific
Asia Pacific's developer-services base, application modernization work and domestic cloud ecosystems support faster adoption of paid coding assistance. India, China, Japan and South Korea have distinct patterns of enterprise procurement: large outsourced development teams must demonstrate client data controls, while regulated domestic buyers weigh local processing and toolchain compatibility. Google and regional platform suppliers provide additional channels, but the model or agent's origin is not the same as the customer's billing region.
Regional spending is expected to reach approximately USD 4.65 billion by 2031 from USD 0.79 billion in 2026, representing about 42.5% annual growth. Its forecast share increases to 30% as customers move from free experimentation to centrally licensed agents, testing and documentation capabilities. The pace still depends on enterprise price realization and the ability to service multiple languages and proprietary application stacks.
Competitive Landscape
Microsoft and GitHub benefit from proximity to repositories, identity management and continuous-integration workflows; their ability to connect Copilot with organization-level policies strengthens enterprise distribution. OpenAI's Codex and Anthropic's Claude Code compete more directly on agent execution, model performance and developer control. Google links its Gemini models with Antigravity and cloud execution tooling, while Amazon Web Services sells Kiro into development work already associated with AWS environments.
Specialist vendors compete on workflow rather than distribution scale. Anysphere develops Cursor; JetBrains sells Junie alongside its IDE ecosystem; Tabnine offers enterprise-oriented coding assistance; Qodo emphasizes review and code quality; Replit supplies an integrated application-building agent; and Cognition markets Devin and Windsurf. GitLab adds AI-assisted development within its own DevSecOps platform. Customers commonly trial more than one solution, so vendor user counts and the value of a software platform's entire contract are not valid substitutes for coding-specific revenue share.
Recent Developments
13 October 2026: Google - Made Gemini 4 Argon available to developers through the paid Gemini API and Antigravity, targeting longer, more complex software engineering workflows.
28 September 2026: Anthropic - Introduced Claude Sonnet 5.5, identifying improved execution speed and pricing for tasks that include software development.
19 August 2026: OpenAI - Described the Codex agent harness as an embeddable platform, enabling partners to integrate governed coding agents into existing applications and workflows.
1 June 2026: GitHub - Activated AI Credit usage-based billing and budget controls for Copilot, changing how intensive agent use is monetized and administered.
19 May 2026: Google - Launched Managed Agents for the Gemini API, allowing coding agents to execute within an isolated cloud sandbox with versionable instructions.
Market Outlook
By 2031, demand will be shaped less by the novelty of code generation than by the economic productivity of supervised agents. Repository-level work, test execution and review preparation will gain budget where teams can identify a completed engineering outcome. Code completion remains important, but the ability to use project context and preserve human accountability will determine the size of advanced subscriptions.
Competition will intensify between vendors that own enterprise developer distribution and specialists offering better execution, model routing or controlled deployment. Consumption-based billing may increase vendor revenue as agent usage expands, but also exposes the cost of repeated failures and lengthy review. Buyers with strong test infrastructure and documented code ownership are positioned to capture earlier returns than organizations treating agents as substitutes for engineering governance.
AI-Driven Code Generation and Software Development Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.30 billion |
| Total Market Size in 2031 | USD 15.50 billion |
| Forecast Unit | Billion |
| Growth Rate | 36.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Application, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Technology
Generative AI
Large Language Models (LLMs)
AI Agents
Retrieval-Augmented Generation (RAG)
By Application
Code Generation
Code Completion
Code Review & Refactoring
Debugging & Testing
Documentation Generation
DevOps Automation
Others
By End-User
IT & Telecommunication
BFSI
Healthcare
Manufacturing
Retail & E-commerce
Government
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
Japan
China
India
South Korea
Taiwan
Australia
Others
Geographical Segmentation
- Middle East and Africa
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Opportunity Summary
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Large engineering backlogs and modernization requirements
3.1.2. Mainstream developer engagement with coding assistants
3.1.3. Agent integration with CI/CD and software delivery systems
3.1.4. Paid demand for security and code quality validation
3.1.5. Expansion of enterprise deployment and model choice
3.2. Market Restraints
3.2.1. Defect propagation and unreliable autonomous changes
3.2.2. Source confidentiality and intellectual-property exposure
3.2.3. Variable inference costs and difficult unit economics
3.2.4. Legacy code and fragmented engineering knowledge
3.2.5. Governance requirements for self-directed tool execution
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Agent Orchestration and Secure Sandboxes
4.2. Repository Retrieval and Context Management
4.3. Code Review and Test Automation
4.4. Enterprise Model Governance
5. AI-DRIVEN CODE GENERATION AND SOFTWARE DEVELOPMENT MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Generative AI
5.3. Large Language Models (LLMs)
5.4. AI Agents
5.5. Retrieval-Augmented Generation (RAG)
6. AI-DRIVEN CODE GENERATION AND SOFTWARE DEVELOPMENT MARKET BY APPLICATION
6.1. Introduction
6.2. Code Generation
6.3. Code Completion
6.4. Code Review & Refactoring
6.5. Debugging & Testing
6.6. Documentation Generation
6.7. DevOps Automation
6.8. Others
7. AI-DRIVEN CODE GENERATION AND SOFTWARE DEVELOPMENT MARKET BY END-USER
7.1. Introduction
7.2. IT & Telecommunication
7.3. BFSI
7.4. Healthcare
7.5. Manufacturing
7.6. Retail & E-commerce
7.7. Government
7.8. Others
8. AI-DRIVEN CODE GENERATION AND SOFTWARE DEVELOPMENT MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East & Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. Japan
8.6.2. China
8.6.3. India
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Australia
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Microsoft Corporation (GitHub)
10.2. OpenAI
10.3. Anthropic PBC
10.4. Google LLC
10.5. Amazon Web Services, Inc.
10.6. Anysphere, Inc. (Cursor)
10.7. JetBrains s.r.o.
10.8. Cognition AI, Inc. (Devin and Windsurf)
10.9. Tabnine Ltd.
10.10. GitLab Inc.
10.11. Qodo
10.12. Replit, Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits to Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected market value of AI-Driven Code Generation and Software Development by 2031?
The AI-Driven Code Generation and Software Development Market is forecast to reach USD 15.50 billion by 2031.
What is the annual growth rate for the AI-Driven Code Generation and Software Development market?
The AI-Driven Code Generation and Software Development Market is expected to expand at approximately 36.3% annually.
Which application classification accounts for the most spending in 2026?
Code generation accounts for an estimated 43% of 2026 spending.
What share do AI agents represent in the 2026 market value?
AI agents represent an estimated 20% of the 2026 market value.
Which region currently has the largest commercial buying base?
North America has the largest current commercial buying base.
Which region is expected to increase revenue contribution through 2031?
Asia Pacific is expected to increase its revenue contribution through 2031.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). AI-Driven Code Generation and Software Development Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/ai-for-code-generation-and-software-development-market