
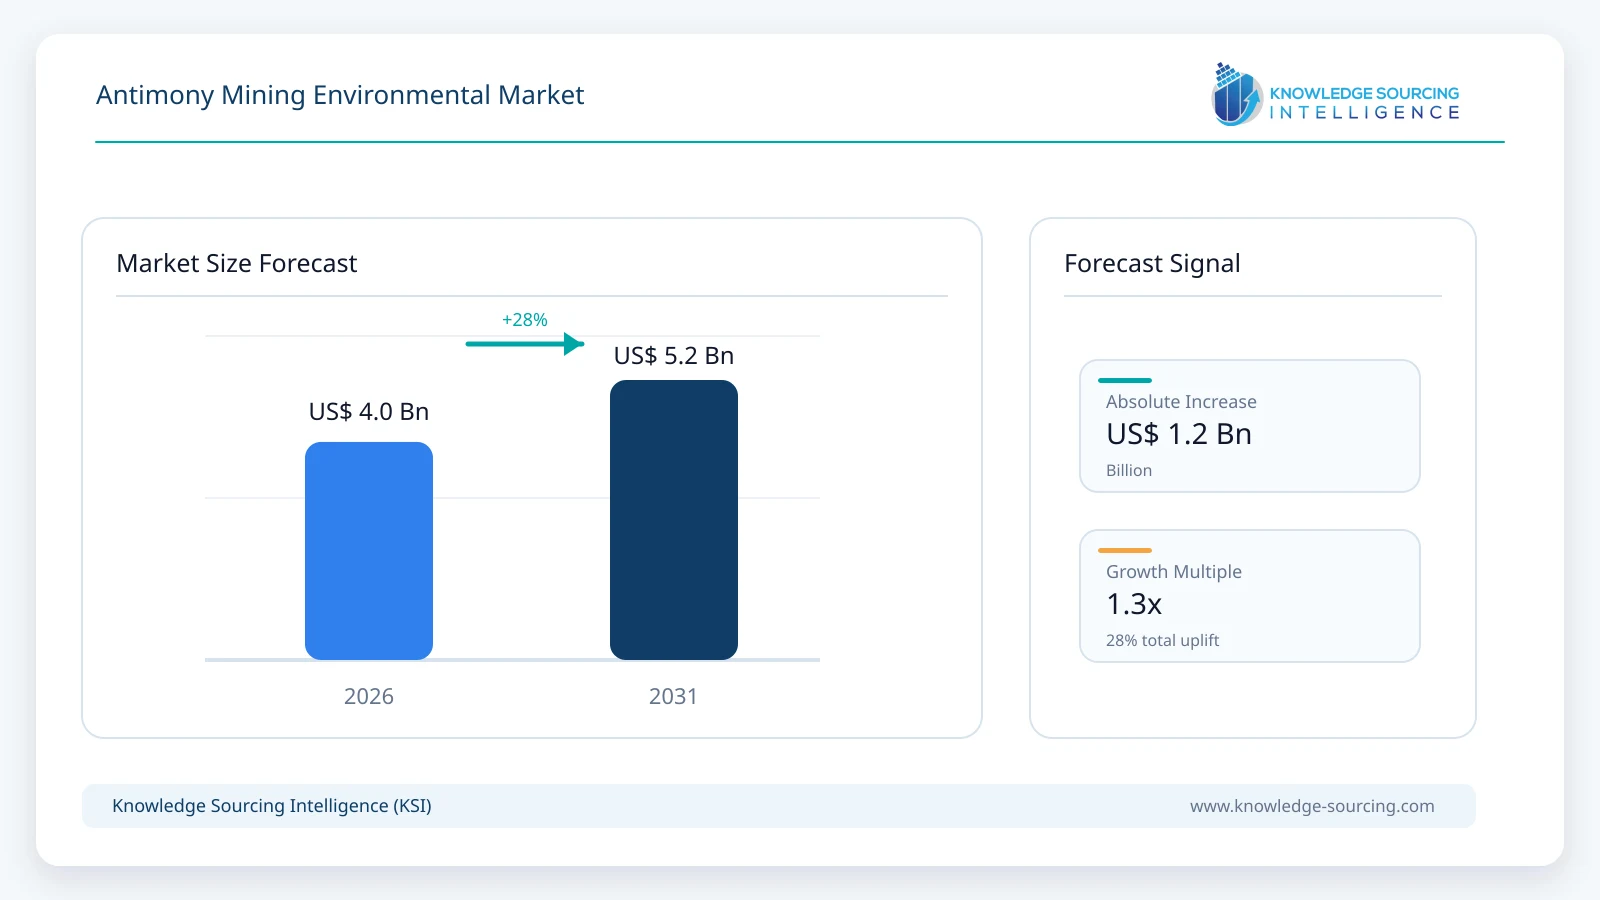
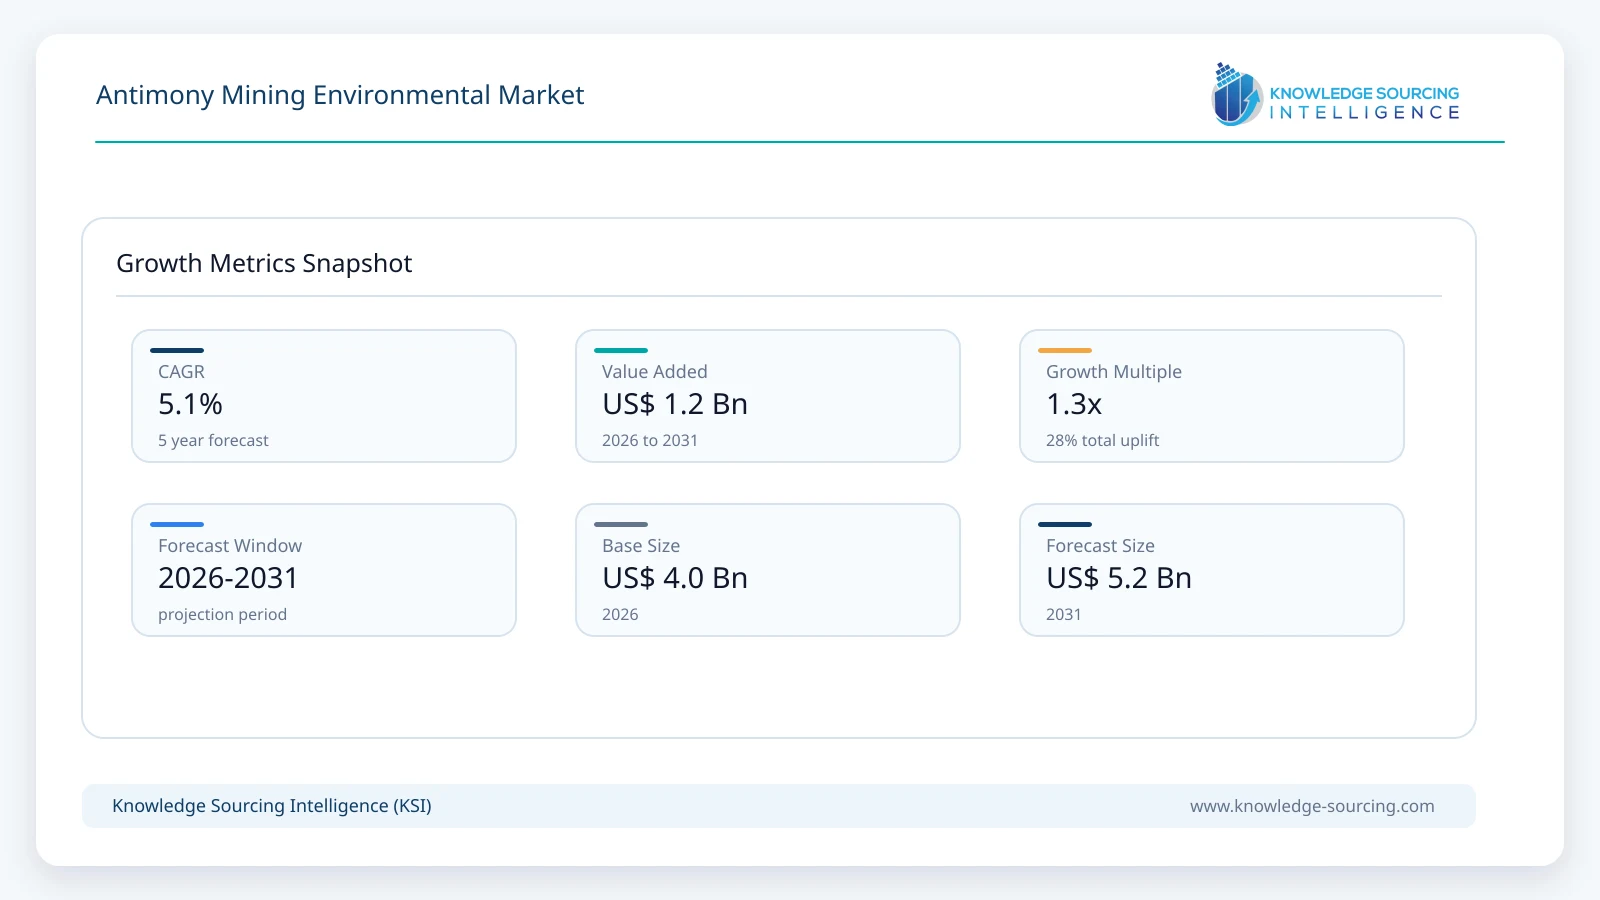
The Antimony Mining Environmental Market is projected to grow from USD 4.05 billion in 2026 to USD 5.20 billion by 2031, at a CAGR of 5.1% during the forecast period.
Highlights:
- 1Antimony trioxide remains the principal product group because of flame-retardant synergist demand.
- 2Flame retardants anchor downstream consumption, with electronics and construction shaping specifications.
- 3Powder formats lead commercial supply, while high-purity metallic products retain strategic demand.
- 4Asia Pacific retains the broadest refining and end-use base across antimony product categories.
- 5North American investment increasingly targets domestic concentrate, metal and specialty-material capacity.
- 6Permitting, residue management and supply volatility differentiate viable projects from early proposals.
The market encompasses antimony materials supplied through mining, mineral recovery, refining and manufacture into compounds or alloys. Commercial products include antimony trioxide and pentoxide, metallic alloy feedstocks, sodium antimonate and other antimony-bearing derivatives used in flame-retardant systems, battery components, glass, ceramics, catalysts and specialist industrial applications. Saleable concentrate and chemical products occupy different points in the chain: the same metal content must not be valued twice when transferred between a mine, smelter and downstream compound plant.
Environmental performance is inseparable from commercial qualification. Mines containing sulfide ore can require site-specific controls for water, tailings, dust and disturbed land, while oxide production must manage emissions and operator exposure. Product buyers also assess impurity specifications and traceability, particularly where antimony enters electronics, construction materials or regulated chemical formulations. Those requirements create value for established facilities capable of documenting both chemical composition and process stewardship.
Antimony production remains concentrated among a small group of countries. The US Geological Survey estimates world mine output at approximately 110,000 tonnes for 2025. China, Russia and Tajikistan together represent most primary extraction, although refining, secondary recovery and compound manufacturing create different commercial footprints from mine production alone. The supply chain therefore remains vulnerable when concentrate sources, qualified processors or export permissions change unexpectedly.
Antimony trioxide is central to polymer fire-safety formulations, usually as a synergist used with other flame-retardant ingredients. Metallic antimony has a separate role in lead alloys and certain specialty applications; sodium antimonate and pentoxide address tighter processing specifications in glass, chemical and materials markets. Environmental and occupational performance cannot be inferred from the word “antimony” alone because dust characteristics, chemical form, exposure pathway and process conditions vary considerably.
New supply projects have begun moving beyond engineering presentations. Nyrstar shipped commercial-grade metal from its Port Pirie demonstration plant in February 2026, while Larvotto advanced Hillgrove into concentrate production and first shipment during the year. In Idaho, Perpetua has pursued Stibnite construction alongside a government-supported trisulfide processing pilot. These assets are not at equivalent stages of production, but they illustrate the range of steps required to create an alternative supply chain.
Market Trends
Secondary Recovery Is Becoming a Strategic Metal Source
Antimony recovery from industrial residues is gaining investment attention because the metal already exists in lead and other metallurgical streams that are collected at scale. Campine approved a new generation of recycling technology in December 2025 to produce additional commercial-grade metal from waste feeds. Such investments can reduce dependence on newly mined concentrates, but the recovery economics hinge on feed chemistry, impurity management and the specification of the final product.
Recycled content is not inherently lower-cost. Salt residues, by-product mixtures and heterogeneous feeds require pretreatment and dedicated recovery steps; purchasing departments must also establish traceability when recycled and primary material are blended. Processors that can repeatedly recover saleable trioxide or metal, rather than merely demonstrate laboratory extraction, are best positioned to serve industrial contracts.
Antimony Supply Chains Are Being Rebuilt Around Regional Refining
Nyrstar’s February 2026 shipment from Port Pirie followed the commissioning of antimony processing within an established multi-metals complex. The importance lies in integration: refining capacity can access antimony from several concentrate streams while sharing infrastructure and metallurgical skills with adjacent operations. It offers a route to greater supply diversity without requiring every buyer to finance an entirely new mine-to-chemical operation.
Regional processing capacity still needs reliable feedstock and cost competitiveness. A demonstration shipment does not establish mature production capacity, and proposed throughput should be separated from annual sales. Refiners able to reach repeatable recoveries, meet customer specifications and control environmental liabilities will determine whether policy interest converts into routine procurement.
Downstream Customers Are Tightening Product Qualification
Flame-retardant compound makers need consistent trioxide particle behavior and controlled impurities, while specialty glass producers may select pentoxide or sodium antimonate for different processing outcomes. Broad commodity availability does not eliminate plant trials: variability in a powder can affect dispersion, opacity and performance, and a metal ingot unsuitable for a particular alloy cannot be substituted merely because its antimony content is high.
Supplier selection increasingly includes batch documentation, material safety data and continuity of service. This creates room for specialist chemical producers even when their raw material comes from the same mining region. It also explains why price volatility does not translate proportionately into end-product demand; customers can temporarily destock, adjust formulation or qualify substitutes.
Mining Projects Are Combining Critical-Mineral Supply with Site Rehabilitation
Perpetua’s Stibnite development illustrates the integration challenge facing new North American antimony supply. Site access, water management, power, waste handling and rehabilitation plans must be developed alongside mineral recovery. Project announcements that emphasize the resource base therefore provide only a partial measure of commercial readiness; environmental approvals and financing have to advance in parallel.
Past mining can leave difficult legacy conditions that complicate new operations. Restoring waterways or stabilizing historical workings can create long-term benefits but also adds cost and schedule exposure. Project developers able to coordinate permitting, construction and measurable closure obligations may gain credibility with customers seeking long-duration supply commitments.
Defense and Battery Buyers Are Seeking Qualified Specialty Grades
The United States Army and Idaho National Laboratory opened a modular pilot facility with Perpetua in July 2026 to test a domestic route to antimony trisulfide. The distinction from trioxide production is material: military specifications, chemical processing and end-use qualification differ, so the facility cannot be counted as commercial capacity for every antimony application.
Lead-acid batteries continue to use selected antimony-bearing alloys in industrial and auxiliary duties, even as other grid designs have reduced the need for antimony in certain battery formulations. Future growth depends on use-specific chemistry rather than a universal assumption that all batteries require antimony. Markets that demand documented purity and secure origin can sustain premiums, but only after supplier qualification.
Antimony Mining Environmental Market Segment Analysis
By Type
Antimony Trioxide
Antimony trioxide is estimated to account for approximately 43% of market revenue in 2026. Its large position reflects established purchasing by flame-retardant compounders, particularly where thermoplastic housings, cable products and engineered building materials require antimony-based synergists. Product consistency matters because small differences in chemistry and powder characteristics can affect downstream performance.
Producers compete on oxide purity, controlled particle size and reliable delivery more than on ore ownership alone. Secondary recovery can provide part of the feedstock, but contaminated residues require careful handling before producing a saleable oxide grade. Pentoxide, sodium antimonate and metallic alloys occupy other technical niches; their demand cannot be treated simply as a substitute for trioxide tonnage.
By Application
Flame Retardants
Construction products, electrical insulation and electronics enclosures provide a recurring market for antimony-containing flame-retardant systems. End-product fire-safety standards are generally performance requirements rather than mandates to use a particular antimony chemistry. This leaves formulation companies scope to consider aluminum-based, phosphorus-based or other alternatives when cost, hazard classification or recycling requirements change.
Flame retardants are projected to represent approximately USD 1.98 billion in 2031. The segment’s commercial outlook rests on the balance between application-specific qualification and substitution pressure. A compounder may retain trioxide where changing a proven recipe creates unacceptable requalification cost, but new designs can adopt different chemistries where comparable performance and processing economics are demonstrated.
By Form
Powder
Powder products account for an indicative 59% of 2026 revenue, led by antimony trioxide and other compounds prepared for controlled dispersion in polymers, coatings and industrial mixtures. Uniformity, dust control and packaging are important elements of the purchased product: a grade that is nominally pure may still be unacceptable if feed handling or particulate exposure cannot be managed in a customer’s production line.
Ingot has a distinct role in alloy manufacture and selected refining routes, while liquid derivatives serve narrower chemical operations. The three categories cover physical form rather than independent additive markets; a tonne converted from ingot to powder during further processing should not inflate total final-sales value. Suppliers with multiple suitable forms can serve customers that are seeking flexibility in handling and blending.
By End-Use Industry
Chemicals
Chemical processors turn antimony-bearing feedstocks into controlled oxide, antimonate, catalyst or specialty formulations. Their purchases are tied to process yields, quality documentation and safe handling obligations, and may differ substantially from direct deliveries to a construction-products plant or electronics assembler. The sector also absorbs residues from other metallurgical operations and creates feedstocks for downstream users.
The Chemicals end-use group is estimated at about USD 1.09 billion in 2026. Growth is supported by value addition at the conversion stage and customer demand for consistent speciality grades, but profit margins remain sensitive to raw-antimony prices. Chemical producers with proprietary recovery technology and flexible sourcing can be less exposed to a single mining basin than buyers relying exclusively on primary concentrate.
Market Drivers
Fire-Safety Materials Retain Established Antimony Specifications
Antimony trioxide supports durable industrial formulations where flame retardancy must be achieved without unacceptable changes to mechanical properties or processing behavior. Electrical enclosures, cables and selected building materials remain relevant demand pools. The industry is not driven by a uniform legal requirement to use trioxide; suppliers benefit when customers have already validated a particular antimony-containing formulation.
Continuing qualification costs can sustain repeat purchases, especially for long-lived products. However, suppliers need to demonstrate uniform powder quality and downstream consistency as compounders increasingly compare alternative flame-retardant systems.
Regional Supply Security Is Supporting New Refining Projects
Export disruptions and price movements have made antimony supply security a board-level issue for certain industrial and defense buyers. New metal production at Port Pirie, renewed concentration at Hillgrove and domestic U.S. processing experiments point to several different ways to reduce exposure to a narrow supplier group.
The opportunity depends on executed capacity and usable product, not a project’s headline resource. Customers entering offtake relationships will still assess cost, specification, delivery reliability and operational permitting before substituting established supplies.
Industrial Recycling Creates Additional Recoverable Feed
Lead-refining residues and other industrial materials can contain recoverable antimony that would otherwise remain in lower-value streams. Campine’s planned technology upgrade illustrates the shift toward recovery of saleable metal as well as oxide. The benefit is strongest where a recycler already controls material collection and has the metallurgy needed to isolate antimony economically.
By-product recovery also creates a more diversified input base for chemical producers. Its limit is feed composition: not all residues can be processed at a profitable yield, and treatment of unwanted contaminants adds technical costs.
Specialist Defense Supply Encourages New Qualification Investment
High-specification antimony trisulfide is sought for defense and selected industrial applications, creating potential demand beyond ordinary oxide purchases. The Perpetua–Army–Idaho National Laboratory pilot demonstrates how production pathways can be trialed before building full commercial capacity.
Qualification may involve chemistry, traceability and performance testing specific to the end user. These requirements can sustain specialized supply agreements but also delay the conversion of a successful pilot into stable delivered revenue.
Glass, Ceramic and Catalyst Processes Support Product Diversification
Sodium antimonate, pentoxide and other derivatives are used in selected manufacturing processes requiring chemical functions beyond traditional flame retardancy. Growth may come from specialized product and impurity specifications rather than very large increases in material tonnage.
For refiners, a broader product slate can improve utilization and reduce reliance on a single downstream industry. Commercial benefits require plant chemistry that can switch economically among grades without raising effluent or residue-handling risks.
Market Restraints
Volatile Antimony Pricing Complicates Procurement and Project Economics
Antimony prices rose sharply in 2025 against a backdrop of export controls and tight availability. The USGS reported an average of about USD 25 per pound for that year, more than double the preceding average. These swings can disrupt customers operating on annual chemical contracts and alter the economics of a proposed new mine or refinery.
High prices can encourage capacity investment, yet they also increase working capital, substitution efforts and the risk of losses on unsold inventories if quotations retreat. Projects should therefore be assessed across price scenarios rather than a single recent spot price.
Wastewater, Tailings and Dust Requirements Raise the Cost of Supply
Antimony-related mining and chemical operations can produce metalliferous water, waste rock, dust and smelter residues requiring controlled management. Treatment requirements depend on the site and chemical species; for perspective, the U.S. federal drinking-water limit for antimony is 0.006 mg/L, which is not itself a universal mining-discharge limit.
Containment, monitoring and long-term site care can add major capital commitments. This raises entry barriers for companies without environmental engineering capabilities and extends the period between discovery and repeat commercial sales.
Downstream Substitution Challenges Volume Growth
Some flame-retardant manufacturers can reduce reliance on antimony through alternative synergists or revised polymer formulations, provided performance and cost targets are met. Battery designs may also lower antimony content where different lead-alloy or battery chemistries are viable.
Substitution rarely occurs instantly in qualified products, but its long-run effect limits how far high antimony prices can be passed through. Producers need technical support and secure specifications to retain customers through repeated reformulations.
Concentrate Availability and Refining Bottlenecks Are Not Interchangeable
A new ore deposit does not automatically provide qualified trioxide or metal for an end customer. Smelters must accommodate concentrate impurities, manage recovery losses and meet off-take chemistry. Similarly, a refinery announcement does not ensure sufficient feedstock will be available at an acceptable delivered price.
The constraint is particularly significant for new regional supply programs that attempt to establish mining, refining and chemical conversion simultaneously. Each stage needs its own investment, commissioning trials and operating permits.
Complex Permitting and Financing Extend Development Timelines
Projects combining extraction with rehabilitation face demanding approval, financing and construction schedules. Water-quality certification, waste treatment, site access and stakeholder challenges can create material delays even after initial project authorization.
The result is a gap between strategic interest and deliverable supply. Large purchasers may secure development-stage agreements, but they need contingency sources until a new facility passes commissioning and demonstrates consistent throughput.
Regional Outlook
Asia Pacific
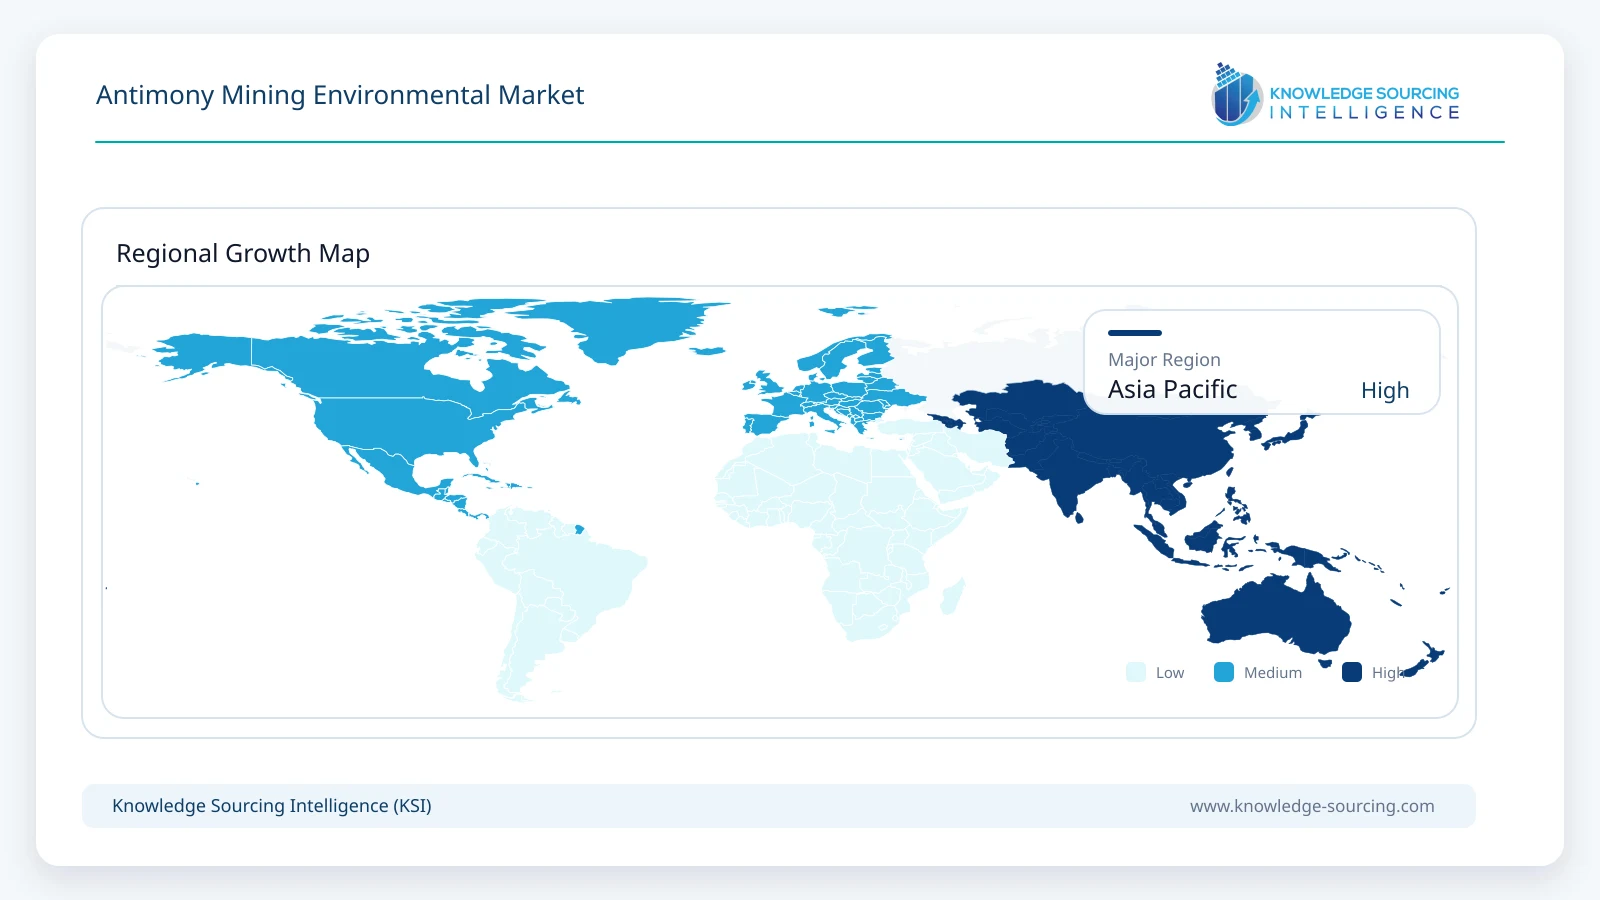
Asia Pacific is the largest regional market, accounting for about 50% of global revenue in 2026. The region combines major ore sources and refining operations with electronics, chemical, automotive and construction customers. China is important as both a processor and purchaser, while Japan, South Korea and Taiwan contribute downstream requirements for precise chemical specifications and traceable industrial inputs.
Mine production and refined-product consumption should not be conflated: Russia and Tajikistan are significant upstream suppliers outside this region, while Asian manufacturers also process imported materials. Environmental investment is increasingly consequential where energy-intensive smelting and chemical operations must meet dust, waste and water-management requirements. Qualification and residue recovery can preserve regional competitiveness as alternative supply channels develop elsewhere.
North America
U.S. supply-chain initiatives are focused on moving from resource access toward qualified metal, oxide and defense-grade forms. United States Antimony operates smelting and oxide capabilities, while Perpetua is advancing Stibnite construction and a specialized pilot route to trisulfide. Canadian critical-mineral projects and Mexico’s metallurgical operations can contribute at different points in the regional supply chain.
North America is projected to be the fastest-growing region at approximately 9.9% CAGR over 2026–2031. Its smaller existing refining base creates scope for growth if announced projects become reliable suppliers. However, the region will continue to import substantial quantities until facilities secure feedstock, operate consistently and satisfy customer specifications as well as their environmental commitments.
Competitive Landscape
Antimony competition differs by product stage. Campine combines chemical manufacture with recycling capability, Nyrstar is developing metal output from an existing multi-metals complex, and United States Antimony supplies metal and oxide through North American operations. Chinese and Japanese manufacturers participate strongly in chemical grades, while Larvotto and Alkane Resources focus on mine or concentrate supply. Perpetua remains in development and should not be compared with established commercial refiners on current antimony sales.
Price, product assay, permitted production and feedstock access have greater explanatory power than a single company-wide market-share ranking. A chemical supplier with modest mining exposure may still control a valuable customer qualification, while an ore producer with substantial reserves may not yet sell finished compounds. Commercial comparison is most useful when it identifies the product being invoiced and whether a capacity figure describes a proposal, a pilot, a demonstrated shipment or recurring production.
Recent Developments
14 October 2026: Larvotto Resources ships first Hillgrove concentrate
Larvotto reported the first shipment of antimony concentrate from the Hillgrove project in New South Wales following the restart and plant commissioning. The event moves the operation beyond initial concentrate production, although steady-state output still depends on the subsequent ramp-up.
28 September 2026: Perpetua advances Stibnite construction
Perpetua reported work on access roads, workforce accommodation and electrical infrastructure at its Stibnite Gold Project. The milestone concerns critical-path construction for future mineral production, not currently realized commercial antimony shipments.
30 July 2026: Perpetua and partners launch trisulfide pilot
Perpetua, the U.S. Army and Idaho National Laboratory opened a modular pilot plant to demonstrate antimony trisulfide processing from Stibnite material. The program addresses a defense-grade chemistry and remains a pilot rather than a commercial-scale trioxide facility.
17 February 2026: Nyrstar ships Australian antimony metal
Nyrstar announced the first shipment of commercial-grade antimony metal from its Port Pirie demonstration plant. The project leverages existing lead-refining infrastructure and provides a practical reference for alternative metal processing capacity.
18 December 2025: Campine approves advanced recycling investment
Campine approved investment in a new generation of antimony recovery technology intended to recover an additional 800–1,000 tonnes a year of metal from industrial waste streams. The throughput is a proposed capability, not a completed annual production result.
Market Outlook
Growth through 2031 will depend on a combination of end-use demand and the successful rebuilding of refining capacity. Existing fire-safety, alloy and chemical applications are likely to remain important, but volume expansion will be tempered by formulation substitution, recycling economics and changing procurement practices. The commercial premium may increasingly lie in reliable certified product rather than raw material scarcity alone.
Environmental performance will influence which new operations reach sustained production. Projects that embed water protection, residue recovery and transparent supply-chain records in plant design are better placed to secure long-term buyers. Investors and customers should distinguish announced capacity from physically commissioned output and track the conversion of specialty pilots into repeat orders.
Antimony Mining Environmental Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.05 billion |
| Total Market Size in 2031 | USD 5.20 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Form, End-Use Industry, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Antimony Trioxide
Antimony Pentoxide
Antimony Alloys
Sodium Antimonate
Others
By Application
Flame Retardants
Lead-Acid Batteries
Plastics
Glass and Ceramics
Catalysts
Others
By Form
Powder
Ingot
Liquid
By End-Use Industry
Chemicals
Electrical and Electronics
Automotive
Construction
Textiles
Defense
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
Japan
China
India
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Fire-Safety Materials Retain Established Antimony Specifications
3.1.2. Regional Supply Security Is Supporting New Refining Projects
3.1.3. Industrial Recycling Creates Additional Recoverable Feed
3.1.4. Specialist Defense Supply Encourages New Qualification Investment
3.1.5. Glass, Ceramic and Catalyst Processes Support Product Diversification
3.2. Market Restraints
3.2.1. Volatile Antimony Pricing Complicates Procurement and Project Economics
3.2.2. Wastewater, Tailings and Dust Requirements Raise the Cost of Supply
3.2.3. Downstream Substitution Challenges Volume Growth
3.2.4. Concentrate Availability and Refining Bottlenecks Are Not Interchangeable
3.2.5. Complex Permitting and Financing Extend Development Timelines
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Sulfide Concentrate Processing
4.2. Antimony Oxide and Antimonate Conversion
4.3. Residue Recycling and Metal Recovery
4.4. Effluent, Tailings and Air-Emission Management
5. ANTIMONY MINING ENVIRONMENTAL MARKET BY TYPE
5.1. Introduction
5.2. Antimony Trioxide
5.3. Antimony Pentoxide
5.4. Antimony Alloys
5.5. Sodium Antimonate
5.6. Others
6. ANTIMONY MINING ENVIRONMENTAL MARKET BY APPLICATION
6.1. Introduction
6.2. Flame Retardants
6.3. Lead-Acid Batteries
6.4. Plastics
6.5. Glass & Ceramics
6.6. Catalysts
6.7. Others
7. ANTIMONY MINING ENVIRONMENTAL MARKET BY FORM
7.1. Introduction
7.2. Powder
7.3. Ingot
7.4. Liquid
8. ANTIMONY MINING ENVIRONMENTAL MARKET BY END-USE INDUSTRY
8.1. Introduction
8.2. Chemicals
8.3. Electrical & Electronics
8.4. Automotive
8.5. Construction
8.6. Textiles
8.7. Defense
9. ANTIMONY MINING ENVIRONMENTAL MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. United Kingdom
9.4.2. Germany
9.4.3. France
9.4.4. Italy
9.4.5. Others
9.5. Middle East & Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. Others
9.6. Asia Pacific
9.6.1. Japan
9.6.2. China
9.6.3. India
9.6.4. South Korea
9.6.5. Taiwan
9.6.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Campine NV
11.2. Nyrstar
11.3. United States Antimony Corporation
11.4. Larvotto Resources Limited
11.5. Alkane Resources Limited
11.6. Perpetua Resources Corp.
11.7. Nihon Seiko Co., Ltd.
11.8. Hunan Chenzhou Mining Group
11.9. Yunnan Muli Antimony Industry
11.10. AMG Critical Materials N.V.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected market size by 2031?
The Antimony Mining Environmental Market is projected to reach USD 5.20 billion by 2031.
What is the Compound Annual Growth Rate (CAGR) for this market?
The Antimony Mining Environmental Market is projected to grow at a CAGR of 5.1% (2026-2031).
Which product group is the principal driver of market demand?
Antimony trioxide is the principal product group driving demand.
Which region holds the broadest antimony refining and end-use base?
Asia Pacific retains the broadest refining and end-use base.
What are the primary applications driving antimony demand?
Flame retardants, battery components, glass, and ceramics drive demand.
Which countries primarily contribute to global antimony mine output?
China, Russia, and Tajikistan represent most primary extraction.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Antimony Mining Environmental Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/antimony-mining-environmental-market