
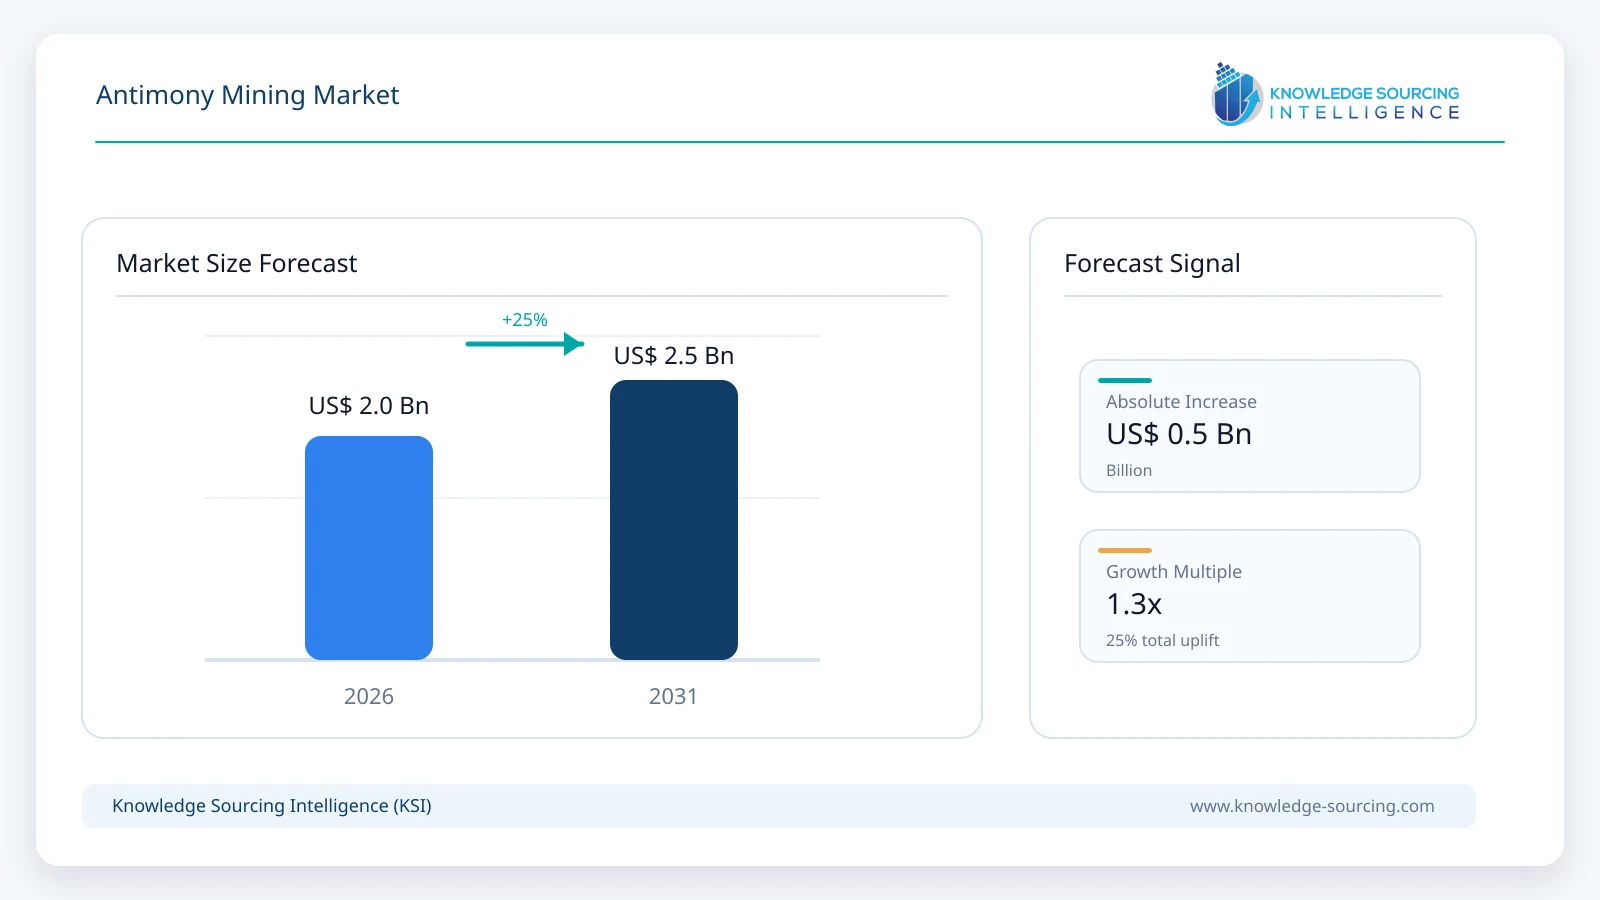
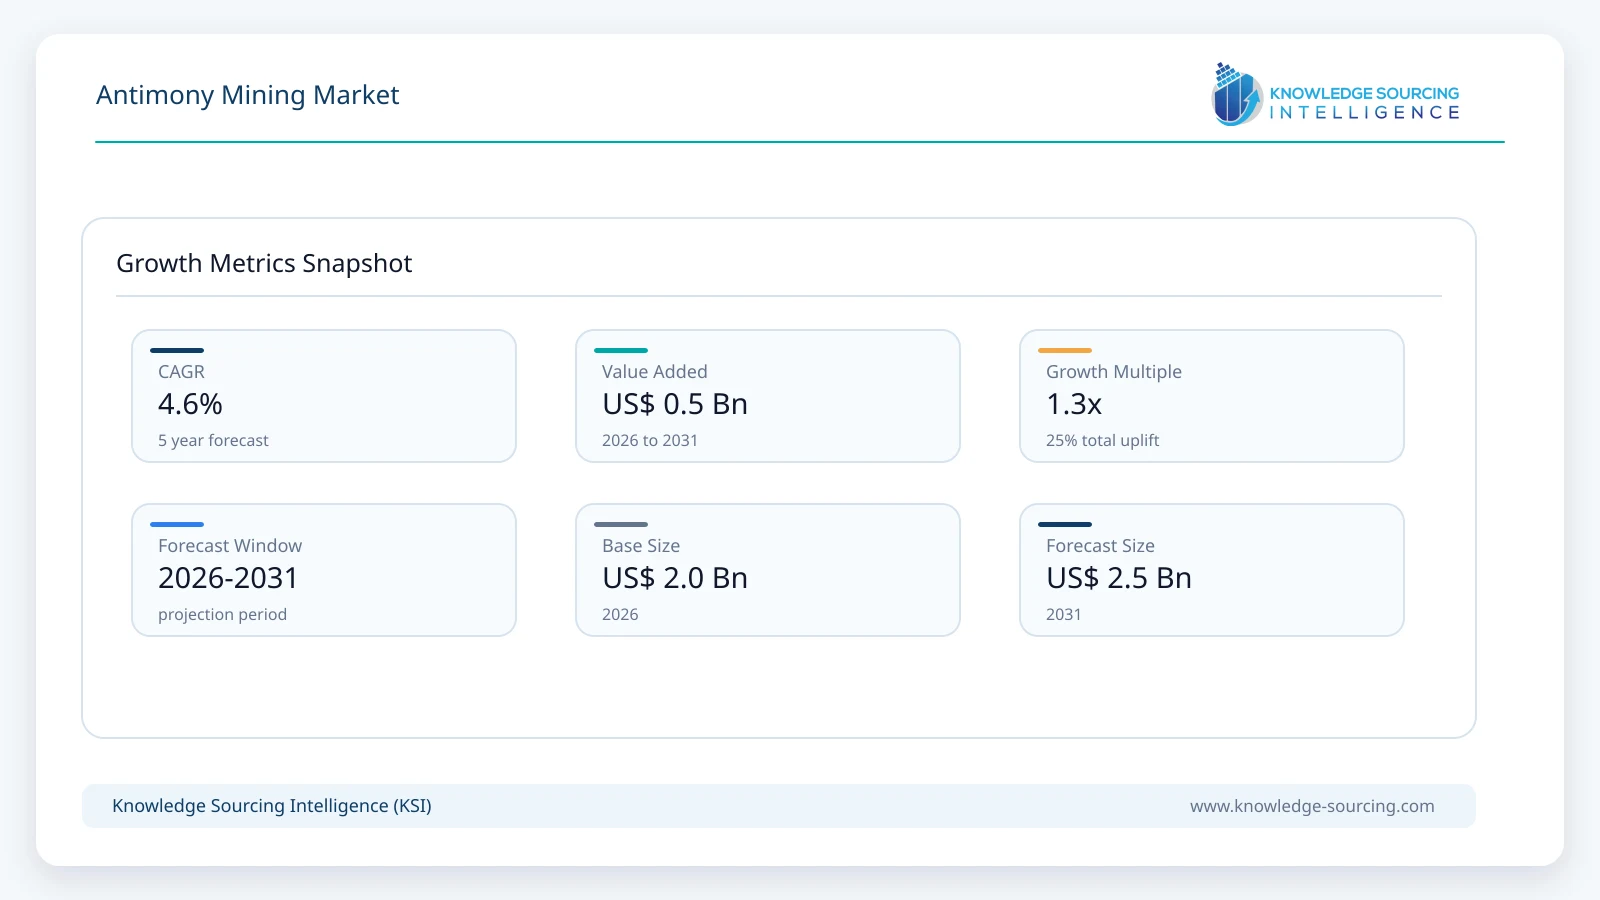
The global Antimony Mining Market is projected to grow from USD 2.0 billion in 2026 to USD 2.5 billion by 2031, registering a CAGR of approximately 4.6% during the forecast period.
Highlights:
- 1Antimony ore and concentrates account for an estimated 58% of 2026 mine-origin value.
- 2Flame-retardant formulations remain the leading application for newly mined antimony.
- 3Electronics represents an estimated 33% of 2026 end-user-linked demand.
- 4Asian mining districts remain the principal source of primary antimony supply.
- 5North American projects are advancing domestic ore extraction and product qualification.
- 6Gold-antimony co-production and processing access strongly influence project economics.
Antimony mining includes extracting antimony-bearing ore and recovering saleable antimony content through mine-site concentration and qualifying integrated primary conversion. Stibnite is the principal ore mineral, but antimony also occurs with gold, lead, zinc and mercury; the recoverable metal content and the selected processing route therefore vary substantially between mines. Commercial mine output reaches buyers as concentrates, ore-derived compounds, metal-bearing feed or other primary products under contracts that reflect payable grade and impurity penalties.
China, Russia and Tajikistan remain central to mined supply. Hunan Gold operates antimony-bearing assets in China, while Tajik production involves Anzob and the Konchoch complex. In Australia, Alkane Resources operates the Costerfield gold-antimony mine and Larvotto Resources has commenced supplying antimony concentrate from Hillgrove. United States Antimony has resumed mining at Stibnite Hill in Montana; Perpetua Resources is developing the substantially larger Stibnite Gold Project in Idaho, rather than delivering current mine output from that project.
Commercial antimony is produced primarily from stibnite, a sulfide mineral that often requires flotation or gravity concentration before smelting or chemical conversion. Complex deposits can carry arsenic, mercury or precious metals, making mineralogy and concentrate specifications decisive for recovery rates and saleable value. Antimony extracted alongside gold may remain economic at different metal prices from a standalone antimony operation because shared mining costs can be supported by another revenue stream.
At the Costerfield mine, Alkane Resources reported 396 tonnes of antimony production during the September 2026 quarter, demonstrating the importance of established gold-antimony operations. Larvotto Resources reached first production and shipment milestones at its Hillgrove mine in 2026. Both projects are Australian examples of processing infrastructure translating mineral inventory into commercial concentrate. By contrast, Perpetua Resources is constructing access, power and accommodation infrastructure at Stibnite; its prospective output cannot be counted as production before commissioning.
Antimony trioxide and antimony-bearing alloys connect mine supply to downstream buyers, but the economics differ across the value chain. A miner receiving concentrate revenue does not also earn the full selling price of an independently operated trioxide or alloy plant. When producers control multiple stages, sale values require careful attribution to the original mined antimony, particularly where imported concentrate or recycled feed shares the same equipment.
Market Trends
New Supply Routes Are Being Built Around Existing Processing Assets
Australia has moved beyond announcements into shipments: Larvotto’s Hillgrove operation produced its first concentrate in September 2026 and dispatched material in October. Costerfield supplies antimony alongside gold through an established underground mine and processing circuit. These assets can offer buyers an alternative origin without waiting for a wholly new mining district, although shipment schedules and concentrate quality still determine how much dependable supply they provide.
In the United States, United States Antimony restarted mining at Stibnite Hill, while Perpetua’s much larger Idaho project remains under construction. The difference matters for procurement: near-term output can enter blending and refining circuits, whereas a permitted development contributes to longer-term supply planning only after capital work, mine commissioning and metallurgical qualification.
Export Licensing Is Reshaping Concentrate and Refined-Product Flows
China’s export licensing requirements for antimony ores, metal and compounds, effective from September 2024, exposed the distinction between where mineral is mined and where material is finally refined. Export documentation and eligible end uses have consequently become additional dimensions of supplier selection.
The IEA has documented widening export controls and regional price divergence across strategic minor minerals. For mining companies, higher spot quotations do not always translate into equivalent realized revenue: freight, treatment charges, financing, licensed destinations and payable-content terms can absorb part of the price benefit. Buyers increasingly evaluate refining access together with mine origin.
Mine Plans Are Becoming More Dependent on Metallurgical Recovery
Antimony-bearing gold deposits create processing decisions that differ from conventional single-metal mining. Operators must balance gold recovery against the grade, mass pull and saleability of antimony concentrate, and certain impurities can trigger stringent off-taker limits. Alkane’s Costerfield reserve statements disclose separate grades for gold and antimony, making the project’s resource economics more transparent than a simple ore-tonnage announcement.
Perpetua’s July 2026 pilot-plant initiative with the U.S. Army and Idaho National Laboratory is intended to test production of high-quality antimony trisulfide from Stibnite material. That work is a qualification step, not evidence of commercial mine production. Product specifications and process reproducibility are increasingly important where security-related customers require defined material performance.
Antimony in Photovoltaic Glass Is Widening the Demand Discussion
Antimony compounds are used in some photovoltaic glass formulations to improve optical performance and glass quality. Research published in Solar Energy Materials and Solar Cells in January 2026 examined potential material constraints as photovoltaic installations expand. This is a different use from antimony in semiconductor devices and must not be conflated with growth in electronic-chip fabrication.
Future demand is sensitive to formulation decisions. Glassmakers can adjust fining chemistry, improve recovery of glass cullet or redesign processes to reduce virgin input. Mining forecasts therefore need to distinguish established antimony-containing glass production from theoretical demand under maximum photovoltaic deployment assumptions.
Antimony Mining Market Segment Analysis
By Type
Antimony Ore
Antimony ore and concentrates lead the Type category under the first-commercial-sale classification. This category includes mine-origin antimony that is sold for further treatment rather than converted into a downstream product within the same integrated producer. Concentrate marketing depends on contained antimony, grade, payable recovery and treatment deductions; two shipments with identical wet tonnage can carry very different commercial value.
The segment is projected to reach approximately USD 1.40 billion by 2031. Production from established Chinese, Russian and Tajik operations remains material, while Hillgrove and emerging North American supply provide incremental diversification. Higher downstream processing does not remove the need for commercially marketable ore and concentrates, particularly where smelters buy feed from multiple mining groups.
By Application
Flame Retardants
Flame-retardant applications remain the largest destination for primary antimony, with an estimated 42% share in 2026. Antimony trioxide works as a synergist in specified halogen-containing systems used in plastics, cable insulation and selected textile treatments. Mine demand depends on the total antimony chemical requirement within these formulations rather than on the value of the finished polymers or the selling price of the additive package.
Through 2031, mine-origin material allocated to flame retardants retains scale even as non-antimony alternatives and formulation changes constrain some applications. Electrical safety specifications and the installed base of existing formulations support continuity, but they do not imply that every new electronic product contains antimony.
By End-User Industry
Electronics
Electronics manufacturers use antimony indirectly through flame-retardant housings, connectors, cables and selected specialty materials, creating a broad but heterogeneous demand channel. The purchasing channel combines several different uses. It is not equivalent to the much smaller quantity of antimony used as a semiconductor dopant; most demand linked to electronics reaches manufacturers through chemical and materials suppliers.
The modeled value assigned to electronics rises to USD 875 million in 2031. The relevant upstream indicator is antimony input into qualified formulations, rather than the total growth rate of electronics shipments.
Market Drivers
Supply Security Is Increasing the Value of Alternative Mine Origins
Import-dependent industrial buyers have become more sensitive to the location of the mine, the processing plant and the jurisdiction controlling exports. Chinese export licensing and heavily concentrated production can interrupt access even when geological reserves exist elsewhere. Australia’s operating gold-antimony mines and planned North American capacity therefore carry procurement significance beyond their immediate output volumes.
Offtake agreements, product qualification and transport arrangements determine how quickly new feed can replace a constrained supplier. Secure origin may justify long-term contracts, but mine operators still need competitive payable terms.
Fire-Safety Specifications Sustain Consumption of Antimony Chemicals
Antimony trioxide remains a well-established synergist in certain halogenated flame-retardant formulations, especially where manufacturers have qualified materials for regulated electrical and industrial uses. Changing an additive can require repeat testing of fire performance, processing behavior and product durability. These qualification costs support continued demand from installed product families.
Mine demand follows net consumption after substitution and recovery rather than final resin sales. Producers benefit most when they can provide consistent impurity control and long-term feed availability.
Gold-Antimony Deposits Improve the Economics of Selected Projects
Costerfield and Stibnite illustrate how gold can share development and operating expenditure with antimony. The contribution of precious metals may finance ore access, underground development or site infrastructure that antimony alone could not support. This can make gold-antimony mines comparatively resilient when antimony pricing falls from temporary peaks.
The benefit is project-specific because metallurgy, recovery and concentrate marketing determine whether both metals can be realized. Mineral resources do not automatically convert into annual output. Technical studies, reserve conversion and commercial processing evidence remain essential before assigning new tonnage to the supply forecast.
Photovoltaic Glass Offers a Distinct Materials-Demand Channel
Certain solar-glass production methods use antimony-based fining agents to improve glass quality. Greater photovoltaic manufacturing activity can increase demand for those formulations, particularly when specialized optical requirements limit immediate changes to the process. This channel operates through glass plants rather than the semiconductor content of a solar cell.
Demand is nevertheless constrained by reformulation and recovery of recycled glass. Primary miners will capture durable incremental demand only when net antimony consumption rises after these offsets. The distinction keeps photovoltaic demand from being modeled as a direct multiple of solar installation growth.
Government Support Is Helping Advance Difficult Domestic Projects
The U.S. Export-Import Bank approved a financing package for Perpetua’s Stibnite project in May 2026, reflecting the strategic value attached to domestic antimony alongside gold. Financing access can accelerate preparatory construction, engineering and procurement at capital-intensive projects that face a long interval before first sales.
New mine output enters the market only after facilities are built and product is qualified. Even so, credible financing reduces one of the major obstacles to a geographically diversified antimony industry.
Market Restraints
Ore Complexity Can Reduce Recovery and Payable Value
Antimony mineralization is frequently associated with arsenic, mercury, gold and other sulfide minerals. The resulting concentrate can require flotation optimization, selective treatment or specialized smelting. More antimony in a resource does not necessarily mean a proportional increase in recovered metal or in the value a buyer will pay.
Metallurgical testing and routine quality controls add time and cost, especially for new projects seeking dependable offtake outside their traditional refining networks.
Environmental Permitting and Legacy Mine Rehabilitation Raise Costs
Sulfide-ore extraction involves water management, tailings storage, dust control and the treatment of antimony-bearing wastes. Some deposits also contain mercury or arsenic, creating additional handling and long-term monitoring obligations. Rehabilitation requirements can be material where a project reopens a historical mining area with existing contamination.
Mine design and environmental compliance affect capital timing as well as ongoing costs. Perpetua’s Stibnite redevelopment involves substantial infrastructure and restoration work before commercial production. A favorable commodity price cannot eliminate these engineering and regulatory obligations.
Smelting Concentration Limits the Benefit of Geographic Mine Diversity
A mine can be located outside China and remain commercially dependent on Chinese metallurgical capacity. Antimony concentrates are not always interchangeable: differences in mineralogy, sulfur content and impurity profile influence the suitable refining route. Small mines may lack the throughput needed to justify a standalone smelter.
Refining bottlenecks can lengthen shipping routes and delay material acceptance. Buyers assessing a non-Chinese ore source must therefore verify the whole conversion route, rather than assuming that a change in country of extraction creates an independent finished-product supply chain.
Price Volatility Complicates Mine Investment Decisions
Antimony quotations rose sharply following export restrictions in 2024 and 2025, but prices for small-volume strategic minerals can respond strongly to trading disruptions and changes in available stocks. Development studies based on exceptional spot prices may not remain robust through a full commodity cycle.
Operators need recovery, capital and operating assumptions that withstand a lower realized selling price. The problem is acute for greenfield mines without an established plant or precious-metal credits. Long-term contract structures can reduce some exposure but often contain payability and price-adjustment provisions.
Material Substitution and Recycling Limit Primary Demand Growth
Antimony is important to selected flame-retardant and lead-alloy specifications, yet aluminum hydroxide, phosphorus-containing chemistries and alternative alloying systems can replace it in some uses. Substitution depends on testing costs and performance, so the effect is gradual and uneven across applications.
Secondary lead smelting also recovers antimonial lead from used batteries, supplying material without new antimony mining. Higher recycling efficiency or changes in battery chemistry can weaken the relationship between finished-product demand and mine production, limiting the case for aggressively increasing primary output.
Regional Outlook
Asia Pacific
Asia Pacific is estimated to account for 63% of mine-origin antimony value in 2026. China remains the largest individual mining base, while Tajikistan, Myanmar and smaller Asian producers contribute substantial additional output. China’s established mining and chemical-processing networks support the region’s position, but treating all Asian mine production as Chinese would obscure the importance of cross-border concentrate flows.
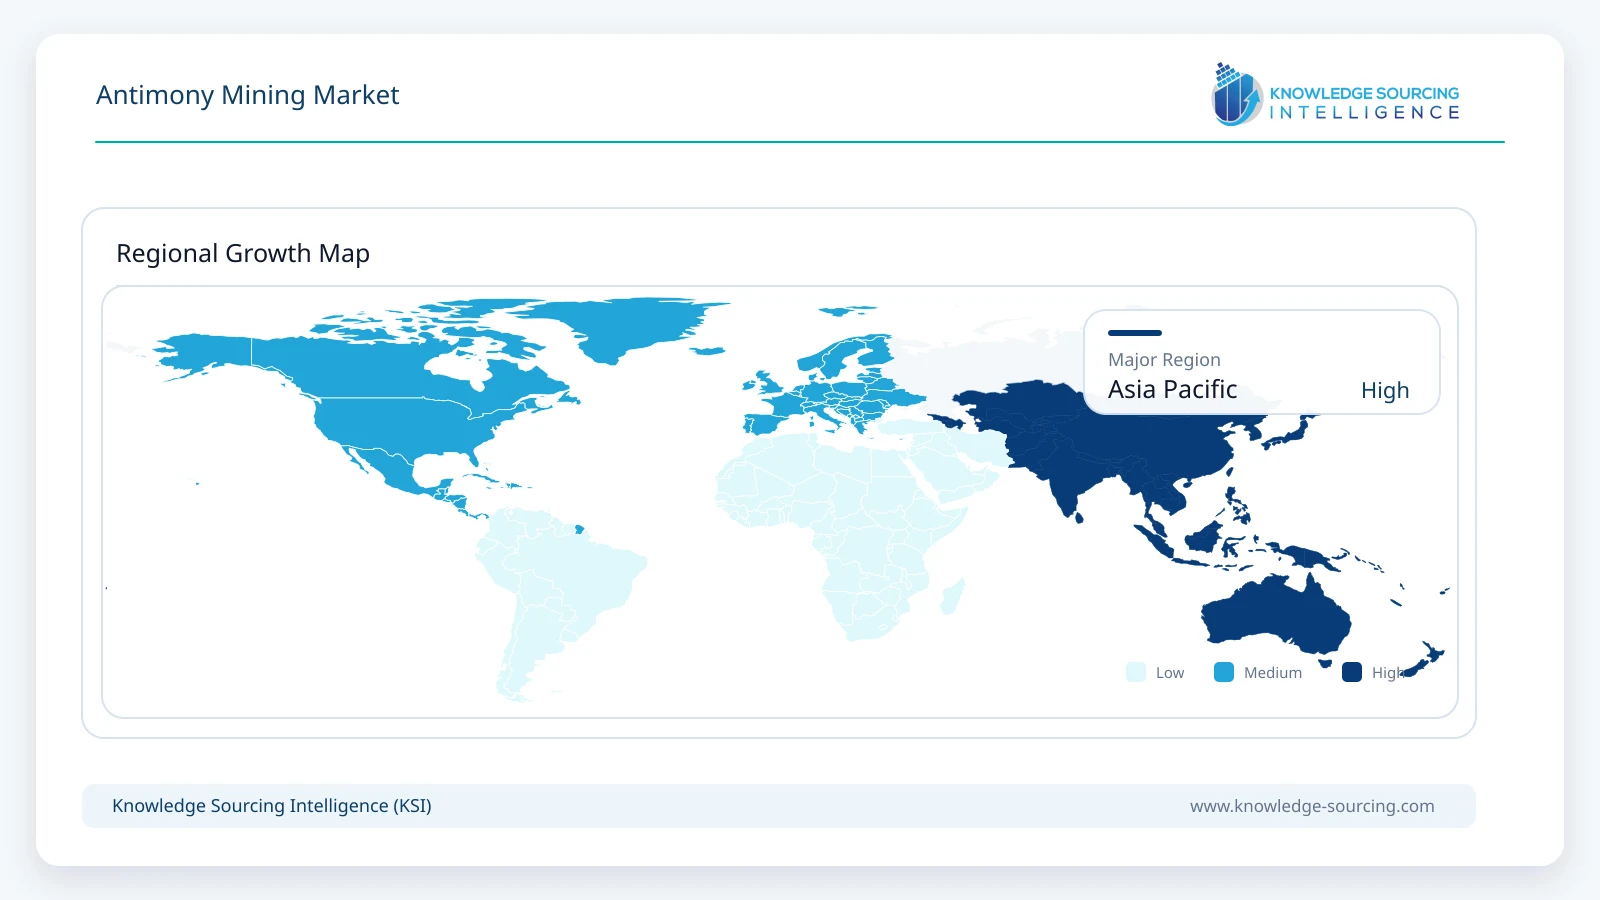
The regional value is projected to reach approximately USD 1.475 billion in 2031, equivalent to a 59% global share. Australian additions from Costerfield and Hillgrove diversify production within the wider region, while China’s ore grades, export controls and refining demand influence the commercial value of new supply. Asia Pacific remains dominant even as North America adds capacity more rapidly from a low starting base.
North America
North American mined antimony begins from a narrow production base, with a modeled 2026 global share of approximately 1%. Mexico has a small established contribution, and United States Antimony has restarted ore extraction in Montana. The region’s mineral potential is larger than its current market position, but licensed processing routes and commercially available feed remain limited.
North America is the fastest-growing region in the modeled outlook, with value rising to approximately USD 200 million by 2031, or 8% of the global total. This prospective shift depends heavily on delivery of larger U.S. projects such as Perpetua’s Stibnite development and on the conversion of resources into saleable material. Delays in commissioning or metallurgical qualification would materially reduce the projected expansion.
Competitive Landscape
China’s Hunan Gold and Tibet Huayu Mining represent established mine-linked antimony supply, while Russia and Tajikistan remain significant producing jurisdictions served by different ownership and export channels. The number of mine operators with publicly documented antimony output is smaller than the broader universe of traders, refiners and chemical formulators. Supplier comparisons must therefore focus on producing deposits, recovered grades and marketable output rather than chemical distribution reach.
Alkane Resources combines existing underground gold-antimony production with resource-extension work at Costerfield. Larvotto Resources has moved Hillgrove through commissioning and initial concentrate shipments, providing a newer Australian source. United States Antimony operates both mining and processing activities, but its mine-origin production should be distinguished from output produced using purchased external feed.
Perpetua Resources occupies a different competitive position as a financed mine developer advancing site infrastructure and antimony qualification work. Project optionality is important for future North American supply but is not equivalent to present market share. Other relevant mine participants include Anzob’s operator Comsup Commodities, TALCO Gold and Turkish antimony miner ODA?. Across the field, the durable differentiators are measured production, access to compatible smelting, impurity management, commercially qualified products and dependable offtake.
Recent Developments
October 2026: Alkane Resources reported 396 tonnes of antimony output from Costerfield for the September quarter, providing current production evidence rather than an announced capacity target.
October 2026: Alkane Resources announced drilling results at Nagambie confirming continuity of gold-antimony mineralization; this expands exploration optionality without creating immediate mine supply.
October 2026: Larvotto Resources announced the first shipment of antimony concentrate from its Hillgrove mine in New South Wales, marking a transition from commissioning to commercial deliveries.
September 2026: Perpetua Resources reported progress on site access, worker accommodation, power infrastructure and exploration at the Stibnite Gold Project; the project remained in development.
August 2026: United States Antimony reported continued mining at Stibnite Hill in Montana following its spring restart, with ore delivered from the mine for subsequent processing.
July 2026: Perpetua Resources announced the opening of a pilot facility with the U.S. Army and Idaho National Laboratory to evaluate production of antimony trisulfide from Stibnite material.
Market Outlook
Additional Australian and North American tonnage is expected to enter a market still dependent on producers in China, Russia and Tajikistan. The important transition is not a rapid disappearance of supply concentration but a gradual increase in qualified sources with different operating and political risks. The mining companies able to combine sustained recovery with saleable concentrate specifications are better placed to retain customers than projects relying mainly on resource size.
Industrial demand should continue to draw on antimony for flame retardants, lead-acid battery alloys and selected glass technologies, while changes in formulations and recycling temper growth in virgin requirements. Procurement practices may place greater weight on traceable origin and complete refining routes, particularly for defense and critical infrastructure users.
Project execution remains the central determinant of the forecast beyond established mines. Site construction, reserve conversion, treatment capacity, transport and environmental obligations can alter the timing of supply additions by years. The market is likely to reward producers that demonstrate actual shipments and responsible operating performance rather than simply announcing exposure to a strategically important mineral.
Antimony Mining Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.0 billion |
| Total Market Size in 2031 | USD 2.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, End-Use Industry, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Antimony Ore
Antimony Trioxide
Antimony Alloys
Others
By Application
Flame Retardants
Lead-Acid Batteries
Semiconductors
Solar Panels
Others
By End-User Industry
Electronics
Automotive
Construction
Energy
Others
By Geography
North America
United States
Mexico
Canada
South America
Bolivia
Brazil
Argentina
Others
Europe
Russia
Türkiye
United Kingdom
Germany
France
Italy
Others
Middle East and Africa
Iran
Saudi Arabia
UAE
Others
Asia Pacific
China
Tajikistan
Myanmar
Australia
Kazakhstan
Kyrgyzstan
India
Japan
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.2. Market Overview
2.3. Market Definition
2.4. Scope of the Study
2.5. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Supply Security Is Increasing the Value of Alternative Mine Origins
3.1.2. Fire-Safety Specifications Sustain Consumption of Antimony Chemicals
3.1.3. Gold-Antimony Deposits Improve the Economics of Selected Projects
3.1.4. Photovoltaic Glass Offers a Distinct Materials-Demand Channel
3.1.5. Government Support Is Helping Advance Difficult Domestic Projects
3.2. Market Restraints
3.2.1. Ore Complexity Can Reduce Recovery and Payable Value
3.2.2. Environmental Permitting and Legacy Mine Rehabilitation Raise Costs
3.2.3. Smelting Concentration Limits the Benefit of Geographic Mine Diversity
3.2.4. Price Volatility Complicates Mine Investment Decisions
3.2.5. Material Substitution and Recycling Limit Primary Demand Growth
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Stibnite and Complex-Ore Beneficiation
4.2. Flotation and Concentrate Upgrading
4.3. Smelting, Oxidation and Alloy Conversion
4.4. Mine-Waste and Impurity Management
5. ANTIMONY MINING MARKET BY TYPE
5.1. Introduction
5.2. Antimony Ore
5.3. Antimony Trioxide
5.4. Antimony Alloys
5.5. Others
6. ANTIMONY MINING MARKET BY APPLICATION
6.1. Introduction
6.2. Flame Retardants
6.3. Lead-Acid Batteries
6.4. Semiconductors
6.5. Solar Panels
6.6. Others
7. ANTIMONY MINING MARKET BY END-USER INDUSTRY
7.1. Introduction
7.2. Electronics
7.3. Automotive
7.4. Construction
7.5. Energy
7.6. Others
8. ANTIMONY MINING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Mexico
8.2.3. Canada
8.3. South America
8.3.1. Bolivia
8.3.2. Brazil
8.3.3. Argentina
8.3.4. Others
8.4. Europe
8.4.1. Russia
8.4.2. Türkiye
8.4.3. United Kingdom
8.4.4. Germany
8.4.5. France
8.4.6. Italy
8.4.7. Others
8.5. Middle East & Africa
8.5.1. Iran
8.5.2. Saudi Arabia
8.5.3. UAE
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Tajikistan
8.6.3. Myanmar
8.6.4. Australia
8.6.5. Kazakhstan
8.6.6. Kyrgyzstan
8.6.7. India
8.6.8. Japan
8.6.9. South Korea
8.6.10. Taiwan
8.6.11. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Hunan Gold Corporation Limited
10.2. Tibet Huayu Mining Co., Ltd.
10.3. Alkane Resources Limited
10.4. Larvotto Resources Limited
10.5. United States Antimony Corporation
10.6. Perpetua Resources Corp. (development stage)
10.7. Comsup Commodities Inc. (Anzob LLC)
10.8. TALCO Gold LLC
10.9. ODA? Elektrik Üretim Sanayi Ticaret A.?.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected market value of antimony mining by 2031?
The Antimony Mining Market is projected to reach USD 2.5 billion by 2031.
What is the compound annual growth rate for antimony mining?
The Antimony Mining Market will register a CAGR of approximately 4.6% (2026-2031).
Which application leads demand for newly mined antimony?
Flame-retardant formulations remain the leading application.
Which region remains the principal source of primary antimony?
Asian mining districts remain the principal supply source.
What percentage of end-user demand does electronics represent?
Electronics represents an estimated 33% of 2026 end-user demand.
What key factor influences antimony mining project economics?
Gold-antimony co-production strongly influences project economics.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Antimony Mining Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/antimony-mining-market