
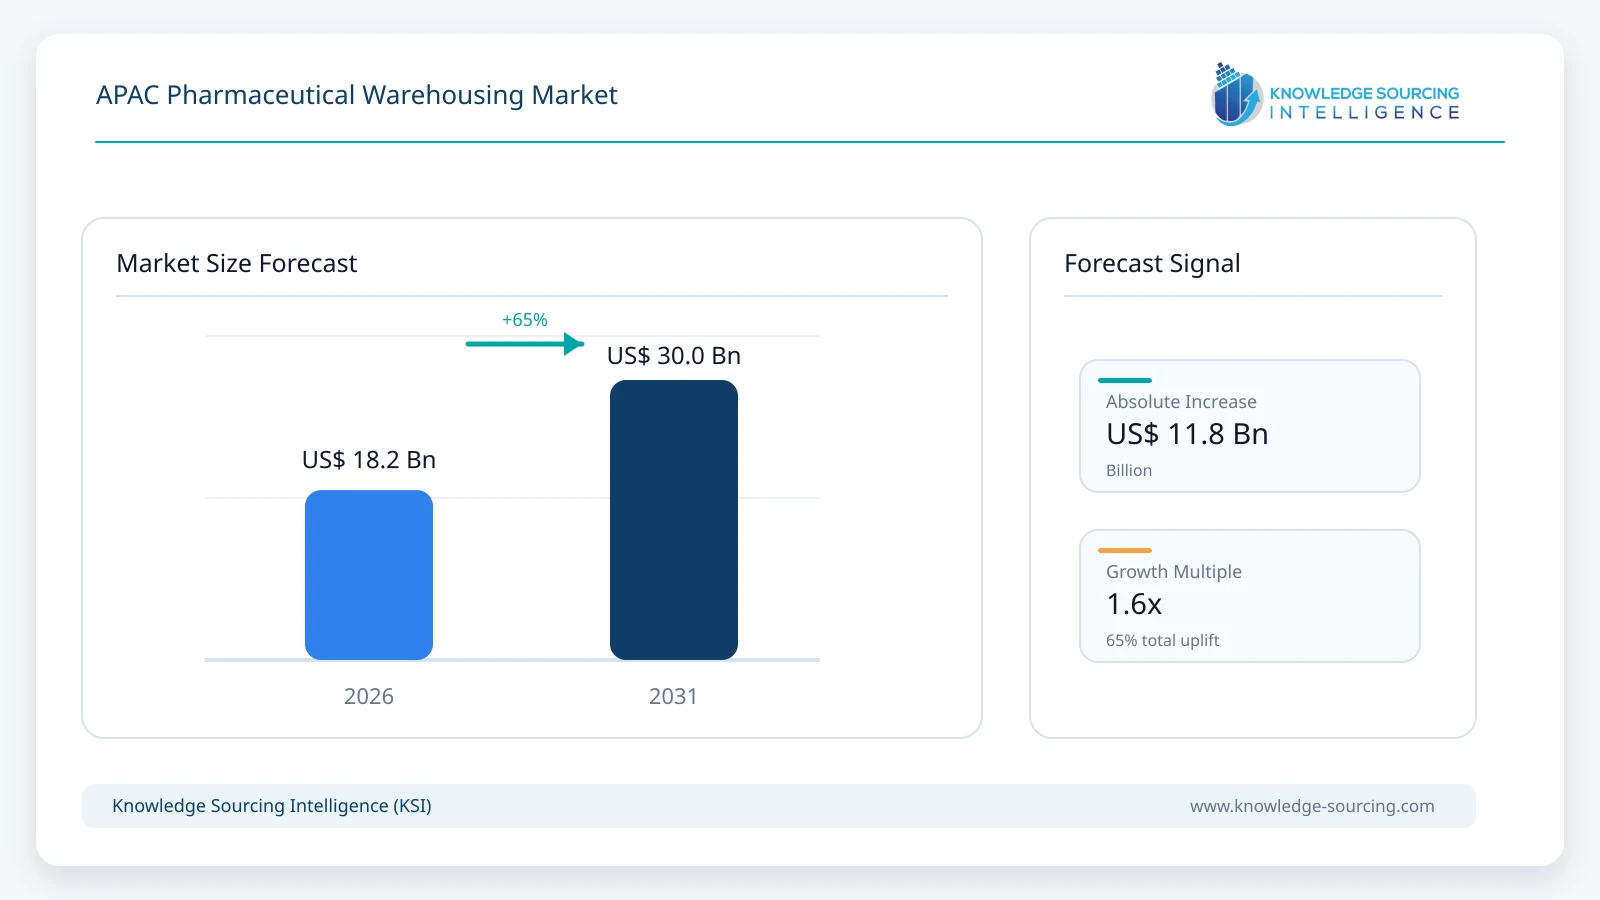
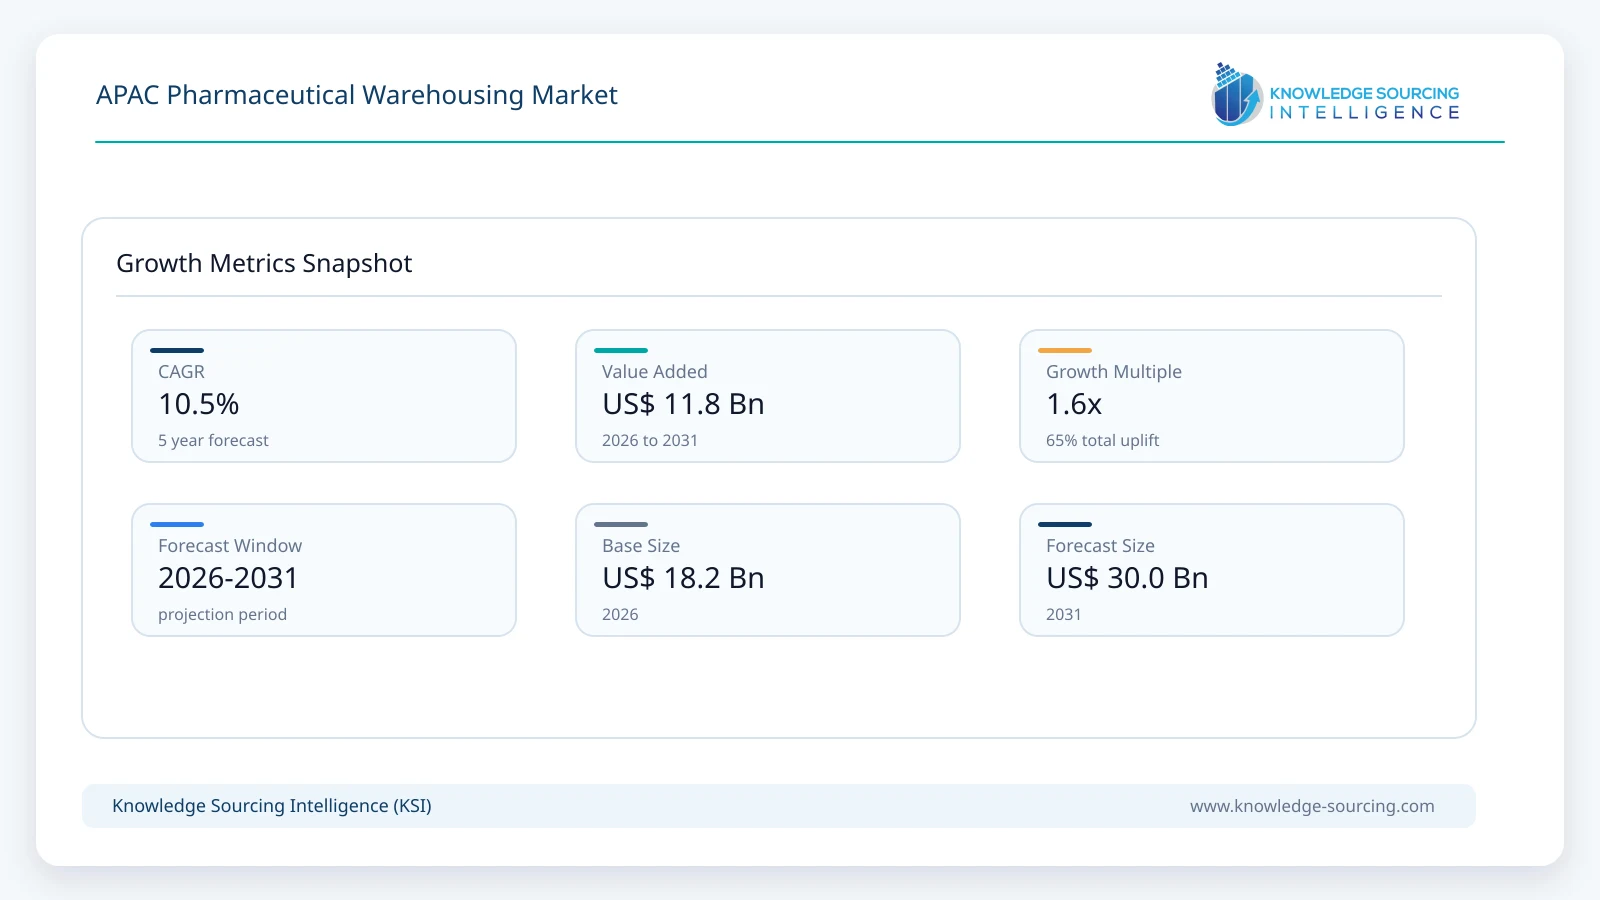
The APAC pharmaceutical warehousing market is projected to increase from USD 18.2 billion in 2026 to USD 30.0 billion in 2031, representing a CAGR of 10.5% during the forecast period.
Highlights:
- 1Ambient storage accounts for approximately 49% of APAC pharmaceutical warehousing revenue in 2026.
- 2Third-party logistics warehousing represents about 63% of market value as outsourcing expands.
- 3Biologics and vaccines generate approximately 39% of warehousing revenue in 2026.
- 4China contributes about 34% of regional pharmaceutical warehousing demand in 2026.
- 5Ultra-cold storage is the fastest-growing temperature category as advanced therapies expand.
Market Overview
APAC contains several of the world's largest pharmaceutical production and consumption markets, creating a broad base of inventory that must be stored under regulated conditions. China's National Bureau of Statistics reported RMB 2.487 trillion of operating revenue for medicine manufacturing enterprises above designated size in 2025. Japan's Ministry of Health, Labour and Welfare reported pharmaceutical production of JPY 10.25 trillion in 2024, while India's Department of Pharmaceuticals reported FY2024-25 pharmaceutical turnover of INR 4.72 lakh crore. South Korea's Ministry of Food and Drug Safety reported record pharmaceutical production of KRW 33.8 trillion in 2025, with exports exceeding USD 10 billion for the first time. The scale of these industries supports recurring warehouse demand even before accounting for imported medicines, clinical-trial stock, and regional redistribution.
The quality requirement is as important as storage volume. Pharmaceutical warehouses must segregate released, quarantined, returned, and rejected stock; maintain specified temperature and humidity conditions; document excursions; control access; and preserve product traceability throughout receipt, storage, and dispatch. World Health Organization guidance treats storage and distribution as regulated quality activities rather than conventional real-estate functions. This raises the economic value of validated facilities with redundant power, mapped temperature zones, calibrated monitoring, warehouse management systems and documented quality processes. Specialist networks are already extensive: Zuellig Pharma operates more than 70 warehouses across Asian markets, while CEVA Logistics supports healthcare operations across 19 APAC countries and operates a 6,500-square-meter healthcare hub in Singapore.
Warehousing architecture is also changing. Large regional hubs in Singapore, Shanghai, Seoul, Hyderabad and other gateways are increasingly paired with national distribution centers and smaller local depots. This allows pharmaceutical companies to centralize slower-moving inventory while keeping critical or high-turnover products closer to hospitals, pharmacies and clinical sites. The operating model is particularly important for biologics, vaccines and specialty medicines because every additional transfer creates temperature, handling and documentation risk. As a result, logistics contracts are moving toward integrated storage, transport, value-added services and digital visibility rather than stand-alone pallet storage.
Market Dynamics
Biologics, Vaccines and Specialty Medicines Increase Temperature-Controlled Storage Intensity
APAC pharmaceutical production is shifting toward products with more demanding storage profiles. South Korea reported that biopharmaceuticals accounted for the majority of its pharmaceutical exports in 2025, while India remains a major global supplier of vaccines and is expanding biosimilar and complex-injectable capacity. These products create higher warehousing revenue per pallet because operators must provide qualified cold rooms, excursion management, continuous monitoring, validated handling procedures and contingency power. The commercial effect extends beyond 2-8°C facilities: selected products require frozen or ultra-low-temperature storage, while clinical-trial materials may need multiple temperature zones within the same depot.
GDP Compliance and Outsourcing Favor Larger Specialist Warehousing Networks
Pharmaceutical manufacturers increasingly outsource storage where external providers can demonstrate validated infrastructure, trained personnel and documented quality systems across multiple markets. Maintaining these capabilities internally can be expensive because warehouses require mapping, calibration, backup systems, security, standard operating procedures, audit readiness and specialized handling. The result is a shift toward healthcare-focused third-party logistics providers that can combine storage with transport, secondary packaging and returns management. CEVA's APAC healthcare network, UPS Healthcare's expansion in Singapore, Kuehne+Nagel's healthcare facilities and Nippon Express's growing GDP-certified footprint illustrate how global operators are building dedicated life-sciences capability rather than treating pharmaceuticals as general cargo.
Pharmaceutical Manufacturing Growth Sustains New Warehouse Capacity in India and South Korea
India and South Korea are important growth markets because manufacturing, exports and clinical activity are expanding simultaneously. India's pharmaceutical turnover reached INR 4.72 lakh crore in FY2024-25, while exports were INR 2.46 lakh crore. South Korea exported more than USD 10 billion of pharmaceuticals in 2025 and recorded its highest production value on record. Growth in finished formulations, biosimilars, vaccines and contract manufacturing increases both manufacturing-site storage and downstream distribution requirements. New logistics investment is therefore concentrating around industrial clusters, airports and major consumption centers where warehouses can serve domestic distribution and export staging from the same network.
Capital Intensity, Power Reliability and Regulatory Fragmentation Remain Constraints
The main restraint is the cost of building and operating validated multi-temperature facilities. Refrigeration, insulation, redundant power, calibrated monitoring, fire protection, security, automation and quality staffing raise capital and operating costs well above conventional warehouses. The challenge is more pronounced in markets with high electricity costs, unstable power or dispersed island geographies. APAC also lacks a single regulatory framework: operators must manage national requirements alongside WHO guidance, customer quality agreements and product-specific storage conditions. This favors large providers with regional quality systems, but it can slow the development of compliant capacity outside major metropolitan and manufacturing hubs.
Segment Analysis
By Temperature Range - Ambient Storage
Ambient storage remains the largest individual temperature category in 2026 because most tablets, capsules, over-the-counter medicines and many active pharmaceutical ingredients can be stored under controlled room-temperature conditions. Modern pharmaceutical ambient warehouses still require temperature mapping, humidity control, access restrictions, segregation and traceability; they are not equivalent to general dry storage. The segment grows steadily as prescription volumes and regional distribution expand, but its share gradually declines because refrigerated, frozen and ultra-cold categories carry higher service value and are growing more rapidly. Multi-temperature facilities are therefore increasingly designed with large ambient zones alongside smaller but more capital-intensive cold rooms.
By Product Type - Biologics and Vaccines
Biologics and vaccines represent the largest high-value product group within pharmaceutical warehousing. Their importance is driven by biosimilars, monoclonal antibodies, insulin, vaccines and other temperature-sensitive therapies that require controlled conditions through storage and distribution. These products also create demand for validated packaging preparation, temperature-data review, quarantine procedures and faster exception handling. The category accounts for an estimated 39% of APAC warehousing revenue in 2026 even though its physical volume is lower than the volume of conventional small-molecule medicines. Cell and gene therapy products remain much smaller, but they are expanding the market for frozen and ultra-low-temperature depots and clinical-trial logistics.
By Service Model - Third-Party Logistics Warehousing
Third-party logistics warehousing is the dominant service model because pharmaceutical companies can obtain validated capacity without owning every facility in the distribution network. Large 3PL providers combine storage with customs support, domestic distribution, secondary packaging, labelling, inventory control and returns processing. The value proposition is strongest for multinational companies operating across several APAC markets, where maintaining separate in-house quality systems and warehouse infrastructure can be inefficient. Outsourcing also allows manufacturers to add capacity more quickly when new products launch or demand shifts between countries. Dedicated in-house warehouses remain important for major manufacturers and strategic production sites, while fourth-party logistics services are growing around network design and control-tower management.
By Country - China
China is the largest country market, supported by the scale of its pharmaceutical manufacturing base, population, hospital network and domestic distribution system. Medicine manufacturing enterprises above designated size generated operating revenue of approximately RMB 2.49 trillion in 2025. Pharmaceutical storage demand is concentrated around coastal manufacturing and consumption hubs such as Shanghai, Jiangsu, Zhejiang, Guangdong and Beijing, while national distribution requires a much broader network of regional and provincial facilities. The market includes large domestic distributors as well as global logistics providers operating GDP-certified locations in Shanghai and other major gateways. The shift toward biologics, specialty drugs and digitally monitored distribution increases the value of compliant temperature-controlled capacity even when conventional medicine volumes grow more slowly.
Technology and Market Indicators
Indicator | Latest Development | Market Impact |
Regional distribution scale | Zuellig Pharma operates more than 70 warehouses across Asian markets and serves all major temperature regimes. | Demonstrates the scale required to support hospital, pharmacy and specialty-product distribution. |
Singapore healthcare hub | UPS Healthcare opened an 11,500 m² facility in Tuas in 2025, doubling its regional footprint. | Strengthens Singapore as a regional inventory and high-value healthcare logistics hub. |
India cold-chain capacity | Kuehne+Nagel opened a temperature-controlled healthcare cross-dock in Hyderabad in May 2026. | Adds compliant capacity close to one of India’s major pharmaceutical manufacturing clusters. |
APAC healthcare network | CEVA supports healthcare logistics across 19 APAC countries and operates nearly 20 patient-centric facilities in the region. | Expands integrated storage, compliance and value-added service options for multinational shippers. |
GDP-certified network | Nippon Express lists GDP-certified pharmaceutical locations across Japan, China, Korea, Taiwan, Singapore, Thailand, Indonesia, Malaysia and India. | Supports cross-border standardization of pharmaceutical handling and quality systems. |
China Market Analysis
China's pharmaceutical warehousing market is anchored by a large domestic manufacturing and consumption base rather than a single export corridor. National Bureau of Statistics data show operating revenue of roughly RMB 2.49 trillion for medicine manufacturing enterprises above the designated size in 2025. This creates substantial flows of raw materials, finished medicines and specialty products across manufacturing clusters and hospital distribution networks. Coastal regions remain the most important logistics locations because they combine production, air and sea gateways, high-income urban demand and established third-party logistics infrastructure. Global operators maintain GDP-certified capacity in Shanghai and other strategic locations, while large domestic distributors operate nationwide networks linked to hospitals and pharmacies.
Future warehouse investment is increasingly differentiated by product type. Conventional small-molecule medicines support large automated ambient distribution centers, while biologics, vaccines, clinical materials and specialty therapies require smaller but more expensive temperature-controlled zones. Continuous monitoring, serialized inventory, electronic batch traceability and quality-system integration are becoming standard requirements for large customers. The result is a two-tier market in which high-throughput general pharmaceutical distribution continues to scale, while cold-chain and specialty depots capture a rising share of capital expenditure and service revenue. Providers with both nationwide coverage and validated specialty capability are best positioned for multinational and high-value domestic contracts.
Competitive Landscape
The APAC pharmaceutical warehousing market combines global logistics groups, regionally dominant healthcare distributors and national specialists. DHL Group, UPS Healthcare, Kuehne+Nagel, Nippon Express, Kintetsu World Express, CEVA Logistics, Yusen Logistics, DB Schenker, FedEx Logistics and Maersk compete for multinational healthcare contracts through regional networks, airport-linked facilities and integrated freight forwarding. Their advantage lies in standardized quality systems, global customer relationships and the ability to connect APAC warehouses with manufacturing and consumption markets in Europe and North America.
Regional healthcare specialists remain equally important. Zuellig Pharma has one of Asia's deepest dedicated healthcare distribution networks, with more than 70 warehouses and broad hospital, clinic and pharmacy coverage. Kerry Logistics and SF Express add strong Greater China and regional distribution reach, while national operators compete through local regulatory familiarity and dense last-mile networks. Competitive differentiation increasingly depends on temperature-range breadth, quality certifications, warehouse-management technology, inventory visibility, secondary packaging capability and the ability to support product launches across multiple countries from a single regional contract.
Automation is becoming a practical differentiator rather than a technology showcase. Pharmaceutical warehouses use automated storage and retrieval, conveyor systems, scanning, warehouse control systems and digital quality records to improve inventory accuracy and reduce manual handling. However, the most valuable technology investments are those that also strengthen compliance, such as continuous temperature monitoring, audit-ready data, electronic quarantine controls and exception alerts. Providers that combine physical automation with strong quality governance can scale faster without weakening traceability as order volumes and SKU complexity increase.
Recent Developments
June 2026: DHL Supply Chain opened a 10,000-square-meter Health Logistics Hub in Icheon, South Korea, expanding specialist pharmaceutical and life-sciences storage capacity.
May 2026: Kuehne+Nagel opened a temperature-controlled healthcare airfreight cross-dock in Hyderabad, strengthening its Indian pharmaceutical logistics network.
March 2026: Zuellig Pharma opened a relocated clinical logistics depot in Misato, Japan, strengthening clinical-trial supply capability.
December 2025: CEVA Logistics and CooperVision opened a regional service center within CEVA’s Singapore healthcare hub, combining centralized inventory with specialized warehouse technology and repackaging capability.
August 2025: DHL Supply Chain opened a 5,980-square-meter medical-device distribution center in Seoul with 15-25°C controlled storage zones.
June 2025: UPS Healthcare announced an 11,500-square-meter healthcare logistics facility in Tuas, Singapore, doubling its regional healthcare footprint.
APAC Pharmaceutical Warehousing Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 18.2 billion |
| Total Market Size in 2031 | USD 30.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Temperature Range, Product Type Stored, Service Model, Country |
| Companies |
|
Market Segmentation
By Temperature Range
Ambient Storage
Cold Chain (2-8°C)
Frozen Storage
Ultra-Cold Storage
By Product Type Stored
Biologics & Vaccines
Small-Molecule Pharmaceuticals
Cell & Gene Therapy Products
Clinical Trial Materials
OTC & Consumer Health Products
By Service Model
Third-Party Logistics (3PL) Warehousing
Fourth-Party Logistics (4PL) Managed Services
Dedicated / In-House Pharmaceutical Warehousing
By Country
China
India
Japan
South Korea
Indonesia
Taiwan
Thailand
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Biologics, Vaccines and Specialty Medicines Increase Temperature-Controlled Storage Intensity
3.1.2. GDP Compliance and Outsourcing Favor Larger Specialist Warehousing Networks
3.1.3. Pharmaceutical Manufacturing Growth Sustains New Warehouse Capacity in India and South Korea
3.2. Market Restraints
3.2.1. Capital Intensity, Power Reliability and Regulatory Fragmentation Remain Constraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Warehouse Management Systems and Serialized Inventory Control
4.2. IoT Temperature and Humidity Monitoring
4.3. Automated Storage and Retrieval Systems
4.4. Ultra-Cold Storage and Validated Packaging
5. APAC PHARMACEUTICAL WAREHOUSING MARKET BY TEMPERATURE RANGE
5.1. Ambient Storage
5.2. Cold Chain (2-8°C)
5.3. Frozen Storage
5.4. Ultra-Cold Storage
6. APAC PHARMACEUTICAL WAREHOUSING MARKET BY PRODUCT TYPE STORED
6.1. Biologics & Vaccines
6.2. Small-Molecule Pharmaceuticals
6.3. Cell & Gene Therapy Products
6.4. Clinical Trial Materials
6.5. OTC & Consumer Health Products
7. APAC PHARMACEUTICAL WAREHOUSING MARKET BY SERVICE MODEL
7.1. Third-Party Logistics (3PL) Warehousing
7.2. Fourth-Party Logistics (4PL) Managed Services
7.3. Dedicated / In-House Pharmaceutical Warehousing
8. APAC PHARMACEUTICAL WAREHOUSING MARKET BY COUNTRY
8.1. China
8.2. India
8.3. Japan
8.4. South Korea
8.5. Indonesia
8.6. Taiwan
8.7. Thailand
8.8. Other APAC Markets
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. DHL Group
10.2. UPS Healthcare
10.3. Kuehne+Nagel International AG
10.4. Nippon Express Holdings, Inc. (NX Group)
10.5. Kintetsu World Express, Inc.
10.6. CEVA Logistics
10.7. Zuellig Pharma Holdings Pte. Ltd.
10.8. S.F. Holding Co., Ltd.
10.9. Yusen Logistics Co., Ltd.
10.10. DB Schenker
10.11. FedEx Logistics
10.12. A.P. Moller - Maersk
10.13. Sinotrans Limited
10.14. CJ Logistics Corporation
10.15. Royal Cargo, Inc.
10.16. Ally Logistic Property Co., Ltd.
10.17. Dimerco Express Corporation
10.18. Kerry TJ Logistics Co., Ltd.
11. RECENT DEVELOPMENTS
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Research Methodology
12.5. Abbreviations
Navigate
Trusted by the world's leading organizations











