
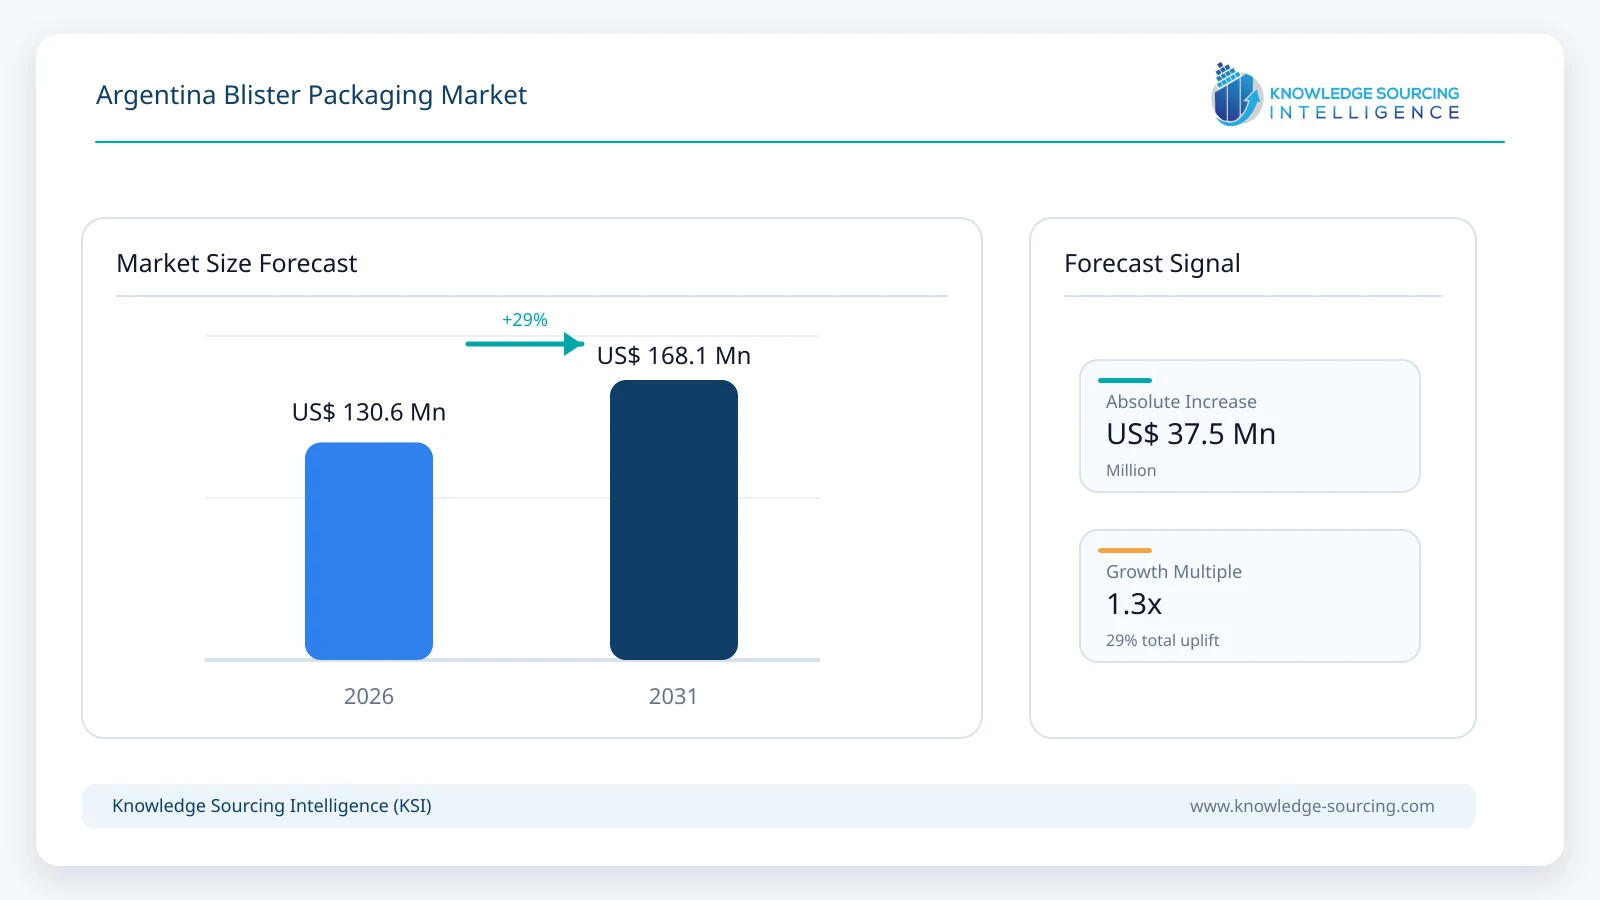
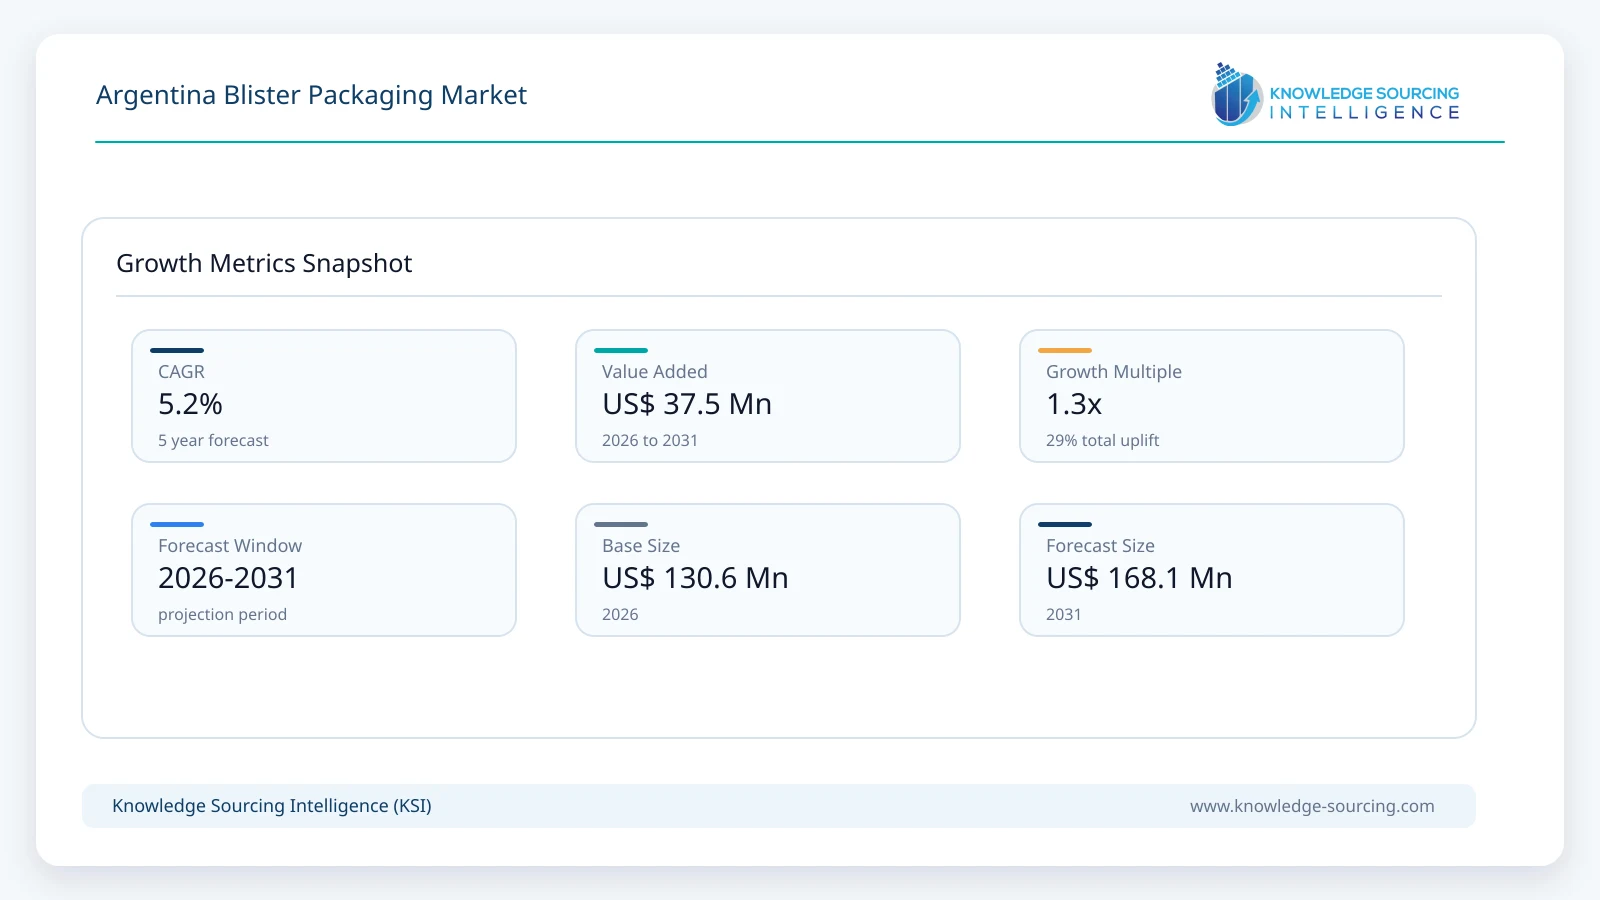
The Argentina blister packaging market is forecast to grow from USD 130.6 million in 2026 to USD 168.1 million by 2031, representing a CAGR of approximately 5.2% during the forecast period.
Highlights:
- 1Pharmaceutical and healthcare applications account for approximately 62% of Argentina blister packaging market value in 2026, supported by large domestic solid-dose manufacturing and dispensing volumes.
- 2Thermoformed blister packaging accounts for approximately 78% of market value in 2026, reflecting the installed base for PVC, PVC/PVDC and related forming structures.
- 3PVC and PVC/PVDC structures account for approximately 49% of market value in 2026, supported by broad compatibility with existing blister lines and cost-sensitive pharmaceutical production.
- 4Push-through blister formats account for approximately 45% of market value in 2026, led by prescription and over-the-counter solid-dose medicines.
- 5High-barrier pharmaceutical structures are gaining value share, particularly PCTFE laminates and cold-form aluminum used for moisture-sensitive formulations.
Argentina has a well-established pharmaceutical manufacturing base. Pfizer's Buenos Aires facility has installed capacity for 940 million tablets, 300 million coated tablets, 36 million hard capsules and 180 million soft capsules annually, while local manufacturers such as Roemmers maintain large dedicated solid-dose plants. Market-wide pharmaceutical volumes also remain substantial: Argentina recorded roughly 745 million medicine packs across ambulatory and institutional channels in 2025, and sector production entered 2026 after twelve consecutive months of year-on-year growth.
The strongest packaging demand comes from high-volume oral solid-dose products, where thermoformed PVC or PVC/PVDC structures remain common, and from moisture-sensitive formulations that require PCTFE laminates or cold-form aluminum. Non-pharmaceutical demand is more fragmented and price-sensitive, with carded, clamshell and slide blisters used for small consumer products, hardware, electrical accessories and personal-care items.
ANMAT regulation shapes pharmaceutical packaging quality, labeling and traceability, but traceability rules do not mandate blister packaging itself. The national system applies to the unit-of-sale package, while Disposition 2891/2026 requires QR or Data Matrix coding on the secondary package of medicinal products, with primary-package coding optional. The commercial implication for blister suppliers is therefore indirect: pharmaceutical manufacturers continue to require compliant primary packaging, while coding and serialization requirements are handled mainly at the secondary-packaging level.
Market Trends
Recyclable Pharma Blisters Gain Attention
Pharmaceutical packaging suppliers are commercializing polypropylene and polyester blister systems designed to reduce reliance on multi-material PVC/aluminum structures. TekniPlex Healthcare is expanding PP and PET-based blister combinations, including recyclable mid-barrier structures, while kp and Constantia have developed compatible recyclable forming and lidding systems. Adoption in Argentina will depend on product stability requirements, recycling infrastructure and qualification costs, but these technologies give local pharmaceutical manufacturers more options for sustainability-led packaging programs without requiring complete replacement of existing thermoforming lines.
Barrier Selection Becomes More Application-Specific
Packaging specifications are becoming more closely aligned with the stability profile of each drug rather than relying on one standard blister structure across a portfolio. Standard PVC remains suitable for lower-barrier applications, while PVDC coatings, PCTFE laminates and cold-form aluminum are selected where moisture or oxygen protection is more demanding. TekniPlex Argentina supplies PVC/Aclar, PVC/PVDC and cold-form aluminum structures locally, giving domestic manufacturers access to several barrier levels within established packaging platforms.
Local Pharma Production Supports Packaging Throughput
Argentina's pharmaceutical industry continued to expand production into 2026 despite weakness in parts of the wider manufacturing economy. INDEC reported that first-quarter 2026 pharmaceutical-sector revenue increased 32.7% year on year, with revenue from national production up 34.3% and exports from national production up 55.4%. CILFA also reported that pharmaceutical output ended 2025 with twelve consecutive months of growth. This supports recurring demand for primary packaging materials, especially for high-volume tablets and capsules produced for domestic and export markets.
Retail Blisters Shift Toward PET and PP
Consumer-product blister packaging is gradually moving from conventional PVC toward PET and polypropylene where clarity, recyclability or retailer sustainability requirements justify the change. Argentine thermoformers such as Bligraf and JC Packing already process several thermoplastic materials across blister and clamshell formats. The transition is more straightforward in non-pharmaceutical applications because qualification requirements are lower and barrier performance is generally less demanding than in medicine packaging.
Market Drivers
Domestic Solid-Dose Manufacturing Provides a Large Addressable Base
Argentina has substantial local capacity for tablets, coated tablets and capsules. Pfizer's Buenos Aires plant alone has installed annual capacity exceeding one billion solid-dose units across tablets and capsules, while Roemmers operates a dedicated 22,000 square meter solid-products facility with annual capacity of 85 million units. These plants sit within a wider national industry that includes large domestic pharmaceutical groups and contract packers. The resulting production base provides steady demand for forming films, lidding foil, printed foil, cold-form structures and packaging services.
Pharmaceutical Production and Export Activity Support Higher Utilization
National pharmaceutical production performed strongly through 2025 and into 2026. INDEC reported first-quarter 2026 growth in both domestic sales and exports from national production, while industry data showed a recovery in medicine-unit volumes during 2025 after the previous year's contraction. Higher plant utilization raises packaging consumption directly because solid-dose output requires primary packaging before products enter domestic distribution or export channels.
High-Barrier Requirements Increase Value per Pack
Sensitive formulations require packaging that provides stronger protection than standard PVC. This creates a higher-value market for PVDC-coated structures, PCTFE laminates and cold-form aluminum. Argentina-based TekniPlex supplies several of these structures, including PVC/Aclar duplex and triplex laminates, PVC/PVDC films and Alu-Alu cold-form material. The value contribution from these products is greater than their unit-volume share because advanced barrier materials carry substantially higher material and conversion costs.
Contract Packaging Supports Smaller and Mid-Sized Laboratories
Not every pharmaceutical manufacturer operates its own complete blistering and secondary-packaging lines. Companies such as Laboratorios Argenpack and Intrafarma provide primary blister packaging, cold-form packaging, printed aluminum and related contract services to third-party laboratories. This outsourced capacity allows smaller companies to launch products without investing in dedicated packaging equipment and supports demand for short-run, multi-SKU and specialist blister formats.
Market Restraints and Challenges
Imported High-Barrier Materials Expose Costs to Currency Movements
Many specialized films, coatings and aluminum structures are sourced internationally or depend on imported inputs. Currency volatility therefore affects the peso cost of PCTFE laminates, high-grade aluminum, specialist coatings and other high-barrier components. Domestic converters can absorb part of the risk through inventory management and local processing, but extended lead times and exchange-rate movements can still affect working capital and customer pricing.
Qualification Requirements Slow Material Changes
Pharmaceutical manufacturers cannot switch forming films or lidding structures as easily as consumer-product companies because packaging is linked to product stability, sealing conditions, machinability and regulatory documentation. Moving from PVC/PVDC or cold-form aluminum to newer recyclable structures requires validation on existing equipment and may require stability work before commercial adoption. This slows material substitution even when a new structure offers a stronger sustainability profile.
Consumer Blister Demand Is More Price Sensitive
Non-pharmaceutical blister applications face greater substitution from paperboard boxes, flexible pouches, molded fiber and simpler thermoformed formats. Retailers and consumer-goods companies can redesign packaging more quickly than pharmaceutical manufacturers, making price and material reduction important purchasing criteria. This keeps consumer and hardware blister margins more exposed to resin prices and competition among local thermoformers.
Argentina Blister Packaging Market Segment Analysis
By Blister Format
Push-Through Blisters
Push-through blister formats are expected to generate approximately USD 78 million by 2031, maintaining the largest format position. Their use is concentrated in tablets and capsules, where aluminum lidding is sealed to thermoformed or cold-formed cavities. The format benefits from high pharmaceutical volumes, well-established production lines and efficient unit-dose presentation. Peelable and peel-push structures serve selected child-resistant, senior-friendly and specialty products, while carded and clamshell formats remain more important in non-pharmaceutical retail applications.
By Material
PVC and PVC/PVDC
PVC and PVC/PVDC structures are forecast to generate approximately USD 77 million by 2031. Their continued position is supported by low material cost, strong thermoformability, widespread machine compatibility and the ability to increase barrier performance through PVDC coatings. Higher-barrier PCTFE and cold-form aluminum gain value share in sensitive pharmaceutical products, while PP and polyester structures expand gradually where recyclability, product compatibility and line qualification support conversion away from conventional PVC-based formats.
By Technology
Thermoformed
Thermoformed blister packaging is expected to account for approximately USD 129 million by 2031. The technology dominates because it supports high-speed production, lower material consumption and broad compatibility with pharmaceutical and consumer-product formats. Cold-form packaging remains smaller in volume but higher in unit value and is used where moisture and light protection are critical. Argentina's installed pharmaceutical base is therefore likely to remain predominantly thermoformed while using cold-form selectively for products that require stronger barrier performance.
By End-User
Pharmaceuticals and Healthcare
Pharmaceutical and healthcare applications are forecast to generate approximately USD 108 million by 2031, remaining the largest end-user segment. Growth is supported by domestic medicine production, export-oriented manufacturing and continued use of blister formats for tablets and capsules. The segment also carries higher average packaging value because regulated applications require tighter material specifications, validated sealing performance and stronger barrier structures than most consumer-goods packaging. Consumer goods and hardware remain important for local thermoformers, but their demand is more fragmented and price-sensitive.
Competitive Environment and Analysis
The Argentina blister packaging market combines local thermoformers, pharmaceutical contract packers and international suppliers of specialist films and lidding materials. TekniPlex maintains a direct Argentine presence and supplies pharmaceutical-grade PVC/Aclar, PVC/PVDC, cold-form aluminum and related high-barrier materials. Laboratorios Argenpack provides blister packaging and printed foil services for pharmaceutical customers, while Bligraf, Ricardo Wagner and JC Packing serve thermoformed blister and consumer-packaging applications from local production facilities.
Global material suppliers influence the higher-value pharmaceutical segment even when production is not located in Argentina. Honeywell supplies Aclar PCTFE used in high-barrier blister laminates, while kp, Constantia Flexibles, Amcor and ACG offer pharmaceutical forming films, lidding and recyclable blister structures. These companies compete primarily on barrier performance, machinability, sustainability, regulatory documentation and consistency across multinational pharmaceutical programs.
Competitive structure has shifted following recent consolidation. Sonoco completed the sale of its Thermoformed and Flexibles Packaging business to TOPPAN in 2025, while WestRock combined with Smurfit Kappa in 2024 to form Smurfit Westrock. Upstream polymer suppliers remain important to resin availability and pricing, but direct competition in the blister market is concentrated among film, foil, thermoforming and contract-packaging specialists.
Recent Developments
September 2026: TekniPlex highlighted its fully transparent, recyclable mid-barrier blister packaging system, featuring a polyolefin blister film paired with a barrier polypropylene lidding film for pharmaceutical applications, with commercial qualification and scale-up activity continuing to progress.
June 2026: INDEC reported first-quarter 2026 pharmaceutical-industry revenue growth of 32.7% year on year, including a 34.3% increase in national-production revenue and 55.4% growth in exports from national production.
May 2026: ANMAT introduced mandatory QR or Data Matrix coding on the secondary packaging of all medicinal products under Disposition 2891/2026, with implementation beginning progressively during 2026.
May 2026: TekniPlex presented recyclable PP- and PET-based pharmaceutical blister structures and high-barrier alternatives at The Pharma Days 2026, including formats designed to run on conventional blister lines.
Market Outlook
Argentina's blister packaging market should continue to expand at a moderate rate through 2031, with pharmaceuticals accounting for most incremental value. The strongest demand will come from oral solid-dose production, higher-barrier packaging for sensitive formulations and contract packaging for laboratories that do not operate dedicated blister lines. Export-oriented pharmaceutical manufacturing provides an additional demand layer because locally produced medicines must meet packaging specifications for destination markets as well as domestic ANMAT requirements.
Material substitution will be gradual rather than abrupt. PVC and PVC/PVDC will retain a large installed base because they are economical and familiar to converters, while PCTFE laminates and cold-form aluminum remain important for higher-barrier products. PP and polyester blister systems should gain share as global suppliers complete qualification programs and pharmaceutical companies adopt recyclable structures where product stability permits.
Local converters will remain competitive in consumer and standard pharmaceutical applications, but the higher-value segment will continue to depend on international material technology. Companies that combine local converting or technical support with access to advanced barrier films, recyclable structures and validated lidding systems will be best positioned as pharmaceutical customers tighten both product-protection and sustainability requirements.
Argentina Blister Packaging Market Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 130.6 million |
| Total Market Size in 2031 | USD 168.1 million |
| Forecast Unit | Million |
| Growth Rate | 5.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Blister Format, Material, Technology, End-User |
| Geographical Segmentation | North America, South America, Europe, Middle East and Africa, Asia Pacific |
| Companies |
|
Market Segmentation
By Blister Format
Push-Through Blisters
Peelable and Peel-Push Blisters
Carded and Face-Seal Blisters
Clamshell and Slide Blisters
Others
By Material
PVC and PVC/PVDC
Polypropylene and Other Polyolefins
PET and Other Polyester Structures
PCTFE-Based High-Barrier Laminates
Cold-Form Aluminum Laminates
Others
By Technology
Thermoformed
Cold-Form
By End-User
Pharmaceuticals and Healthcare
Consumer Goods, Electronics and Hardware
Food and Confectionery
Personal Care and Cosmetics
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Regulatory Framework
4.7. Analyst View
5. ARGENTINA BLISTER PACKAGING MARKET BY BLISTER FORMAT
5.1. Introduction
5.2. Push-Through Blisters
5.3. Peelable and Peel-Push Blisters
5.4. Carded and Face-Seal Blisters
5.5. Clamshell and Slide Blisters
5.6. Others
6. ARGENTINA BLISTER PACKAGING MARKET BY MATERIAL
6.1. Introduction
6.2. PVC and PVC/PVDC
6.3. Polypropylene and Other Polyolefins
6.4. PET and Other Polyester Structures
6.5. PCTFE-Based High-Barrier Laminates
6.6. Cold-Form Aluminum Laminates
6.7. Others
7. ARGENTINA BLISTER PACKAGING MARKET BY TECHNOLOGY
7.1. Introduction
7.2. Thermoformed
7.3. Cold-Form
8. ARGENTINA BLISTER PACKAGING MARKET BY END-USER
8.1. Introduction
8.2. Pharmaceuticals and Healthcare
8.3. Consumer Goods, Electronics and Hardware
8.4. Food and Confectionery
8.5. Personal Care and Cosmetics
8.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. TekniPlex S.A. Argentina
10.2. Laboratorios Argenpack S.A.
10.3. Bligraf S.A.
10.4. Ricardo Wagner S.A.
10.5. JC Packing
10.6. Toppan Holdings Inc.
10.7. Smurfit Westrock plc
10.8. Honeywell International Inc.
10.9. Klöckner Pentaplast Group
10.10. Constantia Flexibles
10.11. Amcor plc
10.12. ACG
10.13. Aluflexpack AG
10.14. Nelipak Corporation
10.15. Intrafarma S.A.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Research Methodology
11.5. Abbreviations
Navigate
Trusted by the world's leading organizations











