
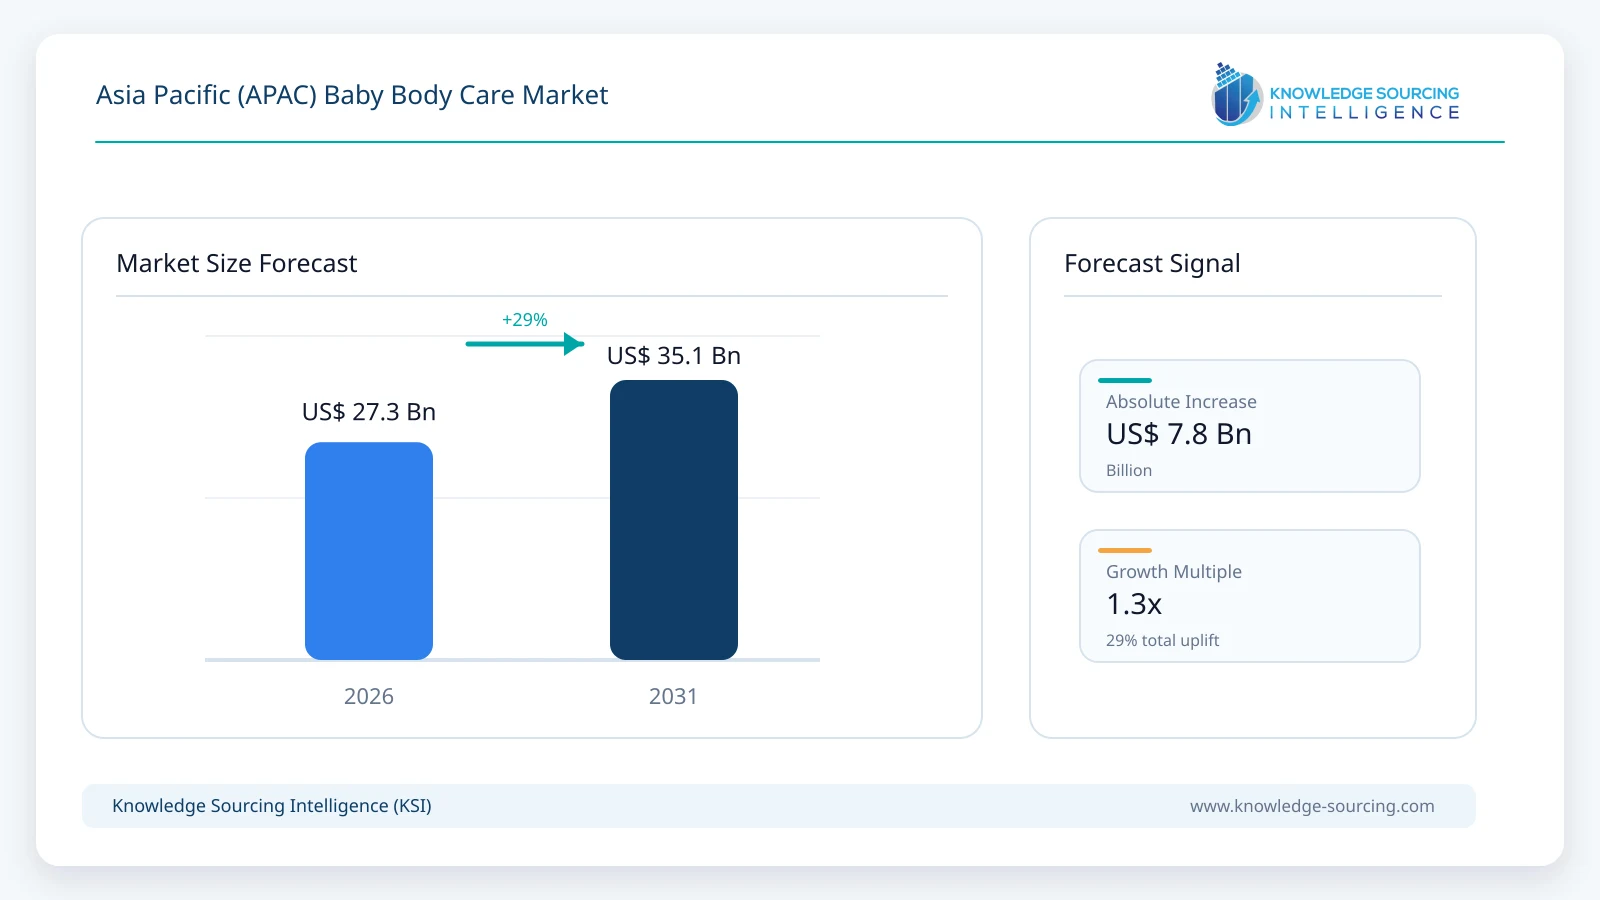
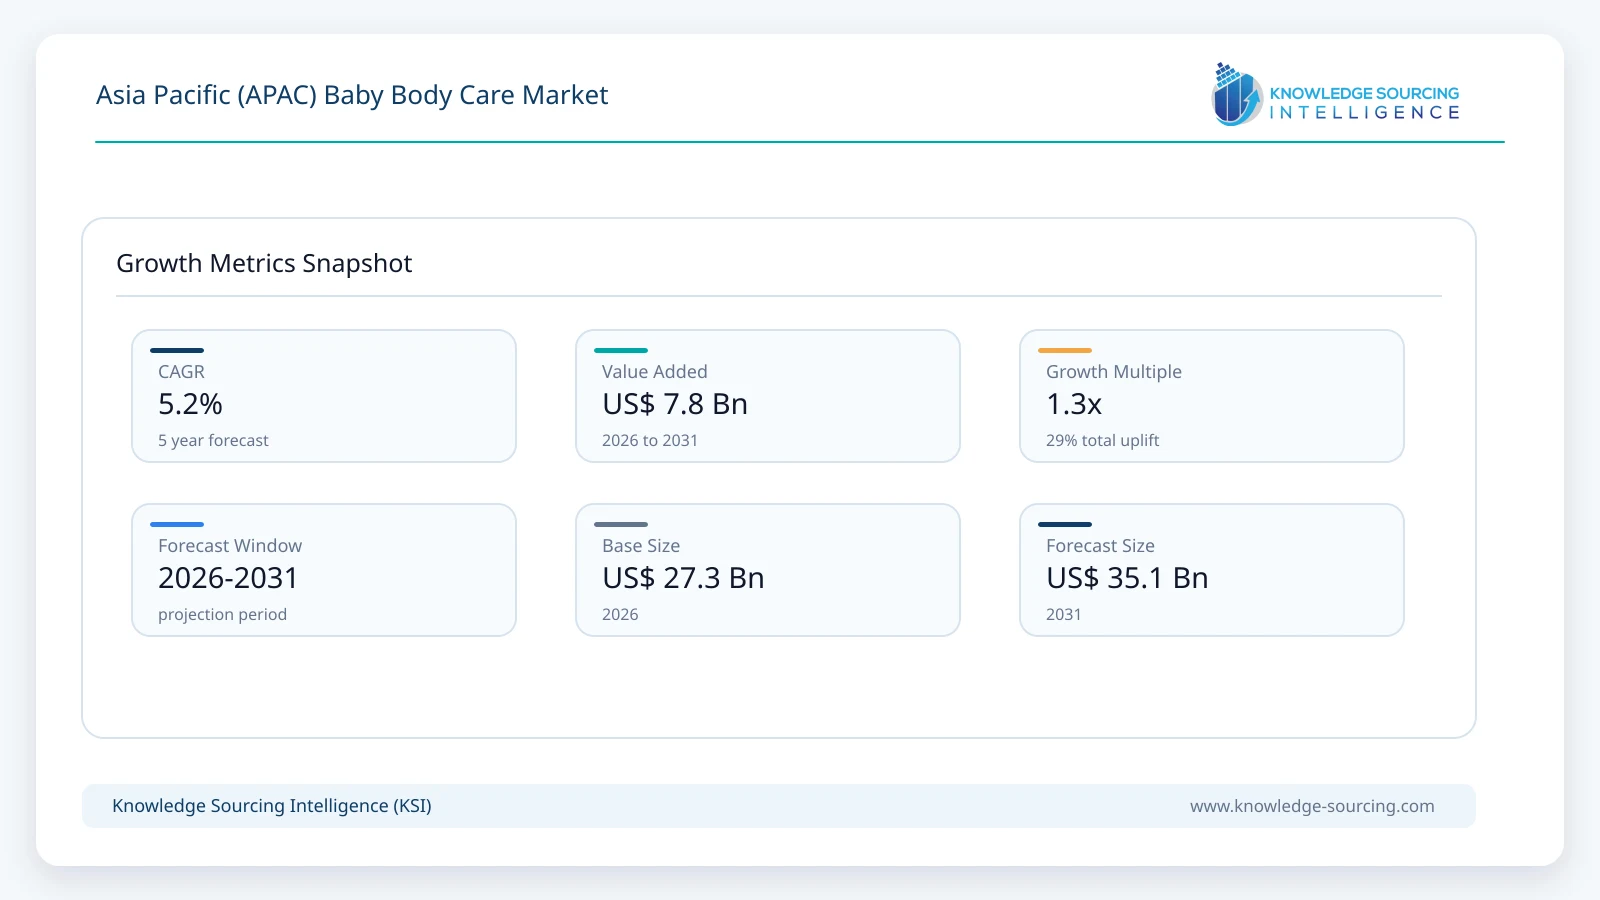
The Asia Pacific (APAC) Baby Body Care Market is expected to expand at a CAGR of 5.15%, reaching a market size of USD 35.1 billion in 2031 from USD 27.3 billion in 2026.
Highlights:
- 1Diapers and wipes account for approximately 75% of regional sales in 2026.
- 2Online channels expand fastest as parents shift repeat purchases to digital replenishment.
- 3Skin care benefits from demand for gentle formulations and skin-barrier protection.
- 4China anchors high-value sales despite a smaller annual birth cohort.
- 5India combines a large infant population with room for greater disposable-diaper penetration.
Baby body care encompasses finished products purchased for infant and young-child hygiene: disposable diapers and wipes, baby shampoos and conditioners, skin cleansers, lotions, moisturizers, oils and closely related toiletries. The main commercial transaction is the sale of these products through mass retail, pharmacy, specialist baby stores and online channels. Infant formula, feeding equipment, strollers, clothing and the material inputs already embedded in a finished diaper or lotion are outside this product category.
Product economics differ markedly between absorbent hygiene and formulated care. Disposable diapers generate frequent repeat purchases and require large-scale nonwoven and absorbent-core conversion, with distribution costs often determining the viable pack size. Lotions, cleansers and specialty skin products carry smaller unit volumes but can command differentiated pricing through formulation, quality assurance and professional recommendation. P&G, Unicharm, Kimberly-Clark and Kao illustrate the scale of diaper competition, while Pigeon, Kenvue, Himalaya and other formulators compete across baby toiletries.
Market Overview
Diaper demand is shaped by two variables that need to be assessed separately: the population of diaper-wearing children and the number of disposable products used per child. More frequent changing, longer use of training pants and a shift from cloth to disposable products can increase sales without an increase in births. Unicharm's 2025 integrated report describes the ongoing spread of disposable-diaper use in India and its differentiated premium and affordable brand positioning in Indonesia. These conditions contrast with Japan and China, where manufacturers increasingly seek higher realization per unit as birth cohorts shrink.
In 2025, China's National Bureau of Statistics recorded 7.92 million births, compared with 9.54 million in 2024, tightening the volume outlook for its mature baby-hygiene market. P&G nevertheless reported product-mix improvements and demand for higher-performing diapers in Greater China, including Pampers Prestige, which uses silk in the topsheet. The contrast matters commercially: premium performance can offset part of a falling user base, but only where households accept a sufficiently large price differential. Kimberly-Clark's 2026 disclosure of a social-media-related disruption to Chinese diaper sales also illustrates how product credibility can affect purchasing even where a company's safety testing is favorable.
Manufacturers are extending skin-comfort features across both diapers and toiletries. Kao markets Merries through dermatology-led product explanations in Indonesia, while formulated-care providers compete over fragrance, pH, allergen claims, moisture retention and suitability for sensitive skin. Retail execution is increasingly a combination of physical trial, consultation and online replenishment. The stronger suppliers will adapt pack sizes and evidence-supported benefit claims to local purchasing power without sacrificing manufacturing consistency or traceability.
Market Trends
Premium Diapers Are Being Designed Around Skin Comfort
P&G's Pampers Prestige incorporates silk fibers in a product sold in China, linking softness and surface feel with premium positioning rather than presenting absorbency as the only distinguishing attribute. Kao's Merries communication in Indonesia similarly emphasizes diaper performance on delicate infant skin. The commercial change is visible in the materials, topsheet construction and testing used to support a higher selling price; a premium carton alone is not sufficient evidence of product differentiation.
For manufacturers, premiumization raises material and quality-control requirements while increasing the incentive to protect brand trust. Product formats with better fit, moisture management and breathable layers may support value growth in markets with fewer infants. However, claims must remain specific to the tested product, and high unit prices create a limit to conversion in lower-income households.
Disposable-Diaper Adoption Is Moving Beyond Major Cities
Unicharm's February 2025 commissioning of an additional factory in Ahmedabad reflects the economics of serving India's large, geographically dispersed infant market. Local conversion capacity can shorten replenishment cycles and help a manufacturer serve both conventional retail and newer online distribution routes. The opportunity is not simply to sell a more expensive product, but to persuade families that disposable pants and taped diapers are practical for daily use.
Expansion into smaller cities and towns requires affordable packs, consistent product availability and customer education on fit and skin hygiene. Distribution density and retailer margins consequently become as important as national advertising. Suppliers that overemphasize high-end urban formats may miss much of the incremental unit demand.
Online Retail Is Reshaping Replenishment and Pricing
Diapers and wipes lend themselves to online repeat buying because sizes, brands and usage rates become predictable after a household establishes a preference. Unicharm describes new e-commerce formats in China, low-price digital challengers in Indonesia and live-commerce activity in Vietnam. Digital channels broaden access but also make price differences between competing packs immediately visible.
Physical outlets retain a role for first purchases, product comparison and advice, particularly where parents are choosing newborn sizes or skin-care treatments. Kao's September 2026 Merries flagship opening with an Indonesian retailer pairs product sales with family education. Manufacturers therefore need coordinated channel management rather than assuming online growth will eliminate specialist stores.
Baby Toiletries Are Moving Toward More Specific Claims
Baby oils, moisturizers and washes are increasingly sold against specific parental concerns such as dryness, irritation, cleansing mildness and fragrance sensitivity. The distinction between a basic toiletry and a higher-value skin-care formulation lies in ingredients, quality systems, testing and the clarity of recommended use. Companies including Pigeon, Kenvue, Beiersdorf and specialist Indian producers compete across different price tiers.
Regulatory classification and consumer expectations differ between countries. A gentle cleanser is not automatically a therapeutic treatment, and statements about preventing eczema or infection require an appropriate substantiation basis. Suppliers that maintain conservative, testable claims may protect long-term customer loyalty more effectively than those relying on poorly defined 'natural' positioning.
Country-Level Demographics Are Splitting the Regional Market
Japan, South Korea and China face more demanding unit-volume conditions than India and parts of Southeast Asia. China's official 2025 birth total reinforces that revenue expansion in mature markets cannot be assumed from population growth. In contrast, UNICEF's India profile reports a very large annual birth cohort, while Unicharm identifies further potential for disposable products to replace reusable alternatives.
Forecasts therefore need different assumptions for the number of infant users, average units purchased and price realization by country. A single regional consumption growth rate would conceal the distinction between premium-led revenue gains and genuine product-penetration growth.
Segment Analysis
By Product Type: Diapers and Wipes
Diapers and wipes remain the largest product group because a child uses multiple units each day over an extended period, creating recurrent household purchasing. Their estimated 2026 value is USD 20.60 billion, across taped diapers, pants, training formats and baby wipes. The category's commercial structure favors suppliers with absorbent-core expertise, dependable conversion plants and wide retail distribution. Unicharm's India expansion and the multi-brand positioning used in Indonesia demonstrate different ways to serve a high-frequency purchase category.
Premium softness and skin comfort can increase spending per unit in China and Japan, while disposable adoption and affordable pants formats underpin growth in India. The segment is projected to reach USD 25.80 billion in 2031, though its percentage of total baby body care spending gradually moderates as formulated skin and hair products grow. Producers must manage the cost of nonwovens, absorbents and packaging alongside channel promotions rather than relying on premium claims alone.
By Distribution Channel: Offline
Offline stores account for approximately 73% of the market in 2026, reflecting the entrenched role of supermarkets, pharmacies, general trade and baby-specialty outlets. New parents often assess size, packaging and product suitability in person before settling into recurring purchases. In markets with fragmented last-mile delivery, local stores also provide immediate access to small packs at a manageable cash outlay.
The channel remains central in 2031, with an expected value of USD 22.46 billion, but gives up share to online replenishment. Kao's Indonesian retail collaboration demonstrates why stores can reposition around professional advice and product demonstration. Manufacturers increasingly negotiate the economics of promotions, shelf space and digital pricing across both routes, since the same consumer may discover a product offline and subsequently buy it online.
Market Drivers
Greater Use of Disposable Hygiene Products
India's large infant cohort and comparatively incomplete disposable-diaper penetration create a sizeable volume opportunity. The consumer shift depends on availability of appropriate sizes, absorbency performance and prices that households can sustain through frequent repeat purchases. Unicharm has expanded its manufacturing and sales reach in India, linking local supply with penetration beyond the largest cities. Unit growth from switching away from cloth products is more durable than promotional demand that merely moves purchases forward.
Premium Absorbency and Skin-Protection Design
Manufacturers are differentiating diapers through moisture retention, topsheet texture, breathability and fit. P&G's silk-containing Pampers Prestige and Kao's dermatology-oriented Merries positioning show how technical features can support premium tiers in China and Indonesia. Products that demonstrate skin comfort under realistic wear conditions can support higher average revenue per unit. The opportunity is strongest where parents trust the product evidence and can afford the recurring cost.
Expansion of Online Replenishment
Online retail and subscription-like repeat ordering improve access to bulky diapers and wipes, especially for households already familiar with their preferred brand and size. Digital storefronts allow specialists to reach customers without extensive physical shelf space. Producers also gain opportunities to manage bundles and mixed product baskets. Yet customer acquisition costs and discounting require discipline; growth in online orders does not necessarily translate into higher supplier profitability.
Growing Demand for Purpose-Designed Baby Skin Care
Infant-specific formulations allow producers to differentiate beyond adult toiletries through gentle cleansing agents, barrier-support ingredients and carefully controlled fragrance systems. Products addressing dryness and routine cleansing can extend household spending beyond diapers and wipes. Kenvue, Pigeon, and regional formulators have recognizable portfolios in these categories. Formulation documentation and practical product instructions matter because infant skin can be sensitive and parents closely scrutinize ingredients.
Localized Production and Channel Reach
Regional manufacturing reduces import exposure for high-volume, low-value-density products such as disposable diapers. Unicharm's additional Indian factory strengthens its ability to serve domestic distribution at scale, while local facilities in other Asian markets allow faster responses to preferred sizes and price tiers. For brands, country-specific procurement, pack design and retail relationships can be more decisive than a single regional advertising campaign. Greater local capacity also limits freight and currency risk.
Market Restraints
Declining Birth Cohorts in Mature Markets
China recorded 7.92 million births in 2025, and shrinking child populations also weigh on Japan and South Korea. When the number of diaper-wearing children falls, manufacturers must increase product usage or average selling price to sustain revenue. Higher-priced formats can offset some pressure but do not guarantee equivalent volume. A brand portfolio overexposed to mature, premium segments may face difficult trade-offs between price, market share and factory utilization.
Price Sensitivity and Low-Cost Competition
Frequent diaper replacement makes even modest differences in the price per piece material for household budgets. In India and parts of Southeast Asia, lower-cost local brands, reusable alternatives and smaller packs can constrain premium conversion. Unicharm's discussion of Indonesian and Thai competitors highlights the role of value-tier offerings and online discounting. Manufacturers with unnecessarily expensive structures may lose repeat business despite technical advantages.
Safety Expectations and Product-Credibility Risks
Concerns about irritation, chemical exposure and quality claims can cause abrupt shifts in purchase behavior. Kimberly-Clark reported that allegations circulating online affected its China diaper business during the second quarter of 2026 despite its account of independent quality testing. Manufacturers must maintain traceable inputs, reliable validation and responsive communication. Unsupported therapeutic or environmental claims also create commercial and regulatory exposure for baby toiletries.
Input Costs and Packaging Constraints
Diaper conversion depends on fluff pulp, superabsorbent polymers, films, adhesives and nonwoven materials; lotions and washes use surfactants, oils, preservatives and packaging components. Changes in resin prices, pulp supply or shipping conditions may compress margins when retailers resist price increases. Recyclability demands add complexity because absorbent hygiene products contain several functional materials that are difficult to separate after use. Product cost reduction must not compromise leakage control or skin contact performance.
Retail Promotions and Channel Conflict
A manufacturer can lose margin when online discounts undercut physical-store pricing, particularly where a baby-store operator is expected to provide in-person advice. E-commerce adds fulfillment costs for bulky diaper cases and can encourage pack-size comparisons that weaken perceived differentiation. Cross-channel coordination requires consistent promotions, inventory visibility and retailer incentives. Faster online growth is not inherently beneficial when discount intensity exceeds logistical savings.
Regional Outlook
China
China accounts for an estimated USD 9.45 billion of baby body care sales in 2026, the largest individual country total in the region. The market has a substantial installed consumer base and high penetration of branded diapers, wipes and infant toiletries. Nevertheless, the National Bureau of Statistics reported only 7.92 million births in 2025, emphasizing why producers are shifting their commercial emphasis from unit additions to product mix and trust. P&G's Pampers Prestige and Unicharm's China-made Moony proposition address perceived softness, fit and breathable performance in a crowded market.
By 2031, China's market is expected to reach USD 11.60 billion, with growth increasingly derived from premium features and broader care baskets rather than larger newborn cohorts. Domestic brands, established multinationals and digitally native competitors operate across highly transparent online price comparisons. Manufacturers therefore need to defend product efficacy and consumer confidence while moderating expectations for volume growth.
India
India is the fastest-growing named country in the model, with an implied 2026–2031 CAGR of approximately 7.9%. The country's annual births substantially exceed those of other major Asia-Pacific economies, and disposable-diaper use has additional room to expand as household incomes, urban distribution and familiarity with pants formats increase. Unicharm began operating its Ahmedabad factory in February 2025, raising its Indian production footprint to three locations and strengthening its ability to serve a wider market.
Sales are projected to reach USD 7.68 billion in 2031, compared with USD 5.25 billion in 2026. Growth will not be uniform across income groups: value packs and frequent small purchases will remain important in lower-income markets, while higher-priced skin-care and premium diaper lines develop among urban customers. Reliable supply and credible product safety are likely to determine how quickly initial trial turns into habitual consumption.
Competitive Landscape
P&G competes through Pampers and its ability to combine material engineering, retail execution and premium product tiers. Unicharm is particularly relevant across Japan, India and Southeast Asia through Moony, MamyPoko and value-sensitive formats; its regional manufacturing network allows differences in product and pricing strategies. Kimberly-Clark's Huggies portfolio emphasizes fit, absorbency and skin comfort, although its 2026 China experience demonstrates the importance of reputation protection in a fast-moving online environment.
Kao's Merries position draws on breathability and skin-performance communication, while Hengan International and Oji Holdings represent important Asian absorbent-hygiene manufacturing capabilities. Finished baby toiletries are supplied by Kenvue through Johnson's Baby, Pigeon, Himalaya Wellness, Honasa Consumer, Dabur, Unilever and Beiersdorf. These participants do not all compete in every product category; diaper converters and formulated skin-care manufacturers face different plant requirements, regulation and brand economics.
Competition is becoming more country specific. In China, premium and digital propositions must offset demographic pressure; in India, cost per diaper, affordable formats and last-mile reach influence market access. Indonesia and Vietnam have additional capacity for branded product adoption but also attract low-price digital sellers. Consolidation among brand owners could alter distribution bargaining power, although announced transactions should not be treated as completed until the required approvals and closing conditions are met.
Recent Developments
22 October 2026: Procter & Gamble reported first-quarter fiscal 2027 results and identified mid-single-digit Baby Care organic sales growth, supported by Greater China and North America volume and premium mix. The disclosure confirms brand-level progress but is not a stand-alone APAC market-size measure.
6 October 2026: Kao Indonesia announced the Merries flagship-store initiative following the 28 September opening with Toko Raja Susu in West Jakarta. The manufacturer combined diaper retail with skin-care education and family engagement, illustrating a more service-oriented specialist channel.
4 August 2026: Kimberly-Clark reported that online allegations had disrupted China diaper sales in the second quarter while describing independent product-quality testing. The event underscores the importance of consumer trust and responsive quality communication.
29 July 2026: Procter & Gamble reported fiscal 2026 results, including low-single-digit Baby Care organic sales growth led by Greater China volume and mix improvements. It highlights the contribution of product differentiation despite demographic pressure.
5 May 2026: Procter & Gamble detailed Pampers Prestige for China, describing silk-containing topsheet technology and super-premium consumer positioning. The manufacturer linked the product's design to demand for softness and protection.
23 October 2025: Kao Malaysia announced the updated Merries diaper range with breathable construction, stretch and leak-control features, following its September local relaunch. The product emphasizes performance benefits in a regional premium diaper segment.
Market Outlook
Through 2031, baby body care revenue will be shaped by a widening gap between mature premium markets and emerging markets where more families are adopting disposable products. China's manufacturers must generate value through reliable product improvement, skin comfort, and channel discipline as newborn numbers decline. India's longer-term opportunity comes from the conversion of occasional use into frequent use, supported by local production and broad retail access.
Online channels will capture a larger share of replenishment purchases, but physical retailers are unlikely to lose their role in initial product selection and baby-specific advice. The strongest suppliers will coordinate these channels and offer clearly differentiated packs without creating costly price conflict. Skin and hair care should become more prominent in the basket as parents seek products formulated for infants rather than general household substitutes.
Across the region, disciplined innovation matters more than adding loosely defined 'natural' claims. Product safety substantiation, absorbent-core efficiency, fit, cost and packaging resilience will influence repeat purchases. Manufacturers with flexible regional plants and consistent quality systems should be better placed to balance premium price realization in East Asia with the affordability required for volume expansion in South and Southeast Asia.
Asia Pacific Baby Body Care Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 27.3 billion |
| Total Market Size in 2031 | USD 35.1 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.15% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Product Type
Diapers and Wipes
Hair Care
Skin Care
Others
By Distribution Channel
Online
Offline
By Geography
China
India
Japan
Taiwan
Australia
South Korea
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Size and Growth, 2026–2031
1.3. Product-Type Outlook
1.4. Distribution Channel Outlook
1.5. Country Opportunity Summary
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Greater Use of Disposable Hygiene Products
3.1.2. Premium Absorbency and Skin-Protection Design
3.1.3. Expansion of Online Replenishment
3.1.4. Growing Demand for Purpose-Designed Baby Skin Care
3.1.5. Localized Production and Channel Reach
3.2. Market Restraints
3.2.1. Declining Birth Cohorts in Mature Markets
3.2.2. Price Sensitivity and Low-Cost Competition
3.2.3. Safety Expectations and Product-Credibility Risks
3.2.4. Input Costs and Packaging Constraints
3.2.5. Retail Promotions and Channel Conflict
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Absorbent Core and Nonwoven Technologies
4.2. Breathable and Skin-Contact Materials
4.3. Infant Cleansing and Emollient Formulations
4.4. Product Testing and Packaging Technologies
5. ASIA PACIFIC BABY BODY CARE MARKET, BY PRODUCT TYPE
5.1. Introduction
5.2. Diapers and Wipes
5.3. Hair Care
5.4. Skin Care
5.5. Others
6. ASIA PACIFIC BABY BODY CARE MARKET, BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Online
6.3. Offline
7. ASIA PACIFIC BABY BODY CARE MARKET, BY GEOGRAPHY
7.1. Introduction
7.2. China
7.3. India
7.4. Japan
7.5. Taiwan
7.6. Australia
7.7. South Korea
7.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. The Procter & Gamble Company
9.2. Unicharm Corporation
9.3. Kimberly-Clark Corporation
9.4. Kao Corporation
9.5. Kenvue Inc.
9.6. Pigeon Corporation
9.7. Hengan International Group Company Limited
9.8. Oji Holdings Corporation
9.9. Himalaya Wellness Company
9.10. Honasa Consumer Limited
9.11. Dabur India Limited
9.12. Unilever PLC
9.13. Beiersdorf AG
9.14. Nobel Hygiene Private Limited
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years
10.4. Key Benefits to Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











