
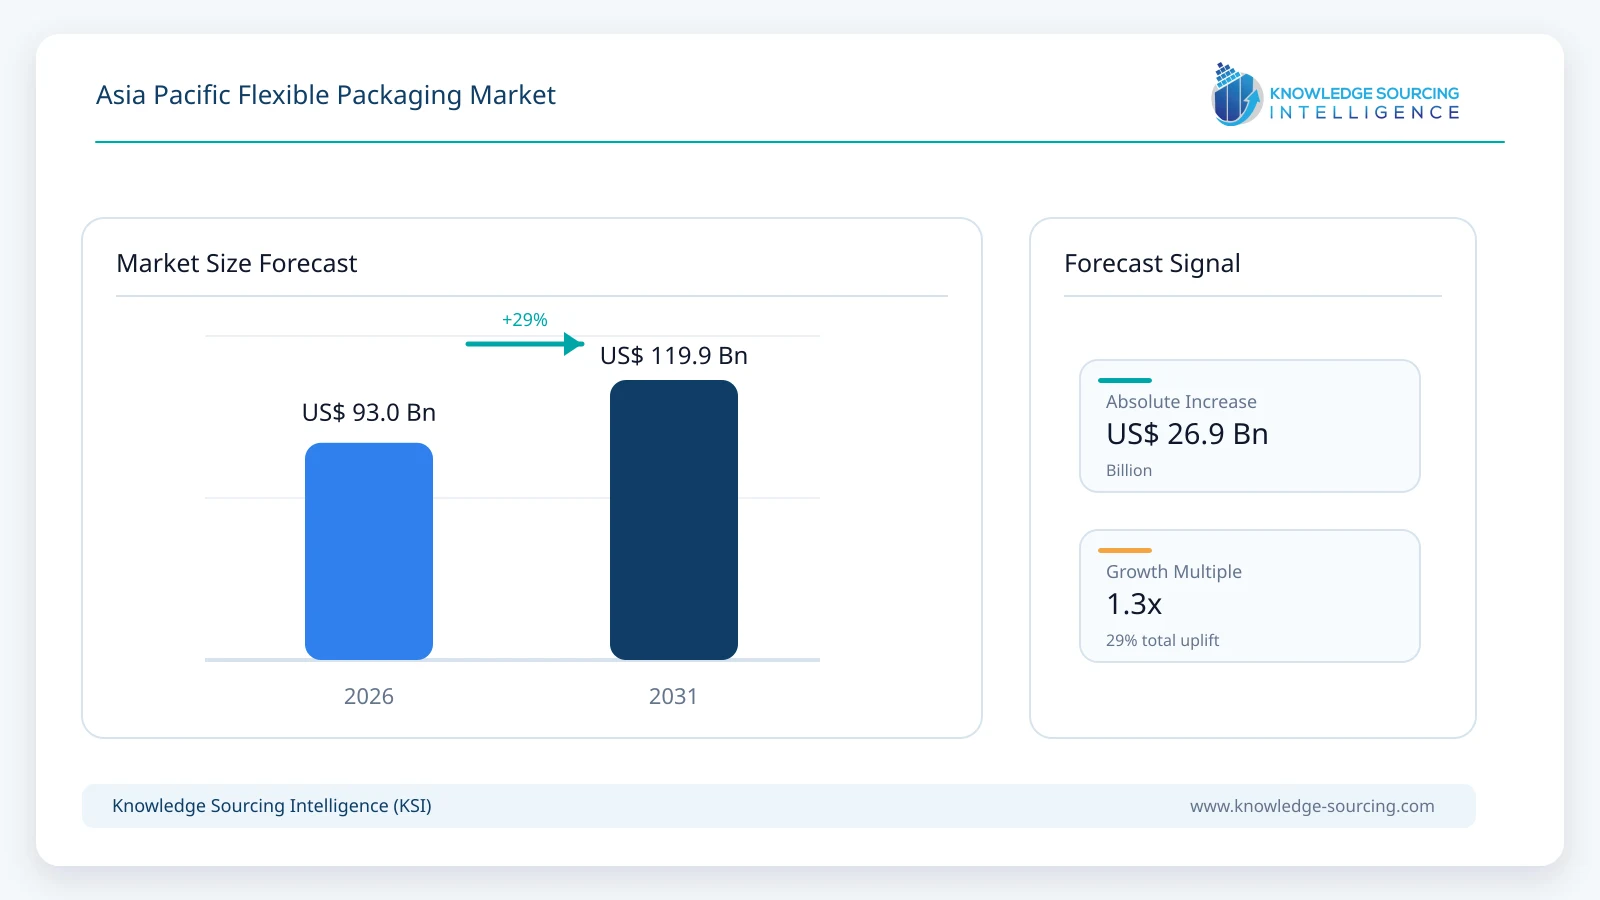
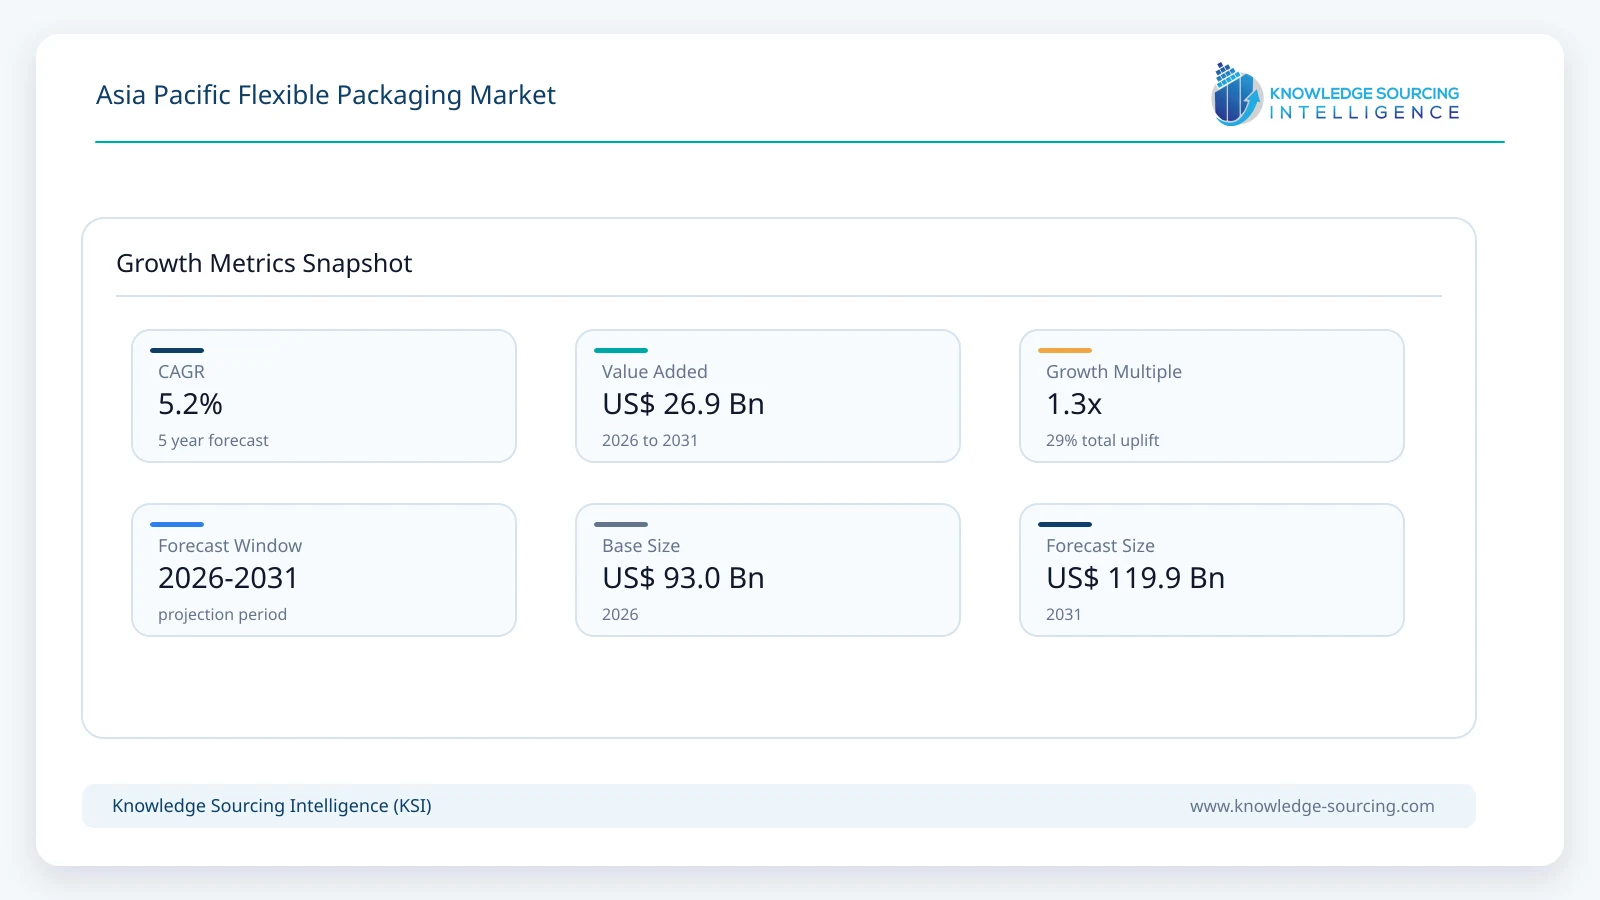
The Asia Pacific flexible packaging market is estimated at USD 93.0 billion in 2026 and is forecast to reach approximately USD 119.9 billion in 2031, representing a CAGR of 5.2% throughout the forecast period.
Highlights:
- 1China remains the largest country market, supported by manufacturing scale and packaged-food demand.
- 2Plastic films retain the largest material share as recyclable mono-material structures gain adoption.
- 3Pouches lead product demand across food, home-care, personal-care, and refill applications regionwide.
- 4Food remains the largest end-user segment, supported by convenience and shelf-life requirements.
- 5Sustainability regulation accelerates recyclable structures, recycled content, and downgauging across regional markets.
The market is shifting from conventional multi-material laminates toward structures designed for recyclability, including mono-PE, mono-PP and mono-PET packaging, alongside increased use of post-consumer recycled content where regulations and food-contact requirements permit. Huhtamaki reported broader commercialization of mono-material and PCR-based flexible packaging in 2025, while UFlex introduced a mono-material PET film at PLASTINDIA 2026. In Thailand, Kao, SCG Packaging, SCG Chemicals and Dow commercialized a mono-material refill bag in June 2026, demonstrating that recyclable flexible structures are moving from pilot development into mainstream consumer applications.
The 2026 estimate represents a measured progression from the earlier market level of approximately USD 84.6 billion in 2024 rather than a change in market scope. The revised forecast reflects stronger regional capacity additions, healthcare packaging investment, convenience-food demand and sustainability-led replacement of legacy structures, while recognizing that resin prices, recycling infrastructure and slower growth in mature Japanese and Australian markets constrain the overall regional CAGR.
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 93.0 billion |
| Total Market Size in 2031 | USD 119.9 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Material, Printing Technology, End User, Geography |
| Companies |
|
The forecast assumes sustained packaged-food and household-product demand, continued capacity investment in India and Southeast Asia, and gradual migration toward recycle-ready flexible structures. Growth is moderated by volatile resin and foil costs, uneven collection and recycling infrastructure, regulatory fragmentation and slower volume expansion in mature markets such as Japan and Australia.
Asia Pacific Flexible Packaging Market Trends
Mono-Material Structures Move into Commercial Scale
Recyclability is increasingly being addressed through packaging redesign rather than only downstream waste management. Mono-material PE, PP and PET structures are replacing selected multi-material laminates where barrier and sealing performance can be maintained. In June 2026, Kao Thailand, SCG Packaging, SCG Chemicals and Dow launched a mono-material refill pouch designed for polyethylene recycling streams, while UFlex introduced a high-seal-strength mono-material PET film at PLASTINDIA 2026.
India and Southeast Asia Attract New Packaging Investment
Capacity expansion is strengthening the supply base outside China. Amcor opened a USD 35 million healthcare-packaging coating facility in Malaysia in April 2026 and expanded healthcare packaging production capability in India in June 2026. India also has a large domestic converting base led by UFlex, Huhtamaki India, Paharpur 3P, TCPL and other suppliers, while Southeast Asian converters such as SCG Packaging, Scientex and Thong Guan support regional food, home-care and consumer-goods customers.
Healthcare Packaging Becomes a Higher-Value Growth Area
Flexible healthcare packaging is expanding as pharmaceutical, medical-device and diagnostics production grows across India and Southeast Asia. High-barrier films, coated medical paper, lidding, sachets and specialty laminates command higher technical requirements than many standard food applications. Amcor's 2026 investments in Malaysia and India highlight the commercial importance of localized sterile and pharmaceutical packaging capability within the region.
Recycling Rules Reshape Material and Design Decisions
Regulation increasingly affects package structure, recycled-content planning and end-of-life design. India's extended producer responsibility framework applies category-specific obligations to flexible plastic packaging, while Japan continues implementation of its Plastic Resource Circulation Act. Australia is also reforming packaging regulation and explicitly identifies soft plastics as a priority. This creates demand for structures that preserve barrier and shelf-life performance while simplifying material composition.
Asia Pacific Flexible Packaging Market Segment Analysis
By Product Type
Pouches
Pouches are estimated at approximately USD 32.6 billion in 2026, representing about 35% of the Asia Pacific flexible packaging market. Stand-up, flat, retort, spouted and refill pouches are used widely across snacks, sauces, pet food, household cleaning, personal care, beverages and ready-to-eat products. Their value proposition combines high print area, low material weight, transport efficiency and convenience features such as zippers and spouts. Refill applications are also supporting pouch demand as brand owners reduce rigid-plastic use while maintaining product protection and shelf visibility.
By Material
Plastic Films
Plastic films are estimated at approximately USD 70.7 billion in 2026, or about 76% of regional market value. PE, PP, PET, polyamide and metallized structures dominate because they provide sealability, moisture resistance, mechanical strength and barrier performance across high-speed packaging lines. The segment is changing rather than disappearing: mono-material PE, PP and PET designs, thinner gauges and recycled-content solutions are increasingly replacing complex laminates where technically feasible. Paper and aluminum remain important for selected applications, but plastic films retain the broadest functionality across food and consumer packaging.
By Printing Technology
Rotogravure
Rotogravure is estimated at approximately USD 50.2 billion in 2026, representing about 54% of printed flexible-packaging value in Asia Pacific. The process remains deeply established across high-volume converters because it delivers consistent image quality, long production runs and strong performance on films used for food, home-care and personal-care packaging. Flexography continues to gain capability and digital printing is expanding in shorter runs and multi-SKU applications, but rotogravure retains the leading regional position due to the scale of packaged-goods production and the installed converting base in China, India and Southeast Asia.
By End User
Food
Food packaging is estimated at approximately USD 51.2 billion in 2026, or about 55% of the regional market. Flexible formats are used extensively for snacks, bakery products, noodles, frozen and chilled foods, sauces, retort meals, confectionery, dairy powders, meat and pet food. The segment benefits from urbanization, convenience consumption, modern retail, e-commerce and the need to extend shelf life across long and complex regional supply chains. Food also drives substantial innovation in high-barrier, retort, easy-open, resealable and recyclable structures because performance and product-protection requirements remain stringent.
By Country
China
China is estimated at approximately USD 39.1 billion in 2026, representing about 42% of Asia Pacific market value. The country combines the region's largest manufacturing base with substantial packaged-food, personal-care, household-product and healthcare demand. It also hosts major local and multinational converting capacity; Amcor, for example, operates a large flexible-packaging plant in Huizhou and an Asia Pacific innovation center in Jiangyin. India is the next major growth market, while Japan, South Korea, Southeast Asia and Australia provide sizable but structurally different demand profiles.
Market Drivers
Packaged-food, convenience, and ready-to-eat consumption sustaining high-volume flexible packaging demand.
India and Southeast Asia manufacturing investment expanding regional converting and healthcare-packaging capacity.
Mono-material and recycle-ready structures accelerating replacement of harder-to-recycle multilayer packaging.
E-commerce and modern retail supporting lightweight, printable, and transport-efficient packaging formats.
Brand demand for downgauging, recycled content, and lower material use driving packaging redesign.
Market Restraints
Volatile polyethylene, polypropylene, PET, aluminum, ink, adhesive, and energy costs affecting converter margins.
Multi-material laminates remain difficult to collect, sort, and recycle economically in many markets.
Recyclability requirements can conflict with barrier, retort, seal-strength, and shelf-life performance needs.
Country-specific EPR, labeling, food-contact, and recycled-content rules increase compliance complexity.
Mature demand in Japan and Australia moderates growth relative to India and Southeast Asia.
Competitive Environment
The Asia Pacific market combines global packaging leaders with strong regional converters. Amcor, Huhtamaki, Constantia Flexibles and Sealed Air supply multinational customers across food, healthcare and consumer applications, while UFlex, TOPPAN, Dai Nippon Printing, SCG Packaging and Rengo bring deep regional converting and materials capabilities. Scientex, Thong Guan, ZACROS, TCPL Packaging, Paharpur 3P and ePac Flexible Packaging add strength in Southeast Asia, Japan, India and Australia.
Competition increasingly extends beyond printing and converting capacity into material science, recyclability, barrier performance and speed to commercialization. Suppliers are investing in mono-material laminates, PCR-compatible structures, paper-based alternatives, high-barrier films, digital printing and local technical support. Scale remains important for commodity food packaging, but higher-value healthcare, retort, pet food and recyclable barrier applications favor companies with proprietary materials, qualification capabilities and close relationships with brand owners.
Recent Developments
June 2026: Amcor expanded healthcare packaging production capability at its Sira facility in Karnataka, India, supporting growing pharmaceutical and medical demand.
June 2026: Kao Thailand, SCG Packaging, SCG Chemicals and Dow commercialized a mono-material refill pouch designed for polyethylene recycling streams.
April 2026: Amcor opened a USD 35 million healthcare packaging coating facility in Malaysia, adding advanced sterile-packaging capability in Southeast Asia.
February 2026: UFlex introduced F-HSS mono-material PET film at PLASTINDIA 2026 for recyclable high-seal-strength packaging structures.
2025: Huhtamaki India scaled commercial production of mono-material and PCR-based flexible packaging solutions across customer applications.
Market Outlook
Asia Pacific flexible packaging demand should continue expanding through 2031, but growth will increasingly come from product redesign and value mix rather than volume alone. China will remain the largest market, while India and Southeast Asia contribute a larger share of incremental capacity and consumption. Food remains the core end-user base, but healthcare and higher-performance consumer applications provide attractive value growth. Suppliers that can simplify material structures, incorporate recycled content where permitted and preserve barrier, sealing and runnability performance are positioned to benefit from the region's shift toward circular packaging.
Asia Pacific Flexible Packaging Market Scope:
Market Segmentation
By Product Type
Pouches
Bags
Films and Wraps
Sachets and Stick Packs
Others
By Material
Plastic Films
Paper
Aluminum Foil
Bioplastics and Compostable Materials
By Printing Technology
Rotogravure
Flexography
Digital Printing
Others
By End User
Food
Beverage
Healthcare and Pharmaceutical
Personal Care and Home Care
Pet Food
Industrial and Other Consumer Products
By Country
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Vietnam
Malaysia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Scope
1.3. Regional Market Reference Point
1.4. Currency and Assumptions
2. RESEARCH METHODOLOGY
2.1. Secondary Research
2.2. Company and Product Validation
2.3. Market Estimation and Regional Triangulation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Asia Pacific Market Size, 2026-2031
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Sustainability and Regulatory Trends
5. ASIA PACIFIC FLEXIBLE PACKAGING MARKET BY PRODUCT TYPE
5.1. Pouches
5.2. Bags
5.3. Films and Wraps
5.4. Sachets and Stick Packs
5.5. Others
6. ASIA PACIFIC FLEXIBLE PACKAGING MARKET BY MATERIAL
6.1. Plastic Films
6.2. Paper
6.3. Aluminum Foil
6.4. Bioplastics and Compostable Materials
7. ASIA PACIFIC FLEXIBLE PACKAGING MARKET BY PRINTING TECHNOLOGY
7.1. Rotogravure
7.2. Flexography
7.3. Digital Printing
7.4. Others
8. ASIA PACIFIC FLEXIBLE PACKAGING MARKET BY END USER
8.1. Food
8.2. Beverage
8.3. Healthcare and Pharmaceutical
8.4. Personal Care and Home Care
8.5. Pet Food
8.6. Industrial and Other Consumer Products
9. ASIA PACIFIC FLEXIBLE PACKAGING MARKET BY COUNTRY
9.1. China
9.2. India
9.3. Japan
9.4. South Korea
9.5. Australia
9.6. Indonesia
9.7. Thailand
9.8. Vietnam
9.9. Malaysia
9.10. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Competitive Positioning
10.2. Product and Material Innovation
10.3. Sustainability Strategy
10.4. Capacity Expansion, Partnerships and Acquisitions
11. COMPANY PROFILES
11.1. Amcor plc
11.2. Huhtamaki Oyj
11.3. UFlex Limited
11.4. TOPPAN Inc.
11.5. Dai Nippon Printing Co., Ltd.
11.6. SCG Packaging Public Company Limited
11.7. Rengo Co., Ltd.
11.8. Scientex Berhad
11.9. Thong Guan Industries Berhad
11.10. Sealed Air Corporation
11.11. Constantia Flexibles Group GmbH
11.12. ZACROS Corporation
11.13. TCPL Packaging Limited
11.14. Paharpur 3P Private Limited
11.15. ePac Flexible Packaging
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Market Definition and Exclusions
12.4. Abbreviations
Navigate
Trusted by the world's leading organizations











