
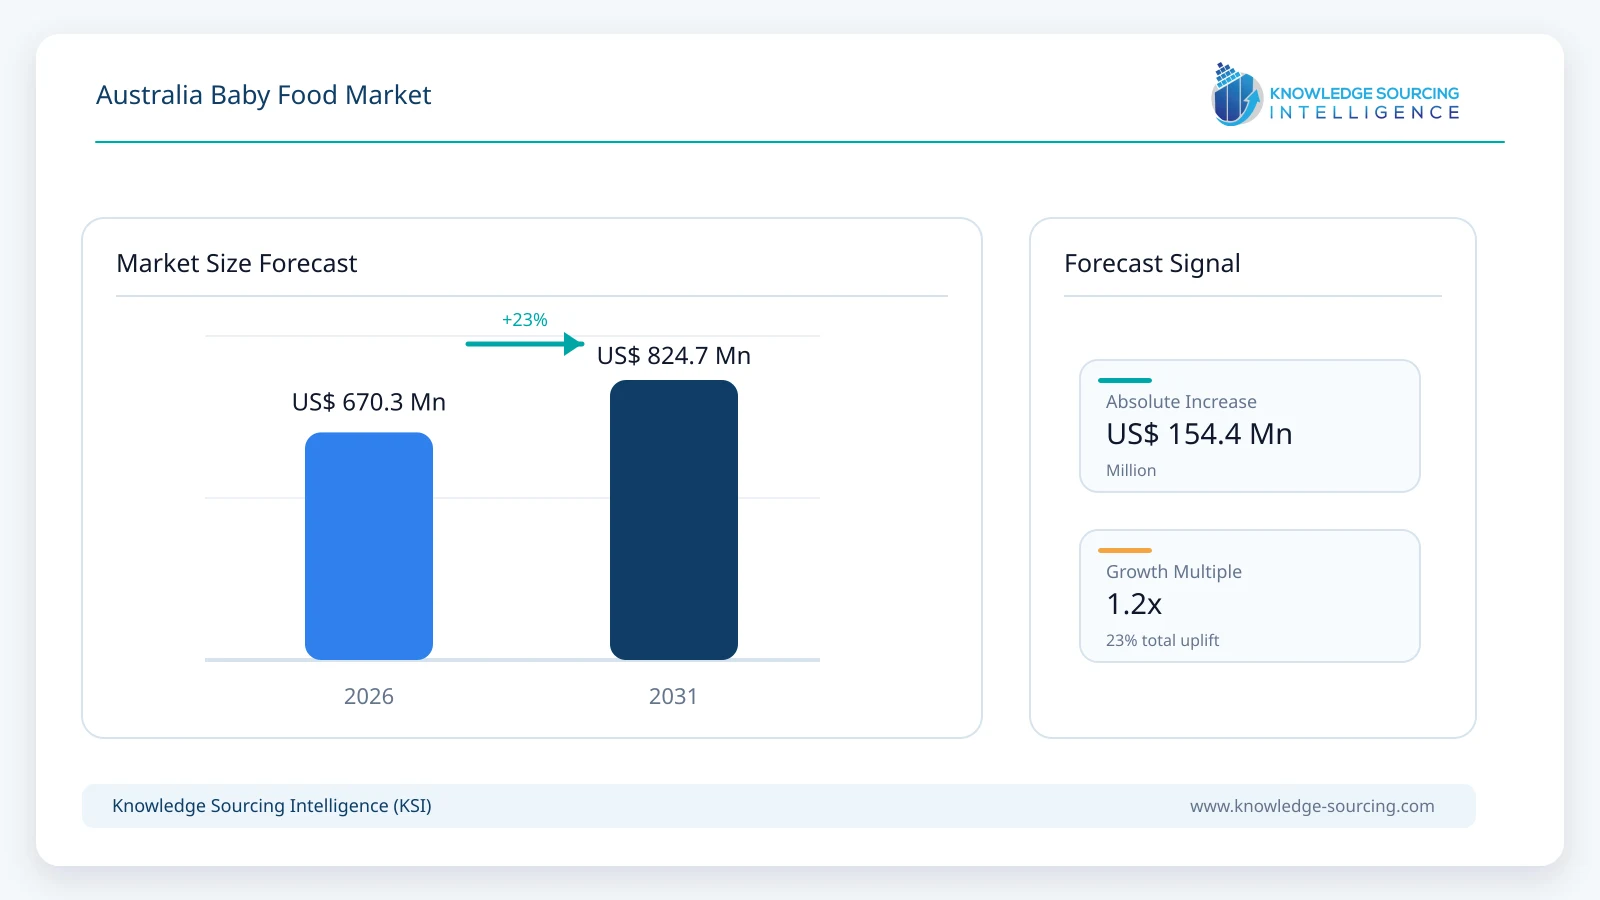
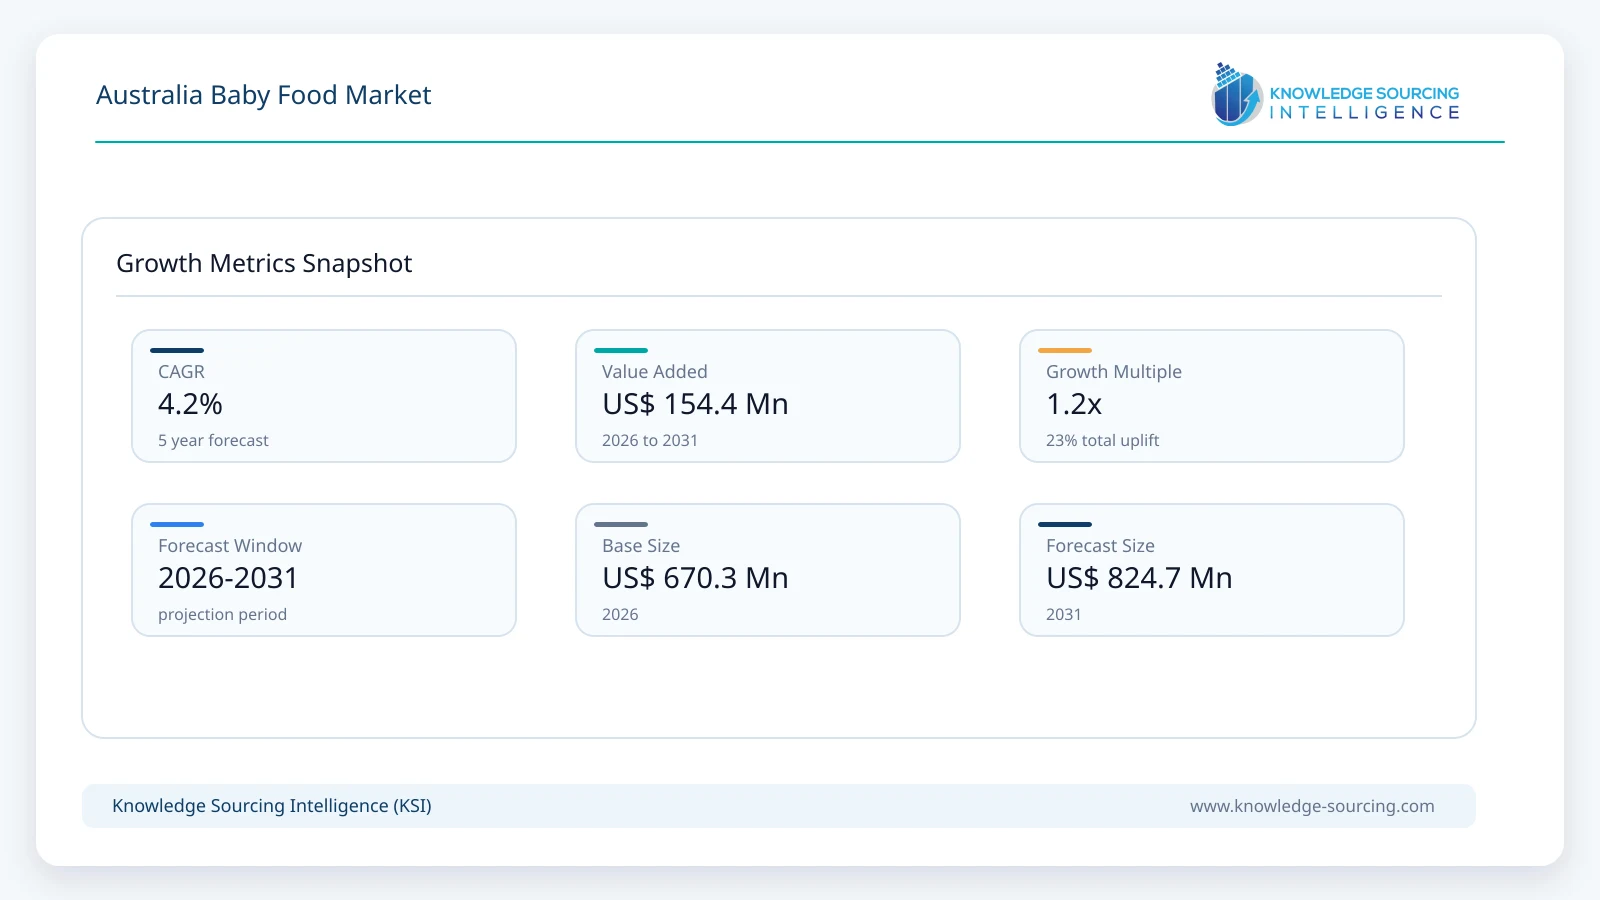
The Australian Baby Food Market is expected to reach USD 824.7 million in 2031, growing at a CAGR of 4.2% between 2026 and 2031, from USD 670.3 million in 2026.
Highlights:
- 1Premium organic certification drives demand for pure, additive-free baby foods sourced from Australian farmers.
- 2Sustainable pouch formats minimize food waste and support convenient, eco-conscious feeding practices.
- 3Innovation in nutrient-dense ingredients incorporates natural elements like bone broth for enhanced nutritional benefits.
- 4Local farming integration strengthens supply chains and ensures traceability for every ingredient in baby nutrition.
Market Overview
The growing number of infants, evolving infant-nutrition practices, product innovation, stringent regulatory standards, and growing accessibility to international specialized baby-food formulations are currently shaping the landscape of the Australian Baby Food Market. The country’s birth rate rose by 3.6% in December 2025, expanding the underlying consumer market for infant and complementary foods.
The Australian Government maintains its commitment to breastfeeding and appropriate infant feeding, while recognising that infant formula is the safest alternative for babies who cannot be breastfed and endorses a highly regulated market for breast-milk substitutes.
Food Standards Australia New Zealand (FSANZ) introduced an updated Australian standard for infant-formula requirements, covering nutrient composition and permitted ingredients as well as labelling and specialized medical-purpose infant products.
The new infant-formula requirements will have a transition period of five years, from September 2024 to September 2029, enabling manufacturers to comply with the updated standard.
FSANZ reviewed young child formula in September 2025 with a view to establishing stricter definitions, independent regulatory arrangements, along with new nutritional and labelling specifications for commodities specifically targeting 1–3-year-olds.
The Australian Government's assessment of commercial infant and toddler foods highlighted nutritional composition, labelling, as well as texture and volume-related problems to rectify, providing an opportunity for food manufacturers to reformulate products and distinguish them based on nutritional quality.
Another area of product development is focused on specialist nutrition, such as follow-on formula and Special Medical Purpose Products for infants (SMPPi) with specific composition and labelling requirements regulated by FSANZ.
Product innovation is growing around nutrient density and functional ingredients. For example, Bellamy's Organic's new formulation features a dual organic GOS and FOS prebiotic blend in Step 1, while the Step 2 formulation also contains about 56% more Omega-3 DHA and Omega-6 ARA compared to previous infant formulations.
Similarly, in January 2025, Australian brand Little Harvesters introduced high-fat, high-protein purée pouches infused with whole-food ingredients, highlighting the opportunity for food brands to introduce products that capitalise on nutrient density rather than traditional sweet fruit puréed baby foods.
Market Drivers
Growing Preference for Convenient Commercial Baby Foods
The commercial baby food market in Australia is driven by the increasing trend of working-class parents seeking quick, convenient, and easy-to-prepare food products, and other households in need of packaged foods for infants and toddlers.
In June 2025, 73% of Australian couple families with children aged 0–14 had both partners employed, according to the Australian Bureau of Statistics. This means a substantial percentage of households are dual-income, increasing the need for convenient and time-efficient meals for their child.
As per the same source, 36% of these families had both parents working full-time, while an additional 35% had one parent working full-time and the other working part-time. This employment structure supports continued demand for prepared and ready-to-serve baby food products that are convenient for working parents.
The food e-commerce channel in Australia was also continuing to grow through 2025, with online sales of food reaching AUD 1.402 billion during April 2025, an increase of AUD 60.8 million, which is +4.5% month on month on a seasonally adjusted basis.
Online availability of food purchases aids the convenient re-ordering of frequently bought baby-food products, especially for parents who balance work and childcare.
Product formats are increasingly designed around simple preparation and use. For example, Bellamy's Organic has launched an easy-open top lid and attachable scoop in their infant-formula portfolio, clearly emphasizing convenience and hygiene in their overall formulation changes.
In Australia, the commercial infant-food landscape is also in the regulatory sphere: with the expiry of the MAIF Agreement on 28 February 2025, the Australian Government began work developing mandatory controls for marketing of infant-formula products.
Major Segment Analysis
Online
By distribution channel, the Australian Baby Food market is segmented into online and offline channels, where the latter is further segmented into sub-categories such as supermarkets & hypermarkets, pharmacies, convenience & specialty baby stores, and others.
The growing adoption of e-commerce, fueled by increasing internet penetration, has expanded the use of online platforms for buying baby care items, including food products.
A growing work culture has shifted parents’ preference towards online platforms. According to the Australian Bureau of Statistics, in June 2025, there were nearly 2.2 million couple families, of which 73% had both parents working with child dependence. The increasing number of working families drives the market for online channels in Australia.
The improved e-commerce trend has further escalated the adoption of digital retail sites for buying baby food in Australia. Likewise, improved internet penetration in the country, with more than 90% of the population having internet access (According to the World Bank), further propels the market trajectory.
Online channels support informed purchase behavior by parents. As demand for nutrient-dense options grows for baby, the shift towards online product surfing and thorough research further expands in Australia.
Cost and time utility offered by digital platforms play a key role in driving adoption frequency in Australia, and companies like Odi providing organic baby food in Australia through its online site, positively influence market growth.
The “Australia Post eCommerce Report 2026” indicates a growing e-commerce shift amongst Australians, with nearly 9.8 million households shopping online in 2025. Such a high number of online shoppers, followed by improved smartphone penetration, stimulates the market outlook for online channels.
Geographical Outlook
New South Wales
New South Wales baby food market is anticipated to show steady growth fuelled by the improved live birth rate and supportive government efforts to improve baby nutrition access.
Being one of the major Australian regions, New South Wales holds high market potential fueled by its significant share of Australia’s total baby population, followed by ongoing lifestyle changes of parents, which have altered their nutrient choices for babies.
According to the Australian Bureau of Statistics, as at March 2026, the region witnessed 1.1% growth in population, signifying an increase in birth rates. Likewise, its natural increase between live births & deaths in New South Wales has also improved, with annual births recorded at 94,743 and deaths at 61,527.
Month-wise birth registration has also improved in New South Wales, with the highest registration recorded in March 2026, which, according to the Data.NSW reached 8,914, representing nearly 18% growth over the same months recorded in 2025.
Improved Baby Bundle package, followed by government initiatives such as “Brighter Beginning: The First 2,000 Days of Life”, has established a framework for adoption of healthier options for baby growth and development in New South Wales.
Besides birth registration and supportive local government policies, the marriage frequency in New South Wales has also shown progression, and according to the local government, in August 2026, the number of marriages recorded stood at 2,720, which showed significant 27% growth over July 2026. This increase in marriages is expected to support demand for highly nutritious options among new parents for their baby.
Key Developments
August 2026: Odi Nutrition launched in Australia. New Zealand baby and children’s nutrition brand Odi entered Australia with organic baby purée pouches, powders, and children’s nutrition products, including wholefood-based formulations featuring vegetables, chickpeas and chicken.
June 2025: Little Harvesters launched its baby-food range. The Australian brand introduced high-fat, high-protein purée pouches made with wholefood ingredients, including organic vegetables, protein and healthy fats, targeting babies and young children.
April 2025: Bega Cheese acquired a 40% stake in Infant Nutrition Canning Australia. Bega completed the acquisition on April 2, 2025, strengthening its involvement in infant-nutrition manufacturing in Australia.
Company Profiles
For the Australian Baby Food Market, Nestlé Australia follows a strategy centred on nutrition-led product innovation, a broad infant and toddler portfolio, and trusted science-based nutrition positioning. The company leverages its global paediatric nutrition expertise while adapting products and consumer communication to Australian parents.
Its Australian portfolio includes NAN infant nutrition products and CERELAC infant cereals, allowing Nestlé to participate across different stages of early-life nutrition. Nestlé also provides educational information on introducing complementary foods, including guidance around infant cereals, textures and the transition from milk to solid foods, supporting its broader nutrition-focused positioning.
Australia Baby Food Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 670.3 million |
| Total Market Size in 2031 | USD 824.7 million |
| Forecast Unit | Million |
| Growth Rate | 4.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Nature Type, Age Group, Distribution Channel, Packaging Type, Region |
| Companies |
|
Market Segmentation
By Product Type
Dried Baby Food
Milk Formula
Prepared Baby Food
Others
By Nature Type
Organic Baby Food
Non-Organic Baby Food
By Age Group
0–6 months
6–12 months
12–24 months
By Distribution Channel
Online
Offline
Supermarkets & Hypermarkets
Pharmacies & Drugstores
Convenience & Specialty Baby Stores
Others
By Packaging Type
Pouches
Glass Jars
Metal Cans and Tins
Cartons and Boxes
Bottles
Others
By Region
New South Wales
Victoria
Queensland
South Australia
Western Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. MARKET DYNAMICS
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
4. BUSINESS LANDSCAPE
4.1. Regulatory, Food Safety & Standards Landscape
4.2. Baby Food Manufacturing & Processing Ecosystem
4.3. Ingredient & Nutritional Supply Chain
4.4. Import/Export Analysis
4.5. Strategic Recommendation
5. TECHNOLOGICAL OUTLOOK
5.1. Baby Food Processing & Formulation Technologies
5.2. Thermal Processing & Food Preservation Technologies
5.3. Freeze-Drying, Dehydration & Powder Technologies
5.4. Smart Food Manufacturing & Automation
5.5. AI-Based Food Quality Inspection & Safety Technologies
6. AUSTRALIA BABY FOOD MARKET BY PRODUCT TYPE (2021-2031)
6.1. Introduction
6.2. Dried Baby Food
6.3. Milk Formula
6.4. Prepared Baby Food
6.5. Others
7. AUSTRALIA BABY FOOD MARKET BY NATURE TYPE (2021-2031)
7.1. Introduction
7.2. Organic Baby Food
7.3. Non-Organic Baby Food
8. AUSTRALIA BABY FOOD MARKET BY AGE GROUP (2021-2031)
8.1. Introduction
8.2. 0–6 months
8.3. 6–12 months
8.4. 12–24 months
9. AUSTRALIA BABY FOOD MARKET BY DISTRIBUTION CHANNEL (2021-2031)
9.1. Introduction
9.2. Online
9.3. Offline
9.3.1. Supermarkets & Hypermarkets
9.3.2. Pharmacies & Drugstores
9.3.3. Convenience & Specialty Baby Stores
9.3.4. Others
10. AUSTRALIA BABY FOOD MARKET BY PACKAGING TYPE (2021-2031)
10.1. Introduction
10.2. Pouches
10.3. Glass Jars
10.4. Metal Cans and Tins
10.5. Cartons and Boxes
10.6. Bottles
10.7. Others
11. AUSTRALIA BABY FOOD MARKET BY REGION (2021-2031)
11.1. Introduction
11.2. New South Wales
11.3. Victoria
11.4. Queensland
11.5. South Australia
11.6. Western Australia
11.7. Others
12. COMPETITIVE ENVIRONMENT AND ANALYSIS
12.1. Major Players and Strategy Analysis
12.2. Market Share Analysis
12.3. Mergers, Acquisitions, Agreements, and Collaborations
12.4. Competitive Dashboard
13. COMPANY PROFILES
13.1. Nestlé Australia Ltd.
13.2. Bellamy's Organic
13.3. PZ Cussons plc (Rafferty's Garden)
13.4. Bubs Australia Limited
13.5. Abbott Australasia Pty. Ltd.
13.6. Danone S.A. (Nutricia Australia – Aptamil/Karicare)
13.7. KRAFT HEINZ AUSTRALIA PTY LIMITED (Heinz/Farex)
13.8. The a2 Milk Company Limited (a2 Nutrition)
13.9. Blackmores Limited
13.10. Little Freddie
14. RESEARCH METHODOLOGY
15. LIST OF FIGURES
16. LIST OF TABLES
Navigate
Trusted by the world's leading organizations











