
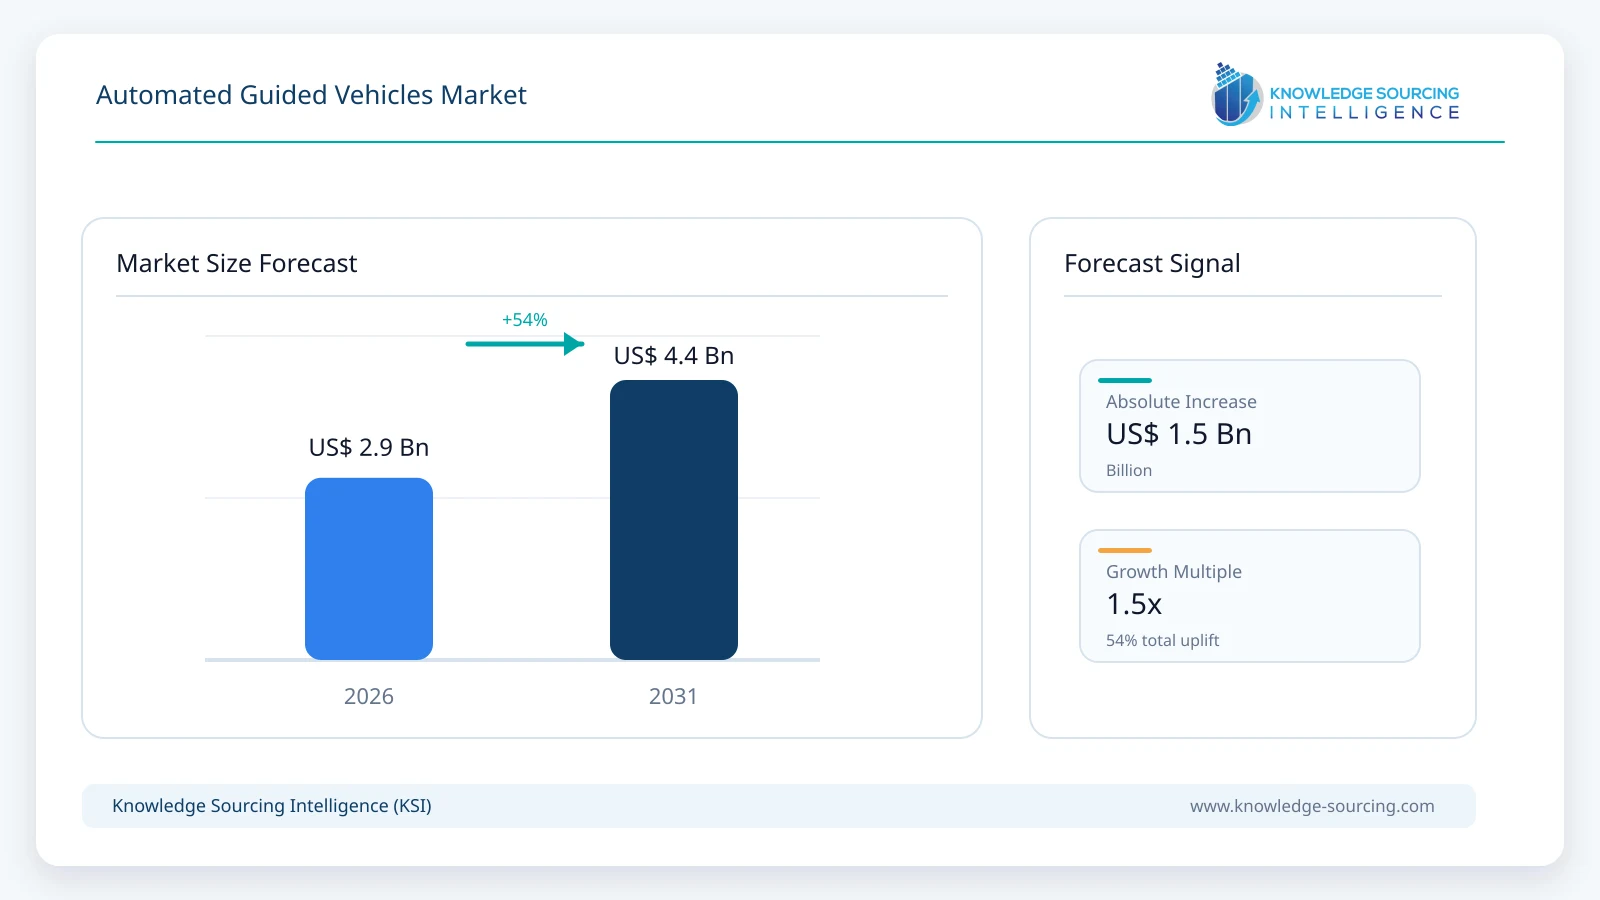
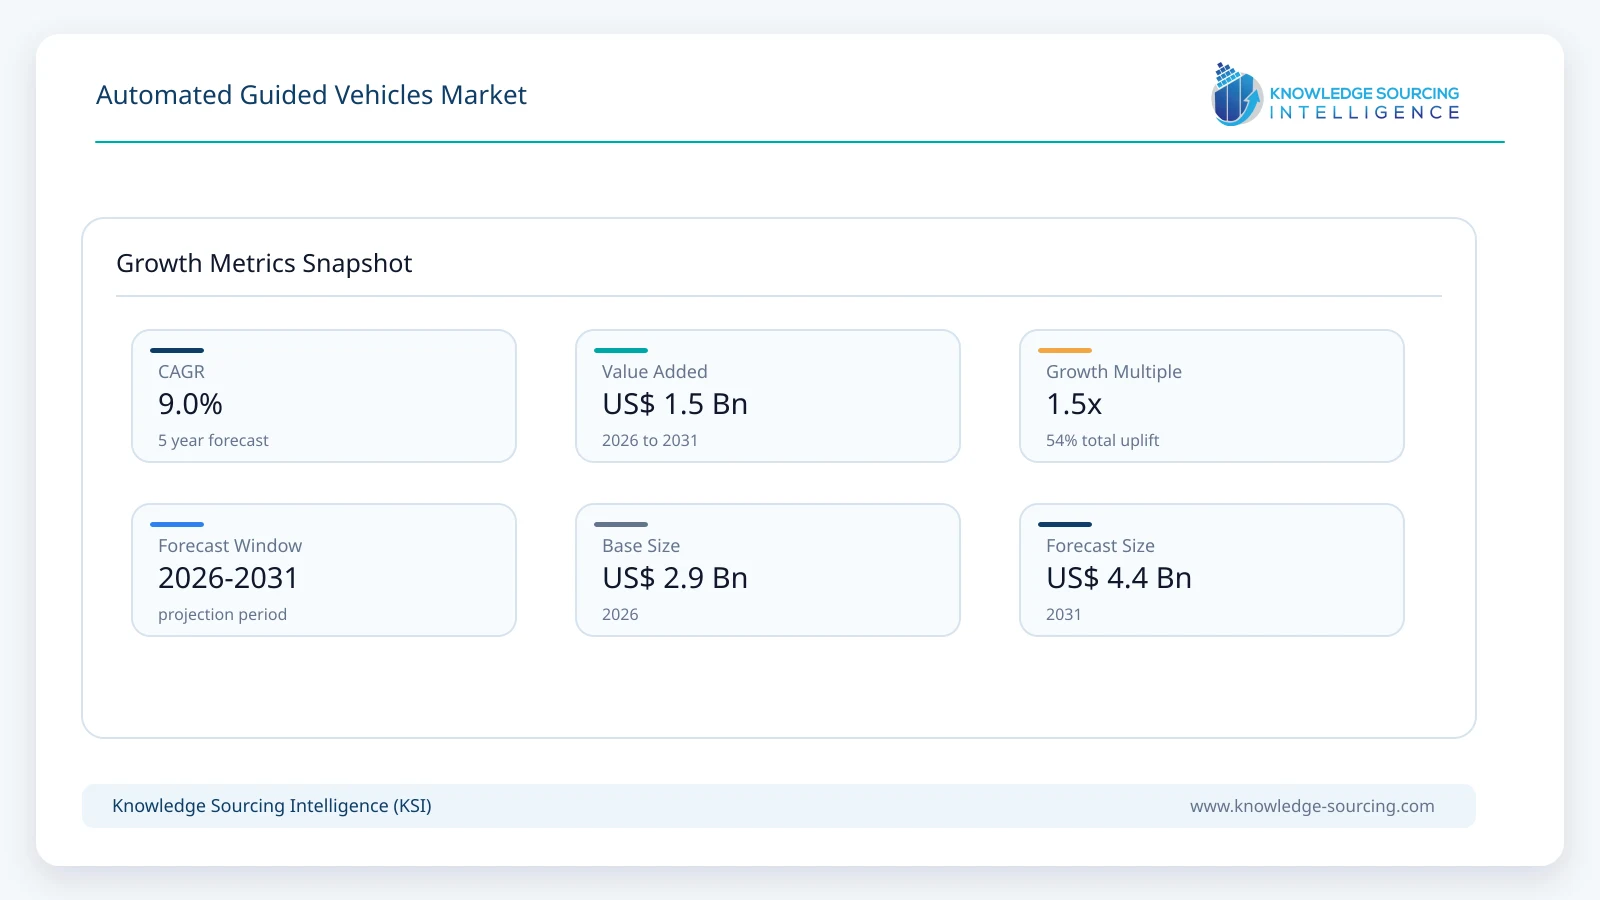
The Automated Guided Vehicles Market is projected to grow at a CAGR of approximately 9.0%, reaching USD 4.41 billion in 2031 from USD 2.87 billion in 2026.
Highlights:
- 1Forklift AGVs represent approximately 29% of 2026 vehicle-system market value.
- 2E-commerce and logistics contribute roughly 30% of demand across industry verticals.
- 3Laser guidance remains established, representing around 42% of 2026 revenue.
- 4High-bay handling is shifting automation beyond basic horizontal pallet transportation.
- 5Fleet interoperability and validated pedestrian safety influence multi-vendor purchasing decisions.
- 6Asia Pacific gains share as local manufacturing and logistics automation expand.
Automated guided vehicles serve manufacturing, distribution and storage operations where a repeatable goods movement can be turned into a reliable, monitored transport task. A forklift AGV places and retrieves pallets from racking, a tugger transports production carts, and an underride vehicle carries a mobile rack through a warehouse. Vehicle specifications differ by load weight, travel path, lift height, battery duty cycle, and positioning requirements; these differences shape the total installed cost and the relevant supplier set. Demand is concentrated in industrial transport operations with sufficient movement intensity to recover engineering and fleet expenditures.
Toyota Material Handling, Dematic, Jungheinrich, Daifuku, E80 Group and specialist robotic-forklift developers offer different combinations of vehicles, fleet controls and engineering services. A single truck can be installed to automate a bottleneck, while high-throughput plants may require coordinated fleets integrated with racking, conveyors and warehouse execution software. The decisive commercial measures are reliable moves per hour, utilization, safe interaction with people and the ease of supporting the equipment over a multi-year operating life.
Market Overview
An AGV moving work-in-progress between assembly cells needs predictable docking and low interruption risk; high-bay storage adds load-height control, accurate pallet detection, and aisle management. Dematic introduced the RTS 120 reach-truck AGV in November 2025 for selective racking in existing and new warehouses, while BALYO markets reach and narrow-aisle trucks. Both target work historically performed by staffed forklifts.
Operating architectures are increasingly mixed. Laser reflectors, magnetic markers, and inductive tracks remain appropriate where routes change infrequently and precise stop positions are essential. Vision-based navigation and localization can reduce fixed infrastructure for some applications, but free navigation does not eliminate the need for protected routes, verified stopping behavior or dependable interfaces to production systems. Jungheinrich’s EKS 215a deployment at the HELMA food distributor demonstrates that even a single automated truck can be economically relevant when it is integrated with an existing conveyor transfer point.
Market Trends
Automated Lift Trucks Are Extending the Reach of AGV Fleets
Pallet storage remains a difficult use case to automate because the vehicle must position a load accurately at height while sharing an aisle with people, conveyors, and other trucks. Dematic’s RTS 120 reach truck is designed for high-bay selective racking, and BALYO offers robotic reach, counterbalance and very-narrow-aisle configurations. The commercial value of these vehicles comes from automated storage and retrieval tasks that previously required a staffed lift truck, not merely from increasing the number of robots on a site.
Adoption depends on aisle geometry, rack tolerances, pallet quality and the frequency of exceptions. Suppliers with adaptable load sensing, reliable pallet interfaces and service support can serve retrofits as well as new automated warehouses. The larger systems must still be justified against manual-truck productivity, especially where daily throughput is variable.
Fleet Control Is Becoming More Important Than Route Automation Alone
Large plants may operate different generations of towing vehicles, lift trucks and mobile carriers, creating scheduling conflicts at intersections and bottlenecks. Common fleet interfaces, including the VDA 5050 approach promoted in industrial automation, are intended to improve communication between master control systems and vehicles. Customers increasingly test whether a new vehicle can join an existing transport network rather than assuming that each vendor should manage a separate isolated fleet.
Interoperability does not automatically extend to equivalent vehicle performance or safety. Mapping conventions, exception handling, priority logic and software updates must be validated on the actual site. Suppliers therefore compete on deployment engineering and stable interfaces as well as on robot hardware.
Mobile Robotics Is Diversifying Beyond Fixed Guidance
Jungheinrich introduced its EAC 212a high-lift mobile robot in February 2026 with contour-based navigation and three-dimensional pallet recognition. The design illustrates how vehicle builders are adding more flexible localization to equipment performing AGV-like logistics functions. Fixed-guidance systems remain attractive for highly repeatable industrial flows, but natural-feature operation can reduce route-modification work when a facility expands or changes its stock-handling processes.
For plant operators, the purchasing question is whether flexible navigation prevents layout rebuilding and improves uptime enough to justify additional sensing and engineering. The operating case differs between high-volume guided routes and frequently reconfigured warehouse zones.
Automated Truck Loading Links Factory Transport to Dispatch
E80 Group reported laser-guided vehicle operation at Barilla’s Pedrignano plant in September 2026, including automated truck-loading functions integrated with warehouse systems. Transferring pallets between finished-goods storage and vehicle loading can remove another manual handoff from the distribution process. The application is demanding because trailer positioning, floor conditions and loading sequences introduce constraints not present in simple point-to-point routes.
Established FMCG users can benefit from predictable pallet formats and repeat shipment cycles, but facilities with irregular loads will require more complex validation. Buyers increasingly assess AGVs as part of outbound logistics performance, where queueing and dock availability affect the value of transport automation.
Segment Analysis
By Type: Forklift AGVs
Forklift AGVs extend automated handling from horizontal pallet transfer into stacking, rack access and material presentation. Their commercial value is driven by the truck, lift mechanism, load-sensing package and site-specific interfaces required to perform work comparable to manned forklift operations. Suppliers such as Toyota Material Handling, Dematic, Jungheinrich and BALYO address these tasks through different truck and automation architectures, with high-bay applications commanding more engineering effort than simple floor transfer.
This category is projected to approach USD 1.46 billion by 2031 as automated reach and counterbalance trucks gain a larger proportion of AGV spending. Adoption is not uniform: load stability, usable aisle widths and the condition of existing pallets can make autonomous operation difficult. Buyers with frequent, repeatable pallet moves are positioned to secure the strongest returns, while irregular facilities may continue using staffed trucks alongside limited automated routes.
By Industry Vertical: E-Commerce and Logistics
E-commerce and logistics facilities have the widest mix of inbound, buffering, replenishment, and outbound movements, making material-flow coordination a central automation issue. The segment is expected to reach approximately USD 1.41 billion in 2031, supported by automated pallet transport in fulfillment centers and third-party logistics warehouses. AGVs play a different role from piece-picking AMRs: they move handling units and pallets between fixed operational zones while other equipment manages order selection and sortation.
The procurement case strengthens when warehouses face extended shifts and predictable peak transport loads. Fleets require integration with the warehouse management system and dependable priority rules so automated vehicles do not move congestion from one part of the site to another. Modernization cycles, rather than e-commerce growth alone, will determine the timing of major deployments.
By Navigation Technology: Laser Guidance
Laser guidance remains established in industrial fleets because it provides repeatable vehicle positioning without continuous floor-installed tracks. Reflector-based systems suit stable production environments, while E80 Group develops laser-guided pallet fleets for food plants, warehouses and automated truck loading. Purchasers select localization technology alongside docking accuracy, safety functions and fleet dispatch requirements.
The segment is modeled to grow at approximately 7.4% per year through 2031, below the overall market as more flexible vision-led systems gain adoption. Laser guidance should remain important for controlled routes and heavy loads, particularly where legacy infrastructure and application validation favor continuity. Competition is increasingly about integrating guidance, docking and fleet dispatch rather than treating vehicle localization as an isolated feature.
Market Drivers
Automating Repetitive Pallet Movement
Factories and distribution centers run many short, repetitive movements between receiving, processing, storage and dispatch. The labor cost of these tasks can become substantial when operations require several shifts or long internal travel distances. Automated forklifts and tow vehicles replace selected transport cycles without requiring an entire production process to be redesigned.
Stable task volumes make the strongest case for high vehicle utilization. The HELMA installation demonstrates how one integrated AGV can be commercially relevant, although staff remain necessary for supervision and exceptions.
Modernization of High-Density Warehouses
Warehouse operators seeking more storage capacity have an incentive to automate repetitive put-away and retrieval in conventional racking. The Dematic RTS 120 demonstrates how reach-truck AGVs can work within established selective rack configurations. Automation can therefore become part of a retrofit rather than a choice restricted to new warehouses.
Buyers weigh lift accuracy and load reliability against reconstruction costs, staffed-truck use and inventory access times. Suppliers that minimize layout changes can reach more existing warehouses.
Production-Line Sequencing and Supply Reliability
Automotive, electronics and machinery plants use controlled material transport to keep stations supplied without overstocking work-in-progress. Tow tractors and assembly vehicles follow timed routes, while forklift AGVs move packaged components from receiving zones to production buffers. The need for consistent sequence and reduced handling damage supports continued investment in dedicated transport fleets.
Scheduling must accommodate machine cycle times, operating interruptions and loading buffers. Reliable interfaces and commissioning support matter more than maximum vehicle speed for a production-line fleet.
Food and Beverage Automation
Food and beverage manufacturers handle repeated pallet formats between packaging, finished-goods storage and outbound loading. E80 Group’s laser-guided systems at Barilla and other producers illustrate the role of AGVs in high-volume consumer goods operations. In cold and chilled facilities, automation may also reduce the amount of human time required in difficult operating conditions.
Regular schedules and consistent pallets support repeatable handling. The most useful systems connect vehicles with warehouse software and dispatch instead of merely substituting for manual forklifts.
Growing Availability of Integrated Automation Platforms
Industrial truck manufacturers increasingly offer autonomous vehicles alongside conventional lift trucks, software and lifecycle service. Toyota Material Handling, KION and Jungheinrich can address a facility’s mixed transport needs through familiar truck platforms and regional maintenance infrastructure. This reduces the perceived adoption burden for customers already operating conventional equipment from these suppliers.
Service availability reduces long-term operating risk, but customers still need compatible fleet interfaces. Dependence on one vendor for software changes or replacement trucks can undermine flexibility.
Market Restraints
High Initial Integration Expenditure
AGV purchase budgets extend beyond vehicle acquisition to include mapping, traffic analysis, docking infrastructure, safety verification, and connection to production or warehouse software. Existing facilities can require changes to pallet handoff points or protected crossings. These costs are particularly material for smaller sites whose transport tasks fluctuate through the working week.
Procurement should follow measurement of repeatable moves and realistic utilization. Congestion and inconsistent loading can prevent technically capable trucks from generating adequate returns.
Safety Validation in Mixed Human-Vehicle Environments
Industrial AGVs share space with pedestrians, manual forklifts, and changing inventory. The safe stopping distance of a loaded truck, protection of blind corners, and emergency recovery procedures must be validated under local operating conditions. Adding more sophisticated navigation does not eliminate these responsibilities.
Changes to routes, speeds, or racking may require renewed safety acceptance testing. Both reliable sensing and operator discipline remain essential after installation.
Unreliable Pallet and Floor Conditions
Automated fork entry relies on pallets that can be detected and lifted within tolerances. Damaged boards, irregular wrapping and uneven floor transitions create exceptions that experienced human operators often correct informally. In many older buildings, variable aisle clearance adds further complexity.
Commissioning complexity can require backup manual handling. Better sensing reduces some exceptions, but cannot correct recurring pallet damage or inadequate floor conditions.
System Interoperability and Legacy Interfaces
AGV controls must exchange transport requests and completion messages with warehouse and manufacturing software, and fleets may contain vehicles from different suppliers. Uneven interface maturity can make dispatch optimization difficult or result in separate control islands with duplicated infrastructure.
A shared communication standard does not guarantee equivalent robot behavior. Buyers still need validated integration, clear documentation and an upgrade path for mixed fleets.
Demand Cyclicality in Capital Equipment
Automated vehicle purchases are often part of multi-year facility expansion or modernization projects. Industrial investment may be postponed when order volumes weaken, borrowing costs rise or customer demand changes. This can create irregular AGV orders even where the underlying case for reducing manual transport remains sound.
Maintenance and modernization can partly cushion equipment-order volatility. Customers may instead fund one-vehicle projects while delaying larger automation commitments.
Regional Outlook
North America
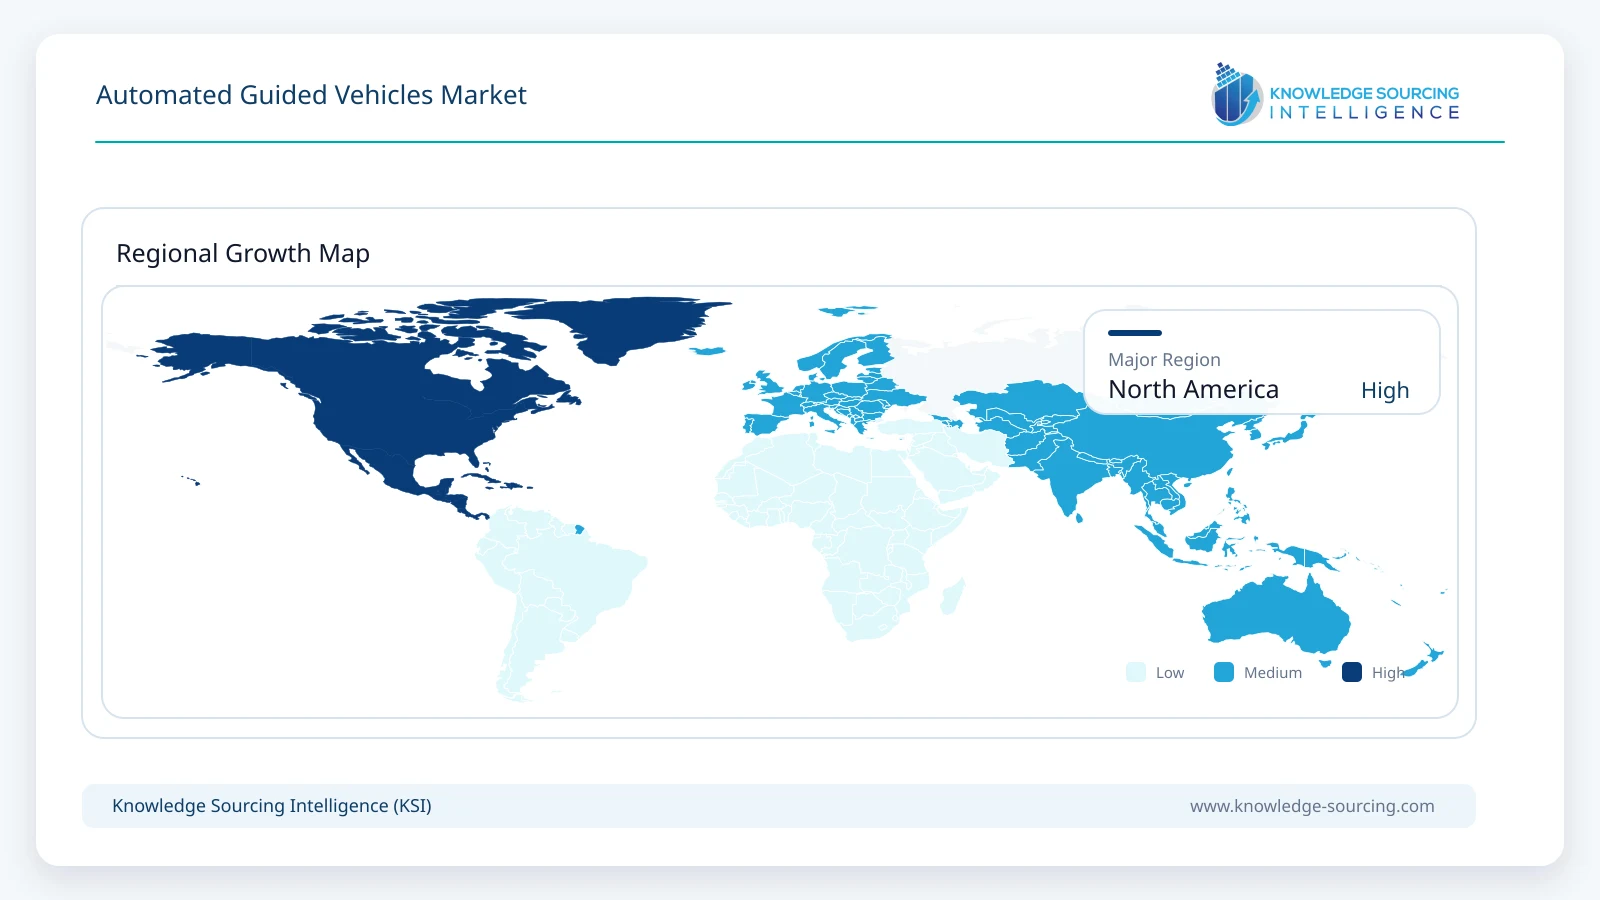
North America is modeled as the largest regional AGV market in 2026, representing approximately 34% of global spending. The United States combines high labor costs with extensive logistics infrastructure and automotive, food processing and semiconductor production sites. Demand encompasses pallet-moving forklifts, production tow vehicles and heavy-load carriers. Established suppliers and systems integrators provide fleet installation and service capabilities for both large distribution centers and manufacturing plants, supporting higher-value automation projects.
Capital intensity keeps North American growth sensitive to project timing. In particular, AGVs must fit the layout and operational discipline of existing warehouses to deliver measurable savings. The regional supplier ecosystem is strong, but standardizing transfers and interfaces across sites remains a major purchasing consideration. Canada and Mexico add opportunities in food logistics and automotive supply chains without having the same scale of high-cost warehouse procurement as the United States.
Asia Pacific
China, Japan and South Korea combine electronics, automotive and logistics automation activity with substantial regional AGV manufacturing capacity. China offers high-volume logistics and production applications, while Japanese suppliers have long experience in precision material transport. India and Southeast Asia are expanding the number of facilities that can justify automated pallet and production-line movement, particularly in newer manufacturing and distribution investments.
Asia Pacific is forecast to record the fastest regional growth, at approximately 12.8% annually through 2031. Increasing adoption of automated logistics among local manufacturers and the expansion of distribution networks support its rising share of global value. Price competition, differences in software integration and uneven service infrastructure across countries will influence supplier selection, so the region’s expansion should not be interpreted as uniform adoption at every site.
Competitive Landscape
Toyota Industries, Dematic, Jungheinrich, Daifuku and Murata Machinery compete through established material-handling engineering, production capability and customer support networks. Their positions are supported by the ability to supply vehicles that handle pallets, trailers or assembly materials alongside software, deployment engineering and maintenance. Forklift-oriented suppliers particularly benefit from familiarity with conventional truck chassis and load-handling requirements. KION’s Dematic business competes in integrated systems, while STILL and Linde offer automated trucks through a broader industrial-vehicle organization.
Specialists differentiate through guidance technology and narrowly defined transport tasks. E80 Group supplies laser-guided pallet flows and truck loading in high-volume consumer goods plants; BALYO focuses on autonomous forklift configurations for varied storage heights; Seegrid supplies autonomous lift trucks and related fleet software. These suppliers do not necessarily compete for the same project economics, because low-level load carriers and high-bay forklifts solve different operating problems. Customer evaluation tends to center on verified throughput, reliable service and realistic integration cost rather than an unsupported global share ranking.
Recent Developments
12 October 2026: E80 Group described a new US automation investment within its long-running Sofidel relationship, extending an integrated intralogistics partnership that has included laser-guided vehicles.
25 September 2026: E80 Group reported automated truck-loading operations at Barilla’s Pedrignano plant using laser-guided vehicles linked with warehouse automation and fleet software.
17 June 2026: Jungheinrich announced an expansion of automated vehicle capacity at Landguth’s distribution center, following commissioning of its automated narrow-aisle facility.
18 May 2026: E80 Group detailed the Refresco Italia Sulmona automation project, including 13 laser-guided vehicles supplying production and finished-goods movements.
19 February 2026: Jungheinrich launched the EAC 212a autonomous high-lift mobile robot with three-dimensional pallet detection and contour-based navigation.
11 November 2025: Dematic introduced its RTS 120 automated reach truck for high-bay selective racking and operation in ambient, chilled and freezer environments.
Market Outlook
AGV purchases will increasingly depend on measurable material-handling outcomes. High-lift forklifts and coordinated fleets that handle standard pallets should capture spending where plants want more automation without wholesale redesign. Guided routes will continue serving repeatable production flows, while flexible navigation expands possible tasks.
Application engineering and service coverage remain valuable where buyers operate mixed fleets over long lifetimes. North America retains substantial high-value procurement; faster Asia Pacific expansion changes the regional demand mix. Reliable interfaces and safety validation carry more weight than broad autonomy claims.
Automated Guided Vehicles Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.87 billion |
| Total Market Size in 2031 | USD 4.41 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Industry Vertical, Navigation Technology, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Tow Vehicles
Forklift AGVs
Unit Load Carriers
Assembly Line Vehicles
Underride/Tunneling AGVs
Hybrid AGVs
By Industry Vertical
Automotive
Food and Beverage
E-Commerce and Logistics
Healthcare and Pharmaceuticals
Electronic and Semiconductors
Aerospace and Defense
Chemicals
Others
By Navigation Technology
Laser Guidance
Magnetic Guidance
Vision Guidance
Inductive Guidance
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Automating Repetitive Pallet Movement
3.1.2. Modernization of High-Density Warehouses
3.1.3. Production-Line Sequencing and Supply Reliability
3.1.4. Food and Beverage Automation
3.1.5. Growing Availability of Integrated Automation Platforms
3.2. Market Restraints
3.2.1. High Initial Integration Expenditure
3.2.2. Safety Validation in Mixed Human-Vehicle Environments
3.2.3. Unreliable Pallet and Floor Conditions
3.2.4. System Interoperability and Legacy Interfaces
3.2.5. Demand Cyclicality in Capital Equipment
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Laser and Reflector Guidance
4.2. Vision Guidance and Localization
4.3. Fleet Interoperability and Software Interfaces
4.4. Safety Sensing and Load Detection
5. AUTOMATED GUIDED VEHICLES MARKET BY TYPE
5.1. Introduction
5.2. Tow Vehicles
5.3. Forklift AGVs
5.4. Unit Load Carriers
5.5. Assembly Line Vehicles
5.6. Underride/Tunneling AGVs
5.7. Hybrid AGVs
6. AUTOMATED GUIDED VEHICLES MARKET BY INDUSTRY VERTICAL
6.1. Introduction
6.2. Automotive
6.3. Food and Beverage
6.4. E-Commerce and Logistics
6.5. Healthcare and Pharmaceuticals
6.6. Electronic and Semiconductors
6.7. Aerospace and Defense
6.8. Chemicals
6.9. Others
7. AUTOMATED GUIDED VEHICLES MARKET BY NAVIGATION TECHNOLOGY
7.1. Introduction
7.2. Laser Guidance
7.3. Magnetic Guidance
7.4. Vision Guidance
7.5. Inductive Guidance
8. AUTOMATED GUIDED VEHICLES MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Toyota Industries Corporation
10.2. Dematic (KION Group)
10.3. Jungheinrich AG
10.4. Daifuku Co., Ltd.
10.5. Murata Machinery, Ltd.
10.6. E80 Group S.p.A.
10.7. BALYO S.A.
10.8. KUKA AG
10.9. Seegrid Corporation
10.10. Mitsubishi Logisnext Co., Ltd. (Rocla AGV Solutions)
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected Automated Guided Vehicles market size for 2031?
The Automated Guided Vehicles Market is projected to reach USD 4.41 billion by 2031.
What is the AGV market's projected CAGR (2026-2031)?
The Automated Guided Vehicles Market is projected to grow at approximately 9.0% CAGR.
Which AGV vehicle type leads market value in 2026?
Forklift AGVs represent approximately 29% of 2026 market value.
Which industries drive the most AGV market demand?
E-commerce and logistics contribute roughly 30% of demand.
What guidance technology held the largest 2026 revenue share?
Laser guidance remains established, representing around 42% revenue.
Which region is gaining market share in AGV adoption?
Asia Pacific is gaining share due to local manufacturing growth.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Automated Guided Vehicles Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automated-guided-vehicle-market