
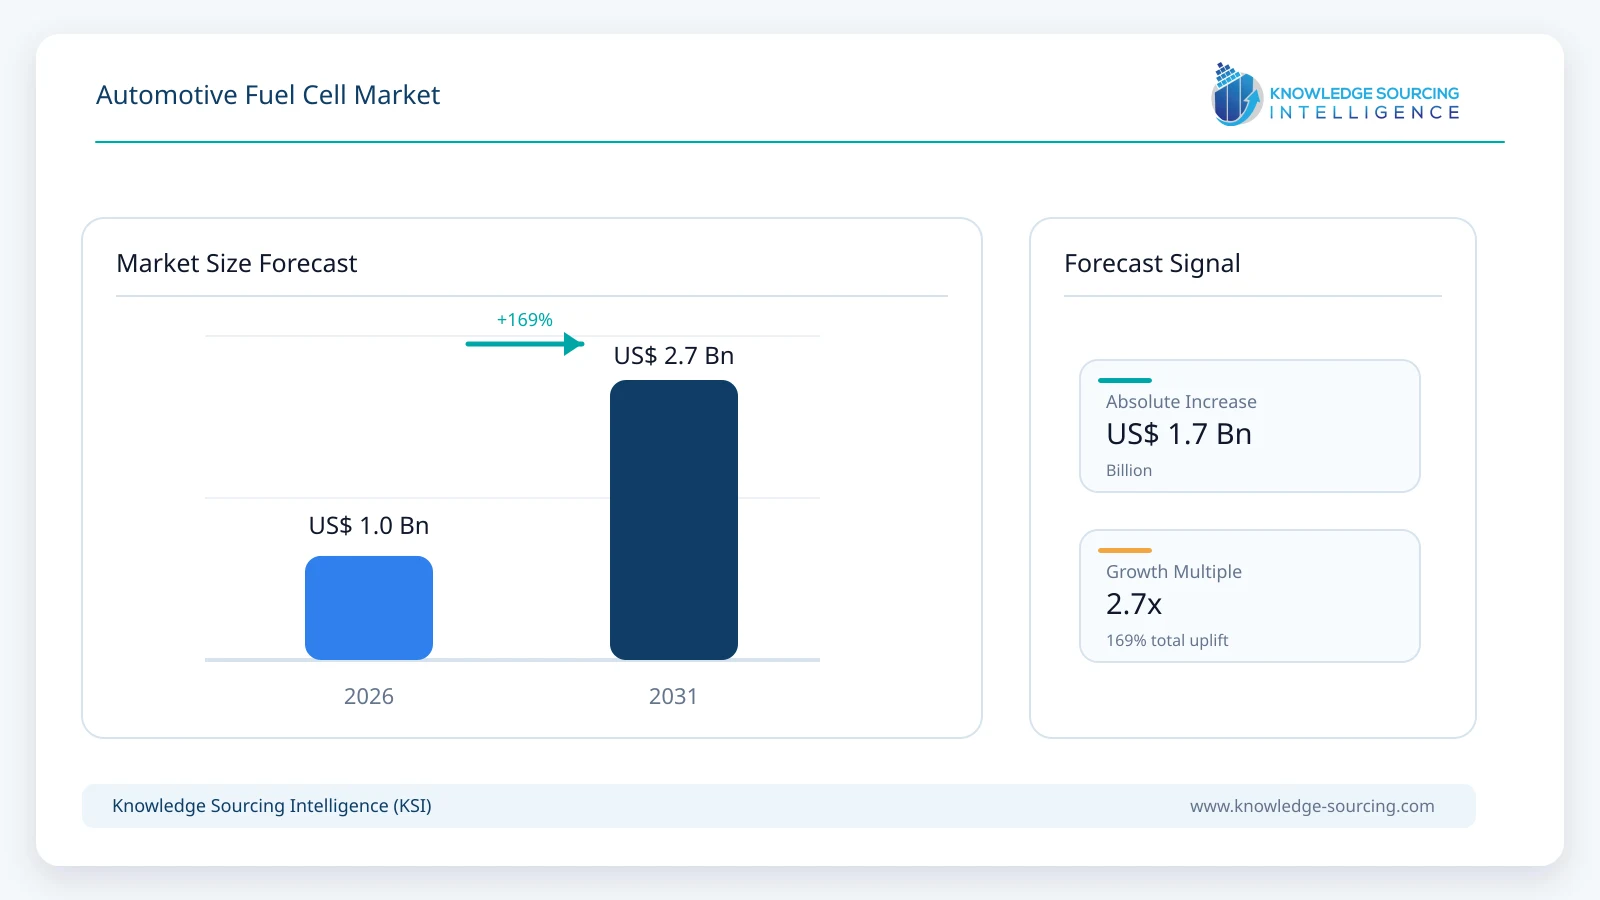
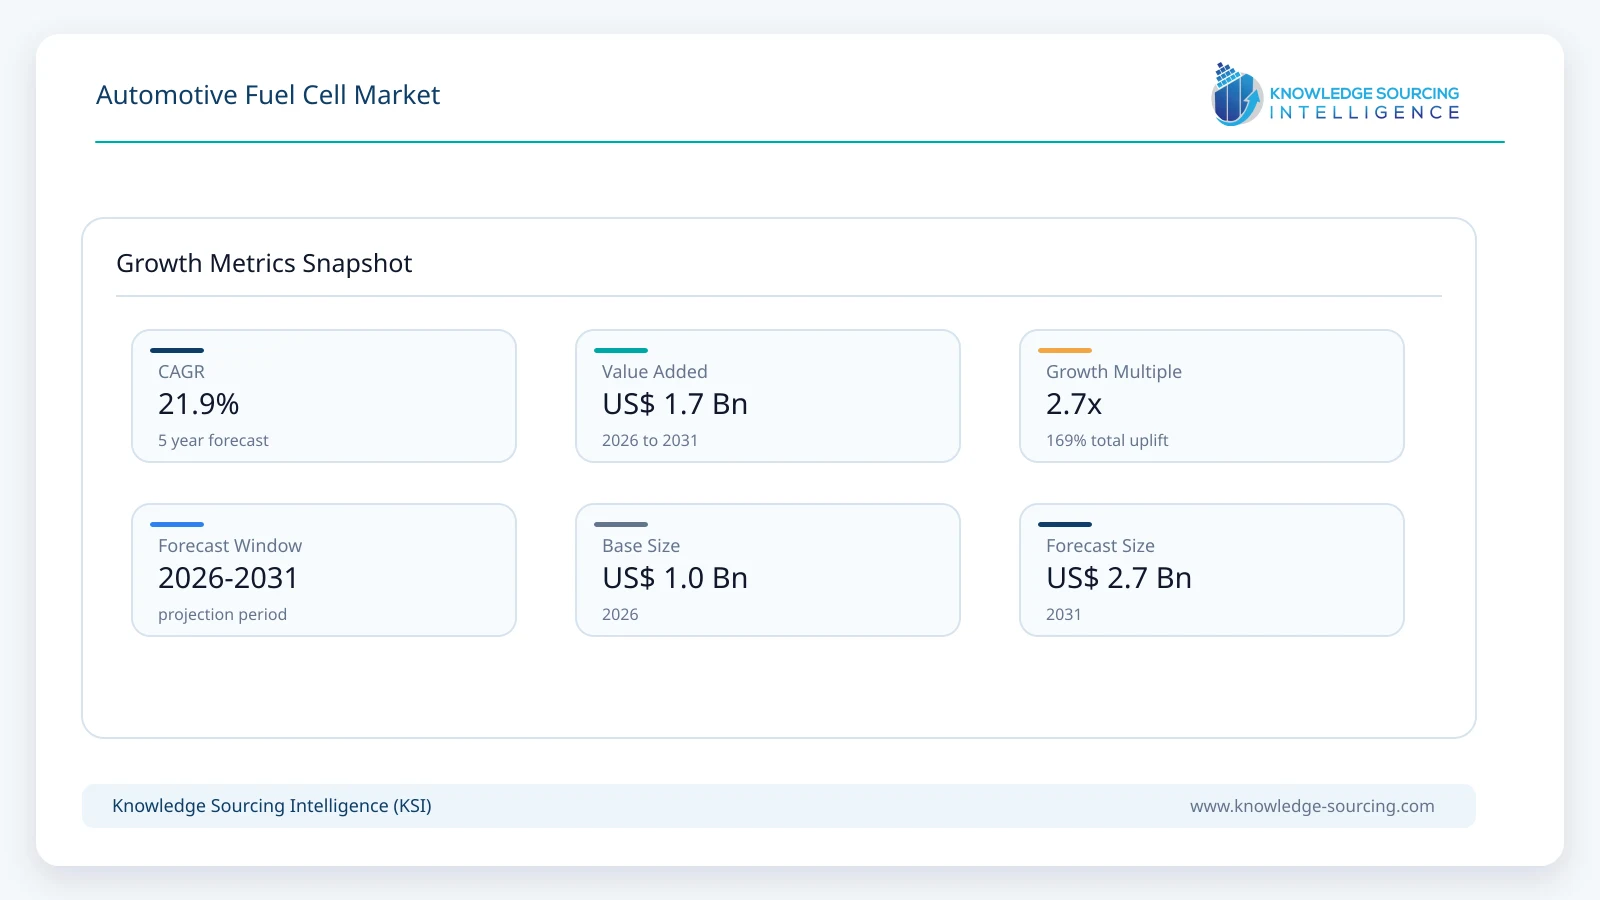
The Automotive Fuel Cell Market is expected to grow at a CAGR of 21.9%, reaching USD 2.69 billion in 2031 from USD 1.00 billion in 2026.
Highlights:
- 1Truck applications account for an estimated 43% of initial market value as suppliers prioritize high-duty-cycle fleets.
- 2Fuel-cell stacks remain the largest hardware value pool, with balance-of-plant engineering shaping system integration.
- 3Hydrogen PEM systems dominate commercial vehicle deployment; alcohol-based automotive applications remain marginal.
- 4Asia Pacific leads demand, supported by Chinese commercial fleets and South Korean passenger vehicles.
- 5European growth is supported by fuel-cell truck development and planned hydrogen corridor infrastructure.
Fuel-cell propulsion systems convert hydrogen and oxygen electrochemically into electricity, with a traction battery or high-power buffer managing transient loads and regenerative braking. Revenue in the automotive fuel-cell market is generated by vehicle-qualified stacks and associated air, fuel, humidity and power-conditioning equipment supplied for road vehicles, together with directly attributable integration and service content. Demand comes from fleet operators and automotive manufacturers requiring zero-tailpipe-emission transport over duty cycles where energy replenishment time, payload or utilization creates a credible operating case.
Hyundai offers a new NEXO passenger system, while Toyota is adapting its third-generation fuel-cell technology for commercial use. Ballard supplies heavy-duty PEM engines for transit-bus programs and cellcentric develops fuel-cell systems for commercial trucking. Buyers increasingly evaluate the fuel-cell package as a validated power system rather than a standalone electrochemical stack; service life, thermal control, availability and refuelling conditions influence the purchasing decision.
Market Overview
A vehicle fuel-cell system contains a membrane electrode assembly, bipolar plates, supporting seals, an air supply path, hydrogen metering, thermal controls and power electronics. In heavy-duty road use, engineering priorities include sustained output at variable temperatures, repeated start-stop events and predictable degradation after thousands of operating hours. A stack designed for a passenger car cannot simply be enlarged for a freight truck without revisiting cooling, air compression, system redundancy and service access.
Toyota introduced its third-generation fuel-cell platform in February 2025 with a focus on commercial durability, fuel efficiency and lower production cost. Hyundai’s latest NEXO incorporates a 110 kW gross-output stack and revised power electronics; the commercial relevance extends beyond vehicle range to component packaging and cold-weather operation. Ballard’s agreement to supply 500 fuel-cell bus engines to New Flyer illustrates a different purchasing model in which an engine supplier provides qualified modules to a bus manufacturer across repeated fleet orders.
Manufacturing remains concentrated in firms able to coordinate membrane-electrode production, bipolar-plate processing, sealing, stack assembly and final vehicle validation. Subcontractors supply catalysts, membranes and air-management components, but integrated system suppliers bear the burden of demonstrating durability and field performance. Local hydrogen supply has an unusually strong effect on demand: reliable depot-scale refuelling can sustain recurring system purchases, whereas an isolated station often cannot support an economically useful fleet.
Market Trends
Commercial Vehicle Programs Are Becoming the Main Volume Test
China’s fuel-cell truck and bus deployments provide the largest recurring field base for automotive stacks, while European and North American orders are increasingly tied to defined depots and routes. The IEA reported that global FCEV stock approached 130,000 in 2025, with recent growth supported by Chinese truck deployment and recovering Korean passenger sales. For vendors, this creates two distinct engineering pathways: compact systems optimized for car cost and packaging, and high-durability power modules intended to maintain output under heavy commercial utilization.
Fuel-cell bus orders are also becoming more explicit commitments. Ballard’s March 2026 agreement with New Flyer covers 500 FCmove-HD+ engines totalling 50 MW, with deliveries beginning in 2026. This is a supplier order rather than proof that the full quantity has already entered service, but it indicates how a repeat chassis platform can reduce engineering cost for subsequent fleet procurements.
Stack Durability and Balance-of-Plant Efficiency Determine Cost
Toyota’s third-generation development emphasizes commercial-vehicle durability and lower fuel-cell system cost, while Honda has specified a new 150 kW module intended to improve durability and power density. Efficiency gains need to extend beyond the membrane-electrode assembly: compressors, humidifiers and cooling pumps consume energy, affecting hydrogen demand over a full duty cycle. Suppliers that optimize these auxiliary loads without compromising membrane hydration or cold starts can improve fuel economy and stack life together.
Design changes must still be validated in actual vehicles. High-speed drive cycles and rapid power changes require coordination with the traction battery, while heavy trucks may operate for long periods at relatively high loads. Reusable component platforms can help manufacturers move across bus and truck programs, but operating hours and thermal-management requirements make direct interchangeability difficult.
Hydrogen Corridors Are Tied to Specific Freight Use Cases
European infrastructure policy requires publicly accessible hydrogen stations along the TEN-T core network at a maximum interval of 200 km by the end of 2030, with capacity and dispensing specifications. The requirement creates a potential enabling condition for intercity freight, but it does not mean those corridors are already usable. Station throughput, service reliability and hydrogen pricing determine whether a nominally completed network can support commercial truck operations.
Fleet operators are likely to commit first where depots, production sites and frequent routes share a fueling plan. That favours bus operators, port logistics and regional freight before dispersed light-duty consumer demand. Fuel-cell suppliers therefore face a narrower but potentially more bankable customer base than the total automotive fleet.
Heavy-Duty Partnerships Are Reorganizing the Supplier Ecosystem
Toyota, Daimler Truck and Volvo Group signed a binding agreement in July 2026 for Toyota to become an equal shareholder in cellcentric, subject to regulatory approvals. The proposed ownership structure would combine multiple heavy-duty vehicle applications with technology development and industrial scale. For suppliers, such consolidation changes the sourcing landscape: a few validated platforms may account for a substantial portion of future fuel-cell truck purchases.
The transition is not uniform. Honda’s January 2026 decision to discontinue the current Honda–GM joint-venture system before year-end illustrates how a manufacturer can retire one production architecture while investing in a next-generation system. Announced partnerships and technology demonstrations should therefore be distinguished from production deliveries and contracted automotive revenue.
Segment Analysis
By Vehicle Type: Trucks
Trucks account for approximately 43% of 2026 market value, reflecting larger fuel-cell systems and substantial balance-of-plant content per vehicle. Long-haul and regional freight fleets can utilize depot or corridor hydrogen supply repeatedly, allowing system expenditure to be evaluated against fuel costs, turnaround time and payload. China has established a concentration of commercial hydrogen vehicles, while European OEM partnerships indicate growing attention to vehicle-qualified fuel-cell modules for heavy trucks.
Heavy-duty fuel-cell revenue is expected to expand as validated truck platforms reach fleet procurement, but orders remain concentrated in selected routes rather than mass-market distribution. Reliability during sustained operation, system diagnostics and maintenance support will influence whether suppliers retain repeat business after pilot phases.
By Component: Fuel Cell Stacks
Fuel-cell stacks deliver the electrochemical conversion capacity at the centre of the propulsion system. Their manufacturing combines catalyst-coated membranes, gas-diffusion layers, bipolar plates, gaskets and precisely controlled compression. Product cost is therefore sensitive to production yields, materials selection, automated assembly and the lifetime performance of the membrane-electrode assembly.
This component represents approximately USD 1.54 billion of the projected 2031 value. Growing production can spread tooling expenditure across more units, but heavy-duty requirements for longevity and stack replacement may offset some material savings. Suppliers compete on demonstrated output retention under real vehicle conditions, not peak laboratory power density alone.
By Propulsion: Fuel Cell Electric Vehicles
Fuel-cell-dominant electric propulsion represents the largest purchasing category because the stack provides the main energy input while the battery buffers transient loads. Hyundai’s NEXO and Toyota’s Mirai demonstrate passenger configurations, whereas bus and truck installations may combine larger stack modules with substantial batteries for regenerative braking and route-specific power management.
The segment is projected to generate roughly USD 2.10 billion in 2031. A separate fuel-cell-hybrid category captures designs where a much larger traction battery and electric drive are central to daily operation, with the fuel cell deployed principally as a range-extending supply. The boundary is based on the intended energy architecture, not merely the presence of any battery.
By Fuel Type: Hydrogen
Commercial automotive fuel-cell development overwhelmingly uses hydrogen-fed polymer-electrolyte membranes because they offer rapid response, compact vehicle integration and established refuelling protocols. The hydrogen-fuelled category accounts for more than 99% of the estimated 2026 value. Oxygen is supplied from ambient air in most road applications, while hydrogen quality and water management are critical to catalyst and membrane durability.
Methanol and ethanol can be processed for electricity through other fuel-cell or reformer architectures, but evidence of serially produced road-vehicle propulsion using these fuels remains limited. They remain small technical categories rather than near-term alternatives of comparable commercial weight to compressed-hydrogen automotive stacks.
Market Drivers
Fleet Decarbonization Requirements on Intensive Routes
Urban bus procurement and freight-fleet decarbonization are creating cases for zero-tailpipe-emission vehicles with high daily utilization. Fuel-cell buses can return to a limited number of depots, allowing investment in hydrogen equipment to serve multiple vehicles and facilitating planned maintenance. Hydrogen trucks face a more demanding infrastructure problem but can benefit where corridors are used repeatedly by predictable freight flows.
Contracted fleet purchases support fuel-cell orders when operators can evaluate vehicle availability, maintenance and hydrogen price together, rather than assessing propulsion technology in isolation.
Commercial-Grade Durability Improvements
Commercial vehicles require long operating life, repeated thermal cycles and sustained power output. Toyota’s third-generation fuel-cell program and Honda’s planned next-generation module are intended to improve durability and system economics. Better stack-life predictability reduces replacement risk for operators and helps component suppliers negotiate multi-year programs.
Validated gains in compressor efficiency, humidification and thermal management can make a durable system more economical even without a sharp decline in initial stack price.
Repeat OEM Platforms and Supplier Commitments
Orders tied to an established vehicle platform create a more credible manufacturing schedule than dispersed prototype activity. Ballard’s New Flyer agreement provides a defined fuel-cell engine supply commitment, while the Toyota–cellcentric agreement illustrates attempts to share development and industrialization across commercial-vehicle programs.
The supplier benefit is a larger repeatable production base, although contract dates and delivery schedules must be distinguished from revenue recognition.
Hydrogen Network Development in Targeted Markets
European AFIR requirements establish a 2030 direction for publicly accessible hydrogen infrastructure along major routes and in urban nodes. China’s localized hydrogen-industry clusters have already supported commercial vehicle use, while targeted stations in Japan and Korea serve established transport fleets and passenger demand.
Infrastructure works best as a demand catalyst when installed supply, vehicle orders and reliable station operations are planned together.
System Integration and Component Reuse
Automakers purchasing a qualified stack-and-balance-of-plant system reduce the number of critical vehicle interfaces they must validate. Standardized electrical and thermal architectures allow fuel-cell developers to reuse core control logic, power conditioning and diagnostic functions across different programs.
For established suppliers, this can lower engineering expenditure per vehicle and increase the chance of follow-on awards after an initial fleet launch.
Market Restraints
Hydrogen Availability and Total Cost of Ownership
Fuel-cell vehicle economics are closely tied to delivered hydrogen price, station utilization and equipment maintenance. The IEA reports that low-emissions hydrogen remains more expensive than conventional hydrogen in most regions, while infrastructure and firm offtake have developed more slowly than earlier plans.
Where fleet hydrogen costs remain uncertain, operators may choose battery-electric vehicles even when a fuel cell could meet the technical duty cycle.
Competition from Battery-Electric Trucks and Buses
The IEA estimated that battery-electric vehicles represented 97% of electric truck sales in 2025. Better battery pricing, charging availability and depot integration provide direct competition on routes that do not require hydrogen refuelling.
Fuel-cell suppliers must demonstrate measurable value in range, payload, refuelling availability or fleet uptime rather than assuming all zero-emission truck demand will migrate toward hydrogen.
Stack Degradation and Maintenance Requirements
Variable power demand, catalyst contamination, cold starts and humidification faults can reduce membrane performance over time. Commercial warranty obligations also require field-service infrastructure and reliable fault diagnostics, both of which raise upfront qualification costs.
Limited production volumes restrict the pool of long-duration fleet data available for proving the economics of each new stack architecture.
Mismatch Between Demonstrations and Serial Production
Hydrogen vehicle announcements often describe prototypes, limited customer trials or future target dates rather than firm annual production. Such programs can consume substantial engineering resources without generating repeated stack sales.
Automakers and component suppliers must avoid adding speculative fleet quantities to capacity plans before vehicle nominations and fuel contracts become executable.
High-Complexity Component Supply Chains
Membranes, catalyst coatings, specialized bipolar plates, compressors and pressure-resistant hydrogen components must satisfy stringent durability requirements. Even when components are technically available, low batch volumes and platform-specific qualification create procurement friction.
Uncertain order volumes make it difficult for subcomponent manufacturers to justify automation and additional plant capacity, slowing unit-cost reductions.
Regional Outlook
Asia Pacific
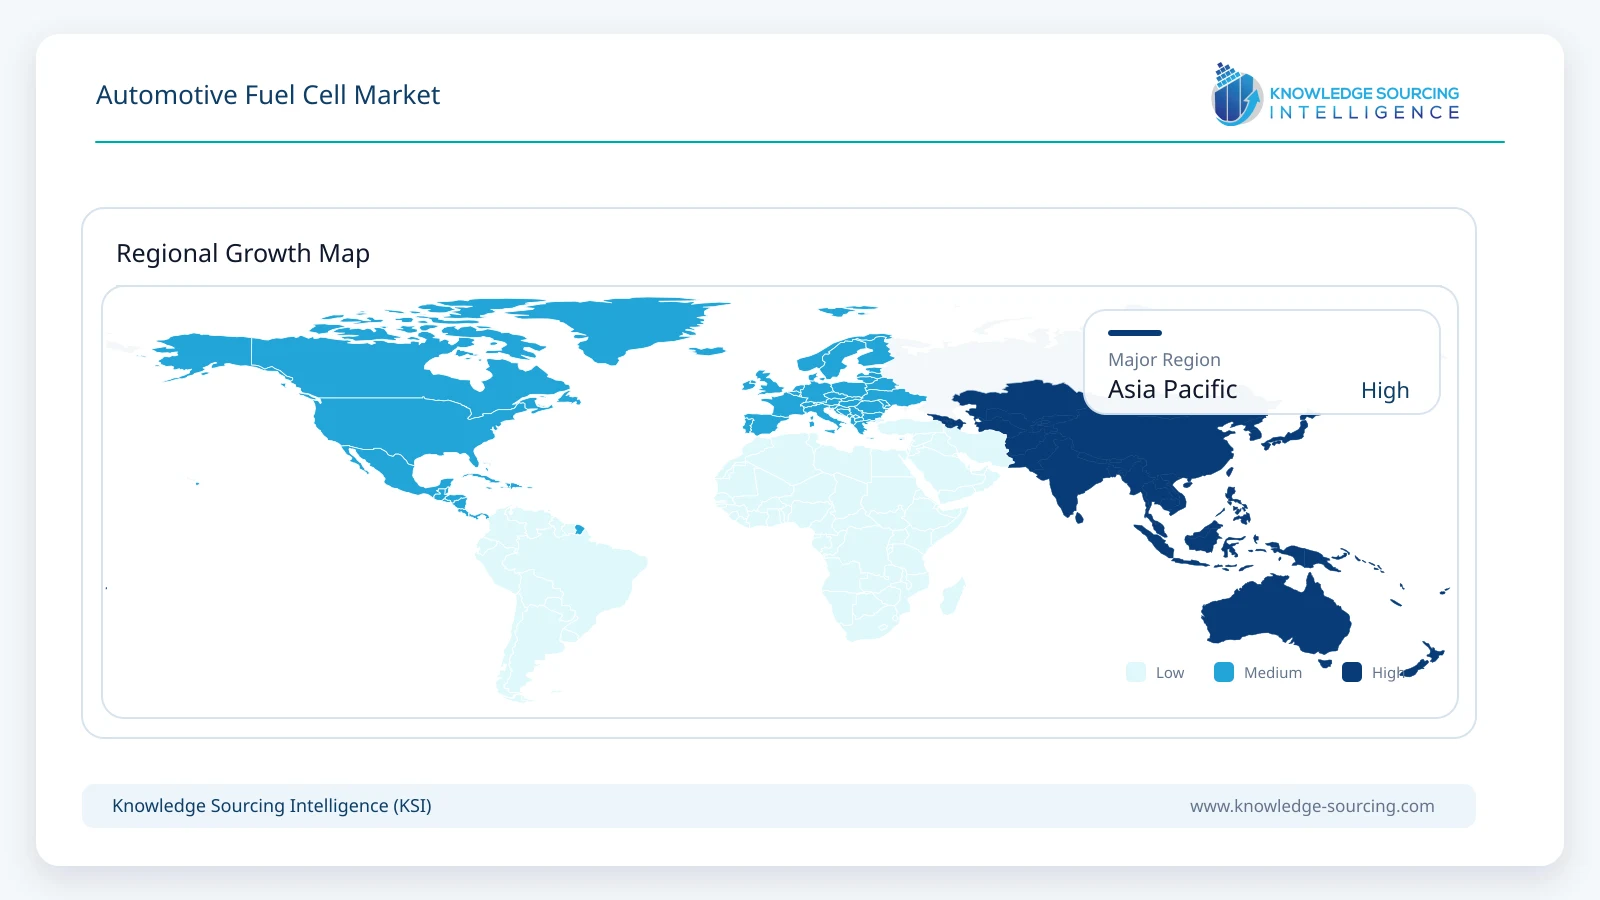
Asia Pacific accounts for approximately 60% of global automotive fuel-cell system value in 2026. China underpins commercial demand through truck and bus deployments, while South Korea remains a leading passenger fuel-cell market through Hyundai and associated suppliers. Japan contributes through Toyota’s fuel-cell platform and industrial partnerships, including the April 2026 light-duty truck development agreement with Isuzu. The region combines vehicle assembly, fuel-cell component production and hydrogen-cluster programs, although the distribution of demand varies sharply among countries.
Revenue is projected to reach approximately USD 1.45 billion in 2031 as commercial installations increase and automotive manufacturers scale validated systems. Chinese truck procurement remains especially significant; Korean passenger demand is more sensitive to retail fueling availability and the ability of a limited number of vehicle models to attract customers.
Europe
European demand is shaped by fuel-cell bus programs, OEM truck development and regulatory expectations for hydrogen infrastructure. The region is estimated to expand at about 31.2% annually between 2026 and 2031, making it the fastest-growing regional market within this forecast. The planned Toyota involvement in cellcentric, alongside ongoing industrial projects from heavy-duty vehicle makers, gives the region a concentration of system engineering even before broad heavy-truck rollout.
EU refuelling rules call for a minimum hydrogen-station network across the TEN-T core corridors by 2030. Achieving the policy target would improve route coverage, but service reliability and delivered fuel cost will still determine how many fleet orders convert from trial vehicles to recurring deployments. Germany, France and the United Kingdom are particularly relevant for supplier development and early fleet deployment.
Competitive Landscape
Automotive fuel-cell competition has several layers. Toyota and Hyundai combine vehicle development with proprietary stack and control technologies; Honda is preparing a new fuel-cell system as it winds down a previous joint-venture product. Ballard focuses on externally supplied PEM engines, notably for buses. Bosch provides commercial fuel-cell power modules and associated automotive integration, while cellcentric is building a heavy-duty truck platform intended for supply across multiple OEM customers.
Specialist system and stack developers such as EKPO Fuel Cell Technologies, SinoHytec, Weichai Power and Horizon Fuel Cell Technologies participate in distinct vehicle programs and regional supply networks. The basis of competition is not merely installed electrical output. Commercial buyers assess stack life, mass and volume, balance-of-plant consumption, service accessibility, validation history and the supplier’s ability to maintain quality over repeated orders. Supplier revenue cannot be inferred directly from the selling price of the vehicle, and planned partnerships are not equivalent to completed system deliveries.
Recent Developments
5 October 2026: Toyota Motor Corporation launched its updated Sora fuel-cell route bus, extending its vehicle-level hydrogen propulsion offering.
27 August 2026: EKPO Fuel Cell Technologies and Akkodis began on-road testing of an NM20 fuel-cell stack in a 40-tonne hydrogen truck for logistics duty.
27 July 2026: Toyota, Volvo Group and Daimler Truck signed a binding agreement for Toyota to join cellcentric as an equal shareholder, subject to regulatory approvals.
15 April 2026: Isuzu and Toyota announced joint development of a light-duty fuel-cell electric truck using Toyota’s third-generation system, targeting production in FY2027.
11 March 2026: Ballard announced an agreement to supply 500 FCmove-HD+ bus engines to New Flyer, with deliveries commencing in 2026.
20 January 2026: Honda announced that production of the current Honda–GM fuel-cell system would end before the close of 2026 as it transitions to its independently developed successor.
Market Outlook
Automotive fuel-cell adoption through 2031 is likely to be determined by the economics of individual fleets rather than a uniform transition across all vehicle classes. Heavy trucks and buses have the clearest prospective value where hydrogen supply can be concentrated and utilization is high, while the passenger-car market remains dependent on a limited set of OEM offerings and an uneven refuelling network. Procurement will also depend on whether improvements in fuel-cell durability and production costs translate into affordable maintenance contracts.
Asia Pacific should remain the largest regional market, while Europe may develop faster from its smaller base if announced truck platforms and hydrogen infrastructure move into dependable service. Manufacturers with validated, modular fuel-cell systems and credible field-support networks are better positioned than firms relying on technology demonstrations alone. Increasing production will reduce some component costs, but delivered hydrogen prices, battery-electric competition and project timing remain decisive constraints.
Automotive Fuel Cell Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.00 billion |
| Total Market Size in 2031 | USD 2.69 billion |
| Forecast Unit | Billion |
| Growth Rate | 21.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Vehicle Type, Component, Propulsion, Fuel Type, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Vehicle Type
Buses
Light Commercial Vehicles (LCVs)
Passenger Cars
Trucks
By Component
Air Compressors
Fuel Compressors
Fuel Cell Stacks
Humidifiers
Power Conditioners
By Propulsion
Fuel Cell Electric Vehicles (FCEV)
Fuel Cell Hybrid Electric Vehicles (FCHEV)
By Fuel Type
Hydrogen
Methanol
Ethanol
By Geography
Asia Pacific
China
South Korea
Japan
India
Taiwan
Thailand
Indonesia
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
North America
United States
Canada
Mexico
Middle East and Africa
Saudi Arabia
United Arab Emirates
Others
South America
Brazil
Argentina
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Fleet Decarbonization Requirements on Intensive Routes
3.1.2. Commercial-Grade Durability Improvements
3.1.3. Repeat OEM Platforms and Supplier Commitments
3.1.4. Hydrogen Network Development in Targeted Markets
3.1.5. System Integration and Component Reuse
3.2. Market Restraints
3.2.1. Hydrogen Availability and Total Cost of Ownership
3.2.2. Competition from Battery-Electric Trucks and Buses
3.2.3. Stack Degradation and Maintenance Requirements
3.2.4. Mismatch Between Demonstrations and Serial Production
3.2.5. High-Complexity Component Supply Chains
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. PEM Fuel-Cell Stack Design and Durability
4.2. Balance-of-Plant and Hydrogen Delivery
4.3. Fuel-Cell and Battery Power Management
4.4. Automotive Validation and Manufacturing Scale-Up
5. AUTOMOTIVE FUEL CELL MARKET BY VEHICLE TYPE
5.1. Introduction
5.2. Buses
5.3. Light Commercial Vehicles (LCVs)
5.4. Passenger Cars
5.5. Trucks
6. AUTOMOTIVE FUEL CELL MARKET BY COMPONENT
6.1. Introduction
6.2. Air Compressors
6.3. Fuel Compressors
6.4. Fuel Cell Stacks
6.5. Humidifiers
6.6. Power Conditioners
7. AUTOMOTIVE FUEL CELL MARKET BY PROPULSION
7.1. Introduction
7.2. Fuel Cell Electric Vehicles (FCEV)
7.3. Fuel Cell Hybrid Electric Vehicles (FCHEV)
8. AUTOMOTIVE FUEL CELL MARKET BY FUEL TYPE
8.1. Introduction
8.2. Hydrogen
8.3. Methanol
8.4. Ethanol
9. AUTOMOTIVE FUEL CELL MARKET BY GEOGRAPHY
9.1. Introduction
9.2. Asia Pacific
9.2.1. China
9.2.2. South Korea
9.2.3. Japan
9.2.4. India
9.2.5. Taiwan
9.2.6. Thailand
9.2.7. Indonesia
9.2.8. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. North America
9.4.1. United States
9.4.2. Canada
9.4.3. Mexico
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. United Arab Emirates
9.5.3. Others
9.6. South America
9.6.1. Brazil
9.6.2. Argentina
9.6.3. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Toyota Motor Corporation
11.2. Hyundai Motor Company
11.3. Ballard Power Systems Inc.
11.4. Robert Bosch GmbH
11.5. cellcentric GmbH & Co. KG
11.6. Honda Motor Co., Ltd.
11.7. EKPO Fuel Cell Technologies GmbH
11.8. Sino-Synergy Hydrogen Energy Technology (Jiaxing) Co., Ltd.
11.9. SinoHytec Co., Ltd.
11.10. Weichai Power Co., Ltd.
11.11. Horizon Fuel Cell Technologies Pte. Ltd.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected market size and growth rate for automotive fuel cells?
Reaches $2.69 billion by 2031, growing at 21.9% CAGR.
Which application segment leads the initial Automotive Fuel Cell Market?
Truck applications account for an estimated 43% of initial market value.
What constitutes the largest hardware value pool in fuel cell systems?
Fuel-cell stacks remain the largest hardware value pool.
Which region leads demand in the Automotive Fuel Cell Market?
Asia Pacific leads demand, driven by China and South Korea.
Which fuel cell system dominates commercial vehicle deployment?
Hydrogen PEM systems dominate commercial vehicle deployment.
What drives demand for automotive fuel cell transport?
Zero-tailpipe-emission transport over specific duty cycles drives demand.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Automotive Fuel Cell Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automotive-fuel-cell-market