
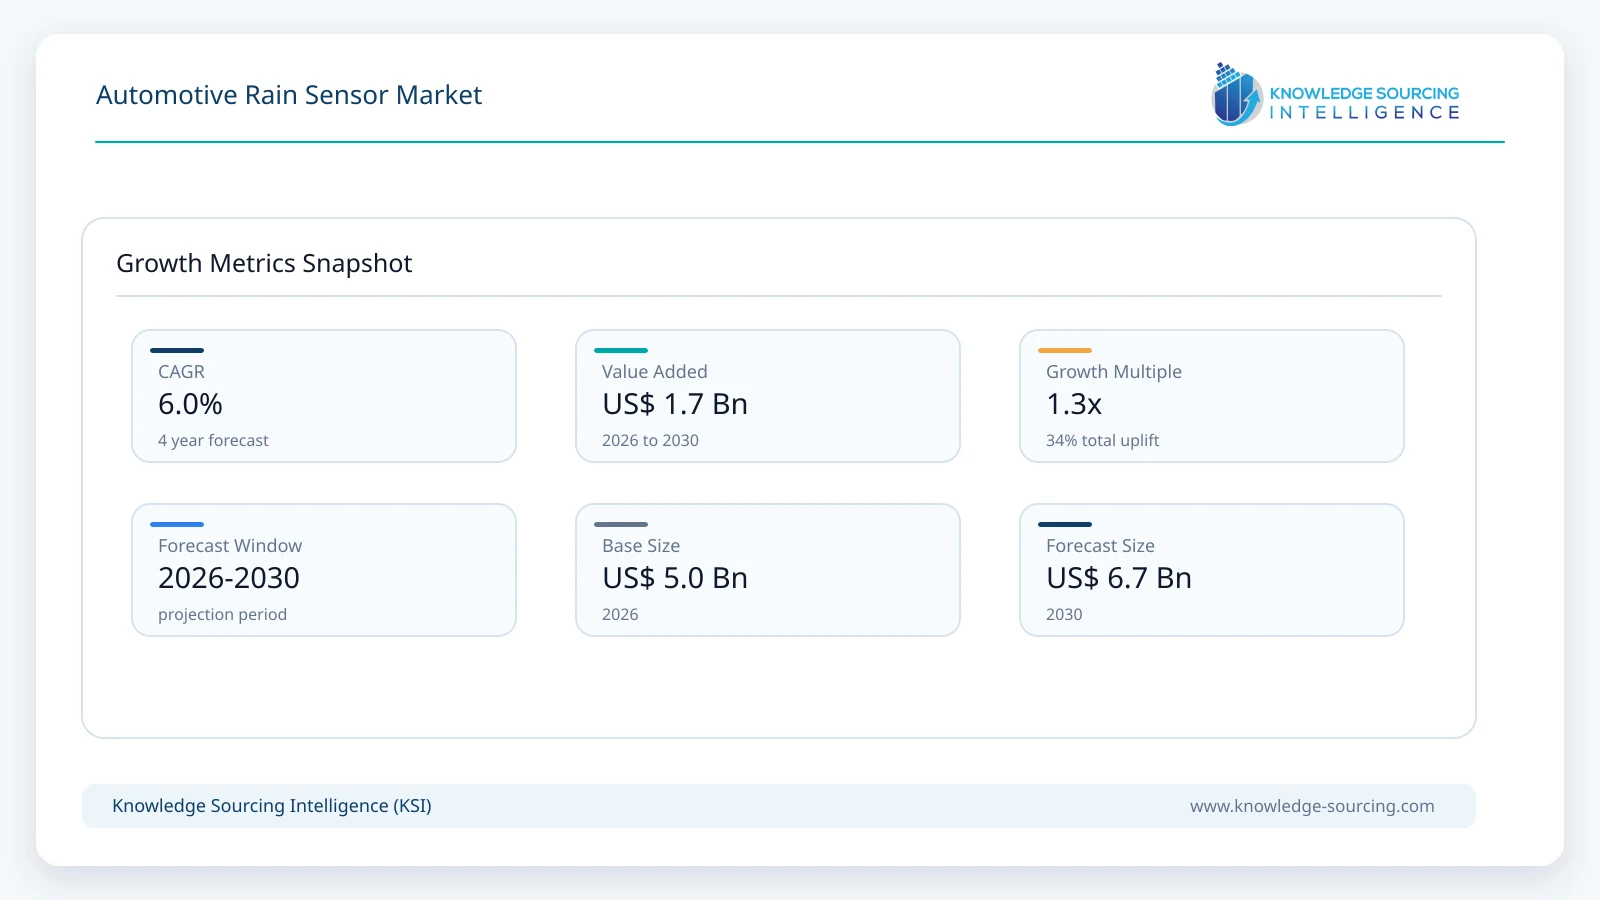
The Automotive Rain Sensor Market is expected to grow at a CAGR of 6.0%, reaching USD 6.71 billion in 2031 from USD 5.01 billion in 2026.
Highlights:
- 1OEM-installed systems represent an estimated 94% of 2026 market value, reflecting factory integration.
- 2Passenger vehicles account for most demand as automatic wiping extends into volume models.
- 3Integrated rain-light modules increasingly support humidity, solar-load and display-brightness functions.
- 4Windshield variation and sunlight interference make sensor calibration a critical supplier capability.
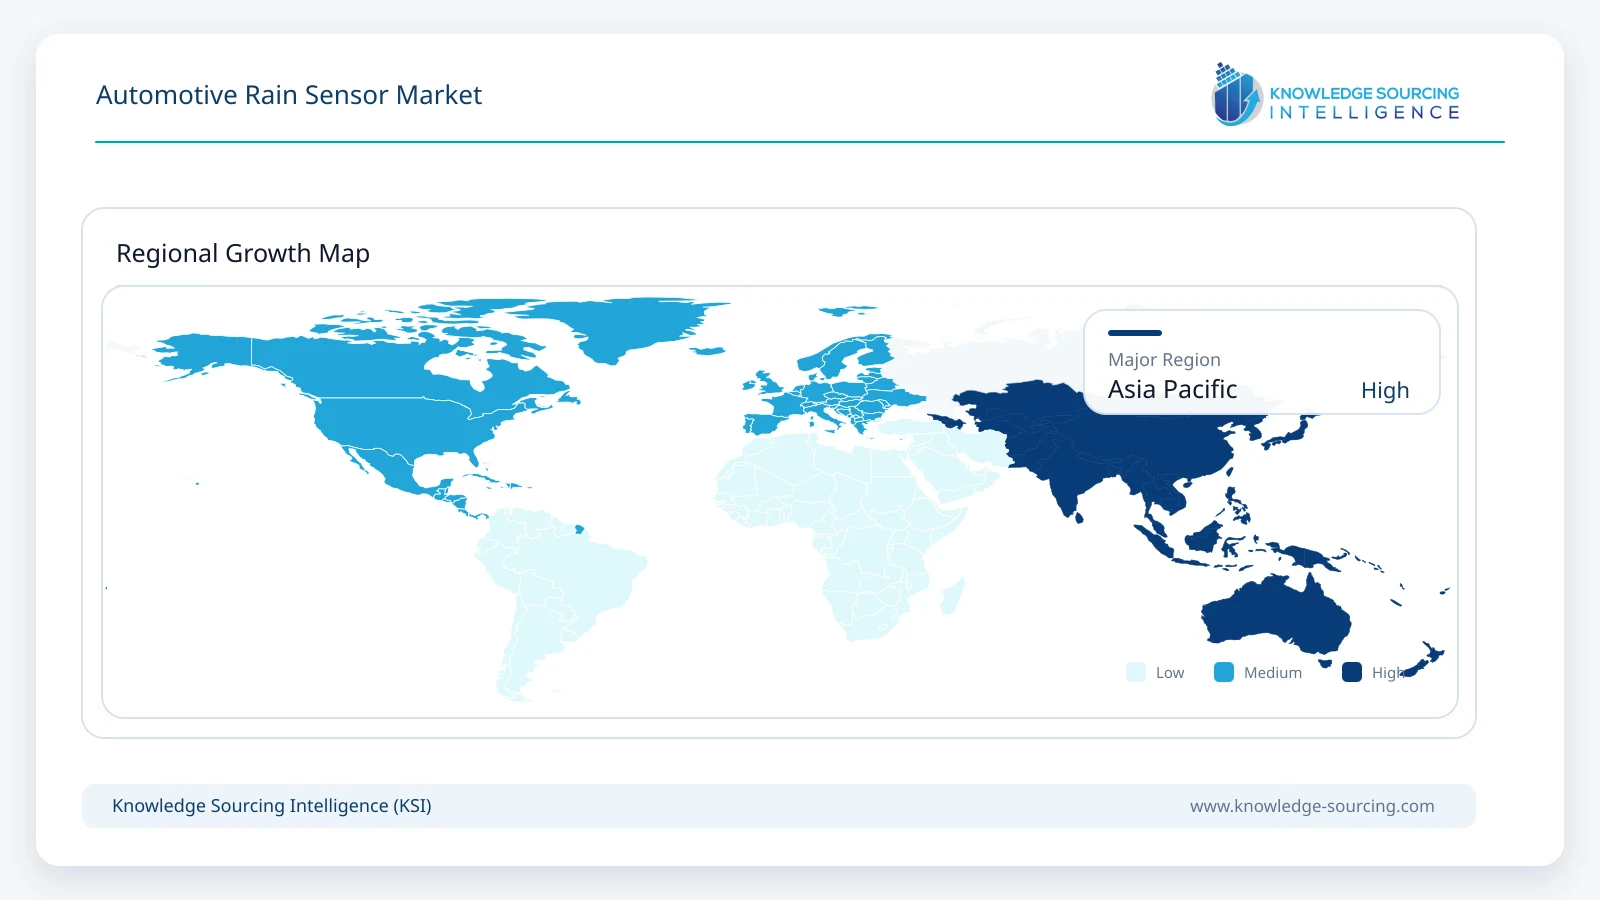
- 5Asia Pacific leads demand, supported by large-scale vehicle production and localized electronics supply.
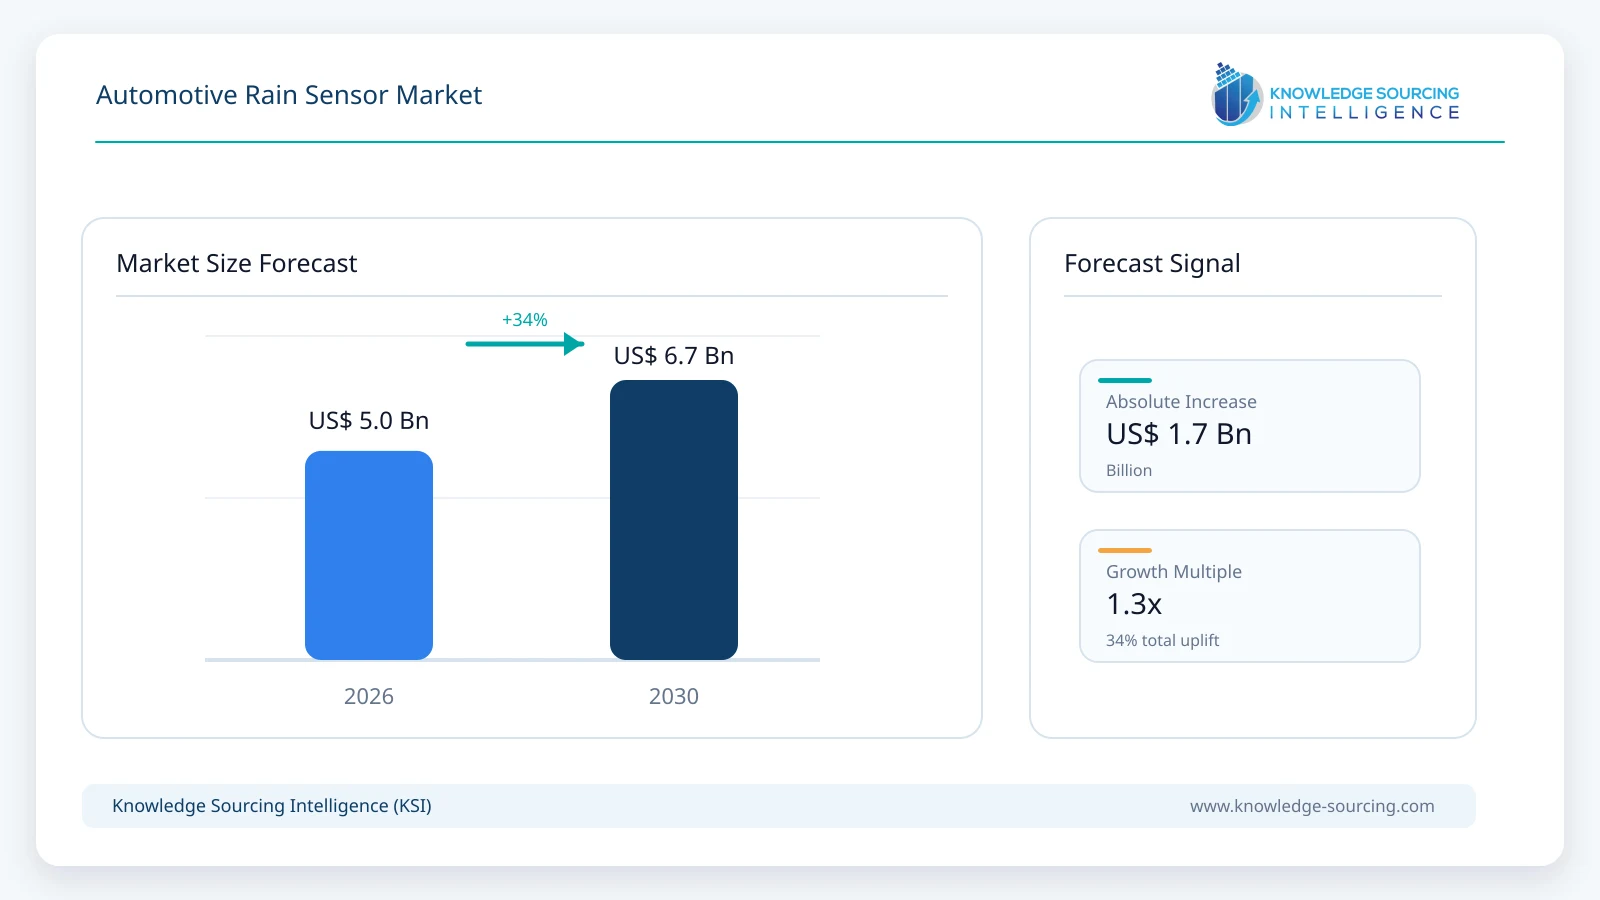
Automotive rain sensors monitor water accumulation on vehicle glazing and convert the measured change in optical reflection into a command for automatic windshield wiping. The commercial systems considered here include complete windshield-mounted rain or rain-light modules, directly associated electronic controls and attributable original-equipment or replacement sensor content. Wiper motors, blades, camera-based driver assistance and unrelated humidity or light sensors are distinct markets, even where manufacturers place several functions inside a shared assembly.
HELLA’s fourth-generation rain-light sensor incorporates rain, ambient light, solar load, humidity and head-up-display brightness functions in one unit. KOSTAL’s seventh-generation stand-alone module is designed for compact placement near the mirror base, and Valeo’s A.U.R.A. platform combines rain response with lighting and selected climate functions. These architectures show why vehicle makers increasingly purchase an integrated environment-sensing module, although revenue attributable to rain-sensing functions must not be mistaken for the full value of other cockpit electronics.
Market Overview
Near-infrared emitters and photodiodes remain central to established automotive rain-sensing designs. When the outer glass surface is dry, internally reflected light reaches the receiver; water changes the optical boundary and reduces the detected signal. The controller translates this variation into wiping commands, taking account of operating thresholds and driver-selected sensitivity. Hamamatsu describes the emitter-photodiode principle and supplies individual optical components, while Melexis provides specialized rain-light interface electronics with sunlight-rejection capabilities.
Sensor packages must work across different windshield thicknesses, inclinations and optical-coupler properties. HELLA specifies distinct variants for conventional passenger windscreens and steeper van glass; KOSTAL focuses on installation near the rear-view mirror. OEMs generally validate the module together with the selected glazing, wiper system and vehicle electrical architecture. Misinterpretation of sun glare or temporary contamination can trigger unnecessary wiping, making rejection algorithms and field robustness commercially important.
The market includes both high-volume original-equipment supply and a narrower replacement channel. Genuine and aftermarket replacement sensors are typically matched to particular vehicle generations, connector types and windshield fittings. Unlike basic wiper consumables, a rain sensor may need correct gel coupling, attachment hardware or vehicle configuration after glass replacement. Consequently, suppliers able to support OE programs, spare-parts identification and workshop procedures participate at different points in the same product lifecycle.
Market Trends
Windshield Modules Combine More Environmental Functions
FORVIA HELLA began series production of locally developed rain-light sensors for a Chinese new-energy-vehicle manufacturer in July 2026. The unit consolidates rain intensity, ambient lighting, sunlight distribution and windshield temperature and humidity signals. This is a production application rather than a design concept and indicates that OEMs are seeking compact environmental sensing assemblies that reduce the number of separately packaged components around the mirror mount.
Valeo’s A.U.R.A. extends the same design approach by offering configurable rain, lighting, fog-prevention, solar and head-up-display functions. Suppliers must manage the differing time constants of these inputs: rain detection requires rapid response, whereas climate controls use slower thermal signals. Integration is commercially attractive only when it avoids unwanted interaction and can be calibrated across vehicle variants without recreating the entire electronics package.
Light-Rain Sensitivity and False-Wipe Rejection Gain Value
A sensor that fails to recognize light drizzle can leave drivers making repeated manual adjustments; one that misreads bright sunlight can command a dry wipe. FORVIA HELLA’s latest Chinese production sensor emphasizes precise sensing of light rain, while Melexis’ dedicated optical interfaces support rejection of interfering sunlight. Both developments address product performance in the situations most likely to expose weaknesses in basic reflection measurement.
Supplier validation therefore involves more than an optical bench test. Different glass laminates, coatings, temperatures, vibration and sensor mounting tolerances can change the received signal. Automotive manufacturers favor stable calibration strategies and fault behavior that remain acceptable as windshields age or are replaced, especially on platforms sold across many climates.
Vehicle Electronics Architecture Shapes Sensor Integration
HELLA’s production rain-light module uses local electronics to evaluate several inputs before the vehicle commands wipers and lamps. KOSTAL offers a stand-alone module that can be placed compactly at the mirror base. Such designs need clear interfaces to body control and wiper electronics; adding more sensor functions does not justify duplicating the same control functions elsewhere in a zonal vehicle architecture.
For suppliers, the architectural decision affects the number of electronic components, connector pins, diagnostics and software integration tasks embedded in each program. Automotive manufacturers may demand a reusable module across vehicle lines, but local glass geometry and feature specifications still require application-specific validation. A stable interface can reduce engineering work and help a supplier retain vehicle-platform business.
Aftermarket Serviceability Influences Original-Equipment Design
Windshield replacement can disturb optical coupling or alter sensor alignment. HELLA’s catalog identifies vehicle-specific rain-light sensor versions and installation constraints, illustrating why a seemingly small electronic part generates long-tail replacement requirements. Quality replacement demand is linked to glass repairs, aging electronics and model-specific fitment rather than the annual sales of new cars alone.
Serviceability also matters during OEM design reviews. An assembly that is difficult to detach or reattach may raise repair costs and customer dissatisfaction over the vehicle life. Suppliers that provide documented fitting, stable part numbering and reliable recalibration procedures are better placed to support both production and replacement business.
Segment Analysis
By Installation Type: Original Equipment Manufacturer (OEM)
Original-equipment installation dominates because rain sensing is tied to the windshield package, mirror housing, electrical interfaces and vehicle software. HELLA, Valeo and KOSTAL illustrate the route from sensor module engineering to a vehicle-specific production application, where environmental testing and production quality are integral to winning a platform contract.
Factory-level integration also enables multifunctional systems that combine wiping, lighting and climate data without requiring separate accessory wiring. By 2031 the OEM channel is expected to represent approximately USD 6.24 billion, even though replacement demand grows from a smaller base. Independent retrofits remain limited by glass attachments, wiring compatibility and the need to avoid false activation.
By Vehicle Type: Passenger Vehicles
Passenger cars account for an estimated 79% of 2026 value, reflecting far larger unit volumes than commercial vehicles and growing installation on mainstream trims. Automatic wiping is particularly attractive when offered within an existing convenience or visibility package, and compact sensor formats help automakers apply the same module family to sedans, SUVs and crossovers.
Commercial vehicles create a different engineering requirement. Steeper windshields and diverse duty cycles can demand revised optics and mounting specifications, as HELLA’s van-specific variants demonstrate. Demand from light and heavy commercial vehicles grows with higher equipment levels, but their lower production volumes keep passenger vehicles the leading application.
Market Drivers
Broader Fitment on High-Volume Passenger Platforms
The expansion of automatic wiping into mid-price vehicles increases the number of sensor-equipped units without requiring a comparable rise in total vehicle output. Shared hardware programs can supply multiple trims with common windshield brackets and electronic interfaces, making the incremental cost of a feature package easier to absorb. Chinese passenger-vehicle competition and expanding vehicle-electronics content reinforce this procurement pattern.
OICA recorded 96.4 million vehicles produced globally in 2025, including 34.53 million in China. These figures indicate the scale of platforms on which suppliers compete, but do not imply universal rain-sensor fitment. The commercial driver is rising sensor penetration within eligible production, alongside the move from discrete rain detectors to multifunctional modules.
Windshield Visibility and Convenience Requirements
Rain sensors remove repeated manual wipe-speed changes during variable precipitation. For drivers, the value lies in maintaining visibility while limiting distraction; for manufacturers, it is a relatively discreet comfort feature that can complement automatic lighting. This functional case remains relevant across combustion, hybrid and battery-electric vehicles because it is not tied to a particular powertrain.
Procurement decisions prioritize timely activation, usable sensitivity adjustment and reliable operation in drizzle or heavy rain. A poorly performing module can produce customer complaints that exceed its component value, so durability and calibration validation remain part of the purchasing case.
Multi-Function Electronic Packaging
The latest HELLA and Valeo products combine rain detection with additional environmental measurements. A single mirror-base or windshield-mounted package can reduce duplicated housings and wiring and help coordinate wiper, lighting and climate decisions. The engineering advantage is particularly relevant when vehicle platforms have limited space behind a large camera or rear-view mirror assembly.
Bundling may increase attributable supplier content where a rain-light module replaces multiple separate devices, but it also creates price negotiations over the overall package. Suppliers gain commercial leverage through integrated sensor performance and validated application software rather than through the raw optical components alone.
Localized Vehicle Electronics Manufacturing
FORVIA HELLA’s July 2026 series-production start in China shows how local engineering and component manufacturing support OEM launch schedules. Chinese vehicle producers can require rapid iterations across windshield designs, software functions and cost targets; suppliers with regional manufacturing and calibration capability can respond without relying entirely on distant design centers.
Localized production is also relevant to supply continuity and program pricing. Although the rain sensor is a small assembly, sourcing reliability matters because the vehicle cannot be completed to specification without its programmed electronics and validated fitment.
Growing Replacement and Glass-Service Activity
Damaged windshields and aging vehicles support a distinct replacement market for vehicle-specific rain sensors and coupling components. HELLA’s aftermarket product documentation illustrates the need to match fitment, windshield inclination and electrical design. Repair networks also benefit when electronic sensor replacement can be completed predictably alongside new glazing.
Replacement activity does not rise in proportion to every vehicle service visit, because many original sensors are reused after windshield repair. Growth therefore depends on actual sensor failure, compatibility and glass-service practices, rather than assuming routine replacement at every wiper-blade change.
Market Restraints
Sensitivity to Windshield Geometry and Optical Coupling
Optical reflection changes with windshield curvature, laminate construction and the coupling interface between the module and glass. HELLA specifies different permissible windscreen inclinations for standard passenger and van variants, demonstrating that one optical package cannot always be transferred without redesign. Automakers also require performance after temperature cycling and production tolerances.
A supplier seeking multiple OEM awards must absorb development and validation costs for each glass family. This can erode the manufacturing savings expected from a common controller and reduces the economic appeal of serving very low-volume models.
False Activation and Unreliable Light-Rain Detection
Strong sunlight, condensation, dirt or poor glass coupling can interfere with the signal used to distinguish rain from a dry windshield. Melexis addresses part of this challenge through sunlight-rejection electronics; FORVIA HELLA emphasizes fine-rain response in its latest production device. Neither feature removes the need for application-level testing.
Frequent unwanted wipes damage user confidence, whereas late activation weakens the visibility benefit. Robust thresholds must balance both outcomes without demanding continual driver intervention, especially on vehicles sold in regions with rapidly changing weather.
Price Pressure on Volume Vehicle Programs
Automakers place substantial cost pressure on small convenience and visibility electronics when competing on retail price. Integrated modules can reduce packaging cost, yet the supplier must deliver optical components, a controller, electrical connectivity and qualification testing within a tightly negotiated program price.
A lower-cost vehicle may use a manually operated wiper even when the platform supports a rain sensor on upper trims. This limits immediate fitment and can delay supplier recovery of tooling and engineering expenditures.
Replacement Complexity After Windshield Repairs
A replacement windshield with different optical properties or incorrectly installed coupling material can compromise a previously functional rain sensor. Workshop technicians may also need access to the correct mounting hardware and vehicle configuration. Improper repair increases the risk of return visits and customer complaints.
The resulting service requirements make aftermarket growth less straightforward than replacement of conventional wiper consumables. Manufacturers need dependable parts identification and installer guidance, while independent suppliers must compete with original-equipment fitment standards.
Limited Standalone Pricing for Rain-Sensor Functions
Vehicle manufacturers increasingly purchase combination rain-light-climate modules. The value of lighting control, solar sensing or head-up-display adjustment may exceed the rain detection subfunction on some programs, complicating apples-to-apples product pricing across suppliers. Procurement teams often negotiate the integrated assembly rather than a standalone rain detector.
For market participants, this can constrain the ability to charge separately for enhanced rain algorithms or new sensing functions. Revenue expansion therefore depends on demonstrable vehicle-system performance and repeatable program wins, not simply on adding functions to a catalogue description.
Regional Outlook
Asia Pacific
Asia Pacific represents an estimated 43% of global market value in 2026. China’s scale and the rapid refresh of domestic vehicle platforms underpin demand for factory-integrated environmental sensors; FORVIA HELLA’s locally engineered and manufactured new-generation unit is a direct example. Japan and South Korea contribute established supplier and vehicle-manufacturing ecosystems, while Indian passenger-vehicle growth expands the pool of models able to offer automatic wiping as an option or standard feature.
The regional market is projected to approach USD 3.08 billion in 2031, with rising equipment penetration complementing vehicle production. Price competition remains intense, especially where new-energy-vehicle manufacturers require compact multifunctional modules at volume prices. Local product engineering and supply responsiveness are therefore central to sustaining supplier business.
South America
Brazil anchors South American demand, supported by its larger domestic vehicle-production and passenger-car market. The region starts from a comparatively low rate of automatic-wiper fitment outside premium vehicle lines, leaving room for incremental penetration as automakers extend convenience packages to mid-price models. Argentina and other assembly markets contribute smaller orders and replacement activity tied to existing fleets.
South America is expected to increase its share of global market value from approximately 4% in 2026 to 6% by 2031, making it the fastest-growing regional market. The pace of expansion will depend on vehicle affordability, imported electronics costs and the availability of sensor-ready windshield designs across locally assembled models.
Competitive Landscape
FORVIA HELLA, Valeo, KOSTAL and DENSO are directly involved in developing automotive rain or rain-light sensing products. HELLA competes through its multigeneration sensor portfolio and OEM-to-aftermarket coverage, with its 2026 Chinese series-production program illustrating local application engineering. Valeo’s A.U.R.A. offers configurable environmental functions, whereas KOSTAL emphasizes compact integration near the mirror base. DENSO lists rain sensors among its vehicle visibility-support products.
Specialized electronic component suppliers occupy a different layer of the value chain. Melexis designs rain-light interface circuits, and Hamamatsu manufactures emitters and photodiodes used within sensing assemblies. These companies support module performance and sourcing but are not automatically competitors for the full assembled sensor contract. Their differentiated roles influence sourcing negotiations, qualification requirements and competition for vehicle programs.
Competition turns on low-level rain recognition, sunlight rejection, windshield compatibility, mechanical packaging and program cost. Global automakers often expect a module family to work across several vehicle lines, but suppliers still need local test capacity and precise glass-interface data. Established aftermarket part catalogs provide an additional route to revenue after the original vehicle platform reaches service age.
Recent Developments
8 September 2026: Automechanika Frankfurt opened with HELLA listing its combined rain/light/climate sensor among the products showcased, confirming its continued presence in vehicle electronics and replacement applications.
28 July 2026: FORVIA HELLA announced series production in China of a new-generation rain-light sensor for a local new-energy-vehicle manufacturer, combining fine-rain recognition with ambient lighting, solar and windshield-condition measurements.
16 June 2025: Valeo published its A.U.R.A. automotive universal rain and ambient sensor offering, detailing automatic wiping, headlamp control and configurable additional visibility and climate-related functions.
Market Outlook
Through 2031, supplier growth will depend more on rain-sensor penetration and the content of multifunctional modules than on the expansion of vehicle output alone. Rain detection is increasingly sold as one element of a validated windshield electronics package, increasing the importance of application software and glass compatibility. Demand from passenger platforms will remain the principal source of volume, while commercial applications require distinct optical and mounting solutions.
Chinese production programs and sensor engineering in the wider Asia Pacific region should sustain the leading regional demand position. South America may register faster growth from a smaller base as vehicle specifications improve, though vehicle affordability and supplier pricing discipline will shape adoption. Across both regions, OEMs will reward low-light-rain performance, reduced false wiping and straightforward production integration.
Aftermarket replacement will provide incremental opportunities where established vehicle populations require accurate sensor fitment and reliable windshield repair procedures. Suppliers combining original-equipment engineering with credible service support are positioned to capture value across more of the vehicle lifecycle without treating every wiper service as a sensor replacement.
Automotive Rain Sensor Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.01 billion |
| Total Market Size in 2031 | USD 6.71 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Installation Type, Vehicle Type, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Installation Type
Original Equipment Manufacturer (OEM)
Aftermarket
By Vehicle Type
Passenger Vehicles
Commercial Vehicles
Light Commercial Vehicles
Heavy Commercial Vehicles
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Israel
Saudi Arabia
Others
Asia Pacific
China
Japan
South Korea
India
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Global Automotive Rain Sensor Market Size, 2026–2031
1.3. Segment and Regional Outlook
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Broader Fitment on High-Volume Passenger Platforms
3.1.2. Windshield Visibility and Convenience Requirements
3.1.3. Multi-Function Electronic Packaging
3.1.4. Localized Vehicle Electronics Manufacturing
3.1.5. Growing Replacement and Glass-Service Activity
3.2. Market Restraints
3.2.1. Windshield Geometry and Optical Coupling
3.2.2. False Activation and Light-Rain Detection
3.2.3. Price Pressure on Volume Programs
3.2.4. Windshield Repair Complexity
3.2.5. Feature Bundling and Pricing
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Infrared Reflection and Optical Readout
4.2. Integrated Rain-Light-Climate Sensors
4.3. Windshield Coupling and Calibration
4.4. Vehicle Control Interfaces
5. AUTOMOTIVE RAIN SENSOR MARKET BY INSTALLATION TYPE
5.1. Introduction
5.2. Original Equipment Manufacturer (OEM)
5.3. Aftermarket
6. AUTOMOTIVE RAIN SENSOR MARKET BY VEHICLE TYPE
6.1. Introduction
6.2. Passenger Vehicles
6.3. Commercial Vehicles
6.3.1. Light Commercial Vehicles
6.3.2. Heavy Commercial Vehicles
7. AUTOMOTIVE RAIN SENSOR MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Others
7.5. Middle East and Africa
7.5.1. Israel
7.5.2. Saudi Arabia
7.5.3. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. Japan
7.6.3. South Korea
7.6.4. India
7.6.5. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Agreements, Partnerships and Product Programs
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. HELLA GmbH & Co. KGaA
9.2. Valeo SE
9.3. KOSTAL Automobil Elektrik GmbH & Co. KG
9.4. DENSO Corporation
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits to Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size for automotive rain sensors in 2031?
The Automotive Rain Sensor Market is projected to reach USD 6.71 billion by 2031.
What is the CAGR for the Automotive Rain Sensor Market (2026-2031)?
The Automotive Rain Sensor Market is expected to grow at a 6.0% CAGR.
Which region leads demand for automotive rain sensors?
Asia Pacific leads demand, supported by vehicle production and electronics supply.
What share of the market do OEM-installed systems represent?
OEM-installed systems represent an estimated 94% of 2026 market value.
What additional functions do integrated rain-light modules support?
They support humidity, solar-load, and display-brightness functions.
What is a critical supplier capability for rain sensors?
Sensor calibration for windshield variation and sunlight interference is critical.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Automotive Rain Sensor Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automotive-rain-sensor-market