
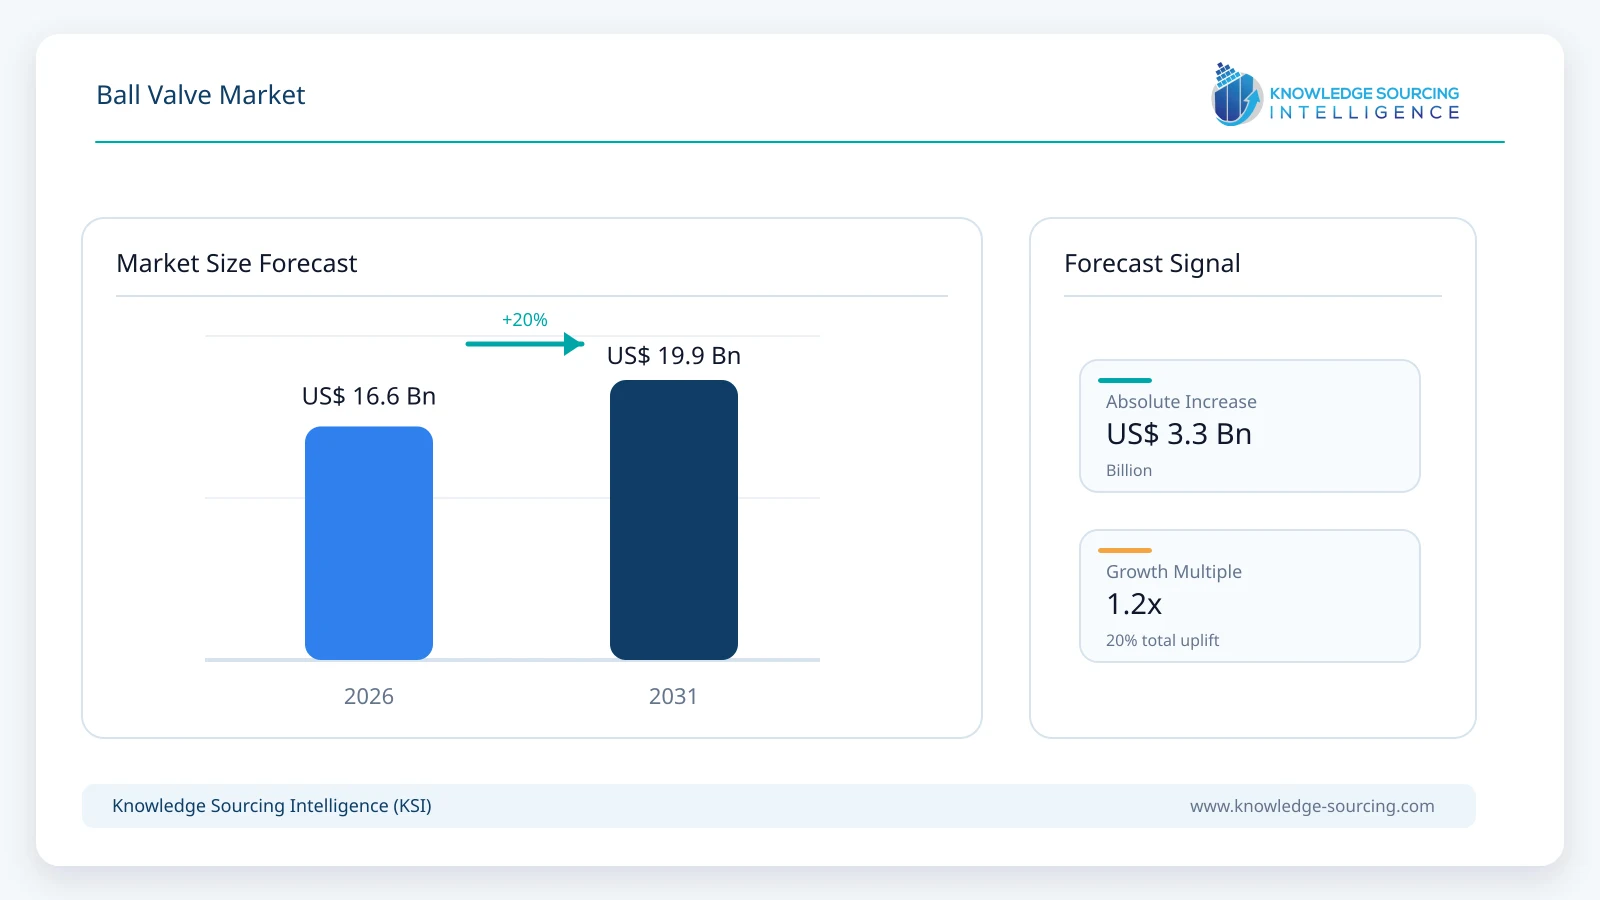
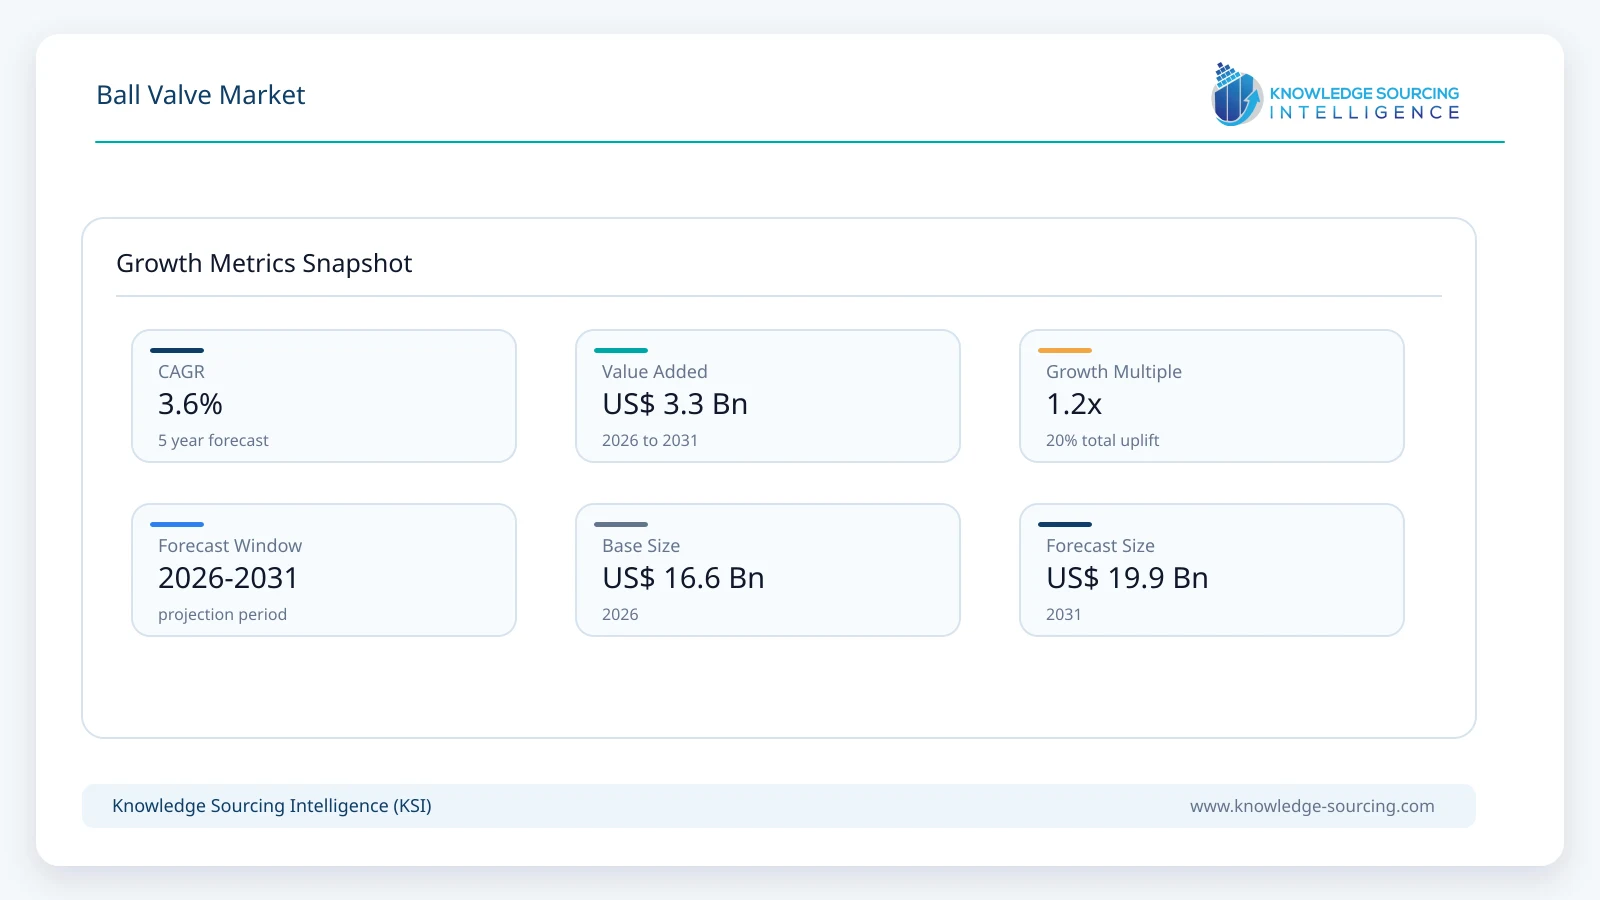
The Ball valve Market is expected to reach USD 19.9 billion in 2031, growing at a CAGR of 3.6% between 2026 and 2031, from USD 16.6 billion in 2026.
Highlights:
- 1Rising demand for reliable flow control across oil, gas, water treatment, and industrial processing is supporting adoption of durable valve solutions.
- 2Growing automation in industrial facilities is driving preference for ball valves with remote monitoring, precise control, and improved operational efficiency.
- 3Advances in materials and sealing technologies are enhancing corrosion resistance, leak prevention, durability, and suitability for demanding operating environments.
- 4Expansion of infrastructure, energy projects, and process industries is creating opportunities for manufacturers offering customized, low-maintenance, and application-specific flow control solutions.
Market Overview
The ball valve market is growing significantly, driven by large investments in fluid-handling infrastructure, process automation, water management, and power generation, along with demanding applications such as chemicals requiring reliable shut-off and flow-control devices. Furthermore, several recent developments emphasize automated, low-emission, high-pressure, cryogenic, and digitally monitored ball-valve solutions.
The industrial valve sector is driven by rising energy and industrial investment worldwide. According to the IEA, global energy investment is projected to reach USD 3.3 trillion in 2025 together with electricity-sector investment reaching approximately USD 1.5 trillion, resulting in opportunities for valves across power-generation and associated process systems.
In addition to oil and gas, growth in electricity infrastructure is generating new valve applications. From 2023 to 2027, global electricity demand is expected to increase by almost 4 per cent each year, as per the IEA, propelled by industrial activity, cooling, electric mobility, data centers, and other electrification trends.
Water reuse and wastewater infrastructure have become key areas of demand for ball valves. As reported by World Bank in 2025, water reuse could increase eightfold by 2040 to reach 430 million/m³/day, incentivizing investments in municipal and industrial treatment and reuse systems, leading to the demand for isolation and flow-control valves.
Increasing industrial automation is leading to integration of ball valves with actuators and control systems. Manufacturers are growing their engineered ball valve portfolio offerings for automated process applications. These product solutions include cryogenic, high-pressure, and high-temperature capabilities designed for demanding services. For example, the Valbart portfolio from Flowserve includes trunnion-mounted ball valves, control ball valves, cryogenic valves, and subsea solutions.
Demand for low-emission and maintenance-efficient valve designs is on the rise. Newer ball-valve designs feature low-emission sealing, double-block-and-bleed, anti-blowout stems, and in-line maintenance to reduce leakage and downtime in critical process applications.
Manufacturing and heavy industry remains a major driving factor for the strong requirement for flow-control equipment. Global crude-steel production was around 1.85 billion tonnes as of 2025, and India produced 165.6 million tonnes. Furthermore, valves are used in steel, mining, processing, and associated industrial facilities in water, gas, cooling, hydraulic, and process-fluid systems.
Market Drivers
Expansion of Oil & Gas and Pipeline Infrastructure
The growing need for ball valves that offer reliable shutoff, flow isolation, and pressure control across pipelines, processing plants, storage terminals, and LNG infrastructure is poised to increase as the oil, natural gas, LNG, and refined-products transportation infrastructure is modernized and expanded over the years.
Global oil and gas investment remains strong; for instance, the International Energy Agency (IEA) forecasts that global upstream oil and gas investment will remain above USD 570 billion in 2025 because extensive capital will be required to further develop production infrastructure and maintain transportation networks.
The major expansion cycle for LNG infrastructure is commencing, with IEA data showing over 90 bcm/year of new liquefaction capacity took final investment decisions in 2025, the second-highest annual total ever, raising associated needs for gas gathering and transmission networks and terminals.
In addition, more than 80 bcm/year of U.S. LNG liquefaction capacity also reached FID in 2025, with projects such as Louisiana LNG, CP2 Phase 1, Corpus Christi Train 8&9, Rio Grande LNG Train 4 and Port Arthur Phase 2 providing enabling gas transmission infrastructure.
Countries globally are expanding gas transportation infrastructure focused on LNG exports. For instance, TC Energy reported that deliveries to U.S. LNG facilities averaged 3.5 Bcf/d in the second quarter of 2025, up 6% year-on-year. The company also noted that its East Lateral XPress project was already in service as of May 2025, helping connect additional supply to Gulf Coast LNG markets.
India is increasing its natural-gas pipeline network expansion. According to the Ministry of Petroleum & Natural Gas, by June 2025, India had about 34,233 km of natural-gas pipelines approved, 25,429 km were functional, and another 10,459 km were under construction, increasing demand for pipeline flow-control equipment like ball valves.
Major Segment Analysis
Energy & Power
By end-user, the ball valve market is segmented into oil and gas, energy and power, chemical, water and wastewater management, pharmaceuticals and biotechnology, and others. The oil and gas sector is expected to grow steadily, fueled by continued investment in oil & natural gas exploration projects.
Rising electricity consumption has accelerated the expansion of power plant infrastructure, which amplifies the market trajectory. The energy and power segment is anticipated to grow considerably, fueled by investment in new power plants and upgrading old ones.
Growing global energy demand has expanded various power grid projects, which is expected to propel the requirement for durable ball valves that are used in cooling-water isolation, steam conditioning and other related services.
The International Energy Agency’s “Electricity 2026” indicates that global electricity generation reached 32,001 TWh in 2025, with projections for 2026 reaching up to 33,172 TWh and 37,874 TWh for 2030.
Likewise, the growing energy transition fueled by a significant shift towards renewable sources is set to expand the percent share of low-emission sources such as solar and nuclear up to 50% in global electricity generation by 2030. Such growth supports the construction of nuclear and solar power plants that use ball valves for reliable flow isolation.
Regulatory support to minimize carbon footprint has encouraged implementation of investments and establishment of future energy projects, thereby expanding the market outlook in global regions such as China, the United States, and the European region.
Global Players like AMPO POYAM VALVES are offering customized liquid & gas flow components for power plants. Likewise, companies like Valmet have emphasized on valve innovation, with the recent acquisition of Severn Group expanding its portfolio. Such strategic maneuvers support the transparency of global market.
Geographical Outlook
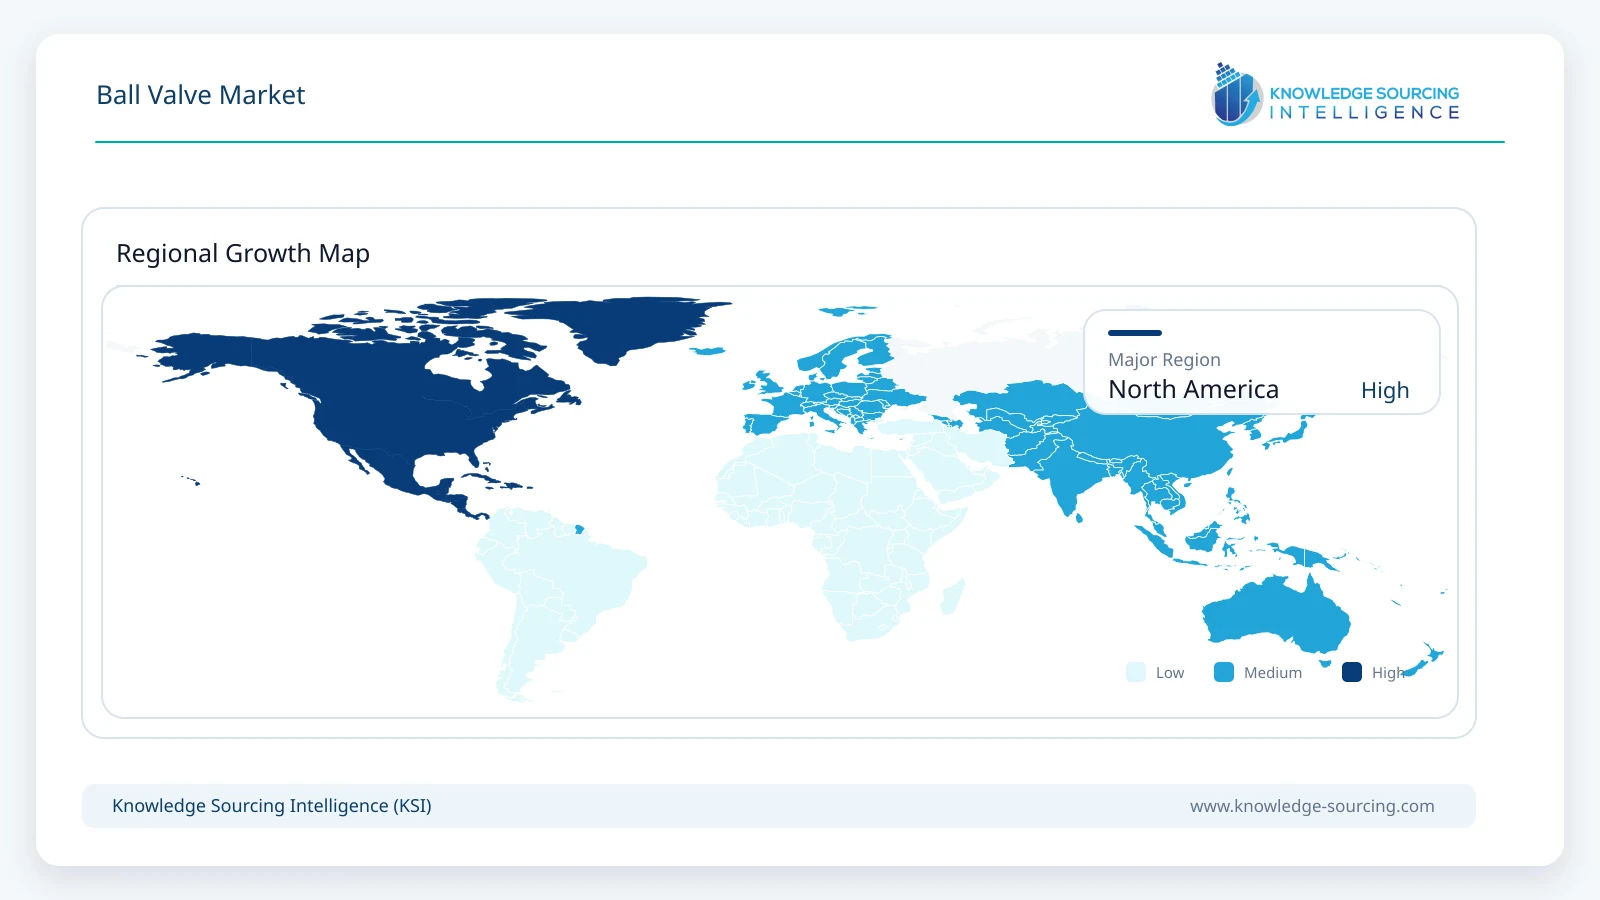
North America: the US
The United States ball valve market is projected to show significant growth fueled by improved industrial output.
High industrial output supported by continued investment in industrial infrastructure expansion and modernization has played an integral role in driving the demand for components like ball valves in the US market.
Improved strength of crude oil and natural gas operating rotary rigs, which, according to the US Energy Information Administration, stood at 585 (Number of Elements) as of July 2026, further supports the demand for high-pressure & tight-sealing ball valves.
Broader infrastructure construction volume due to heavy investment in residential and commercial units escalates the requirement for corrosion-resistant plumbing ball valves. According to the US Census, in July 2026, construction spending stood at USD 2,157.58 billion, with USD 1,614.71 billion invested in private construction.
Likewise, investments in wastewater treatment projects such as the recent completion of a USD 72 million wastewater treatment project in Buffalo and HASI’s investment in the Pasco Center wastewater treatment facility, have positively influenced the demand for durable ball valves for maintaining liquid flow.
Rapid adoption, technological maturity and infrastructure growth offer wide market opportunities for major manufacturers that have invested in new innovations for the US market. For instance, in June 2026, Alberts N.V. showcased its “Apollo 76F-HCA” stainless ball valve ideal for deionized water systems in data centers.
Company Profiles
Emerson Electric Co.
Emerson Electric Co. follows a strategy centered on broadening its ball-valve portfolio, improving valve reliability and integrating valves with digital automation and predictive-maintenance technologies. Through its Final Control business, Emerson offers floating, segmented, throttling and trunnion-mounted ball valves under brands including Fisher, KTM and AEV, enabling it to serve applications ranging from standard process isolation to severe-service and cryogenic operations.
The company is also focusing on intelligent, connected valve solutions, using digital valve controllers, real-time analytics, and reliability services to help customers monitor valve performance, reduce maintenance requirements, and improve plant efficiency. Emerson has also emphasized solutions for emissions reduction, energy efficiency, and demanding process applications, including chemical, petrochemical, LNG, and industrial-gas operations.
Key Developments
September 2026: Emerson introduced Fisher Startup & Commissioning Kits, designed to protect valve components from debris and damage during plant commissioning and improve long-term valve reliability.
June 2026: Flowserve completed its acquisition of Trillium Flow Technologies’ Valves Division, adding specialized flow-control capabilities serving nuclear, power-generation, industrial, and infrastructure applications.
April 2026: BAC Valves joined the Meca-Inox Group following an acquisition, combining complementary expertise in stainless-steel ball valves, butterfly valves, and specialized industrial flow-control solutions.
April 2026: Emerson introduced the Fisher SVX Steam Conditioning Valve, expanding its valve portfolio for combined-cycle power plants and other demanding steam applications.
Ball Valve Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 16.6 billion |
| Total Market Size in 2031 | USD 19.9 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 3.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Ball Valve Type, Port Type, Body Style, Material, Size, Operation, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Ball Valve Type
Floating Ball Valve
Trunnion-Mounted Ball Valve
Rising Stem Ball Valve
Multi-Port Ball Valve
Others
By Port Type
Full Port
Reduced Port
Standard Port
V Port
By Body Style
Single Body
Split Body
Top Entry
Welded
By Material
Stainless Steel
Carbon Steel
Cast Iron / Ductile Iron
Brass / Bronze
PVC / CPVC
Other Materials
By Size
Up to 1" (DN 25)
1" - 6"
6" - 25"
25" - 50"
Above 50"
By Operation
Manual
Pneumatic
Electric
Hydraulic
By End-User
Oil and Gas
Energy and Power
Chemical
Water and Wastewater Management
Pharmaceutical and Biotechnology
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. MARKET DYNAMICS
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
4. BUSINESS LANDSCAPE
4.1. Regulatory & Standards Landscape
4.2. Manufacturing & Component Ecosystem
4.3. Raw Material & Supply Chain Analysis
4.4. Global Trade Statistics & Major Supplier/Buyer Analysis
4.5. Pricing Analysis
4.6. Strategic Recommendations
5. TECHNOLOGICAL OUTLOOK
5.1. Smart & Automated Ball Valve Technologies
5.2. Low-Emission & Fugitive-Emission Control Technologies
5.3. High-Pressure, High-Temperature & Severe-Service Ball Valve Technologies
5.4. Cryogenic & LNG Ball Valve Technologies
5.5. Advanced Manufacturing & Digital Engineering Technologies
6. OIL & GAS / PROCESS INDUSTRY DEMAND ANALYSIS
6.1. Upstream, Midstream and Downstream Demand
6.2. Pipeline Construction and Replacement
6.3. Severe-Service and High-Pressure Applications
7. BALL VALVE MARKET BY BALL VALVE TYPE (2021-2031)
7.1. Introduction
7.2. Floating Ball Valve
7.3. Trunnion-Mounted Ball Valve
7.4. Rising Stem Ball Valve
7.5. Multi-Port Ball Valve
7.6. Others
8. BALL VALVE MARKET BY PORT TYPE (2021-2031)
8.1. Introduction
8.2. Full Port
8.3. Reduced Port
8.4. Standard Port
8.5. V Port
9. BALL VALVE MARKET BY BODY STYLE (2021-2031)
9.1. Introduction
9.2. Single Body
9.3. Split Body
9.4. Top Entry
9.5. Welded
10. BALL VALVE MARKET BY MATERIAL (2021-2031)
10.1. Introduction
10.2. Stainless Steel
10.3. Carbon Steel
10.4. Cast Iron / Ductile Iron
10.5. Brass / Bronze
10.6. PVC / CPVC
10.7. Other Materials
11. BALL VALVE MARKET BY SIZE (2021-2031)
11.1. Introduction
11.2. Up to 1" (DN 25)
11.3. 1" - 6"
11.4. 6" - 25"
11.5. 25" - 50"
11.6. Above 50"
12. BALL VALVE MARKET BY OPERATION (2021-2031)
12.1. Introduction
12.2. Manual
12.3. Pneumatic
12.4. Electric
12.5. Hydraulic
13. BALL VALVE MARKET BY END-USER (2021-2031)
13.1. Introduction
13.2. Oil and Gas
13.3. Energy and Power
13.4. Chemical
13.5. Water and Wastewater Management
13.6. Pharmaceutical and Biotechnology
13.7. Others
14. BALL VALVE MARKET BY GEOGRAPHY (2021-2031)
14.1. Introduction
14.2. North America
14.2.1. By Ball Valve Type
14.2.2. By Port Type
14.2.3. By Body Style
14.2.4. By Material
14.2.5. By Size
14.2.6. By Operation
14.2.7. By End-User
14.2.8. By Country
14.2.8.1. United States
14.2.8.2. Canada
14.2.8.3. Mexico
14.3. South America
14.3.1. By Ball Valve Type
14.3.2. By Port Type
14.3.3. By Body Style
14.3.4. By Material
14.3.5. By Size
14.3.6. By Operation
14.3.7. By End-User
14.3.8. By Country
14.3.8.1. Brazil
14.3.8.2. Argentina
14.3.8.3. Others
14.4. Europe
14.4.1. By Ball Valve Type
14.4.2. By Port Type
14.4.3. By Body Style
14.4.4. By Material
14.4.5. By Size
14.4.6. By Operation
14.4.7. By End-User
14.4.8. By Country
14.4.8.1. Germany
14.4.8.2. United Kingdom
14.4.8.3. France
14.4.8.4. Spain
14.4.8.5. Others
14.5. Middle East and Africa
14.5.1. By Ball Valve Type
14.5.2. By Port Type
14.5.3. By Body Style
14.5.4. By Material
14.5.5. By Size
14.5.6. By Operation
14.5.7. By End-User
14.5.8. By Country
14.5.8.1. Saudi Arabia
14.5.8.2. UAE
14.5.8.3. Others
14.6. Asia Pacific
14.6.1. By Ball Valve Type
14.6.2. By Port Type
14.6.3. By Body Style
14.6.4. By Material
14.6.5. By Size
14.6.6. By Operation
14.6.7. By End-User
14.6.8. By Country
14.6.8.1. China
14.6.8.2. Japan
14.6.8.3. India
14.6.8.4. South Korea
14.6.8.5. Indonesia
14.6.8.6. Thailand
14.6.8.7. Others
15. COMPETITIVE ENVIRONMENT AND ANALYSIS
15.1. Major Players and Strategy Analysis
15.2. Market Share Analysis
15.3. Mergers, Acquisitions, Agreements, and Collaborations
15.4. Competitive Dashboard
16. COMPANY PROFILES
16.1. Aalberts N.V.
16.2. Amco Industrial Valves
16.3. American Valve
16.4. Emerson Electric Co.
16.5. Flowserve Corporation
16.6. JC Valves (TTV-JC Valve Group)
16.7. Parker Hannifin Corporation
16.8. Powell Valves
16.9. Tiger Valve Company
16.10. Aquatrol (including Kingston Valves)
16.11. BELIMO Holding AG
17. RESEARCH METHODOLOGY
18. LIST OF FIGURES
19. LIST OF TABLES





Frequently asked questions
What is the projected size and growth rate of the Ball Valve Market?
The Ball Valve Market will reach USD 19.9 billion by 2031, growing at 3.6% CAGR.
What are the primary growth drivers for the Ball Valve Market?
Demand in oil, gas, water treatment, industrial automation, and energy investments.
Which industries are key demand areas for ball valves?
Oil, gas, water treatment, power generation, chemicals, and infrastructure projects.
What technological advancements are influencing the Ball Valve Market?
Automation, advanced materials, low-emission designs, and digital monitoring are key.
What future opportunities exist in the Ball Valve Market?
Infrastructure expansion, energy projects, water reuse, and industrial automation solutions.
How do energy investments impact the Ball Valve Market?
Trillions in energy and electricity investment create significant valve opportunities.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Ball Valve Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/ball-valve-market