Bamboo Packaging Market - Strategic Insights and Forecasts (2026-2031)
Bamboo Packaging Market Size, Share, Forecasts and Trends Analysis By Material Form (Molded Bamboo Fiber and Pulp, Bamboo Paper and Paperboard, Solid Bamboo and Hybrid Packaging), By Packaging Type (Foodservice Containers and Tableware, Boxes, Cartons and Mailers, Bottles, Jars and Tubes, Protective Packaging and Inserts, Reusable Transport and Other Packaging), By End User (Food and Beverages, Cosmetics and Personal Care, E-Commerce, Electrical and Electronics, Automotive, Agriculture and Others), and Region
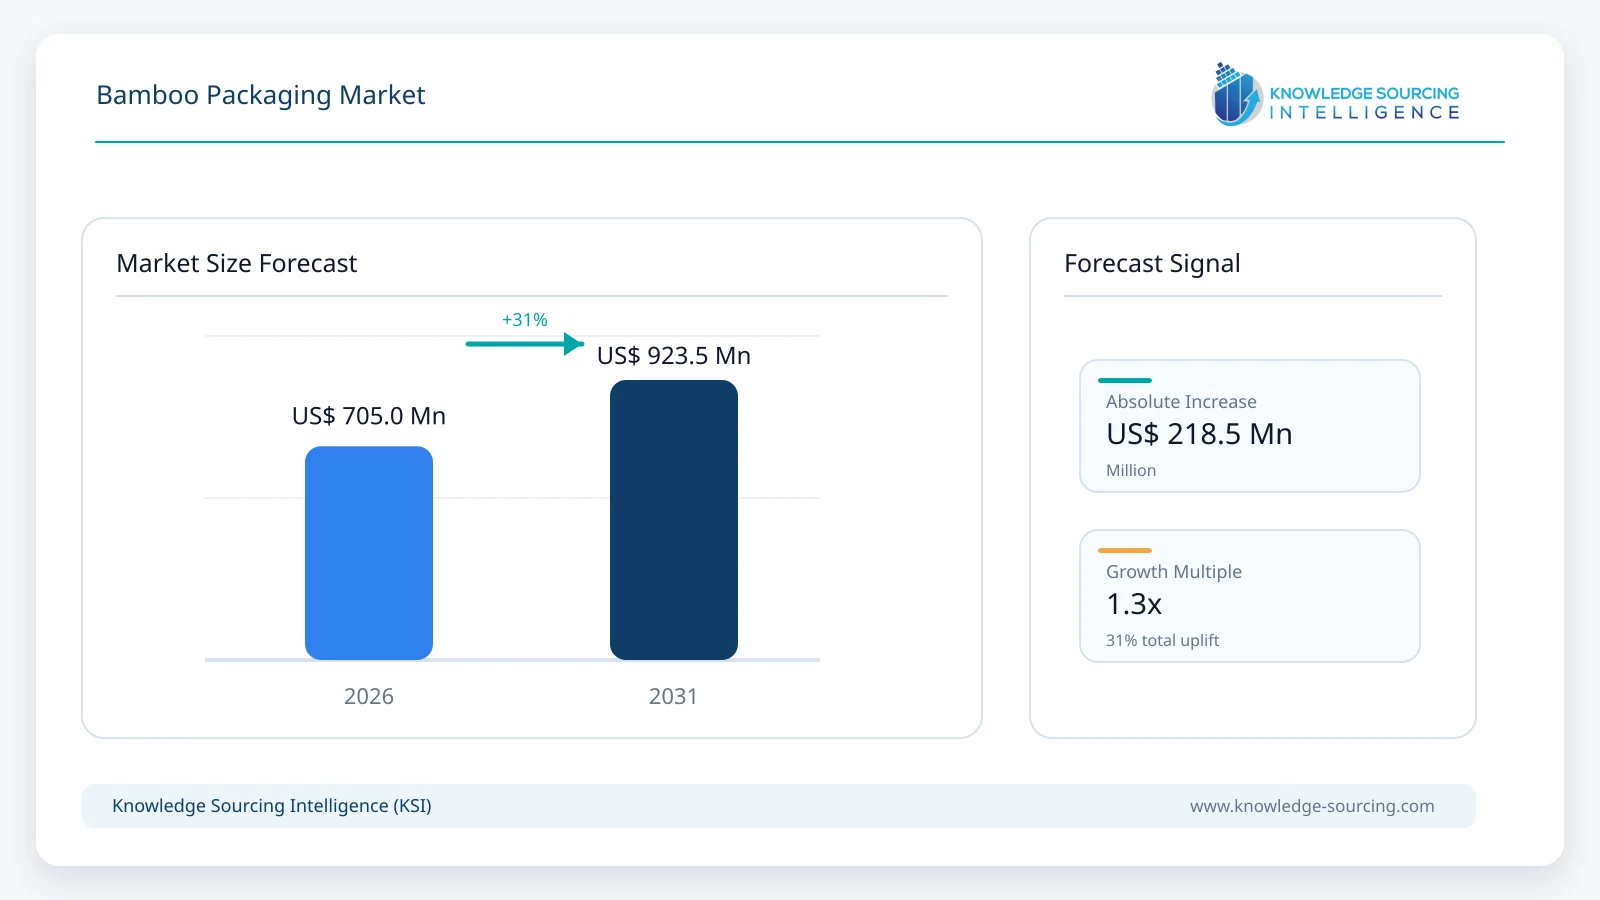
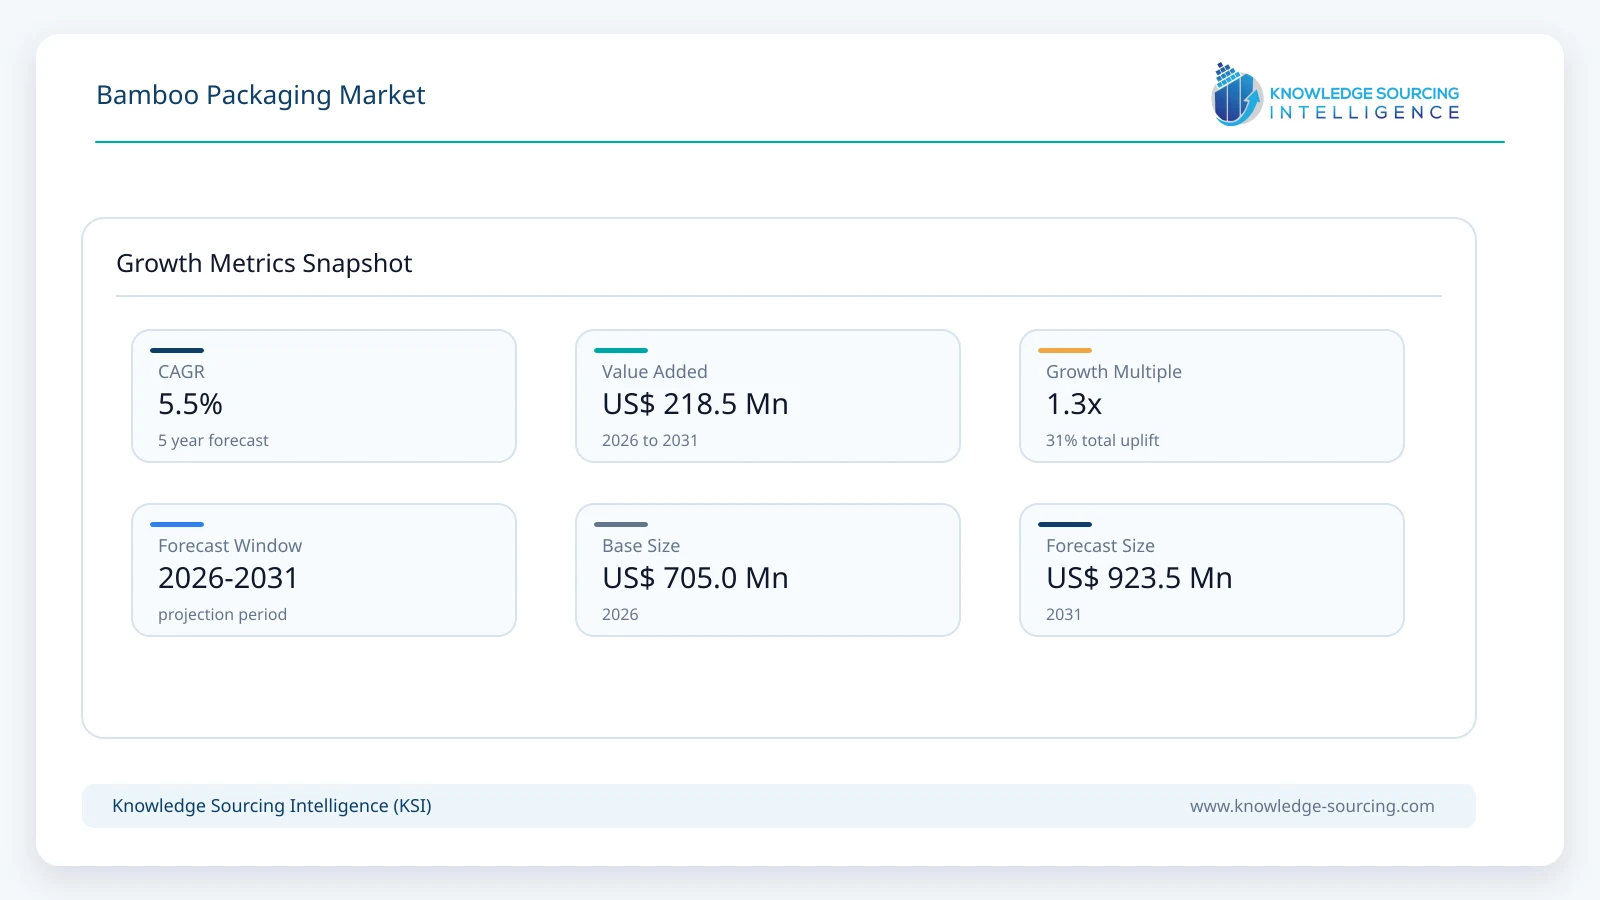
Bamboo Packaging Market is anticipated to grow at a 5.55% CAGR, increasing from USD 705.0 million in 2026 to USD 923.5 million in 2031.
Highlights:
1
Molded bamboo fiber and pulp account for approximately 52% of global bamboo packaging market value in 2026, equivalent to around USD 366.6 million.
2
Foodservice containers and tableware represent approximately 31% of market value in 2026 and remain the largest packaging-format category.
3
Food and beverages account for approximately 40% of global market value in 2026, supported by takeaway containers, trays, cups and other fiber-based formats.
4
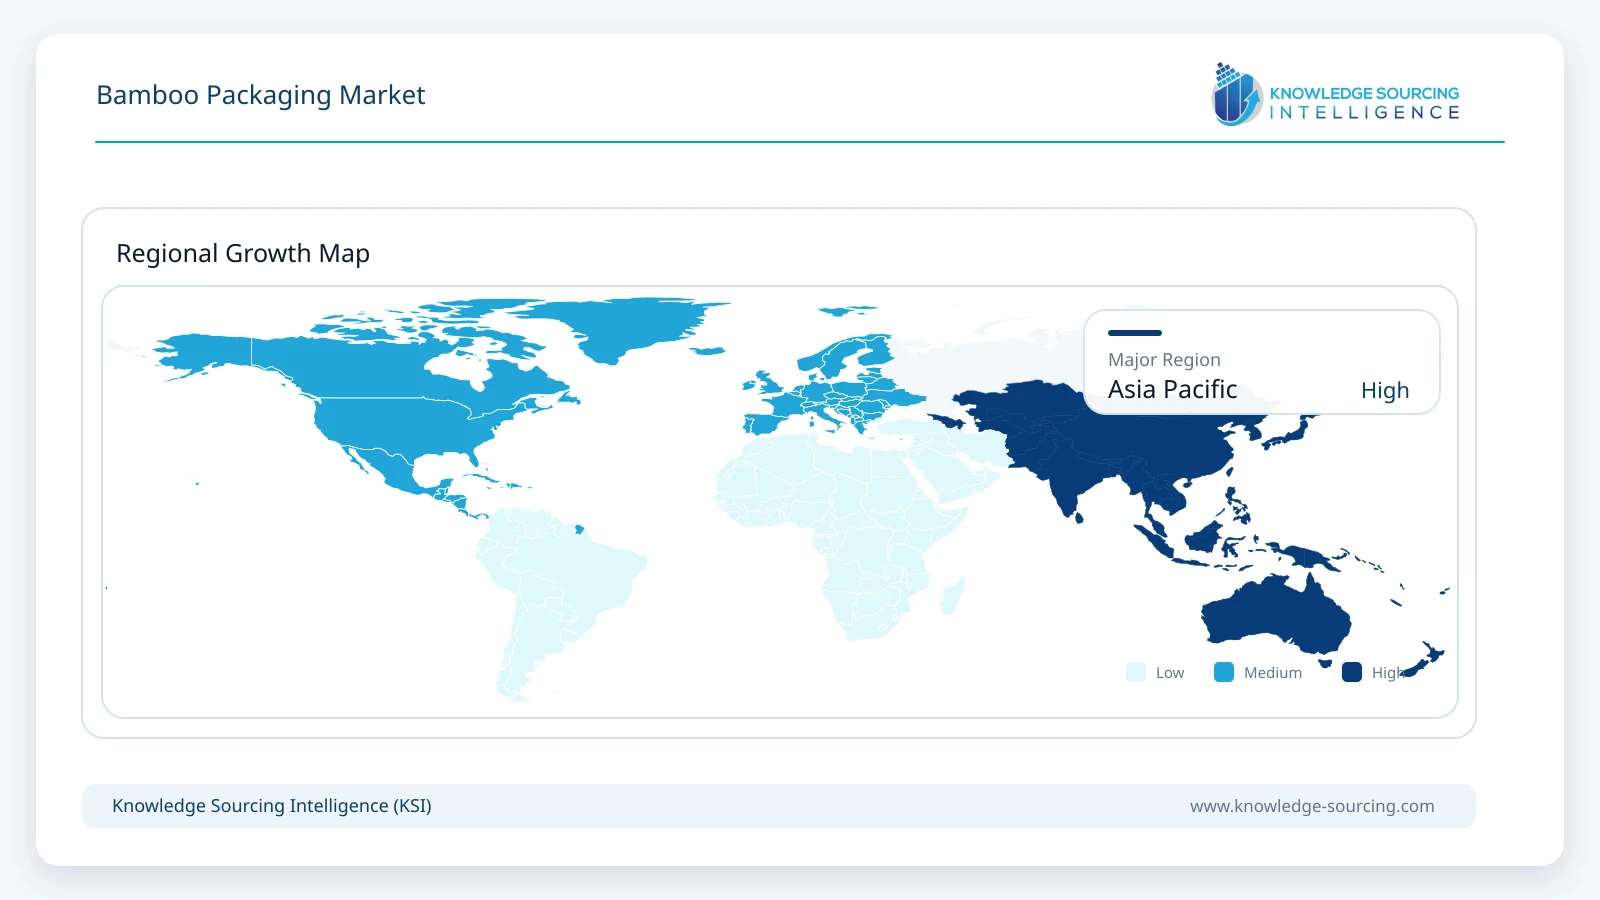
Asia Pacific accounts for approximately 48% of global bamboo packaging market value in 2026 due to its concentration of bamboo resources, pulping and converting capacity.
5
Cosmetics and personal care packaging is projected to grow at approximately 8.2% annually through 2031 as brands adopt bamboo shells, lids, jars and refillable hybrid formats.
Demand is developing alongside the broader movement toward renewable fiber packaging, particularly where manufacturers can replace rigid plastic, expanded foam, or conventional decorative packaging without compromising functional performance. International Bamboo and Rattan Organization initiatives increasingly position bamboo as an industrial feedstock for pulp, paper, and selected plastic-substitution applications, while commercial manufacturers are expanding its use across foodservice containers, protective molded packaging, and premium consumer products.
Commercial adoption is strongest where bamboo can use manufacturing technologies already established in the wider pulp and molded-fiber industry. Golden Arrow uses bamboo and bagasse to produce molded packaging for electronics, luxury goods and cosmetics, while PANABAM manufactures bamboo-fiber food containers, bowls, trays and other foodservice products. Bamboo-pulp paper manufacturers are also supplying material for cups, bowls and other paper-based formats. These developments allow bamboo packaging to scale through existing converting and forming processes rather than requiring a completely separate manufacturing ecosystem.
Market Trends
Precision Molded Fiber Is Moving Bamboo Into Premium Packaging
Wet-pressed and precision molded-fiber technologies are improving surface quality, dimensional accuracy and branding options, allowing bamboo-based packaging to enter applications previously dominated by thermoformed plastic or premium paperboard. Golden Arrow uses bamboo and bagasse in molded-fiber packaging for electronics, luxury products and cosmetics and offers high-precision tooling, embossing, printing and custom surface finishes. These capabilities are important because electronics and beauty companies require packaging to provide both protection and presentation rather than simply reduce plastic content. The development of higher-quality molded surfaces also allows bamboo fiber to function as primary consumer-facing packaging instead of remaining limited to internal protective inserts. As forming technology improves, value growth increasingly comes from more complex and higher-margin applications rather than only from commodity food trays or disposable tableware.
Bamboo Cosmetic Packaging Is Moving Toward Hybrid and Refillable Designs
Beauty and personal-care companies increasingly use bamboo as part of multi-material packaging systems rather than attempting to manufacture entire packages from untreated bamboo. Bamboo is frequently used for external shells, caps, lids and decorative structures around glass, aluminium or polymer containers that provide the required moisture and chemical barriers. This approach allows brands to reduce visible plastic content and create a distinctive premium appearance without compromising formula protection. Suppliers such as APG Packaging, Three Bamboo and Yilin Bamboo offer bamboo jars, bottles, tubes, droppers and other cosmetic formats, while refillable systems are increasing the useful life of decorative outer components. The resulting opportunity is particularly attractive because cosmetics packaging has a higher unit value than most disposable foodservice formats, enabling manufacturers and brands to absorb the additional machining, finishing and assembly costs associated with bamboo components.
Bamboo Pulp Is Expanding in Foodservice Packaging
Foodservice remains the largest volume-oriented opportunity because bamboo pulp can be formed into trays, plates, bowls, clamshells and takeaway containers using processes already established for molded pulp and bagasse. PANABAM supplies bamboo-fiber containers, trays, plates and beverage accessories and reports industrial-scale production capacity, while bamboo-pulp paper suppliers provide base materials for cups and bowls. This allows bamboo to participate in a much larger transition from conventional plastic and foam packaging toward molded plant-fiber alternatives. Competition remains strong from bagasse, recycled paper and conventional wood pulp, meaning bamboo does not automatically gain share simply because it is renewable. Its strongest position is where local raw-material availability, product stiffness, surface quality or sustainability positioning provides an advantage over competing fibers.
Market Drivers
Packaging Regulation Is Increasing Demand for Plastic Alternatives
Packaging regulation is strengthening the commercial case for renewable and fiber-based alternatives. The European Union’s Packaging and Packaging Waste Regulation introduces progressively stricter requirements around recyclability, packaging reduction, reuse and waste prevention, while California’s SB 54 framework establishes extended producer responsibility and long-term targets for reducing single-use plastic packaging. These regulations do not specifically require bamboo, but they increase the number of packaging applications in which manufacturers are evaluating molded fiber, paper and other renewable materials as substitutes for conventional plastics. Bamboo benefits where it can use existing pulp-processing infrastructure while providing an additional renewable fiber source. The effect is strongest in disposable foodservice packaging, e-commerce protection and consumer goods where the regulatory and brand pressure to reduce conventional plastic content is most visible.
Molded Plant Fiber Is Becoming More Commercially Established
Bamboo packaging benefits from investment in the wider molded-fiber industry because the same tooling, forming and drying technologies can be adapted for different plant-fiber feedstocks. Commercial molded fiber is already used for electronics trays, food containers, cup carriers, industrial protection and premium consumer packaging, reducing the technical barriers to adopting bamboo pulp. Golden Arrow uses bamboo and bagasse for molded electronics and beauty packaging, while dedicated bamboo suppliers manufacture foodservice containers at industrial scale. This established manufacturing base allows suppliers to focus on fiber formulation, surface finish, barrier coatings and cost rather than developing an entirely new packaging platform. As molded fiber becomes more precise and visually refined, bamboo can participate in higher-value applications where conventional pulp packaging previously lacked the appearance or dimensional consistency required by brand owners.
Beauty Brands Are Using Bamboo for Premium Sustainability Positioning
Cosmetics and personal care provide one of the strongest value-growth opportunities because bamboo contributes both to sustainability messaging and package appearance. Natural grain, texture and colour enable brands to differentiate skincare, fragrance and personal-care products while reducing reliance on conventional decorative plastics. Bamboo packaging suppliers now offer bottles, jars, pumps, mascara tubes, lipstick components and refillable systems, allowing brands to use the material across broader product ranges rather than individual promotional items. The economics are more favourable than in commodity food packaging because beauty products can support higher packaging expenditure per unit. This is helping cosmetics and personal care grow faster than the overall bamboo packaging market and gradually increase its share through 2031.
Market Restraints
Bamboo Does Not Provide All Required Barrier Properties
Bamboo alone does not provide sufficient moisture, oil or chemical resistance for many primary-packaging applications. Cosmetic containers often require glass, aluminium or polymer liners, while foodservice packaging may need barrier coatings to resist water, fats or prolonged contact with hot food. These additional materials can complicate recyclability or compostability if the package cannot be separated easily or if the coating is incompatible with existing recovery systems. The technical challenge is therefore not simply replacing plastic with bamboo but developing structures that maintain product integrity while still delivering a meaningful environmental benefit. This limits bamboo’s suitability for some liquid, high-moisture and long-shelf-life products and explains why hybrid packaging remains common in cosmetics and other demanding applications.
Cost and Supply-Chain Scale Limit Broader Adoption
Bamboo packaging remains considerably smaller than conventional paper, plastic and bagasse packaging industries, limiting economies of scale in several applications. Processing, finishing and transportation costs can be higher where production is located far from end markets, while premium bamboo components often require additional machining or manual finishing. INBAR has also highlighted the importance of stronger international standards and more developed bamboo value chains to support wider adoption. Cost sensitivity is particularly important in takeaway food packaging and e-commerce, where buyers purchase large quantities and can switch between bamboo, recycled paper, bagasse and other fibers. Bamboo therefore achieves stronger penetration when it offers a clear functional, local-resource or branding advantage rather than competing solely as a more sustainable material.
Segment Analysis
By Material Form: Molded Bamboo Fiber and Pulp
Molded bamboo fiber and pulp account for approximately USD 366.6 million in 2026 and are projected to reach around USD 498.7 million by 2031, representing a CAGR of approximately 6.35%. The segment remains the largest material form because molding technology allows bamboo pulp to replace selected rigid plastic, foam and conventional molded-pulp structures across foodservice, electronics, cosmetics and protective packaging. Wet-pressed systems are particularly important in higher-value applications because they provide smoother surfaces, tighter tolerances and more detailed shapes than basic dry-pressed fiber products. Golden Arrow’s use of bamboo and bagasse across premium molded-fiber applications illustrates this movement toward more technically demanding packaging. Growth is expected to remain above the overall market as molded pulp benefits from both regulatory pressure on rigid plastics and ongoing improvements in tooling, barrier performance and surface finishing.
By Packaging Type: Foodservice Containers and Tableware
Foodservice containers and tableware account for approximately USD 218.6 million in 2026 and are projected to reach around USD 304.8 million by 2031, representing growth of approximately 6.88% annually. Bamboo pulp can be formed into bowls, trays, plates, clamshells and other disposable formats using equipment broadly similar to that employed for bagasse and other molded fibers. This gives the category a practical path to scale where local pulp availability and product economics are competitive. Regulations targeting single-use plastics also increase the number of foodservice applications in which fiber alternatives are being evaluated. The segment nevertheless remains price sensitive because bamboo competes directly with bagasse, recycled paper and conventional paperboard. Growth is therefore strongest where suppliers combine food-contact certification, moisture resistance and high-volume manufacturing with competitive unit costs.
By End User: Food and Beverages
Food and beverages account for approximately USD 282.0 million in 2026 and are projected to reach approximately USD 378.6 million by 2031, representing a CAGR of around 6.07%. The segment remains the largest end-user category because takeaway food, catering, beverages and packaged foods create substantially larger unit volumes than cosmetics or electronics. Bamboo packaging is used particularly in disposable containers, trays, plates, cups and related fiber formats where it competes with plastic, wood pulp and bagasse. Regulatory pressure on single-use plastics provides a supportive demand environment, although bamboo’s actual penetration depends strongly on relative material cost and local supply availability. Cosmetics and personal care grow faster at approximately 8.17% annually, increasing from around USD 162.2 million in 2026 to USD 240.1 million in 2031, but remain smaller because their unit volumes are substantially lower.
Regional Outlook
Asia Pacific
Asia Pacific accounts for approximately USD 338.4 million in 2026 and is projected to reach approximately USD 424.8 million by 2031, representing a CAGR of around 4.65%. The region remains the largest market because bamboo cultivation, pulping and specialist packaging manufacturing are heavily concentrated in China and other Asian economies. Many dedicated bamboo packaging suppliers operate production facilities in China, giving the region established access to raw materials, machining skills and export-oriented converting capacity. Asia Pacific’s share gradually moderates through the forecast period as adoption increases more rapidly in regulated European and North American markets, but the region remains the principal manufacturing base and largest overall market in 2031.
Europe
Europe is projected to grow from approximately USD 148.0 million in 2026 to USD 212.4 million in 2031, representing a CAGR of approximately 7.49%. This makes it the fastest-growing major region during the forecast period. The EU Packaging and Packaging Waste Regulation strengthens requirements around recyclability, waste reduction and packaging optimization, increasing interest in renewable fiber solutions across foodservice, cosmetics, e-commerce and consumer goods. Bamboo competes with established European wood-pulp and recycled-fiber industries, so regulatory pressure alone does not guarantee adoption. Growth is strongest in premium or specialized applications where bamboo provides additional differentiation alongside its renewable-material characteristics.
Competitive Environment and Analysis
The bamboo packaging market remains fragmented and includes molded-fiber manufacturers, bamboo cosmetic-packaging specialists and upstream bamboo-pulp suppliers. Golden Arrow has developed a differentiated position in precision molded fiber for electronics, luxury products and cosmetics, while PANABAM and similar suppliers focus more heavily on foodservice and plant-fiber packaging. APG Packaging, Yilin Bamboo and Three Bamboo compete in cosmetics through bamboo jars, bottles, caps, tubes and refillable hybrid systems. Bamboo-pulp and paper manufacturers provide upstream materials for cups, bowls and other converted products.
Competitive requirements vary considerably by application. Foodservice suppliers compete on price, certifications, grease resistance and production capacity, while electronics packaging requires dimensional accuracy and protective performance. Cosmetics suppliers differentiate through finishing, appearance, engraving and integration with glass or plastic refill systems. This limits the likelihood that any one supplier will dominate the total market and creates opportunities for specialists focused on individual packaging categories.
Recent Developments
August 2026: The EU Packaging and Packaging Waste Regulation entered into application, strengthening packaging-reduction and recyclability requirements across the European market.
June 2026: INBAR promoted bamboo-based substitutes for selected plastic applications during WTO Trade and Environment Week and called for stronger standards and green procurement frameworks.
May 2026: California’s permanent SB 54 regulations became effective, advancing extended producer responsibility and long-term plastic source-reduction requirements.
2026: INBAR continued showcasing bamboo pulp, paper and plastic-substitute products as part of its international Bamboo as a Substitute for Plastic initiative.
December 2025: Golden Arrow’s FIREWALL molded-fiber packaging design received the Platinum Prize in the sustainable and eco-friendly packaging category at the World Front Design Award.
Market Outlook
Molded bamboo fiber and pulp remain the largest material category and reach approximately USD 498.7 million by 2031, supported by foodservice, protective packaging and premium molded-fiber applications. Foodservice containers and tableware remain the largest packaging-format segment and reach approximately USD 304.8 million, while bottles, jars and other beauty-oriented formats grow faster from a smaller base.
Food and beverages remain the largest end-user market and reach approximately USD 378.6 million in 2031, while cosmetics and personal care gain share as premium and refillable bamboo-hybrid packaging becomes more widely used. Asia Pacific remains the largest regional market because of its raw-material and manufacturing base, although its growth is more moderate at approximately 4.65%. Europe expands faster at approximately 7.49% annually as regulatory pressure increases demand for renewable and recyclable packaging alternatives.
The market’s long-term development depends on practical performance rather than bamboo content alone. Suppliers must demonstrate acceptable barrier properties, structural strength, food-contact compliance, consistent appearance and competitive conversion costs while competing against recycled paper, bagasse, wood pulp and increasingly optimized plastic packaging. Bamboo is therefore expected to expand most successfully in applications where renewable feedstock, material performance and brand differentiation reinforce one another rather than where it competes only on sustainability claims.
Bamboo Packaging Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 705.0 million
Total Market Size in 2031
USD 923.5 million
Forecast Unit
USD Million
Growth Rate
5.55%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Material Form, Packaging Type, End User, Geography
Companies
Golden Arrow Packaging & Innovation
APG Packaging
Three Bamboo
Yilin Bamboo
Clement Packaging
PANABAM
HTAECO
Market Segmentation
By Material Form
Molded Bamboo Fiber and Pulp
Bamboo Paper and Paperboard
Solid Bamboo and Hybrid Packaging
By Packaging Type
Foodservice Containers and Tableware
Boxes, Cartons and Mailers
Bottles, Jars and Tubes
Protective Packaging and Inserts
Reusable Transport and Other Packaging
By End User
Food and Beverages
Cosmetics and Personal Care
E-Commerce
Electrical and Electronics
Automotive
Agriculture and Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Market Estimation
2.4. Segment Modelling
2.5. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Bamboo Packaging Market Size, 2026-2031
3.3. Material Form Outlook
3.4. Packaging Type Outlook
3.5. End-User Outlook
3.6. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Packaging Regulation Increasing Demand for Plastic Alternatives
4.1.2. Molded Plant Fiber Becoming More Commercially Established
4.1.3. Beauty Brands Using Bamboo for Premium Sustainability Positioning
4.2. Market Restraints
4.2.1. Barrier and Moisture-Resistance Limitations
4.2.2. Cost and Supply-Chain Scale
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Packaging Regulation and Certification Environment
5. TECHNOLOGICAL OUTLOOK
5.1. Wet-Pressed Molded Bamboo Fiber
5.2. Precision Fiber Molding
5.3. Bamboo Pulp Paper and Paperboard
5.4. Fiber Barrier Coatings
5.5. Refillable Bamboo-Hybrid Packaging
5.6. Printing and Surface Finishing
6. BAMBOO PACKAGING MARKET BY MATERIAL FORM
6.1. Molded Bamboo Fiber and Pulp
6.2. Bamboo Paper and Paperboard
6.3. Solid Bamboo and Hybrid Packaging
7. BAMBOO PACKAGING MARKET BY PACKAGING TYPE
7.1. Foodservice Containers and Tableware
7.2. Boxes, Cartons and Mailers
7.3. Bottles, Jars and Tubes
7.4. Protective Packaging and Inserts
7.5. Reusable Transport and Other Packaging
8. BAMBOO PACKAGING MARKET BY END USER
8.1. Food and Beverages
8.2. Cosmetics and Personal Care
8.3. E-Commerce
8.4. Electrical and Electronics
8.5. Automotive
8.6. Agriculture and Others
9. BAMBOO PACKAGING MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. France
9.3.3. United Kingdom
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. South Korea
9.5.5. Indonesia
9.5.6. Thailand
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
The bamboo packaging market is anticipated to grow from USD 705.0 million in 2026 to USD 923.5 million in 2031. This represents a Compound Annual Growth Rate (CAGR) of 5.55% over the forecast period, indicating a steady expansion in its adoption across various industries.
Molded bamboo fiber and pulp account for approximately 52% of the global bamboo packaging market value in 2026, equating to around USD 366.6 million. In terms of application formats, foodservice containers and tableware represent the largest category, comprising approximately 31% of the market value in 2026.
The Food and Beverages sector is a primary consumer, accounting for approximately 40% of global market value in 2026, driven by demand for takeaway containers, trays, and cups. Cosmetics and personal care packaging is projected to exhibit the highest annual growth, at approximately 8.2% through 2031, as brands increasingly adopt bamboo shells, lids, jars, and refillable hybrid formats.
Asia Pacific accounts for approximately 48% of the global bamboo packaging market value in 2026. This dominance is primarily attributed to its high concentration of bamboo resources within the region, alongside established pulping and converting capacities that support production.
Precision molded fiber and wet-pressed technologies are significantly improving the surface quality, dimensional accuracy, and branding options for bamboo packaging. This advancement allows bamboo-based packaging, exemplified by companies like Golden Arrow, to enter premium applications previously dominated by thermoformed plastic or high-end paperboard, offering superior protection and presentation for electronics, luxury goods, and cosmetics.
Demand is developing alongside the broader movement toward renewable fiber packaging, particularly for replacing rigid plastic or expanded foam without compromising performance. Initiatives by organizations like the International Bamboo and Rattan Organization increasingly position bamboo as an industrial feedstock, while commercial manufacturers leverage existing pulp and molded-fiber industry technologies to scale production across various consumer and industrial applications.