
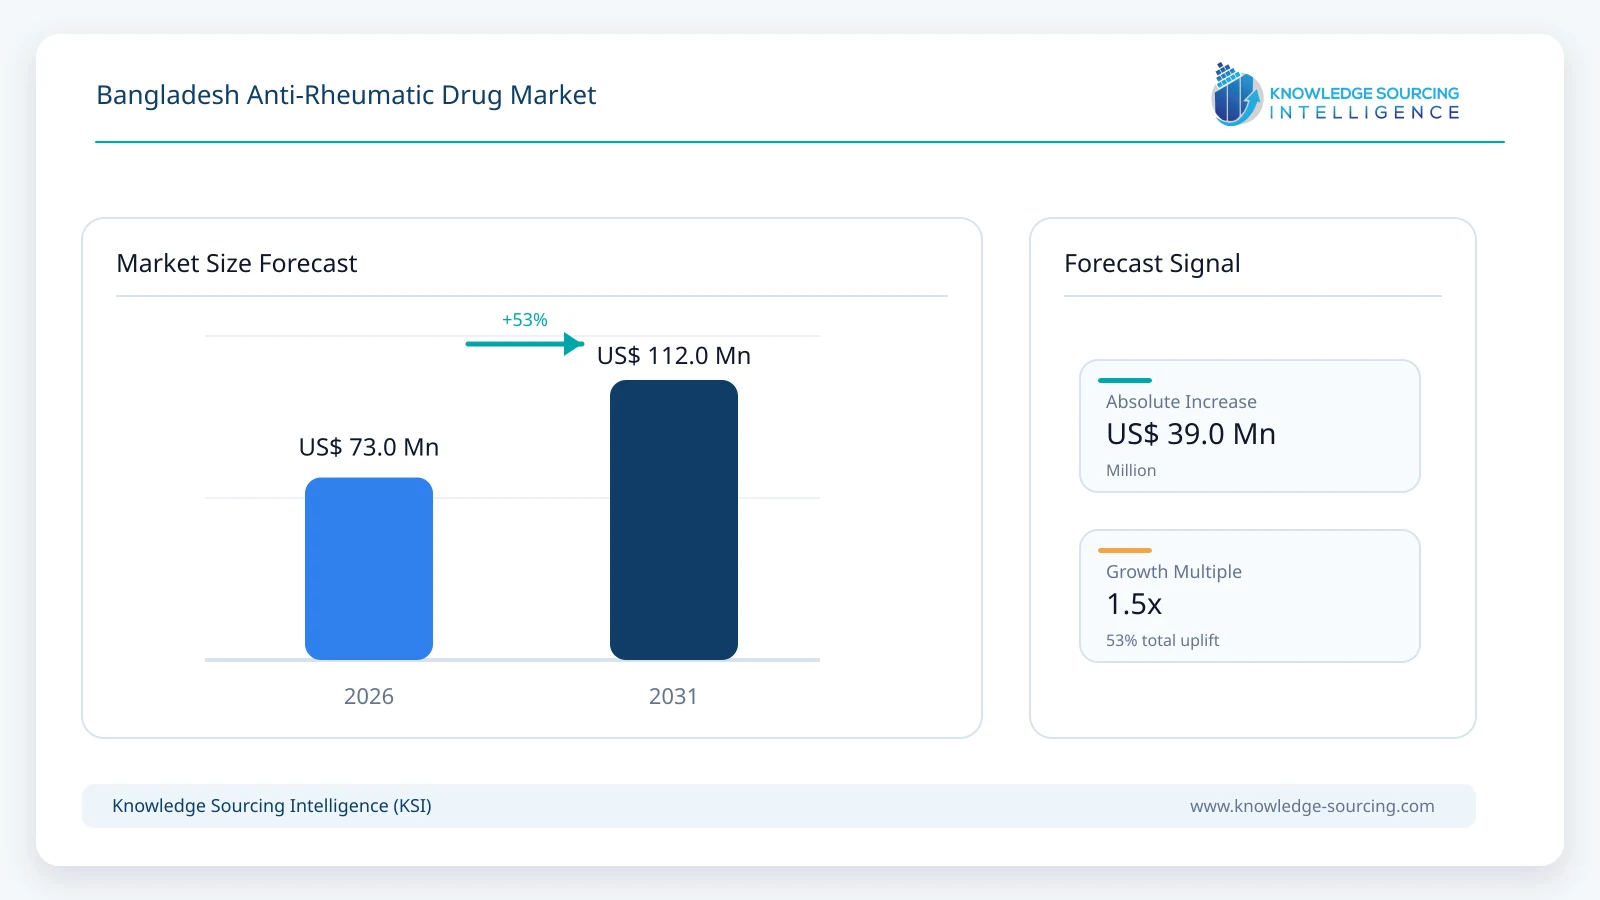
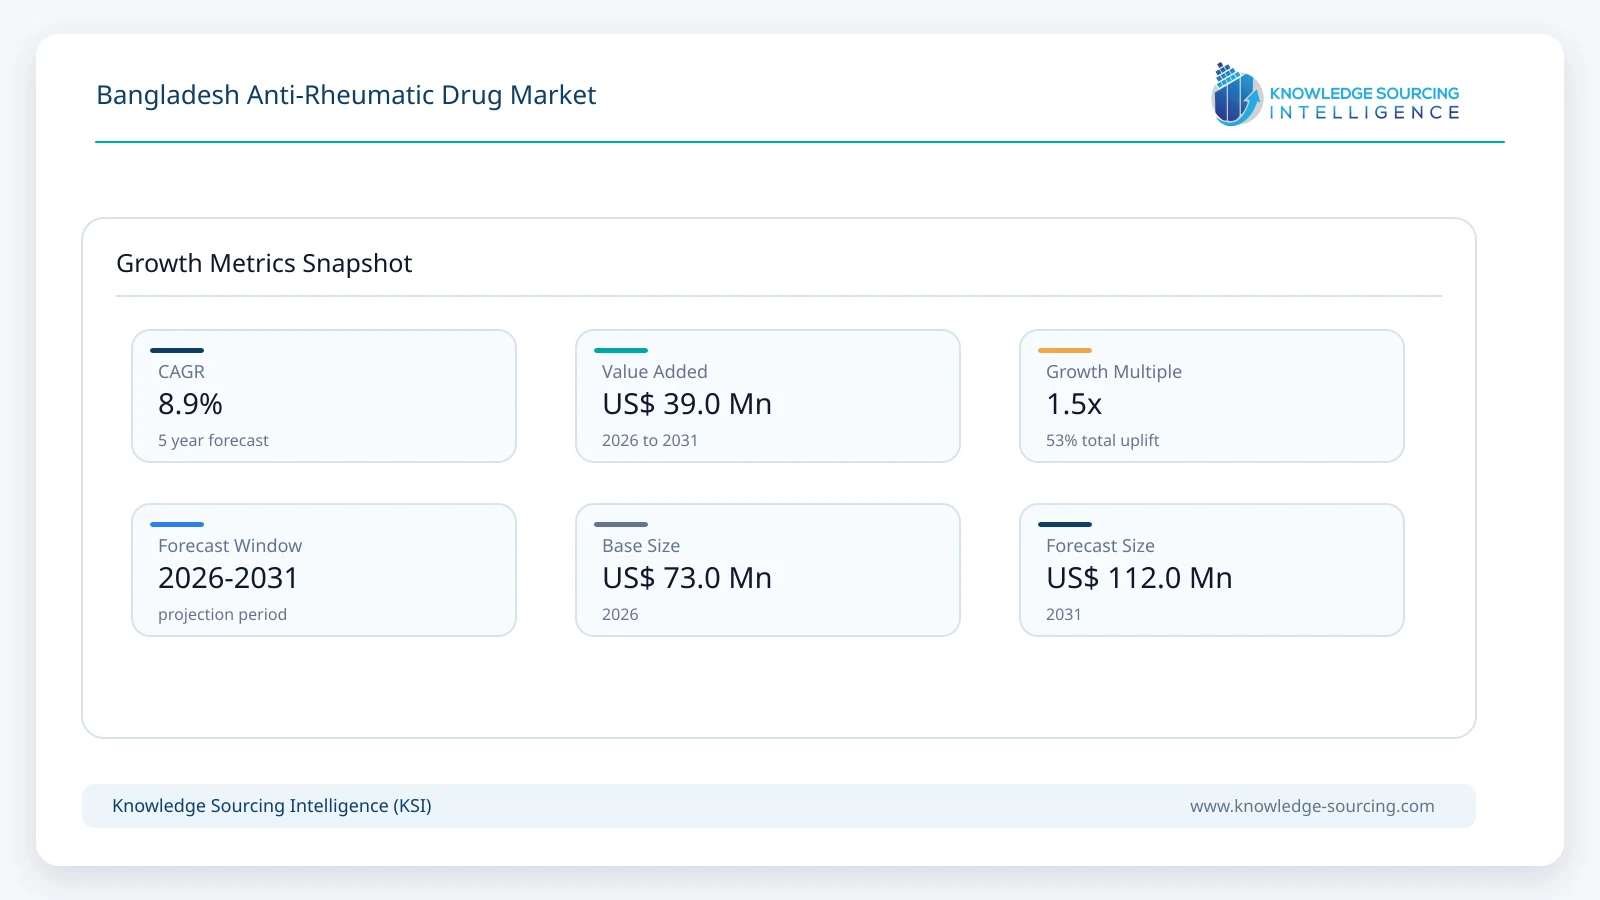
The Bangladesh Anti-Rheumatic Drug Market is expected to grow from USD 73.00 million in 2026 to USD 112.00 million by 2031, registering a CAGR of 8.94% over the forecast period.
Highlights:
- 1Conventional synthetic DMARDs remain the first-line foundation of rheumatoid arthritis management.
- 2Targeted synthetic therapies represent approximately 27% of current drug-category value.
- 3Domestic manufacturers offer multiple tofacitinib and baricitinib brands alongside established treatments.
- 4Oral therapies dominate access because routine outpatient treatment requires practical repeat dispensing.
- 5Biologic adoption remains sensitive to refrigeration, screening, infusion capacity and sustained affordability.
- 6Dhaka concentrates specialist prescribing, while Chattogram offers substantial room for access expansion.
Treatment of inflammatory rheumatic diseases in Bangladesh follows a tiered therapeutic pathway. Methotrexate, hydroxychloroquine, sulfasalazine and leflunomide provide the conventional disease-modifying foundation; tofacitinib, baricitinib and upadacitinib extend the range of oral options for selected patients requiring escalation. Biological products such as etanercept, adalimumab, rituximab and tocilizumab serve patients with more difficult-to-control disease, although their economics and monitoring requirements differ sharply from those of tablets.
The market includes medicines supplied in Bangladesh for rheumatoid arthritis, psoriatic arthritis, axial inflammatory arthritis and related rheumatic indications. It covers conventional and targeted synthetic DMARDs, biological DMARDs and attributable anti-inflammatory treatment, rather than general-purpose analgesic sales across unrelated conditions. Delta Pharma, Incepta, Square Pharmaceuticals, ACME Laboratories, Aristopharma and Ziska illustrate the domestic manufacturing and formulation base. Specialist prescribing, pharmacy access and the affordability of repeat prescriptions influence which products capture the most value.
The Bangladesh Rheumatology Society recommends methotrexate as the anchor therapy for active rheumatoid arthritis unless contraindicated, with alternatives such as sulfasalazine and leflunomide for patients unable to use it. The treatment pathway is not a simple progression from inexpensive pills to biologics. Physicians must weigh persistent inflammation, disease activity, comorbidities, prior drug response, the patient’s ability to return for monitoring and the likely affordability of several years of therapy. Low-priced formulations expand treatment reach, but medication adherence and follow-up determine how much of the clinically eligible population translates into sustained drug demand.
Delta Pharma markets Methotrax, Reumaflex, Tofacit, Baricit and Upacit XR; Incepta supplies Nodia, Tofacent and injectable TNF inhibitors, while Square lists tofacitinib and baricitinib products. These portfolios give prescribers a range of products across established and newer treatment classes without necessarily indicating equivalent use or sales volumes. Targeted synthetic drugs are important because they can be administered orally, avoiding some logistical burdens of injectable biological treatment, although their use requires risk assessment and laboratory surveillance.
The practical market constraint is the treatment pathway as a whole. Bangladesh’s high infectious-disease burden makes tuberculosis and hepatitis screening relevant before targeted or biologic treatment, while blood count and liver-function monitoring can affect dose continuation. Pharmacy supply and price competition favor generic oral drugs, whereas specialty products depend more heavily on rheumatology referral, procurement and patient support. Commercial performance consequently reflects the patient’s full care experience, not just molecule availability.
Market Trends
Oral JAK Inhibitors Extend the Treatment Ladder
Tofacitinib, baricitinib and upadacitinib are represented in local manufacturers’ portfolios, allowing clinicians to consider targeted synthetic treatment without relying exclusively on imported injectable biologics. Delta Pharma’s Tofacit, Baricit and Upacit offerings, together with Incepta’s Tofacent and Square’s Tofator, demonstrate the breadth of marketed dosage choices. Different dose strengths and extended-release formulations can support prescribing flexibility, but do not eliminate the need for screening and risk-based patient selection.
For manufacturers, the commercial issue is maintaining continuity across repeated prescriptions while competing on manufacturing consistency, availability and price. As patients cycle between treatments after inadequate response, product support and reliably supplied brands can matter as much as initial listing. Expansion will be gradual because eligibility for a targeted drug is narrower than the full diagnosed arthritis population.
Conventional DMARDs Retain a Strong Clinical and Economic Position
Methotrexate remains central to Bangladesh Rheumatology Society recommendations, making it difficult for new therapeutic classes to displace the existing base of treatment. Patients frequently require dose adjustment and ongoing safety monitoring rather than a one-time prescription. Delta’s Methotrax and Incepta’s Nodia demonstrate how domestic manufacturers participate in the conventional category through several established molecules.
The economics of long-term care reinforce that position. Conventional therapies are generally easier to dispense at community pharmacies, while patients who cannot afford targeted treatment may continue with alternative combinations of established drugs. The resulting market is likely to show rising value in premium oral and biological therapies without a comparable collapse in conventional prescription volume.
Biological Therapy Depends on Specialist Infrastructure
Injectable TNF inhibitors and IL-6-directed medicines expand options when conventional treatment is inadequate. Incepta lists etanercept and adalimumab products, and Roche Bangladesh identifies Actemra as an approved tocilizumab option for rheumatoid arthritis. The clinical distinction is material: biologics often require cold-chain handling, injection technique or hospital infusion arrangements and pre-treatment infection screening, particularly where latent tuberculosis is a concern.
This creates a different route to market from routine oral medicines. Manufacturers and hospitals must support distribution temperature control, authenticated supply and predictable access to follow-up treatment. Competitive differentiation therefore rests partly on supply assurance and service capability rather than only the nominal medicine price.
Clinical Guidance Is Increasingly Locally Specific
Bangladesh’s 2023 rheumatology recommendations, published in 2024, explicitly consider constrained budgets, infection risks and the practical appeal of targeted oral options. The guidance recommends clinical reassessment after treatment initiation and risk screening before JAK inhibitors and biologics. These national considerations are important because treatment algorithms written for high-income health systems do not transfer directly to a market where affordability can determine drug sequencing.
A Bangladesh clinical study of baricitinib and methotrexate, published in 2026 and supplied with study medicines by Delta Pharma, adds local evidence to an already established treatment category. Its presence does not by itself demonstrate national sales growth, but contributes to clinician familiarity with locally available products and relevant treatment decisions.
Bangladesh Anti-Rheumatic Drug Market Segment Analysis
By Drug Class
Conventional Synthetic DMARDs
Conventional synthetic DMARDs generate an estimated USD 28.0 million in 2026. Their leading role reflects the widespread use of methotrexate as initial disease-modifying therapy and the place of hydroxychloroquine, leflunomide and sulfasalazine as alternatives or combination treatments. These molecules typically require long-duration dispensing, with repeated laboratory checks affecting adherence and prescription renewal.
Growth in this category is supported by better diagnosis and the treatment of patients who previously relied on episodic relief. It is nevertheless slower than targeted oral therapy because aggressive price competition constrains average realized revenue. Domestic companies that combine competitive pricing with a broad and dependable dosage portfolio are positioned to protect prescription volumes as the escalation market develops.
By Disease Type
Rheumatoid Arthritis
Rheumatoid arthritis remains the primary commercial indication because persistent inflammatory disease creates long-duration demand for conventional, targeted and biological disease-modifying therapies. Bangladesh Rheumatology Society guidance gives clinicians a locally relevant framework for when to begin methotrexate, assess response and consider an alternative or more advanced class. This reinforces continuous disease control rather than treatment of isolated pain episodes.
The rheumatoid arthritis segment is projected to account for approximately 75% of market value in 2031. Its value reflects both the breadth of initial therapy and the use of costlier medicines among patients with refractory disease. Other inflammatory conditions share some of the same molecules, but their patient pools and prescribing pathways are smaller or less consistently documented.
By Route of Administration
Oral Medicines
Oral products dominate the current market as long-term rheumatic disease treatment is largely managed outside inpatient care. Methotrexate and leflunomide are established options, while tablet and extended-release JAK inhibitor formulations add higher-value choices for selected patients. The oral route also permits dispensing through established retail pharmacy networks, although availability does not guarantee appropriate monitoring.
Oral therapy is expected to approach USD 94.0 million in 2031. Demand for injectables rises in more complex disease, but biologics require refrigeration, administration training and additional spending. The relative convenience of tablets therefore shapes both market size and the competitive strategies of local manufacturers across the treatment ladder.
By Distribution Channel
Retail and Community Pharmacies
Retail and community pharmacies represent the largest channel because patients collecting oral prescriptions for chronic inflammatory disease generally require frequent refills close to home. Manufacturers compete for dependable pharmacy placement, stock availability and affordability, while physicians influence molecule choice and dose management. Hospital pharmacies remain important where the prescription originates in specialist services or the drug requires supervised administration.
The retail channel contributes an estimated 60% of market revenue in 2026. More repeat dispensing outside tertiary centers can increase reach, but an effective distribution model must avoid unsupervised escalation and inappropriate corticosteroid use. Consistent packaging, counseling and access to prescribers are therefore practical parts of channel performance.
Market Drivers
Large Burden of Persistent Inflammatory Joint Disease
Bangladesh Rheumatology Society publications describe rheumatoid arthritis as a substantial local clinical problem, with repeated treatment needed to protect mobility and joint function. Unlike short episodes of musculoskeletal pain, active inflammatory arthritis can require years of disease-modifying therapy. A larger pool of patients completing diagnosis and follow-up supports recurring demand across multiple prescription classes.
Commercial gains are concentrated where symptoms lead to rheumatology referral, laboratory assessment and a sustained prescription. Growth in nominal patient awareness alone is insufficient if treatment is interrupted by travel costs or monitoring expenses.
Availability of Locally Made Targeted Medicines
Delta, Incepta, Square, ACME and Aristopharma list locally supplied JAK inhibitors, offering different brands and dose presentations. Their presence expands commercial choice beyond originator import channels and can reduce some of the access barriers associated with newer oral immunomodulators.
The central purchasing decision nevertheless remains the clinically appropriate treatment choice. Drug makers able to maintain dependable supplies and credible prescribing information can benefit as more rheumatologists use stepwise escalation after inadequate conventional therapy.
Earlier Diagnosis and Structured Disease Monitoring
Rheumatology recommendations emphasize treatment targets, response checks and modification of therapy when inflammation remains active. Increasing use of structured follow-up can reduce the period when patients rely exclusively on symptom relief, thereby raising the share receiving disease-modifying treatment.
This mechanism favors both conventional and advanced therapies. Laboratories and specialist appointments are complements to medicine demand because monitoring supports safe continuation rather than merely generating a prescription at diagnosis.
Expanded Choice of Biological and Biosimilar Medicines
Incepta markets injectable etanercept and adalimumab, while Roche Bangladesh identifies a registered tocilizumab product. For selected patients with severe disease, those classes provide treatment options that operate through different immune pathways from conventional synthetic medicines.
Biologic uptake remains modest compared with oral drugs, but a relatively small change in treated patient numbers can contribute meaningful value because per-patient medicine spending is higher. Dependable cold-chain and specialist prescribing are central to this opportunity.
Long-Term Supply Networks in Secondary Cities
Community pharmacy distribution extends the reach of maintenance prescriptions beyond Dhaka’s specialist hospitals. When rheumatology care develops in regional medical centers, patients may be able to obtain repeat oral therapy locally instead of travelling for every prescription refill.
Improved continuity particularly benefits manufacturers of low-cost conventional drugs and established targeted tablets. It also supports a wider geographic market without implying that all divisions have equal specialist access today.
Market Restraints
Affordability of Continuous Advanced Treatment
Patients may face several years of medicine and monitoring expenditure, with advanced treatment unaffordable even when a suitable product is listed locally. Targeted agents and biologics consequently address a smaller paying population than clinical prevalence alone might suggest.
Financial interruptions also weaken treatment continuity. Manufacturers need affordable pack sizes and stable pricing, while providers must consider the total cost of follow-up rather than medicine price in isolation.
Tuberculosis and Other Infection-Screening Requirements
Before JAK inhibitors or biological DMARDs, Bangladesh Rheumatology Society guidance recommends attention to latent tuberculosis and viral hepatitis screening. These safeguards have particular significance in settings with substantial infectious-disease exposure.
Screening, vaccination review and repeat assessment increase the complexity of specialist prescribing. Patients who cannot complete the required evaluation may remain on less intensive treatment, limiting the immediately treatable market for premium therapies.
Safety Monitoring and Drug-Specific Risk Assessment
Conventional and targeted medicines have different monitoring needs. Methotrexate requires attention to hepatic and hematological toxicity, while JAK inhibitors carry important warnings concerning infection and thromboembolic or cardiovascular risk in selected patients.
Adherence to screening and follow-up is therefore necessary for sustainable growth. Product availability without a safe treatment pathway can lead to poor outcomes and constrain physician willingness to escalate.
Uneven Rheumatology Specialist Availability
Complex inflammatory arthritis often requires a trained clinician to distinguish it from osteoarthritis, gout or non-inflammatory pain. Specialist concentration in major cities can delay accurate diagnosis and affect which medicines are prescribed.
Regional market growth depends on referral capacity and laboratory infrastructure. It cannot be inferred from population share alone, because patients in underserved areas may be diagnosed late or receive treatment through general practice.
Cold-Chain and Procurement Burdens for Injectables
Injectable biological products create greater logistical demands than widely available tablets. Consistent refrigeration, authentication and predictable procurement are necessary to avoid interruptions in treatment, especially outside major tertiary facilities.
Hospitals and specialty suppliers must balance inventory cost against a comparatively small eligible patient base. These characteristics can slow the rollout of biological medicines even where clinical demand exists.
Regional Outlook
Dhaka Division
Dhaka leads Bangladesh’s anti-rheumatic drug market, representing an estimated 35.6% of national value in 2026. The capital’s concentration of tertiary hospitals, rheumatology specialists, diagnostic laboratories and large pharmaceutical distribution networks supports both initial disease-modifying treatment and escalation to higher-value medicines. Patients from outside the division may also travel to Dhaka for complex care, which makes the point of treatment relevant to the location of recorded medicine sales.
Its position is likely to remain strong through 2031, although expansion of specialist care elsewhere may gradually reduce the capital’s proportion of national demand. Wider availability of biological therapy is tied to referral pathways and monitoring facilities rather than population size alone. For suppliers, institutional contracting and physician-facing clinical support are particularly important in this division.
Chattogram Division
Chattogram offers the fastest modelled expansion among the eight divisions, with drug-market revenue forecast to rise at approximately 12.0% annually over 2026–2031. Its large population base, metropolitan medical facilities and industrial employment centers provide a basis for broader outpatient prescribing, while rural areas still face substantial access constraints. Improved referral networks can bring patients with persistent inflammatory symptoms into long-term treatment sooner.
The division’s share increases as more targeted oral medicines become accessible through specialist clinics and retail pharmacies. The opportunity should not be read as equivalent to an immediate surge in biologic injections: hospital support, cold-chain reliability and screening capacity remain necessary for that segment. Expansion of conventional treatment adherence is likely to precede significant premium-therapy penetration.
Competitive Landscape
Bangladesh’s anti-rheumatic pharmaceutical competition is anchored by local manufacturers with overlapping generic portfolios. Delta Pharma supplies conventional and JAK-inhibitor products across its DMARD range; Incepta combines small-molecule offerings with injectable etanercept and adalimumab; Square supplies tofacitinib and baricitinib. ACME, Aristopharma and Ziska participate through verified targeted synthetic products. Competition takes place through prescriber confidence, drug availability, presentation choice and price rather than a single dominant technology platform.
Roche Bangladesh supplies Actemra for rheumatoid arthritis, illustrating the presence of multinational biological therapy alongside domestic formulations. The supplier set is not uniform: some businesses compete mainly in recurring oral prescriptions, whereas others address specialist-administered medicine. As care broadens outside major cities, the capacity to supply routine tablets consistently and support safe escalation becomes an increasingly important commercial distinction.
Recent Developments
March 2026: A Bangladesh randomized clinical study comparing baricitinib doses with methotrexate was published in BMC Rheumatology; the study acknowledged Delta Pharmaceuticals as the supplier of the baricitinib and methotrexate used. The result adds local clinical evidence around existing rheumatology medicines rather than documenting a new product launch.
May 2025: Incepta Pharmaceuticals revised the prescribing-information text for its Shieldex (etanercept) injection, covering its rheumatoid arthritis and related inflammatory indications. This was a product-document update, not evidence of a newly introduced brand or an expanded national approval.
Market Outlook
The most consequential change through 2031 is expected to be a broader treatment ladder within a price-sensitive pharmaceutical market. Conventional synthetic drugs will continue to account for a large volume of care, while targeted oral products increase their share where patients remain symptomatic after first-line therapy. Local manufacturers with reliable generic portfolios are well positioned to serve this transition, provided treatment remains subject to appropriate clinical assessment.
Biological medicines will remain commercially significant but comparatively constrained by patient affordability, specialist supply and infection screening. Dhaka is likely to retain the largest concentration of advanced prescriptions, while Chattogram’s larger patient-access gains support faster growth. The long-term market will be shaped by adherence, medical follow-up and the ability to connect diagnosis with continuous treatment, rather than by drug availability alone.
Bangladesh Anti-Rheumatic Drug Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 73.00 million |
| Total Market Size in 2031 | USD 112.00 million |
| Forecast Unit | USD Million |
| Growth Rate | 8.94% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Drug Class, Disease Type, Route of Administration, Distribution Channel, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Drug Class
Conventional Synthetic DMARDs
Targeted Synthetic DMARDs/JAK Inhibitors
Biological DMARDs and Biosimilars
Indication-Attributable NSAIDs and Glucocorticoids
By Disease Type
Rheumatoid Arthritis
Psoriatic Arthritis
Axial Spondyloarthritis/Ankylosing Spondylitis
Other Inflammatory Rheumatic Diseases
By Route of Administration
Oral
Parenteral
By Distribution Channel
Retail and Community Pharmacies
Hospital Pharmacies
Specialty and Direct Institutional Supply
By Geography
Dhaka
Chattogram
Rajshahi
Khulna
Rangpur
Mymensingh
Sylhet
Barishal
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Large Burden of Persistent Inflammatory Joint Disease
3.1.2. Availability of Locally Made Targeted Medicines
3.1.3. Earlier Diagnosis and Structured Disease Monitoring
3.1.4. Expanded Choice of Biological and Biosimilar Medicines
3.1.5. Long-Term Supply Networks in Secondary Cities
3.2. Market Restraints
3.2.1. Affordability of Continuous Advanced Treatment
3.2.2. Tuberculosis and Other Infection-Screening Requirements
3.2.3. Safety Monitoring and Drug-Specific Risk Assessment
3.2.4. Uneven Rheumatology Specialist Availability
3.2.5. Cold-Chain and Procurement Burdens for Injectables
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Conventional Synthetic DMARDs
4.2. JAK-Inhibitor Treatment
4.3. Biologic and Biosimilar Therapy
4.4. Pharmaceutical Supply, Monitoring and Safety
5. BANGLADESH ANTI-RHEUMATIC DRUG MARKET BY DRUG CLASS
5.1. Introduction
5.2. Conventional Synthetic DMARDs
5.3. Targeted Synthetic DMARDs / JAK Inhibitors
5.4. Biological DMARDs and Biosimilars
5.5. Indication-Attributable NSAIDs and Glucocorticoids
6. BANGLADESH ANTI-RHEUMATIC DRUG MARKET BY DISEASE TYPE
6.1. Introduction
6.2. Rheumatoid Arthritis
6.3. Psoriatic Arthritis
6.4. Axial Spondyloarthritis / Ankylosing Spondylitis
6.5. Other Inflammatory Rheumatic Diseases
7. BANGLADESH ANTI-RHEUMATIC DRUG MARKET BY ROUTE OF ADMINISTRATION
7.1. Introduction
7.2. Oral
7.3. Parenteral
8. BANGLADESH ANTI-RHEUMATIC DRUG MARKET BY DISTRIBUTION CHANNEL
8.1. Introduction
8.2. Retail and Community Pharmacies
8.3. Hospital Pharmacies
8.4. Specialty and Direct Institutional Supply
9. BANGLADESH ANTI-RHEUMATIC DRUG MARKET BY GEOGRAPHY
9.1. Introduction
9.2. Dhaka
9.3. Chattogram
9.4. Rajshahi
9.5. Khulna
9.6. Rangpur
9.7. Mymensingh
9.8. Sylhet
9.9. Barishal
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Agreements, Product Introductions and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Delta Pharma PLC
11.2. Incepta Pharmaceuticals Ltd.
11.3. Square Pharmaceuticals PLC
11.4. The ACME Laboratories Ltd.
11.5. Aristopharma Ltd.
11.6. Ziska Pharmaceuticals Limited
11.7. Roche Bangladesh
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected market size for Bangladesh anti-rheumatic drugs by 2031?
The Bangladesh Anti-Rheumatic Drug Market is projected to reach USD 112.00 million by 2031.
What is the Compound Annual Growth Rate (CAGR) for this market?
The Bangladesh Anti-Rheumatic Drug Market is registering an 8.94% CAGR over the forecast period.
Which drug category currently holds significant market value?
Targeted synthetic therapies represent approximately 27% of current drug-category value.
Which drug type dominates access for anti-rheumatic treatment in Bangladesh?
Oral therapies dominate access due to practical repeat dispensing requirements.
Where is specialist prescribing concentrated, and where is room for expansion?
Dhaka concentrates specialist prescribing; Chattogram offers substantial room for expansion.
Who are the key domestic manufacturers in the Bangladesh market?
Delta, Incepta, Square, ACME, Aristopharma, and Ziska are key manufacturers.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Bangladesh Anti-Rheumatic Drug Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/bangladesh-anti-rheumatic-drug-market