
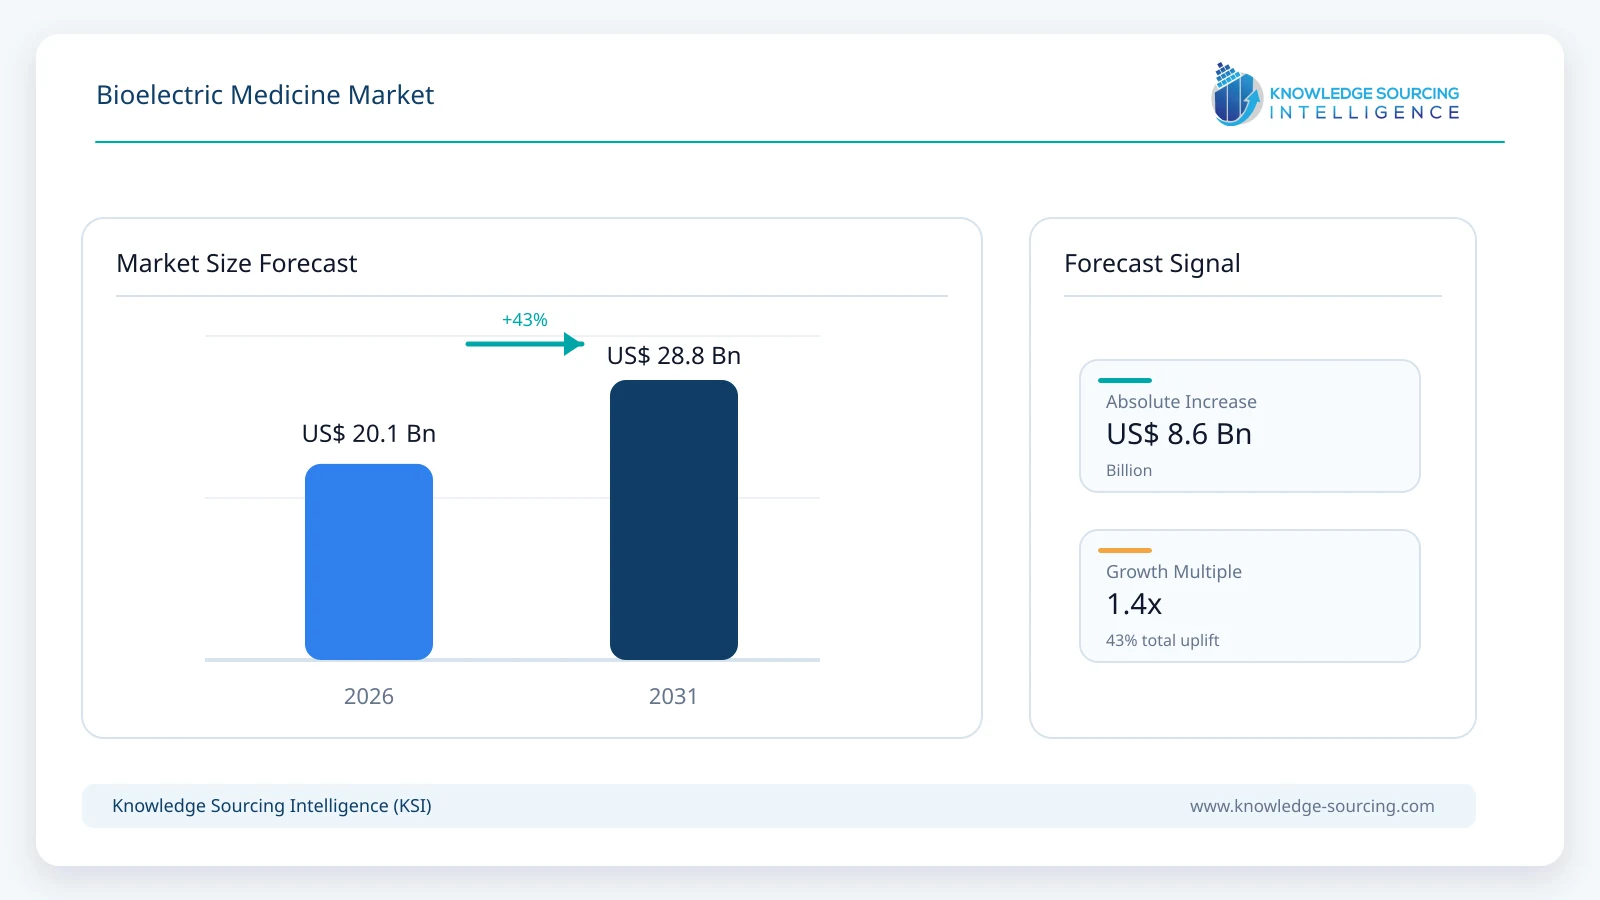
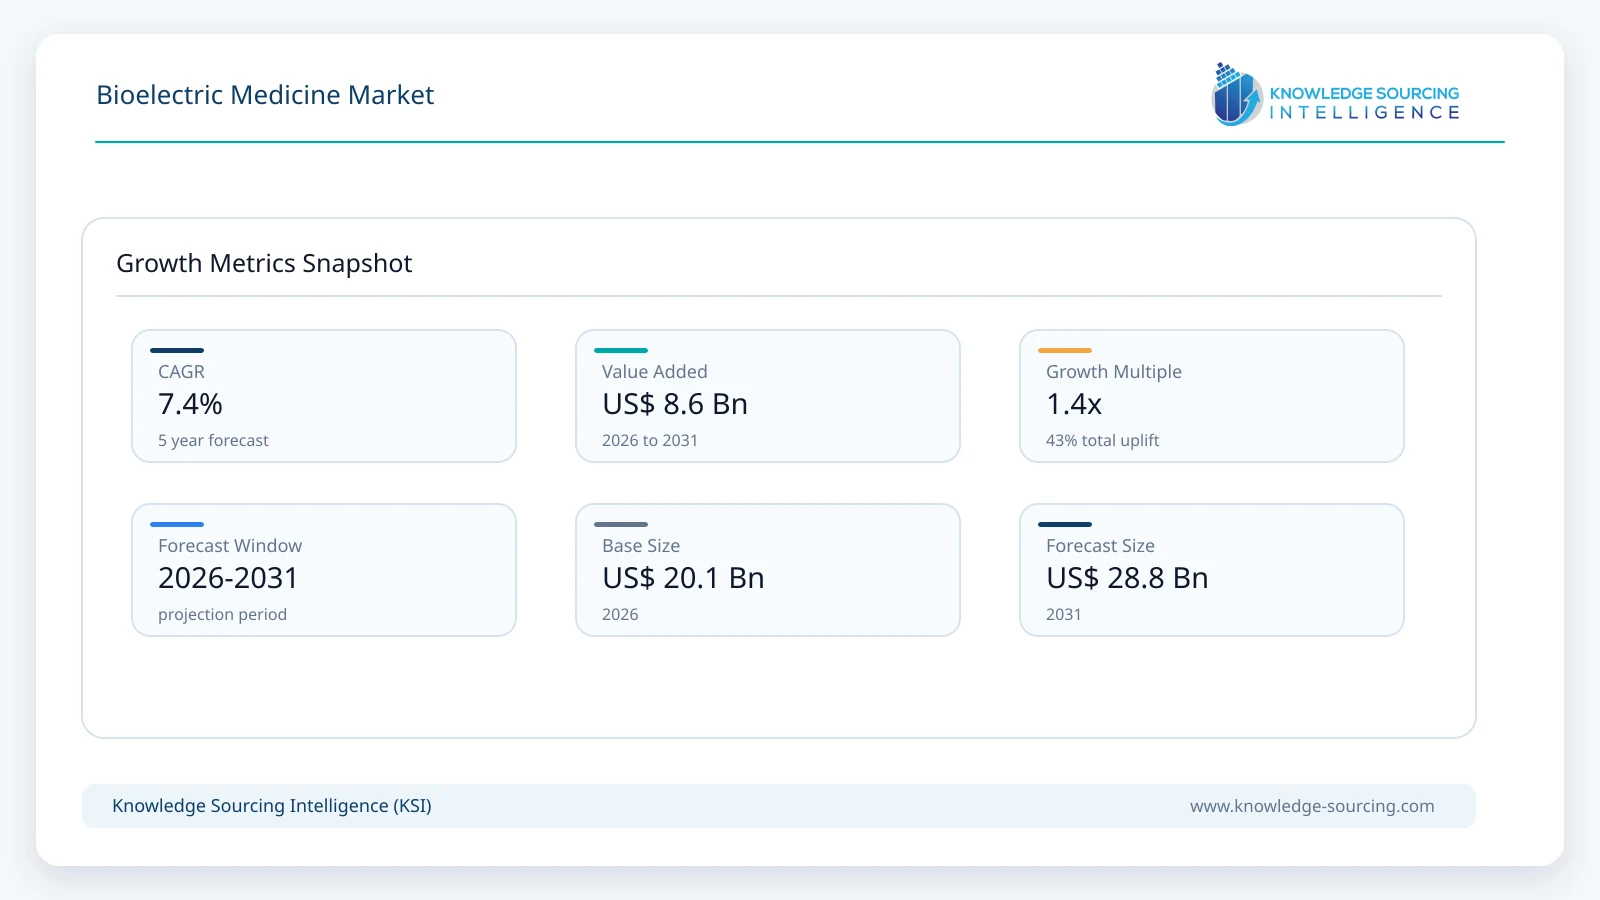
Bioelectric Medicine Market is estimated at USD 20.15 billion in 2026 and is forecast to reach approximately USD 28.77 billion in 2031, representing a CAGR of 7.4% across the forecast period.
Highlights:
- 1Neuromodulation demand is expanding across cardiac, neurological, pain, hearing, and inflammatory indications.
- 2Chronic disease burden is widening the clinical need for electrical therapies.
- 3Closed-loop stimulation is shifting competition toward sensing, personalization, and therapy control.
- 4Reimbursement and clinical evidence increasingly influence adoption of implantable bioelectric therapies.
- 5Non-invasive stimulation is broadening the addressable market beyond surgical neuromodulation procedures.
- 6Regulatory scrutiny remains high for implantable devices because of safety and long-term performance risks.
Key Highlights
Market Overview
The commercial base includes established therapies such as cardiac pacemakers, implantable cardioverter defibrillators, spinal cord stimulators, deep brain stimulators, vagus nerve stimulators, cochlear implants, sacral nerve stimulators, peripheral nerve stimulators, and transcutaneous electrical stimulation devices. Demand is therefore spread across cardiovascular care, pain management, neurological disease, hearing loss, rehabilitation, and selected inflammatory disorders.
Clinical need provides a broad demand base. The World Health Organization estimates that neurological conditions affect more than 40% of the global population, while epilepsy affects about 50 million people worldwide. Parkinson’s disease affected more than 8.5 million people in 2019, and disabling hearing loss already requires rehabilitation for about 430 million people.
Purchasing decisions differ by application. Hospitals and specialist centers assess clinical evidence, safety, implant longevity, MRI compatibility, programming capability, procedure time, service support, and reimbursement. Patients and clinicians also weigh device size, recharge requirements, surgical burden, and expected symptom control. For suppliers, recurring replacement procedures, programming services, accessories, and software can extend revenue beyond the initial implant.
The commercial opportunity is increasingly moving toward systems that can adjust stimulation to patient-specific signals rather than deliver fixed electrical output. Clinical evidence for closed-loop spinal cord stimulation and responsive epilepsy systems supports this direction. At the same time, non-invasive vagus nerve stimulation is creating a lower-procedure pathway for selected indications. The market will therefore develop through both expansion of established device categories and selective commercialization of newer neural interfaces.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Neurological conditions | More than 40% of the global population | A broad disease burden supports long-term demand for neurological therapies and neuromodulation. |
Epilepsy | About 50 million people worldwide | Drug-resistant cases create a clinical need for alternatives to medication, including implanted stimulation. |
Parkinson’s disease | More than 8.5 million people in 2019 | The growing neurological burden supports demand for therapies such as deep brain stimulation. |
Disabling hearing loss | 430 million people requiring rehabilitation | Hearing implants address a large clinical need where conventional amplification provides limited benefit. |
U.S. chronic pain | 24.3% of adults in 2023 | The scale of chronic pain supports a large clinical base for spinal and peripheral neuromodulation. |
Global ageing | 1.4 billion people aged 60+ projected by 2030 | Age-related neurological, cardiovascular, sensory, and functional disorders can expand the addressable patient pool. |
Market Drivers
Large unmet need in drug-resistant neurological disease. About 50 million people worldwide live with epilepsy, and WHO estimates that up to 70% could become seizure-free with appropriate diagnosis and treatment. However, treatment access remains uneven, particularly in low- and middle-income countries. Drug-resistant patients form a more specialized clinical population in which stimulation devices can complement or replace inadequate pharmacological control. NeuroPace's RNS System uses brain activity to deliver responsive stimulation for adults with drug-resistant focal epilepsy, illustrating how clinical need is moving demand toward targeted neural intervention.
Persistent chronic pain is supporting spinal and peripheral stimulation. U.S. National Center for Health Statistics data shows that 24.3% of adults experienced chronic pain in 2023, while 8.5% experienced high-impact chronic pain. This creates a large population for which long-term pain control can require approaches beyond medication and conventional procedures. Clinical evidence also supports more controlled stimulation. In the EVOKE trial, closed-loop spinal cord stimulation produced a higher proportion of patients achieving at least 50% pain reduction at 36 months than open-loop therapy.
Improved device control is raising the value of neuromodulation systems. Fixed stimulation delivers a preset output even when patient movement changes the relationship between electrodes and neural tissue. Medtronic's Inceptiv system introduced closed-loop sensing that detects evoked compound action potentials and adjusts stimulation in real time. The commercial effect is broader than a new hardware feature. Better control can support clinician confidence, reduce unwanted stimulation, improve patient experience, and differentiate products in replacement and upgrade decisions.
Clinical validation is expanding bioelectric medicine beyond established indications. Research has moved electrical stimulation toward inflammatory and autoimmune disorders, where the vagus nerve can influence immune pathways. SetPoint Medical received FDA approval in July 2025 for its implantable vagus nerve stimulation system for adults with moderately to severely active rheumatoid arthritis who have inadequate response or intolerance to specified drug therapies. The development gives suppliers a regulatory precedent for using neural stimulation outside conventional neurological indications.
Hearing loss creates a separate implant demand pathway. WHO estimates that 430 million people require rehabilitation for disabling hearing loss, with the burden concentrated heavily in low- and middle-income countries. Cochlear implants electrically stimulate the auditory nerve and are intended for people who receive limited benefit from hearing aids. Regulatory expansion has also widened eligible populations in selected cases, including FDA approval for certain patients with single-sided deafness. This supports continued product development around implant reliability, sound processing, connectivity, and clinical access.
Market Restraints and Challenges
Surgical and long-term device risks restrict patient selection. Implantable stimulation requires a procedure and creates exposure to infection, lead problems, battery limitations, device failure, and revision surgery. Cochlear implant guidance from the FDA, for example, identifies surgical complications, infection, device failure, and uncertainty around some long-term effects as relevant risks. Similar considerations apply across implanted neural devices. These risks make clinical evidence, implant reliability, MRI compatibility, and long-term service support central to purchasing decisions.
Regulatory evidence requirements extend development cycles. Many implanted neurostimulators fall into high-risk regulatory categories. FDA classifies implanted neuromuscular stimulators as Class III devices, while PMA is the primary pathway for Class III devices requiring the most stringent evidence of safety and effectiveness. In Europe, active implantable devices are classified as Class III under the Medical Device Regulation. Smaller companies must therefore fund clinical studies, quality systems, regulatory submissions, manufacturing validation, and post-market monitoring before reaching commercial scale.
Reimbursement can determine procedure penetration. Device efficacy does not automatically translate into hospital adoption. Hospitals must recover the cost of implants, operating-room time, physician services, follow-up, programming, and replacement procedures. LivaNova reported that higher U.S. Medicare reimbursement for VNS procedures took effect on January 1, 2026, with hospital outpatient payment increases of about 48% for new implants and 47% for end-of-service procedures compared with 2025 rates. The change illustrates how payment levels can directly influence provider economics.
Manufacturing qualification creates supply-chain rigidity. Implantable devices require controlled materials, specialized components, sterilization, battery systems, hermetic packaging, and validated manufacturing processes. FDA records show repeated supplier, material, testing, and manufacturing-process changes involving Medtronic, Abbott, and Boston Scientific neuromodulation systems during 2025 and 2026. Such changes require regulatory control and validation rather than simple supplier substitution. The resulting qualification burden can increase operating costs and limit the speed at which manufacturers respond to component shortages.
Major Segment Analysis
Spinal Cord Stimulators
Spinal cord stimulation represents a commercially important product category because it addresses chronic pain, a large and persistent clinical burden, while supporting recurring revenue from implants, replacement components, programming, and follow-up care. Buyers assess pain outcomes alongside battery life, MRI access, lead configuration, programming flexibility, implant size, and evidence from controlled clinical studies.
The technology is also becoming more differentiated. Closed-loop systems can sense neural responses and adjust stimulation instead of relying solely on fixed output. Medtronic's Inceptiv uses evoked compound action potential sensing, while long-term EVOKE results showed stronger pain-response rates for closed-loop therapy than open-loop stimulation at 36 months. This raises competitive pressure on suppliers to improve sensing, personalization, recharge systems, imaging compatibility, and clinical evidence rather than compete only on basic stimulation hardware.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Established neuromodulation infrastructure, specialist care, clinical research, and reimbursement support for implantable therapies. | High device and procedure costs, payer requirements, and stringent FDA evidence standards can restrict access. |
Europe | Established use of cardiac rhythm management, cochlear implants, and neuromodulation, supported by specialist healthcare systems. | MDR compliance, clinical evidence requirements, and differences in national reimbursement can lengthen market entry and adoption. |
Asia Pacific | Large neurological and chronic disease populations, expanding specialist capacity, and growing medical-device investment in China, Japan, South Korea, and India. | Uneven reimbursement, specialist availability, pricing pressure, and differences in regulatory and hospital infrastructure. |
South America | Brazil and Argentina provide the strongest addressable specialist markets, supported by tertiary hospitals and private healthcare capacity. | Import dependence, uneven reimbursement, limited specialist access, and foreign-exchange pressure can restrict device adoption. |
Middle East and Africa | Healthcare investment in Saudi Arabia, the UAE, and Israel is supporting specialist procedures and advanced medical-device adoption. | Limited specialist capacity in several countries, import dependence, procedure costs, and unequal healthcare access constrain wider adoption. |
North America benefits from established clinical pathways for pacemakers, defibrillators, spinal cord stimulation, deep brain stimulation, VNS, and other implantable therapies. The United States also has a large chronic-pain population, with CDC data showing that 24.3% of adults experienced chronic pain in 2023. Reimbursement changes can materially influence procedure economics. LivaNova reported that U.S. Medicare payment rates for VNS procedures increased from January 2026, improving hospital economics for eligible procedures.
Europe combines mature medical-device markets with stricter regulatory oversight. The EU Medical Device Regulation classifies active implantable devices as Class III, requiring extensive clinical, technical, and post-market evidence. Adoption therefore depends not only on clinical performance but also on conformity assessment, reimbursement decisions, hospital budgets, and national healthcare priorities. The United Kingdom's strengthened post-market surveillance requirements for active implantable devices add further lifecycle obligations for suppliers.
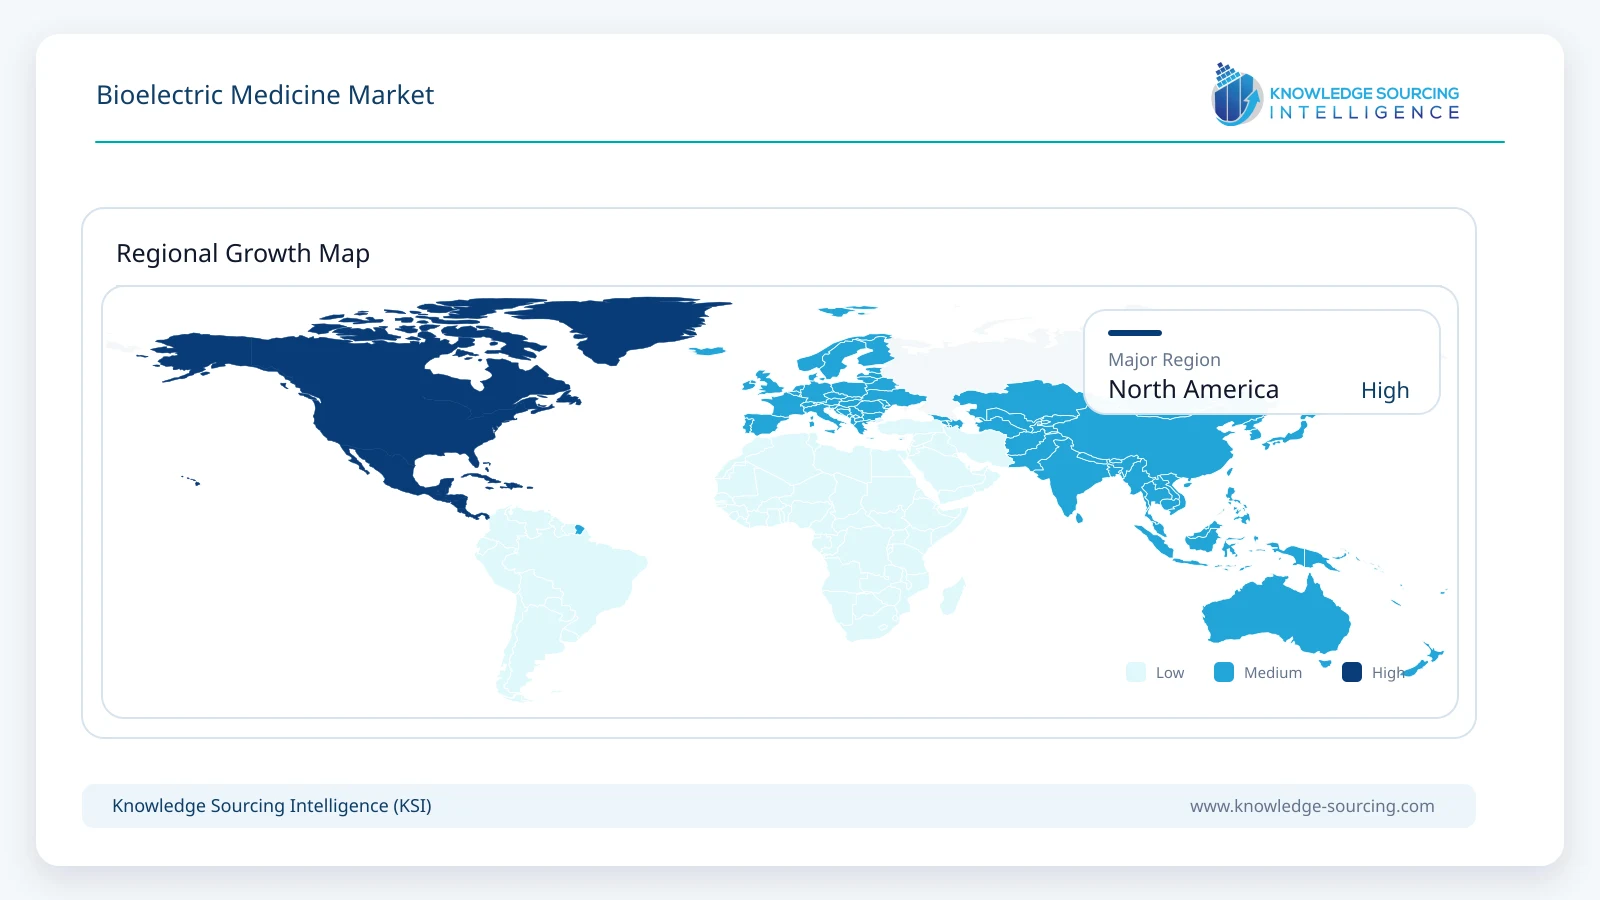
Asia Pacific has the widest variation in commercial conditions. Japan has an established market for implantable medical technologies, while China combines a large patient base with domestic medical-device development and hospital investment. India, South Korea, Indonesia, and Thailand offer additional demand potential, but access depends heavily on specialist availability, reimbursement, procedure affordability, and local hospital capability. Suppliers seeking wider regional penetration must therefore balance premium technology with price and service requirements.
South America remains concentrated around countries with stronger tertiary-care infrastructure, particularly Brazil and Argentina. Imported devices account for an important part of the supply base, making currency movements, import costs, regulatory approvals, and hospital purchasing budgets relevant to supplier economics. Market expansion is likely to remain concentrated in specialist hospitals and private healthcare networks before reaching broader patient populations.
The Middle East and Africa present a mixed opportunity. Saudi Arabia, the UAE, and Israel have developed specialist healthcare capabilities and continue to invest in medical infrastructure, while several African and lower-income Middle Eastern markets face shortages of trained specialists and limited access to complex implant procedures. These differences make distributor networks, clinical training, after-sales support, and government or institutional procurement important factors in regional expansion.
Competitive Landscape
The competitive structure combines large diversified medical-device companies with specialist neuromodulation firms. Medtronic, Abbott, and Boston Scientific compete across established implant categories, while LivaNova has a focused position in VNS. Cochlear addresses implantable hearing solutions, and BIOTRONIK participates in cardiac rhythm management.
Specialists such as Nevro, electroCore, NeuroPace, and SetPoint Medical compete through narrower technologies and indications. Competitive differentiation is shifting toward sensing, software, clinical evidence, battery performance, MRI access, non-invasive delivery, and disease-specific outcomes. NeuroPace's FDA-approved ECoG Assistant and Medtronic's closed-loop SCS illustrate the increasing role of data and adaptive stimulation in product differentiation.
Recent Developments
May 2026: NeuroPace received FDA approval for ECoG Assistant, an AI-enabled clinician feature for its RNS System. The development extends the role of intracranial EEG data from therapy delivery toward clinical review and treatment decision support.
April 2026: Bioness Medical acquired the PoNS System product line, expanding from functional electrical stimulation into non-invasive central neuromodulation for gait and balance disorders after neurological injury or disease.
January 2026: Resonetics agreed to acquire Resolution Medical, adding design and manufacturing capabilities for complex devices across neuromodulation, structural heart and interventional cardiology, broadening its bioelectronics manufacturing capabilities substantially.
January 2026: LivaNova's higher Medicare reimbursement for VNS Therapy procedures for drug-resistant epilepsy became effective in the United States. The change increased hospital outpatient payment levels and reduced a reimbursement barrier that had affected procedure economics.
July 2025: SetPoint Medical received FDA approval for its implantable vagus nerve stimulation system for adults with moderately to severely active rheumatoid arthritis after inadequate response or intolerance to specified drug therapies. The approval expands bioelectric medicine into autoimmune disease and creates a new commercial indication for vagus nerve stimulation.
Regulatory and Policy Environment
Regulatory requirements remain central to commercial entry because many bioelectric devices are implanted, interact directly with neural or cardiac tissue, and may remain in the body for years. In the United States, Class III devices generally require FDA premarket approval based on scientific evidence demonstrating safety and effectiveness. FDA's device classification database identifies implanted neuromuscular stimulators as Class III, while individual spinal, deep brain, and incontinence stimulation systems continue to receive detailed PMA supplements covering manufacturing, materials, components, and process changes.
European regulation places active implantable devices in Class III, creating high evidence and conformity requirements before commercialization. The framework also increases the importance of clinical evaluation, technical documentation, quality management, and post-market evidence. Manufacturers targeting Europe must therefore plan regulatory work alongside product development rather than treat approval as a final commercial step.
The United Kingdom strengthened post-market surveillance from June 2025. The rules cover active implantable devices and require manufacturers to monitor safety and performance, report serious incidents, identify trends, and take corrective action. The UK government is also developing further medical-device reforms, including additional pre-market requirements. These measures increase compliance costs but also make lifecycle safety data more important for market access and supplier credibility.
Outlook and Strategic Implications
The 2026-2031 period should favor bioelectric therapies that combine established clinical indications with better control of stimulation, lower procedure burden, stronger evidence, and clearer reimbursement. Established categories such as pacemakers, defibrillators, spinal cord stimulators, deep brain stimulators, VNS systems, sacral nerve stimulators, and cochlear implants will remain the commercial foundation. Newer applications will face a higher evidence threshold because clinical adoption depends on proving outcomes that justify a device-based intervention.
Closed-loop stimulation, neural sensing, software-assisted programming, and non-invasive delivery are likely to receive greater development attention. The commercial value of these technologies will depend on whether they reduce adverse stimulation, improve treatment response, simplify follow-up, or lower the total cost of care. NeuroPace's ECoG Assistant and Medtronic's closed-loop SCS show how data processing is becoming part of the product proposition rather than a separate support function.
For manufacturers, the main strategic priorities are clinical evidence, reimbursement support, manufacturing reliability, regulatory readiness, and differentiation at the level of therapy outcomes. Suppliers that can combine durable hardware with sensing, software, remote support, and disease-specific clinical evidence should be better positioned to defend pricing. For hospitals and healthcare systems, purchasing decisions will increasingly depend on total treatment economics rather than device price alone. For investors and technology providers, the most commercially relevant opportunities are likely to emerge where large disease populations intersect with inadequate treatment response, measurable clinical outcomes, and a regulatory pathway that supports broader adoption.
Bioelectric Medicine Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 20.15 billion |
| Total Market Size in 2031 | USD 28.77 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 7.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Application, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
BY PRODUCT TYPE
Cardiac Pacemakers
Implantable Cardioverter Defibrillators
Spinal Cord Stimulators
Deep Brain Stimulators
Vagus Nerve Stimulators
Cochlear Implants
Sacral Nerve Stimulators
Peripheral Nerve Stimulators
Transcutaneous Electrical Nerve Stimulation Devices
Other Bioelectronic Devices
BY APPLICATION
Arrhythmia
Pain Management
Epilepsy
Depression
Parkinson's Disease
Essential Tremor
Sensorineural Hearing Loss
Urinary and Fecal Incontinence
Paralysis and Spinal Cord Injury
Rheumatoid Arthritis and Autoimmune Disorders
Migraine
Other Neurological and Chronic Conditions
BY END-USER
Hospitals
Ambulatory Surgical Centers
Specialty Clinics
Rehabilitation Centers
Research and Academic Institutions
Home Healthcare Settings
Others
BY GEOGRAPHY
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
Japan
China
India
South Korea
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Force Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. BIOELECTRONIC MEDICINE MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Cardiac Pacemakers
5.3. Implantable Cardioverter Defibrillators
5.4. Spinal Cord Stimulators
5.5. Deep Brain Stimulators
5.6. Vagus Nerve Stimulators
5.7. Cochlear Implants
5.8. Sacral Nerve Stimulators
5.9. Peripheral Nerve Stimulators
5.10. Transcutaneous Electrical Nerve Stimulation Devices
5.11. Other Bioelectronic Devices
6. BIOELECTRONIC MEDICINE MARKET BY APPLICATION
6.1. Introduction
6.2. Arrhythmia
6.3. Pain Management
6.4. Epilepsy
6.5. Depression
6.6. Parkinson's Disease
6.7. Essential Tremor
6.8. Sensorineural Hearing Loss
6.9. Urinary and Fecal Incontinence
6.10. Paralysis and Spinal Cord Injury
6.11. Rheumatoid Arthritis and Autoimmune Disorders
6.12. Migraine
6.13. Other Neurological and Chronic Conditions
7. BIOELECTRONIC MEDICINE MARKET BY END-USER
7.1. Introduction
7.2. Hospitals
7.3. Ambulatory Surgical Centers
7.4. Specialty Clinics
7.5. Rehabilitation Centers
7.6. Research and Academic Institutions
7.7. Home Healthcare Settings
7.8. Others
8. BIOELECTRONIC MEDICINE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Spain
8.4.5. Others
8.5. The Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Israel
8.5.4. Others
8.6. Asia Pacific
8.6.1. Japan
8.6.2. China
8.6.3. India
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
10. COMPANY PROFILES
10.1. Medtronic plc
10.2. Abbott Laboratories
10.3. Boston Scientific Corporation
10.4. LivaNova PLC
10.5. Cochlear Limited
10.6. BIOTRONIK SE & Co. KG
10.7. Nevro Corp.
10.8. electroCore, Inc.
10.9. NeuroPace, Inc.
10.10. SetPoint Medical
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size and growth rate for bioelectric medicine?
The Bioelectric Medicine Market is forecast to reach $28.77 billion by 2031, growing at 7.4% CAGR.
What are the primary drivers of the Bioelectric Medicine Market growth?
Expanding neuromodulation demand and rising chronic disease burden are key drivers.
Which therapeutic areas drive demand in bioelectric medicine?
Cardiovascular, pain management, neurological, and hearing loss are key therapeutic areas.
What emerging technology trend is influencing the market?
Closed-loop stimulation and non-invasive therapies are key future market trends.
Which established therapies define the Bioelectric Medicine Market?
Pacemakers, ICDs, spinal cord, deep brain, and vagus nerve stimulators are key.
What factors influence the adoption of implantable bioelectric therapies?
Reimbursement, clinical evidence, and safety increasingly influence adoption.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Bioelectric Medicine Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/bioelectric-medicine-market