
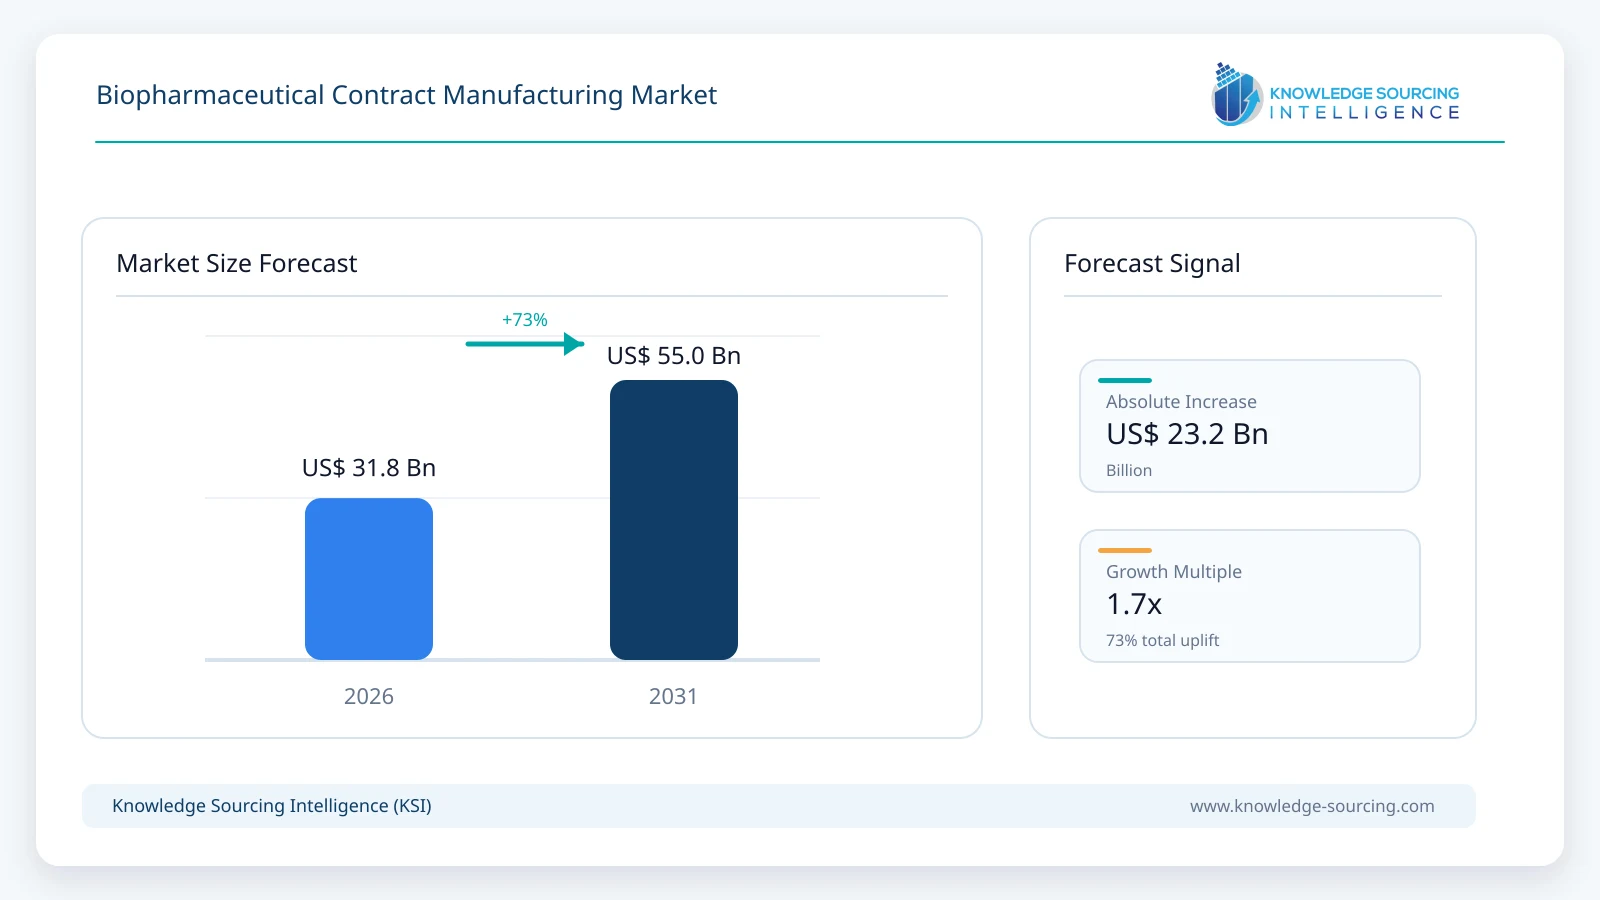
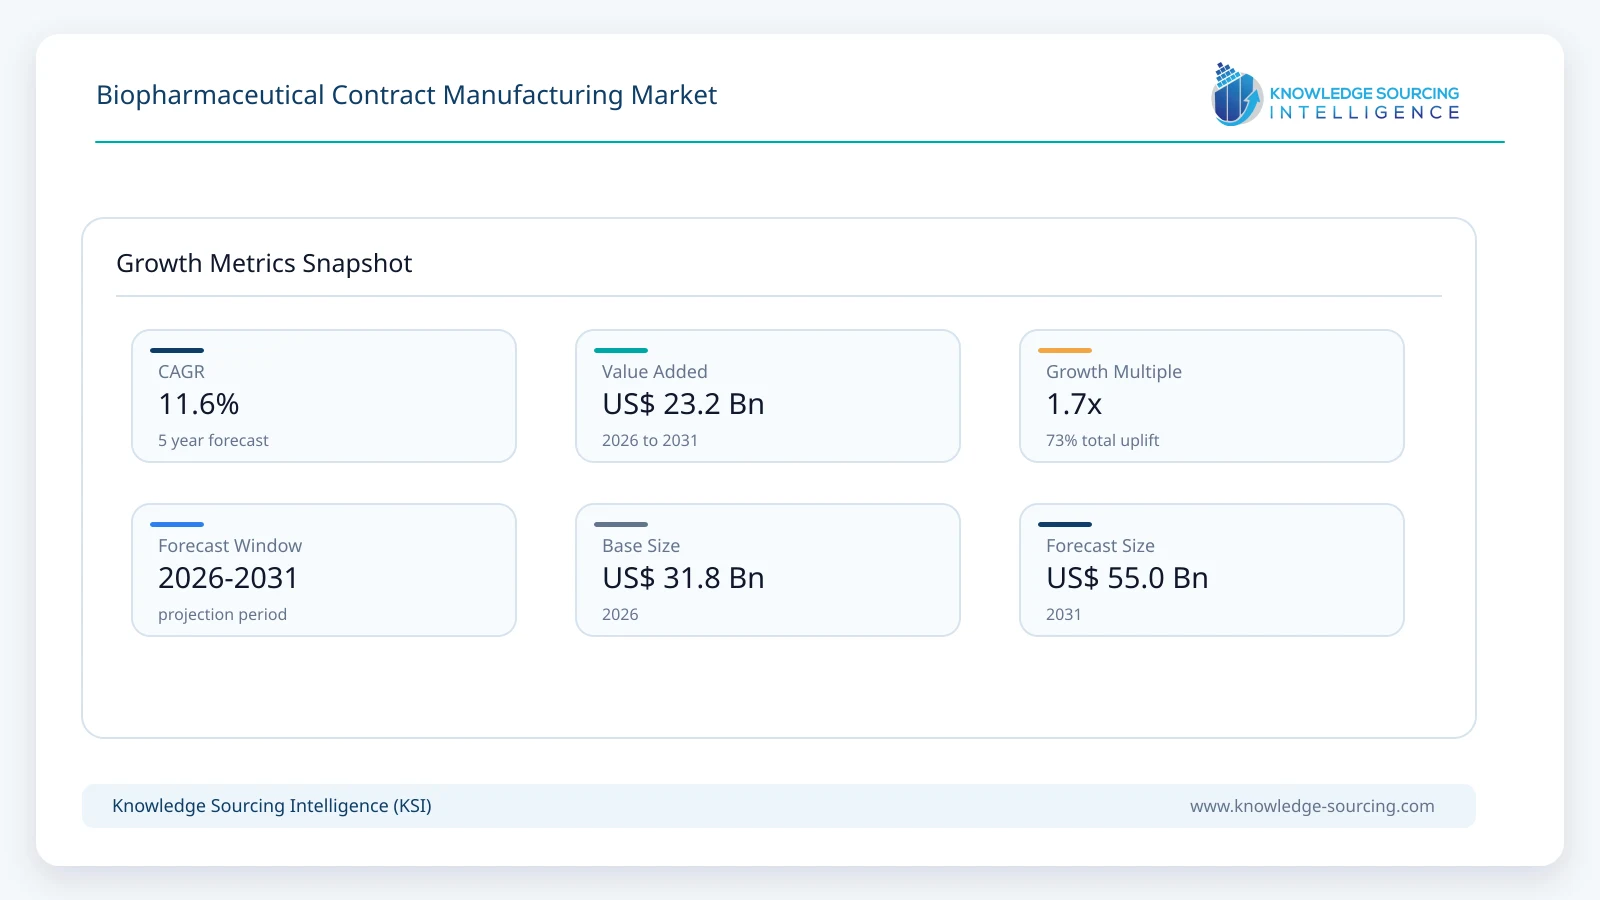
The global biopharmaceutical contract manufacturing market is forecast to grow from USD 31.8 billion in 2026 to USD 55.0 billion in 2031, representing a CAGR of 11.6% during the forecast period.
Highlights:
- 1July 2026Lonza expanded a strategic collaboration with a leading U.S. biopharmaceutical company, adding two commercial biologics programs with options for two more. The multi-site relationship has the potential to generate multi-billion cumulative Swiss-franc contract value.
- 2July 2026FUJIFILM Biotechnologies’ Holly Springs, North Carolina facility was selected for the FDA PreCheck Pilot Program, and the company said it would accelerate expansion at the site as demand for U.S. manufacturing increases.
- 3July 2026AGC Biologics announced a commercial manufacturing agreement for its Yokohama site worth hundreds of millions of dollars, strengthening its mammalian manufacturing position in Asia.
- 4March 2026:Samsung Biologics completed the acquisition of a biologics manufacturing facility in Rockville, Maryland, adding 60,000 liters of drug-substance capacity and establishing its first U.S. manufacturing site.
- 5March 2026:WuXi Biologics reported record 2025 results, including 209 new integrated projects, 74 late-stage programs, 25 commercial projects and 34 process-performance-qualification campaigns scheduled for 2026.
- 6March 2026:Rentschler Biopharma reported that the newest manufacturing line at its Milford, Massachusetts site was fully operational, completing the company’s largest expansion and increasing U.S. clinical-to-commercial capacity.
Key Highlights
• Mammalian-cell manufacturing is estimated to account for approximately 78.0% of global contract manufacturing revenue in 2026.
• Innovator biologics are estimated to represent approximately 84.0% of 2026 revenue, reflecting the scale of commercial monoclonal antibodies and complex proteins.
• Drug-substance manufacturing is estimated to generate approximately 57.0% of 2026 market revenue, making it the largest service segment.
• Commercial manufacturing is estimated to account for approximately 71.0% of 2026 revenue as approved biologics require recurring, validated supply.
• Oncology is estimated to represent approximately 37.0% of 2026 contract manufacturing revenue, supported by antibodies, bispecifics and ADC-related programs.
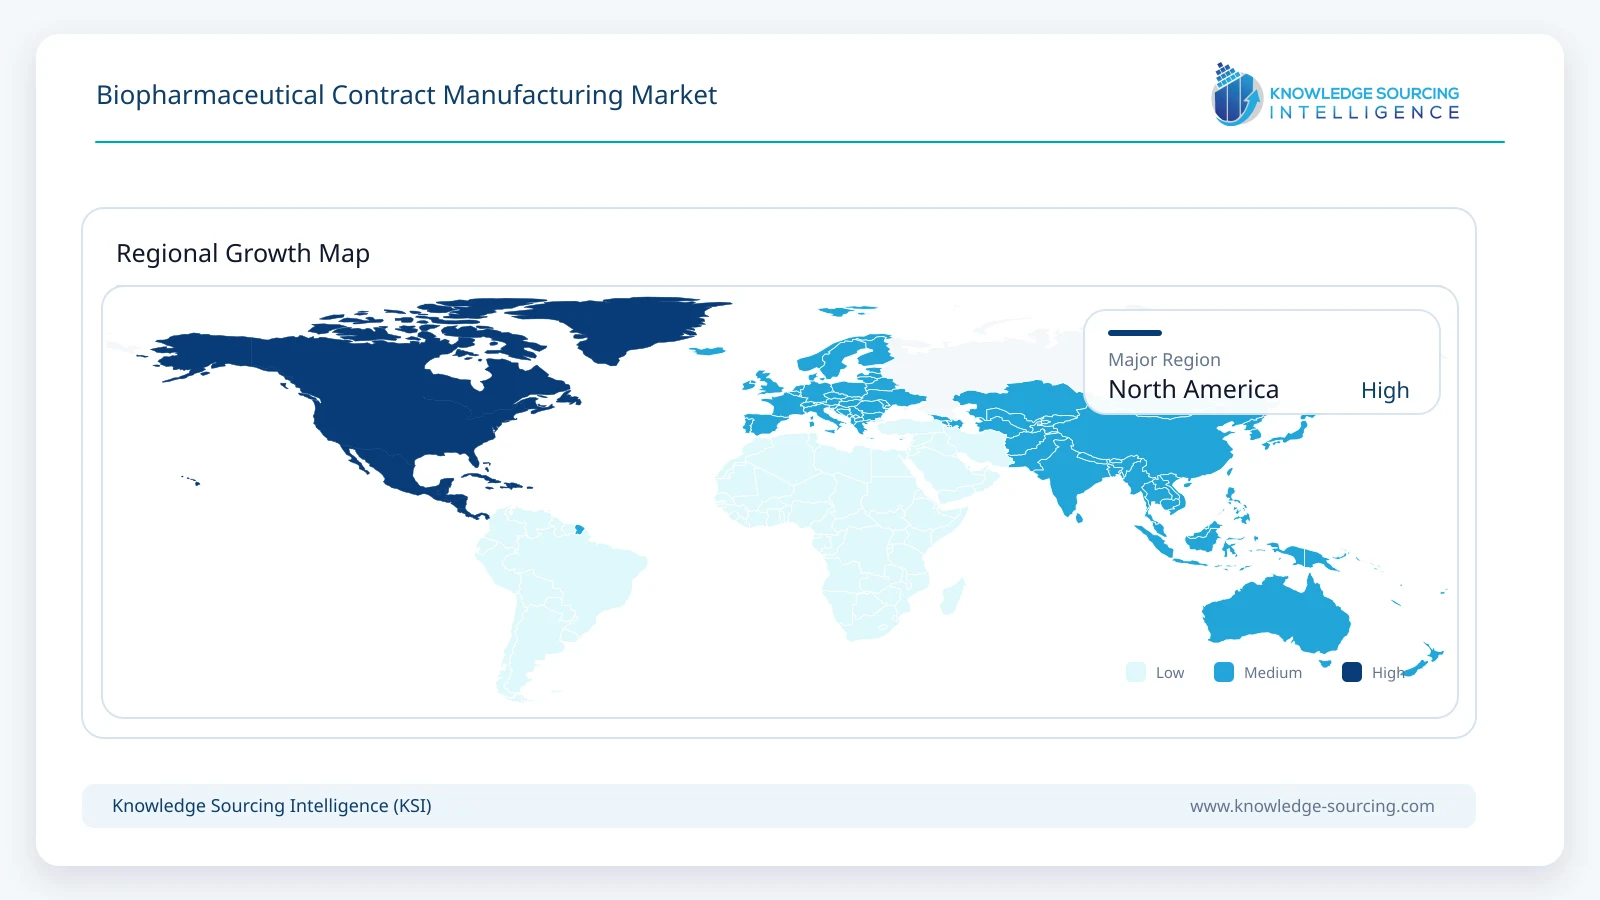
• North America is estimated to account for approximately 40.0% of global revenue in 2026, supported by concentrated biopharma R&D and commercial demand.
Market Overview
Biopharmaceutical contract manufacturing covers outsourced development and GMP manufacturing services used to produce biologic drug substance and drug product for biotechnology and pharmaceutical companies. The market includes monoclonal antibodies, recombinant proteins, vaccines, biosimilars, antibody-derived molecules and selected advanced biologic modalities produced through mammalian or microbial expression systems. It includes process development, technology transfer, clinical and commercial drug-substance manufacturing, sterile fill-finish, analytical and quality-control services, and packaging activities directly linked to contracted biologic production.
The market excludes small-molecule API manufacturing, stand-alone discovery research, laboratory instruments, raw materials and in-house biopharmaceutical manufacturing performed entirely within a drug sponsor’s own facilities. Dedicated autologous cell-therapy manufacturing is treated separately where the production model is materially different from conventional large-molecule biomanufacturing. This boundary keeps the market focused on outsourced biologic production and the services required to move programs from process development through commercial supply.
Current supplier disclosures demonstrate the scale of outsourced biologics manufacturing. Lonza reported CHF 3.649 billion of 2025 Integrated Biologics revenue, while Samsung Biologics reported KRW 4.557 trillion of 2025 revenue. WuXi Biologics generated RMB 21.8 billion of 2025 revenue across its integrated biologics platform, including RMB 9.46 billion from late-stage and commercial manufacturing activities. FUJIFILM reported JPY 257.2 billion of Bio CDMO revenue for FY2025, reflecting the increasing contribution of new large-scale facilities. These suppliers represent only part of a broader market that also includes Thermo Fisher Scientific, Boehringer Ingelheim, Catalent, AGC Biologics, KBI Biopharma, Rentschler Biopharma and other regional specialists.
Demand is shifting toward larger, longer and more integrated outsourcing relationships. Biopharma companies increasingly seek manufacturing partners that can retain a program from cell-line and process development through validation, commercial drug substance and sterile drug product. Lonza stated that mammalian and drug-product CDMO market segments are expected to grow at low- to mid-teen rates over the next five years, while WuXi Biologics reported 74 Phase III and 25 commercial programs at the end of 2025. Long-term capacity reservations and multi-program agreements are becoming more important as sponsors seek to secure validated supply while limiting the capital required for owned manufacturing networks.
Biopharmaceutical Contract Manufacturing Market Trends
Large-Scale Mammalian Capacity Continues to Expand
Commercial monoclonal antibodies and other recombinant proteins require large-scale, highly controlled cell-culture manufacturing. Leading CDMOs are therefore expanding mammalian capacity in major pharmaceutical regions. Samsung Biologics brought Plant 5 to CGMP readiness in 2025 and completed the acquisition of a 60,000-liter facility in Rockville, Maryland in March 2026, increasing its global drug-substance capacity to 845,000 liters. Lonza commenced commercial operation of a new large-scale mammalian asset in Visp during the first half of 2026.
Capacity growth is increasingly tied to customer contracts rather than purely speculative builds. FUJIFILM secured a manufacturing agreement worth more than USD 3 billion with Regeneron in 2025 and continued to ramp large-scale capacity in Denmark and North Carolina. This model provides better visibility for both sponsors and CDMOs because capacity is supported by multi-year demand commitments and validated technology transfers.
Complex Biologics Increase the Value of Process Expertise
The biologics pipeline is moving beyond conventional monospecific antibodies toward bispecifics, multispecifics, antibody-drug conjugates, fusion proteins and high-concentration formulations. These products can require more demanding cell-line, purification, analytical and drug-product processes than established antibodies. WuXi Biologics reported that bispecifics and ADCs represented two-thirds of its new integrated projects in 2025, while bi- and multispecific programs contributed nearly 20% of total revenue and grew by more than 120% year over year.
Complexity favors CDMOs that can integrate development and manufacturing because process choices made early in a program affect scale-up, comparability, formulation, fill-finish and regulatory filings. Providers are investing in process intensification, continuous manufacturing, high-concentration formulation and bioconjugation to differentiate beyond simple bioreactor capacity.
Geographic Diversification Becomes a Supply-Resilience Requirement
Biopharmaceutical sponsors increasingly value manufacturing networks that can support supply from more than one region. The objective is not simply lower cost; geographic diversification helps reduce exposure to single-site disruptions, trade barriers, logistics delays and geopolitical risk. Samsung Biologics’ U.S. expansion, FUJIFILM’s large North Carolina investment and Lonza’s multi-site mammalian network illustrate this shift.
North America, Europe and Asia Pacific are all adding capacity, but the strategic emphasis is moving toward globally replicated processes and standardized quality systems. CDMOs able to transfer a process between qualified sites can provide continuity while keeping production close to major commercial markets.
Integrated Drug Substance and Fill-Finish Services Gain Importance
Sponsors increasingly prefer to reduce the number of handoffs between drug-substance production and sterile drug-product manufacturing. Integrated models lower technology-transfer complexity and can shorten release and supply timelines. Samsung Biologics is expanding drug-product capabilities, Lonza is investing in commercial-scale aseptic capacity, KBI Biopharma works with fill-finish partners to provide end-to-end programs, and AGC Biologics expanded U.S. fill-finish access through a strategic partnership in 2026.
This integration is particularly important for high-value biologics that require controlled cold-chain handling, complex formulations, prefilled syringes or lyophilization. Drug-product capability is therefore becoming a more important criterion in CDMO selection, especially for late-stage and commercial programs.
Market Segmentation by Source
Mammalian
Mammalian-cell contract manufacturing is estimated at approximately USD 24.80 billion in 2026. The segment is the largest source category because monoclonal antibodies, Fc-fusion proteins, many bispecific antibodies and other complex glycoproteins depend on mammalian expression systems, primarily CHO-based production.
The segment benefits from a large installed commercial base and continuing pipeline growth. Samsung Biologics operates one of the world’s largest mammalian manufacturing networks, while Lonza, WuXi Biologics, FUJIFILM Biotechnologies, Thermo Fisher Scientific, Boehringer Ingelheim, Rentschler Biopharma, KBI Biopharma and AGC Biologics maintain clinical or commercial mammalian capabilities. Investment is increasingly directed toward flexible single-use systems for smaller-volume programs and larger stainless-steel or intensified platforms for high-volume commercial supply.
Demand is also broadening beyond conventional antibodies. Bispecifics, fusion proteins, antibody-drug conjugate intermediates and higher-concentration biologics require specialized development and purification strategies, supporting higher-value contracts and deeper technical relationships between sponsors and manufacturing partners.
Market Segmentation by Product Type
Innovator Biologics
Innovator biologics are estimated at approximately USD 26.71 billion in 2026. The segment includes original monoclonal antibodies, recombinant proteins, vaccines and other proprietary biologic therapies manufactured under contract for clinical development and commercial supply.
Innovator programs dominate outsourced value because they frequently require customized process development, analytical methods, technology transfer and regulatory support in addition to manufacturing capacity. Complex molecules can remain with the same CDMO for many years as they progress from early clinical batches to process performance qualification and recurring commercial production.
The continued expansion of biologics pipelines and the increasing number of complex modalities support long-duration outsourcing relationships. Large pharmaceutical companies use CDMOs to supplement internal networks, while emerging biotechnology companies often rely on outsourced manufacturing as their primary route to clinical and commercial supply.
Market Segmentation by Service
Drug Substance Manufacturing
Drug-substance manufacturing is estimated at approximately USD 18.13 billion in 2026. The segment covers upstream cell culture or fermentation, harvest, purification, bulk drug-substance handling and associated GMP operations required to produce the active biologic before sterile filling.
The segment carries high value because commercial drug-substance manufacturing requires validated processes, substantial capital equipment, quality systems and regulatory inspection readiness. Large-scale mammalian contracts can extend across multiple years and require dedicated or reserved capacity, particularly for high-volume antibodies and biologics with growing indications.
Process intensification is becoming an important competitive factor. CDMOs are seeking higher titers, shorter cycle times and greater output from existing footprints through intensified fed-batch, perfusion and continuous processing. These improvements can lower cost per gram while increasing the flexibility of manufacturing networks.
Market Segmentation by Scale of Operation
Commercial Operation
Commercial manufacturing is estimated at approximately USD 22.58 billion in 2026. The segment includes routine GMP production for approved biologics, process performance qualification support, lifecycle changes and recurring drug-substance or drug-product supply under commercial agreements.
Commercial programs generate the largest revenue pool because validated supply continues for multiple years and often expands as products gain indications or geographic approvals. Samsung Biologics reported full utilization across Plants 1 through 4 in early 2026, while WuXi Biologics ended 2025 with 25 commercial manufacturing projects and 34 PPQs scheduled for 2026. Lonza is also expanding multi-program collaborations that can generate multi-billion-franc cumulative contract value.
Once a process is approved at a manufacturing site, switching suppliers can be costly and time-consuming because sponsors must manage comparability, regulatory filings and supply continuity. This creates high retention for well-performing CDMOs and makes quality, delivery reliability and inspection history critical commercial differentiators.
Market Segmentation by Therapeutic Area
Oncology
Oncology-related contract manufacturing is estimated at approximately USD 11.77 billion in 2026. Cancer remains the largest therapeutic-area value pool because of the extensive commercial and clinical pipeline for monoclonal antibodies, bispecifics, checkpoint inhibitors, targeted proteins and antibody-drug conjugates.
The oncology pipeline also contains a high concentration of technically complex molecules, increasing demand for specialized cell-line development, high-productivity processes, advanced purification, conjugation and sterile drug-product capabilities. CDMOs that combine biologics and bioconjugation services are particularly well positioned as ADC pipelines progress toward late-stage development and commercial supply.
Commercial expansion of established oncology biologics, new indications and combination regimens supports recurring manufacturing volume, while emerging biotech pipelines provide a continuous source of clinical programs. This combination of commercial scale and innovation keeps oncology central to outsourced biopharmaceutical production.
Market Drivers
Growth of the Global Biologics Pipeline
The number and complexity of biologics programs continue to increase across antibodies, recombinant proteins and advanced antibody formats. Lonza reported that the biologics clinical pipeline has historically grown by about 9% annually over the last decade. A larger pipeline creates demand for cell-line development, process development, clinical batches, validation and commercial manufacturing.
Outsourcing is particularly important for emerging biotechnology companies that do not own large GMP facilities. These companies can preserve capital by using CDMOs while retaining the ability to scale programs as clinical evidence improves.
Capital Preservation and Flexible Capacity Access
Biologics facilities require substantial investment, long construction timelines and specialized operating teams. Outsourcing allows sponsors to access existing capacity without committing to fixed assets before product demand is proven. This is valuable both for early-stage biotech companies and for large pharmaceutical companies managing portfolio volatility.
Flexible CDMO capacity also helps sponsors manage product launches, indication expansion and demand uncertainty. Contracts can combine dedicated suites, reserved capacity and multi-product facilities depending on the scale and risk profile of a program.
Rising Demand for Complex and High-Value Modalities
Bispecific antibodies, ADCs, high-concentration biologics and other next-generation modalities require specialized process and analytical capabilities. The technical burden increases the value of experienced manufacturing partners and supports higher service intensity per program.
CDMOs are responding by investing in bioconjugation, process intensification, continuous manufacturing and advanced formulation. These capabilities allow providers to retain programs across more stages of the development and manufacturing lifecycle.
Need for Supply Resilience and Geographic Redundancy
The biopharmaceutical industry is reducing dependence on single-site manufacturing strategies. Sponsors increasingly evaluate whether CDMOs can provide alternative sites, regional proximity and robust business-continuity arrangements. Geographic redundancy can reduce exposure to logistics disruptions, regulatory delays and geopolitical events.
The trend is supporting new U.S. capacity as well as continued investment in Europe and Asia. Samsung Biologics’ Rockville acquisition and FUJIFILM’s North Carolina investment are examples of major Asian-headquartered groups building capacity closer to North American customers.
Increasing Outsourcing by Large Pharmaceutical Companies
Outsourcing is no longer limited to small biotechnology firms. Large pharmaceutical companies use external manufacturing to supplement internal networks, access specialized technologies and avoid overbuilding capacity for changing portfolios. Long-term agreements can cover multiple molecules, development stages and manufacturing sites.
Lonza’s July 2026 expansion of a strategic collaboration with a leading U.S. biopharmaceutical company illustrates this model, adding commercial biologics programs and options for additional molecules under a broader multi-site relationship.
Market Restraints
High Regulatory and Quality Requirements
Biopharmaceutical manufacturing is subject to stringent GMP, validation, data-integrity and regulatory requirements. Quality events can delay clinical programs, interrupt commercial supply and require expensive remediation. Sponsors therefore place substantial weight on inspection history, deviation management and quality culture when selecting manufacturing partners.
As CDMOs manage more products and complex facilities, maintaining consistent quality across sites becomes more difficult. Regulatory inspections and remediation can temporarily reduce usable capacity, as recent industry experience has shown.
Long Technology-Transfer and Validation Timelines
Moving a biologic process between facilities requires detailed technology transfer, engineering runs, analytical comparability and regulatory documentation. Late-stage transfers can take many months and may create supply risk if the receiving site has not previously handled similar processes.
This makes manufacturing relationships relatively sticky but also creates a barrier for sponsors seeking to change suppliers. CDMOs must demonstrate reliable scale-up and transfer processes to win late-stage programs from competitors or sponsor-owned sites.
Capacity Mismatch Across Molecules and Scales
The industry can experience simultaneous shortages and underutilization because capacity is not fully interchangeable. A 20,000-liter commercial antibody process cannot simply move into a small single-use suite, while low-volume complex biologics may be uneconomic in very large stainless-steel facilities.
CDMOs therefore need a portfolio of scales and technologies. Incorrect capacity mix can reduce utilization and profitability even when overall biologics demand remains strong.
Pricing Pressure and Customer Concentration
Large pharmaceutical customers can negotiate aggressively on long-term manufacturing contracts, particularly when multiple CDMOs have qualified capacity. At the same time, major commercial products can represent a meaningful share of a facility’s revenue, increasing exposure if a molecule loses demand or a sponsor changes its network strategy.
Providers are responding by broadening customer portfolios, increasing integration and differentiating through technology, speed and reliability rather than competing only on price.
Skilled Workforce and Operational Complexity
Biologics facilities require experienced personnel across upstream processing, downstream purification, analytical development, aseptic operations, quality control, engineering and regulatory compliance. Rapid capacity expansion can create hiring and training bottlenecks, particularly in new manufacturing clusters.
Automation and digital manufacturing can improve consistency, but they do not eliminate the need for experienced technical teams. Workforce availability therefore remains an important constraint on how quickly new capacity can reach efficient commercial operation.
Regional Outlook
North America
North America is estimated at approximately USD 12.72 billion in 2026. The region contains the world’s largest concentration of biotechnology funding, clinical development activity and high-value biologics commercialization, supporting demand for both domestic and global CDMO capacity.
The United States is the core regional market. Thermo Fisher Scientific, Catalent, KBI Biopharma, AGC Biologics, Rentschler Biopharma, Abzena, Just-Evotec Biologics and other providers operate biologics facilities in the country, while global groups are increasing their U.S. manufacturing presence. Samsung Biologics completed its Rockville acquisition in March 2026, and FUJIFILM is ramping a major large-scale campus in Holly Springs, North Carolina.
Regional demand is also supported by the preference of many sponsors to maintain domestic or near-market supply for critical medicines. U.S. policy attention to pharmaceutical manufacturing resilience and the FDA’s manufacturing initiatives reinforce the strategic value of local capacity, although cost and workforce constraints can be higher than in some Asian markets.
Competitive Landscape
The market combines very large global platforms with specialized biologics CDMOs. Lonza, Samsung Biologics, WuXi Biologics, FUJIFILM Biotechnologies and Thermo Fisher Scientific operate broad development and manufacturing networks, while Boehringer Ingelheim combines internal biopharmaceutical expertise with third-party contract manufacturing. AGC Biologics, Rentschler Biopharma, KBI Biopharma, Catalent and other specialists compete through targeted capabilities, flexible scales and customer service.
Scale is important but does not determine competitiveness by itself. Sponsors evaluate technical fit, inspection history, technology-transfer execution, capacity availability, project management and supply reliability. Smaller CDMOs can compete successfully when they offer specialized expertise or more flexible operating models for early-stage and complex products.
Competition is increasingly moving toward integrated platforms. Drug-substance manufacturers are adding sterile fill-finish, analytical and formulation capabilities, while drug-product specialists seek earlier involvement in development programs. Providers are also differentiating through continuous processing, proprietary cell lines, intensified manufacturing, digital quality systems and geographically diversified production networks.
Recent Developments
Market Outlook
Biopharmaceutical contract manufacturing is expected to remain one of the faster-growing segments of pharmaceutical outsourcing through 2031. Growth is supported by a larger biologics pipeline, increasing molecule complexity, greater use of external capacity and the need for geographically resilient manufacturing networks. Commercial mammalian production will remain the largest value pool, while integrated drug-substance and drug-product services gain strategic importance.
Capacity expansion is likely to remain concentrated among providers that can secure long-term customer commitments and demonstrate consistent regulatory performance. Large new facilities can take several years to reach efficient utilization, so operating execution will be as important as announced bioreactor capacity. CDMOs with diversified scale, strong process development and multiple qualified sites are positioned to manage changing product demand more effectively.
By 2031, competition is expected to center increasingly on end-to-end program ownership, faster technology transfer, intensified processing, complex biologics capability and supply resilience. The market is forecast to add approximately USD 23.2 billion in annual revenue between 2026 and 2031 as outsourcing becomes more deeply embedded in the biopharmaceutical manufacturing model.
Biopharmaceutical Contract Manufacturing Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 31.8 billion |
| Total Market Size in 2031 | USD 55.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 11.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Source, Product Type, Service, Scale of Operation, Therapeutic Area, Geography |
| Companies |
|
Market Segmentation
By Source
Mammalian
Non-mammalian
By Product Type
Innovator Biologics
Biosimilars
By Service
Drug Substance Manufacturing
Process Development
Fill & Finish Operations
Analytical and Quality Control Studies
Packaging and Labeling
By Scale of Operation
Commercial Operation
Clinical Operations
By Therapeutic Area
Oncology
Autoimmune Diseases
Metabolic Diseases
Cardiovascular Diseases
Neurology
Infectious Diseases
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Switzerland
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Singapore
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Major Market Opportunities
3.4. Segment and Regional Summary
3.5. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Growth of the Global Biologics Pipeline
4.1.2. Capital Preservation and Flexible Capacity Access
4.1.3. Rising Demand for Complex and High-Value Modalities
4.1.4. Need for Supply Resilience and Geographic Redundancy
4.1.5. Increasing Outsourcing by Large Pharmaceutical Companies
4.2. Market Restraints
4.2.1. High Regulatory and Quality Requirements
4.2.2. Long Technology-Transfer and Validation Timelines
4.2.3. Capacity Mismatch Across Molecules and Scales
4.2.4. Pricing Pressure and Customer Concentration
4.2.5. Skilled Workforce and Operational Complexity
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Capacity and Technology Trends
5. BIOPHARMACEUTICAL CONTRACT MANUFACTURING MARKET BY SOURCE
5.1. Introduction
5.2. Mammalian
5.3. Non-mammalian
6. BIOPHARMACEUTICAL CONTRACT MANUFACTURING MARKET BY PRODUCT TYPE
6.1. Introduction
6.2. Innovator Biologics
6.3. Biosimilars
7. BIOPHARMACEUTICAL CONTRACT MANUFACTURING MARKET BY SERVICE
7.1. Introduction
7.2. Drug Substance Manufacturing
7.3. Process Development
7.4. Fill & Finish Operations
7.5. Analytical and Quality Control Studies
7.6. Packaging and Labeling
8. BIOPHARMACEUTICAL CONTRACT MANUFACTURING MARKET BY SCALE OF OPERATION
8.1. Introduction
8.2. Commercial Operation
8.3. Clinical Operations
9. BIOPHARMACEUTICAL CONTRACT MANUFACTURING MARKET BY THERAPEUTIC AREA
9.1. Introduction
9.2. Oncology
9.3. Autoimmune Diseases
9.4. Metabolic Diseases
9.5. Cardiovascular Diseases
9.6. Neurology
9.7. Infectious Diseases
9.8. Others
10. BIOPHARMACEUTICAL CONTRACT MANUFACTURING MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. United States
10.2.2. Canada
10.2.3. Mexico
10.3. South America
10.3.1. Brazil
10.3.2. Argentina
10.3.3. Others
10.4. Europe
10.4.1. United Kingdom
10.4.2. Germany
10.4.3. France
10.4.4. Switzerland
10.4.5. Italy
10.4.6. Spain
10.4.7. Others
10.5. Middle East and Africa
10.5.1. Saudi Arabia
10.5.2. UAE
10.5.3. Others
10.6. Asia Pacific
10.6.1. China
10.6.2. Japan
10.6.3. India
10.6.4. South Korea
10.6.5. Singapore
10.6.6. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Capacity and Technology Positioning
11.3. Contracting and Partnership Models
11.4. Market Share Analysis
11.5. Mergers, Acquisitions and Capacity Expansion
11.6. Competitive Dashboard
12. COMPANY PROFILES
12.1. Lonza Group AG
12.2. Samsung Biologics Co., Ltd.
12.3. WuXi Biologics (Cayman) Inc.
12.4. FUJIFILM Biotechnologies
12.5. Thermo Fisher Scientific Inc. / Patheon
12.6. Boehringer Ingelheim GmbH
12.7. AGC Biologics
12.8. Catalent, Inc.
12.9. Rentschler Biopharma SE
12.10. KBI Biopharma, Inc.
12.11. Ajinomoto Bio-Pharma Services
12.12. Recipharm AB
12.13. Abzena
12.14. Just - Evotec Biologics
12.15. Curia Global, Inc.
13. APPENDIX
Navigate
Trusted by the world's leading organizations











