
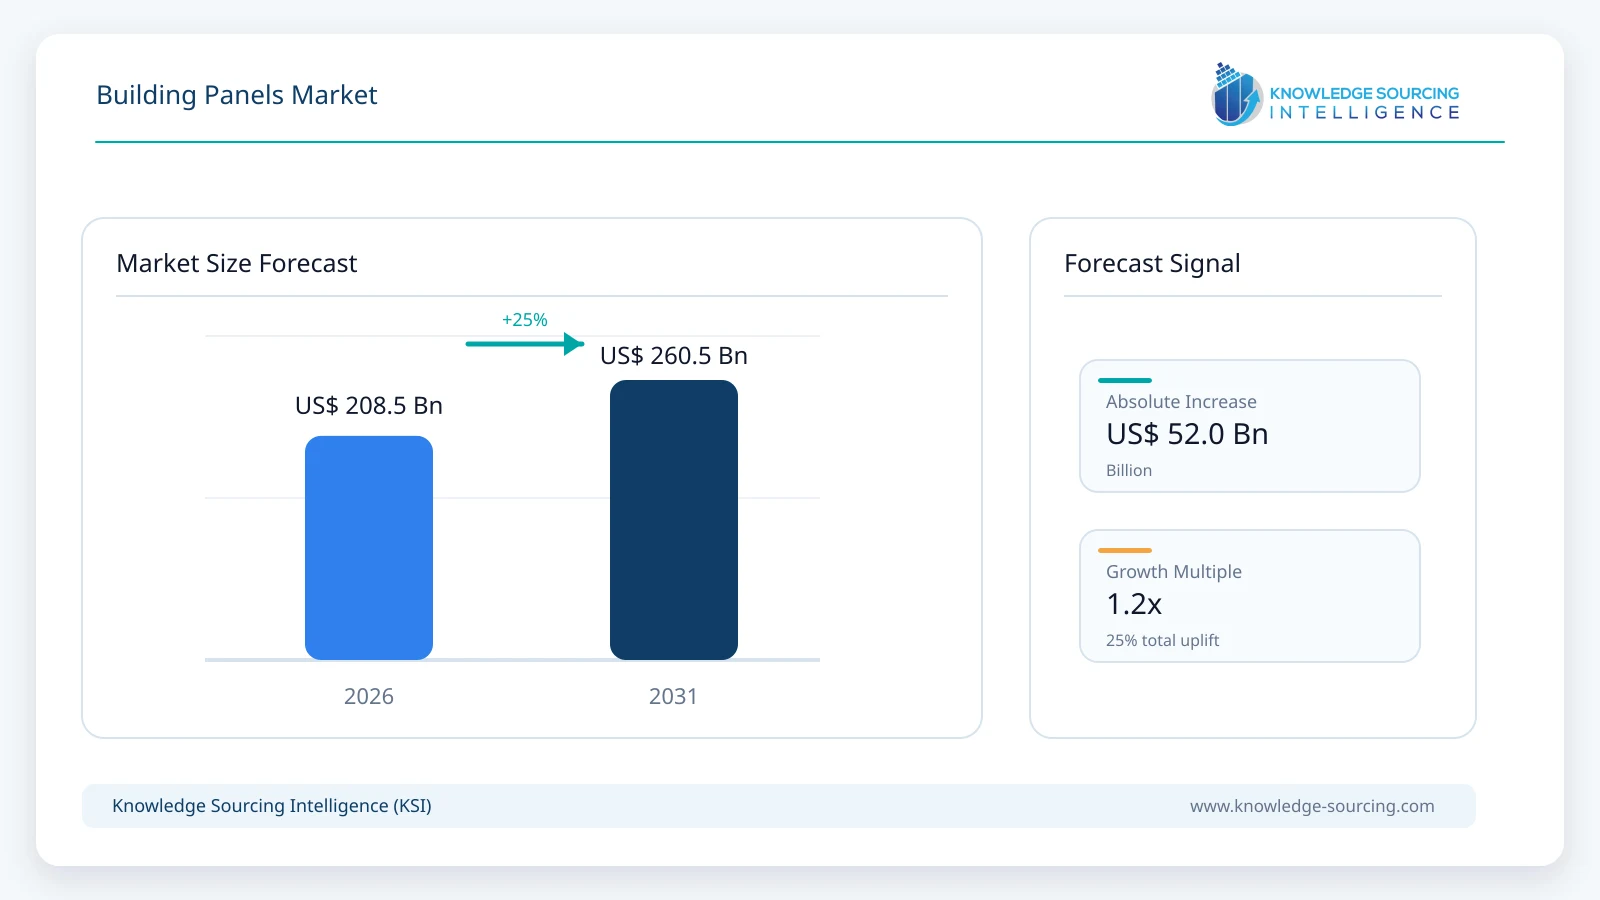
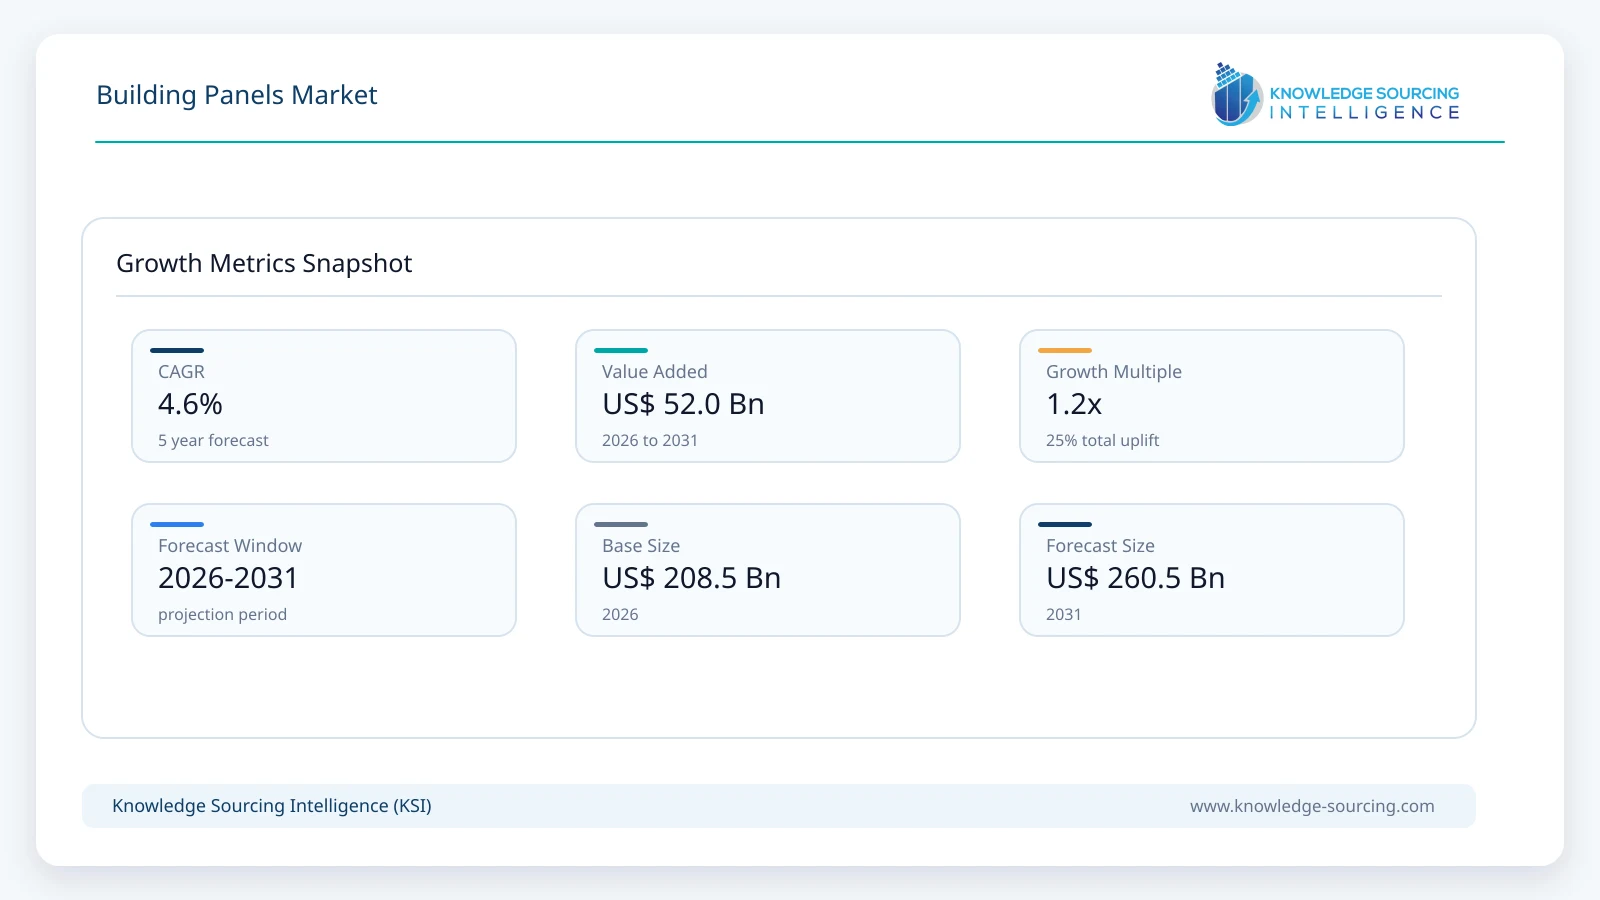
The global building panels market is forecast to grow from USD 208.5 billion in 2026 to USD 260.5 billion in 2031, representing a CAGR of 4.6% during the forecast period.
Highlights:
- 1Wood-based structural panels are estimated to account for approximately 56.0% of global building panel revenue in 2026 because OSB, plywood and other structural wood panels are used extensively in residential and light-commercial construction.
- 2Wall panels are estimated to represent approximately 45.0% of 2026 market revenue, spanning structural wood sheathing, insulated metal wall panels, structural insulated panels and other factory-made wall systems.
- 3Residential construction is estimated to account for approximately 51.0% of global market revenue in 2026, reflecting the large volume of wood-based structural panels used in housing and renovation.
- 4Asia Pacific is estimated to account for approximately 43.0% of global market revenue in 2026, supported by construction volumes, regional wood-panel production and expanding industrial use of insulated panel systems.
- 5Energy efficiency and construction labor shortages are increasing adoption of factory-made insulated panels because they combine enclosure, insulation and exterior/interior surfaces in a faster installation process.
- 6Fire performance, embodied carbon and integrated energy functions are becoming more important product differentiators, with 2026 launches spanning new insulated metal wall-panel designs and façade systems.
Market Overview
The building panels market covers factory-manufactured panel products used as structural, enclosure or insulated elements in building construction. The scope includes construction-grade wood structural panels such as oriented strand board and plywood, insulated metal and sandwich panels, structural insulated panels, selected vacuum and advanced insulation panels, and other prefabricated wall, roof and floor panel systems.
The market excludes gypsum wallboard, glass façade units, standalone insulation boards sold without a panel assembly, conventional bricks or blocks, precast concrete structural systems not sold as panelized building products, and furniture-grade wood panels used primarily outside construction. This boundary preserves the large structural wood-panel market while keeping the analysis focused on products that function as building panels.
The competitive landscape spans two distinct but increasingly connected groups. Wood-products manufacturers such as West Fraser, Weyerhaeuser and LP Building Solutions serve high-volume structural sheathing and engineered-wood demand. Insulated-envelope specialists such as Kingspan, Nucor, ArcelorMittal Construction, Isopan, Metecno and Ruukki serve commercial, industrial, logistics, cold-storage and high-performance building applications.
Energy codes and construction productivity are increasing the value of higher-performance panel systems. Kingspan reported EUR 7.54 billion of 2025 revenue in its Insulated Building Envelopes segment, with 2026 year-to-date panel order intake ahead of the prior year. Nucor operates nine insulated metal panel manufacturing facilities in the United States and Canada under the CENTRIA and Metl-Span brands, demonstrating the scale of the North American commercial and industrial panel market.
The market is not uniform across panel technologies. Wood structural panels are highly exposed to housing starts, repair and remodeling and timber economics, while insulated sandwich panels are more closely linked to industrial, logistics, cold-chain, data-center and commercial construction. The combined market therefore grows at a moderate rate even though advanced insulated-panel subcategories can expand faster.
Market Trends
Insulated Panels Gain Share in Commercial and Industrial Envelopes
Insulated metal and sandwich panels combine exterior skin, insulation and interior liner in one factory-made product, reducing on-site assembly and improving thermal continuity. Warehouses, cold storage, factories, logistics facilities and data centers increasingly use these systems to shorten construction schedules.
Kingspan, Nucor, Isopan, Metecno and Ruukki continue to invest in panel capacity and new products, supporting gradual penetration beyond traditional industrial applications.
Fire Performance Drives Core-Material and Certification Decisions
Building owners and insurers increasingly specify tested fire performance for façade and roof systems. Mineral-wool cores are gaining importance in higher-risk applications, while PIR systems continue to compete through thermal efficiency and improved fire-rated formulations.
Certification such as FM Approvals and national fire classifications is becoming a commercial requirement in logistics, energy, cold-chain and critical-infrastructure projects rather than only a technical differentiator.
Panels Integrate Energy and Building-Envelope Functions
Roof and wall panels are increasingly designed as platforms for solar, daylighting and low-carbon envelope solutions. Kingspan launched PowerPanel 2.0 by integrating photovoltaic capability with its insulated panel system and planned wider European rollout during 2026.
Integrated products can reduce installation interfaces and help building owners combine envelope upgrades with energy generation, supporting higher value per square meter even in mature construction markets.
Aesthetics and Architectural Profiles Expand Beyond Industrial Buildings
Insulated panels are increasingly being designed for visible architectural façades rather than only utilitarian industrial buildings. Kingspan introduced KingRib wall insulated metal panels in North America in January 2026, and Ruukki launched the Grid15 three-dimensional surface profile for sandwich panels in September 2026.
Improved finishes, concealed fastening and three-dimensional profiles support adoption in offices, commercial facilities and public buildings where appearance is as important as thermal performance.
Segment Analysis
By Panel Type - Wood-Based Structural Panels
Wood-based structural panels are estimated at approximately USD 116.76 billion in 2026. The segment includes construction-grade OSB, plywood and related structural wood panels used in walls, roofs, floors and sheathing applications.
This is the largest market segment because wood-frame housing and light-commercial construction consume very high panel volumes in North America, Europe and parts of Asia Pacific. Demand is cyclical with housing activity but supported by repair, remodeling and engineered-wood substitution.
By Application - Wall Panels
Wall-panel applications are estimated at approximately USD 93.83 billion in 2026. The segment spans structural wood sheathing, insulated metal wall panels, structural insulated wall panels and other factory-made enclosure systems.
Wall applications lead because almost every building requires extensive vertical enclosure area. Higher-performance energy codes also increase the value of insulated wall systems in commercial and industrial projects.
By End Use - Residential
Residential construction is estimated at approximately USD 106.34 billion in 2026. Housing consumes large quantities of OSB, plywood and structural panels for walls, roofs and floors, particularly in timber-frame markets.
Repair and remodeling provide an additional demand base that can offset weaker new housing starts. Prefabricated and panelized housing systems also support gradual adoption of higher-value structural insulated panels.
By Geography - Asia Pacific
Asia Pacific is estimated at approximately USD 89.66 billion in 2026. China, Japan, India, South Korea, Southeast Asia and Australia collectively represent large construction markets and major production bases for wood and metal panel products.
Industrial construction, logistics infrastructure, cold storage and energy-efficient building standards are supporting growth in insulated panels, while regional wood-panel production serves both domestic and export markets.
Market Drivers
Energy-Efficiency Requirements
Building codes increasingly require lower thermal transmittance and reduced air leakage. Factory-made insulated panels can provide continuous insulation and controlled joints while simplifying the number of envelope layers installed on site.
This supports higher-value panel systems in commercial, industrial and renovation applications, particularly in Europe and other regulation-intensive markets.
Construction Labor and Schedule Pressure
Panelized construction shifts work from the jobsite into factories, reducing the number of separate trades needed for walls and roofs. Large-format panels can enclose buildings quickly and create weather-tight structures earlier in the project schedule.
Labor shortages and higher site wages therefore improve the economic case for prefabricated envelope systems even when the material cost is higher than conventional assemblies.
Industrial, Logistics and Cold-Chain Expansion
Warehouses, food-processing facilities, cold stores and logistics centers require large wall and roof areas with predictable thermal and hygienic performance. Insulated metal panels are well suited to these requirements.
Data-center and advanced manufacturing construction also creates demand for high-performance, rapidly installed envelope systems.
Residential Repair and Engineered-Wood Demand
Wood-based structural panels benefit from housing construction, repair and remodeling and the continued use of timber-frame building systems. OSB and plywood remain essential sheathing products in major residential markets.
Engineered wood can also support lower-weight and more material-efficient construction compared with some traditional structural approaches.
Market Restraints
Construction Cyclicality
Building-panel demand is exposed to interest rates, housing starts, commercial development and industrial capital spending. New construction can slow rapidly when financing conditions weaken.
Large manufacturers therefore rely on geographic diversification, renovation demand and multiple end-use sectors to reduce volatility.
Raw-Material Price Volatility
Wood panels are sensitive to timber, resin and energy costs, while insulated metal panels depend on steel, aluminum and polymer or mineral-wool insulation inputs. Rapid raw-material movements can affect pricing and margins.
Project-based customers may delay purchases or switch specifications when panel prices change materially.
Fire and Building-Code Compliance
Panel assemblies must satisfy structural, fire, thermal, moisture and wind requirements that differ by jurisdiction and building type. Façade fire safety has become especially important for insulated panels and exterior systems.
Certification and testing increase product-development costs but are necessary for access to high-value commercial and critical-infrastructure projects.
Competition from Conventional Construction Systems
Building panels compete with masonry, built-up walls and roofs, precast concrete, curtain wall and site-installed insulation systems. Contractors may prefer familiar methods where labor is inexpensive or where panel logistics are difficult.
Panel adoption is strongest when speed, energy performance, quality control and lifecycle benefits outweigh material-price premiums.
Regional Outlook
Asia Pacific
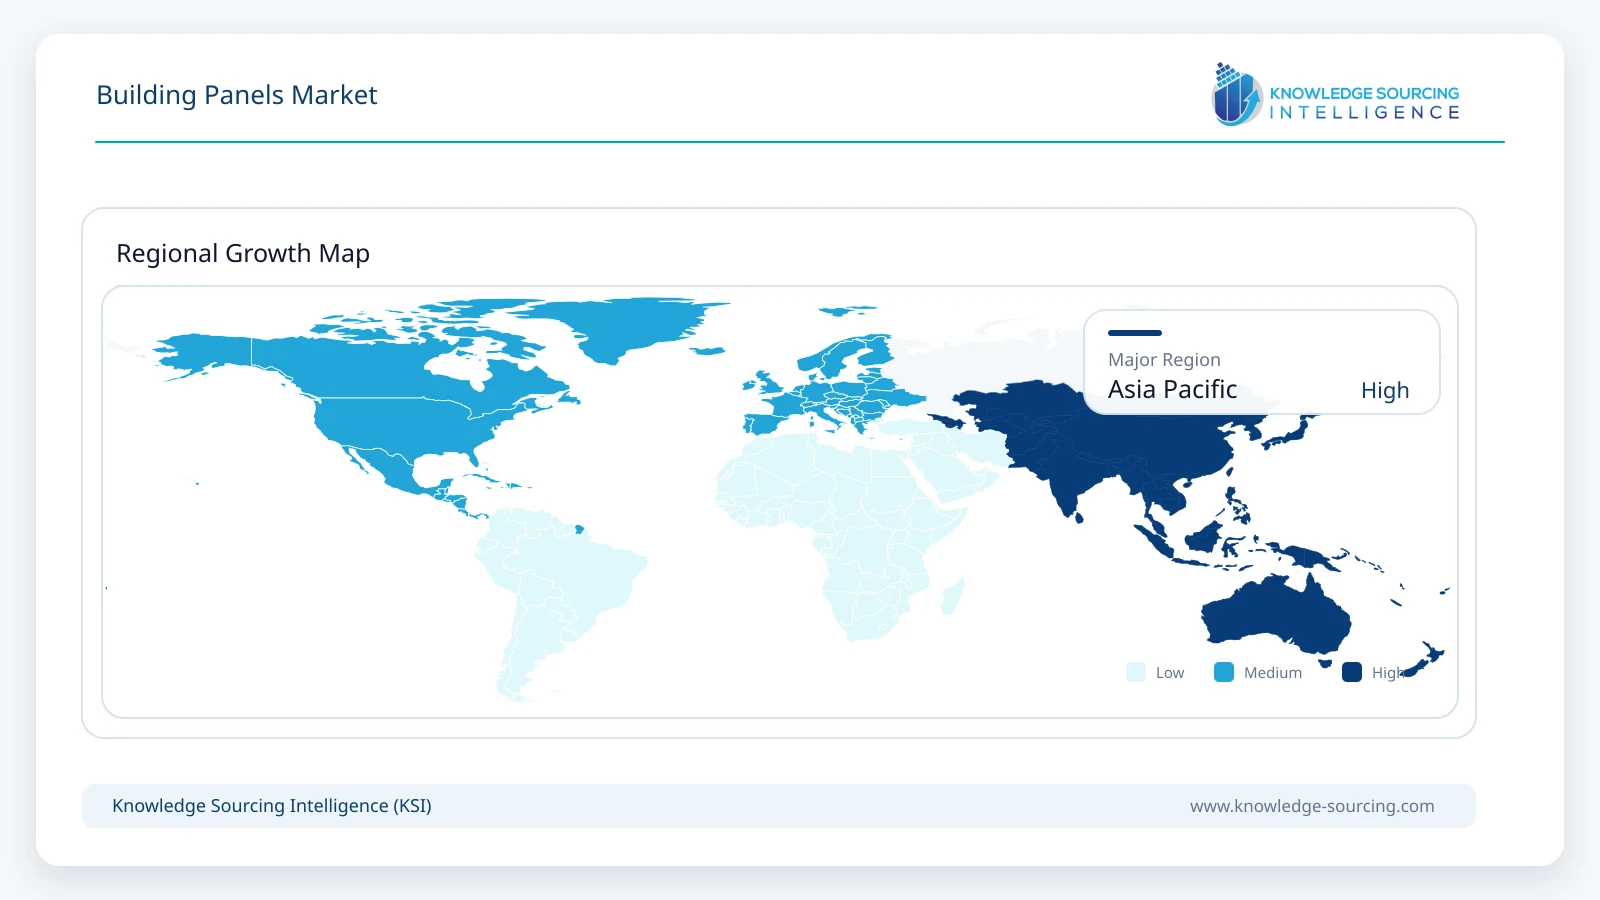
Asia Pacific is the largest regional market because of construction volume, wood-panel manufacturing and rapid industrial development. China remains a major producer, while India and Southeast Asia are expanding warehousing, cold-chain and manufacturing capacity.
Japan, South Korea and Australia maintain strong demand for high-performance building envelopes and engineered wood products.
North America
North America is a major structural wood-panel market because of timber-frame residential construction and is also one of the largest insulated metal panel markets. Nucor operates nine IMP plants in the United States and Canada, while Kingspan continues to expand regional capacity.
Data centers, cold storage, logistics, manufacturing and multifamily construction are important non-residential demand sources.
Europe
Europe has a dense insulated-panel supplier base and stringent building-energy requirements. Kingspan, ArcelorMittal Construction, Isopan, Metecno, Ruukki, BRUCHA and other producers compete across wall, roof and façade applications.
Renovation and embodied-carbon requirements are becoming increasingly important alongside traditional new construction.
Middle East and Africa
Gulf markets use insulated panels extensively in industrial, logistics, cold-chain and commercial buildings because high cooling loads make thermal performance economically important.
African demand is more fragmented but is supported by cold storage, food processing, warehouses and prefabricated construction.
South America
Brazil and other major markets support demand from industrial construction, logistics, food processing and commercial buildings. Local steel and insulation input costs influence project economics.
Insulated panel systems are attractive where rapid installation and temperature control are critical.
Competitive Environment
The market is fragmented across wood-products companies and insulated-envelope specialists. West Fraser, Weyerhaeuser and LP Building Solutions have large positions in structural wood panels, while Kingspan, Nucor, ArcelorMittal Construction, Isopan, Metecno and Ruukki compete in insulated metal and sandwich panels.
The insulated-panel market is becoming more consolidated and international. Kingspan has expanded manufacturing across multiple regions, Nucor has built a large North American platform around CENTRIA and Metl-Span, and Isopan operates internationally through the Manni Group and Marcegaglia joint venture structure. Regional manufacturers remain important because panel transport costs favor local production.
Competitive differentiation includes thermal performance, fire certification, coating durability, structural span, aesthetics, product availability and technical support. Large suppliers increasingly sell complete envelope systems rather than individual panel products, allowing them to bundle roofs, walls, insulation and related accessories.
Recent Developments
September 2026: Ruukki Construction introduced the Grid15 three-dimensional façade profile for its SPA sandwich panels, expanding architectural design options for insulated panel systems.
January 2026: Kingspan Insulated Panels North America launched KingRib Wall insulated metal panels for commercial wall applications.
2026: Kingspan began wider rollout of PowerPanel 2.0, integrating photovoltaic generation with its QuadCore insulated panel platform after initial launch in Ireland and Britain.
2025-2026: Kingspan expanded panel manufacturing with new or recently completed facilities in the United States, Germany, Australia, New Zealand and Paraguay.
2025-2026: Isopan continued expanding certified PIR and mineral-wool sandwich-panel offerings across Europe and international markets, including FM Approved panel ranges for higher-risk applications.
Market Outlook
The building panels market is expected to grow at a moderate pace through 2031, with faster value growth in insulated and higher-performance systems than in commodity structural panels. Energy standards, labor productivity and industrial construction support gradual substitution toward factory-made envelope products, while wood-based panels remain tied to residential construction and renovation cycles.
Future competitive advantage will depend on combining thermal and fire performance with lower embodied carbon, faster installation, architectural flexibility and integrated functions such as solar generation. Manufacturing footprint will remain important because panels are bulky products and local supply improves lead times and project economics.
Building Panels Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 208.5 billion |
| Total Market Size in 2031 | USD 260.5 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Panel Type, Application, End Use, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Panel Type
Wood-Based Structural Panels
Oriented Strand Board
Structural Plywood
Other Construction Wood Panels
Insulated Metal and Sandwich Panels
PIR/PUR Core Panels
Mineral-Wool Core Panels
Structural Insulated Panels
Vacuum and Advanced Insulation Panels
Others
By Application
Wall Panels
Roof Panels
Floor and Other Panels
By End Use
Residential
Commercial and Industrial
Institutional and Infrastructure
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency and Study Period
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Major Product and Application Trends
3.4. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Energy-Efficiency Requirements
4.1.2. Construction Labor and Schedule Pressure
4.1.3. Industrial, Logistics and Cold-Chain Expansion
4.1.4. Residential Repair and Engineered-Wood Demand
4.2. Market Restraints
4.2.1. Construction Cyclicality
4.2.2. Raw-Material Price Volatility
4.2.3. Fire and Building-Code Compliance
4.2.4. Competition from Conventional Construction Systems
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
5. BUILDING PANELS MARKET BY PANEL TYPE
5.1. Introduction
5.2. Wood-Based Structural Panels
5.2.1. Oriented Strand Board
5.2.2. Structural Plywood
5.2.3. Other Construction Wood Panels
5.3. Insulated Metal and Sandwich Panels
5.3.1. PIR/PUR Core Panels
5.3.2. Mineral-Wool Core Panels
5.4. Structural Insulated Panels
5.5. Vacuum and Advanced Insulation Panels
5.6. Others
6. BUILDING PANELS MARKET BY APPLICATION
6.1. Introduction
6.2. Wall Panels
6.3. Roof Panels
6.4. Floor and Other Panels
7. BUILDING PANELS MARKET BY END USE
7.1. Introduction
7.2. Residential
7.3. Commercial and Industrial
7.4. Institutional and Infrastructure
8. BUILDING PANELS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. India
8.6.4. South Korea
8.6.5. Australia
8.6.6. Southeast Asia
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Structural Wood Panel Competition
9.3. Insulated Panel Competition
9.4. Fire, Thermal and Low-Carbon Product Positioning
9.5. Mergers, Acquisitions and Capacity Expansion
9.6. Competitive Dashboard
10. COMPANY PROFILES
10.1. West Fraser Timber Co. Ltd.
10.2. Weyerhaeuser Company
10.3. LP Building Solutions
10.4. Kronospan
10.5. EGGER Group
10.6. Kingspan Group plc
10.7. Nucor Corporation / CENTRIA / Metl-Span
10.8. ArcelorMittal Construction
10.9. Isopan S.p.A. / Manni Group
10.10. Metecno Group
10.11. SSAB / Ruukki Construction
10.12. Tata Steel Construction
10.13. BRUCHA Gesellschaft m.b.H.
10.14. Assan Panel
10.15. EPACK Prefab
11. APPENDIX





Frequently asked questions
What is the projected growth of the Building Panels Market?
Market forecast to reach $260.5 billion by 2031, growing at 4.6% CAGR.
Which panel type accounts for the largest market revenue?
Wood-based structural panels are estimated at 56.0% of 2026 global revenue.
Which end-use industry dominates the Building Panels Market?
Residential construction is estimated to account for 51.0% of 2026 revenue.
Which region is the largest market for building panels?
Asia Pacific is estimated to account for 43.0% of 2026 global revenue.
What key factors drive building panel market growth?
Energy efficiency and labor shortages increase factory-made insulated panel adoption.
What are becoming important building panel product differentiators?
Fire performance, embodied carbon, and integrated energy functions are key.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Building Panels Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/building-panels-market