
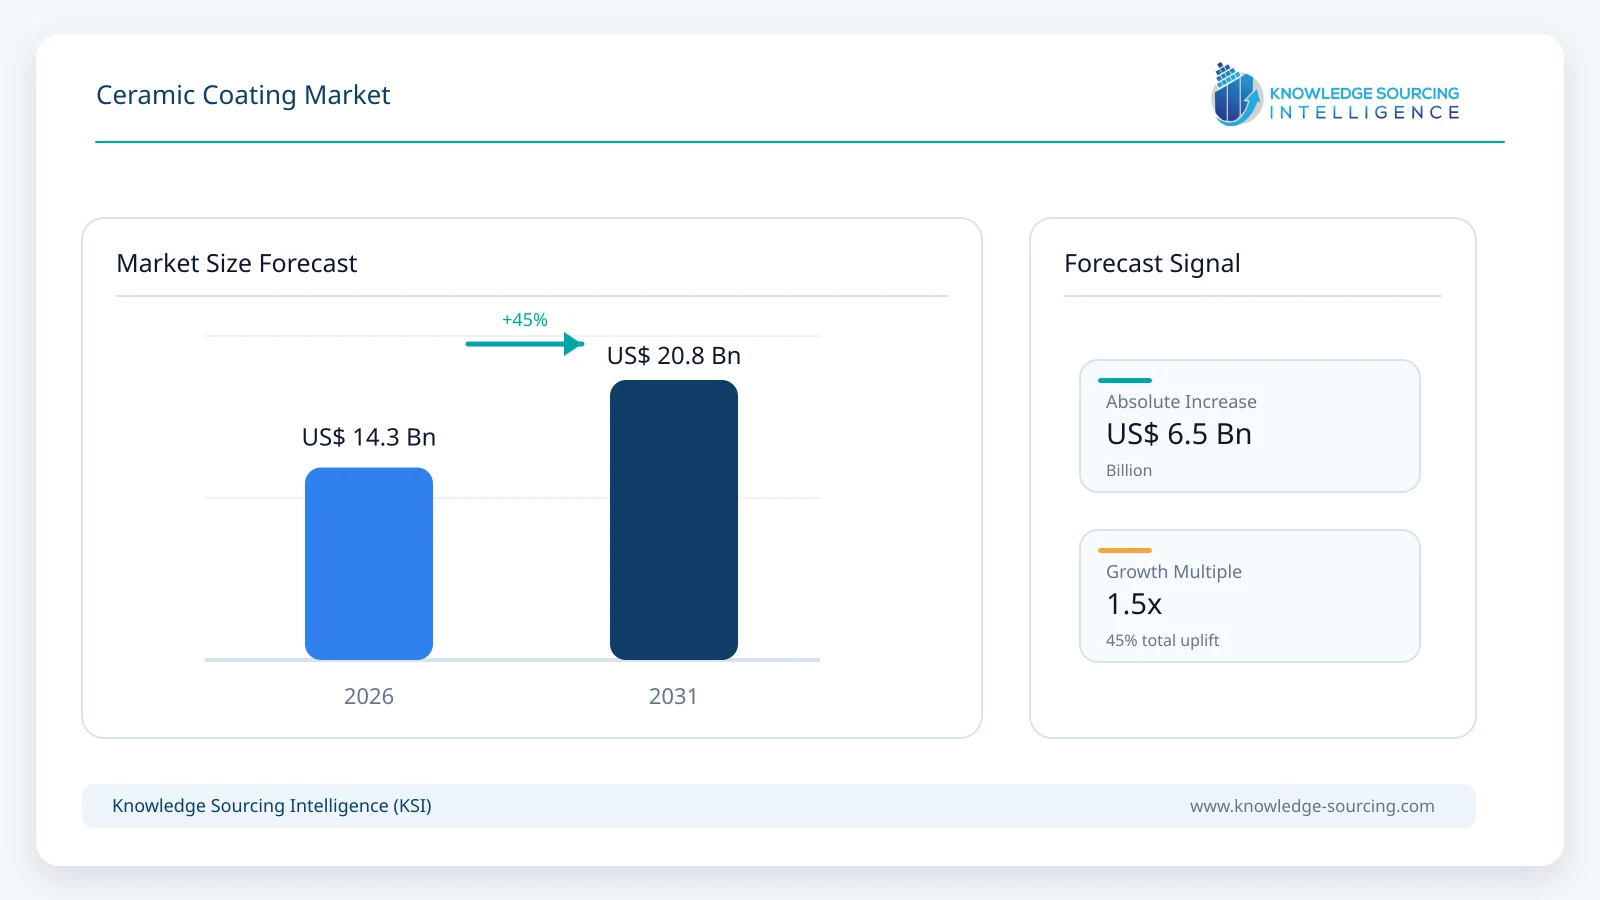
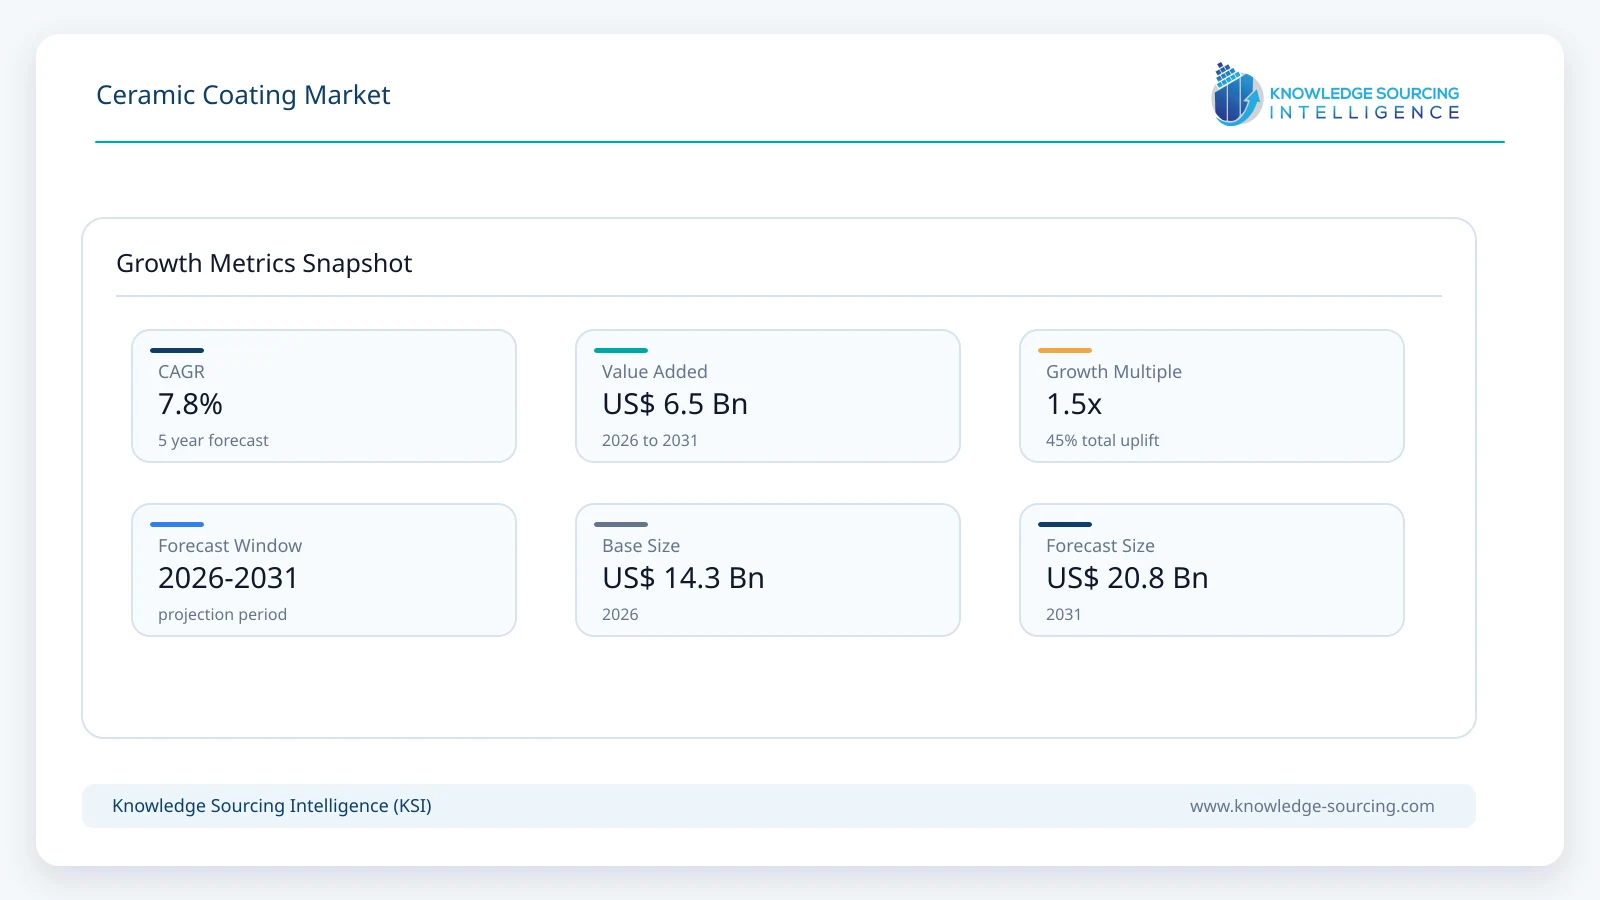
The Ceramic Coating Market is projected to grow from USD 14.3 billion in 2026 to USD 20.8 billion by 2031, at a CAGR of 7.8% across the forecast period.
Highlights:
- 1Growing demand for durable surface protection in automotive applications is driving ceramic coating adoption through enhanced scratch resistance, chemical protection, gloss retention, and easier vehicle maintenance.
- 2Increasing use of advanced coatings across aerospace, industrial machinery, and electronics is supporting demand for improved thermal stability, corrosion resistance, and long-lasting surface performance.
- 3Rising consumer preference for premium vehicle detailing is encouraging manufacturers to develop innovative formulations offering hydrophobic properties, ultraviolet protection, and superior aesthetic finishes.
- 4Continuous advancements in nanotechnology and coating application techniques are improving product durability, application efficiency, and performance across diverse commercial and industrial environments.
The global ceramic coating market is expanding beyond traditional aerospace & automotive applications, with manufacturers increasingly requiring surface enhancements that resist wear, corrosion, oxidation, and chemicals, and can withstand thermal and electrical loads. Ceramic-based coating technologies are seeing new applications from investments in semiconductors, EVs, advanced ceramics, power equipment, and specialized manufacturing.
Rapid growth in semiconductor manufacturing is giving immense potential for ceramic coating equipment and other components. According to the Semiconductor Equipment and Materials International (SEMI), semiconductor manufacturing equipment billings worldwide were US$135.1 billion in 2025, a 15% year-on-year increase.
In addition, wafer-processing equipment grew by 12%, while advanced packaging and testing also showed higher growth rates, increasing demand for plasma, chemicals, heat, and particle-contamination-resistant surfaces.
Ceramic coatings are creating a potential application area for EV–battery safety and thermal management. For instance, Zircotec launched its ElectroHold ceramic coating technology for use in EV battery enclosures and cooling plates in September 2025. The coating combines dielectric insulation, fire protection, and thermal management properties, allowing manufacturers to replace heavyweight steel structures with lighter-weight aluminium and composite materials .
The rise in EV manufacturing is offering an opportunity in the growing demand for advanced surface technologies. In June 2025, India's Ministry of Heavy Industries opened an application portal for the Scheme to Promote Manufacturing of Electric Passenger Cars in India (SPMEPCI) to draw global EV makers and strengthen domestic capabilities.
The manufacturers' focus on high-performance machining is creating opportunities for ceramic and ceramic-related coating technologies. For instance, in June 2025, Oerlikon introduced BALDIA VARIA, a CVD diamond coating specially designed for cutting tools machining CFRP, graphite, zirconia ceramics, and other materials.
Power-generation equipment is driving demand for coatings capable of operating in extreme conditions. In August 2025, India’s Ministry of Science & Technology announced the development of high-temperature protective coatings for gas turbine and boiler components operating under high pressure and high-temperature conditions. These components are susceptible to degradation mechanisms such as oxidation, corrosion, and thermo-mechanical fatigue, which can significantly reduce their component life. It also highlights the continued development of thermal-spray-based protective coating technologies for power-generation applications.
Market Drivers
Aerospace Propulsion Requirements: The pursuit of higher bypass ratios and increased combustion temperatures in jet engines necessitates ceramic matrix composites and coatings to prevent component failure, driving steady demand in the defense and commercial aviation sectors.
Decarbonization of Power Generation: As the energy sector shifts toward hydrogen-firing in gas turbines, the requirement for advanced ceramic insulators that can withstand hydrogen-induced corrosion is creating a new structural demand segment.
Semiconductor Manufacturing Expansion: The rise in global chip production requires plasma-resistant ceramic coatings for vacuum chamber components to prevent contamination, linking market growth directly to the electronics supply chain.
Stringent Emission Standards: Global mandates for reduced CO2 and NOx emissions in heavy-duty vehicles drive the adoption of ceramic thermal barriers, which improve thermodynamic efficiency within the combustion chamber.
Rising Demand for High-Performance Coatings in Automotive and Aerospace
The increase in vehicle and aircraft production, coupled with rising operating temperatures, lightweight-material adoption, and tighter durability requirements, is driving demand for ceramic and related advanced high-performance coatings that deliver thermal protection, wear resistance, corrosion protection, and extended component life.
Global aircraft production continues to be a key driver of demand. For instance, Airbus delivered 793 commercial aircraft in 2025, compared with 766 in 2024, and ended the year with an order backlog of over 8,754 aircraft, showing continued healthy demand for advanced protective coatings used on engines, turbine components, landing gear, and other highly critical parts.
Aeronautical manufacturers are becoming more focused on the efficiency and durability of specific components. At the 2025 Paris Air Show, Oerlikon presented new PVD coatings for turbine components operating under conditions of corrosion, erosion, and wear at very high temperatures, including BALORA PVD MCrAlY and BALINIT TURBINE PRO.
The rising adoption of electric vehicles demands new coating requirements. The International Energy Agency (IEA) reported that the total number of electric cars on the roads in 2025 was estimated at more than 20 million, growing at a rate of 20%/year, with EVs accounting for one in four new cars sold worldwide.
The research and development work continues to develop extreme-environment coatings. NASA's Glenn Research Center continues to provide coating-development capabilities across various fields, including thermal and environmental barrier coatings, plasma spray, thermal spray, sputtering techniques, e-beam evaporation methods, and slurry coating technologies associated with aerospace work for thermal environmental degradation and extreme operating conditions.
Market Restraints and Opportunities
High Energy Intensity of Production: The manufacturing of ceramic coatings, particularly through thermal spray and CVD, requires substantial electricity for high-temperature sintering, making the market sensitive to regional energy price fluctuations.
Technical Skill Gap: The application of advanced ceramic coatings requires specialized equipment and highly trained technicians, which can act as a bottleneck for adoption in emerging economies.
Opportunity in Healthcare Implants: The bio-inert nature of oxide ceramics presents a significant growth opportunity for coating orthopedic and dental implants to improve biocompatibility and wear resistance.
Nano-technology Innovation: The development of self-cleaning and anti-viral ceramic coatings for public infrastructure and healthcare facilities represents a high-value growth niche in the post-pandemic regulatory environment.
Raw Material And Pricing Analysis
The ceramic coating market is highly dependent on the availability of high-purity inorganic minerals, specifically alumina (Al2O3), zirconia (ZrO2), and various silicates. Alumina remains the most widely consumed raw material due to its balance of hardness and cost-effectiveness, while zirconia is prioritized for high-thermal applications. Pricing is largely dictated by the purity levels required for industrial-grade applications; for instance, "95-99% purity" alumina is a standard benchmark for the monolithic ceramics that are processed into coating powders.
Pricing dynamics are currently influenced by the high energy costs associated with the extraction and refining of these minerals. Sintering processes are energy-intensive, and as global energy prices fluctuate, manufacturers often face margin compression. Furthermore, the supply chain for rare-earth stabilizers used in zirconia coatings, such as yttria, is geographically concentrated, leading to regional pricing variations and potential supply tightness during periods of geopolitical instability. Strategic margin management in this sector typically involves long-term supply contracts and the integration of recycled ceramic waste back into the production cycle.
Supply Chain Analysis
The supply chain for ceramic coatings is characterized by high production concentration among a few specialized chemical and material science firms. The process begins with the extraction of raw ores, which are refined into sub-micron powders. These powders are then categorized by particle size and morphology, as the efficiency of technologies like High-Velocity Oxy-Fuel (HVOF) spraying is directly dependent on the flowability and melting characteristics of the feedstock.
Transportation of these materials is often subject to hazard classifications, particularly for powders that may pose respiratory risks if not handled in controlled environments. Manufacturing strategies are increasingly leaning toward "near-shoring" or integrated manufacturing, where coating facilities are located in close proximity to major automotive or aerospace hubs to minimize logistics costs and lead times. This regionalization helps mitigate the risks of global shipping disruptions but increases exposure to local regulatory changes and labor market constraints.
Government Regulations
Jurisdiction | Key Regulation / Agency | Market Impact Analysis |
Europe | REACH (EC 1907/2006) | Restricts the use of hazardous substances like hexavalent chromium, mandating the transition to safer ceramic-based surface treatments. |
United States | EPA TSCA / Section 6(g) | Phasing out certain volatile organic compounds (VOCs) and solvents used in traditional painting, accelerating demand for dry ceramic coating processes. |
Global / International | ISO 9100 / AS9100 | Standardizes quality management for aerospace coatings, ensuring high-reliability demand and creating a barrier to entry for non-certified manufacturers. |
Key Developments
April 2026: Axalta Coating Systems launched the Zencore™ Cabinet Coating System, reducing coating process steps while improving durability, throughput efficiency, and finish consistency for industrial coating applications.
February 2026: Henkel introduced Loctite Stycast UV 7998 conformal coating, a solvent-free UL 94 V-0 rated formulation designed for sustainable electronics protection and industrial coating applications.
March 2026: Corning Incorporated launched Gorilla® Glass Ceramic 3, an advanced glass ceramic material delivering improved durability and drop resistance for next-generation mobile device coating applications.
March 2025: Corning Incorporated introduced Gorilla® Glass Ceramic, a new transparent glass ceramic cover material engineered to improve toughness and drop performance for consumer electronics coatings.
Ceramic Coating Market Segmentation
By Technology
Thermal Spray
The thermal spray segment is expected to remain a major technology segment in the ceramic coatings market through 2031, supported by increasing adoption of plasma spray, high-velocity oxygen fuel (HVOF), high-velocity air fuel (HVAF), and emerging suspension and cord-based spray processes. Demand is being reinforced by aerospace, industrial gas turbines, power generation, automotive, steel processing, and other applications requiring thermal protection, wear resistance, corrosion protection, and electrical insulation.
Aerospace is accelerating the development of advanced thermal barrier and environmental barrier coatings. A 2026 strategic roadmap published in the Journal of Thermal Spray Technology recognized advanced thermal spray coatings as a technology of interest for next-generation aircraft and propulsion systems, especially for thermal barrier, oxidation-resistant bond layer, wear protection, and environmental barrier applications. The roadmap identifies coatings required for higher-temperature, lower-carbon aircraft propulsion systems.
New thermal spray technologies are being used that are going beyond the old powder-based technologies. In 2026, the International Materials Applications & Technologies Conference featured a study of the erosion performance of high-entropy zirconate ceramic topcoats applied with Suspension Plasma Spray (SPS), compared with conventional YSZ coatings. The development reveals a trend towards more sophisticated ceramic chemistries and controlled microstructures for high wear applications in aerospace and energy.
John Cockerill India launched its New Generation High-Pressure High-Velocity Air Fuel (HP-HVAF) technology-based Rolls Coating Facility at Taloja in June 2026. The plant's coatings, grinding, finishing, balancing, inspection, and quality control services are designed to help manufacturers of steel-processing rolls attain longer roll life, better steel strip quality, and minimize maintenance downtime in India and Southeast Asia.
Curtiss-Wright's expanded thermal spray capabilities are available for aerospace and industrial customers in India. In September 2026, the company announced the expansion of its Bangalore facility with plasma spray, HVOF and flame spray, as well as materials testing, analysis and engineering support. The new capabilities aim to bolster locally available advanced surface-engineering services in the aerospace, defense, power generation, automotive and industrial sectors.
Global investments in advanced thermal spray technologies are increasing as manufacturers seek to improve coating performance, component durability, and production efficiency. In 2026, developments across aerospace, steel processing, energy, and industrial applications have included the adoption of HP-HVAF, HVOF, plasma spray, and suspension plasma spray technologies, supporting the broader shift toward higher-performance and application-specific ceramic coating solutions.
Coating solutions for porosity and surface protection are new to the thermal spray market. Aremco's Ceramacoat™ 503-VFG-C is a ceramic-based, high-temperature sealant for sealing micro-porosity in thermal spray coatings. It overcomes one of the drawbacks of thermally sprayed surfaces (residual porosity) and shows the trend for complementary products that enhance the functional performance of thermal-spray systems.
Thermal spray is used not only to manufacture new components, but also to extend lifecycle and refurbish existing components. John Cockerill's Taloja facility and Curtiss-Wright's Bangalore capabilities are examples of growing investment in local coating and refurbishment facilities. These developments enable the restoration and protection of existing components by plasma spray, HVOF, and HP-HVAF processes, which can reduce part replacement and increase component service life and reliability.
By Type
Oxide Coatings
Oxide coatings, particularly those based on aluminum and chromium oxides, hold the largest share of the market by type. Their adoption is driven by exceptional chemical stability and resistance to oxidative degradation at high temperatures. In the chemical processing industry, oxide coatings are utilized to line pipes and reaction vessels that handle aggressive acids. The demand for these coatings is structurally linked to the growth of the global chemical and pharmaceutical industries, which require high-purity environments and long-lasting equipment.
By End-User
Aerospace and Defense
The aerospace and defense segment is characterized by the highest technical requirements in the market. Operational advantages in this segment include the use of ceramic coatings to enable the "lean-burn" technology required for modern fuel-efficient engines. By providing a thermal barrier, these coatings allow engines to operate at temperatures higher than the melting point of the underlying metal components, directly increasing thrust and reducing fuel consumption.
Regional Analysis
North America
North America exhibits high demand for advanced ceramic coatings, primarily supported by a robust aerospace and defense industrial base. The region is a hub for engine manufacturers who utilize ceramic matrix composites and specialized coatings to meet stringent FAA performance standards. Furthermore, the U.S. market is heavily influenced by the EPA's environmental mandates, which are driving a rapid transition toward low-VOC and chrome-free coating technologies in the automotive aftermarket and industrial sectors.
The United States ceramic coating market is projected to show significant growth fueled by continued emphasis on equipment longevity.
High industrial productivity supported by heavy capital investment in equipment and machinery has increased the demand for coating solutions offering high thermal resistance and structural durability in US sectors, which supports the need for ceramic coatings.
Regulatory standards such as EPA National Emission Standards for Hazardous Air Pollutants (NESHAP) are encouraging the transition towards sustainable and longer-lifespan-offering coatings in the United States, which is driving new market innovations.
Progressive vehicle productivity, followed by growing consumer awareness regarding protective coating benefits, has amplified the market outlook for ceramic coating in the US automotive sector. The International Organization of Motor Vehicle Manufacturers (OICA) indicates that, in Q1 2026, US total vehicle production reached 2.55 million units with nearly 2% growth.
Pioneering global defense spending, the United States allocates billions of dollars to military equipment maintenance. According to the “FY 2027 Department of War Overview Budget, the Operation & Maintenance budget stood at USD 88.864 billion for the Department of the Army, USD 110.966 billion for the Department of the Navy, and USD 102.986 billion for the Department of the Air Force.
The improved demand for high-performance coatings in industrial machinery maintenance has played a key role in driving the aftermarket demand for ceramic coatings in the US. Various brands such as SONAX have capitalized on this trend through their extensive range of ceramic coatings for US vehicles.
Europe
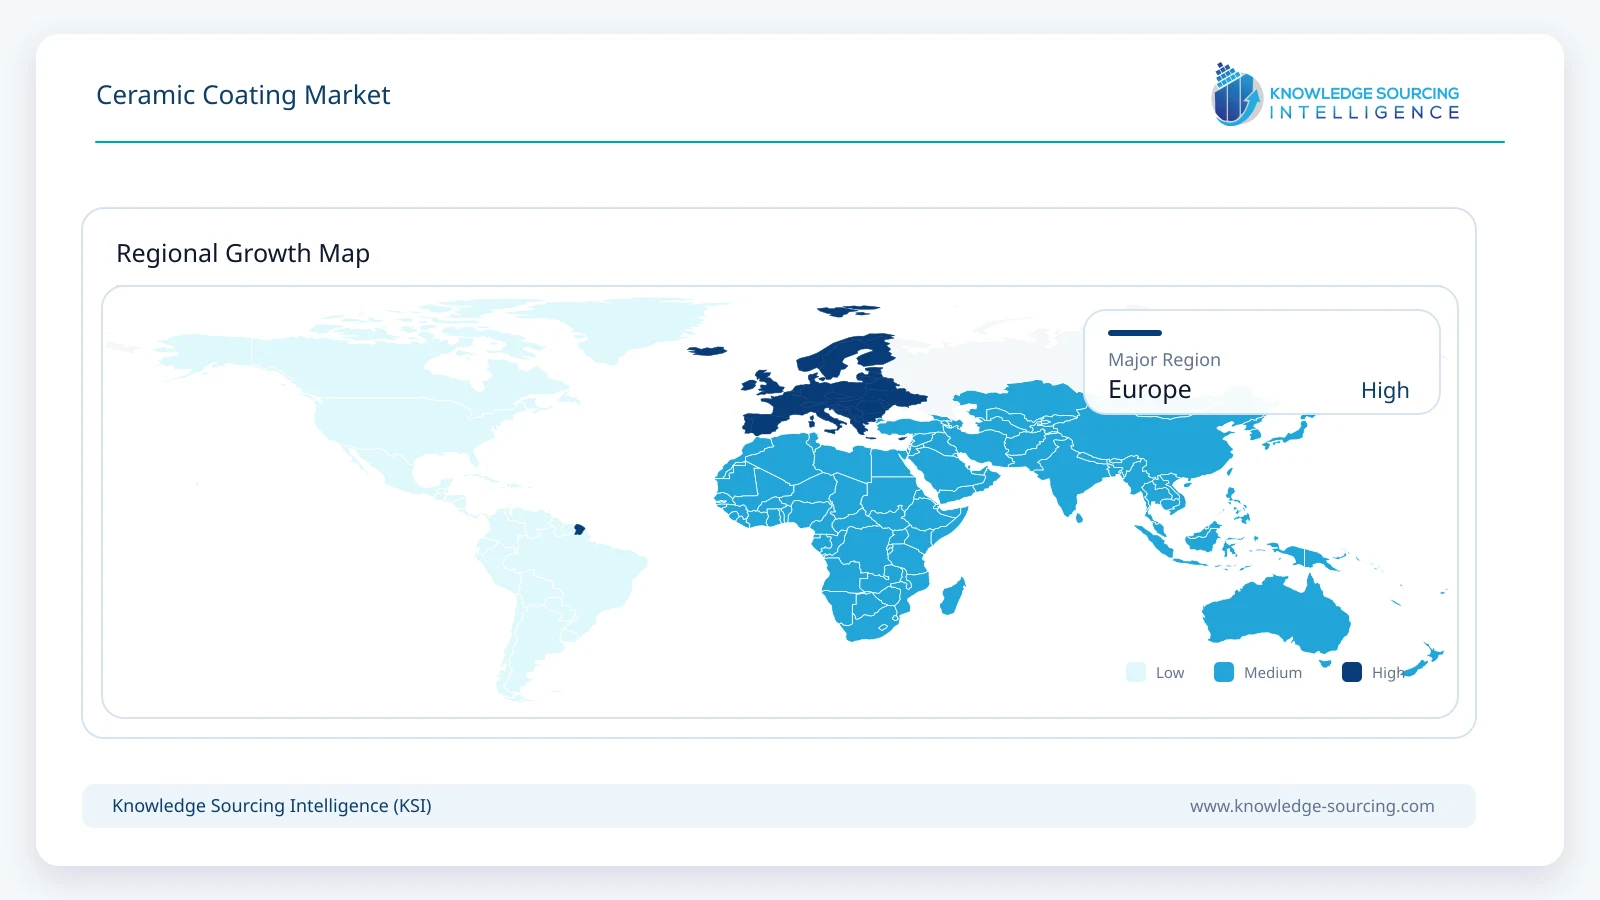
The European market is defined by a strong emphasis on sustainability and circular economy principles. Regulatory frameworks such as REACH are the primary drivers for innovation, forcing companies to develop bio-based or highly inert ceramic alternatives to traditional chemical coatings. Germany and France remain the regional leaders, underpinned by their advanced automotive and machinery manufacturing sectors. The demand in Europe is also seeing a shift toward high-value specialized coatings for renewable energy infrastructure, such as wind turbine components.
Asia-Pacific
Asia-Pacific is the fastest-growing and largest regional market, driven by massive infrastructure expansion and a dominant electronics manufacturing sector. China, India, and Japan are the key contributors, where the demand for ceramic coatings is linked to the production of consumer electronics, automobiles, and semiconductors. The region benefits from lower production costs and a high concentration of raw material suppliers, although it faces increasing pressure to adopt more stringent environmental regulations similar to Western markets.
Middle East and Africa
In the Middle East, particularly Saudi Arabia and the UAE, the demand for ceramic coatings is increasingly tied to the energy sector and desalination projects. Under the Saudi Vision 2030, there is a strategic shift toward localizing the production of advanced materials to support industrial diversification. Ceramic coatings are critical in this region for protecting oil and gas infrastructure from sand erosion and high-salinity corrosion.
South America
The South American market, led by Brazil and Argentina, is primarily driven by the automotive and mining industries. Brazil's role as a regional leader in vehicle manufacturing supports a steady demand for ceramic protective layers. Additionally, the mining sector in the Andean region utilizes ceramic coatings to protect heavy equipment from the abrasive nature of mineral extraction, focusing on extending the maintenance-free life of capital assets.
List of Companies
Saint-Gobain
MBI Coatings
Element 119
APS Materials Inc.
Praxair S.T. Technology Inc. (Linde PLC)
Keronite Group Ltd.
Nanoshine Ltd. (Ceramic Pro)
Ultramet Inc.
Saint-Gobain
Saint-Gobain’s strategy in the ceramic coating market focuses on high-value, specialized technical applications specifically targeting demanding sectors like aerospace, semiconductor manufacturing, industrial energy, and automotive. Rather than competing in generic consumer markets, Saint-Gobain aligns its surface solutions around specialized thermal spray powders, rods, and flexicords engineered for extreme temperature resistance, electrical insulation, and anti-wear protection.
A central pillar of its long-term growth is co-developing custom coating chemistries alongside OEM partners, supported by proprietary application technologies like the Rokide® process. Furthermore, Saint-Gobain prioritizes sustainability and lightweighting, engineering advanced thermal barrier coatings (TBCs) that improve fuel efficiency and prolong component lifespan across harsh industrial environments.
Keronite Group Ltd.
Keronite specializes in Plasma Electrolytic Oxidation (PEO), a technology that transforms the surface of light alloys like aluminum, magnesium, and titanium into hard ceramic layers. Their market position is niche but highly strategic, focusing on the "light-weighting" trend in the aerospace and automotive industries. Keronite’s competitive advantage is its proprietary electrolyte formulations and precise process control, which allow for coatings with superior adhesion and corrosion resistance compared to traditional anodizing. Their strategy involves deep collaborative R&D with OEMs to solve specific thermomechanical challenges in next-generation transport systems.
Nanoshine Ltd.
Operating under the "Ceramic Pro" brand, Nanoshine Ltd. is a dominant player in the nano-ceramic coating segment, particularly in the automotive and marine aftermarkets. Their strategy centers on a global network of over 6,500 certified installers and a product line-up that utilizes molecular bonding to provide high-gloss, hydrophobic protection. The company's competitive advantage is its early adoption of nanotechnology, which allows for thinner coatings yet more durable than traditional waxes or sealants. Nanoshine is increasingly diversifying into industrial and architectural coatings, leveraging its strong brand recognition and SGS-certified non-toxic formulations.
Analyst View
The ceramic coating market is driven by the structural necessity for high-temperature durability and environmental compliance. Rapid innovation in nano-ceramics and plasma technologies will define competitive dynamics, though high energy costs remain a challenge. The outlook is robustly positive.
Ceramic Coating Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 14.3 billion |
| Total Market Size in 2031 | USD 20.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Type, End-User, Geography |
| Companies |
|
Market Segmentation
By Technology
Thermal Spray
Chemical Vapour Deposition (CVD)
Physical Vapour Deposition (PVD)
Others
By Type
Oxide
Nitride
Silicate
Carbide
Others
By End User
Healthcare and Medical Devices
Energy and Power
Automotive
Aerospace and Defense
Electronics & Semiconductor
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. MARKET DYNAMICS
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
4. BUSINESS LANDSCAPE
4.1. Regulatory, Certification & Standards Landscape
4.2. Ceramic Coating Manufacturing & Equipment Ecosystem
4.3. Ceramic Raw Material, Precursor & Supply Chain Analysis
4.4. Import/Export Analysis
4.5. Strategic Recommendations
5. TECHNOLOGICAL OUTLOOK
5.1. Advanced Thermal Spray & High-Performance Ceramic Coating Technologies
5.2. Advanced PVD, CVD & Sol-Gel Deposition Technologies
5.3. High-Temperature, Wear-Resistant & Corrosion-Resistant Ceramic Coating Technologies
5.4. Multifunctional, Nanostructured & Composite Ceramic Coating Technologies
5.5. Advanced Manufacturing, Surface Engineering & Digital Coating Technologies
6. CERAMIC COATING MARKET BY TECHNOLOGY (2021-2031)
6.1. Introduction
6.2. Thermal Spray
6.3. Chemical Vapour Deposition (CVD)
6.4. Physical Vapour Deposition (PVD)
6.5. Others
7. CERAMIC COATING MARKET BY TYPE (2021-2031)
7.1. Introduction
7.2. Oxide
7.3. Nitride
7.4. Silicate
7.5. Carbide
7.6. Others
8. CERAMIC COATING MARKET BY END USER (2021-2031)
8.1. Introduction
8.2. Healthcare and Medical Devices
8.3. Energy and Power
8.4. Automotive
8.5. Aerospace and Defense
8.6. Electronics & Semiconductor
8.7. Others
9. CERAMIC COATING MARKET BY GEOGRAPHY (2021-2031)
9.1. Introduction
9.2. North America
9.2.1. By Technology
9.2.2. By Type
9.2.3. By End User
9.2.4. By Country
9.2.4.1. United States
9.2.4.2. Canada
9.2.4.3. Mexico
9.3. South America
9.3.1. By Technology
9.3.2. By Type
9.3.3. By End User
9.3.4. By Country
9.3.4.1. Brazil
9.3.4.2. Argentina
9.3.4.3. Others
9.4. Europe
9.4.1. By Technology
9.4.2. By Type
9.4.3. By End User
9.4.4. By Country
9.4.4.1. Germany
9.4.4.2. France
9.4.4.3. United Kingdom
9.4.4.4. Spain
9.4.4.5. Others
9.5. Middle East and Africa
9.5.1. By Technology
9.5.2. By Type
9.5.3. By End User
9.5.4. By Country
9.5.4.1. Saudi Arabia
9.5.4.2. UAE
9.5.4.3. Others
9.6. Asia Pacific
9.6.1. By Technology
9.6.2. By Type
9.6.3. By End User
9.6.4. By Country
9.6.4.1. China
9.6.4.2. India
9.6.4.3. Japan
9.6.4.4. South Korea
9.6.4.5. Indonesia
9.6.4.6. Thailand
9.6.4.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Compagnie de Saint-Gobain
11.2. MBI Coatings
11.3. Oerlikon Metco (Insertion)
11.4. APS Materials, Inc
11.5. Linde Advanced Material Technologies, Inc. (Linde AMT)
11.6. Keronite Group Ltd.
11.7. Nanoshine Ltd. (Ceramic Pro)
11.8. Ultramet, Inc.
11.9. Morgan Advanced Materials
11.10. Aremco Products, Inc.
12. RESEARCH METHODOLOGY
13. LIST OF FIGURES
14. LIST OF TABLES
Navigate
Trusted by the world's leading organizations











