
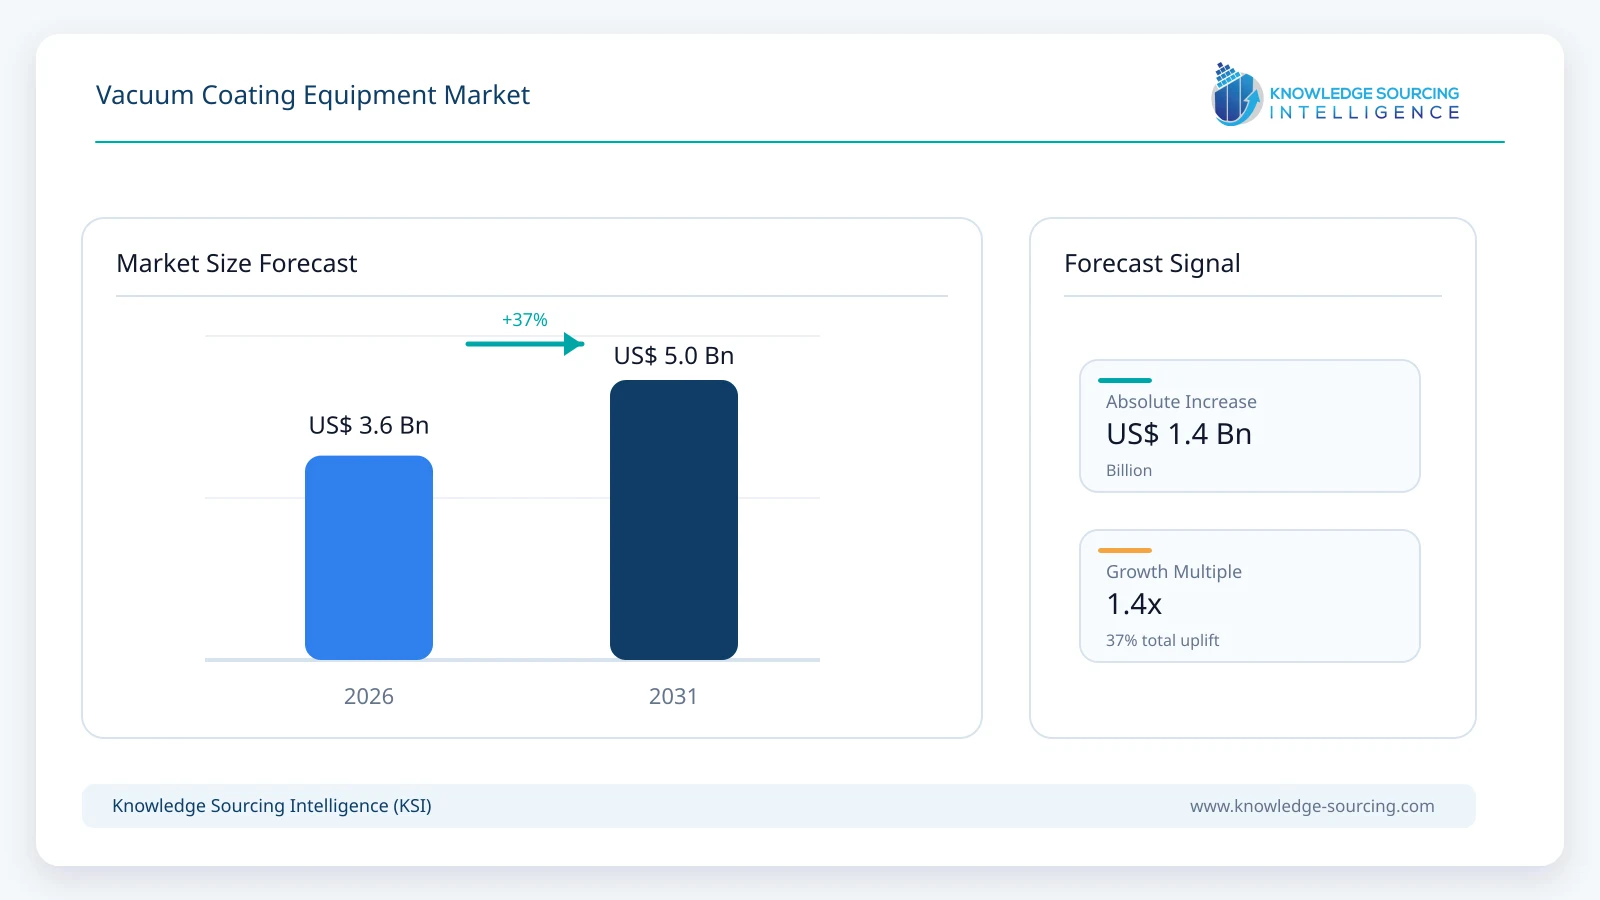
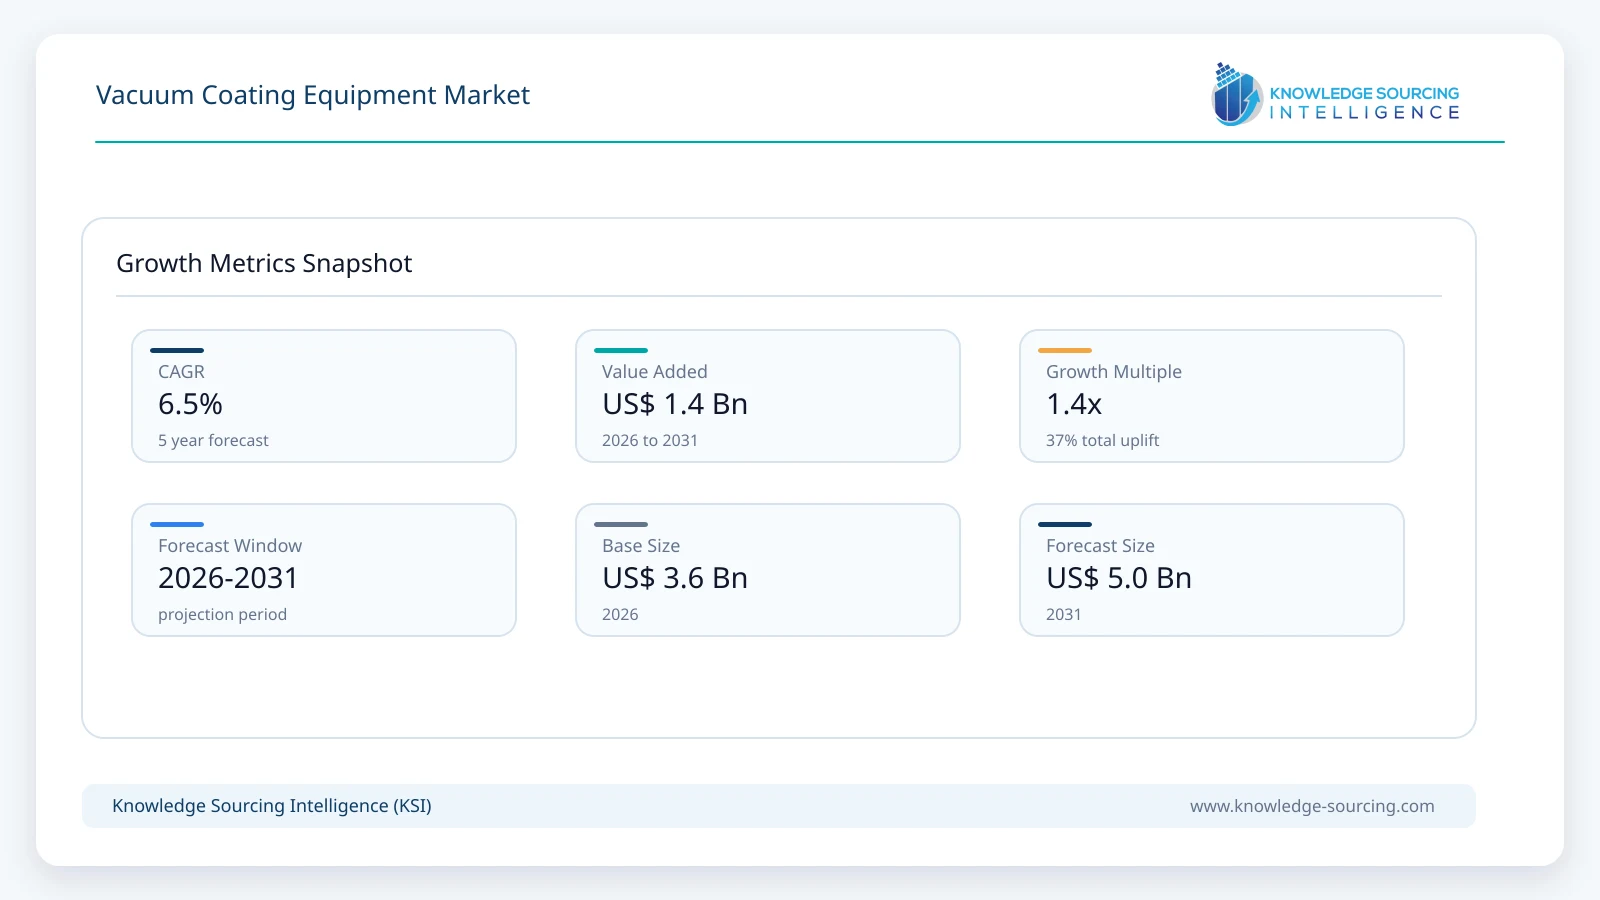
The vacuum coating equipment market is growing at a CAGR of 6.5%, from USD 3.65 billion in 2026 to USD 5.00 billion by 2031.
Highlights:
- 1Physical vapor deposition accounts for approximately 58% of global equipment revenue in 2026.
- 2Electronics represents about 37% of demand as semiconductor and photonics investment accelerates.
- 3Asia Pacific contributes approximately 48% of global vacuum coating equipment revenue in 2026.
- 4Optical-film equipment benefits from precision optics, sensors, displays and wafer-level optical components.
- 5Service, retrofit and productivity upgrades are becoming more important across the installed equipment base.
- 6Capital-spending cycles in glass, solar and automotive remain the principal source of demand volatility.
Vacuum coating equipment is a specialized capital-equipment market serving manufacturers that need thin functional layers deposited under controlled pressure. The commercial equipment base ranges from batch PVD systems for tools, medical devices and decorative components to high-throughput sputtering and evaporation lines for optics, glass, polymer films, photovoltaic products and electronics. Process requirements differ materially by application. Precision optics and semiconductor-related components require extremely tight thickness and contamination control, while packaging and large-area glass emphasize throughput, web handling or substrate size. This diversity supports a fragmented supplier landscape in which application engineering is as important as the underlying vacuum chamber and deposition source.
The 2026 demand environment is stronger than 2025 in several technology-intensive end markets. SEMI forecasts global semiconductor manufacturing equipment sales of USD 165.9 billion in 2026, up 23.2% year on year, with leading-edge logic, advanced memory and packaging driving the increase. Vacuum coating systems represent only a specialized portion of that capital base, but the same investment cycle supports sputtering, seed-layer, optical-filter and specialty deposition equipment. ULVAC reported FY2026 vacuum-equipment sales of JPY 210.8 billion and a 51.4% increase in orders, while SINGULUS TECHNOLOGIES increased first-half 2026 revenue to EUR 45.3 million from EUR 31.3 million and secured new deposition-system orders for MicroLED, MRAM and solar applications.
Other end markets provide a broader demand floor. Global solar photovoltaic additions exceeded 600 GW in 2025, creating continued need for coating systems used in cell architectures, transparent conductive layers and related thin-film processes. Electric-car sales exceeded 20 million units in 2025, supporting advanced sensors, displays, glazing, power electronics and wear-resistant components. Precision optics is also expanding into lithography, astronomy, satellite systems, augmented reality and wafer-level optics. At the same time, Bühler reported delayed investment decisions in glass coating during 2025, illustrating why the market remains cyclical despite strong structural demand for functional surfaces.
Selected Segment Estimates
Dimension | Selected Subsegment | 2026 Indicator | Forecast Interpretation |
Process | Physical Vapor Deposition (PVD) | ~58% share; ~USD 2.12 billion | Largest process family across optics, tools, automotive, electronics and large-area coating. |
Material | Metal Coatings | ~63% share; ~USD 2.30 billion | Broad use in conductive, reflective, decorative and wear-resistant thin films sustains the lead. |
Application | Optical Films | ~25% share; ~USD 0.91 billion | Growth supported by precision optics, sensors, displays, photonics and wafer-level filters. |
Industry Vertical | Electronics | ~37% share; ~USD 1.35 billion | Largest vertical as semiconductor, advanced packaging and high-value electronic components expand. |
Geography | Asia Pacific | ~48% share; ~USD 1.75 billion | Largest regional demand pool, led by China, Taiwan, South Korea and Japan. |
Market Dynamics
Semiconductor and Advanced Packaging Investment Is Raising Demand for High-Precision Deposition
Artificial-intelligence infrastructure, high-bandwidth memory, leading-edge logic and advanced packaging are lifting capital investment across semiconductor manufacturing. Many front-end deposition tools sit outside the industrial vacuum-coating category, but the same investment cycle increases demand for specialty sputtering, seed-layer, magnetic, optical and wafer-level coating systems. ULVAC is contributing seed-sputtering technology to the US-JOINT advanced-packaging consortium in Silicon Valley, while SINGULUS has secured recent orders for MicroLED and MRAM deposition systems. Equipment suppliers that can meet cleanroom requirements, automate wafer handling and maintain repeatability across complex multilayer stacks are positioned to capture the highest-value projects.
Precision Optics and Photonics Are Expanding Beyond Traditional Display Applications
Optical coating demand is broadening from conventional lenses and displays into semiconductor lithography, autonomous-driving sensors, satellite instruments, hyperspectral sensing and large-aperture scientific optics. VON ARDENNE commissioned its OPTA X300 deposition tool in an ISO 5 cleanroom in April 2026 for semiconductor and optical applications and introduced the SKYVA2000 platform for mirrors up to two meters in diameter in July 2026. These systems illustrate the shift toward tighter process monitoring, larger or more complex substrates and multilayer stacks. Precision optics typically supports higher equipment value per installation because coating uniformity and defect control directly affect component performance.
Installed-Base Services, Retrofits and Automation Create Recurring Revenue
Vacuum coating systems often remain in production for many years, creating a substantial aftermarket for chamber refurbishment, deposition-source upgrades, pumps, controls, software and process optimization. Customers increasingly prefer productivity improvements that extend existing equipment life where full replacement is not economical. In June 2026, VON ARDENNE agreed to continue service, spare parts, upgrades and new-equipment support for Applied Materials WEB Coating roll-to-roll systems after Applied discontinued its Flexible Technology Group activities. This type of installed-base transfer demonstrates the commercial importance of lifecycle support and gives established suppliers access to customers beyond new-system sales.
Long Qualification Cycles and Uneven Capital Spending Restrain Project Timing
Vacuum coating projects are capital intensive and usually require extensive process qualification before volume production. Delays are common when customers change product roadmaps, defer factory expansion or face weaker end-market economics. Bühler reported an 8.3% decline in Leybold Optics orders during 2025, with delayed decisions in glass coating partly offset by stronger precision-optics and semiconductor activity. SINGULUS also reported order delays in solar and semiconductor equipment during 2025 before activity improved in 2026. These cycles can create substantial year-to-year volatility even when the long-term need for thin-film deposition continues to increase.
Segment Analysis
By Process - Physical Vapor Deposition (PVD)
Physical vapor deposition is the largest process family, accounting for approximately 58% of 2026 market value. Magnetron sputtering, arc evaporation, electron-beam evaporation and thermal evaporation are used across optical coatings, tools, automotive components, flexible films, glass and selected electronic devices. PVD offers strong control over film thickness and composition while allowing metals, nitrides, oxides and other functional materials to be deposited without the liquid waste associated with many conventional coating processes. CVD and plasma-enhanced CVD remain important where conformality, chemistry or film properties require gas-phase reactions and are expected to grow slightly faster than the overall market through 2031.
By Application - Optical Films
Optical films represent one of the largest application pools because antireflection, high-reflection, filter, heat-control and wavelength-selective coatings are required across consumer electronics, automotive sensors, precision instruments, photonics and scientific optics. The move toward wafer-level optics and filter-on-chip components adds semiconductor-style handling and cleanliness requirements to traditional optical coating. Suppliers are therefore combining higher-throughput batch or inline architectures with optical monitoring, automated loading and improved particle control. Large-area systems remain relevant for architectural and vehicle glass, but near-term growth is stronger in higher-value precision optics than in commodity glass coating.
By Industry Vertical - Electronics
Electronics is the largest industry vertical at approximately 37% of 2026 equipment revenue. Demand spans semiconductor-related components, displays, sensors, magnetic devices, micro-light-emitting diodes, advanced packaging and optical filters. Asia-based manufacturing clusters dominate volume, while North America and Europe are increasing localized investment in semiconductor and photonics capacity. Electronics projects generally require higher levels of automation, process repeatability and contamination control than decorative or general industrial coating, supporting higher equipment values and a larger service requirement throughout the system lifecycle.
Technology and Demand Indicators
Indicator | Latest Development | Market Impact |
Semiconductor equipment | SEMI forecasts USD 165.9 billion of global semiconductor equipment sales in 2026. | Supports specialty deposition, wafer-level optics and advanced-packaging coating demand. |
Vacuum equipment orders | ULVAC FY2026 vacuum-equipment orders increased 51.4% year on year. | Signals stronger investment across semiconductor, electronics and industrial vacuum applications. |
Specialty deposition | SINGULUS secured 2026 orders for MicroLED, MRAM and solar vacuum coating systems. | Shows demand broadening across semiconductor and energy applications. |
Precision optics | VON ARDENNE commissioned OPTA X300 in April 2026 and launched SKYVA2000 in July. | Expands addressable demand in photonics, semiconductor optics, aerospace and scientific systems. |
Solar manufacturing | Global solar PV additions exceeded 600 GW in 2025. | Supports coating equipment for high-efficiency cells and thin-film functional layers. |
Electric vehicles | Global electric-car sales exceeded 20 million units in 2025. | Raises coating requirements in sensors, displays, power electronics, glazing and durable components. |
Asia Pacific Market Analysis
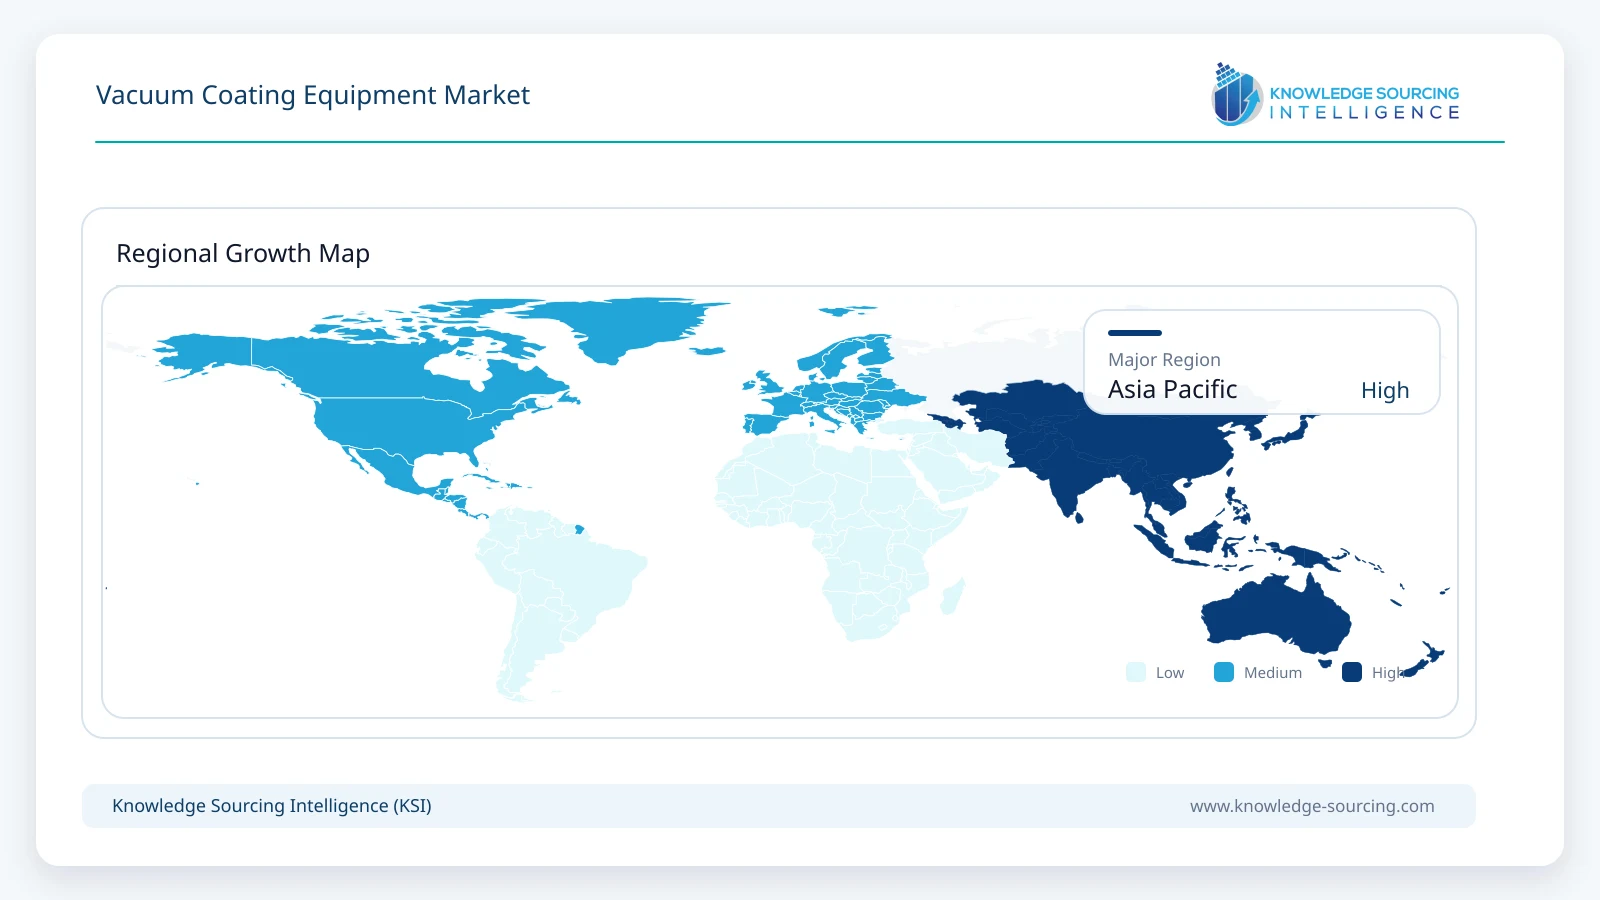
Asia Pacific is the largest regional market, accounting for approximately 48% of global vacuum coating equipment revenue in 2026. The region combines the world’s most concentrated semiconductor and display manufacturing base with large solar, automotive, optics and industrial-coating supply chains. SEMI expects China, Taiwan and South Korea to remain the three largest destinations for semiconductor equipment spending through 2028. Japan adds a strong domestic equipment ecosystem through suppliers such as ULVAC, Optorun and Shincron, while China continues to expand local deposition-equipment capability across displays, solar and electronics.
Regional demand is not limited to semiconductor fabs. China remains the world’s largest producer of solar modules and electric vehicles, both of which use functional thin films across cells, glass, electronics and components. South Korea and Taiwan are concentrated in advanced displays, memory, logic and packaging, while Japan has deep precision-optics and materials capabilities. India is becoming a more relevant market as semiconductor, solar, automotive and advanced-manufacturing investment expands. The combination of manufacturing scale and local equipment ecosystems gives Asia Pacific a structural advantage, although pricing pressure from Chinese suppliers is increasing competition for Japanese and European equipment manufacturers.
Competitive Landscape
The competitive landscape ranges from diversified vacuum-technology groups to application-specific coating-equipment specialists. ULVAC has one of the broadest vacuum-equipment portfolios and reported JPY 210.8 billion of vacuum-equipment sales in the fiscal year ended June 2026. Bühler Leybold Optics is strong in precision optics, glass and large-area coating, while VON ARDENNE competes across glass, web coating, solar, precision optics and semiconductor-related applications. SINGULUS TECHNOLOGIES focuses on modular deposition platforms for solar, semiconductor, medical and decorative applications. Oerlikon Balzers and IHI Hauzer are particularly strong in industrial PVD systems and hard coatings.
Competition increasingly centers on process performance rather than chamber hardware alone. Buyers evaluate coating uniformity, deposition rate, uptime, contamination control, substrate handling, energy consumption, in-situ monitoring and the supplier’s ability to transfer a validated process into volume production. Digital controls and remote service are becoming standard expectations, while cleanroom-compatible automation is important in semiconductor and photonics applications. Suppliers with established process libraries and application centers can shorten customer qualification cycles, which is a meaningful advantage in markets where each new coating stack may require months of testing.
Lifecycle support is another differentiator. Large coating systems can remain productive for a decade or more, giving suppliers recurring opportunities in pumps, targets, components, software, retrofits and process upgrades. VON ARDENNE’s 2026 continuation of support for Applied Materials roll-to-roll web coating systems illustrates how service relationships can outlast the original equipment supplier’s product strategy. The installed base therefore creates a more stable revenue layer that partially offsets volatility in new-system capital spending.
Recent Developments
August 2026: SINGULUS TECHNOLOGIES reported first-half revenue of EUR 45.3 million, up from EUR 31.3 million a year earlier, with higher order intake.
July 2026: VON ARDENNE launched the SKYVA2000 vacuum coating platform for large-aperture optical mirrors up to two meters in diameter.
June 2026: VON ARDENNE agreed to continue service, upgrades and new-equipment support for Applied Materials WEB Coating roll-to-roll systems.
April 2026: VON ARDENNE commissioned its OPTA X300 deposition tool in an ISO 5 cleanroom for semiconductor and precision-optics applications.
April 2026: ULVAC joined the US-JOINT advanced semiconductor packaging consortium, contributing seed-sputtering and vacuum-process expertise.
January 2026: SINGULUS TECHNOLOGIES received a follow-up order for a TIMARIS deposition system for MicroLED production.
2025: Bühler Leybold Optics maintained strong precision-optics and semiconductor activity despite delayed glass-coating investment decisions.
Vacuum Coating Equipment Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.65 billion |
| Total Market Size in 2031 | USD 5.00 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Process, Material, Application, Industry Vertical, Geography |
| Companies |
|
Market Segmentation
By Process
Physical Vapor Deposition (PVD)
Magnetron Sputtering
Arc Evaporation
Thermal and Electron-Beam Evaporation
Chemical Vapor Deposition (CVD)
Plasma-Enhanced CVD (PECVD)
Other CVD Systems
Other Vacuum Coating Processes
By Material
Metal
Ceramic and Other Functional Materials
By Application
Transparent Electrical Conductors
Optical Films
Packaging
Hard and Wear-Resistant Coatings
Others
By Industry Vertical
Electronics
Automotive
Power and Renewable Energy
Healthcare and Medical Devices
Aerospace and Precision Optics
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Others
Middle East and Africa
Saudi Arabia
South Africa
Others
Asia Pacific
China
Japan
South Korea
Taiwan
India
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Semiconductor and Advanced Packaging Investment Is Raising Demand for High-Precision Deposition
3.1.2. Precision Optics and Photonics Are Expanding Beyond Traditional Display Applications
3.1.3. Installed-Base Services, Retrofits and Automation Create Recurring Revenue
3.2. Market Restraints
3.2.1. Long Qualification Cycles and Uneven Capital Spending Restrain Project Timing
3.2.2. High Equipment Cost and Process Complexity Limit Adoption in Smaller Manufacturers
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Environmental, Safety and Process Standards
4. TECHNOLOGICAL OUTLOOK
4.1. Magnetron Sputtering and High-Rate PVD
4.2. Plasma-Enhanced CVD
4.3. In-Situ Optical and Process Monitoring
4.4. Automated Substrate Handling and Cleanroom Integration
4.5. Digital Controls, Predictive Maintenance and Remote Service
5. VACUUM COATING EQUIPMENT MARKET BY PROCESS
5.1. Physical Vapor Deposition (PVD)
5.1.1. Magnetron Sputtering
5.1.2. Arc Evaporation
5.1.3. Thermal and Electron-Beam Evaporation
5.2. Chemical Vapor Deposition (CVD)
5.2.1. Plasma-Enhanced CVD (PECVD)
5.2.2. Other CVD Systems
5.3. Other Vacuum Coating Processes
6. VACUUM COATING EQUIPMENT MARKET BY MATERIAL
6.1. Metal
6.2. Ceramic and Other Functional Materials
7. VACUUM COATING EQUIPMENT MARKET BY APPLICATION
7.1. Transparent Electrical Conductors
7.2. Optical Films
7.3. Packaging
7.4. Hard and Wear-Resistant Coatings
7.5. Others
8. VACUUM COATING EQUIPMENT MARKET BY INDUSTRY VERTICAL
8.1. Electronics
8.2. Automotive
8.3. Power and Renewable Energy
8.4. Healthcare and Medical Devices
8.5. Aerospace and Precision Optics
8.6. Others
9. VACUUM COATING EQUIPMENT MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. South Africa
9.4.3. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. South Korea
9.5.4. Taiwan
9.5.5. India
9.5.6. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. ULVAC, Inc.
11.2. Bühler Leybold Optics
11.3. VON ARDENNE GmbH
11.4. SINGULUS TECHNOLOGIES AG
11.5. Oerlikon Balzers
11.6. IHI Hauzer Techno Coating B.V.
11.7. Applied Materials, Inc.
11.8. Veeco Instruments Inc.
11.9. Optorun Co., Ltd.
11.10. Shincron Co., Ltd.
11.11. CVD Equipment Corporation
11.12. PVD Products, Inc.
11.13. Denton Vacuum, LLC
11.14. Mustang Vacuum Systems
11.15. AJA International, Inc.
11.16. Impact Coatings AB
11.17. Kolzer S.R.L.
11.18. IZOVAC Ltd.
12. RECENT DEVELOPMENTS
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Research Methodology
13.5. Abbreviations
Navigate
Trusted by the world's leading organizations











