
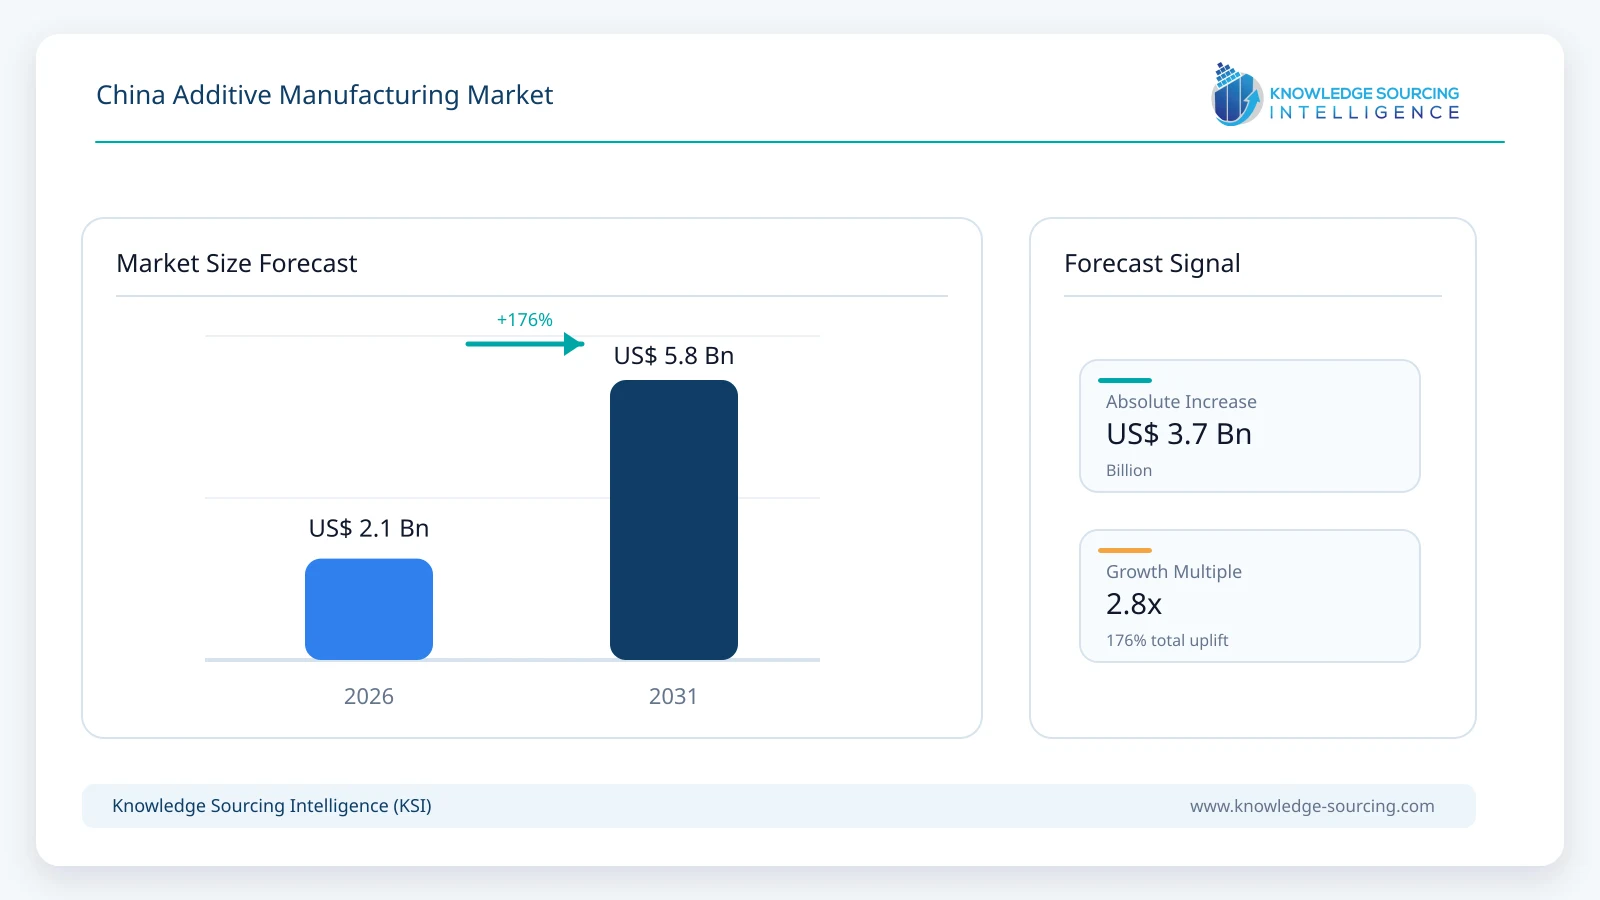
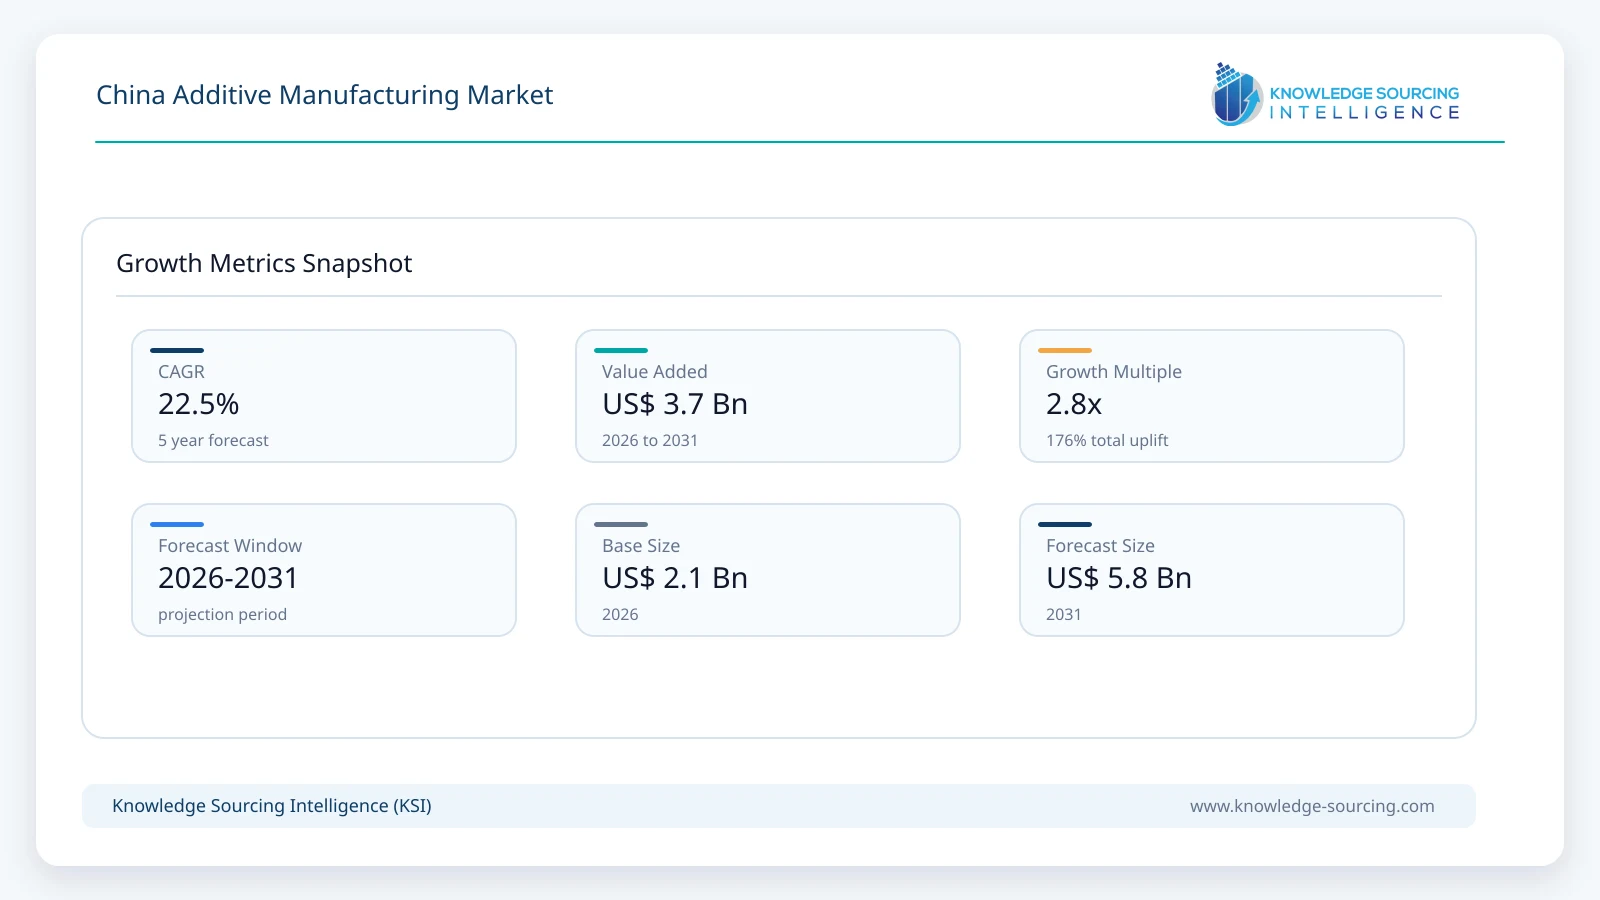
The China Additive Manufacturing market is forecast to grow at a CAGR of 22.5%, reaching USD 5.8 billion in 2031 from USD 2.1 billion in 2026.
Highlights:
- 1Governmental strategies, particularly the "Made in China 2025" initiative, explicitly target Additive Manufacturing (AM) as a critical technology to upgrade the industrial base, directly driving the need for high-end industrial AM hardware and services.
- 2The Hardware component segment constituted the largest revenue share in 2023, reflecting significant domestic investment in establishing production capabilities rather than merely adopting the technology for services.
- 3Rising demand for electric vehicles (EVs) creates a substantial catalyst for metal AM, as OEMs leverage the technology for lightweighting components and rapid prototyping, thereby directly increasing the consumption of metal AM systems and materials.
- 4The high initial capital investment required for industrial-grade AM equipment and the pervasive shortage of skilled professionals present dual constraints that challenge the widespread adoption by Small and Medium-sized Enterprises (SMEs).
The Chinese Additive Manufacturing market is transitioning rapidly from a foundational R&D focus to an application-centric industrialization phase, fundamentally reshaping the domestic manufacturing landscape. This strategic shift is backed by a concentrated national effort to secure a leading position in advanced manufacturing, viewing AM not as an optional technology but as an essential upgrade path for established industrial sectors. The market dynamics are characterized by vigorous domestic hardware competition, increased utilization of metal and ceramic materials, and a potent demand for customized solutions across high-value sectors such as aerospace and healthcare. This trajectory establishes AM as a key enabling technology for China's broader economic and technological self-sufficiency goals.
China Additive Manufacturing Market Analysis:
Growth Drivers
The paramount factor propelling market growth is the national mandate for industrial modernization. The explicit goal of the "Made in China 2025" policy to substitute a significant portion of traditional manufacturing with 3D printing directly translates into sustained, state-backed capital expenditure for AM systems. This regulatory push creates guaranteed demand for industrial-grade AM hardware and software licenses across state-owned enterprises and their supply chains. Furthermore, the burgeoning electric vehicle market is a potent growth driver for specialized metal AM components. OEMs are increasingly adopting AM for functional parts, like heat exchangers and complex structural nodes, to achieve aggressive lightweighting objectives, directly increasing the procurement of high-performance metal powder bed fusion (PBF) systems and high-value titanium and aluminum alloy powders.
Challenges and Opportunities
A primary challenge constraining growth is the elevated barrier to entry marked by the high initial capital investment for industrial AM systems. This financial hurdle limits adoption primarily to large corporations and research institutions, inhibiting market diffusion among smaller, agile manufacturers who could otherwise drive service requirements. An equally significant constraint is the limited availability of engineers and technicians proficient in AM design for manufacturing (DfAM) and post-processing. This skills gap bottlenecks the transition of R&D concepts into commercial production, suppressing the demand for advanced services. Conversely, the opportunity lies in the rising domestic demand for customized medical implants, a factor driving market penetration in the healthcare sector. The requirement for patient-specific devices compels manufacturers to adopt AM, creating a sustained, high-margin demand for both medical-grade AM services and certified polymer/metal materials.
Raw Material and Pricing Analysis
Additive Manufacturing is inherently a physical product market. Key raw materials include polymer, metal, and ceramic powders/filaments. Pricing dynamics are heavily influenced by the raw material supply chain's complexity, particularly for high-performance metal powders like titanium and nickel superalloys, which require specialized spheroidization processes. The majority of the global production capacity for certain metal feedstocks is centrally controlled, but Chinese companies have been actively investing in domestic production and global mining assets to secure the upstream supply. This strategic investment aims to decouple domestic AM material costs from global supply volatility, a factor that will eventually increase the price competitiveness of Chinese-made metal AM services and drive up the internal demand for domestically sourced materials.
Supply Chain Analysis
The global AM supply chain is transitioning from a decentralized model to one with clear regional dominance, with China emerging as a critical global production hub, especially for polymer-based industrial and desktop machines. Logistical complexities stem from dependencies on foreign suppliers for highly specialized components, such as high-power lasers and advanced galvanometer systems used in PBF technology. While China possesses a robust base for general manufacturing, a dependency on specific foreign-sourced core components introduces a minor bottleneck. However, the domestic industry is actively localizing the production of these key elements, which reinforces the long-term trend of a self-contained, vertically integrated Chinese AM supply chain.
Government Regulations:
Jurisdiction | Key Regulation / Agency | Market Impact Analysis |
People's Republic of China | Made in China 2025 (State Council) | Strategic policy that identifies AM as a core technology for industrial modernization, guaranteeing state investment and creating mandated demand for domestic AM hardware and services in targeted industries like aerospace and new energy vehicles. |
People's Republic of China | 14th Five-Year Plan for the Development of Advanced Manufacturing (MIIT) | Emphasizes the importance of AM technologies, translating into increased R&D funding and subsidies for domestic companies. This drives demand for new, higher-speed, larger-format industrial AM systems. |
China Additive Manufacturing Market Segment Analysis:
Selective Laser Sintering (SLS) Technology Analysis
The SLS technology segment is specifically propelled by its unparalleled suitability for batch production of complex polymer parts with minimal need for support structures. Sectors like consumer electronics and automotive prototyping demand robust, functional parts in small to medium volumes, a requirement that traditional injection molding cannot meet cost-effectively or rapidly. The versatility of SLS, capable of processing a wide range of materials, including nylon and polyamides, directly translates into increased system procurement by independent service bureaus. These bureaus leverage the high packing density and material diversity of SLS to aggregate demand from multiple clients, establishing it as a workhorse technology for rapid manufacturing rather than just prototyping, thereby driving sales of larger-build-volume machines.
Aerospace & Defense End-User Industry Analysis
The need for AM in the Aerospace & Defense sector is uniquely driven by the imperative for part consolidation, lightweighting, and reduction of supply chain lead times for mission-critical components. Unlike other sectors, this industry operates under stringent certification requirements, meaning demand is heavily focused on certified metal PBF technologies (like Laser Sintering and EBM) and high-performance materials (e.g., titanium alloys). AM allows engineers to redesign components, consolidating dozens of parts into a single, complex geometry, which drastically cuts assembly time and weight, a critical metric for fuel efficiency and performance. This necessity is high-value, resulting in procurement of the largest, most technologically advanced metal AM systems and long-term service contracts for certified part production.
China Additive Manufacturing Market Competitive Analysis:
The Chinese AM market features intense competition between established global players and rapidly innovating domestic firms. This landscape is defined by the strategic dominance of local companies in the industrial and consumer segments, often challenging international market leaders on price and customization.
Bright Laser Technologies (BLT): As a leading Chinese metal AM systems manufacturer, BLT specializes in Laser Powder Bed Fusion (L-PBF) equipment, offering a holistic approach that includes equipment, metal powders, and engineering services. Their strategic positioning emphasizes large-scale industrial systems, such as the BLT-S series, for high-volume, precision manufacturing, primarily targeting the high-value Aerospace and Defense sectors with verified, end-use parts.
Farsoon Technologies: Farsoon has successfully established itself as a major supplier of open-platform Polymer and Metal PBF systems. The company’s focus on an open material policy attracts a broad user base, from research institutes to manufacturing services. Its product portfolio, including the FS series of metal PBF machines, is strategically positioned to offer industrial-grade performance with greater user control over materials, capturing significant market share by reducing proprietary vendor lock-in.
China Additive Manufacturing Market Developments:
April 2026: Bright Laser Technologies (BLT) launched BLT-TA19, a high-strength, high-temperature, low-cost titanium alloy specifically developed for additive manufacturing, expanding material options for aerospace, industrial, and advanced engineering applications.
March 2026: Bright Laser Technologies (BLT) announced that its topology-optimised pure copper cold plates produced through metal additive manufacturing would debut at TCT Asia 2026, highlighting advanced thermal-management applications for high-performance electronics and industrial systems.
November 2025: Eplus3D officially launched the EP-M550 metal powder bed fusion (PBF) system at Formnext 2025, introducing a new industrial-scale additive manufacturing platform designed to improve production efficiency and scalability.
November 2025: Anyuan Mold partnered with UnionTech to introduce the Fuees430 four-laser metal 3D printer, targeting faster, customised footwear-mould production and advancing metal additive manufacturing applications in China.
China Additive Manufacturing Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.1 billion |
| Total Market Size in 2031 | USD 5.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 22.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Technology, End-User Industry |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Component
By Technology
By End-user Industry
Table of Contents
1. EXECUTIVE SUMMARY 
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE 
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. CHINA ADDITIVE MANUFACTURING MARKET BY COMPONENT
5.1. Introduction
5.2. Hardware
5.3. Software
5.4. Services
5.5. Material
6. CHINA ADDITIVE MANUFACTURING MARKET BY TECHNOLOGY
6.1. Introduction
6.2. Selective Laser Sintering (SLS)
6.3. Laser Sintering (LS)
6.4. Electron Beam Melting (EBM)
6.5. Fused Disposition Modelling
6.6. Stereolithography (SLA)
7. CHINA ADDITIVE MANUFACTURING MARKET BY END-USER INDUSTRY
7.1. Introduction
7.2. Aerospace & Defense
7.3. Health Care
7.4. Automotive
7.5. Construction
7.6. Consumer
7.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Creality
9.2. Bambu Lab
9.3. Farsoon Hi-Tech
9.4. BLT
9.5. UnionTech
9.6. FlashForge
9.7. Elegoo
9.8. Anycubic
9.9. Star Rapid
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key benefits for the stakeholders
10.5. Research Methodology
10.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected market size and growth rate for the China Additive Manufacturing market between 2026 and 2031?
The China Additive Manufacturing market is forecast to grow at a robust CAGR of 22.5%, expanding significantly from USD 2.1 billion in 2026 to an estimated USD 5.8 billion by 2031. This growth is predominantly driven by national industrial modernization mandates and rising demand from high-value sectors.
Which component segment holds the largest revenue share in the China Additive Manufacturing market, and what materials are seeing increased utilization?
The Hardware component segment constituted the largest revenue share in 2023, indicating substantial domestic investment in establishing production capabilities. The market is also characterized by increased utilization of metal and ceramic materials, including high-performance titanium and aluminum alloy powders, driven by demand for customized solutions.
What strategic governmental initiatives are influencing the growth and direction of the China Additive Manufacturing market?
Governmental strategies, particularly the "Made in China 2025" initiative, explicitly target Additive Manufacturing as a critical technology to upgrade the industrial base. This policy creates sustained, state-backed capital expenditure for AM systems and is foundational to China's broader economic and technological self-sufficiency goals.
What are the primary characteristics of the competitive landscape within the China Additive Manufacturing market?
The Chinese Additive Manufacturing market is defined by vigorous domestic hardware competition, reflecting significant investment in establishing production capabilities rather than merely adopting the technology for services. The market is transitioning rapidly from an R&D focus to an application-centric industrialization phase, fundamentally reshaping the manufacturing landscape.
What are the key challenges hindering the wider adoption of Additive Manufacturing in China, particularly for SMEs?
A primary challenge constraining growth is the high initial capital investment required for industrial-grade AM equipment, which disproportionately affects Small and Medium-sized Enterprises (SMEs). Additionally, a pervasive shortage of skilled professionals presents a dual constraint, limiting widespread adoption and efficient utilization of advanced AM technologies across the industry.
How is the growth of the Electric Vehicle (EV) market specifically influencing the demand for Additive Manufacturing solutions in China?
The burgeoning electric vehicle market is a potent growth driver for metal AM, as OEMs increasingly leverage the technology for lightweighting components and rapid prototyping. This directly increases the procurement of high-performance metal powder bed fusion (PBF) systems and high-value titanium and aluminum alloy powders for functional parts like heat exchangers.
Cite this report
Knowledge Sourcing Intelligence. (Aug 2026). China Additive Manufacturing Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/china-additive-manufacturing-market