
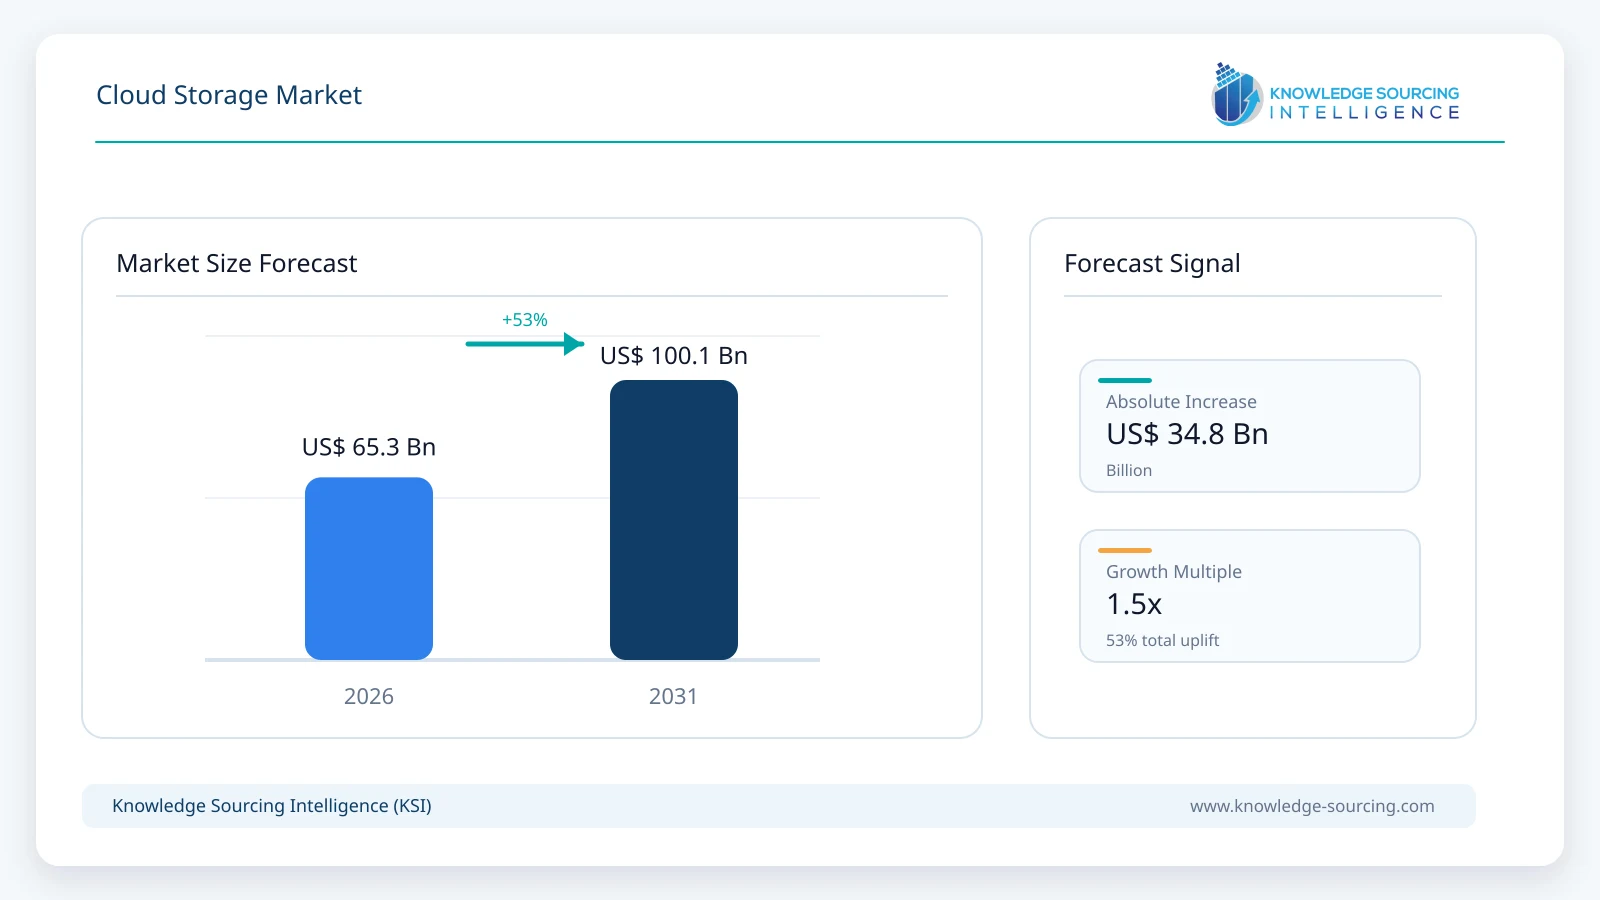
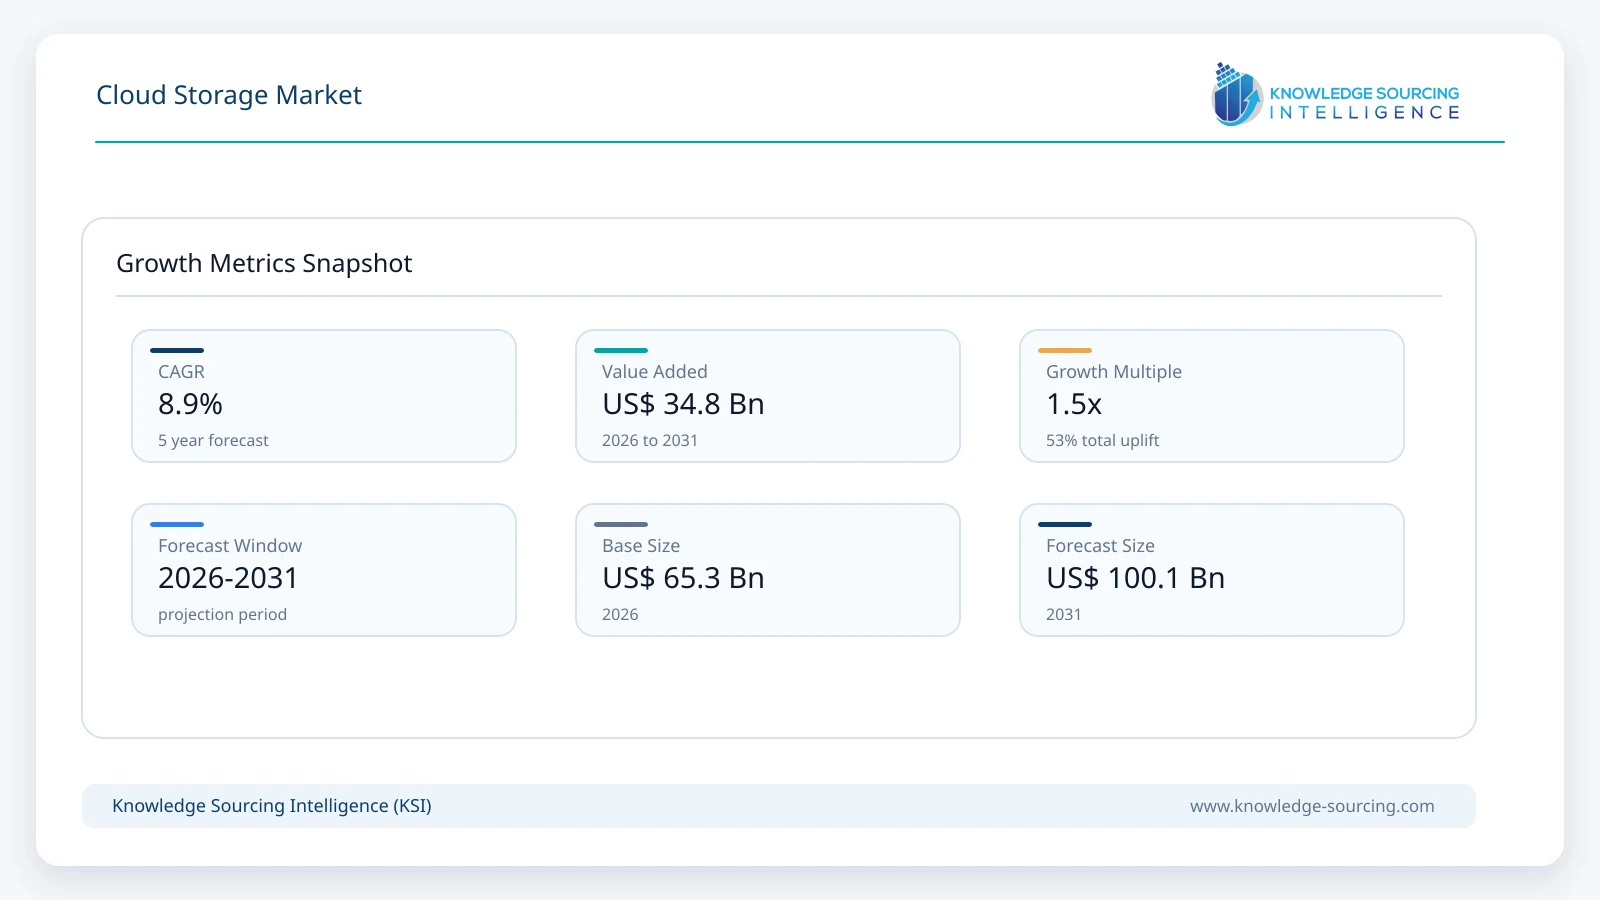
The Cloud Storage Market for BFSI Industry is forecast to grow at a CAGR of 8.9%, reaching USD 100.1 billion in 2031 from USD 65.3 billion in 2026.
Highlights:
- 1Cloud storage spending in BFSI is increasingly linked to regulatory resilience and digital banking modernization.
- 2Hybrid cloud deployments remain commercially important for balancing compliance, scalability, and workload flexibility.
- 3Cybersecurity, operational resilience, and data governance have become primary purchasing criteria for financial institutions.
- 4AI-enabled banking, real-time payments, and digital lending are increasing demand for scalable storage architectures.
- 5Competition is shifting beyond storage capacity toward compliance frameworks, security controls, and managed cloud services.
Market Overview
Banks, insurers, capital market firms, and financial service providers increasingly require storage platforms capable of supporting high transaction volumes, low latency, long-term data retention, and continuous availability while complying with strict supervisory requirements. Procurement decisions therefore extend beyond storage performance to include encryption, geographic data residency, cyber resilience, disaster recovery, interoperability, and audit readiness.
Enterprise cloud adoption within financial services continues to expand as institutions modernize legacy core systems and develop AI-enabled applications. Cloud storage demand is increasingly generated by digital banking platforms, open banking ecosystems, mobile payment infrastructure, wealth management platforms, regulatory reporting systems, and advanced analytics workloads. Buyers increasingly prefer providers capable of combining scalable infrastructure with industry-specific compliance frameworks, integrated identity management, automated backup, and immutable recovery capabilities. Official banking guidance across multiple jurisdictions increasingly emphasizes operational resilience, third-party risk management, and technology governance, reinforcing the commercial importance of resilient cloud storage environments.
Competitive value is distributed across hyperscale cloud providers, enterprise infrastructure vendors, managed service providers, and storage software specialists. While hyperscale platforms compete through global infrastructure and integrated cloud services, enterprise technology vendors increasingly differentiate themselves through hybrid cloud architectures, regulatory compliance capabilities, storage optimization, and migration services. Financial institutions are also adopting multi-cloud strategies to reduce concentration risk, improve business continuity, and maintain greater operational flexibility as supervisory scrutiny of critical technology providers continues to increase.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Basel Committee focus on ICT risk | 2026 | ICT resilience has become central to banking supervision, increasing demand for resilient cloud storage. |
UK Critical Third Party regime | 2025–2026 | Cloud providers serving financial institutions face direct regulatory oversight. |
RBI cloud outsourcing framework | 2023–2025 guidance | Indian BFSI organizations require stronger governance for outsourced cloud infrastructure. |
IBM Financial Services Cloud Framework | Current commercial offering | Financial institutions increasingly seek preconfigured compliance controls rather than standalone infrastructure. |
DTCC Cloud First modernization | 2026 | Financial market infrastructure operators continue migrating critical workloads to cloud environments. |
Key indicator: The Basel Committee published dedicated ICT risk management practices for banks in 2026.
Commercial meaning: Cloud storage procurement increasingly depends on operational resilience, governance, and recovery capabilities rather than storage cost alone.
Market Drivers
Expansion of digital banking platforms and transaction-intensive workloads.
Banks are processing larger volumes of digital payments, customer interactions, real-time settlements, and API-driven financial services than traditional infrastructure was designed to support. Mobile banking, embedded finance, open banking initiatives, and AI-assisted customer services generate continuous growth in structured and unstructured data requiring scalable storage with high availability. This shift has increased procurement of object storage, backup storage, and hybrid cloud architectures capable of supporting analytics alongside operational workloads. Cloud providers are responding through industry-specific storage services, integrated security capabilities, and financial services compliance frameworks designed for regulated environments.
Operational resilience and regulatory oversight are reshaping storage procurement.
Cloud adoption within BFSI is increasingly influenced by regulatory expectations concerning operational continuity, third-party risk management, cyber resilience, and recovery capabilities rather than infrastructure economics alone. Supervisory authorities increasingly require financial institutions to demonstrate governance over outsourced technology services, disaster recovery arrangements, and operational resilience testing. The Basel Committee's ICT risk management guidance and similar national supervisory frameworks have elevated resilient storage architecture from an IT consideration to a board-level risk management priority. Consequently, buyers increasingly evaluate storage providers according to resilience testing, audit support, encryption standards, workload isolation, and recovery performance in addition to capacity and pricing.
Hybrid cloud strategies are reducing infrastructure concentration risk.
Many financial institutions no longer view exclusive dependence on a single cloud environment as an optimal long-term operating model. Instead, regulated organizations increasingly distribute applications and storage across private infrastructure and public cloud environments to improve workload portability, maintain sensitive datasets under tighter governance, and reduce dependence on individual technology providers. Enterprise suppliers have expanded hybrid storage portfolios to support consistent data management across on-premise infrastructure and hyperscale cloud environments. The approach also enables institutions to align storage placement with national data residency requirements while retaining elasticity for customer-facing digital services and analytical workloads.
Artificial intelligence and advanced analytics are increasing enterprise storage requirements.
Financial institutions are integrating machine learning, fraud detection, customer behavior analytics, document intelligence, and generative AI into business operations. These workloads require access to rapidly expanding repositories of structured transaction data, customer records, documents, images, and compliance archives. Storage procurement increasingly favors platforms supporting high-performance access, lifecycle management, metadata services, and integration with AI development environments. Hyperscale cloud providers continue expanding storage and AI services within unified platforms, while enterprise infrastructure vendors are strengthening data governance capabilities to meet financial sector security expectations. As AI deployment matures across banking operations, storage performance, governance, and retrieval efficiency are expected to become increasingly important competitive differentiators.
Market Restraints and Challenges
Regulatory compliance and data sovereignty requirements increase implementation complexity.
Financial institutions operate under stringent regulations governing customer data protection, record retention, operational resilience, and cross-border data transfers. Requirements such as the European Union's Digital Operational Resilience Act (DORA), the General Data Protection Regulation (GDPR), national banking regulations, and central bank outsourcing frameworks require organizations to maintain detailed oversight of cloud-hosted data and critical service providers. Institutions operating across multiple jurisdictions often need separate storage architectures, encryption policies, and recovery procedures to satisfy local regulatory obligations. This raises implementation costs and lengthens migration timelines, particularly for multinational banks that manage customer information across several legal jurisdictions. Cloud providers have responded by expanding regional data centers, compliance certifications, and sovereign cloud offerings, but regulatory fragmentation continues to complicate deployment decisions. According to the European Banking Authority and the European Commission, financial entities must strengthen ICT risk management and third-party oversight under DORA, increasing governance responsibilities for cloud deployments.
Legacy core banking infrastructure slows cloud migration.
Many established financial institutions continue to rely on core banking platforms developed over several decades. These systems support mission-critical payment processing, customer account management, lending operations, and settlement activities, making migration technically demanding and operationally sensitive. Cloud storage projects frequently require extensive application redesign, data validation, interoperability testing, and phased migration strategies to minimize service disruption. Financial institutions must also maintain uninterrupted business continuity during migration while satisfying internal audit and regulatory expectations. Several technology providers, including IBM, Microsoft, Oracle, and Dell Technologies, emphasize hybrid deployment models because they allow customers to modernize gradually without replacing critical legacy infrastructure immediately. As a result, migration projects often extend over multiple years, delaying the realization of operational savings and increasing implementation costs.
Cybersecurity threats continue to raise storage investment requirements.
Ransomware attacks, credential theft, insider threats, and supply-chain attacks remain persistent operational risks for banks and insurers. Cloud storage environments must therefore incorporate immutable backups, continuous monitoring, encryption, privileged access controls, multi-factor authentication, and rapid recovery capabilities. These requirements increase infrastructure complexity and operating expenditure, particularly for institutions managing highly sensitive financial and customer data. Regulatory authorities increasingly expect financial organizations to demonstrate cyber resilience rather than relying solely on preventive security controls. The U.S. Cybersecurity and Infrastructure Security Agency (CISA) and financial regulators continue to emphasize resilient backup strategies and incident recovery planning as essential components of operational resilience. Vendors have expanded cyber recovery services, yet maintaining security across hybrid and multi-cloud environments remains resource intensive for many organizations.
Vendor concentration and third-party dependency remain strategic concerns.
Large financial institutions increasingly depend on a limited number of hyperscale cloud providers for storage, compute, and AI infrastructure. While these platforms offer operational efficiency and global scalability, regulators have expressed concerns regarding concentration risk, systemic resilience, and potential service disruption affecting multiple financial institutions simultaneously. Supervisory authorities in Europe, the United Kingdom, and several Asia-Pacific markets have strengthened oversight of critical third-party technology providers and require financial institutions to conduct more comprehensive outsourcing risk assessments. Consequently, procurement teams increasingly evaluate workload portability, interoperability, contractual exit provisions, and multi-cloud compatibility before selecting long-term storage partners. These additional governance requirements extend procurement cycles but reduce operational dependency on a single provider over time.
Major Segment Analysis
Hybrid Cloud
Hybrid cloud represents the most commercially important deployment model because it enables financial institutions to balance regulatory compliance with operational flexibility. Banks frequently retain highly sensitive customer records, payment data, and core banking applications within private infrastructure while using public cloud resources for analytics, customer engagement platforms, backup storage, disaster recovery, and AI development. This architecture helps institutions satisfy data residency requirements without sacrificing scalability for rapidly expanding digital services.
Purchasing decisions within this segment extend beyond storage capacity. Financial institutions increasingly evaluate interoperability with existing core systems, encryption capabilities, policy-based data management, workload portability, cyber recovery features, and centralized governance across multiple environments. Integration services and migration expertise therefore play an important role alongside storage infrastructure.
Technology suppliers continue expanding hybrid cloud portfolios through unified management platforms, automated data movement, and policy-driven lifecycle management. IBM, Microsoft, Oracle, Dell Technologies, Hewlett Packard Enterprise, NetApp, and Hitachi Vantara increasingly position hybrid storage as a long-term operating model rather than a transitional migration strategy. Continued regulatory attention toward operational resilience and concentration risk is expected to reinforce investment in hybrid architectures throughout the forecast period, particularly among large banking institutions managing diverse regulatory obligations across several markets.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Digital banking modernization, AI adoption, cloud investment | Cybersecurity regulation and concentration risk |
Europe | DORA implementation, data governance, operational resilience | Cross-border compliance and outsourcing oversight |
Asia Pacific | Digital payment expansion, cloud-first banking initiatives | Diverse regulatory frameworks and localization requirements |
Middle East and Africa | Financial sector digitization and smart government programs | Uneven cloud infrastructure maturity |
South America | Banking digitization and fintech expansion | Economic volatility and regulatory differences |
North America
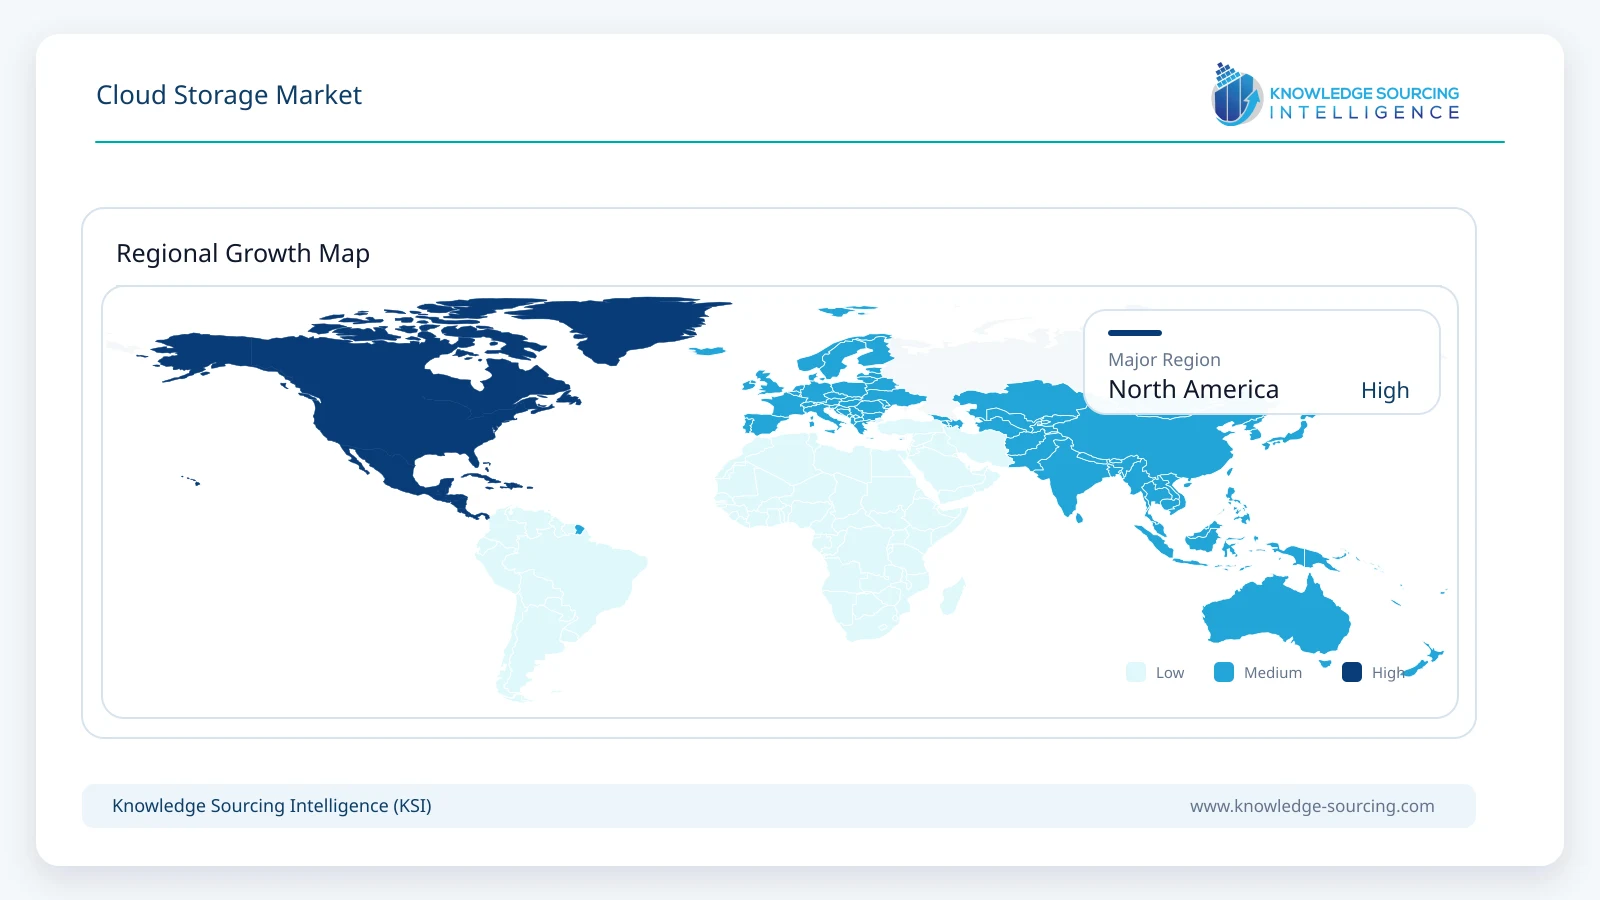
North America continues to account for a substantial share of enterprise cloud adoption within financial services because of mature banking infrastructure, extensive cloud investment, and widespread deployment of digital financial services. Large commercial banks, insurance companies, payment processors, and capital market institutions continue modernizing legacy technology platforms while expanding AI-enabled customer services and fraud detection capabilities. The United States also hosts the largest concentration of hyperscale cloud providers, allowing financial institutions to access integrated storage, analytics, cybersecurity, and disaster recovery services through established cloud ecosystems. Regulatory agencies increasingly emphasize operational resilience, third-party risk management, and cybersecurity governance, encouraging institutions to strengthen backup architectures and multi-cloud strategies rather than relying exclusively on single-provider deployments.
Europe
Implementation of the Digital Operational Resilience Act (DORA) is reshaping technology investment across European financial institutions. Banks operating within the European Union are strengthening ICT governance, cloud oversight, incident reporting, and operational resilience capabilities to comply with the regulation. These requirements are encouraging investment in resilient storage architectures, immutable backup solutions, and enhanced disaster recovery capabilities. Financial institutions also remain highly focused on GDPR compliance, cross-border data governance, and outsourcing risk management, making hybrid deployment models particularly attractive. Technology vendors continue expanding sovereign cloud offerings and regional infrastructure to address data residency requirements while supporting multinational banking operations across the region.
Asia Pacific
Asia Pacific continues to generate strong commercial demand through rapid digital payment adoption, expanding mobile banking ecosystems, government-backed digital infrastructure, and continued investment in financial technology. China, India, Japan, Australia, Singapore, and several Southeast Asian markets are expanding cloud adoption across banking and insurance operations while strengthening cybersecurity and financial sector supervision. Central banks throughout the region increasingly publish cloud outsourcing guidance, cybersecurity frameworks, and operational resilience expectations that influence procurement decisions. Domestic cloud providers remain important in several markets because of localization requirements, although global hyperscale providers continue expanding regional infrastructure to support financial sector customers. Growing volumes of digital transactions and AI-driven banking services are expected to sustain long-term storage demand across both established financial institutions and rapidly expanding fintech ecosystems.
Middle East and Africa
Financial sector modernization programs across the Gulf Cooperation Council countries, together with expanding digital banking initiatives in parts of Africa, continue supporting investment in secure cloud infrastructure. Saudi Arabia and the United Arab Emirates have introduced national digital economy strategies while encouraging cloud adoption under regulated frameworks. Demand increasingly originates from banking modernization, digital payment infrastructure, and government-supported financial inclusion initiatives. However, uneven cloud infrastructure maturity, differing regulatory frameworks, and varying cybersecurity capabilities continue to influence the pace of adoption across the broader region.
Competitive Landscape
Competition in the cloud storage market for the BFSI industry is concentrated among hyperscale cloud providers, enterprise infrastructure vendors, and hybrid cloud specialists that can satisfy stringent financial-sector security and compliance requirements. Amazon Web Services, Microsoft, Google Cloud, IBM, Oracle Corporation, Hewlett Packard Enterprise Development LP, Dell Technologies, NetApp, Fujitsu, and Hitachi Vantara compete on more than storage performance or pricing. Financial institutions increasingly assess vendors on regulatory compliance, cyber resilience, encryption, workload portability, geographic data residency, disaster recovery, service availability, and integration with existing banking applications.
Hyperscale providers continue expanding region-specific cloud infrastructure, compliance certifications, AI-enabled data services, and sovereign cloud capabilities to address regulatory expectations in financial services. Enterprise infrastructure vendors, meanwhile, are strengthening hybrid cloud portfolios that allow banks to retain sensitive workloads on private infrastructure while extending analytical, backup, and disaster recovery functions into public cloud environments. Managed service capabilities and migration expertise have become important competitive differentiators because many banking organizations continue modernizing decades-old core systems rather than replacing them outright.
Barriers to entry remain relatively high. Financial institutions typically conduct extensive technical validation, cybersecurity assessments, regulatory due diligence, and resilience testing before selecting storage partners. Once deployed, cloud storage platforms become closely integrated with core banking applications, security frameworks, and compliance processes, increasing switching costs and encouraging long-term supplier relationships. Vendors therefore continue investing in compliance programs, regional infrastructure expansion, partner ecosystems, and automation tools to strengthen customer retention while addressing evolving supervisory expectations. Official company disclosures from AWS, Microsoft, IBM, Oracle, and Dell Technologies continue to emphasize regulated industry solutions, cyber resilience, AI integration, and hybrid cloud investment as strategic priorities.
Recent Developments
March 2026 – Nasuni (Acquisition): Nasuni acquired Resilio, adding high-speed data movement and synchronization technology to its cloud file storage platform. The combination strengthens data accessibility, disaster recovery, and multi-cloud capabilities for highly regulated BFSI organizations.
July 2025 – Hitachi Vantara (Product Launch): Hitachi Vantara made Virtual Storage Platform One available through Google Cloud Marketplace, expanding hybrid cloud storage deployment, two-way data mobility, and data protection capabilities for regulated enterprises, including BFSI environments.
June 2025 – Pure Storage (Product Launch): Pure Storage introduced its Enterprise Data Cloud, unifying cloud and on-premises storage management through an intelligent control plane. The platform enhances cyber resilience, governance, and scalable data services for financial institutions.
June 2025 – Pure Storage (Product Launch): Pure Storage unveiled next-generation FlashArray and FlashBlade platforms alongside its Enterprise Data Cloud architecture, enabling secure, high-performance cloud storage modernization, ransomware resilience, and simplified data management for banking and financial workloads.
Regulatory and Policy Environment
Financial-sector cloud adoption is increasingly governed by operational resilience requirements rather than conventional outsourcing policies alone. Supervisory authorities now expect regulated institutions to demonstrate continuous oversight of critical technology providers, robust cyber recovery capabilities, resilient backup environments, and well-defined exit strategies before approving large-scale cloud deployments.
Within the European Union, the Digital Operational Resilience Act (DORA) establishes harmonized requirements for ICT risk management, incident reporting, resilience testing, and oversight of critical third-party ICT providers. These provisions encourage financial institutions to strengthen governance over cloud-hosted storage, disaster recovery planning, and third-party operational controls while increasing demand for compliant infrastructure across the region.
North American regulators continue emphasizing cybersecurity resilience, third-party risk management, and operational continuity through guidance issued by banking supervisory agencies and cybersecurity authorities. Financial institutions are increasingly required to demonstrate secure backup strategies, ransomware recovery capabilities, and comprehensive governance over outsourced cloud services, influencing procurement priorities across storage infrastructure projects.
Across Asia Pacific, central banks and financial regulators have introduced cloud outsourcing frameworks, cybersecurity standards, and data governance requirements that shape technology investment decisions. India, Singapore, Australia, Japan, and several Southeast Asian jurisdictions have strengthened supervisory expectations concerning cloud adoption, resilience testing, and outsourcing governance. These developments encourage institutions to adopt hybrid deployment models, localized data storage, and enhanced compliance monitoring while allowing continued modernization of digital banking services.
Outlook and Strategic Implications
Cloud storage investment across the BFSI sector is expected to remain closely aligned with regulatory modernization, operational resilience, cybersecurity preparedness, and digital banking transformation throughout the 2026–2031 forecast period. Rather than replacing existing infrastructure completely, many financial institutions are expected to continue modernizing through phased hybrid cloud strategies that reduce operational risk while supporting new digital services and AI-enabled business processes.
Demand will increasingly favor storage platforms capable of combining regulatory compliance with automation, cyber recovery, policy-driven governance, lifecycle management, and integration with AI and analytics environments. As generative AI, fraud analytics, real-time payments, and open banking ecosystems continue expanding, storage performance alone will no longer represent the principal purchasing criterion. Buyers are expected to prioritize resilience, governance, interoperability, and long-term operational flexibility when selecting technology partners.
Strategic implications
Financial institutions: Procurement strategies are expected to prioritize hybrid cloud architectures, immutable backup capabilities, multi-cloud resilience, and regulatory compliance over standalone infrastructure cost savings.
Cloud service providers: Continued investment in sovereign cloud infrastructure, industry-specific compliance frameworks, regional data centers, and AI-enabled storage management will remain important for serving regulated financial institutions.
Enterprise technology vendors: Integration services, migration expertise, cybersecurity capabilities, and unified hybrid cloud management platforms are likely to become increasingly important sources of competitive differentiation.
Regulators and policymakers: Operational resilience, concentration risk oversight, and third-party governance frameworks will continue influencing technology adoption patterns, supplier qualification processes, and long-term market structure.
Overall, commercial competition is expected to shift toward vendors capable of delivering secure, policy-compliant, and operationally resilient storage ecosystems that integrate seamlessly with evolving banking platforms, AI-driven workloads, and increasingly demanding supervisory requirements. Institutions that successfully balance regulatory obligations with scalable cloud adoption are likely to achieve greater operational efficiency while improving business continuity and customer service capabilities in an increasingly digital financial services environment.
Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 65.3 billion |
| Total Market Size in 2031 | USD 100.1 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 8.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution, Deployment Model, Services, Enterprise Size, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Solution
Primary Storage
Backup Storage
Archive Storage
Disaster Recovery Storage (DRaaS)
Object Storage
File and Block Storage
By Deployment Model
Public Cloud
Private Cloud
Hybrid Cloud
By Services
Integration and Migration
Consulting
Managed Services
Support and Maintenance
By Enterprise Size
Large
Small and Medium-sized Business (SMB)
By Geography
North America
United States
Canada
Mexico
Others
South America
Brazil
Argentina
Others
Europe
Germany
France
Italy
United Kingdom
Others
Middle East and Africa
Israel
Saudi Arabia
UAE
Others
Asia Pacific
Japan
China
India
Australia
Malaysia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Currency
1.5. Assumptions
1.6. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Sources
3. EXECUTIVE SUMMARY
4. MARKET DYNAMICS
4.1. Market Segmentation
4.2. Market Drivers
4.3. Market Restraints
4.4. Market Opportunities
4.5. Porter’s Five Force Analysis
4.5.1. Bargaining Power of Suppliers
4.5.2. Bargaining Power of Buyers
4.5.3. Threat of New Entrants
4.5.4. Threat of Substitutes
4.5.5. Competitive Rivalry in the Industry
4.6. Life Cycle Analysis - Regional Snapshot
4.7. Market Attractiveness
5. CLOUD STORAGE MARKET FOR BFSI INDUSTRY FORECAST BY SOLUTION
5.1. Primary Storage
5.2. Backup Storage
5.3. Archive Storage
5.4. Disaster Recovery Storage (DRaaS)
5.5 Object Storage
5.6. File and Block Storage
6. CLOUD STORAGE MARKET FOR BFSI INDUSTRY FORECAST BY DEPLOYMENT MODEL
6.1. Public Cloud
6.2. Private Cloud
6.3. Hybrid Cloud
7. CLOUD STORAGE MARKET FOR BFSI INDUSTRY FORECAST BY SERVICES
7.1. Integration and Migration
7.2. Consulting
7.3. Managed Services
7.4. Support and Maintenance
8. CLOUD STORAGE MARKET FOR BFSI INDUSTRY FORECAST BY ENTERPRISE SIZE
8.1. Large
8.2. SMB (Small and Medium-sized business)
9. CLOUD STORAGE MARKET FOR BFSI INDUSTRY FORECAST BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.1.4. Others
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. France
9.3.3. Italy
9.3.4. United Kingdom
9.3.5. Others
9.4. Middle East and Africa
9.4.1. Israel
9.4.2. Saudi Arabia
9.4.3. UAE
9.4.4. Others
9.5. Asia Pacific
9.5.1. Japan
9.5.2. China
9.5.3. India
9.5.4. Australia
9.5.5. Malaysia
9.5.6. Others
10. COMPETITIVE INTELLIGENCE
10.1. Recent Deals and Investment
10.2. Strategies of Key Players
10.3. Investment Analysis
11. COMPANY PROFILES
11.1. Amazon Web Services, Inc.
11.1.1. Company Overview
11.1.2. Financials
11.1.3. Products and Services
11.1.4. Recent Developments
11.2. Microsoft
11.2.1. Company Overview
11.2.2. Financials
11.2.3. Products and Services
11.2.4. Recent Developments
11.3. IBM
11.3.1. Company Overview
11.3.2. Financials
11.3.3. Products and Services
11.3.4. Recent Developments
11.4. Google
11.4.1. Company Overview
11.4.2. Financials
11.4.3. Products and Services
11.4.4. Recent Developments
11.5. Hewlett Packard Enterprise Development LP
11.5.1. Company Overview
11.5.2. Financials
11.5.3. Products and Services
11.5.4. Recent Developments
11.6. FUJITSU
11.6.1. Company Overview
11.6.2. Financials
11.6.3. Products and Services
11.6.4. Recent Developments
11.7. Oracle Corporation
11.7.1. Company Overview
11.7.2. Financials
11.7.3. Products and Services
11.7.4. Recent Developments
11.8. Dell Technologies
11.8.1. Company Overview
11.8.2. Financials
11.8.3. Products and Services
11.8.4. Recent Developments
11.9. NetApp
11.9.1. Company Overview
11.9.2. Financials
11.9.3. Products and Services
11.9.4. Recent Developments
11.10. Hitachi Vantara
11.10.1. Company Overview
11.10.2. Financials
11.10.3. Products and Services
11.10.4. Recent Developments
LIST OF FIGURES
LIST OF TABLES
DISCLAIMER





Frequently asked questions
What is the projected market size for BFSI cloud storage by 2031?
The Cloud Storage Market is forecast to reach USD 100.1 billion by 2031.
What is the expected CAGR for the BFSI Cloud Storage Market?
The Cloud Storage Market is projected to grow at an 8.9% CAGR.
What are the primary growth drivers for BFSI cloud storage?
Digital banking modernization, regulatory resilience, and AI-enabled banking drive growth.
What deployment trend is key for BFSI cloud storage?
Hybrid cloud deployments remain commercially important for balancing compliance and scalability.
What are key purchasing criteria for financial institutions?
Cybersecurity, operational resilience, and data governance are primary criteria.
How do regulations influence cloud storage demand in BFSI?
Regulations emphasize operational resilience and governance, reinforcing demand for resilient cloud storage.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Cloud Storage Market for BFSI Industry - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/cloud-storage-market-for-bfsi-industry