
The CNG Tanks/Cylinders Market is projected to expand steadily during the forecast period, supported by the increasing deployment of CNG vehicles, expansion of city gas distribution infrastructure, demand for lightweight composite cylinders, and the adoption of CNG in passenger, commercial, and public transport fleets.
Highlights:
- 1CNG cylinder manufacturers are improving storage designs while meeting stringent pressure and safety requirements.
- 2Vehicle operators are increasingly adopting CNG systems as cleaner fuel alternatives for transportation applications.
- 3Regulatory authorities are strengthening cylinder inspection, certification, traceability, and compliance requirements for CNG applications.
- 4Automotive suppliers are developing lighter cylinder solutions to improve vehicle weight management and storage efficiency.
Compressed Natural Gas (CNG) tanks and cylinders are high-pressure storage systems designed to contain natural gas for use in vehicles, mobile gas distribution systems, and selected stationary applications. Unlike conventional liquid-fuel tanks, CNG cylinders must withstand significantly higher operating pressures and repeated filling cycles. They are manufactured using steel, aluminum, carbon-fiber composites, glass-fiber composites, or combinations of metal liners and composite reinforcement. Cylinder construction ranges from Type I all-metal cylinders to Type IV fully composite cylinders, with each design offering different combinations of weight, durability, pressure performance, packaging flexibility, and cost.
The market is increasingly influenced by the transition toward lower-emission transportation and the expansion of natural gas infrastructure. In India, the Petroleum and Natural Gas Regulatory Board (PNGRB) reported 9,026 CNG stations as of June 2026 across 312 geographical areas. This represents a substantial expansion of the CNG distribution ecosystem and creates a larger addressable market for vehicle-mounted cylinders, storage systems, and related high-pressure gas equipment.
Government data also demonstrates the long-term expansion of CNG infrastructure. A Government of India publication reported that CNG stations increased from about 968 in 2014 to more than 8,477 by 2025, while the city gas distribution network expanded substantially during the same period. A separate government publication reported that the number of CNG-powered vehicles in India had increased from around 1 million in 2014 to more than 7 million by 2026, highlighting the expanding installed base that supports demand for CNG storage equipment.
The CNG Tanks/Cylinders Market therefore extends beyond the manufacture of individual cylinders. It includes the material supply chain, cylinder manufacturing, composite reinforcement, valves and pressure-relief components, testing and certification, vehicle integration, storage systems, and replacement demand. Increasing emphasis on vehicle safety, weight reduction, driving range, and packaging efficiency is encouraging manufacturers to develop higher-capacity and lighter storage solutions.
From a market application perspective, transportation remains the central demand area. The Ministry of Petroleum and Natural Gas describes CNG as predominantly used as an auto-fuel within India's city gas distribution system. At the same time, CNG is gaining relevance in buses, light commercial vehicles, heavy-duty fleets, logistics operations, and mobile gas distribution. This diversification is supporting demand across different cylinder capacities and construction types.
CNG Tanks/Cylinders Market Drivers:
Expansion of CNG vehicle infrastructure is accelerating demand for CNG tanks and cylinders
The expansion of CNG refuelling infrastructure is one of the most direct demand drivers for CNG tanks and cylinders because each additional CNG vehicle requires an appropriate high-pressure onboard storage system. India's current infrastructure provides a strong example of this relationship. PNGRB reported 9,026 CNG stations as of June 2026, covering 312 geographical areas. The expansion is also continuing through new approvals and infrastructure-development initiatives. During the 2026 PNG Drive 2.0 campaign, PNGRB reported that 474 new CNG stations were added, while 32 new districts were connected to the city gas distribution system. The campaign ran from January through June 2026.
The Indian government has also demonstrated that CNG remains a priority fuel for transportation. In March 2026, the government stated that domestic piped gas and CNG for vehicles were receiving 100% supply allocation during a period of international gas-supply disruption. This policy prioritization supports the reliability of CNG as a transportation fuel and reduces the risk that short-term supply disruptions will immediately undermine CNG vehicle operations.
The expansion of infrastructure is important for the cylinder market because it increases both first-fit and replacement demand. New CNG vehicles require new cylinders, while existing cylinders require inspection, maintenance, replacement, and eventual retirement according to applicable safety requirements. As the installed vehicle base becomes larger, replacement demand can become a recurring component of the market rather than relying exclusively on new vehicle sales.
Government-supported transition toward cleaner commercial and urban mobility is strengthening CNG cylinder demand
Environmental regulations and clean-mobility policies are creating additional opportunities for CNG vehicles, particularly in urban transport and commercial fleets. The Commission for Air Quality Management in NCR and Adjoining Areas has implemented measures encouraging cleaner vehicle technologies. For example, its directions require that only CNG, electric, or other specified cleaner technologies be additionally inducted in certain three-wheeler fleets, while conventional petrol and diesel vehicles face restrictions in specified vehicle categories from January 2026.
CAQM has also restricted the entry of specified commercial goods vehicles into Delhi unless they meet defined cleaner-fuel requirements, including BS-VI, CNG, LNG, or electric propulsion. The measure specifically targets light, medium, and heavy commercial goods vehicles and forms part of the broader effort to reduce vehicular pollution in the National Capital Region.
These measures are relevant to the CNG Tanks/Cylinders Market because commercial vehicles generally require larger and more robust storage systems than passenger vehicles. Increasing CNG penetration in fleet applications can therefore shift demand toward higher-capacity cylinders, multi-cylinder systems, lightweight composite storage, and integrated fuel-system packages.
Government environmental assessments also support the positioning of natural gas as a transition fuel. PNGRB stated in January 2026 that CNG buses and cars can emit substantially lower particulate matter than comparable diesel-fuelled vehicles and estimated approximately 20% to 40% lower carbon dioxide emissions per kilometre compared with petrol and diesel vehicles. Such comparisons continue to support CNG adoption in applications where operators require an alternative to conventional liquid fuels but where battery-electric infrastructure, range, payload, or charging requirements remain challenging.
Growth of commercial vehicles and public transport is creating demand for higher-capacity CNG storage systems
Commercial transportation is becoming an increasingly important application for CNG cylinder manufacturers. Trucks, buses, delivery vehicles, refuse vehicles, and other high-utilization fleets can benefit from CNG where fuel economics, refuelling infrastructure, and fleet operating patterns support the technology. Commercial vehicles typically require higher onboard fuel capacity because they travel longer distances and operate for more hours per day. This creates demand for multiple cylinders, larger-capacity configurations, and lightweight storage systems that minimize the effect of fuel-system weight on payload.
Company developments in 2026 demonstrate this trend. In February 2026, Hexagon Agility announced an approximately US$12 million order for natural-gas fuel systems from a Mexican trucking company. The company stated that the heavy-duty trucks are expected to travel more than 12 million miles annually and can achieve ranges of up to 1,200 miles on a single fill. The development illustrates the increasing role of high-capacity CNG fuel systems in long-haul commercial transportation and supports demand for advanced cylinder configurations.
In April 2026, Hexagon Agility announced that it would deliver CNG fuel systems for 350 new TRATON Group intercity transit buses serving France. The systems are scheduled for delivery during 2026 and 2027 and incorporate the company's Type 4 composite cylinder technology. This development is particularly relevant to the CNG Tanks/Cylinders Market because it directly connects public transport fleet expansion with demand for advanced composite cylinders.
CNG Tanks/Cylinders Market Segment Analysis:
Vehicle Type: Passenger Vehicles remain a major demand segment, while commercial vehicles are increasing their importance
Passenger vehicles represent a significant application for CNG cylinders because CNG has become an established alternative-fuel option in several large automotive markets. Passenger-car applications generally emphasize compact packaging, safety, sufficient driving range, low system weight, and preservation of usable luggage space. These requirements are encouraging vehicle manufacturers and cylinder suppliers to improve cylinder placement and packaging rather than simply increasing tank size.
India provides a particularly strong example of this trend. Maruti Suzuki continues to offer CNG as part of its multi-powertrain strategy and stated in its 2025-26 annual report that its strategy includes CNG/CBG, battery-electric, hybrid, and ethanol-based technologies. In July 2026, the company launched an updated Brezza with an S-CNG variant using a new underbody CNG tank configuration designed to preserve boot space. The company also stated that the S-CNG version incorporates Idle Start-Stop technology and delivers a claimed fuel efficiency of 26.9 km/kg.
The significance of underbody cylinder placement extends beyond a single vehicle model. Packaging is becoming a key differentiating factor in the passenger-vehicle CNG market. Conventional large-cylinder arrangements can compromise cargo capacity, while optimized configurations can preserve vehicle utility. This creates opportunities for cylinder manufacturers capable of delivering high volumetric efficiency, robust safety performance, and compact integration.
Commercial vehicles represent another important growth segment. Light commercial vehicles, medium and heavy trucks, buses, and public transport vehicles require larger storage capacity and often operate under demanding duty cycles. The growth of CNG-powered buses and freight vehicles can therefore generate greater demand per vehicle than passenger-car applications.
Tata Motors' 2026 product activity illustrates this trend. In June 2026, Tata Motors Commercial Vehicles launched the Intra V40, a small commercial vehicle using CNG-plus-petrol bi-fuel technology. The vehicle has a 110-litre CNG tank and a stated payload of 1,525 kg. In July 2026, Tata Motors also unveiled the LPO 1620 CNG bus at Prawaas 5.0 as part of its passenger mobility portfolio. These launches indicate that CNG storage demand is expanding across both goods transportation and passenger mobility.
Material Type: Type IV composite cylinders are gaining strategic importance because of weight reduction and packaging advantages
Material type is a major technology differentiator in the CNG Tanks/Cylinders Market. Type I cylinders use an all-metal construction and remain important because of their established manufacturing base, durability, and comparatively lower cost. Type II and Type III designs combine metal liners with composite reinforcement, providing a transition between conventional steel storage and fully composite systems. Type IV cylinders use a non-metallic liner with full composite reinforcement and are increasingly associated with applications where weight reduction and higher packaging flexibility are priorities.
Type IV technology is particularly important in commercial vehicles because reducing storage-system weight can increase available payload or allow additional onboard gas capacity without creating an equivalent increase in vehicle mass. Composite cylinders can also provide greater design flexibility, supporting multi-cylinder systems and vehicle-specific packaging.
Hexagon Agility's 2026 developments provide direct evidence of this technology trend. In February 2026, the company announced delivery of its 6,000th carbon-fiber gas-distribution cylinder to Processkontroll Green Technology. Hexagon stated that approximately 1,000 additional cylinders were expected to be delivered to the customer within a 12-month period as biomethane infrastructure expanded in the Nordic region. While the application includes biomethane rather than only conventional CNG, the development demonstrates the growing commercial deployment of high-pressure carbon-fiber cylinder technology for gaseous-fuel storage and distribution.
The same trend is visible in vehicle applications. Hexagon Agility announced in July 2026 that it had signed an exclusive three-year agreement with IVECO BUS to supply complete CNG fuel systems across IVECO's global CNG bus range. The systems will incorporate Type 4 carbon-fiber cylinders, and the companies stated that their collaboration had already supported more than 10,000 CNG buses globally. This agreement strengthens the role of Type IV composite technology in the international CNG bus market.
CNG Tanks/Cylinders Market Geographical Outlook:
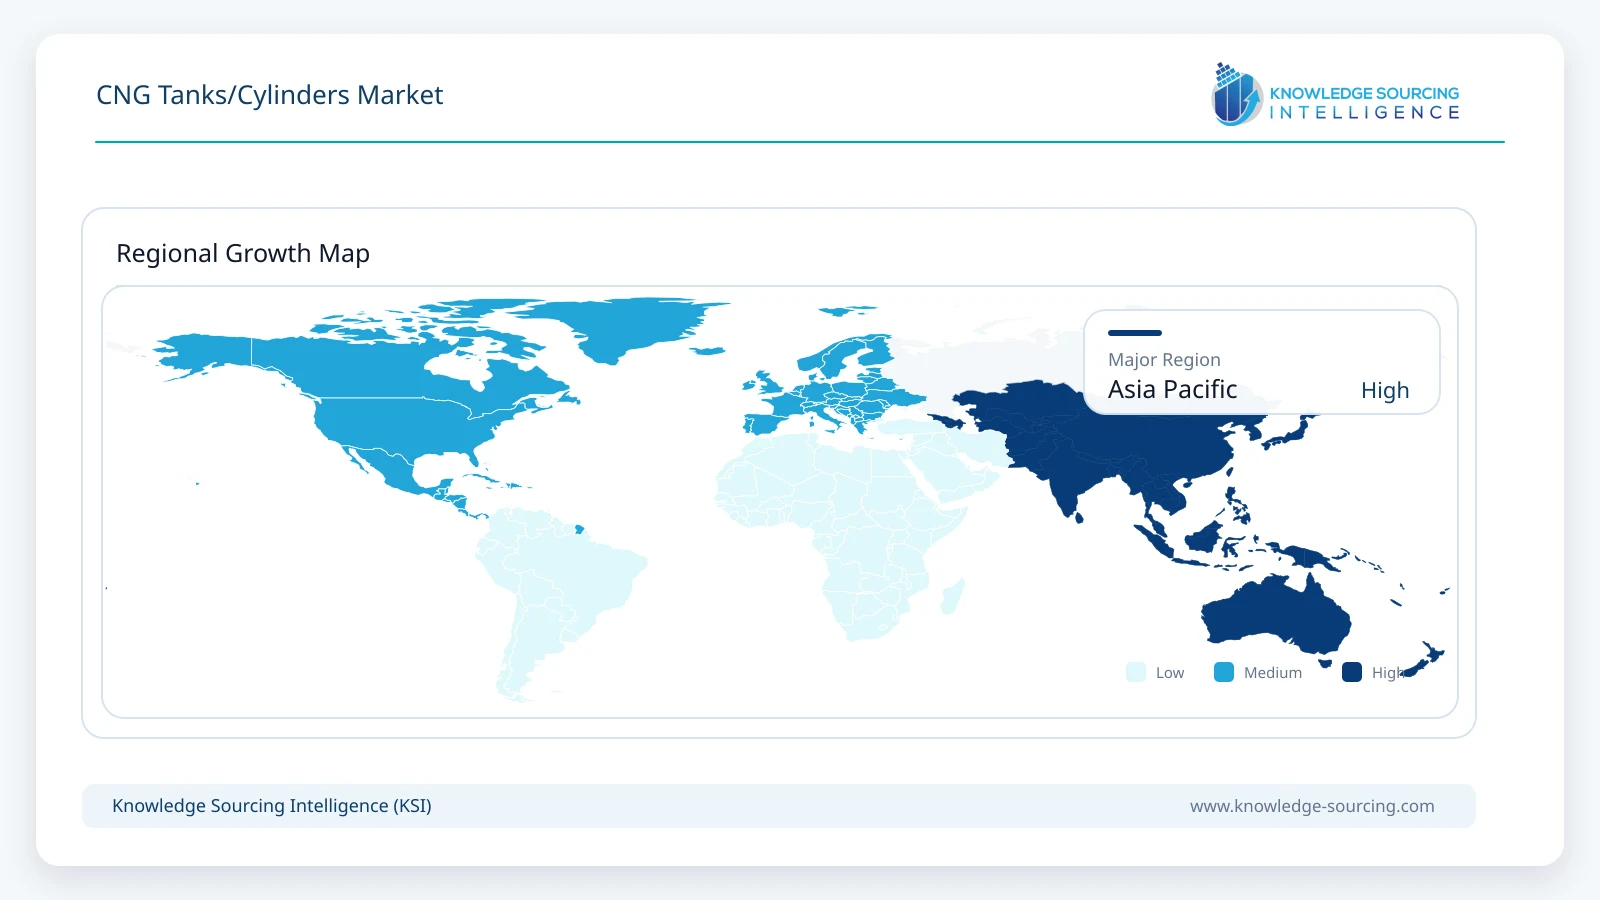
Asia Pacific is expected to remain a significant regional market, supported by expanding CNG infrastructure and vehicle adoption.
Asia Pacific is positioned as a major market for CNG tanks and cylinders because of its large vehicle population, urbanization, growing commercial transportation activity, and established natural-gas distribution networks. China, India, Japan, South Korea, and Southeast Asian markets have different CNG adoption profiles, but collectively they provide a broad base for cylinder demand across passenger vehicles, commercial fleets, buses, and industrial applications.
India is particularly important to the regional market. Government data indicates that CNG stations increased from 738 in 2014 to 7,720 in 2025, while city gas distribution coverage expanded to nearly 100% on a population and geographical-area basis under the cited government assessment. PNGRB's more recent June 2026 data shows that the number of CNG stations had reached 9,026, demonstrating continued infrastructure expansion after the 2025 level.
The scale of infrastructure development creates opportunities for both steel and composite-cylinder suppliers. Steel cylinders are likely to retain a strong position in applications where cost, established manufacturing infrastructure, and durability are major purchasing criteria. Composite cylinders can gain share where vehicle weight, range, payload, and packaging requirements justify their higher material and manufacturing costs.
India's policy environment also supports the regional outlook. During the first half of 2026, PNGRB's PNG Drive 2.0 generated 474 additional CNG stations and connected 32 new districts to the CGD supply network. In April 2026, the government also reported that more than 467 applications for CNG and CBG dispensing stations had been processed on a priority basis since March, with 157 final licences and 38 prior construction approvals granted. These developments indicate that CNG infrastructure expansion remains an active policy and investment priority.
China and other Asian markets are also relevant because of their large commercial vehicle populations and established gas-fuel ecosystems. The regional market is expected to increasingly differentiate between conventional steel cylinders and advanced composite systems as fleet operators focus on total cost of ownership, payload optimization, range, and regulatory compliance.
CNG Tanks/Cylinders Market Restraints:
High cylinder cost and material costs can restrain adoption of advanced CNG storage technologies
Cost remains an important constraint, particularly for Type III and Type IV composite cylinders. Carbon fiber and other advanced reinforcement materials can be considerably more expensive than conventional steel. Composite manufacturing also requires specialized winding, curing, inspection, testing, and quality-control processes. These factors can increase the initial cost of the vehicle fuel-storage system and slow adoption in price-sensitive passenger and commercial vehicle markets.
At the same time, the economics of CNG storage must be assessed at the complete vehicle-system level rather than only at the cylinder purchase price. A lighter cylinder can reduce vehicle weight, potentially improve operating efficiency, increase payload capacity, or enable greater fuel storage within a defined vehicle envelope. Consequently, higher upfront cylinder costs can be partially offset by operating benefits in high-utilization applications. The challenge for manufacturers is to reduce production costs while maintaining safety, durability, and certification performance.
Refuelling availability, driving range, and vehicle packaging constraints can limit CNG cylinder demand
CNG vehicles remain dependent on adequate refuelling infrastructure. Although CNG station networks are expanding rapidly in markets such as India, infrastructure availability can still vary by city, route, and geographic region. Commercial fleet operators with fixed routes may find CNG easier to adopt than private users or long-distance operators whose routes extend beyond established CNG corridors.
Vehicle range is also influenced by cylinder capacity and available packaging space. Increasing cylinder capacity can improve range but adds weight and may reduce usable cargo space. Smaller cylinders reduce weight and packaging requirements but can require more frequent refuelling. This creates an engineering trade-off between capacity, weight, range, cost, and available vehicle space.
Safety and compliance requirements also increase manufacturing complexity. CNG cylinders operate at high pressures and must meet applicable vehicle and pressure-vessel standards. Everest Kanto Cylinder Limited, for example, states that its Type I onboard CNG cylinders are manufactured to standards including ISO 11439, NZS 5454, ECE R110, and IS 15490, illustrating the level of technical and regulatory compliance expected from vehicle-cylinder manufacturers.
CNG Tanks/Cylinders Market Developments:
July 2026- Maruti Suzuki launched an updated Brezza with an S-CNG variant featuring a new underbody CNG tank configuration designed to preserve boot space. The company stated that the S-CNG model also includes Idle Start-Stop technology and achieves a claimed fuel efficiency of 26.9 km/kg. The development highlights the increasing importance of cylinder packaging and vehicle integration in passenger-car CNG applications.
July 2026- Hexagon Agility signed an exclusive three-year global agreement with IVECO BUS to supply complete CNG fuel systems for IVECO's global CNG bus range. The systems will incorporate advanced carbon-fiber Type 4 cylinders. Hexagon Agility and IVECO BUS stated that their collaboration has already supported the delivery of more than 10,000 CNG buses globally, while the new agreement extends the relationship across Europe, Latin America, Asia Pacific, Africa, and the Middle East. The development provides direct evidence of continued demand for Type IV composite CNG storage systems in public transportation.
July 2026- Tata Motors introduced the LPO 1620 CNG as part of its passenger mobility portfolio at Prawaas 5.0. The company also showcased its next-generation Ultra Prime and Starbus Prime ranges. The launch expands the company's current CNG offering in commercial passenger transportation and supports demand for CNG storage systems in bus applications.
June 2026- Tata Motors launched the Intra V40 with CNG-plus-petrol bi-fuel technology for small commercial vehicle and pickup applications. The vehicle uses a 110-litre CNG tank and offers a stated payload of 1,525 kg. The launch is significant for the CNG Tanks/Cylinders Market because it expands CNG storage demand into high-load last-mile commercial transportation, where tank capacity, payload, range, and packaging are critical purchase considerations.
CNG Tanks/Cylinders Market Future Outlook:
The CNG Tanks/Cylinders Market is expected to maintain a positive outlook as CNG infrastructure expands and manufacturers increasingly integrate natural-gas technology into passenger vehicles, commercial vehicles, buses, and fleet applications. The strongest opportunities are likely to emerge where CNG provides a practical balance between fuel economics, emissions performance, range, and infrastructure availability.
The market is also moving toward greater differentiation by cylinder construction. Type I steel cylinders are expected to remain important because of their established supply chain and cost advantages. However, Type III and Type IV composite cylinders are likely to gain strategic importance in applications where weight reduction and vehicle packaging are critical. The increasing adoption of carbon-fiber cylinders in bus and commercial-vehicle fuel systems, demonstrated by recent Hexagon Agility developments, supports this technology direction.
India is likely to remain a particularly important market because of the rapid expansion of CNG stations and CGD infrastructure. With 9,026 CNG stations reported by PNGRB as of June 2026 and continued station additions through government-supported initiatives, the country's installed base of CNG vehicles and associated cylinder demand is positioned for continued expansion.
The next phase of market development will increasingly depend on improving the total economics of CNG storage. Manufacturers will need to balance material costs, pressure performance, safety, durability, weight, capacity, and manufacturing scalability. For passenger vehicles, compact underbody configurations and improved packaging are likely to remain important. For buses and commercial vehicles, higher-capacity systems and lightweight composite cylinders can provide greater value by improving range and reducing the payload penalty associated with fuel storage.
Another important opportunity is the convergence of CNG and renewable natural gas. Biomethane and renewable natural gas can use much of the same high-pressure storage infrastructure as conventional natural gas, creating an additional addressable market for cylinder manufacturers. Hexagon Agility's 2026 carbon-fiber cylinder milestone and its activity in biomethane distribution demonstrate how high-pressure gas-storage technology is increasingly being applied across both mobility and stationary/mobile gas infrastructure.
Overall, the CNG Tanks/Cylinders Market is transitioning from a conventional steel-cylinder market toward a broader high-pressure gaseous-fuel storage ecosystem. Growth in CNG vehicles, commercial fleets, public transport, mobile gas distribution, and renewable gas applications will create opportunities across multiple cylinder types and capacities. Companies that combine manufacturing scale with advanced composite technology, safety certification, lightweight design, and integrated fuel-system capabilities are likely to be best positioned to capture future demand.
CNG Tanks/Cylinders Market Scope:
| Report Metric | Details |
|---|---|
| Forecast Unit | Billion |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Raw Material, Vehicle Type, Application, Material Type, Capacity, End-User, Geography |
| Companies |
|
Market Segmentation
By Raw Material
- Steel
- Aluminum
- Carbon Fiber Composites
- Glass Fiber Composites
- Others
By Vehicle Type
- Passenger Vehicles
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Buses and Public Transport Vehicles
By Application
- On-Board CNG Storage
- Stationary CNG Storage
- Mobile CNG Storage
- Others
By Material Type
- Type I (All-Metal Cylinder)
- Type II (Metal Liner with Hoop-Wrapped Composite)
- Type III (Metal Liner with Fully Wrapped Composite)
- Type IV (Polymer Liner with Fully Wrapped Composite)
By Capacity
- Up to 20 Liters
- 20 to 50 Liters
- Above 50 Liters
By End-User
- Transportation
- Industrial
- Commercial and Other Applications
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- Rest of Middle East and Africa
- Asia Pacific
- China
- Japan
- South Korea
- India
- Indonesia
- Rest of Asia Pacific
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base Year and Forecast Period
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.4.1. Bargaining Power of Suppliers
4.4.2. Bargaining Power of Buyers
4.4.3. Threat of New Entrants
4.4.4. Threat of Substitutes
4.4.5. Competitive Rivalry
4.5. Industry Value Chain Analysis
4.6. Future Market Outlook
5. CNG TANKS/CYLINDERS MARKET BY RAW MATERIAL
5.1. Introduction
5.2. Steel
5.3. Aluminum
5.4. Carbon Fiber Composites
5.5. Glass Fiber Composites
5.6. Others
6. CNG TANKS/CYLINDERS MARKET BY VEHICLE TYPE
6.1. Introduction
6.2. Passenger Vehicles
6.3. Light Commercial Vehicles
6.4. Medium and Heavy Commercial Vehicles
6.5. Buses and Public Transport Vehicles
7. CNG TANKS/CYLINDERS MARKET BY APPLICATION
7.1. Introduction
7.2. On-Board CNG Storage
7.3. Stationary CNG Storage
7.4. Mobile CNG Storage
7.5. Others
8. CNG TANKS/CYLINDERS MARKET BY MATERIAL TYPE
8.1. Introduction
8.2. Type I (All-Metal Cylinder)
8.3. Type II (Metal Liner with Hoop-Wrapped Composite)
8.4. Type III (Metal Liner with Fully Wrapped Composite)
8.5. Type IV (Polymer Liner with Fully Wrapped Composite)
9. CNG TANKS/CYLINDERS MARKET BY CAPACITY
9.1. Introduction
9.2. Up to 20 Liters
9.3. 20 to 50 Liters
9.4. Above 50 Liters
10. CNG TANKS/CYLINDERS MARKET BY END-USER
10.1. Introduction
10.2. Transportation
10.3. Industrial
10.4. Commercial and Other Applications
11. CNG TANKS/CYLINDERS MARKET BY GEOGRAPHY
11.1. Introduction
11.2. North America
11.2.1. United States
11.2.2. Canada
11.2.3. Mexico
11.3. South America
11.3.1. Brazil
11.3.2. Argentina
11.3.3. Rest of South America
11.4. Europe
11.4.1. Germany
11.4.2. United Kingdom
11.4.3. France
11.4.4. Spain
11.4.5. Italy
11.4.6. Rest of Europe
11.5. Middle East and Africa
11.5.1. Saudi Arabia
11.5.2. United Arab Emirates
11.5.3. Egypt
11.5.4. Rest of Middle East and Africa
11.6. Asia Pacific
11.6.1. China
11.6.2. Japan
11.6.3. South Korea
11.6.4. India
11.6.5. Indonesia
11.6.6. Rest of Asia Pacific
12. COMPETITIVE ENVIRONMENT AND ANALYSIS
12.1. Major Players and Strategy Analysis
12.2. Market Share Analysis
12.3. Mergers, Acquisitions, Agreements, and Collaborations
13. COMPANY PROFILES
13.1. Hexagon Agility
13.2. Faber Industrie
13.3. Everest Kanto Cylinder Limited
13.4. Praxair Technologies, Inc.
13.5. Maruti Koatsu Cylinders Limited
13.6. Indoruss Synergy Pvt. Ltd.
13.7. Quantum Fuel Systems
13.8. Beijing Sinocleansky Technologies Corp.
13.9. Anhui Clean Energy Co., Ltd.
13.10. Worthington Industries
Navigate
Trusted by the world's leading organizations











