
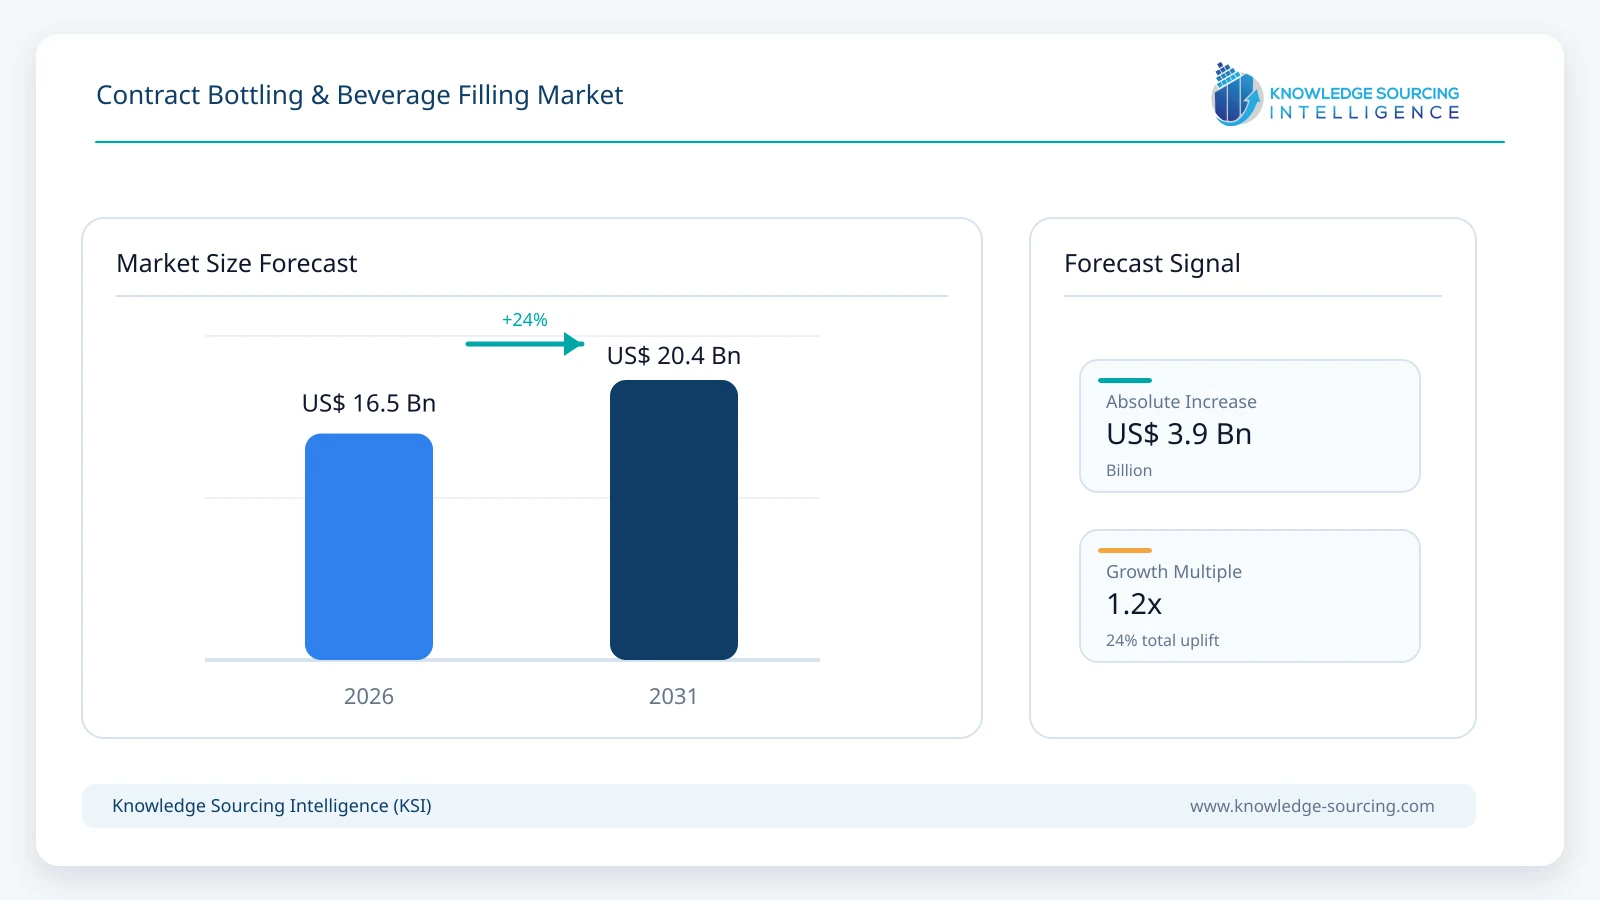
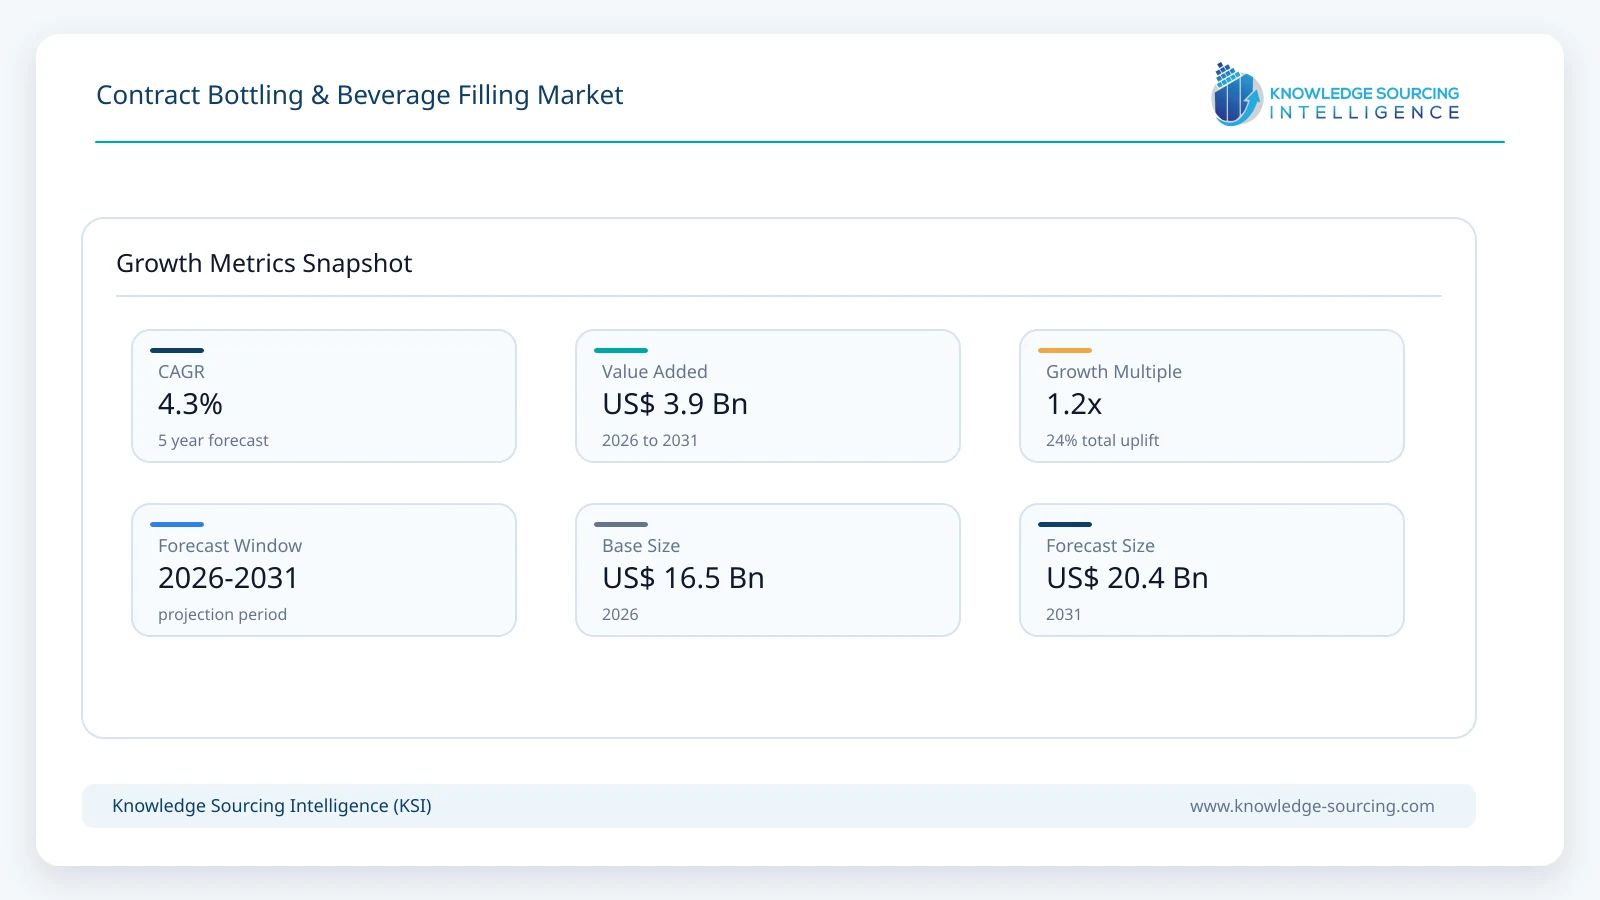
The Contract Bottling & Beverage Filling Market is expected to reach USD 20.4 billion in 2031, growing at a CAGR of 4.3% between 2026 and 2031, from USD 16.5 billion in 2026.
Highlights:
- 1Outsourcing enables Beverage brands to improve operational flexibility, particularly for new product launches, seasonal offerings, private-label products, and specialized packaging requirements.
- 2Sustainability is reshaping packaging requirements, encouraging contract fillers and bottlers to adopt recyclable materials, alternative formats, and packaging solutions with lower environmental impacts.
- 3Automation and digital technologies are transforming filling operations, supporting greater production flexibility, equipment efficiency, quality control, and faster adaptation to changing beverage formats.
- 4Demand for flexible manufacturing capabilities is increasing, as beverage companies introduce diverse products, packaging formats, and formulations while seeking efficient outsourced production and commercialization.
Market Overview
The contract bottling & beverage filling market is a crucial segment of the global beverage industry, providing outsourced manufacturing, filling, and packaging services that enable beverage brands to optimize capital allocation, accelerate product commercialization, and maintain operational flexibility in an increasingly competitive marketplace. The demand for production facilities is high, driven by both large multinational beverage corporations and start-up brands. These companies seek scalable production across beverage categories such as carbonated soft drinks, bottled water, juices, functional beverages, dairy-based drinks, alcoholic beverages, and ready-to-drink formulations.
The Coca-Cola Company stated that it increased its production of low- or no-calorie beverage portfolio, such as Coca-Cola Zero Sugar, to about 31 percent of its global beverage volume in 2025, while its beverage portfolio consists of water, sports, coffee, tea, juice, dairy, and plant-based beverages.
In addition, the growth is supported by fundamental changes in the industry, including an increase in private labels, shortening of product innovation cycles, and growing complexity of regulatory and sustainability compliance. These factors suggest that specialized contract bottlers with advanced technological capabilities and certified quality systems will be the primary beneficiaries.
The rising spending on automated filling lines, aseptic and high-speed canning technologies, digital quality assurance, and sustainable packaging solutions provides service differentiation while facilitating the building of long-term brand owner and contract bottler relationships.
Regulatory and sustainability standards are crucial factors that determine the company's operations in the contract bottling & beverage filling market. Hence, compliance works as a barrier to entry for new players and as a competitive differentiator for existing players.
Some of the main food safety and quality legislation are the FDA Food Safety Modernization Act (FSMA) in the U.S., EU Food Hygiene Regulations (EC 852/2004), Hazard Analysis and Critical Control Points (HACCP), ISO 22000 Food Safety Management Systems, BRCGS Global Standard for Food Safety, and FSSC 22000. These standards cover hygiene, traceability, and risk management in bottling plants.
Additionally, to improve their sustainable outlook, contractual bottlers are gradually aligning with frameworks such as ISO 14001 Environmental Management Systems, ISO 50001 Energy Management, EU Packaging and Packaging Waste Directive, Extended Producer Responsibility (EPR) regulations, and global initiatives like the UN Sustainable Development Goals (SDGs).
Brooklyn Bottling Group, Refresco Holding, G3 Enterprises Inc., Western Innovations Inc., CSD Copackers, TLC Beverage Brands, Big Brands, LLC, Pomona Bottling Group, DrinkPAK, and Assemblies Unlimited Inc. together cover a wide spectrum of the key players in the Contract Bottling & Beverage Filling Market. Their range extends from large multinational operators to specialized regional and niche service providers. They offer services such as contract bottling, filling, and packaging of drinks in various categories, including carbonated soft drinks, bottled water, functional beverages, alcoholic drinks, and ready-to-drink products. At the same time, they cater to different packaging formats like bottles, cans, and cartons.
Market Drivers
Expansion of Health, Functional, and Premium Beverage Segments
The expansion of health, functional, and premium beverage segments is a leading growth driver in the contract bottling & beverage filling market. Changing consumer lifestyles, along with a growing emphasis on preventive health, are driving demand for beverage products that provide nutritional benefits, have clean-label formulations, and come with an enhanced and premium lifestyle positioning.
Similarly, increasing self-consciousness among consumers is driving the demand for vitamin- and mineral-fortified drinks, probiotics, and plant-based and dairy-alternative beverages, which requires specialized beverage manufacturing and filling processes, prompting the need for contract bottlers and beverage fillers.
The development of health, functional, and premium beverages is increasingly associated with the rise in global prevalence of obesity and the growing consumer awareness of the health risks that come with diets, thus driving a change in beverage consumption patterns and production strategies.
According to the World Health Organization (WHO) data from December 2025, the number of people globally living with obesity was more than one billion.
Additionally, the World Obesity Atlas 2026 report estimated that the number of children aged 5-19 years living with obesity in the world will rise to 228 million by 2040 from 177 million in 2025, while prevalence is rising from 8.7% to11.9% from 2025 to 2040. ?
Contract bottlers are increasingly seen as strategic production partners who support faster product launches, offer greater flexibility, and provide scalability while also ensuring regulatory compliance and consistent quality. This makes them indispensable for capturing growth opportunities in the rapidly evolving health, functional, and premium beverage categories.
Expansion of beverage brand outsourcing models.
Many beverage companies are prioritizing asset-light operating structures. Rather than committing capital to manufacturing facilities, brands increasingly allocate investment toward product development, marketing, digital commerce, and distribution expansion. This trend is particularly visible among emerging beverage companies and premium niche brands. Contract bottlers benefit because they provide immediate production capability without lengthy facility construction or equipment procurement cycles.
Growing complexity of beverage portfolios.
The number of stock-keeping units within beverage categories continues to increase. Functional beverages, energy drinks, plant-based beverages, flavored waters, low-alcohol products, and premium ready-to-drink offerings require varied filling specifications and packaging formats. Frequent product changes make dedicated in-house production less efficient for many brand owners. Contract fillers capable of rapid line changeovers and multi-format packaging are capturing a larger share of outsourced production volumes.
Rising demand for packaged water and health-oriented beverages.
Consumer demand has shifted toward bottled water, reduced-sugar products, sports drinks, functional beverages, and fortified formulations. These categories often require specialized filling environments, ingredient handling systems, and quality controls. Contract bottlers have expanded capabilities to accommodate these requirements, increasing their strategic importance within beverage supply chains.
Investment in multi-format packaging infrastructure.
Beverage consumption increasingly spans bottles, cans, cartons, and specialty packaging. Contract fillers are investing in production lines capable of handling multiple formats within the same facility. This capability helps beverage companies respond more quickly to changing retailer requirements and consumer preferences. It also reduces packaging-related operational risks.
Retail and distribution channel expansion.
Modern retail networks, convenience stores, foodservice channels, and e-commerce platforms continue to broaden beverage distribution opportunities. Wider distribution creates larger production requirements while increasing service expectations. Beverage companies often require geographically distributed manufacturing partners capable of supporting regional demand fluctuations and rapid replenishment cycles.
Market Restraints and Challenges
Packaging material cost volatility.
Contract bottlers remain exposed to fluctuations in aluminum, PET resin, glass, paperboard, and transportation costs. Packaging frequently represents one of the largest components of beverage production expenses. Sudden cost increases can compress margins when customer contracts limit immediate price adjustments.
Stringent food safety and quality requirements.
Food safety regulations continue to become more demanding across major beverage-producing regions. Compliance requires investments in traceability systems, testing protocols, sanitation controls, workforce training, and certification programs. Smaller contract fillers may face greater financial pressure when meeting evolving regulatory standards.
High capital requirements for production upgrades.
Modern filling facilities require substantial investment in automated filling systems, packaging equipment, inspection technologies, and warehouse infrastructure. Multi-format production capability further increases capital requirements. Smaller providers may struggle to finance upgrades while maintaining competitive pricing.
Capacity balancing challenges.
Demand patterns can vary considerably across beverage categories and seasons. Bottled water, alcoholic beverages, carbonated drinks, and specialty beverages often experience different production cycles. Maintaining optimal utilization rates while preserving capacity flexibility remains a recurring operational challenge for contract bottlers.
Customer concentration risks.
Some contract manufacturers derive a substantial portion of revenue from a limited number of beverage brands. The loss of a major customer, supplier consolidation, or shifts toward in-house production can materially affect facility utilization and profitability. Larger providers increasingly diversify customer portfolios to reduce this exposure.
Major Market Segment
Paper & Paperboard
By material, the contract bottling & beverage filling market is segmented into plastic, glass, metal, paper & paperboard, and others. The paper & paperboard segment is expected to grow significantly, fueled by the growing transition towards eco-compatible materials.
Investment in sustainable beverage packaging driven by changing consumer preferences has shaped the overall market outlook. The paper & paperboard segment is anticipated to grow consistently, fueled by constant regulatory pressure to support low-carbon packaging.
The growing sustainability shift in beverage packaging has played a key role in expanding the adoption scope of paper & paperboard material in contract bottling and filling. Likewise, packaging firms such as Frugalpac have capitalized on this trend by investing in paper bottles to decarbonize beverage sector.
Regulatory support provided through EPR (Extended Producer Responsibility) schemes has inclined the market shift from PET bottles towards multi-layer paperboard cartons and fiber-based bottles globally.
Besides the low-carbon content offered by paper bottles, the low breakage and maintenance also offer logistics advantages, which have positively influenced their adoption in contract bottling and filling. Hence, major beverage brands, namely Diageo, Unilever, and PepsiCo, are investing in such packaging media.
Technological progress and brand commitments have encouraged beverage manufacturers to upgrade their packaging options. For instance, in July 2026, SalzburgMilch launched its children’s beverage products “Alex” and “Lisa” in SIG’s DomeMini aseptic filling cartons in Europe. In addition to being a dairy producer, the company also acts as a contract filler for plant-based alternatives in the EU.
Implementation of “Packaging and Packaging Waste Regulations” has provided a framework to reduce packaging waste volume in regions like Europe. A similar trend is emerging across other major global economies, which is expected to have a direct impact on paper-based contract bottling and filling solutions.
Non-Alcoholic Beverages
The non-alcoholic beverage segment represents the most commercially important demand category for contract bottling and beverage filling services. The segment encompasses carbonated drinks, bottled water, fruit juices, sports beverages, energy drinks, flavored waters, and functional beverages. Unlike many alcoholic beverage categories, non-alcoholic beverages generally involve higher production frequencies, broader retail distribution, and larger packaging volumes.
Purchasing criteria within this segment extend beyond filling costs. Beverage companies require strict quality assurance, high production consistency, rapid changeover capability, and access to multiple packaging formats. Bottled water producers may prioritize throughput efficiency and cost competitiveness, while functional beverage manufacturers often place greater emphasis on formulation integrity, ingredient handling, and smaller production batches.
Product innovation is particularly active within this segment. Reduced-sugar beverages, fortified drinks, protein-based products, and wellness-oriented formulations continue to expand category complexity. Contract fillers that support frequent product launches and short-run production schedules are increasingly differentiated from providers focused solely on high-volume manufacturing.
The segment also influences investment decisions across the broader market. New canning lines, aseptic filling systems, PET bottling facilities, and automated quality-control platforms are frequently justified by anticipated demand from non-alcoholic beverage customers.
Geographical Outlook
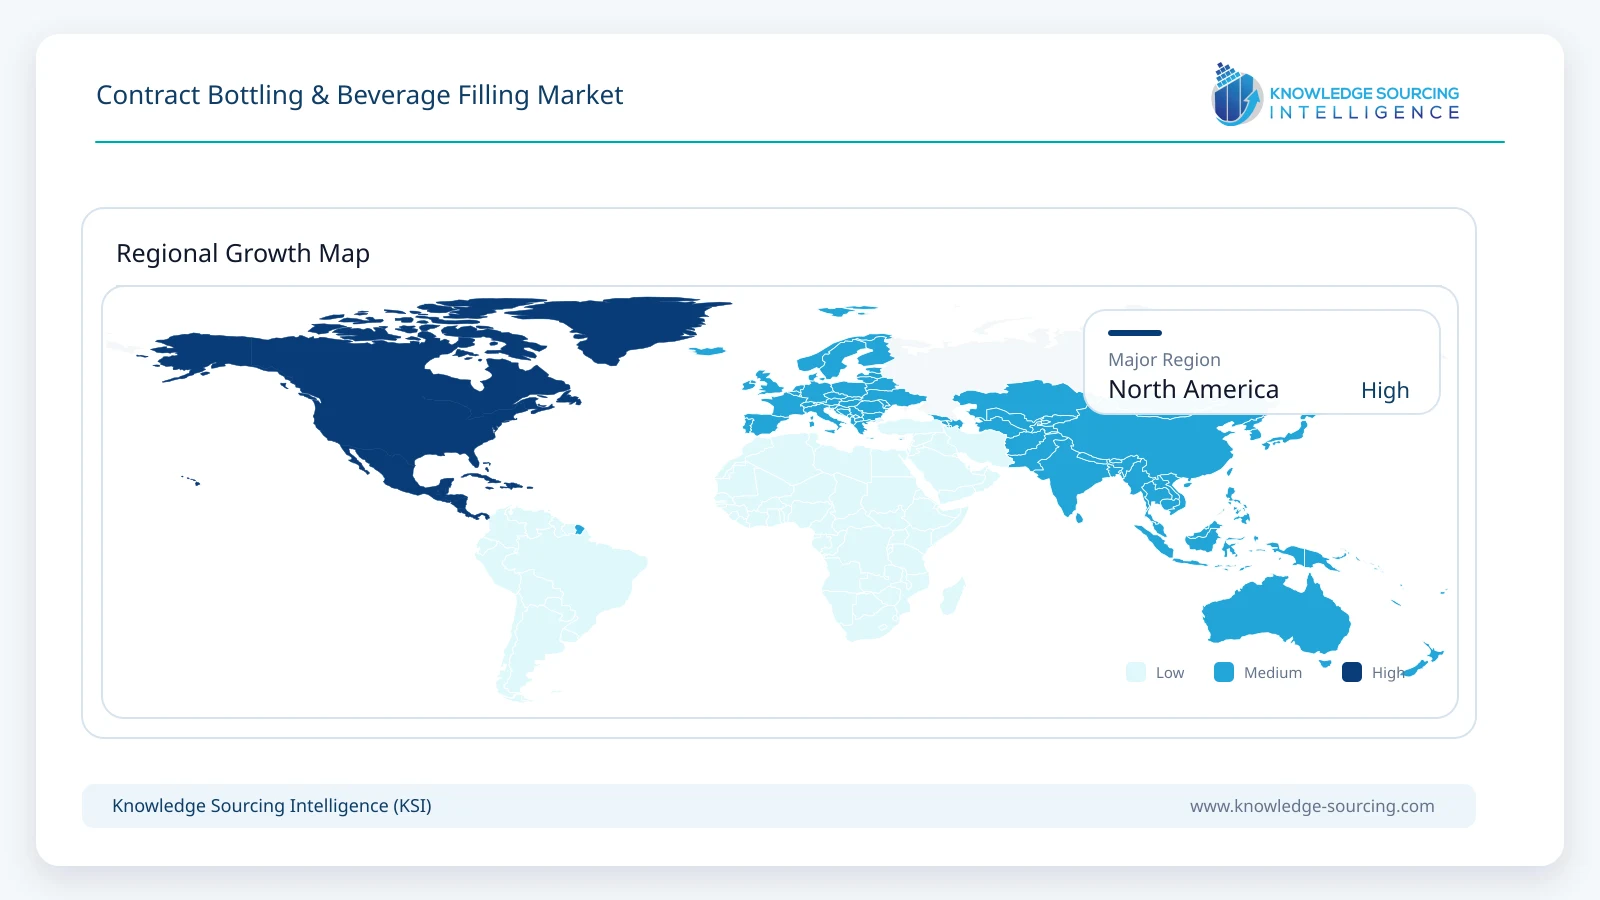
Region | Main Demand Signal | Principal Constraint |
North America | High outsourcing penetration and beverage innovation activity | Labor and operating cost pressures |
Europe | Sustainability regulations and premium beverage production | Regulatory complexity and energy costs |
Asia Pacific | Expanding packaged beverage consumption and manufacturing investment | Supply-chain fragmentation |
South America | Rising packaged beverage demand and regional brand expansion | Economic volatility |
Middle East and Africa | Growing bottled water consumption and food manufacturing investment | Infrastructure and logistics limitations |
North America: the US
The United States contract bottling & beverage filling market is projected to show significant growth fueled by strong clinical research investment.
The presence of a strong consumer landscape, followed by continued efforts undertaken by the governing authorities to implement EPR schemes for packaging across US states, has outlined the quality standards to be adopted by contract fillers in the country.
Similarly, improved beverage consumption, followed by growing brand proliferation, has positively influenced the demand for customized beverage packaging in the United States. According to the Beverage Marketing Corporation, consumption of major beverages such as bottled water grew by 2.5% in 2025.
Capacity expansion by domestic contract fillers has accelerated market transparency in the US. For instance, in 1st September 2026, JBM Packaging opened its 52,500 sq ft facility in Lebanon, Ohio, which expanded its contract packaging operations in the United States.
Likewise, global players such as Refresco enjoy a wide customer base in the United States by forming strategic collaborations with major beverage manufacturers, and the recent acquisition of SunOpta has further expanded the company’s business footprint. In 22nd September 2026, the company expanded its production line at its Midlothian, Texas, facility.
The regulatory shift towards eco-friendly packaging and positive e-commerce growth has also transformed the market landscape, with beverage manufacturers relying on contract fillers to achieve customized packaging that matches dynamic market trends.
Europe
Packaging sustainability regulations are influencing supplier strategies throughout Europe. Recycled-content requirements, extended producer responsibility programs, and packaging waste directives are encouraging investments in recyclable materials and production efficiency. Demand remains strong across bottled water, alcoholic beverages, and premium functional drink categories.
Asia Pacific
China, India, Japan, South Korea, Indonesia, and Thailand continue to support expanding beverage production. Urbanization, rising disposable income, modern retail development, and packaged beverage consumption contribute to demand growth. International beverage companies are also expanding regional production networks to improve supply resilience and reduce transportation costs.
South America
Brazil represents the largest regional opportunity due to its extensive beverage manufacturing sector and consumer base. Contract filling demand is supported by bottled water, carbonated beverages, juices, and alcoholic products. Economic cycles and currency fluctuations remain important operational considerations.
Middle East and Africa
Bottled water consumption remains a major demand driver in several Middle Eastern markets due to climatic conditions and population growth. Governments are also encouraging food and beverage manufacturing investment to strengthen domestic production capabilities. Infrastructure development continues to improve long-term market prospects, although logistics constraints remain uneven across the region.
Competitive Landscape
The contract bottling and beverage filling market exhibits a mixed competitive structure. Large multinational providers operate alongside regional specialists and niche packaging contractors. Scale provides advantages in purchasing power, customer acquisition, and geographic coverage, while smaller providers often compete through flexibility, customer service, and specialized production capabilities.
Refresco Holding represents one of the most established participants in outsourced beverage manufacturing and competes through extensive production capacity, broad packaging capabilities, and multinational customer relationships. The company's strategy reflects growing customer demand for integrated manufacturing and supply-chain support.
G3 Enterprises, Inc. maintains a strong presence in wine-related bottling operations, while Tjoapack emphasizes specialized filling and packaging capabilities. Companies such as Brooklyn Bottling Group and Pomona Bottling Group compete through regional manufacturing networks and beverage production expertise.
Competition increasingly centers on:
Multi-format packaging capability
Production flexibility
Food safety certification
Geographic proximity to customers
Sustainability performance
Automation and operational efficiency
Supply-chain integration
Speed of product commercialization
Barriers to entry remain moderate to high due to equipment costs, regulatory requirements, quality assurance obligations, and customer qualification processes.
Key Developments
June 2026: The Alkaline Water Company signed an LOI to acquire Eureka Beverages, a Canadian bottling and canning co-packer. The move expands contract filling capacity and strengthens North American private-label beverage manufacturing operations.
May 2026: Refresco completed the acquisition of SunOpta, expanding its North American beverage contract manufacturing and filling network. The deal strengthens aseptic bottling, plant-based beverage processing, and co-packing capacity across multiple high-growth drink categories.
April 2026: Nepra Foods entered a non-binding LOI to acquire Artesian Fusion’s bottling and co-packing assets in Idaho. The transaction adds water sourcing, bottling infrastructure, and contract beverage filling capabilities for private-label expansion.
January 2026: Valencia Nutrition commissioned Phase II of its PET bottle manufacturing and beverage filling facility in Hyderabad. The expansion increases high-speed bottling capacity for juice and functional drinks under contract manufacturing arrangements.
November 2025: Redwood Beverage Group acquired a large West Sacramento beverage co-packing facility previously operated by Manna Beverages. The asset adds large-scale contract bottling capacity for teas, juices, energy drinks, and packaged water.
2025: Refresco, the global independent beverage solutions provider, announced that it has agreed to acquire Telemark Kildevann Holding AS, a leading Norwegian beverage manufacturer. This transaction is subject to regulatory approval.
Regulatory and Policy Environment
Food safety regulations remain among the most influential factors affecting contract bottling operations. Compliance requirements generally include traceability systems, sanitation controls, ingredient monitoring, packaging verification, and recall management procedures. Regulatory compliance affects facility design, equipment selection, workforce training, and operating costs.
Packaging policy is becoming increasingly important. Extended producer responsibility programs, recycled-content mandates, deposit-return systems, and packaging waste reduction targets are altering packaging procurement decisions across major markets. Contract bottlers are adapting by investing in recyclable materials, lightweight packaging solutions, and more efficient production systems.
Alcoholic beverage filling operations face additional labeling, taxation, and distribution requirements that vary by jurisdiction. Suppliers serving multinational customers must manage differing compliance obligations across countries, increasing administrative complexity.
Environmental regulations also influence water usage, wastewater treatment, emissions management, and energy consumption. Facilities capable of demonstrating strong environmental performance may gain advantages during supplier qualification processes.
Outlook and Strategic Implications
Contract bottling and beverage filling services are expected to become increasingly integrated within beverage supply chains during the 2026-2031 period. Product diversification, packaging complexity, and capital discipline among beverage companies are likely to support continued outsourcing activity across both alcoholic and non-alcoholic categories.
Several factors will determine competitive performance during the forecast period:
Ability to support multiple packaging formats within a single facility.
Investment in automation and production efficiency.
Access to reliable packaging material supply.
Compliance with evolving food safety and sustainability regulations.
Geographic proximity to key consumer markets.
Capability to manage short production runs and rapid product launches.
The market is gradually shifting from pure manufacturing outsourcing toward broader production partnerships. Beverage companies increasingly expect contract bottlers to provide packaging procurement, logistics coordination, quality management, regulatory support, and commercialization assistance. Providers capable of delivering these integrated services are likely to secure stronger customer relationships and greater participation in future beverage product launches.
From a strategic perspective, capacity flexibility may become as important as production scale. Beverage categories continue to fragment, and customer demand increasingly favors suppliers that can balance efficiency with responsiveness. Companies that combine operational reliability, regulatory compliance, and multi-format production capability are expected to be best positioned to capture future contract manufacturing opportunities.
Contract Bottling and Beverage Filling Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 16.5 billion |
| Total Market Size in 2031 | USD 20.4 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 4.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Packaging Type, Material, Beverage Type, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Packaging Type
Bottles
Cans
Cartons
Pouches
Others
By Material
Plastic
Glass
Metal
Paper & Paperboard
Others
By Beverage Type
Alcoholic
Wine
Beer
Spirits
Other Alcoholic Beverages
Non-Alcoholic
Carbonated Drinks
Fruit Juice
Bottled Water
Energy & Sports Drinks
Tea & Coffee / RTD Beverages
Dairy & Plant-Based Beverages
Functional & Other Beverages
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Taiwan
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. MARKET DYNAMICS
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
4. BUSINESS LANDSCAPE
4.1. Regulatory & Standards Landscape
4.2. Contract Bottling & Beverage Filling Ecosystem
4.3. Beverage Ingredients & Packaging Supply Chain
4.4. Import/Export Analysis
4.5. Strategic Recommendation
5. TECHNOLOGICAL OUTLOOK
5.1. High-Speed & Flexible Beverage Filling Technologies
5.2. Aseptic & Extended-Shelf-Life Filling Technologies
5.3. Hot-Fill, Cold-Fill & Carbonated Beverage Filling Technologies
5.4. High-Pressure Processing & Non-Thermal Technologies
5.5. Smart Filling & Automated Production Systems
5.6. Digitalization, AI & Digital-Twin Technologies
6. CONTRACT BOTTLING & BEVERAGE FILLING MARKET BY PACKAGING TYPE (2021-2031)
6.1. Introduction
6.2. Bottles
6.3. Cans
6.4. Cartons
6.5. Pouches
6.6. Others
7. CONTRACT BOTTLING & BEVERAGE FILLING MARKET BY MATERIAL (2021-2031)
7.1. Introduction
7.2. Plastic
7.3. Glass
7.4. Metal
7.5. Paper & Paperboard
7.6. Others
8. CONTRACT BOTTLING & BEVERAGE FILLING MARKET BY BEVERAGE TYPE (2021-2031)
8.1. Introduction
8.2. Alcoholic
8.2.1. Wine
8.2.2. Beer
8.2.3. Spirits
8.2.4. Other Alcoholic Beverages
8.3. Non-Alcoholic
8.3.1. Carbonated Drinks
8.3.2. Fruit Juice
8.3.3. Bottled Water
8.3.4. Energy & Sports Drinks
8.3.5. Tea & Coffee / RTD Beverages
8.3.6. Dairy & Plant-Based Beverages
8.3.7. Functional & Other Beverages
9. CONTRACT BOTTLING & BEVERAGE FILLING MARKET BY GEOGRAPHY (2021-2031)
9.1. Introduction
9.2. North America
9.2.1. By Packaging Type
9.2.2. By Material
9.2.3. By Beverage Type
9.2.4. By Country
9.2.4.1. United States
9.2.4.2. Canada
9.2.4.3. Mexico
9.3. South America
9.3.1. By Packaging Type
9.3.2. By Material
9.3.3. By Beverage Type
9.3.4. By Country
9.3.4.1. Brazil
9.3.4.2. Argentina
9.3.4.3. Others
9.4. Europe
9.4.1. By Packaging Type
9.4.2. By Material
9.4.3. By Beverage Type
9.4.4. By Country
9.4.4.1. Germany
9.4.4.2. United Kingdom
9.4.4.3. France
9.4.4.4. Italy
9.4.4.5. Spain
9.4.4.6. Others
9.5. Middle East and Africa
9.5.1. By Packaging Type
9.5.2. By Material
9.5.3. By Beverage Type
9.5.4. By Country
9.5.4.1. Saudi Arabia
9.5.4.2. UAE
9.5.4.3. Others
9.6. Asia Pacific
9.6.1. By Packaging Type
9.6.2. By Material
9.6.3. By Beverage Type
9.6.4. By Country
9.6.4.1. China
9.6.4.2. Japan
9.6.4.3. India
9.6.4.4. South Korea
9.6.4.5. Indonesia
9.6.4.6. Taiwan
9.6.4.7. Thailand
9.6.4.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Refresco Holding B.V.
11.2. Brooklyn Bottling Corp.
11.3. G3 Enterprises, Inc.
11.4. Pomona Bottling Group UG (haftungsbeschränkt)
11.5. DrinkPAK
11.6. Big Brands LLC
11.7. TLC Beverage Brands Company
11.8. Western Innovations, Inc.
11.9. CSD Co-Packers LLC
11.10. Assemblies Unlimited, Inc.
12. RESEARCH METHODOLOGY
13. LIST OF FIGURES
14. LIST OF TABLES





Frequently asked questions
What is the projected market size and growth for 2026-2031?
Market reaches $20.4 billion by 2031, growing at 4.3% CAGR from $16.5 billion.
What are the primary growth drivers in this market?
Outsourcing flexibility, sustainability, automation, and diverse product demand drive growth.
How does sustainability impact contract bottling operations?
Sustainability drives adoption of recyclable materials and lower environmental impact solutions.
What technological advancements are shaping the market?
Automation, digital technologies, and high-speed canning are transforming operations.
Which types of beverages utilize contract bottling services?
Services cover carbonated, water, juices, functional, dairy, and alcoholic beverages.
What key challenges or differentiating factors exist for bottlers?
Regulatory and sustainability compliance act as both barriers and differentiators.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Contract Bottling & Beverage Filling Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/contract-bottling-beverage-filling-market