
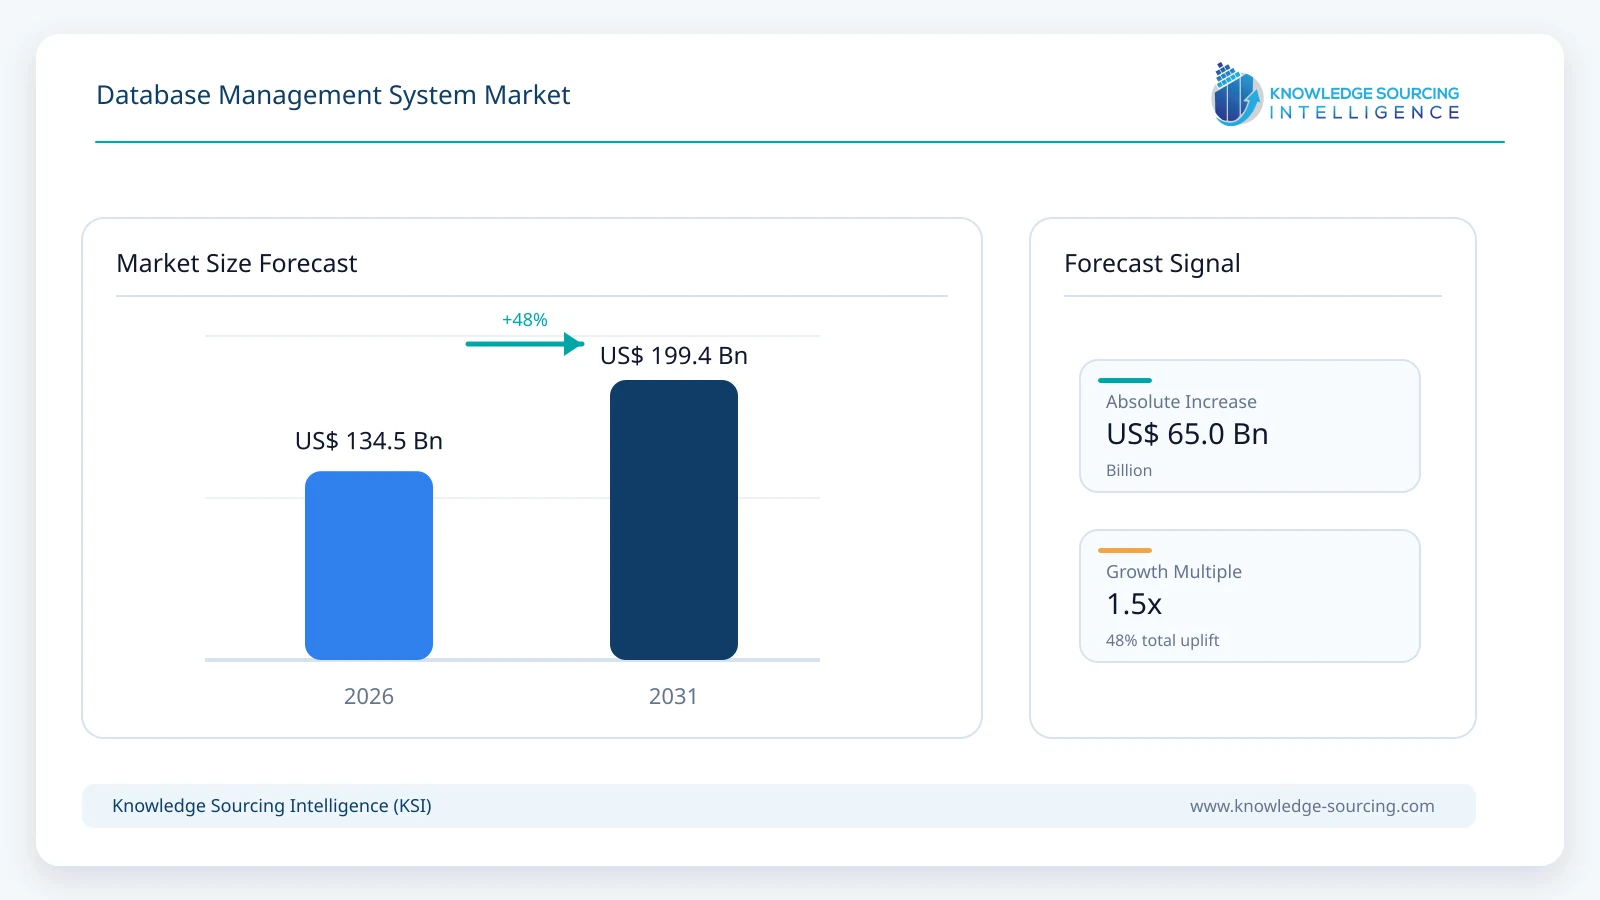
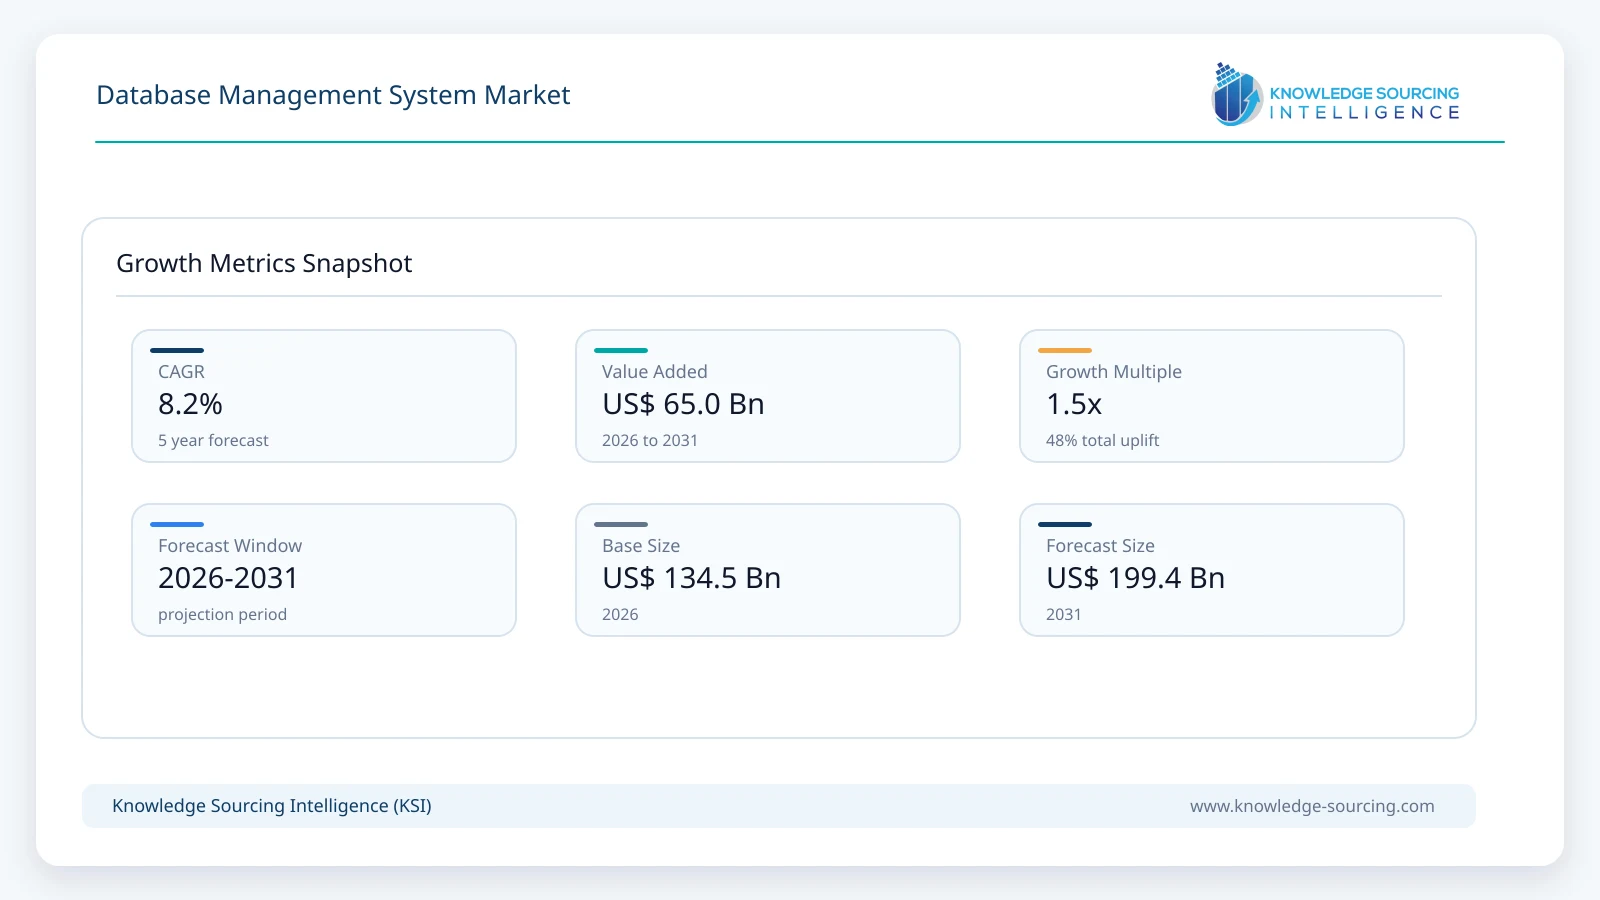
The Database Management System market is forecast to grow at a CAGR of 8.20%, reaching USD 199.45 billion in 2031 from USD 134.49 billion in 2026.
Highlights:
- 1Growing enterprise data volumes and AI adoption continue to accelerate investment in modern database infrastructure.
- 2Cloud deployment represents the leading commercial opportunity as organizations expand managed database services.
- 3Relational Database Management Systems (RDBMS) remain the largest revenue-generating database category due to widespread enterprise application adoption.
- 4Asia Pacific is expected to record strong investment activity supported by cloud infrastructure expansion and enterprise digitalization.
- 5Data privacy regulations are strengthening demand for secure, compliant database platforms with advanced governance capabilities.
- 6Competition increasingly focuses on cloud integration, automation, multi-cloud compatibility, and AI-enabled database administration.
The database management system (DBMS) market forms the foundation of modern enterprise information architecture by enabling organizations to store, organize, secure, retrieve, and analyze structured and unstructured data across business applications. As enterprises generate data from cloud applications, connected devices, digital commerce, industrial automation, financial transactions, and artificial intelligence (AI) workloads, database platforms have become strategic infrastructure rather than back-office software. Organizations are investing in database modernization to improve scalability, ensure high availability, strengthen cybersecurity, and support real-time analytics while reducing operational complexity.
Demand is increasingly shifting from traditional database deployments toward cloud-native, distributed, and multi-model database architectures. Enterprise buyers now prioritize elasticity, workload automation, resilience, and integration with analytics, AI, and application development environments instead of evaluating databases solely on storage performance. Procurement decisions are also influenced by total cost of ownership, regulatory compliance, disaster recovery capabilities, and vendor ecosystem maturity. Hybrid deployment models remain common because many organizations continue to operate mission-critical applications on-premises while expanding cloud infrastructure for new digital initiatives.
The industry structure includes established enterprise software vendors alongside specialized database technology providers offering relational, NoSQL, NewSQL, graph, document, and object-oriented database platforms. Cloud hyperscalers continue to strengthen their position by integrating database services into broader cloud ecosystems, encouraging customers to adopt managed database offerings that reduce infrastructure administration. At the same time, enterprises increasingly avoid dependence on a single vendor by adopting multi-cloud data strategies that improve operational flexibility.
Industry demand is particularly strong across banking, healthcare, telecommunications, manufacturing, retail, and government sectors where uninterrupted access to accurate, secure, and compliant data directly influences operational performance. Financial institutions require databases capable of processing millions of transactions while maintaining regulatory compliance. Healthcare organizations rely on high-performance database systems to support electronic health records, medical imaging, genomics research, and connected healthcare platforms. Manufacturers deploy databases to manage industrial automation, predictive maintenance, and production planning, while retailers require scalable platforms supporting omnichannel commerce and personalized customer engagement.
Data governance has become another major purchasing consideration. Organizations face growing obligations to protect customer information, manage cross-border data transfers, maintain audit trails, and demonstrate regulatory compliance. Consequently, buyers increasingly evaluate encryption, identity management, backup automation, access controls, and compliance reporting as essential database capabilities rather than optional features.
The market also reflects broader enterprise investment in AI. Generative AI, machine learning, recommendation engines, and predictive analytics require databases capable of supporting vector search, distributed processing, and high-volume transactional workloads simultaneously. Vendors are responding by integrating AI-assisted administration, automated indexing, intelligent query optimization, and workload management into their platforms, reducing operational overhead while improving application performance.
Market Drivers
Expansion of Cloud-Native Enterprise Applications
Organizations continue migrating enterprise resource planning, customer relationship management, digital commerce, and analytics workloads to cloud environments. These applications require highly available, elastic database services capable of supporting fluctuating workloads without manual infrastructure provisioning. Enterprises increasingly prefer managed database platforms that reduce administrative overhead while improving service availability. Vendors respond by expanding cloud-native database portfolios, introducing automated scaling, continuous backup, and integrated monitoring capabilities. This shift supports recurring subscription revenue while encouraging long-term customer relationships.
Artificial Intelligence and Advanced Analytics Requirements
AI adoption has substantially altered enterprise database requirements. Traditional transactional databases are being complemented by platforms capable of supporting real-time analytics, vector search, and machine learning pipelines. Enterprises increasingly seek database architectures that combine transactional consistency with analytical performance, enabling AI models to access current operational data. Database suppliers continue integrating AI-assisted administration and intelligent workload optimization to reduce database administration costs while improving operational efficiency.
Growing Regulatory Focus on Data Governance
Governments worldwide continue strengthening data protection legislation covering personal information, financial records, and critical infrastructure. Enterprises therefore invest in database systems offering encryption, access management, immutable backups, auditing, and regulatory reporting capabilities. Compliance requirements have transformed database modernization from an IT upgrade into a business risk management initiative. Vendors increasingly differentiate their platforms through governance automation, policy enforcement, and integrated security services.
Growth of Digital Financial Services
Banking institutions, payment processors, insurance providers, and financial technology companies require databases capable of maintaining transactional integrity with minimal downtime. Real-time payments, fraud detection, open banking initiatives, and digital lending platforms generate continuous demand for highly resilient database platforms. Financial institutions prioritize high availability, disaster recovery, and regulatory compliance, encouraging sustained investment in enterprise-grade database technologies.
Market Restraints and Challenges
Complexity of Legacy Database Migration
Many enterprises operate business-critical applications built on legacy database platforms developed over several decades. Migrating these environments involves application redesign, data validation, testing, and operational risk. Downtime concerns frequently delay modernization projects, particularly within highly regulated industries. Vendors increasingly provide migration automation tools, compatibility services, and consulting support to reduce implementation risks.
Rising Database Administration Skills Gap
Modern distributed databases require expertise spanning cloud architecture, cybersecurity, automation, performance tuning, and data governance. Many organizations struggle to recruit experienced database professionals capable of managing increasingly complex hybrid environments. This shortage increases implementation costs and slows deployment schedules. Suppliers continue introducing low-code administration, AI-driven optimization, and autonomous database capabilities to address workforce limitations.
Vendor Lock-In Concerns
Organizations adopting managed cloud databases often become closely integrated with specific cloud ecosystems. Migration between providers can involve application redesign, data conversion, and operational disruption. Enterprises increasingly evaluate interoperability, open-source compatibility, and multi-cloud deployment flexibility before selecting database vendors. Providers are responding by improving portability and supporting industry-standard interfaces.
Escalating Cybersecurity Risks
Database platforms remain primary targets for ransomware, insider threats, and unauthorized access because they contain valuable business and customer information. Organizations must continuously invest in encryption, privileged access management, monitoring, and recovery capabilities. Security investments increase operational expenditure while extending procurement evaluation cycles.
Major Segment Analysis
Cloud Deployment
Cloud deployment represents the most commercially important segment because it fundamentally changes how enterprises procure, operate, and scale database infrastructure. Rather than purchasing dedicated hardware and maintaining internal database environments, organizations increasingly consume managed database services that automate provisioning, upgrades, backups, monitoring, and disaster recovery.
Demand is strongest among enterprises pursuing application modernization, digital customer engagement, and AI implementation. Buyers prioritize operational flexibility, consumption-based pricing, geographic redundancy, and seamless integration with cloud-native development tools. These purchasing priorities are particularly relevant for organizations experiencing unpredictable workloads, seasonal demand fluctuations, or rapid international expansion.
Competition within this segment extends beyond database functionality. Vendors differentiate through migration services, workload optimization, integrated analytics, cybersecurity capabilities, and support for hybrid and multi-cloud architectures. Long-term contracts increasingly depend on service reliability, ecosystem compatibility, and operational simplicity rather than traditional licensing models alone.
Commercially, cloud deployment generates recurring subscription revenue and strengthens customer retention by embedding database services within broader enterprise cloud environments. Continued investment in hyperscale data centers and enterprise cloud migration programs is expected to sustain demand throughout the forecast period.
Regional Analysis
North America
North America maintains a leading position due to extensive enterprise cloud adoption, mature software industries, and substantial investment in AI infrastructure. Large enterprises continue modernizing legacy databases while expanding managed cloud database services. Strict cybersecurity requirements and regulatory oversight encourage sustained investment in secure enterprise database platforms.
Europe
European demand is supported by manufacturing modernization, financial services digitization, and strong regulatory frameworks governing personal data protection. Organizations emphasize compliance, data residency, and governance capabilities when selecting database platforms. Hybrid cloud deployments remain common because many enterprises balance operational modernization with regulatory obligations.
Asia Pacific
Asia Pacific represents an attractive investment destination driven by expanding cloud infrastructure, digital banking, e-commerce, telecommunications, and government digitalization initiatives. China, India, Japan, South Korea, and Southeast Asian economies continue investing in hyperscale data centers and enterprise software modernization. Buyers increasingly adopt cloud databases while maintaining selected mission-critical workloads within domestic infrastructure to satisfy regulatory requirements.
Middle East & Africa
Government digital transformation initiatives, smart city investments, financial sector modernization, and expanding cloud infrastructure support market development across the region. Enterprise adoption continues to improve, although skills availability and infrastructure maturity remain uneven across individual markets.
South America
Brazil leads regional demand through financial services modernization, retail digitalization, and enterprise cloud migration. Economic uncertainty occasionally delays large infrastructure investments, but organizations continue prioritizing database modernization projects that improve operational efficiency and cybersecurity resilience.
Competitive Landscape
Competition remains concentrated among established enterprise software providers, cloud infrastructure companies, and specialized database technology vendors. Suppliers compete through database performance, workload automation, AI integration, cloud-native capabilities, cybersecurity, pricing flexibility, and ecosystem compatibility rather than storage capacity alone.
Strategic partnerships with cloud providers, system integrators, application developers, and enterprise consulting firms continue strengthening commercial reach. Vendors increasingly expand managed database portfolios while supporting hybrid and multi-cloud deployments to address enterprise procurement preferences. Product differentiation also depends on automation capabilities, developer productivity tools, high availability, regulatory compliance features, and integrated analytics. Geographic expansion remains closely linked to investments in regional cloud infrastructure and local data center availability.
Recent Developments
May 2026: MongoDB introduced new enterprise AI database capabilities at MongoDBlocal London 2026, including native embedding generation, persistent agent memory, and real-time operational data features to support production-scale AI agents.
February 2026: IBM announced the general availability of Databases for MongoDB Gen 2, delivering a fully managed database service on VPC-based infrastructure with enhanced security, networking, and higher-performance snapshot-based backup capabilities.
February 2026: Oracle launched Oracle GoldenGate Veridata 26c, adding MongoDB support, native job scheduling, enhanced administration, and expanded heterogeneous database validation to improve continuous data integrity across hybrid and lakehouse environments.
Regulatory and Policy Environment
The regulatory environment increasingly shapes enterprise database procurement. Data protection regulations, including regional privacy laws, financial sector requirements, healthcare information standards, and government cybersecurity frameworks, require organizations to maintain strong controls over data storage, processing, and access. Compliance obligations encourage investment in encryption, identity management, audit logging, backup resilience, and data governance capabilities.
Industry standards supporting information security management, cloud security assurance, and business continuity continue influencing procurement criteria. Governments also encourage cloud adoption through national digital economy strategies while introducing requirements governing critical infrastructure, sovereign data management, and cybersecurity resilience. Vendors capable of demonstrating regulatory compliance across multiple jurisdictions gain competitive advantages in highly regulated industries.
Outlook and Strategic Implications
Over the 2026–2031 forecast period, enterprise database investment will increasingly align with AI deployment, hybrid cloud infrastructure, cybersecurity resilience, and regulatory compliance rather than traditional infrastructure replacement cycles. Procurement decisions are expected to prioritize operational automation, workload portability, database observability, and integration with analytics platforms.
Cloud-managed database services are likely to capture a growing share of enterprise spending as organizations seek predictable operating costs and simplified infrastructure management. At the same time, demand for hybrid architectures will remain strong because regulated industries continue balancing modernization objectives with compliance and operational continuity requirements.
Technology suppliers that combine AI-enabled database management, strong governance capabilities, multi-cloud interoperability, and enterprise-grade security will be well positioned to address evolving customer priorities. Strategic investment opportunities will increasingly emerge from industry-specific database solutions, sovereign cloud deployments, and platforms optimized for AI-driven enterprise applications. Organizations that modernize database infrastructure while strengthening governance and cybersecurity capabilities are expected to improve operational agility, support data-intensive innovation, and maintain long-term competitiveness.
Database Management System Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 134.49 billion |
| Total Market Size in 2031 | USD 199.45 billion |
| Forecast Unit | Billion |
| Growth Rate | 8.20% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Deployment, Enterprise Size, Industry Vertical, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
- Relational Database Management System (RDBMS)
- NoSQL Database Management System
- Object-Oriented Database Management System (OODBMS)
- NewSQL Database Management System
By Deployment
- Cloud
- On-premises
By Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
By Industry Vertical
- BFSI
- Healthcare
- Retail and E-commerce
- IT and Telecommunications
- Manufacturing
- Government and Public Sector
- Others
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- United Kingdom
- Germany
- France
- Spain
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Asia Pacific
- China
- Japan
- India
- South Korea
- Indonesia
- Taiwan
- Thailand
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. DATABASE MANAGEMENT SYSTEM MARKET BY TYPE
5.1. Introduction
5.2. Relational Database Management System (RDBMS)
5.3. NoSQL Database Management System
5.4. Object-Oriented Database Management System (OODBMS)
5.5. NewSQL Database Management System
6. DATABASE MANAGEMENT SYSTEM MARKET BY DEPLOYMENT
6.1. Introduction
6.2. Cloud
6.3. On-premises
7. DATABASE MANAGEMENT SYSTEM MARKET BY ENTERPRISE SIZE
7.1. Introduction
7.2. Small and Medium Enterprises (SMEs)
7.3. Large Enterprises
8. DATABASE MANAGEMENT SYSTEM MARKET BY INDUSTRY VERTICAL
8.1. Introduction
8.2. BFSI
8.3. Healthcare
8.4. Retail and E-commerce
8.5. IT and Telecommunications
8.6. Manufacturing
8.7. Government and Public Sector
8.8. Others
9. DATABASE MANAGEMENT SYSTEM MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Type
9.2.2. By Deployment
9.2.3. By Enterprise Size
9.2.4. By Industry Vertical
9.2.5. By Country
9.2.5.1. United States
9.2.5.2. Canada
9.2.5.3. Mexico
9.3. South America
9.3.1. By Type
9.3.2. By Deployment
9.3.3. By Enterprise Size
9.3.4. By Industry Vertical
9.3.5. By Country
9.3.5.1. Brazil
9.3.5.2. Argentina
9.3.5.3. Others
9.4. Europe
9.4.1. By Type
9.4.2. By Deployment
9.4.3. By Enterprise Size
9.4.4. By Industry Vertical
9.4.5. By Country
9.4.5.1. United Kingdom
9.4.5.2. Germany
9.4.5.3. France
9.4.5.4. Spain
9.4.5.5. Others
9.5. Middle East and Africa
9.5.1. By Type
9.5.2. By Deployment
9.5.3. By Enterprise Size
9.5.4. By Industry Vertical
9.5.5. By Country
9.5.5.1. Saudi Arabia
9.5.5.2. United Arab Emirates
9.5.5.3. Others
9.6. Asia Pacific
9.6.1. By Type
9.6.2. By Deployment
9.6.3. By Enterprise Size
9.6.4. By Industry Vertical
9.6.5. By Country
9.6.5.1. China
9.6.5.2. Japan
9.6.5.3. India
9.6.5.4. South Korea
9.6.5.5. Indonesia
9.6.5.6. Taiwan
9.6.5.7. Thailand
9.6.5.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. IBM Corporation
11.2. Microsoft Corporation
11.3. Oracle Corporation
11.4. SAP SE
11.5. MongoDB, Inc.
11.6. MarkLogic Corporation
11.7. Hewlett Packard Enterprise Company
11.8. Amazon Web Services, Inc.
11.9. InterSystems Corporation
11.10. Cloudera, Inc.





Frequently asked questions
What is the projected market size and growth rate for the Database Management System (DBMS) market from 2026 to 2031?
The Database Management System market is forecast to grow at a Compound Annual Growth Rate (CAGR) of 8.20% between 2026 and 2031. This growth is expected to increase the market's value from USD 134.49 billion in 2026 to an estimated USD 199.45 billion by 2031. This indicates a significant expansion and strategic importance of DBMS in modern enterprise information architecture.
What are the primary strategic shifts and architectural trends influencing the Database Management System market outlook?
The Database Management System Market is experiencing a notable shift from traditional database deployments towards cloud-native, distributed, and multi-model database architectures. Enterprises are increasingly prioritizing solutions that offer elasticity, workload automation, resilience, and seamless integration with analytics, AI, and application development environments. Hybrid deployment models also remain common as organizations balance existing on-premises mission-critical applications with new cloud infrastructure initiatives.
Which specific industries are exhibiting strong demand for Database Management Systems during the forecast period (2026-2031)?
Industry demand for DBMS is particularly robust across key sectors such as banking, healthcare, telecommunications, manufacturing, retail, and government. Financial institutions require databases capable of processing millions of transactions while maintaining regulatory compliance. Healthcare organizations rely on high-performance systems for electronic health records and medical imaging, while manufacturers deploy databases to manage industrial automation and predictive maintenance.
How is the competitive landscape structured within the Database Management System market?
The industry structure comprises established enterprise software vendors, specialized database technology providers offering diverse platforms (relational, NoSQL, NewSQL, graph, document, object-oriented), and cloud hyperscalers. Cloud hyperscalers are strengthening their position by integrating database services into broader cloud ecosystems. However, enterprises are increasingly adopting multi-cloud data strategies to reduce dependence on a single vendor.
What are the key factors driving enterprise procurement decisions for Database Management Systems currently?
Enterprise buyers now prioritize several critical factors beyond just storage performance, including elasticity, workload automation, resilience, and deep integration with analytics, AI, and application development environments. Procurement decisions are also significantly influenced by total cost of ownership, regulatory compliance, robust disaster recovery capabilities, and the maturity of the vendor ecosystem. Organizations are also investing in modernization to improve scalability and cybersecurity.
Why are organizations prioritizing database modernization, and what critical objectives does it address?
Organizations are investing in database modernization to achieve vital objectives such as improving scalability, ensuring high availability, and strengthening cybersecurity measures. These efforts also aim to support real-time analytics capabilities and reduce operational complexity. Modernization is crucial for managing the increasing volume of structured and unstructured data generated from cloud applications, connected devices, and AI workloads.
Cite this report
Knowledge Sourcing Intelligence. (Jul 2026). Database Management System Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/database-management-system-market