
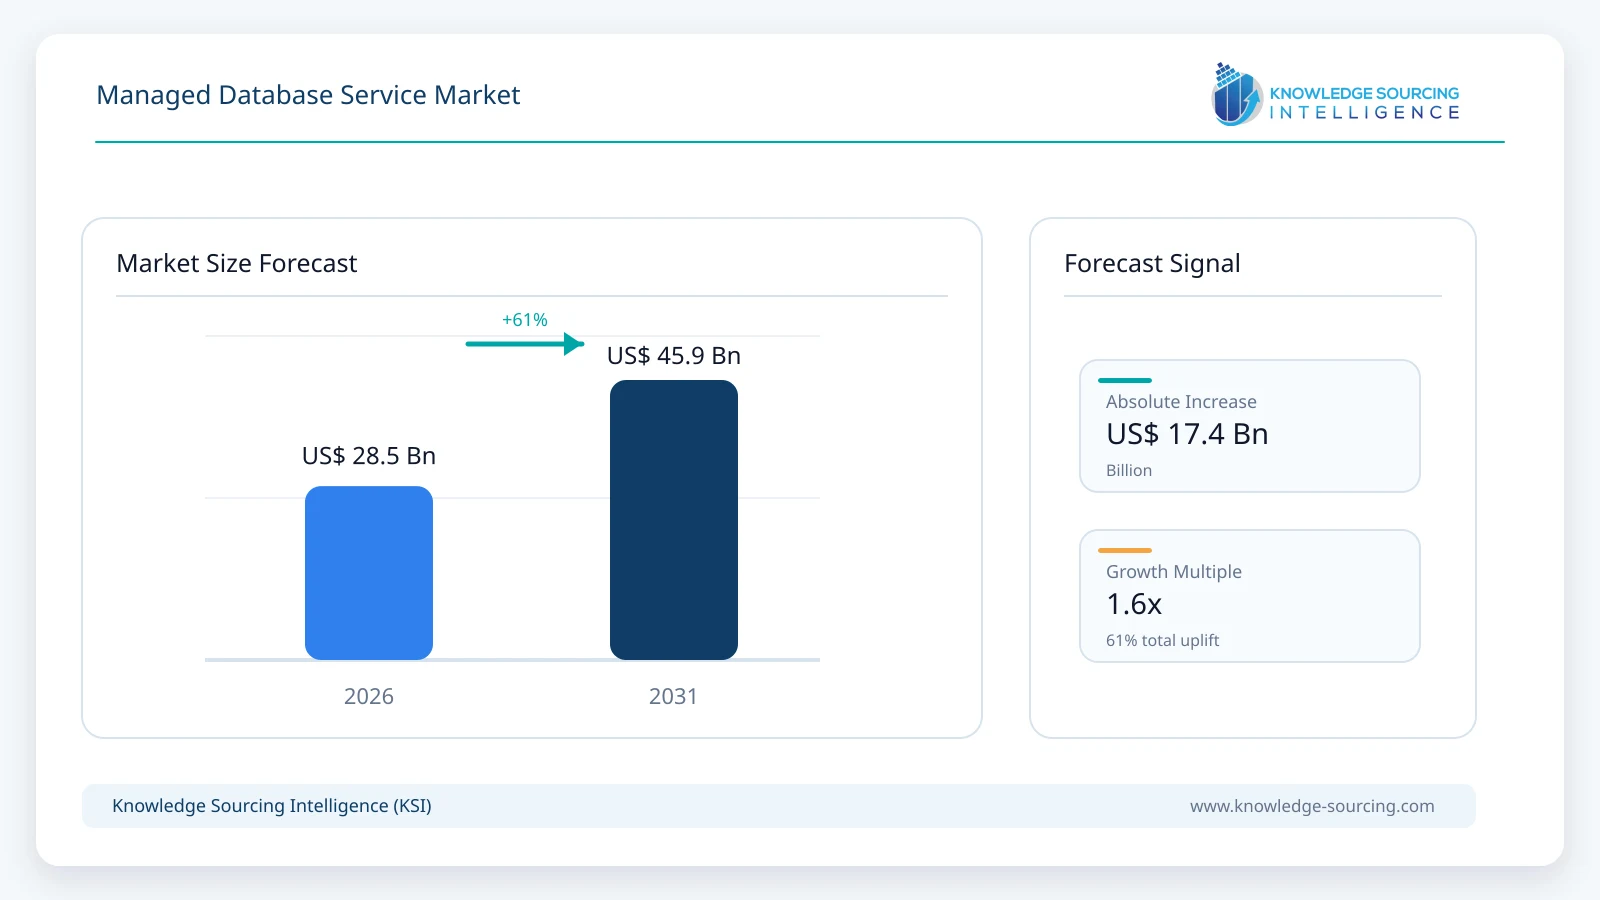
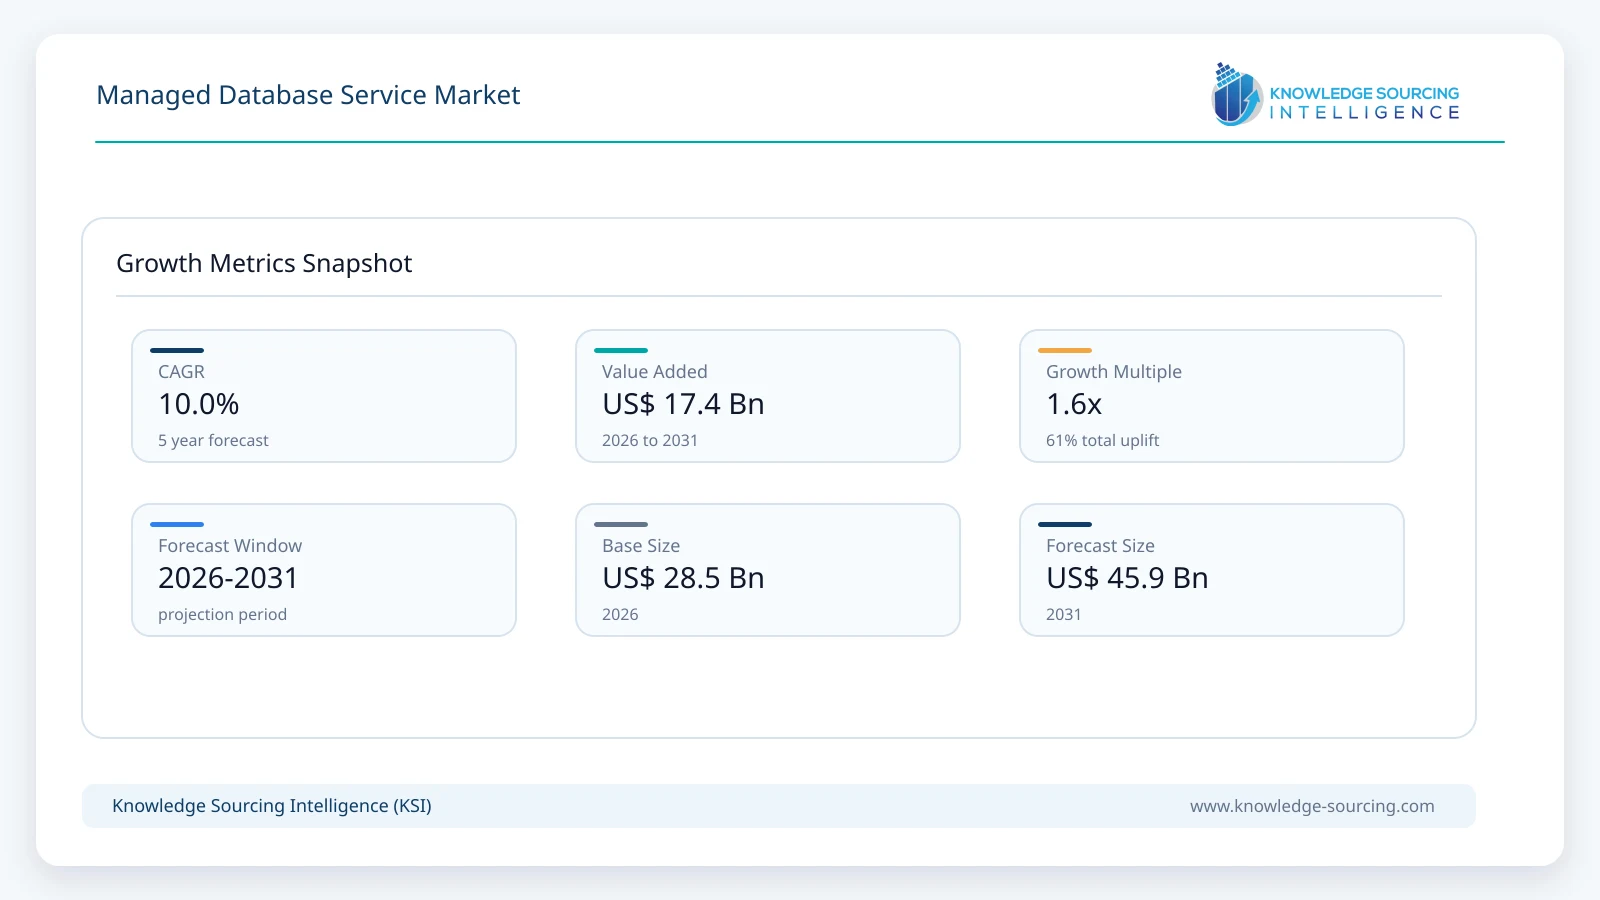
The Managed Database Service Market is forecast to grow at a CAGR of approximately 10.0%, increasing from USD 28.5 billion in 2026 to USD 45.9 billion by 2031.
Highlights:
- 1Relational databases account for approximately 60% of global managed database service market value in 2026 and remain the largest database type.
- 2Numeric data represents approximately 45% of market value by data source in 2026 due to the scale of transactional, financial and operational database workloads.
- 3Large enterprises account for approximately 68% of market value in 2026 because complex application estates generate substantial requirements for availability, security and database administration.
- 4IT and telecommunications accounts for approximately 27% of market value in 2026 and remains the largest end-user sector.
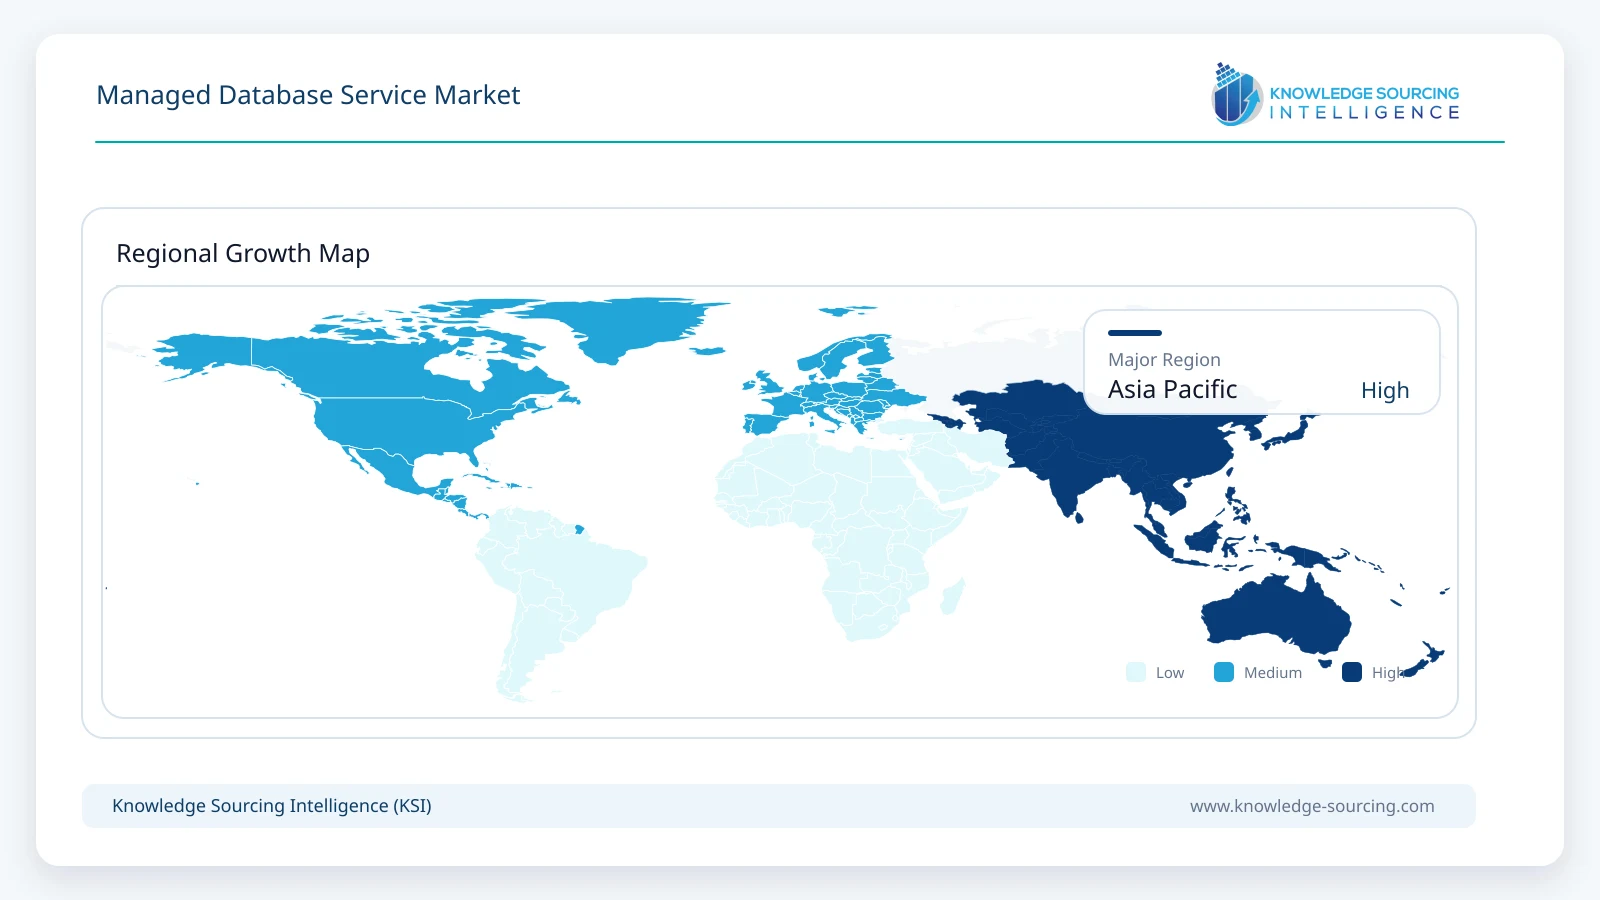
- 5North America represents approximately 39% of global market value in 2026, while Asia Pacific records the strongest major-region growth through 2031.
Managed database services transfer routine database administration functions such as infrastructure provisioning, software patching, backup, replication, monitoring, security configuration and recovery to the service provider while allowing application teams to focus on data models and application development.
The market extends across relational, NoSQL and in-memory database architectures and includes services delivered by hyperscale cloud providers as well as specialist database companies. Major platforms include Amazon RDS and Aurora, Microsoft Azure SQL Database and Azure Cosmos DB, Google Cloud SQL, AlloyDB and Spanner, Oracle AI Database cloud services, IBM database services and MongoDB Atlas.
Database architecture is becoming more closely integrated with AI workloads. Google Cloud stated at Next 2026 that it was embedding AI functions across AlloyDB, Cloud SQL and Spanner and introduced database onboarding and observability agents designed to automate database selection, provisioning and performance diagnosis. Microsoft similarly introduced Azure HorizonDB in public preview in June 2026 as a fully managed PostgreSQL-compatible database integrating transactional data, vector search and AI capabilities.
Market Trends
Managed Databases Are Becoming AI-Native Data Platforms
Managed database providers are adding vector search, embeddings, graph functions and agent-oriented interfaces directly to operational databases. This reduces the need for developers to move application data into separate specialist systems before using it in AI applications.
Google Cloud announced in April 2026 that new database tools for AlloyDB, Spanner and Cloud SQL would allow AI agents to query and interact with managed data directly. The company also introduced AI-powered database onboarding and observability agents and expanded AlloyDB search capabilities. Spanner's architecture is similarly evolving beyond conventional distributed relational workloads toward relational, graph, vector and other data models within a single managed service.
Microsoft is following the same direction. At Build 2026, the company introduced Azure HorizonDB as a managed PostgreSQL-compatible database for AI applications and expanded Azure Cosmos DB with semantic reranking and agent-memory capabilities.
MongoDB extended Atlas in August 2026 with automated embeddings, reranking APIs and additional vector-search capabilities intended to give AI applications real-time context from operational data.
The competitive boundary between operational databases and AI infrastructure is therefore becoming less distinct. Managed database platforms increasingly compete on their ability to serve both conventional application transactions and AI retrieval workloads.
Database Management Is Becoming More Automated
Managed services originally differentiated primarily through automated backups, patching and infrastructure provisioning. The next stage increasingly involves automated diagnosis, optimization, migration and workload management.
Google Cloud's Database Observability Agent is designed to identify database-performance issues and recommend remediation across AlloyDB, Bigtable, Cloud SQL and Spanner. Its Database Onboarding Agent evaluates workload requirements and recommends appropriate database services and deployment configurations.
Microsoft is similarly extending management automation through Azure SQL and its broader managed database estate. In August 2026, Microsoft made automatic backup immutability generally available for Azure SQL Database and Azure SQL Managed Instance, automatically protecting recent point-in-time backups against alteration or deletion.
Automation improves the economics of managed databases because organizations can operate larger database estates without increasing database-administration headcount proportionally. This becomes increasingly important as enterprises deploy more applications, microservices and AI agents, each of which can create new operational data requirements.
PostgreSQL Is Increasingly Central to Managed Database Strategies
PostgreSQL has become a major competitive battleground across managed database providers. AWS offers both Amazon RDS for PostgreSQL and Aurora PostgreSQL-Compatible Edition, while Google provides Cloud SQL for PostgreSQL and AlloyDB. Microsoft operates Azure Database for PostgreSQL and introduced PostgreSQL-compatible HorizonDB during 2026.
AWS stated in May 2026 that Aurora PostgreSQL and Amazon RDS for PostgreSQL maintain defined version-currency timelines to allow customers to adopt new PostgreSQL community releases while continuing to use fully managed infrastructure. Microsoft also expanded migration and security tooling around Azure Database for PostgreSQL during Build 2026.
The appeal of PostgreSQL reflects open-source compatibility, extensive developer familiarity and the ability of cloud providers to add differentiated managed capabilities around a common database foundation. Providers can compete through storage architecture, scalability, availability, AI functionality and management tooling without requiring customers to adopt entirely proprietary query languages.
Market Drivers
Application Modernization Is Moving Databases to Managed Services
Enterprises modernizing legacy applications increasingly reassess whether they need to operate database infrastructure themselves. Managed services remove responsibility for operating-system maintenance, database patching, backup configuration, replication infrastructure and many routine availability tasks.
AWS provides managed PostgreSQL through both RDS and Aurora and supports automated database maintenance while preserving compatibility with widely used open-source engines. Microsoft introduced Azure Accelerate for Databases in April 2026 specifically to help organizations assess, migrate and modernize database estates as they prepare applications for AI.
Google Cloud also introduced enhanced move-to-managed migration capabilities during Next 2026, including PostgreSQL consolidation and migration support embedded directly into Cloud SQL, AlloyDB and Database Center.
These services lower migration friction and expand the addressable managed database market beyond cloud-native applications. Existing enterprise workloads running Oracle, SQL Server, PostgreSQL, MySQL and other databases can increasingly be migrated while retaining familiar database semantics and development practices.
AI Applications Require More Operational Data Infrastructure
AI applications increasingly need access to live enterprise data rather than static model-training datasets alone. Agents and retrieval-based applications require databases that can provide transactional records, vector representations, relationships and real-time context with predictable latency.
Google reports that Spanner handles more than six billion queries per second at peak and manages more than 17 exabytes of data across Google's own infrastructure while maintaining globally consistent operation. Its cloud database roadmap increasingly combines these operational characteristics with vector and graph capabilities.
MongoDB is similarly positioning Atlas as an operational data foundation for AI. In August 2026, the company added automated embeddings, reranking and enhanced vector retrieval directly to Atlas, allowing developers to use operational data without maintaining separate embedding pipelines.
As AI applications move from experimentation into production, managed databases benefit because enterprises need resilient data infrastructure that can scale alongside unpredictable agent and application workloads while maintaining security and governance.
Operational Complexity Favors Outsourced Database Management
Database operations become increasingly complex as organizations run multiple database engines across clouds, regions and applications. High availability, disaster recovery, encryption, auditability and performance tuning require specialist expertise that may be difficult to maintain internally across every database platform.
Cloud providers increasingly incorporate these capabilities directly into managed offerings. Microsoft's current database strategy emphasizes reliability, scalability, operational simplicity, developer productivity and AI readiness across Azure SQL Database, Azure Database for PostgreSQL and Azure Cosmos DB.
AWS continues to expand operational tools around Amazon RDS and Aurora, including CloudWatch Database Insights for identifying lock contention and other performance issues.
The value proposition therefore extends beyond reducing server-management effort. Managed databases increasingly provide standardized operational controls that would otherwise need to be assembled, maintained and monitored independently by enterprise database teams.
Market Restraints
Database Migration Remains Complex for Large Application Estates
Migrating an established database involves more than transferring data. Applications may depend on stored procedures, extensions, proprietary data types, database-specific functions, authentication models and latency relationships with other systems. These dependencies can make moving a mature application to a new managed database expensive and technically risky.
Providers are developing migration tooling specifically because this remains a significant adoption barrier. Google introduced expanded move-to-managed capabilities for PostgreSQL at Next 2026, while Microsoft added database discovery and assessment tools designed to evaluate Oracle and PostgreSQL environments before migration.
Large enterprises may therefore adopt managed databases gradually, beginning with new applications and selected modernization projects rather than migrating their complete database estate simultaneously.
Data Sovereignty and Vendor Dependence Affect Deployment Decisions
Managed database services place important operational functions within a provider's infrastructure and control plane. This can create concerns around data residency, regulatory compliance, portability and dependency on proprietary service capabilities.
Enterprises in financial services, government, healthcare and other regulated industries may need databases to operate within particular jurisdictions or infrastructure environments. Database vendors are responding through sovereign-cloud options, hybrid deployments and products that can operate across several environments.
Google's introduction of Spanner Omni in April 2026 illustrates this direction. The downloadable version of Spanner allows organizations to run the database in their own data centers, across clouds or locally rather than restricting deployment to Google Cloud.
Hybrid and portable architectures reduce some concerns but can also weaken the operational simplicity that initially makes fully managed database services attractive.
Segment Analysis
By Type: Relational Database
Relational managed databases are projected to reach approximately USD 25.2 billion by 2031. The category remains central to enterprise application infrastructure because transactional systems, financial applications, ERP platforms and many customer-facing services continue to depend on structured relational data and SQL.
The segment is supported by strong competition among major cloud providers. AWS offers Amazon RDS and Aurora across engines including PostgreSQL and MySQL, Microsoft maintains Azure SQL Database and Azure Database for PostgreSQL, Google provides Cloud SQL and AlloyDB, and Oracle continues extending its database platform across cloud and multicloud deployments.
Relational databases are also absorbing functionality once associated primarily with separate database categories. PostgreSQL-compatible services increasingly support vector search, while distributed SQL platforms combine relational consistency with horizontal scale. This convergence allows relational services to remain relevant even as application architectures become more diverse.
By Data Source: Numeric Data
Numeric-data workloads are projected to generate approximately USD 21.6 billion in managed database service revenue by 2031. Financial transactions, orders, inventory records, telemetry, billing data and operational metrics remain fundamental database workloads across nearly every major industry.
The growth of connected applications increases both the volume and frequency of these records. Managed databases are well suited to workloads where organizations require rapid writes, consistent transactions, replication and automated recovery without maintaining the underlying infrastructure directly.
Documents and audio-visual data grow strongly as AI applications generate greater demand for unstructured and semi-structured information. However, numeric and structured operational data remains the foundation of core transactional applications and continues to represent the largest single data-source category.
By Enterprise Size: Large Enterprises
Large-enterprise spending is projected to reach approximately USD 29.8 billion by 2031. These organizations operate complex application estates and typically require multiple database technologies across customer-facing systems, internal applications, analytics and regulated workloads.
Managed services provide particular value to large organizations because database administration can otherwise become fragmented across hundreds or thousands of instances. Centralized monitoring, automated backup, identity integration and managed high availability allow infrastructure teams to standardize controls while application teams continue using different database engines.
Small and medium enterprises grow faster as serverless and consumption-based database models lower entry barriers. Large enterprises nevertheless remain the largest customer segment because of substantially greater workload scale, resilience requirements and total database spending.
By End User: IT and Telecommunications
IT and telecommunications is projected to reach approximately USD 11.5 billion by 2031. The sector generates large volumes of customer, network, billing and application data and is also an early adopter of cloud-native software development.
Telecommunications operators increasingly use managed databases for customer applications, digital channels and network-related software, while technology companies use them to support SaaS products, developer platforms and AI-enabled applications.
BFSI remains another major end-user category because transaction integrity, availability and regulatory control make databases central to financial operations. Retail, healthcare and manufacturing record stronger growth from smaller bases as digital commerce, connected equipment and AI applications create additional operational data workloads.
Regional Outlook
North America
North America is projected to reach approximately USD 17.0 billion by 2031 and remains the largest regional managed database service market. The region hosts many of the industry's leading providers, including Amazon Web Services, Microsoft, Google, Oracle, IBM and MongoDB, and contains a large base of enterprises adopting cloud and AI infrastructure.
Product development is particularly active. Microsoft introduced HorizonDB and expanded Cosmos DB AI capabilities during Build 2026, Google launched database agents and new Spanner functionality at Next 2026, and MongoDB continued expanding Atlas as an AI-oriented operational data platform.
North American enterprises also maintain substantial legacy database estates, creating continued opportunities for migration and modernization in addition to cloud-native application growth.
Asia Pacific
Asia Pacific is projected to reach approximately USD 14.7 billion by 2031 and records the strongest growth among major regions. Expansion is supported by cloud adoption across India, Southeast Asia, Japan, South Korea and Australia as well as the large digital-platform market in China.
MongoDB's September 2026 appointment of a dedicated head of Asia Pacific and Japan was explicitly linked by the company to enterprises moving AI initiatives from pilot to production across the region. Global cloud providers are also continuing to expand regional infrastructure and database availability to meet data-residency and latency requirements.
The region benefits from a growing developer population, increasing cloud-native application development and continued modernization of financial, telecommunications, retail and government systems. These factors allow Asia Pacific to gain global market share through 2031.
Competitive Environment and Analysis
The managed database service market includes hyperscale cloud providers, database software vendors and specialist managed-service companies. AWS maintains one of the broadest portfolios through Amazon RDS, Aurora, DynamoDB and other managed database services. Microsoft competes through Azure SQL Database, Azure Database for PostgreSQL, Azure Cosmos DB and newer offerings including HorizonDB. Google Cloud's portfolio includes Cloud SQL, AlloyDB, Spanner, Bigtable and Firestore.
Oracle is expanding AI capabilities directly within its database platform. In March 2026, Oracle introduced new agentic AI functionality for Oracle AI Database, enabling AI agents to work with enterprise operational and analytic data across cloud, multicloud and on-premises deployments.
MongoDB differentiates through its document-oriented Atlas platform and is adding vector retrieval and AI functions around live operational data. Specialist providers and service companies compete through migration, optimization and administration expertise across multiple database vendors.
Competitive differentiation is increasingly shifting from basic database hosting toward automated operations, AI integration, multi-model capabilities, portability and migration tooling. Customers are likely to favor services that combine familiar database technologies with lower operational effort while avoiding unnecessary application redesign.
Recent Developments
August 2026: MongoDB expanded Atlas with automated embeddings, reranking APIs and enhanced vector-search capabilities designed to give AI applications and agents access to real-time operational context.
August 2026: Microsoft made automatic backup immutability generally available for Azure SQL Database and Azure SQL Managed Instance, adding automatic protection for recent point-in-time backups.
June 2026: Microsoft introduced Azure HorizonDB in public preview as a fully managed PostgreSQL-compatible database integrating transactional data, vector search and AI functionality.
June 2026: Google introduced graph algorithms within Spanner Graph to support connected-data analysis directly within its managed distributed database environment.
April 2026: Google announced Spanner Omni, extending Spanner deployment beyond Google Cloud to customer data centers and other infrastructure environments.
March 2026: Oracle announced new agentic AI capabilities for Oracle AI Database to support AI applications using enterprise operational and analytical data.
Market Outlook
The managed database service market is forecast to increase from USD 28.51 billion in 2026 to USD 45.89 billion in 2031 at a CAGR of approximately 9.99%. The market is evolving from managed versions of conventional database engines toward broader operational data platforms that combine automated administration with AI search, vector processing, graph functionality and intelligent performance management.
Relational databases remain the largest type through 2031 because enterprise transaction systems continue to rely heavily on SQL and structured data. Their role is also broadening as relational services incorporate capabilities previously associated with separate vector, graph and document databases.
Large enterprises remain the principal source of market spending, while smaller companies benefit from consumption-based and serverless models that reduce infrastructure-management requirements. IT and telecommunications continues to represent the largest end-user category, with BFSI, retail, healthcare and manufacturing providing additional growth as application modernization expands.
North America remains the largest regional market, while Asia Pacific gains share through faster cloud adoption and AI-related database investment. Competitive advantage increasingly depends on the ability to automate database operations while allowing enterprise data to support both conventional applications and AI agents.
Managed database services are therefore becoming part of the core AI and application infrastructure stack rather than functioning simply as outsourced database administration. Providers that combine operational reliability, migration support, open database compatibility and AI-native functionality are positioned most strongly through 2031.
Managed Database Service Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 28.5 billion |
| Total Market Size in 2031 | USD 45.9 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Data Source, Enterprise Size, End User, Geography |
| Companies |
|
Market Segmentation
By Type
Relational Database
NoSQL Database
In-Memory Database
Others
By Data Source
Audio & Visual Data
Documents
Numeric Data
Others
By Enterprise Size
Small
Medium
Large
By End User
BFSI
IT & Telecommunication
Manufacturing
Retail
Healthcare
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Market Estimation
2.4. Segment Modelling
2.5. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Managed Database Service Market Size, 2026-2031
3.3. Type Outlook
3.4. Data Source Outlook
3.5. Enterprise Size Outlook
3.6. End-User Outlook
3.7. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Application Modernization and Cloud Migration
4.1.2. AI Applications and Operational Data Requirements
4.1.3. Increasing Database Operational Complexity
4.2. Market Restraints
4.2.1. Database Migration Complexity
4.2.2. Data Sovereignty and Vendor Dependence
4.3. Porter's Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Data Governance and Regulatory Environment
5. TECHNOLOGICAL OUTLOOK
5.1. AI-Native Databases
5.2. Vector Search
5.3. Distributed SQL
5.4. Multi-Model Databases
5.5. Serverless Database Architecture
5.6. Autonomous Database Management
6. MANAGED DATABASE SERVICE MARKET BY TYPE
6.1. Relational Database
6.2. NoSQL Database
6.3. In-Memory Database
6.4. Others
7. MANAGED DATABASE SERVICE MARKET BY DATA SOURCE
7.1. Audio & Visual Data
7.2. Documents
7.3. Numeric Data
7.4. Others
8. MANAGED DATABASE SERVICE MARKET BY ENTERPRISE SIZE
8.1. Small
8.2. Medium
8.3. Large
9. MANAGED DATABASE SERVICE MARKET BY END USER
9.1. BFSI
9.2. IT & Telecommunication
9.3. Manufacturing
9.4. Retail
9.5. Healthcare
9.6. Others
10. MANAGED DATABASE SERVICE MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.1.3. Mexico
10.2. South America
10.2.1. Brazil
10.2.2. Argentina
10.2.3. Others
10.3. Europe
10.3.1. Germany
10.3.2. France
10.3.3. United Kingdom
10.3.4. Spain
10.3.5. Others
10.4. Middle East and Africa
10.4.1. Saudi Arabia
10.4.2. UAE
10.4.3. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. India
10.5.3. Japan
10.5.4. South Korea
10.5.5. Indonesia
10.5.6. Thailand
10.5.7. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Amazon Web Services, Inc.
12.2. Microsoft Corporation
12.3. Google LLC
12.4. Oracle Corporation
12.5. MongoDB, Inc.
12.6. IBM Corporation
12.7. Snowflake Inc.
12.8. SAP SE
12.9. DigitalOcean Holdings, Inc.
12.10. Alibaba Cloud
12.11. Tencent Cloud
12.12. Aiven
12.13. Percona LLC
12.14. Rackspace Technology
12.15. Buchanan Technologies
13. APPENDIX
Navigate
Trusted by the world's leading organizations











