Dental Implants Market - Strategic Insights and Forecasts (2026-2031)
Dental Implants Market Size, Share, Forecasts and Trends Analysis By Type (Endosteal Implants, Subperiosteal Implants, Zygomatic Implants), By Material (Titanium and Titanium Alloys, Zirconia and Ceramic Materials, Other Materials), By End User (Dental Clinics, Hospitals, Academic and Research Institutions), and Region
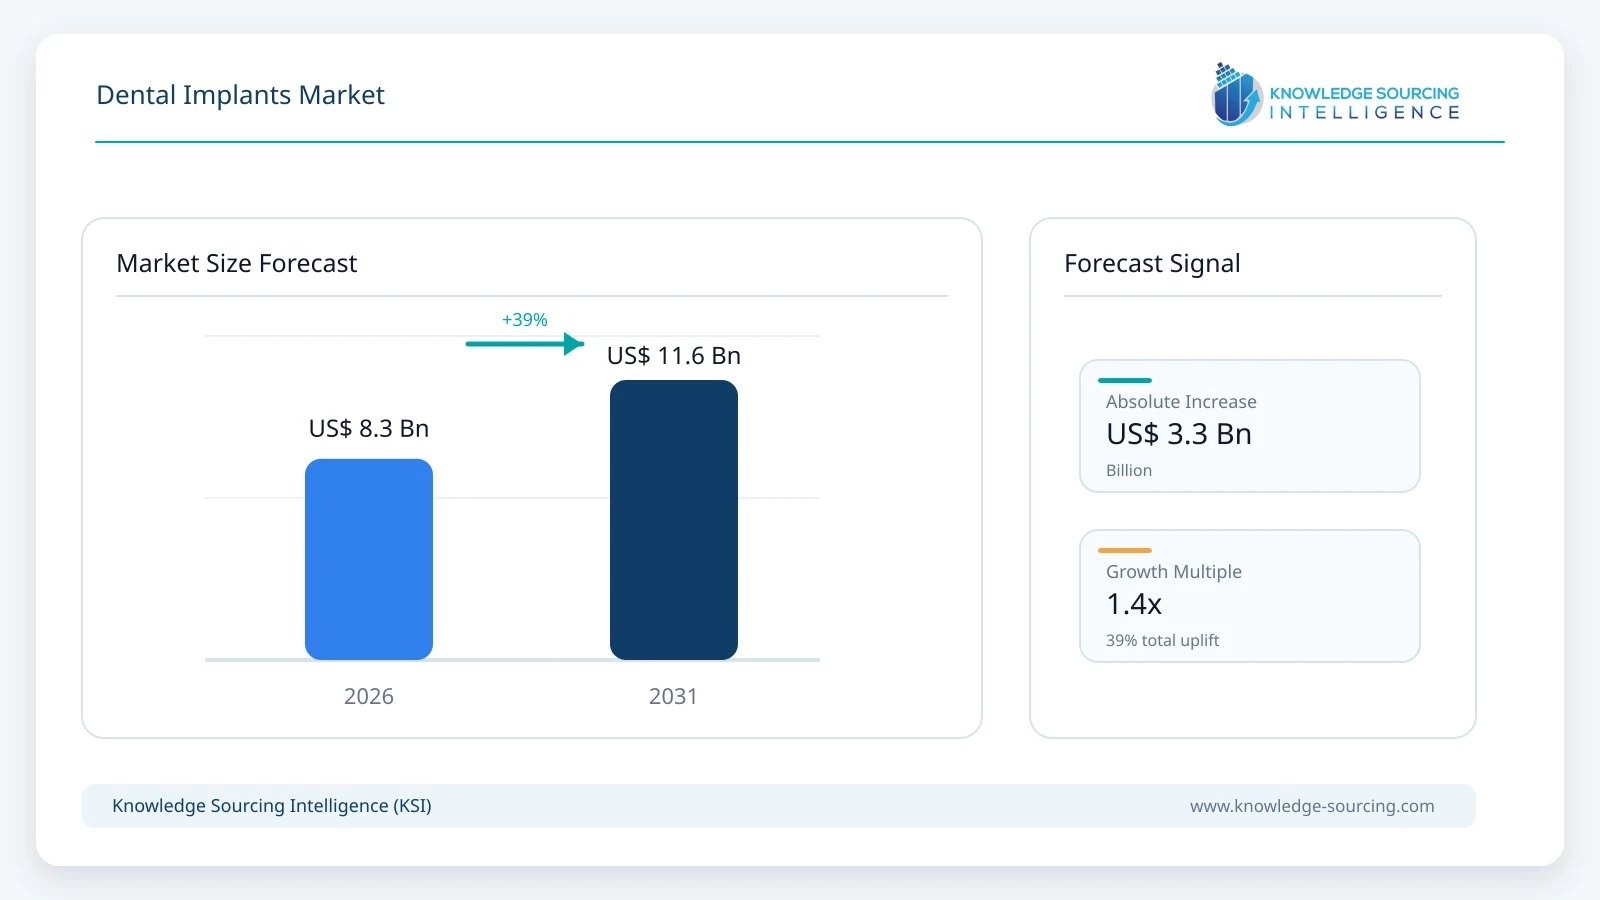
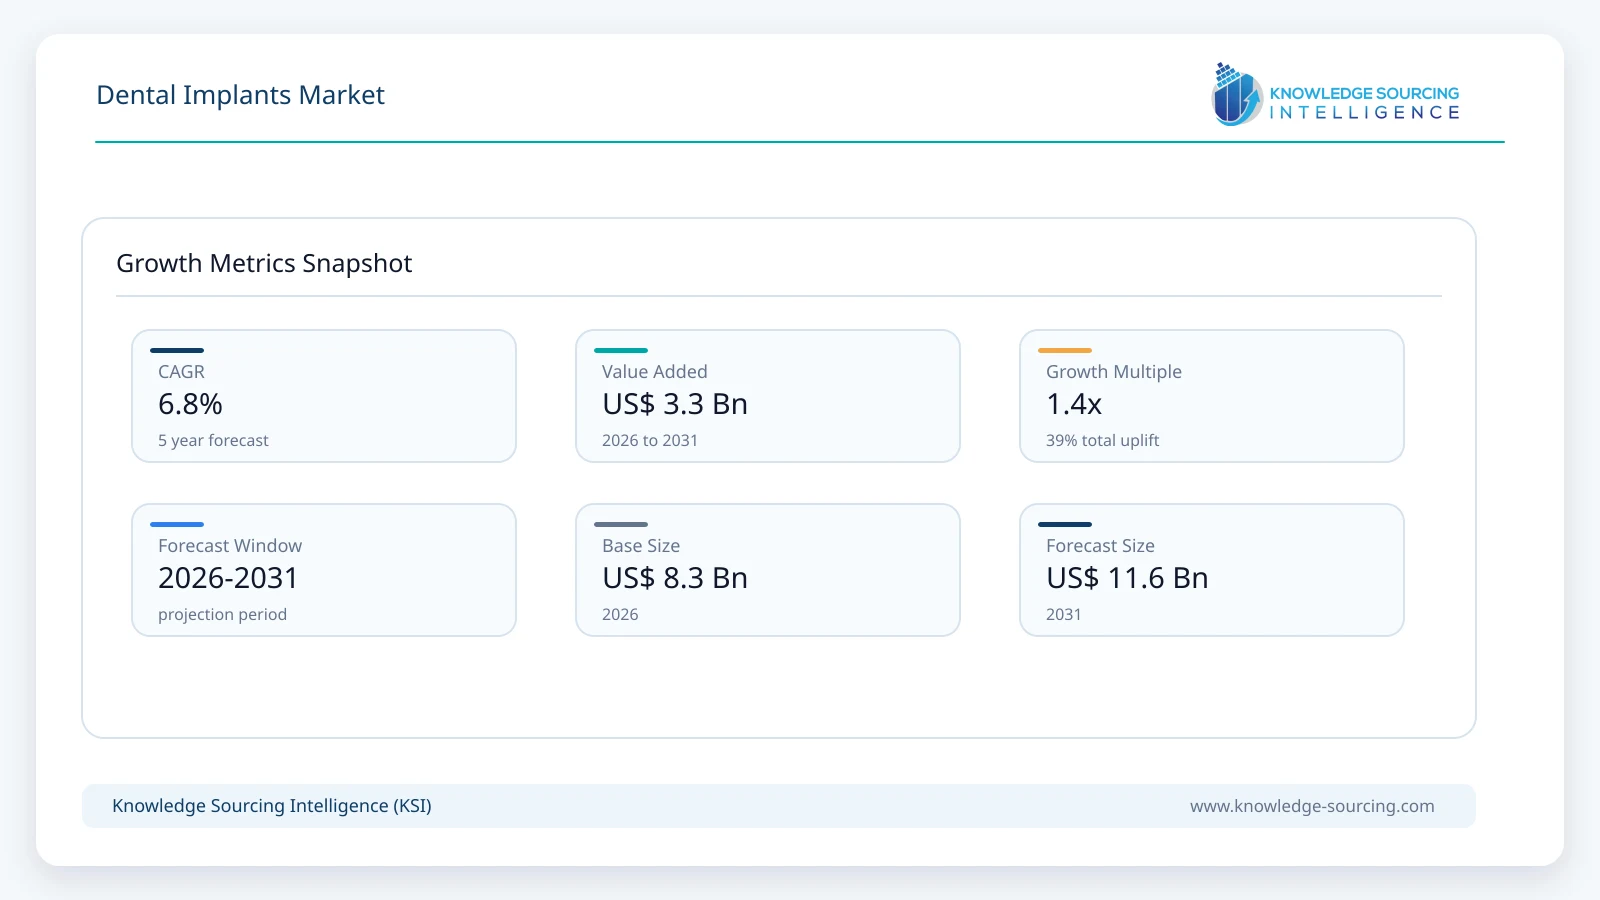
The global dental implants market is forecast to grow at a CAGR of 6.8%, increasing from USD 8.30 billion in 2026 to USD 11.55 billion in 2031.
Dental Implants Market - Strategic Insights and Forecasts (2026-2031) market growth projection from $8.30B in 2026 to $11.55B by 2031 at a CAGR of 6.8%.
Highlights:
1
Endosteal implants account for approximately 92% of global dental implant revenue in 2026.
2
Zirconia implant systems are projected to grow at approximately 9.1% annually through 2031.
3
Dental clinics generate about USD 6.1 billion of global implant-system demand in 2026.
4
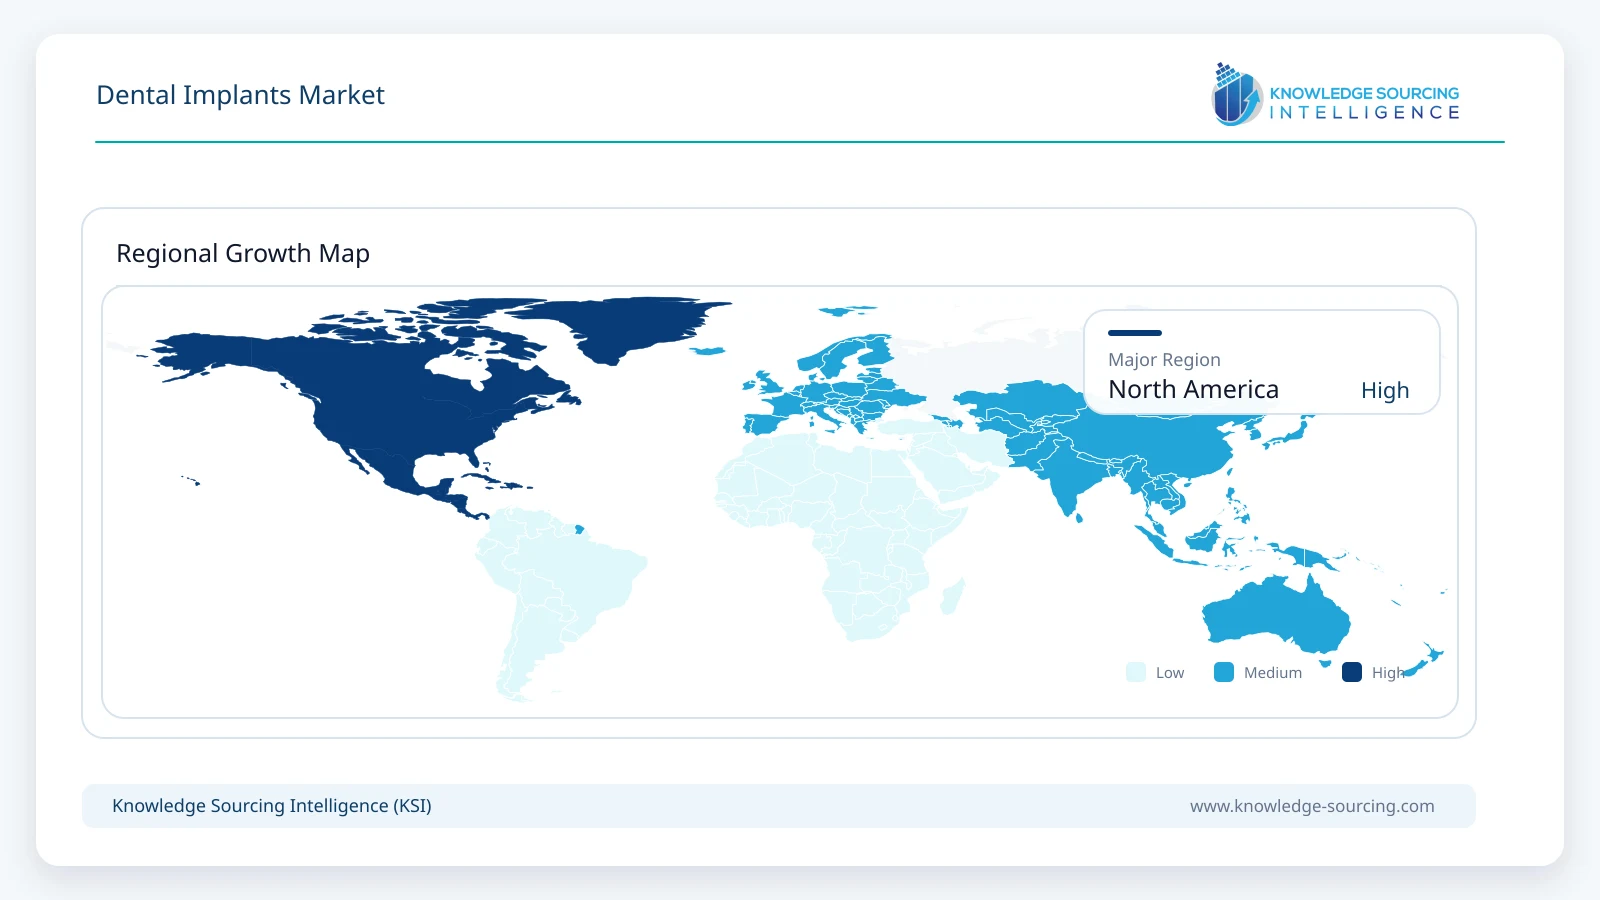
North America accounts for approximately 34% of global dental implant revenue in 2026.
5
Full-arch, immediate-placement and digitally guided workflows are increasing implant-system value per treated case.
6
Premium and challenger brands are expanding clinician education and local production to widen treatment access.
Market Overview
Modern dental implantology is dominated by root-form endosseous implants placed into the maxillary or mandibular bone. Treatment generally combines an implant fixture, prosthetic connection or abutment, surgical instruments and a restorative workflow that may include digital imaging, guided placement and custom prosthetic design. Implant manufacturers compete through macrogeometry, thread design, surface modification, connection design, implant diameter and length, prosthetic compatibility and the breadth of surgical and digital workflows surrounding the implant. Immediate placement and loading protocols have increased the importance of primary stability and workflow predictability, while full-arch treatment has raised demand for angled components, multi-unit abutments and specialized implants for compromised bone.
The commercial market is relatively concentrated at the premium end but remains fragmented across regional and value brands. Straumann estimated the addressable global implant market at CHF 6.1 billion in 2025 and its own market share above 35%, while Envista operates Nobel Biocare, Implant Direct and Alpha-Bio Tec across premium and value positions. Dentsply Sirona participates through Astra Tech Implant System and MIS, Osstem and Dentium have substantial Asian and international footprints, and MegaGen, ZimVie, BioHorizons Camlog, Thommen Medical, BEGO and Bicon compete in specific price points or clinical niches. This multi-brand structure is important because implant adoption depends not only on product performance but also on local clinical education, distributor reach, case support and restorative ecosystem availability.
Market Trends
Digital Implant Workflows Are Moving From Planning Tools to Integrated Treatment Ecosystems
Implant dentistry is increasingly managed as an end-to-end digital workflow rather than a sequence of separate surgical and laboratory steps. Intraoral scanning, cone-beam CT data, virtual implant planning, guided surgery, dynamic navigation, CAD/CAM prosthetics and chairside or laboratory 3D printing are being linked through common software platforms. Straumann continues to expand the AXS ecosystem around implant planning, guided surgery and restorative workflows, while Nobel Biocare integrates DTX Studio with NobelGuide and X-Guide. Dentsply Sirona combines implant systems with digital imaging, intraoral scanning and CAD/CAM technologies. The commercial effect is a shift in competition from the implant fixture alone toward workflow simplicity, treatment speed and the ability to move clinical data between diagnosis, surgery and prosthetic production without repeated manual steps.
Immediate and Full-Arch Treatment Is Increasing Demand for Specialized Implant Designs
Treatment concepts that reduce the interval between extraction, implant placement and restoration are becoming more prominent, particularly in full-arch rehabilitation. These protocols require high primary stability, predictable prosthetic connections and components that can manage angulation or reduced bone availability. Straumann iEXCEL combines several implant geometries under one prosthetic connection, Nobel Biocare continues to develop the All-on-4 and zygomatic treatment ecosystem, and BioHorizons launched Pro Zygoma in 2026 for remote anchorage in severely resorbed maxillae. MegaGen also received U.S. clearance for its zygomatic implant system in June 2026 and announced the U.S. launch of BLUEDIAMOND ZYGOMA in September. Specialized full-arch solutions remain a smaller part of total unit volume, but they carry higher procedural complexity and strengthen demand for integrated implants, components, instruments and guided workflows.
Market Drivers
Large Untreated Tooth-Loss Pool Supports Long-Term Procedure Growth
The underlying need for tooth replacement remains large. The World Health Organization estimates that oral diseases affect nearly 3.7 billion people globally and that complete tooth loss affects almost 7% of people aged 20 years or older and roughly 23% of people aged 60 years or older. Not every edentulous or partially edentulous patient is clinically suitable for, can afford or chooses implant treatment, but the gap between potential need and current treatment volumes creates a durable expansion opportunity. Straumann estimates approximately 220 million people each year both need and can afford implant treatment, compared with only around 16 million treatments currently performed. Aging populations in developed markets support replacement demand, while rising incomes and expanding private dental networks are gradually increasing access in emerging markets.
Clinical Education and Value-Segment Expansion Are Increasing Implant Access
Dental implant adoption is constrained by clinician training as much as by patient demand, so manufacturers increasingly treat education as part of the commercial model. Straumann reported more than 10,700 education activities and over 370,000 professionals trained in 2025, with 42% of activities conducted in low- and middle-income countries. Osstem operates structured implant education programs and a global network of training facilities, while Nobel Biocare, BioHorizons and other suppliers maintain dedicated clinical education programs. At the same time, challenger and value brands are expanding into markets where premium implant pricing historically limited penetration. Neodent, Implant Direct, Alpha-Bio Tec, MIS, Osstem, Dentium and MegaGen all widen the price spectrum available to clinicians, supporting higher procedure volumes without requiring the entire market to move toward premium systems.
Market Restraint
High Out-of-Pocket Treatment Costs and Procedure Complexity Restrict Patient Conversion
Dental implant treatment remains expensive relative to removable dentures and many conventional tooth-replacement options because the final patient cost includes diagnostics, surgery, implant components, restorative work, laboratory services and follow-up care. Coverage is limited in many public and private insurance systems, making patient affordability sensitive to local income levels and financing availability. Complex cases can also require bone grafting, sinus elevation or advanced full-arch procedures, increasing both cost and treatment time. The procedure is technique-sensitive and depends on appropriate diagnosis, surgical planning and prosthetic execution. Manufacturers are reducing these barriers through guided surgery, simplified kits, digital planning, value implant brands and clinician education, but affordability and access to trained implant practitioners remain the principal constraints on converting underlying tooth-loss need into actual implant procedures.
Segment Analysis
By Type - Endosteal Implants
Endosteal implants are projected to generate approximately USD 10.45 billion in global market revenue by 2031. Root-form implants placed directly into bone remain the standard solution for single-tooth replacement, multi-unit restorations and most full-arch procedures, giving the category a much larger addressable patient base than subperiosteal or zygomatic alternatives. Competition within the segment is increasingly differentiated by tapered versus parallel designs, bone- and tissue-level placement, surface technology, narrow-diameter options and compatibility with immediate protocols. Zygomatic implants are expected to grow faster from a much smaller base because they provide a graftless treatment option for selected patients with severe maxillary bone loss. Subperiosteal implants are also receiving renewed interest through patient-specific digital design, but they remain a niche option relative to conventional endosseous systems.
By Material - Titanium and Titanium Alloys
Titanium and titanium-alloy implant systems are projected to represent approximately USD 9.75 billion of market value by 2031. Their position is supported by decades of clinical evidence, favorable osseointegration, mechanical strength and the ability to support a wide range of implant diameters and loading protocols. Manufacturers differentiate titanium implants through alloy composition, surface roughness, hydrophilic treatments and implant-abutment connection designs rather than through the base material alone. Zirconia is growing more quickly in selected esthetic and metal-free indications, especially among patients and clinicians seeking ceramic alternatives. Straumann and Neodent have expanded ceramic implant offerings, and Camlog markets the CERALOG system. However, narrower product ranges, different handling characteristics and the larger evidence base around titanium keep titanium dominant through the forecast period.
By End User - Dental Clinics
Dental clinics are projected to reach approximately USD 8.65 billion in implant-system demand by 2031. Implant treatment is primarily delivered through private dental practices, specialist oral-surgery and periodontology clinics, implant centers and dental service organizations rather than hospital settings. The clinic segment benefits from the expansion of corporate dentistry and specialist full-arch networks, which can standardize workflows, invest in digital equipment and purchase implants through larger supply contracts. Manufacturers increasingly support these customers with digital planning, case services, financing, education and integrated restorative systems. Hospitals remain relevant for medically complex patients, trauma and maxillofacial cases, while universities and research centers contribute to training, clinical evidence and adoption of new implant technologies but represent a much smaller commercial purchasing base.
By Geography - North America
North America is projected to generate approximately USD 3.75 billion in dental implant revenue by 2031. The region combines high dental expenditure, widespread specialist practice, mature digital dentistry adoption and a large premium implant market. Straumann, Envista, Dentsply Sirona, BioHorizons, ZimVie, MegaGen and other suppliers maintain substantial U.S. commercial operations, while full-arch treatment networks have increased the visibility of implant-supported rehabilitation. Europe remains another major implantology market with strong penetration in Germany, Italy, Spain and other countries, while Asia Pacific is expected to expand faster through rising treatment volumes, local manufacturing and value-oriented brands. China remains strategically important despite procurement-related price pressure, and South Korea has developed a large implant manufacturing base led by Osstem, Dentium and MegaGen.
Competitive Environment
The market is led by manufacturers that combine implant hardware with prosthetic components, digital workflows, regenerative products and clinical education. Straumann Group has the strongest global implantology position and uses Straumann for the premium segment alongside Neodent and other challenger brands. Envista competes through Nobel Biocare, Implant Direct and Alpha-Bio Tec, while Dentsply Sirona combines Astra Tech Implant System and MIS with a broader digital dentistry portfolio. Osstem, Dentium and MegaGen have built globally competitive positions from South Korea, particularly in value and mid-priced systems. Henry Schein participates through BioHorizons Camlog, and ZimVie remains a significant dental implant supplier after becoming privately held under ARCHIMED in October 2025.
Competitive differentiation is shifting toward treatment ecosystems rather than isolated implant specifications. Premium suppliers emphasize clinical evidence, surface technologies, immediate protocols, guided surgery and restorative integration, while challenger brands compete through price, simplified workflows and geographic expansion. Local manufacturing is also becoming more important. Straumann has expanded implant production in China and Brazil, while multiple Korean manufacturers use domestic scale to support international distribution. Because clinicians often standardize around one or two implant systems and maintain dedicated surgical kits, prosthetic inventories and training, switching costs can be meaningful even when competing fixtures appear technically similar.
Recent Developments
September 2026: MegaGen America announced the launch of the BLUEDIAMOND ZYGOMA implant system for complex full-arch rehabilitation, following U.S. FDA clearance of MegaGen's zygomatic implant system in June 2026.
June 2026: BioHorizons launched Pro Zygoma, its first remote-anchorage implant, targeting graftless full-arch treatment in patients with severely resorbed maxillae.
February 2026: Nobel Biocare acquired Versah, adding Densah burs and osseodensification technology to its implant and regenerative workflow portfolio.
February 2026: Straumann reported that more than one million iEXCEL implants had been sold during 2025 and continued expanding the system globally across premium implantology markets.
December 2025: Nobel Biocare added the DEXIS Imprevo intraoral scanner to its digital dentistry portfolio, strengthening integration between scanning, diagnostics, planning and implant restoration workflows.
Dental Implants Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 8.30 billion
Total Market Size in 2031
USD 11.55 billion
Forecast Unit
USD Billion
Growth Rate
6.8%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Type, Material, End-User, Geography
Companies
Straumann Group
Envista Holdings Corporation (Nobel Biocare
Implant Direct
Alpha-Bio Tec)
Dentsply Sirona Inc.
Osstem Implant Co. Ltd.
Dentium Co. Ltd.
MegaGen Implant Co. Ltd.
ZimVie Inc.
Market Segmentation
By Type
Endosteal Implants
Subperiosteal Implants
Zygomatic Implants
By Material
Titanium and Titanium Alloys
Zirconia and Ceramic Materials
Other Materials
By End User
Dental Clinics
Hospitals
Academic and Research Institutions
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Large Untreated Tooth-Loss Pool Supports Long-Term Procedure Growth
3.1.2. Clinical Education and Value-Segment Expansion Are Increasing Implant Access
3.2. Market Restraint
3.2.1. High Out-of-Pocket Treatment Costs and Procedure Complexity Restrict Patient Conversion
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Digital Implant Planning and Guided Surgery
4.2. Immediate Placement and Loading Systems
4.3. Zirconia and Metal-Free Implant Systems
4.4. Zygomatic and Full-Arch Implant Solutions
5. DENTAL IMPLANTS MARKET BY TYPE
5.1. Introduction
5.2. Endosteal Implants
5.3. Subperiosteal Implants
5.4. Zygomatic Implants
6. DENTAL IMPLANTS MARKET BY MATERIAL
6.1. Introduction
6.2. Titanium and Titanium Alloys
6.3. Zirconia and Ceramic Materials
6.4. Other Materials
7. DENTAL IMPLANTS MARKET BY END USER
7.1. Introduction
7.2. Dental Clinics
7.3. Hospitals
7.4. Academic and Research Institutions
8. DENTAL IMPLANTS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Israel
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Thailand
8.6.7. Indonesia
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations