
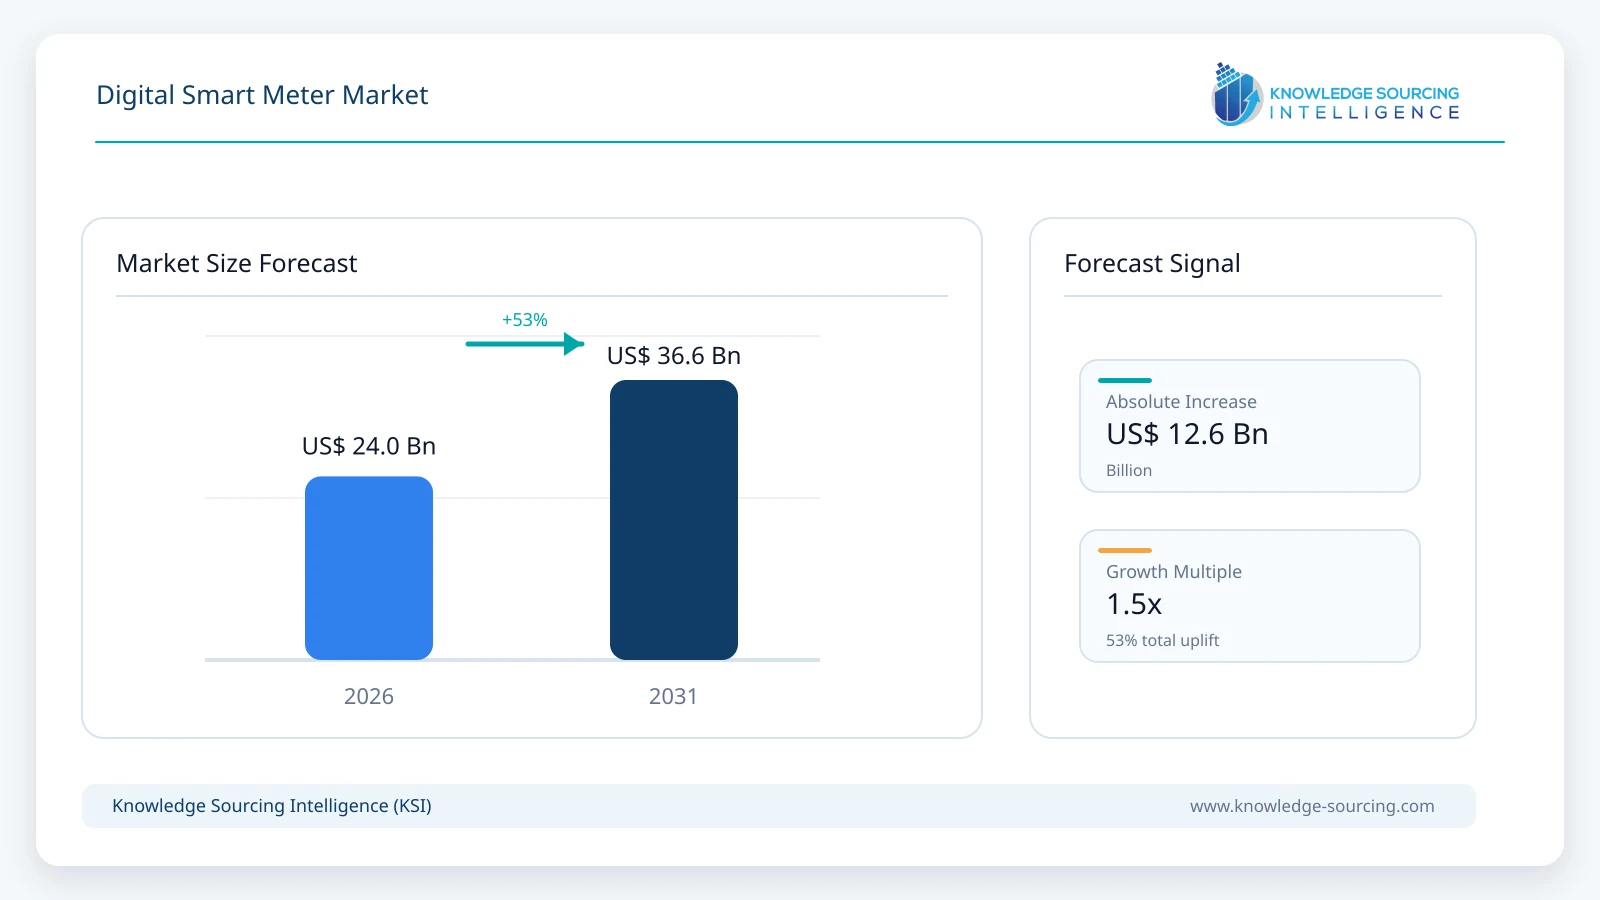
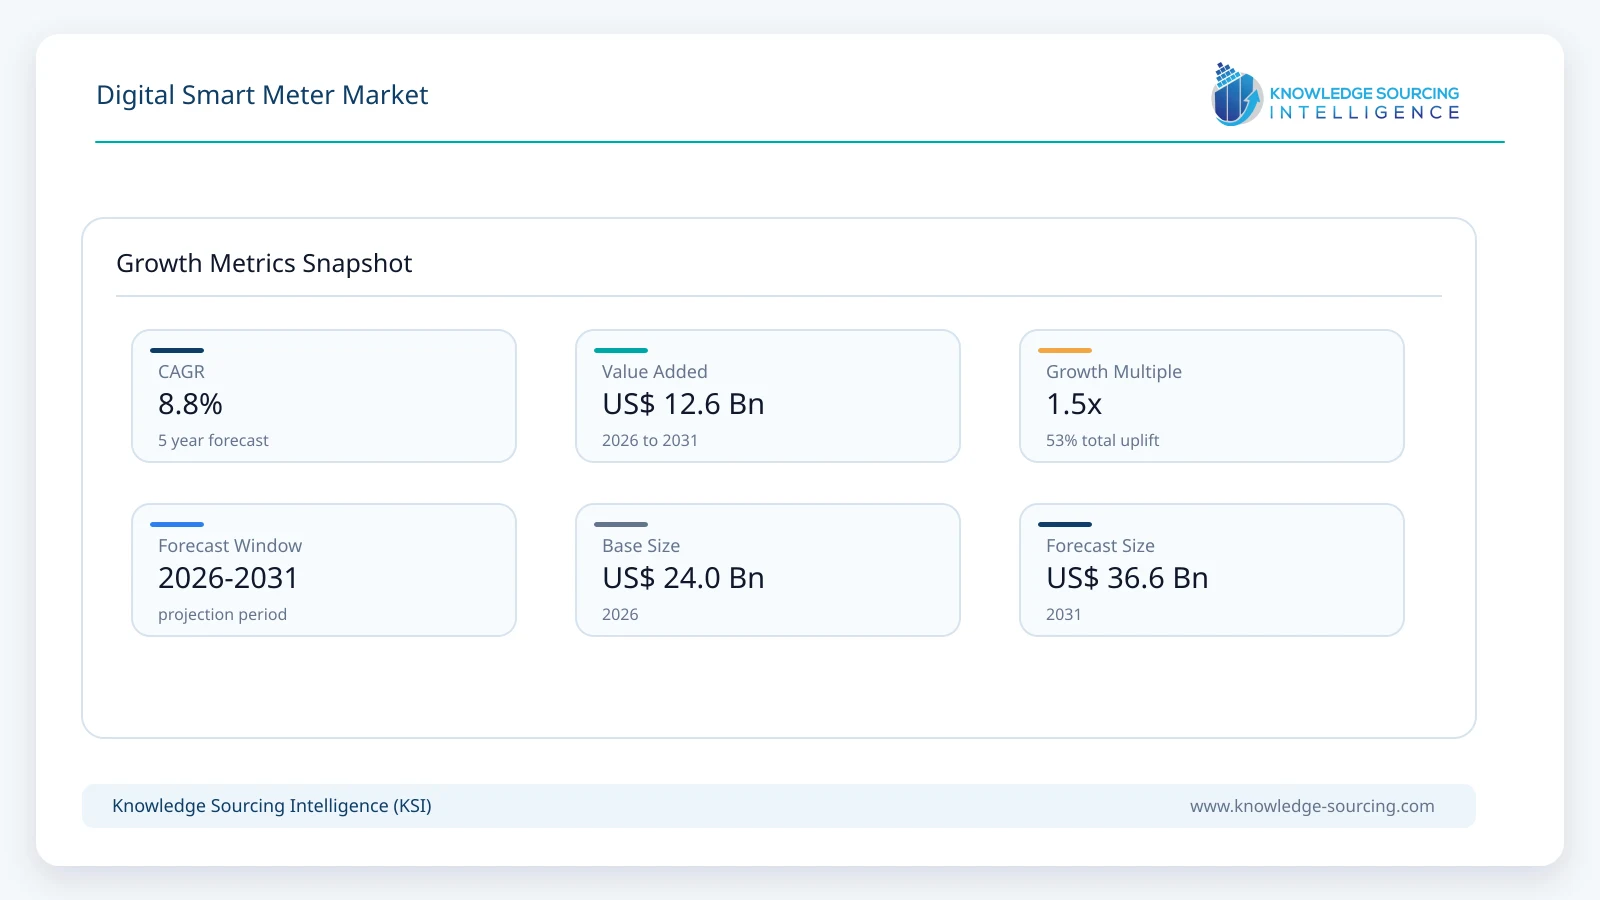
The Global Digital Smart Meter market is forecast to grow at a CAGR of 8.8%, reaching USD 36.6 billion in 2031 from USD 24.0 billion in 2026.
Highlights:
- 1Grid modernization is a primary demand catalystUtilities use smart meters to obtain granular consumption information, automate meter operations, improve outage visibility, and support distribution-system planning.
- 2Residential applications represent a major installed baseU.S. data show residential customers accounted for the largest share of AMI installations, while commercial and industrial applications remain important for interval measurement and energy management.
- 3Asia Pacific offers substantial deployment volumeIndia's RDSS alone covers sanctioned smart-metering works for 19.79 crore consumers, creating a large procurement pipeline.
- 4Interoperability is becoming a purchasing criterionItron and CHINT Global introduced a smart meter based on the DLMS Generic Companion Profile standard in March 2025, targeting simpler multi-vendor integration.
- 5Regulation is shifting toward service quality and data functionalityEuropean rules emphasize interoperability, cybersecurity, data access, privacy, and actual time-of-use information, while UK regulators have introduced compensation requirements for certain smart-meter service failures.
- 6Competition is moving toward integrated solutionsRecent supplier activity shows greater emphasis on communications, grid-edge intelligence, data platforms, and utility software alongside meter hardware.
The Digital Smart Meter Market covers electronic electricity meters that measure consumption digitally and communicate metering information through wired or wireless networks for billing, monitoring, grid management, demand response, and customer energy-management applications. The market includes single-phase and three-phase meters deployed across residential, commercial, and industrial electricity connections. Depending on the deployment architecture, digital smart meters can form part of broader advanced metering infrastructure (AMI), incorporating communications networks, head-end systems, meter-data management, analytics, and utility control applications.
The commercial importance of smart meters has shifted beyond replacing mechanical or manually read meters. Utilities now evaluate metering investments according to their ability to reduce field-service requirements, improve billing accuracy, identify abnormal consumption, support flexible tariffs, provide network visibility, and integrate distributed energy resources. This change affects procurement specifications. Meter accuracy remains fundamental, but utilities increasingly assess communication reliability, interoperability, cybersecurity, remote firmware management, data availability, lifecycle cost, and compatibility with existing utility platforms.
The United States illustrates the scale already achieved in a mature smart-metering market. According to the U.S. Energy Information Administration, utilities reported 140.5 million AMI installations in 2024, including approximately 123.0 million residential, 16.5 million commercial, and 0.94 million industrial installations. The same dataset shows AMI installations increasing from 64.7 million in 2015 to 140.5 million in 2024, while conventional AMR installations declined materially over the period.
FERC's 2025 assessment provides another indication of market maturity. Its analysis reported 128.4 million advanced meters in the United States in 2023, equivalent to a 76.8% penetration rate. Residential, commercial, and industrial customer classes each recorded advanced-meter penetration above 70%, although penetration differed materially between regions.
The investment case is different in markets where smart-meter penetration remains lower. In these countries, utilities can still justify procurement through basic operational benefits such as automated meter reading, reduced estimated billing, prepaid electricity, improved collection efficiency, and lower field-service requirements. India provides a particularly important example. Under the Revamped Distribution Sector Scheme (RDSS), smart-metering works had been sanctioned for 45 distribution utilities across 28 states and union territories, covering 19.79 crore consumers, 52.53 lakh distribution transformers, and 2.05 lakh feeders. By December 31, 2025, 3.90 crore smart meters had been installed under RDSS, while total smart-meter installations across various Indian schemes reached 5.28 crore.
The procurement model in India also demonstrates why smart-meter economics extend beyond hardware. Prepaid smart meters can provide distribution companies with advance revenue collection, lower receivables, reduced working-capital requirements, and improved cash flow. Consequently, utilities facing financial pressure may place greater value on integrated metering, communications, payment, and data-management capabilities than on the meter's unit price alone.
Great Britain demonstrates another demand model in which smart meters form part of a national energy-system programme. At the end of June 2026, more than 42 million smart and advanced meters were operating in homes and small businesses across Great Britain, representing 72% of all meters. Around 40 million were smart meters, with 92% operating in smart mode. During the second quarter of 2026, large suppliers installed approximately 1.1 million smart and advanced meters, including 568,000 smart-meter replacements.
Replacement demand is becoming an important component of mature markets. Utilities that have already completed large-scale deployments must replace meters affected by equipment ageing, communications technology changes, functional requirements, or end-of-life conditions. This creates a recurring revenue opportunity that differs from the initial mass-rollout cycle.
Buyer behavior is therefore becoming more sophisticated. Distribution utilities generally purchase through tenders, framework agreements, multi-year contracts, or integrated AMI programmes. Evaluation criteria can include meter accuracy, communications performance, interoperability, cybersecurity, installation requirements, warranty coverage, local technical support, data integration, and total cost of ownership. Large utilities also consider whether a supplier can support millions of endpoints over a decade or longer.
Technology adoption is similarly moving toward systems rather than isolated meters. Utilities increasingly want smart meters that can provide granular data to distribution-management platforms, demand-response programmes, customer portals, distributed-energy-resource systems, and asset-management applications. The commercial implication is that meter suppliers with strong communications, software, integration, and lifecycle-service capabilities can compete for a larger portion of utility expenditure.
The market is consequently shaped by three overlapping procurement cycles: first-time smart-meter deployment, replacement of legacy or ageing smart meters, and capability upgrades involving communications, edge intelligence, cybersecurity, or interoperability. The relative importance of these cycles varies substantially by country.
Market Drivers
Utility Needs to Reduce Metering and Field-Service Costs
Traditional meter-reading models require recurring field visits, workforce scheduling, vehicle deployment, and manual data collection. Digital smart meters replace much of this activity with automated data transmission.
The economic benefit becomes particularly important for utilities with large geographically dispersed customer bases. Remote reading can reduce the frequency of physical visits while allowing utilities to obtain consumption information more consistently. The business case becomes stronger where labor costs, difficult terrain, extreme weather, or security conditions make manual meter reading expensive.
The U.S. Department of Energy describes AMI as a system combining two-way communications, smart meters, utility databases, and energy-management systems. Its stated applications include demand response, customer energy management, and more reliable utility operations.
For buyers, the result is a shift from evaluating meters purely as billing instruments toward assessing their contribution to operational expenditure reduction. Suppliers therefore compete on communications reliability, installation simplicity, remote diagnostics, and software compatibility as much as measurement performance.
Expansion of Distributed Energy Resources and Flexible Loads
Solar rooftop, battery storage, electric vehicles, heat pumps, and flexible commercial loads complicate conventional distribution planning. Utilities need more granular information about where electricity is consumed, generated, or shifted.
Smart meters provide a data layer between customers and the distribution network. Their value increases when utilities integrate meter information with distributed-energy-resource management, distribution automation, outage management, and demand-response systems.
This trend is particularly important in mature electricity systems where the challenge is not simply adding meters but extracting more operational value from the installed base. Itron's 2025 collaboration with Schneider Electric, for example, connects distributed-intelligence-enabled meters with Schneider Electric's distribution-management environment to provide greater visibility into load, voltage, transformers, and distributed energy resources.
The commercial consequence is higher demand for meters capable of supporting advanced communications and local intelligence rather than basic automated reading alone.
Government-Supported Mass Deployment Programmes
Government policy can materially reduce the investment barrier for utilities. India provides a strong example through RDSS, where smart metering is explicitly connected to distribution-sector efficiency and financial sustainability. The scheme's sanctioned scale creates procurement requirements for millions of endpoints rather than isolated pilot installations.
Australia has adopted another policy model. The Australian Energy Market Commission introduced rules requiring smart meters to be deployed across the National Electricity Market by 2030. The Australian Government stated that the rollout beginning in December 2025 would support improved network information, outage response, rooftop solar, batteries, and electric vehicles.
Such programmes create predictable demand but also place pressure on suppliers to meet standardized technical requirements, delivery schedules, installation capacity, and customer-protection obligations.
Demand for Better Billing and Revenue Management
Smart meters can provide utilities with actual consumption data instead of relying on estimated readings. This reduces disputes and supports more accurate billing.
The benefit is especially important for utilities operating under prepaid models or in markets where collection losses are substantial. India's Ministry of Power specifically identifies improved revenue collection, lower receivables, interest savings, and better cash flow as benefits associated with prepaid smart metering.
Consequently, smart-meter procurement can be justified through financial performance rather than grid modernization alone. This broadens the addressable customer base to utilities where technical grid automation is not yet the primary investment objective.
Greater Use of Time-Based Electricity Pricing
Smart meters provide the measurement capability required for time-of-use tariffs, demand-response programmes, and other pricing structures that vary according to system conditions.
European Union electricity-market rules require smart-metering systems, where deployed, to provide actual consumption information and support access to historical and near-real-time data. The rules also emphasize interoperability with consumer energy-management systems and smart grids.
As utilities introduce more flexible tariffs, meters become an enabling infrastructure component. Buyers therefore increasingly consider measurement intervals, communication latency, data availability, cybersecurity, and integration capability when specifying equipment.
Market Restraints and Challenges
High Upfront Deployment and Integration Costs
Large-scale smart-meter programmes require more than meter procurement. Utilities may need communications networks, head-end systems, meter-data management, cybersecurity controls, customer platforms, installation teams, testing facilities, and system integration.
This makes total project cost considerably more important than the meter's quoted unit price. Utilities with constrained capital budgets may delay deployment when the expected operating savings do not justify the initial investment.
A practical mitigation approach is phased deployment. Utilities can prioritize high-loss areas, dense customer clusters, regions with expensive manual reading, or areas requiring improved distribution visibility. Modular communications and meter-agnostic systems can also reduce the cost of future upgrades.
Interoperability and Legacy-System Constraints
Utilities often operate heterogeneous technology estates built over several decades. Replacing meters without considering existing head-end, billing, customer-information, outage-management, and distribution-management systems can create integration problems.
Interoperability is therefore becoming a procurement requirement. Itron's March 2025 collaboration with CHINT Global specifically addressed the use of the DLMS Generic Companion Profile to simplify integration across smart-meter technologies and reduce custom interface requirements.
Suppliers that cannot integrate with established utility systems may face longer qualification cycles or exclusion from large tenders.
Cybersecurity and Data-Privacy Requirements
Smart meters expand the digital attack surface of electricity distribution networks. Each connected endpoint represents a potential communication path into a wider infrastructure ecosystem.
Regulatory requirements increasingly reflect this concern. EU electricity-market rules require smart-meter security and data communication to comply with relevant security requirements while also protecting customer privacy and personal data.
For suppliers, cybersecurity can increase development, certification, testing, software-maintenance, and lifecycle-support costs. Utilities must also establish access controls and data-governance processes. The challenge is particularly important when meters support remote firmware updates, remote disconnection, or distributed intelligence.
Communications Technology Obsolescence
A smart meter can remain physically functional while its communication technology becomes obsolete. Network shutdowns, spectrum changes, coverage limitations, or changes in communications standards can force utilities to replace otherwise serviceable equipment.
This issue creates both a risk and an aftermarket opportunity. Suppliers increasingly need modular communication architecture, remote upgrade capability, long-term support commitments, and compatibility with multiple network technologies.
The UK provides a relevant example. Honeywell announced in September 2025 that it would supply advanced smart communication modules and batteries for 67,000 gas meters as part of an upgrade programme responding partly to the UK's planned 2G network shutdown.
Customer Acceptance and Installation Performance
Mass deployment depends on successful installation at customer premises. Failed appointments, communication problems, inaccurate installation records, or unclear customer communication can undermine programme economics.
Regulators are therefore placing greater emphasis on service quality. Ofgem announced in January 2026 that new standards would require automatic £40 compensation in specified circumstances, including installation delays exceeding six weeks and certain unresolved smart-meter problems.
Utilities and suppliers consequently face pressure to improve installation scheduling, technical support, customer communication, and post-installation troubleshooting.
Major Segment Analysis
Residential Segment
The residential segment represents the most commercially important end-user segment because household electricity connections generally account for the largest number of metering points. The scale of the installed base creates substantial procurement volumes, while replacement cycles generate recurring demand after initial deployment programmes mature.
U.S. government statistics illustrate the scale. EIA reported approximately 123.0 million residential AMI installations in 2024, compared with 16.5 million commercial and 0.94 million industrial installations. Residential AMI therefore represents the largest volume opportunity within the U.S. digital-metering ecosystem.
Residential procurement differs from industrial metering because utilities typically prioritize mass-installation economics, compact designs, reliable communications, remote configuration, cybersecurity, and low failure rates. Installation labor can become a major project cost, particularly where meters are located inside homes or require additional communications equipment.
Prepayment and flexible tariff capabilities can also increase residential value. In India, the government explicitly links prepaid smart metering with improved revenue collection and lower receivables for distribution companies. This creates a strong financial incentive for utilities operating in regions with collection challenges.
Residential smart meters also support customer-facing services. In Great Britain, the government identifies automatic readings, accurate billing, consumption information, smart tariffs, and demand management among the benefits of the national programme.
Competitive differentiation in this segment is therefore shifting from basic measurement accuracy toward lifecycle economics. Suppliers need to demonstrate reliable communications, low installation complexity, long service life, secure firmware management, compatibility with utility platforms, and responsive technical support.
The segment also offers significant replacement demand. Great Britain recorded approximately 568,000 smart-meter replacements by large suppliers during the second quarter of 2026 alone. These replacements included meters reaching the end of operational life and meters requiring compatibility with newer communications technology.
For suppliers, the residential segment therefore combines very large endpoint volumes with recurring replacement opportunities. Utilities, meanwhile, increasingly view the meter as an infrastructure asset that must remain operational across long programme lifecycles.
Regional Analysis
North America
North America represents a mature smart-metering market, particularly in the United States. EIA data show 140.5 million AMI installations in the U.S. in 2024. FERC's 2025 assessment reported advanced-meter penetration of 76.8% in 2023, although regional penetration varied considerably.
Demand is increasingly driven by replacement, grid modernization, distributed energy resources, outage management, and the need to extract greater value from existing AMI networks. Utilities are moving from deployment-oriented procurement toward capability-oriented investment.
U.S. DOE project records also show continued investment in AMI upgrades and grid-resilience programmes. Projects during 2025 included new AMI implementation, replacement of existing AMI meters, communications-network upgrades, and AMI applications for outage reporting and customer usage information.
Canada follows a similar modernization direction, although deployment intensity varies by province and utility. Procurement decisions are influenced by utility ownership structures, provincial regulation, communications availability, cybersecurity requirements, and the economics of replacing legacy systems.
Mexico remains a more selective opportunity, with demand influenced by utility modernization priorities, distribution efficiency requirements, and infrastructure investment. Compared with the U.S., procurement is more sensitive to project financing, regulatory priorities, and deployment economics.
Europe
Europe combines mature deployments with substantial replacement and modernization opportunities. EU electricity-market rules establish detailed requirements covering interoperability, cybersecurity, data protection, consumer data access, and time-of-use information. Where smart-meter deployment is positively assessed, EU legislation provides for a target of at least 80% customer coverage within specified timeframes.
The region's procurement environment is therefore strongly standards-driven. Suppliers need to demonstrate technical compliance rather than compete solely on price.
The UK remains one of Europe's most visible deployment markets. By June 2026, more than 42 million smart and advanced meters were operating in Great Britain, representing 72% of all meters. The market is transitioning from pure rollout toward replacement, service quality, communications continuity, and system optimization.
Poland also illustrates continued deployment activity. Iskraemeco announced in March 2025 that it would supply smart electricity meters for Enea Operator's programme involving approximately three million remotely read meters by 2030. In April 2025, the company also announced a contract with TAURON Dystrybucja for a remote-reading system associated with an AMI upgrade programme running from 2025 to 2032.
European buyers are consequently placing greater weight on interoperability, data security, long-term communications support, and integration with flexible-grid applications.
Asia Pacific
Asia Pacific represents one of the largest volume opportunities because several countries combine large electricity customer bases with active distribution-system modernization.
India is particularly important. Government data show 5.28 crore smart meters installed nationwide across schemes by December 2025, including 3.90 crore under RDSS. The sanctioned RDSS programme covers 19.79 crore consumer smart meters.
China's large electricity system and extensive utility infrastructure create substantial potential for digital metering, although procurement is strongly influenced by domestic utility structures, local standards, manufacturing capabilities, and government planning.
Japan and South Korea have mature electricity infrastructures and stronger emphasis on system reliability, data management, distributed energy integration, and advanced grid functions. Australia is entering another important deployment phase. AEMC's rule requires smart meters to be deployed across the National Electricity Market by 2030, with rollout beginning in December 2025.
The region's principal constraint is market heterogeneity. Supplier strategies must accommodate different regulatory systems, communication technologies, utility structures, procurement procedures, and local manufacturing requirements.
Middle East and Africa
The Middle East presents opportunities through utility modernization, infrastructure expansion, prepaid electricity programmes, and efforts to improve consumption visibility. Saudi Arabia and the UAE have relatively strong utility investment capacity and can support large-scale digital infrastructure programmes.
The African market is more fragmented. Utilities often face high non-technical losses, constrained capital budgets, uneven communications infrastructure, and challenges in recovering electricity revenues. These conditions can nevertheless strengthen the economic case for prepaid smart meters and remote monitoring.
Supplier competition in the region often depends on local partnerships, financing arrangements, installation capability, technical support, and the ability to operate under demanding environmental conditions. Projects may also require localized manufacturing or assembly arrangements.
South America
South America offers a mixed deployment environment. Brazil is the largest opportunity within the regional grouping because of its electricity-system scale and utility modernization requirements. Smart meters can support loss reduction, remote services, billing accuracy, and distributed-energy integration.
Argentina and other South American markets face greater variability in investment capacity and regulatory conditions. Procurement can therefore be project-specific rather than continuous.
The principal commercial opportunity is to address utilities where smart metering produces measurable operational or revenue benefits. Suppliers that can demonstrate a clear payback through reduced field operations, better collection, or loss identification are likely to be better positioned than suppliers competing only through hardware pricing.
Competitive Landscape
The competitive structure includes multinational electrical-equipment companies, specialist metering suppliers, utility-technology providers, and businesses combining meters with communications or software.
The supplied competitive universe includes ABB Ltd., Aclara Technologies LLC, Holley Technology Ltd., Honeywell International Inc., Iskraemeco Group, Itron Inc., Networked Energy Services, and Schneider Electric.
Competition increasingly depends on the ability to supply complete utility solutions rather than standalone meters. Itron's 2025 collaboration with Schneider Electric illustrates this direction, integrating Itron grid-edge intelligence with Schneider Electric's digital-grid capabilities and Microsoft data and AI infrastructure.
Interoperability is another competitive differentiator. Itron and CHINT Global's 2025 GCP-compliant meter initiative illustrates supplier efforts to reduce proprietary integration barriers and make multi-vendor AMI deployment easier for utilities.
Aclara also demonstrated the importance of regional manufacturing and established utility relationships. In March 2026, Hubbell announced that Aclara Meters Philippines had signed a two-year agreement with MERALCO to supply approximately 72,000 smart meters as the initial phase of a 10-year AMI programme targeting approximately 12 million endpoints.
Honeywell is expanding competition beyond the physical meter into connectivity and utility-management systems. In March 2025, Honeywell announced that its smart meters would incorporate Verizon 5G connectivity, supporting remote data access and utility-management applications.
Iskraemeco's recent European activity demonstrates another competitive model based on standards, regional projects, and AMI system integration. Its 2025 projects with Enea Operator and TAURON Dystrybucja show how long-term utility contracts can combine meter supply with remote-reading and head-end infrastructure.
The resulting competition is multidimensional. Hardware price remains relevant, particularly in high-volume tenders, but utilities also compare communications architecture, interoperability, cybersecurity, software integration, local service capabilities, installation economics, warranty terms, and lifecycle support.
Recent Developments
July 2026: Adani Energy Solutions reported 13.44 million cumulative smart meter installations and maintained a 24.6-million-meter order book, strengthening its position in India’s digital metering infrastructure.
June 2026: Itron announced collaboration with Watercare Services to deploy 100,000 Intelis wSource digital water meters, supporting Auckland’s broader plan to connect nearly 500,000 smart meters.
June 2026: Adani Energy Solutions signed an agreement to acquire 100% of IntelliSmart for INR 3,050 crore, targeting a combined portfolio exceeding 4.7 crore smart meters.
March 2026: Landis+Gyr announced Festival Hydro’s deployment of its Revelo platform, adding advanced grid sensing and metering capabilities to support demand flexibility, planning, and system reliability.
February 2026: Adani Energy Solutions announced it had crossed 1 crore electricity smart meters, becoming the first Indian player to reach this deployment milestone across multiple distribution companies.
Regulatory and Policy Environment
Regulation is one of the strongest structural influences on digital smart-meter procurement because electricity meters are part of regulated utility infrastructure.
In the European Union, Directive 2019/944 establishes requirements for smart-metering systems, including interoperability, accurate measurement, customer access to consumption information, cybersecurity, privacy, and support for demand response. Where smart-meter deployment proceeds following a positive assessment, the directive provides for at least 80% customer coverage within specified deployment periods.
The European framework also creates a compliance requirement for older systems. Smart-metering installations that began before July 2019 may continue during their lifetime, but systems that fail specified requirements cannot remain in operation beyond July 2031. This provision can support replacement demand for legacy equipment that does not satisfy current functional or security requirements.
In Great Britain, Ofgem regulates metering-related requirements while the Department for Energy Security and Net Zero oversees the national smart-metering programme. In January 2026, Ofgem approved tougher service standards that introduced automatic compensation for specified installation and repair failures.
The UK programme also demonstrates the importance of communications infrastructure. Ofgem selected DCC2 Ltd as the successor Smart Meter Communication Licence holder in February 2026, with responsibility for governance, cost control, business strategy, and technology-roadmap functions.
In the United States, FERC annually assesses advanced metering and demand response, while EIA collects utility data covering AMI deployment by state, sector, and balancing authority. The regulatory environment is more decentralized than in Europe, making state-level policy and utility investment plans particularly important.
India's RDSS represents a direct government-led mechanism for smart-meter adoption. Its scale links metering deployment with distribution-sector financial and operational improvements. Cybersecurity and data privacy have also become explicit policy considerations within the programme.
Australia's national-market rules provide another important regulatory signal. AEMC's final rule requires smart meters across the National Electricity Market by 2030, while incorporating customer protections around installation costs, tariff changes, and information.
Across markets, regulation is therefore moving beyond minimum measurement accuracy. Procurement increasingly incorporates communications reliability, interoperability, cybersecurity, data governance, customer rights, and lifecycle support.
Outlook and Strategic Implications
The Digital Smart Meter Market is entering a phase in which replacement and capability upgrades become as important as first-time deployments. Mature markets already have large installed bases, so future spending will increasingly involve replacing ageing meters, upgrading communications, improving interoperability, and adding grid-edge functionality.
Utilities are likely to prioritize projects that demonstrate measurable operational returns. Procurement teams will assess reduced field visits, fewer estimated bills, lower collection losses, improved outage management, better distribution visibility, and support for flexible tariffs. In emerging markets, revenue recovery may remain a stronger investment justification than advanced grid analytics.
The residential segment should remain commercially important because of its endpoint volume. However, commercial and industrial customers can generate higher value per meter where utilities require granular measurement for demand management, power-quality monitoring, distributed generation, or complex tariff structures.
Communications architecture will remain a central technology decision. Utilities increasingly need systems that can operate across long lifecycles while accommodating changes in cellular networks, RF infrastructure, utility communication systems, and cybersecurity requirements. Suppliers with modular architectures should have an advantage when buyers seek to reduce future replacement risk.
Interoperability will also influence competitive positioning. The emergence of standards-based initiatives such as the DLMS Generic Companion Profile indicates that utilities want greater freedom to integrate equipment from multiple vendors. This can reduce vendor lock-in but also places greater pressure on suppliers to differentiate through service quality, software capabilities, reliability, lifecycle economics, and integration expertise.
The market's economics will increasingly extend into software and services. Smart meters generate data, but the commercial value depends on how utilities use that information. Meter-data management, grid-edge analytics, outage applications, demand-response systems, customer engagement, distributed-energy-resource management, and asset planning can increase the value derived from the installed meter base.
Recent supplier activity supports this shift. Itron's 2025 grid-edge initiatives and its collaboration with Schneider Electric show how meter data are being connected with broader distribution-management systems. Honeywell's integration of smart-meter connectivity with utility-management platforms points in the same direction.
Replacement planning will become a major strategic issue for utilities. Great Britain's 2026 statistics show that replacements already constitute a substantial portion of installation activity. The government reported 570,000 smart and advanced-meter replacements during the second quarter of 2026, including 568,000 smart meters. Similar replacement cycles should emerge elsewhere as early-generation smart-meter fleets reach the end of their useful lives or become incompatible with newer communications requirements.
Cybersecurity will remain a procurement differentiator rather than a secondary technical issue. Utilities will increasingly require secure authentication, encrypted communications, controlled firmware updates, access management, vulnerability monitoring, and defined vendor-support obligations. Compliance costs will rise, but failure to meet security requirements can create larger financial and operational risks.
For suppliers, the strongest strategic opportunities lie in combining hardware with communications, software, integration, and lifecycle services. Large tenders increasingly favor vendors capable of supporting long-duration programmes, while regional partnerships remain important for installation, regulatory compliance, manufacturing, and after-sales support.
For utilities, the central strategic question will shift from whether to deploy smart meters to how to extract greater value from the installed endpoint base. That requires integration between metering, distribution management, customer systems, distributed-energy resources, tariff design, and demand-response programmes.
From 2026 through 2031, procurement decisions are therefore expected to be shaped by five factors: replacement requirements, grid modernization expenditure, regulatory mandates, distributed-energy integration, and total cost of ownership. Markets with government-backed deployment programmes should continue generating large endpoint orders, while mature markets should increasingly favor replacement, communications upgrades, interoperability, cybersecurity, and grid-edge functionality.
The competitive outcome will depend less on the ability to manufacture a digital electricity meter and more on the ability to provide a dependable metering platform over its full operating life. Suppliers that combine accurate measurement with secure communications, interoperable architectures, utility software, regional support, and long-term service capabilities will be better positioned to capture high-value procurement programmes.
Digital Smart Meter Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 24.0 billion |
| Total Market Size in 2031 | USD 36.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 8.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, End-User, Geography |
| Companies |
|
Market Segmentation
By Type
Air-Jacketed Cell Culture Incubators
Water-Jacketed Cell Culture Incubators
Direct Heat Cell Culture Incubators
By Sensor Type
Infra-red (IR) Sensor
Thermal Conductivity (TC) Sensor
By Application
Pharmaceutical and Biotechnology Applications
Clinical and Diagnostic Laboratories
Academic and Research Applications
IVF Processes
Cancer Research
Stem Cell Research
Tissue Engineering and Regenerative Medicine
Other Applications
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
Japan
China
India
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base Year and Forecast Period
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Market Estimation and Forecasting
2.4. Data Validation and Triangulation
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Regulatory and Policy Environment
4.6. Analyst View
5. DIGITAL SMART METER MARKET BY TYPE
5.1. Introduction
5.2. Single Phase
5.2.1. Market Trends and Opportunities
5.2.2. Growth Prospects
5.2.3. Geographic Opportunities
5.3. Three Phase
5.3.1. Market Trends and Opportunities
5.3.2. Growth Prospects
5.3.3. Geographic Opportunities
6. DIGITAL SMART METER MARKET BY END-USER
6.1. Introduction
6.2. Residential
6.2.1. Market Trends and Opportunities
6.2.2. Growth Prospects
6.2.3. Geographic Opportunities
6.3. Commercial
6.3.1. Market Trends and Opportunities
6.3.2. Growth Prospects
6.3.3. Geographic Opportunities
6.4. Industrial
6.4.1. Market Trends and Opportunities
6.4.2. Growth Prospects
6.4.3. Geographic Opportunities
7. DIGITAL SMART METER MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By End-User
7.2.3. By Country
7.2.3.1. United States
7.2.3.1.1. Market Trends and Opportunities
7.2.3.1.2. Growth Prospects
7.2.3.2. Canada
7.2.3.2.1. Market Trends and Opportunities
7.2.3.2.2. Growth Prospects
7.2.3.3. Mexico
7.2.3.3.1. Market Trends and Opportunities
7.2.3.3.2. Growth Prospects
7.3. South America
7.3.1. By Type
7.3.2. By End-User
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.1.1. Market Trends and Opportunities
7.3.3.1.2. Growth Prospects
7.3.3.2. Argentina
7.3.3.2.1. Market Trends and Opportunities
7.3.3.2.2. Growth Prospects
7.3.3.3. Others
7.3.3.3.1. Market Trends and Opportunities
7.3.3.3.2. Growth Prospects
7.4. Europe
7.4.1. By Type
7.4.2. By End-User
7.4.3. By Country
7.4.3.1. Germany
7.4.3.1.1. Market Trends and Opportunities
7.4.3.1.2. Growth Prospects
7.4.3.2. United Kingdom
7.4.3.2.1. Market Trends and Opportunities
7.4.3.2.2. Growth Prospects
7.4.3.3. France
7.4.3.3.1. Market Trends and Opportunities
7.4.3.3.2. Growth Prospects
7.4.3.4. Spain
7.4.3.4.1. Market Trends and Opportunities
7.4.3.4.2. Growth Prospects
7.4.3.5. Others
7.4.3.5.1. Market Trends and Opportunities
7.4.3.5.2. Growth Prospects
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By End-User
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.1.1. Market Trends and Opportunities
7.5.3.1.2. Growth Prospects
7.5.3.2. United Arab Emirates
7.5.3.2.1. Market Trends and Opportunities
7.5.3.2.2. Growth Prospects
7.5.3.3. Others
7.5.3.3.1. Market Trends and Opportunities
7.5.3.3.2. Growth Prospects
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By End-User
7.6.3. By Country
7.6.3.1. China
7.6.3.1.1. Market Trends and Opportunities
7.6.3.1.2. Growth Prospects
7.6.3.2. Japan
7.6.3.2.1. Market Trends and Opportunities
7.6.3.2.2. Growth Prospects
7.6.3.3. India
7.6.3.3.1. Market Trends and Opportunities
7.6.3.3.2. Growth Prospects
7.6.3.4. South Korea
7.6.3.4.1. Market Trends and Opportunities
7.6.3.4.2. Growth Prospects
7.6.3.5. Australia
7.6.3.5.1. Market Trends and Opportunities
7.6.3.5.2. Growth Prospects
7.6.3.6. Others
7.6.3.6.1. Market Trends and Opportunities
7.6.3.6.2. Growth Prospects
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. ABB Ltd.
9.2. Aclara Technologies LLC (Hubbell Incorporated)
9.3. Holley Technology Ltd.
9.4. Honeywell International Inc.
9.5. Iskraemeco Group
9.6. Itron Inc.
9.7. Networked Energy Services
9.8. Schneider Electric
Navigate
Trusted by the world's leading organizations











