
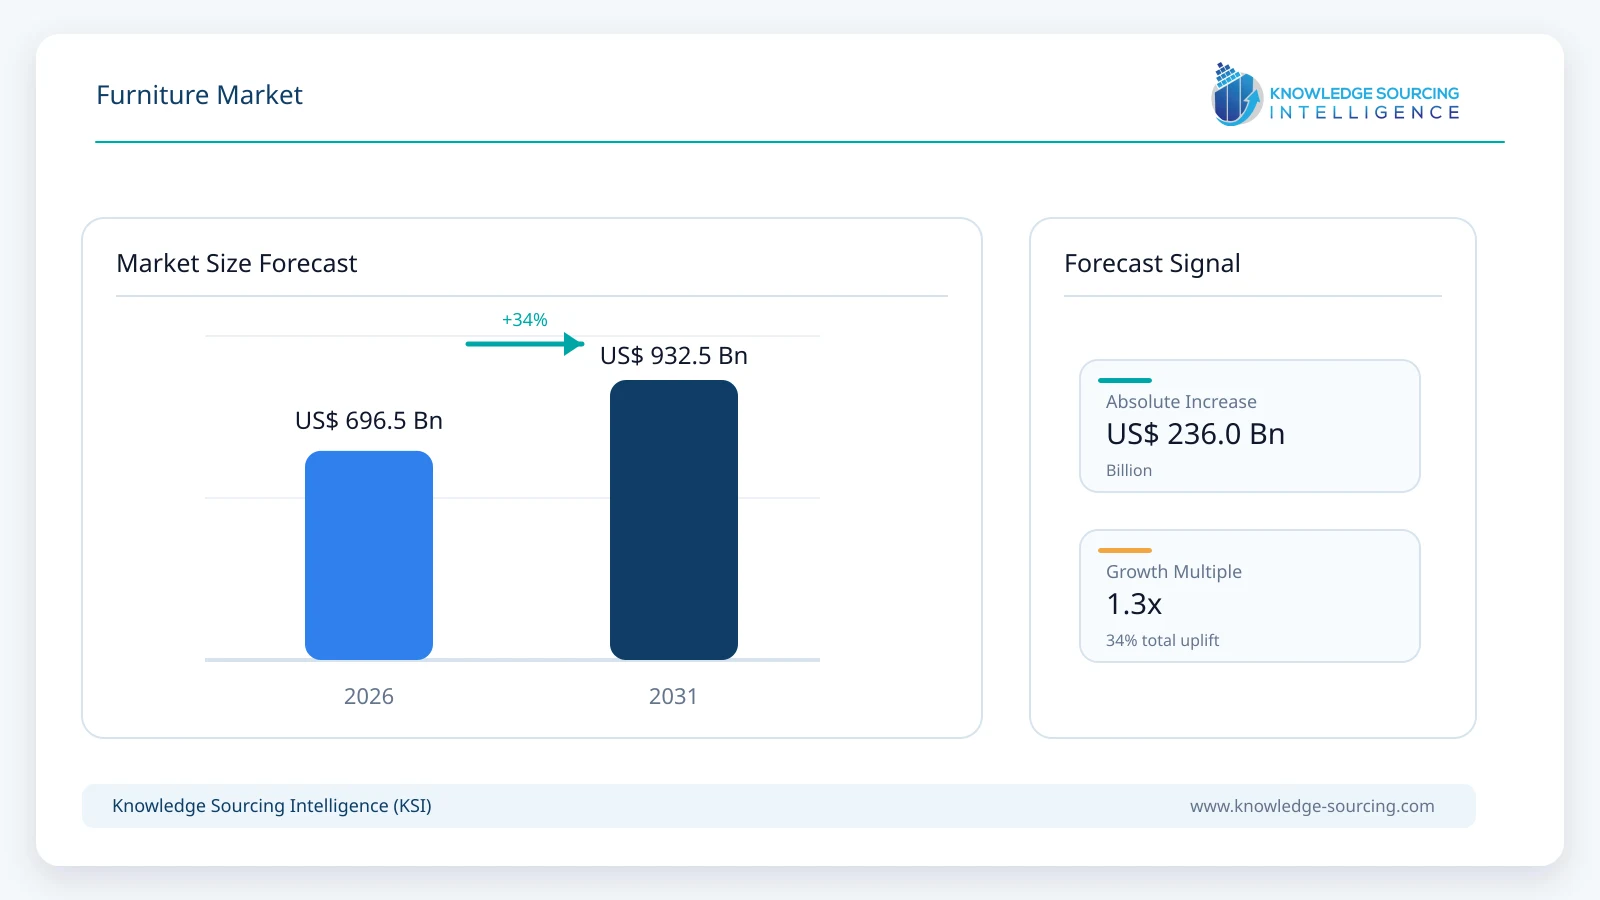
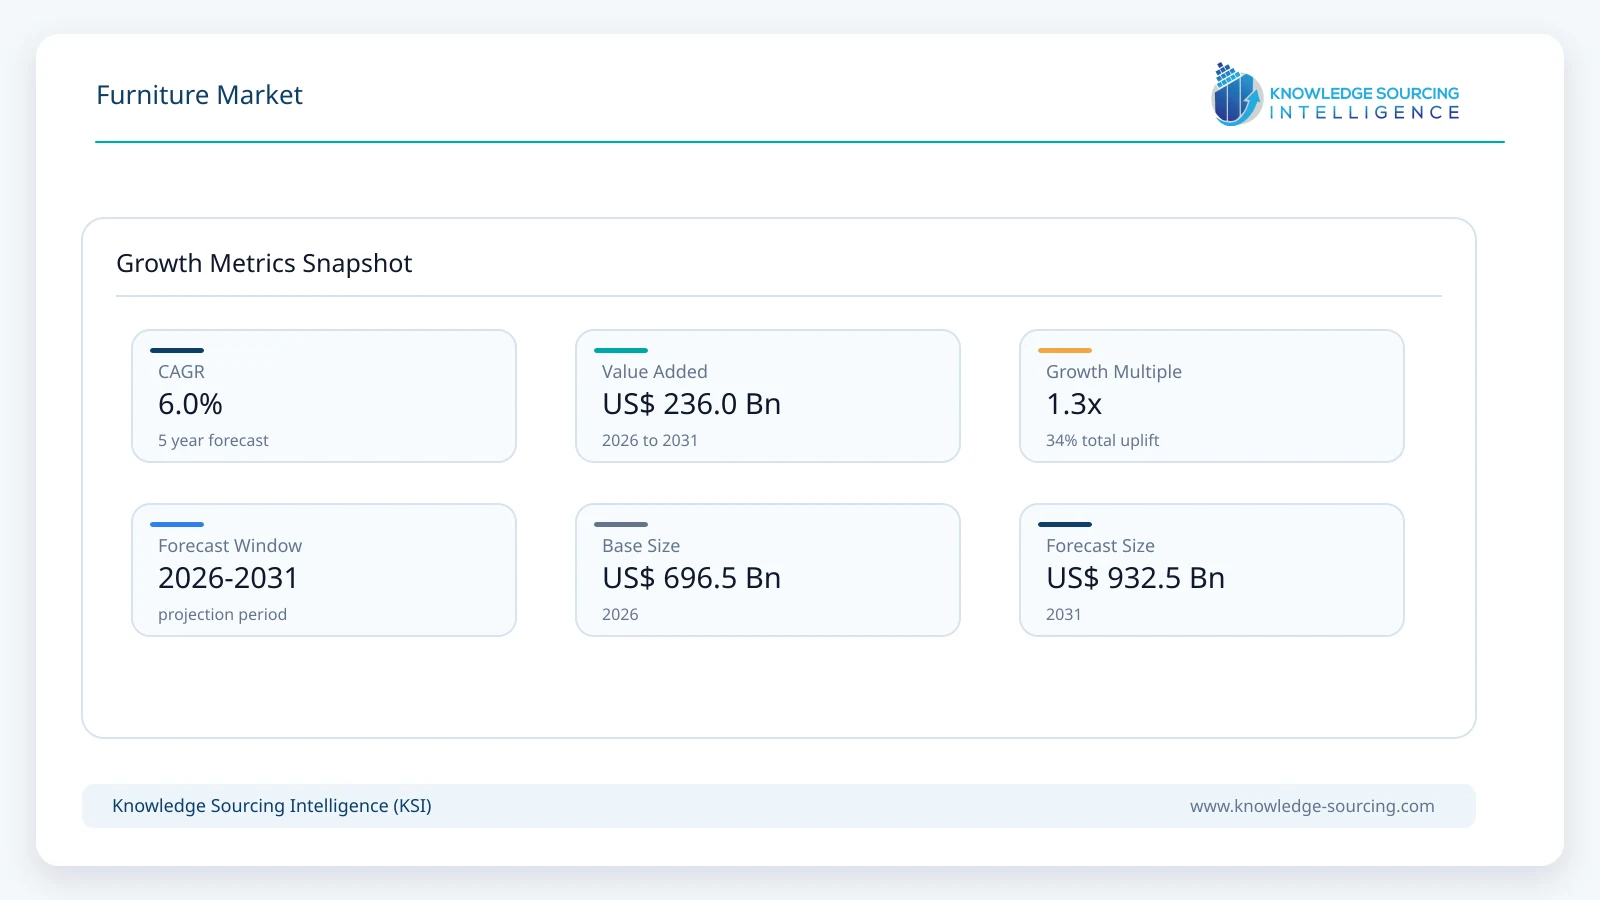
The global furniture market is forecast to grow from USD 696.5 billion in 2026 to USD 932.5 billion in 2031, representing a CAGR of 6.0% during the forecast period.
Highlights:
- 1Residential furniture accounts for approximately 67% of global furniture market value in 2026, supported by housing, replacement demand and household furnishing expenditure.
- 2Offline channels account for approximately 74% of global market value in 2026, although online furniture sales continue to grow faster as retailers improve visualization, fulfillment and omnichannel services.
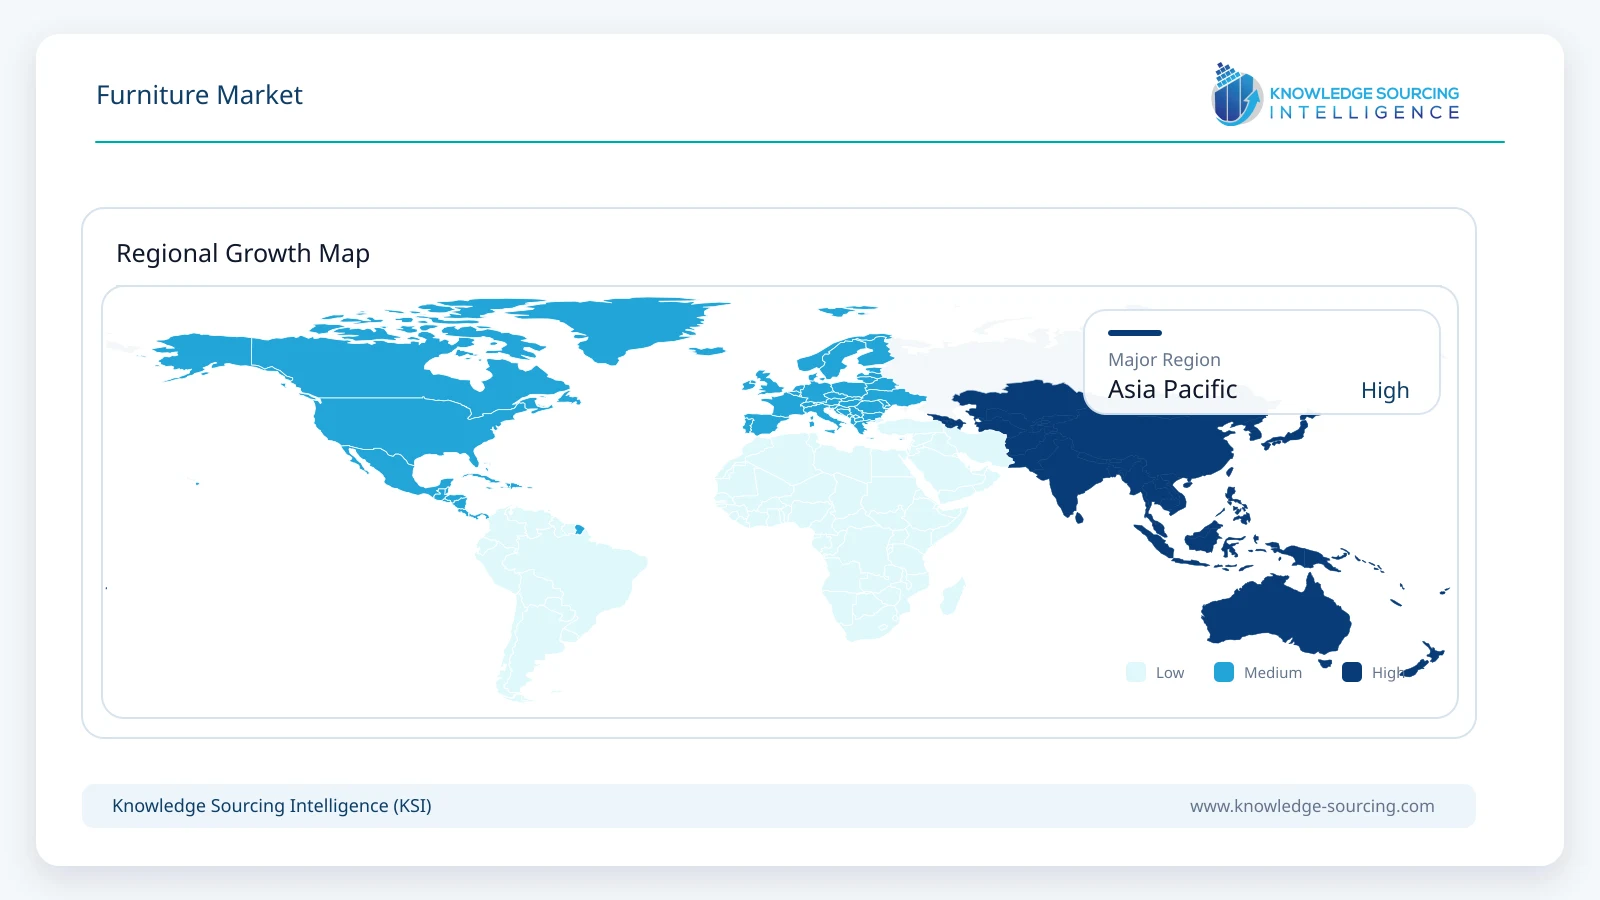
- 3Asia Pacific accounts for approximately 45% of global furniture market value in 2026, supported by its large population, manufacturing base, urbanization and expanding middle-income consumer population.
- 4China accounts for approximately 24% of global furniture market value in 2026, reflecting the country's large domestic consumer base and significant furniture manufacturing ecosystem.
- 5Circularity is becoming more commercially relevant, with major retailers expanding product repair, resale, refurbishment and buy-back models alongside conventional furniture sales.
The market includes furniture used across residential and commercial environments, covering major products such as beds, sofas, tables, chairs, wardrobes, cabinets, storage systems, office furniture and related furnishing solutions. It excludes standalone decorative accessories, household appliances and construction materials that do not perform a furniture function.
Residential demand remains the largest component of the market because furniture purchases are closely tied to household formation, housing construction, renovation, relocation and replacement cycles. Commercial demand is supported by offices, hospitality, educational facilities, healthcare environments, retail spaces and other institutional applications. Market growth therefore reflects both consumer expenditure and wider construction and real-estate activity.
The industry is also moving toward a more integrated retail model. IKEA reported EUR 44.6 billion in retail sales during FY2025 and noted that online sales represented approximately 28% of turnover, while store visits continued increasing. The combination shows that physical retail and digital furniture shopping are increasingly complementary rather than substitutes. Digital channels are particularly important during product discovery and price comparison, while stores remain valuable for testing comfort, examining material quality, consulting design specialists and arranging larger purchases.
Market Trends
Omnichannel Furniture Retail Is Becoming the Standard
Furniture retail is increasingly organized around a combination of digital discovery and physical experience. Consumers use websites, apps and marketplaces to compare dimensions, configurations, materials, prices and reviews before visiting stores or placing online orders, while retailers are integrating delivery, installation, planning and after-sales support across channels. IKEA reported that online sales represented approximately 28% of its FY2025 turnover while physical visitation increased to 915 million store visits, indicating that digital growth does not necessarily reduce the commercial relevance of physical locations. Large furniture purchases remain more complicated than conventional e-commerce because dimensions, room compatibility, comfort, assembly and logistics influence conversion. Retailers are therefore investing in visualization tools, room planning, smaller urban stores, pickup points and appointment-based design services rather than relying solely on large warehouse formats. This supports online growth while preserving physical retail's role in higher-consideration purchases.
Furniture Design Is Increasingly Focused on Flexibility and Space Efficiency
Urban households, smaller living spaces and hybrid working patterns are strengthening demand for modular, multifunctional and easily reconfigurable furniture. Storage beds, expandable dining tables, modular sofas, compact workstations and furniture designed for repeated assembly and relocation allow consumers to extract more functionality from limited space. This trend also influences product engineering because manufacturers increasingly need to balance low weight, structural strength, flat-pack transportation, repairability and ease of assembly. IKEA's FY2025 product strategy emphasized easier assembly, disassembly and reuse across major furniture systems, reflecting broader industry interest in extending product life and supporting customers who move more frequently. Commercial furniture is experiencing a related shift as offices adopt more flexible layouts, collaborative spaces and shared workstations rather than traditional fixed desk configurations, encouraging manufacturers to develop modular systems that can be adapted without completely refurnishing a workspace.
Circular Furniture Models Are Moving Beyond Sustainability Messaging
Furniture companies are increasingly integrating circularity into product design, materials and retail services. IKEA's current circularity strategy targets greater use of recycled and renewable materials while designing products for reuse, repair, refurbishment and recycling, and it plans circular services across at least 80% of its markets by FY2030. Buy-back and resale programs are already operating in multiple markets, allowing retailers to create second-life furniture channels while providing customers with lower-priced alternatives. Circularity has a stronger commercial rationale in furniture than in many fast-moving consumer categories because products can remain usable for years and often retain resale value. Manufacturers are therefore experimenting with removable covers, standardized components, spare parts, recycled wood and metals, refurbishment and resale. The development can reduce material dependence while also creating new customer touchpoints after the original sale.
Market Drivers
Housing and Residential Development Sustain Furniture Replacement and First-Time Demand
Residential furniture demand is structurally linked to housing activity because newly completed homes require furnishing while relocation, renovation and household formation create recurring replacement demand. Urbanization is especially relevant in developing economies where expanding cities generate sustained demand for apartments, storage systems, beds, seating and dining furniture. Furniture demand does not depend exclusively on new construction because existing households replace products according to age, changing family requirements, design preferences and home renovation. The growth of smaller urban housing is also changing the type of furniture purchased, increasing demand for compact, modular and multifunctional designs. Manufacturers able to combine affordability, efficient shipping and flexible use therefore address a broader consumer base than premium design-oriented suppliers alone. In emerging markets, organized furniture retail and digital distribution add another growth layer by giving consumers greater access to standardized branded products that were previously concentrated in major metropolitan areas.
Hospitality and Commercial Infrastructure Support Non-Residential Demand
Hotels, restaurants, offices, healthcare facilities, educational buildings and other commercial properties require substantial furniture expenditure during construction, refurbishment and brand repositioning. Hospitality is particularly furniture-intensive because guest rooms, restaurants, lounges and public areas must be furnished and periodically renovated. Office furniture demand is more complex following changes in workplace utilization, but hybrid working has not eliminated commercial furniture expenditure. Instead, many employers are redesigning spaces around collaboration, ergonomics, flexible seating and shared work environments. Commercial customers typically place greater emphasis on durability, standardized replacement, installation and lifecycle service than residential consumers, creating opportunities for specialist suppliers such as Steelcase, MillerKnoll, Haworth, HNI and Kokuyo. Growth therefore comes from both greenfield commercial construction and the reconfiguration of existing properties, particularly where companies or hospitality operators need to update space utilization rather than expand overall floor area.
Digital Distribution Is Expanding Market Accessibility
Furniture has historically been difficult to sell online because of product size, transportation cost and the importance of physical evaluation. Improved digital visualization, product photography, configurators, reviews, financing and home delivery are reducing these barriers. Large retailers increasingly allow shoppers to move between online planning and physical fulfillment, while digital-native companies use extensive catalogs without maintaining equally large showroom networks. IKEA's online turnover share and continued investment in smaller store formats illustrate how furniture distribution is becoming channel-agnostic rather than purely store-led. Online channels are particularly valuable for standardized products such as shelving, desks, storage, occasional furniture and flat-pack ranges where dimensions and specifications can be communicated clearly. Larger upholstered furniture remains more dependent on physical experience, but even these purchases increasingly begin online. As logistics improve, digital penetration is expected to increase without removing the role of physical stores.
Market Restraints and Challenges
Furniture Demand Is Sensitive to Housing and Consumer Spending Cycles
Furniture is a durable purchase that households can postpone when disposable income, housing transactions or consumer confidence weaken. Unlike essential consumables, sofas, tables, beds and storage systems are often used beyond their expected replacement cycle during economic uncertainty. Higher mortgage rates or weaker housing turnover can also reduce demand because moving households represent an important source of furniture purchases. Premium brands are particularly exposed to discretionary spending, while value-oriented suppliers can gain share as consumers trade down rather than cancel purchases entirely. IKEA's decision to reduce prices substantially across its range contributed to higher customer numbers and volumes in FY2025 even though nominal retail sales declined slightly, demonstrating the importance of affordability when consumers remain price-sensitive. The market therefore grows structurally over time but can experience significant short-term variation according to housing conditions and household purchasing power.
Raw Material and Freight Volatility Affect Margins
Furniture manufacturing uses wood, engineered panels, steel, aluminium, foam, textiles, leather, plastics, adhesives and numerous hardware components, exposing producers to several commodity and supply-chain cycles simultaneously. Large and bulky finished products also carry relatively high transportation and warehousing costs. Manufacturers can reduce exposure through flat-pack design, lightweight materials, regional sourcing and automated production, but raw-material inflation can still pressure margins or require retail price increases. Sustainability requirements add another layer because companies increasingly seek certified wood, recycled materials and lower-emission production without materially increasing final product prices. Larger global manufacturers can use procurement scale to manage these pressures more effectively, while smaller producers may have greater difficulty absorbing changes in material and freight costs.
Furniture Market Segment Analysis
By Furniture Type
Residential
Residential furniture is projected to generate approximately USD 622 billion by 2031, remaining the largest market segment as household formation, renovation, replacement demand and urban housing sustain purchases across bedroom, living-room, kitchen, dining and storage categories. Residential demand also provides the broadest range of price points, from mass-market flat-pack products to bespoke and luxury furniture, allowing the segment to participate in both emerging-market volume growth and developed-market premiumization. Compact housing is increasing demand for storage-integrated and multifunctional products, while consumers increasingly expect furniture to balance appearance, practicality and ease of assembly. Large retailers continue investing heavily in residential categories: IKEA reported that furniture remained particularly strong in FY2025, with storage and kitchen products among the best-performing areas. Commercial furniture grows alongside hospitality and workplace investment, but the frequency and breadth of household purchasing keep residential applications dominant through 2031.
By Distribution Channel
Online
Online furniture sales are projected to reach approximately USD 291 billion by 2031, gaining share as digital product discovery, home delivery, virtual planning and integrated omnichannel fulfillment improve. Furniture remains less digitally penetrated than smaller consumer goods because shoppers often need to evaluate dimensions, material quality and comfort, but the distinction between online and offline purchasing is becoming less meaningful. Consumers can research online, examine products in a showroom and place orders digitally, or configure products online before arranging delivery or store collection. IKEA reported that e-commerce represented 28% of turnover in FY2025, while its physical store traffic also increased, illustrating the complementary nature of both channels. Digital growth is strongest for standardized, configurable and flat-pack products where specifications are easy to communicate, while expensive upholstered and luxury furniture remains more dependent on physical experience and design consultation.
Major Region
Asia Pacific
Asia Pacific is projected to generate approximately USD 432 billion in furniture revenue by 2031, maintaining its position as the largest regional market. The region combines a substantial manufacturing base with large consumer markets in China, India, Japan, South Korea, Indonesia and Southeast Asia.
Urbanization and household formation support residential demand, while hospitality, commercial real estate and retail development create additional furniture requirements. Asia Pacific also contains a wide spectrum of consumer purchasing power, allowing value-oriented mass furniture and premium design categories to expand simultaneously. International retailers continue extending distribution across the region, while strong domestic manufacturing ecosystems give local brands advantages in sourcing and logistics. India's increasing importance is reflected by IKEA's expansion of online availability into Delhi-NCR and additional North Indian markets, extending access beyond its established store network. The combination of domestic consumption, export manufacturing and continuing urban development keeps Asia Pacific central to the global market through the forecast period.
Major Country
China
China remains the largest individual furniture market within Asia Pacific, supported by its urban population, residential base, domestic manufacturing capacity and established furniture supply chain. Demand spans value-oriented household furniture, premium residential products, office furniture, hospitality furnishings and extensive online retail. The country's manufacturing ecosystem also gives producers access to wood processing, panels, metal components, textiles, hardware and export logistics within a highly integrated supply base. Market growth is becoming less dependent on rapid housing construction than in earlier periods and increasingly reflects replacement purchases, home renovation, product upgrades and digital retail. Chinese furniture companies are also strengthening design and branding capabilities rather than competing solely on manufacturing cost. While property-sector weakness can affect short-term demand, the size of the installed household base provides significant recurring replacement requirements, allowing China to remain the most commercially important country market within the region through 2031.
Competitive Environment and Analysis
The global furniture industry remains fragmented despite the scale of leading international brands. IKEA combines global sourcing, standardized product engineering, flat-pack logistics and integrated retail, while Ashley Furniture maintains a large manufacturing and retail presence in North America and international markets. MillerKnoll, Steelcase, Haworth, HNI and Kokuyo are more exposed to office and institutional furniture, while Williams-Sonoma operates several residential furnishing brands including Pottery Barn and West Elm. RH competes at the luxury end through integrated galleries, digital channels and hospitality-linked brand positioning. Wayfair maintains a digitally centered home-furnishing platform with a very broad assortment. Competitive differentiation increasingly depends on design, pricing, supply-chain efficiency, omnichannel retail, delivery reliability, sustainability and after-sales services rather than manufacturing capability alone. Circular services, resale and repair could gradually create another competitive layer by extending customer relationships beyond the initial purchase.
Recent Developments
March 2026: IKEA expanded its Indian urban retail presence with a city-format store in Pune, supporting a more compact omnichannel expansion model.
FY2025: IKEA reported EUR 44.6 billion in retail sales, with customer numbers and sales volumes increasing by approximately 3% and online channels accounting for 28% of turnover.
2026: IKEA continued expanding circular retail services centered on repair, resale, refurbishment and buy-back programs as part of its FY2030 circularity strategy.
2026: Major U.S. home-furnishing companies continued emphasizing integrated physical and digital retail, with RH operating galleries, websites and Sourcebooks as interconnected sales channels.
2025-2026: IKEA expanded online coverage into North India, including Delhi-NCR and additional satellite markets, strengthening digital accessibility in one of the world's faster-growing large consumer markets.
Market Outlook
Residential furniture remains the largest component of demand as household formation, renovation and product replacement sustain recurring purchases, while commercial furniture benefits from hospitality, workplace and institutional investment. The market is becoming increasingly omnichannel, with digital channels gaining share but physical stores remaining important for product evaluation, design services and high-consideration purchases.
Asia Pacific remains the largest region through 2031, supported by its large consumer base, manufacturing scale and continuing urban development, while China remains the most important individual market within the region. Circularity, repairability and resale are expected to become increasingly relevant product and retail considerations, but affordability and design remain central to mass-market competition.
Furniture Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 696.5 billion |
| Total Market Size in 2031 | USD 932.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Furniture Type, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Furniture Type
Residential
Commercial
By Distribution Channel
Online
Offline
By Geography
North America
By Furniture Type
By Distribution Channel
By Country
United States
Canada
Mexico
South America
By Furniture Type
By Distribution Channel
By Country
Brazil
Argentina
Others
Europe
By Furniture Type
By Distribution Channel
By Country
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
By Furniture Type
By Distribution Channel
By Country
Saudi Arabia
UAE
Israel
South Africa
Others
Asia Pacific
By Furniture Type
By Distribution Channel
By Country
China
Japan
India
South Korea
Australia
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Furniture Manufacturing and Raw Material Outlook
3.7. E-Commerce and Omnichannel Furniture Retail
3.8. Circular Furniture and Sustainable Materials
3.9. Strategic Recommendations
4. FURNITURE MARKET BY FURNITURE TYPE
4.1. Introduction
4.2. Residential
4.3. Commercial
5. FURNITURE MARKET BY DISTRIBUTION CHANNEL
5.1. Introduction
5.2. Online
5.3. Offline
6. FURNITURE MARKET BY GEOGRAPHY
6.1. Introduction
6.2. North America
6.2.1. By Furniture Type
6.2.2. By Distribution Channel
6.2.3. By Country
6.2.3.1. United States
6.2.3.2. Canada
6.2.3.3. Mexico
6.3. South America
6.3.1. By Furniture Type
6.3.2. By Distribution Channel
6.3.3. By Country
6.3.3.1. Brazil
6.3.3.2. Argentina
6.3.3.3. Others
6.4. Europe
6.4.1. By Furniture Type
6.4.2. By Distribution Channel
6.4.3. By Country
6.4.3.1. Germany
6.4.3.2. United Kingdom
6.4.3.3. France
6.4.3.4. Italy
6.4.3.5. Spain
6.4.3.6. Others
6.5. Middle East and Africa
6.5.1. By Furniture Type
6.5.2. By Distribution Channel
6.5.3. By Country
6.5.3.1. Saudi Arabia
6.5.3.2. UAE
6.5.3.3. Israel
6.5.3.4. South Africa
6.5.3.5. Others
6.6. Asia Pacific
6.6.1. By Furniture Type
6.6.2. By Distribution Channel
6.6.3. By Country
6.6.3.1. China
6.6.3.2. Japan
6.6.3.3. India
6.6.3.4. South Korea
6.6.3.5. Australia
6.6.3.6. Indonesia
6.6.3.7. Thailand
6.6.3.8. Others
7. COMPETITIVE ENVIRONMENT AND ANALYSIS
7.1. Major Players and Strategy Analysis
7.2. Market Share Analysis
7.3. Mergers, Acquisitions, Agreements, and Collaborations
7.4. Competitive Dashboard
8. COMPANY PROFILES
8.1. Inter IKEA Systems B.V.
8.2. Ashley Furniture Industries, LLC
8.3. MillerKnoll, Inc.
8.4. Steelcase Inc.
8.5. Haworth, Inc.
8.6. HNI Corporation
8.7. Kokuyo Co., Ltd.
8.8. Okamura Corporation
8.9. Godrej Interio
8.10. Williams-Sonoma, Inc.
8.11. RH
8.12. Wayfair Inc.
8.13. La-Z-Boy Incorporated
8.14. Nitori Holdings Co., Ltd.
8.15. Natuzzi S.p.A.
9. APPENDIX
9.1. Market Definition and Scope
9.2. Currency
9.3. Assumptions
9.4. Base and Forecast Years
9.5. Research Methodology
Navigate
Trusted by the world's leading organizations











