
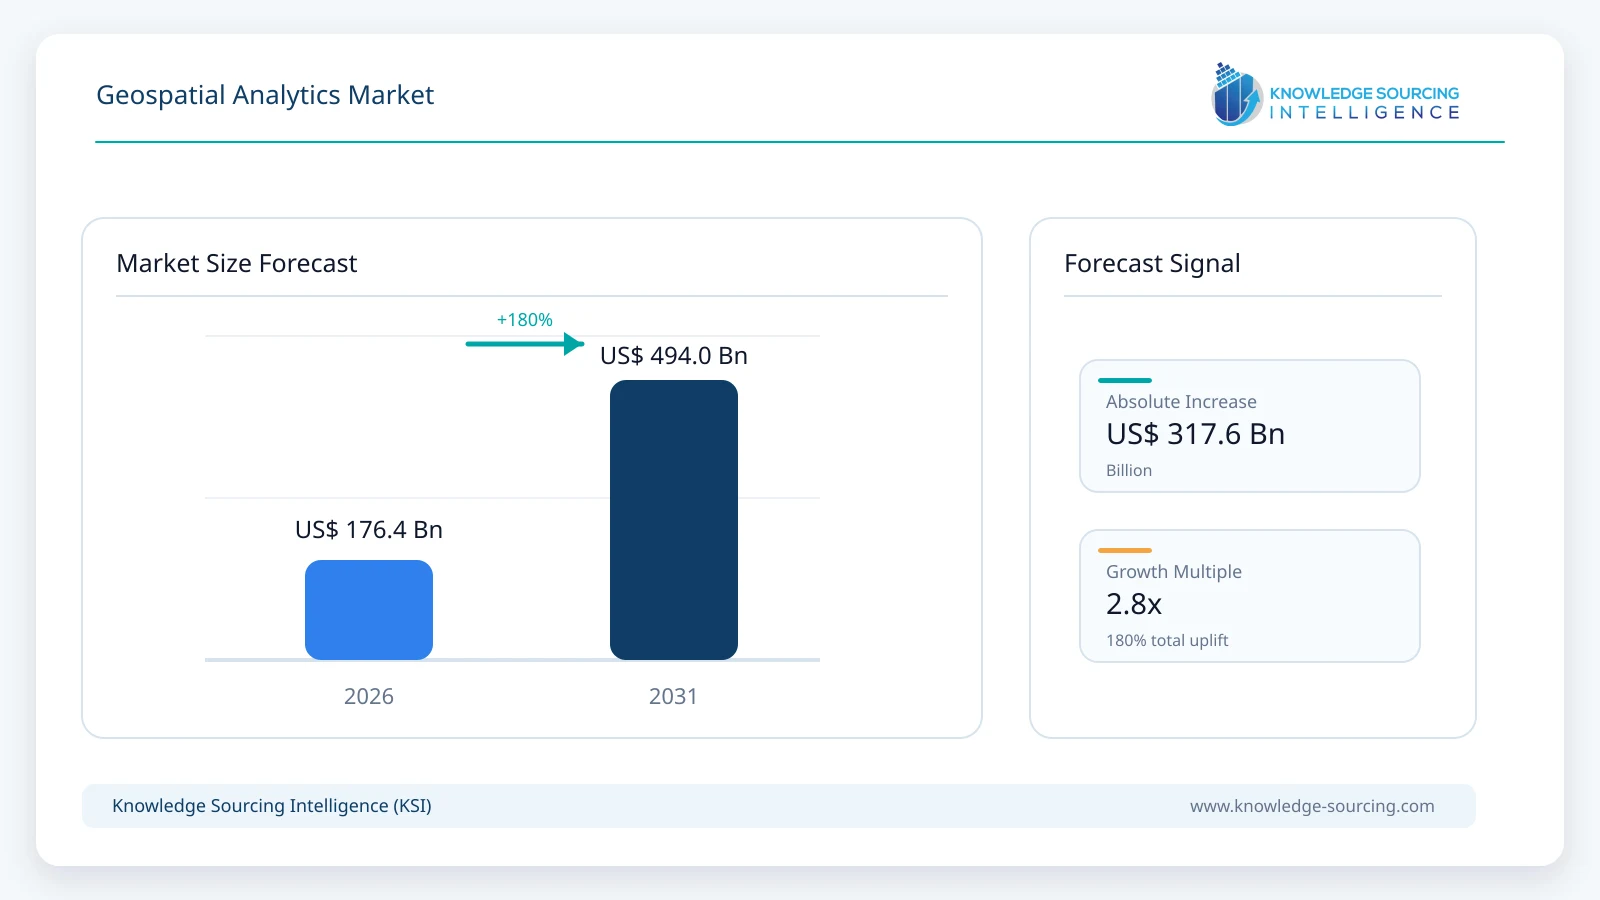
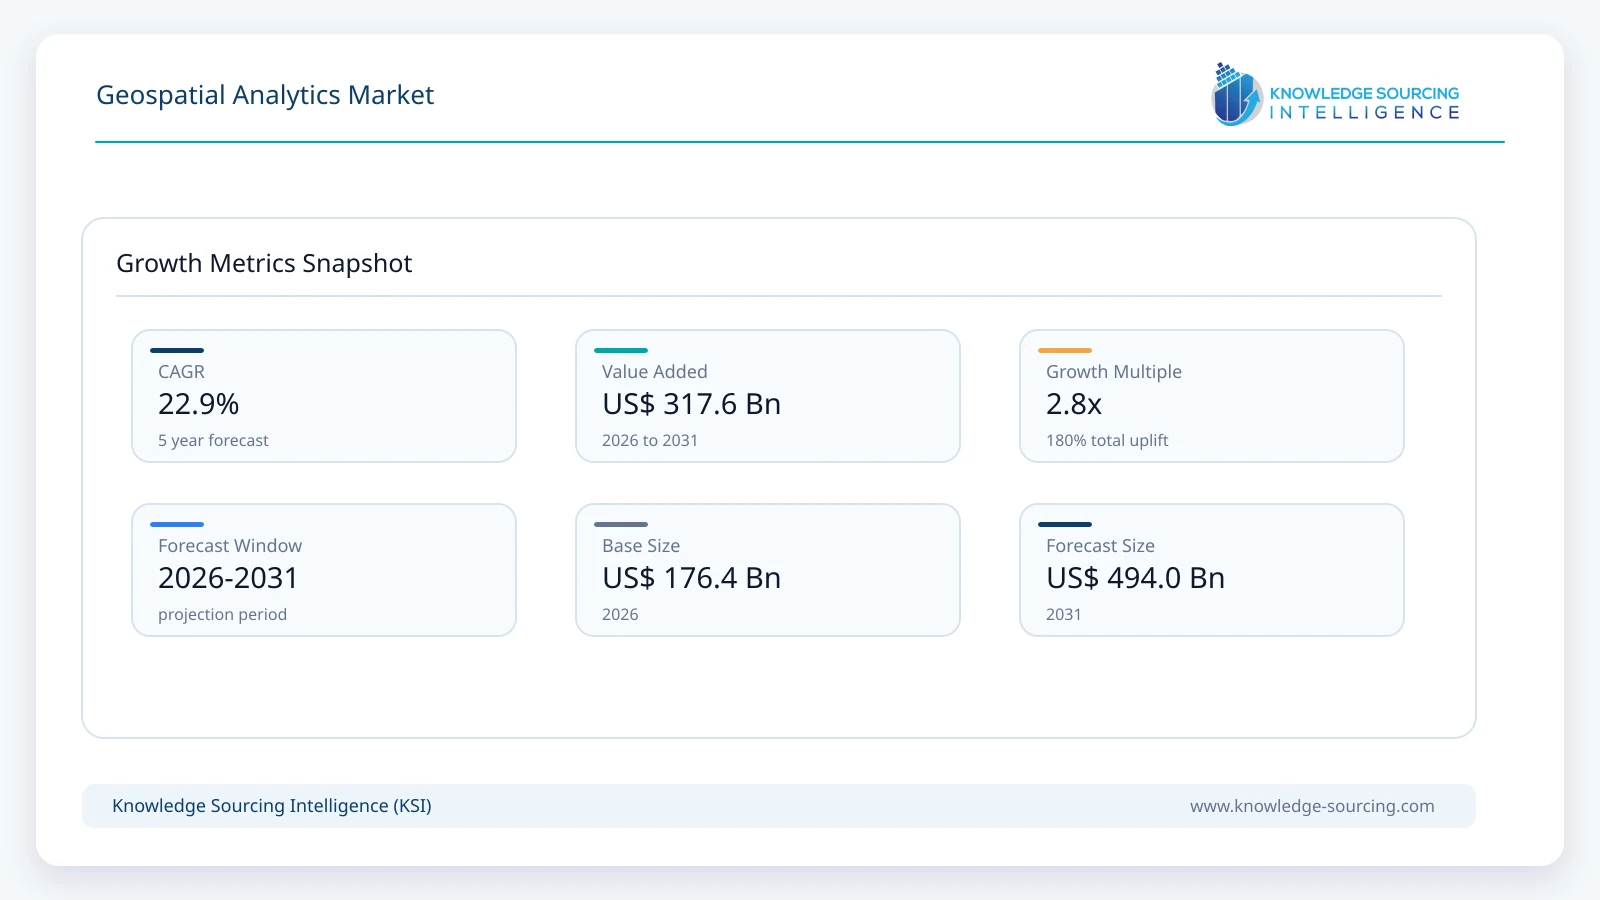
The global geospatial analytics market is forecast to grow at a CAGR of 22.9%, reaching USD 494.0 billion in 2031 from USD 176.4 billion in 2026.
Highlights:
- 1Software accounts for approximately 62% of global geospatial analytics market value in 2026, equivalent to around USD 109.4 billion.
- 2Network and location analytics represents approximately 34% of market value in 2026 and remains the largest analytics category.
- 3Large enterprises account for approximately 67% of market value in 2026, although small and medium enterprises are projected to grow faster through 2031.
- 4Military intelligence represents approximately 26% of market value in 2026 as governments expand commercial GEOINT, automated monitoring and AI-enabled analysis.
- 5North America accounts for approximately 38% of global market value in 2026, while Asia Pacific is projected to record faster growth at approximately 26.1% annually through 2031.
The existing market trajectory is being supported by the rapid increase in location-enabled data generated by satellites, mobile devices, connected infrastructure, vehicles, IoT sensors and enterprise systems. Geospatial platforms increasingly combine this information with cloud computing, machine learning and visualization tools to identify spatial relationships and automate decisions across defense, transportation, utilities, agriculture, public safety, infrastructure planning and commercial operations.
The volume and accessibility of geospatial data continue to increase. The European Space Agency estimates that the global downstream space market, covering satellite communications, Earth observation and GNSS-related products and services, reached approximately EUR 490 billion in 2025, with GNSS-related activity representing the majority of downstream demand. Satellite-derived information is increasingly embedded within broader digital services rather than consumed only as standalone imagery. USGS similarly continues to expand open access to long-running Landsat data, while the planned Landsat 10 mission will introduce 26 spectral bands and finer spatial resolution when it launches in 2031.
Market Trends
GeoAI Is Moving from Task-Specific Models to Foundation Models
Artificial intelligence is becoming deeply integrated into geospatial workflows. Esri reported in July 2026 that ArcGIS now provides more than 100 pretrained AI models and is expanding toward geospatial foundation models capable of learning reusable representations from imagery, maps, demographic data and other spatial information. These models can support feature extraction, similarity search, predictive modelling and natural-language interaction without requiring users to train a new model for every application.
The development reduces one of the major barriers to geospatial analysis: the specialist expertise and training data traditionally required to convert imagery and spatial databases into actionable information. Foundation models can be adapted across land-use classification, asset identification, environmental monitoring and change detection, while generative and agentic interfaces make advanced GIS functions accessible through natural-language instructions. Geospatial analytics therefore increasingly shifts from analysts manually querying layers toward AI systems identifying patterns, performing spatial operations and presenting results to decision-makers.
Real-Time Geospatial Analytics Is Expanding Beyond Traditional GIS
Geospatial systems are increasingly ingesting live information from vehicles, industrial equipment, IoT devices and operational sensors. Esri released ArcGIS Velocity for ArcGIS Enterprise in July 2026, extending real-time data ingestion, analytics and automated alerting to self-hosted environments as well as its existing cloud platform. The system is designed for applications including transportation, logistics and public safety, where organizations need to process continuously changing spatial information rather than static maps.
This capability broadens geospatial analytics into operational decision-making. Fleet operators can identify route deviations or congestion, utilities can monitor geographically distributed assets, and public agencies can combine location feeds with weather or incident data to coordinate response. The increasing availability of high-frequency sensor and positioning data consequently raises demand for streaming analytics, cloud processing and automated spatial alerts.
Natural-Language Interfaces Are Reducing GIS Complexity
Agentic AI is beginning to change how non-specialists interact with geospatial information. Planet demonstrated an agentic geospatial application in 2026 that allows users to submit questions such as identifying construction activity across a geographic area and receive maps, change-detection results and supporting information without manually reviewing large imagery archives. Planet’s platform combines satellite imagery, AI-based change detection and contextual information through a map-based conversational interface.
This transition is strategically important because the addressable customer base for geospatial analytics has historically been constrained by the need for trained GIS analysts. Natural-language interaction does not eliminate geospatial expertise, particularly for complex analysis, but it allows business, operations and policy teams to perform preliminary analysis directly. The market increasingly moves toward analytics embedded within decision workflows rather than specialist GIS software used separately from operational systems.
Market Drivers
Expansion of Commercial Earth Observation and Geospatial Data
The quantity, frequency and variety of commercial Earth-observation data are increasing rapidly. Satellite operators can now capture large geographic areas at frequent intervals, while government datasets such as Landsat provide long historical records that can be combined with commercial high-resolution imagery. Planet states that its satellite constellation captures imagery of the Earth’s land mass and approximately 20 million square kilometres of open water each day, creating an archive suitable for automated detection of changes in land use, infrastructure, agriculture and other physical activity.
The value increasingly comes from converting this data into analytics rather than simply providing imagery. Planet has demonstrated onboard AI object detection using its Pelican satellites, while Hexagon strengthened its airborne mapping capabilities in June 2026 through the acquisition of ITRES, adding hyperspectral and thermal imaging to its LiDAR, optical imagery and digital-twin technologies. These developments broaden both the amount of source data and the range of detectable physical characteristics, increasing demand for software capable of processing and interpreting geospatial information.
Defense Agencies Are Increasing Commercial GEOINT and AI Procurement
Defense and intelligence applications represent an important source of demand because governments increasingly combine classified systems with commercially available imagery, data and analytical services. The U.S. National Geospatial-Intelligence Agency states that its commercial GEOINT strategy is designed to complement existing imagery sources with non-traditional datasets and geospatial analytical services. Its Commercial Operations organization specifically evaluates AI-based capabilities including object detection, object classification, broad-area search and area monitoring.
The procurement pipeline remains active. NGA awarded Esri a USD 37.1 million Enterprise Geographic Information System task order in July 2026 and held an AI-focused Industry Day covering future contracts for imagery exploitation, analytic systems, machine-learning model development and AI-enabled tools. The transition from imagery procurement toward automated analysis increases the value of geospatial software and services per user because defense customers require persistent monitoring, AI-enabled prioritization and integration of multiple data sources.
Infrastructure and Digital-Twin Adoption Is Increasing Spatial Analysis Requirements
Infrastructure owners increasingly combine engineering models with real-world geographic context to plan, construct and operate transport, energy, water and urban assets. Bentley’s 2026 MicroStation release expanded 3D geospatial analysis alongside AI-assisted engineering workflows, while its wider infrastructure-AI strategy links digital twins, connected asset data and predictive analysis.
Geospatial context is particularly important for linear infrastructure such as roads, transmission networks, pipelines and railways where asset condition and surrounding terrain must be analyzed together. Smart-city and utility applications add operational sensor feeds to these spatial models, increasing demand for software that can integrate GIS, engineering and real-time data. This creates a broader commercial market than traditional mapping because geospatial analytics becomes part of asset management, capital planning and operational decision systems.
Market Restraints
Fragmented Data and Interoperability Increase Implementation Complexity
Organizations frequently maintain geospatial information across separate GIS platforms, engineering systems, sensor databases, satellite imagery repositories and enterprise applications. Combining these datasets can require extensive data preparation, coordinate-system reconciliation and integration work before useful analysis can begin. The challenge becomes greater when organizations attempt to combine historical data with continuously updated satellite, IoT and operational feeds.
Open standards and analysis-ready data reduce some of this complexity. USGS Landsat Collection 2 provides internationally recognized analysis-ready products designed to improve interoperability with other Earth-observation platforms such as Sentinel-2. However, commercial deployments still need to reconcile proprietary datasets, varying resolutions, different update frequencies and access restrictions. Integration requirements can therefore lengthen projects and increase professional-services expenditure, particularly for enterprises with large legacy information systems.
Specialized Skills and Data Governance Remain Important Constraints
AI-assisted GIS is reducing the technical barrier to basic analysis, but complex geospatial workflows still require expertise in spatial statistics, remote sensing, cartography, data engineering, and application-specific interpretation. NGA’s professional geospatial-analysis framework emphasizes data acquisition and management, geospatial science, spatial reasoning, and communication of analytical findings, illustrating that robust analysis requires more than access to software.
Data governance creates an additional challenge. Geospatial information can reveal sensitive infrastructure, individual movement, defense assets, or commercially valuable operating information. Organizations therefore need controls around data access, sovereignty, cybersecurity, and permissible usage. These requirements can slow deployment in government, healthcare, utilities, and other regulated sectors even as cloud and AI technologies make geospatial processing technically easier.
Segment Analysis
By Component: Software
Software accounts for approximately USD 109.4 billion in 2026 and is projected to reach around USD 321.1 billion by 2031, representing growth of approximately 24.0% annually. The segment benefits from the migration of GIS toward cloud platforms, real-time analytics, GeoAI, digital twins, and AI-assisted decision systems. Esri’s expansion of ArcGIS into foundation models, agentic workflows, and real-time data processing demonstrates how software functionality is extending beyond conventional mapping.
Services remain substantial because organizations require implementation, data engineering and specialized analysis, but software increases its relative share as analytics become more automated and reusable through cloud and subscription platforms. The ability to distribute geospatial functionality through APIs and enterprise applications also allows location intelligence to reach users who may never interact directly with a traditional GIS interface.
By Type: Network and Location Analytics
Network and location analytics represents approximately USD 60.0 billion in 2026 and is projected to reach around USD 170.4 billion by 2031, corresponding to growth of approximately 23.2% annually. The segment covers routing, accessibility, proximity, network optimization and location-based analysis used across transportation, retail, utilities, telecommunications and logistics. Growth is supported by the increasing availability of real-time positioning and IoT data, allowing organizations to analyze not only where assets are located but how they move and interact across networks.
Geo-visualization grows faster at approximately 25.5% annually and reaches around USD 148.2 billion by 2031 as 3D environments, digital twins and AI-generated spatial representations gain wider adoption. However, network and location analytics remains the largest type because route optimization, site selection, infrastructure planning and proximity analysis have broad commercial applications across multiple industries.
By Enterprise Size: Large Enterprises
Large enterprises account for approximately USD 118.2 billion in 2026 and are projected to reach around USD 306.3 billion by 2031. Their market position reflects the scale of geospatial deployments across defense organizations, national utilities, telecommunications companies, transportation operators and multinational enterprises that maintain extensive assets and data infrastructure.
Small and medium enterprises grow faster at approximately 26.4% annually, increasing from around USD 58.2 billion in 2026 to USD 187.7 billion by 2031. Cloud delivery, APIs and AI-assisted geospatial tools reduce the requirement for large internal GIS teams and dedicated computing infrastructure, making sophisticated location intelligence accessible to smaller organizations. The resulting market gradually becomes less concentrated around large institutional users even though they remain the largest customer category through 2031.
By Application: Military Intelligence
Military intelligence accounts for approximately USD 45.9 billion in 2026 and is projected to reach approximately USD 138.3 billion by 2031, representing growth of around 24.7% annually. Defense customers increasingly use commercial satellite imagery, computer vision and automated spatial analysis to monitor vessels, facilities, infrastructure and geographic activity across large areas. NGA’s Commercial Operations explicitly targets AI-based object detection, classification, broad-area search and area monitoring, while its CIBORG initiative provides a standardized acquisition route for commercial imagery, data and analytics.
Climate-change adaptation grows slightly faster at approximately 25.0% annually but remains smaller, reaching about USD 59.3 billion in 2031. Disaster-risk reduction and public-safety applications also expand rapidly as near-real-time imagery, weather information and spatial modelling become integrated into emergency planning and response.
Regional Outlook
North America
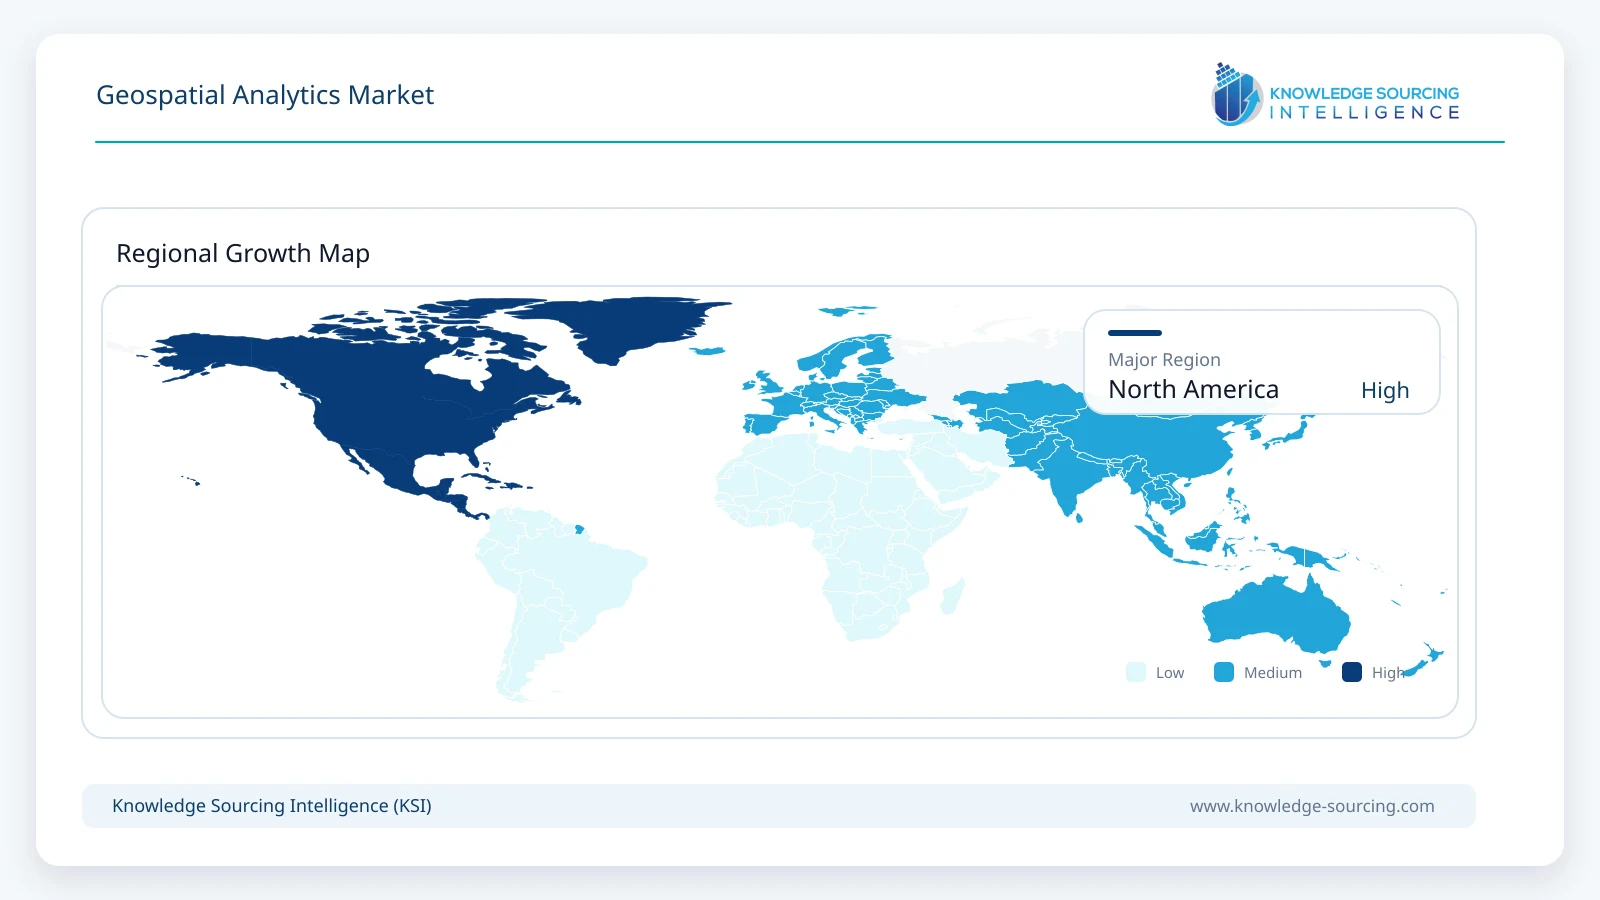
North America accounts for approximately USD 67.0 billion in 2026 and is projected to reach around USD 172.9 billion by 2031. The region remains the largest market because the United States hosts major GIS, cloud, satellite-imagery, defense and infrastructure-software companies alongside substantial government procurement. Esri, Google, Planet, Maxar, Trimble, Bentley Systems and several specialized geospatial technology companies maintain major operations in the region, while U.S. federal agencies remain significant users of commercial and internally developed GEOINT capabilities.
Government investment continues to support the ecosystem. NGA’s 2026 procurement activity includes enterprise GIS licensing and AI-focused programs, while USGS maintains one of the world’s largest freely accessible archives of calibrated Earth-observation information. North America remains the largest market through 2031, although its relative share moderates as adoption accelerates elsewhere.
Asia Pacific
Asia Pacific is projected to grow from approximately USD 51.2 billion in 2026 to USD 163.0 billion in 2031 at a CAGR of approximately 26.1%, making it the fastest-growing major region. Growth is being supported by urban development, infrastructure investment, agriculture monitoring, logistics, smart-city programs and expanding national space capabilities across China, India, Japan, South Korea and Southeast Asia.
Commercial providers are increasingly targeting the region with persistent monitoring and AI-enabled GEOINT. Planet reported in 2026 that customers across Asia Pacific are moving from static imagery toward time-series analysis, automated change detection and early-warning applications, particularly across defense and strategic monitoring. Rapid infrastructure development also creates large requirements for surveying, asset mapping and urban planning. Asia Pacific consequently approaches North America’s market value by 2031 while maintaining the strongest major-region growth rate.
Competitive Environment and Analysis
The geospatial analytics market combines dedicated GIS vendors, measurement and positioning companies, cloud and mapping platforms, satellite-imagery providers and infrastructure-software companies. Esri maintains one of the broadest enterprise GIS platforms and continues to expand ArcGIS through GeoAI, foundation models, real-time analytics and agentic workflows. Hexagon combines geospatial software with LiDAR, positioning, airborne imaging and digital-twin technologies, while Trimble integrates positioning and geospatial data with construction, surveying and transportation workflows. Bentley Systems links geospatial context with infrastructure engineering and digital twins.
Google provides large-scale mapping, location and cloud-based geospatial capabilities, while TomTom remains important in location technology and mapping. Planet and Maxar contribute satellite imagery and analytical information that feed geospatial workflows, while CARTO focuses on cloud-native spatial analytics. Fugro applies geospatial data and analysis particularly in infrastructure, energy and marine environments, and RMSI provides geospatial and engineering services.
Competition increasingly moves beyond map creation toward automation and decision intelligence. Esri’s 2026 foundation-model releases, Planet’s agentic geospatial AI development and Hexagon’s addition of hyperspectral and thermal airborne mapping demonstrate the convergence of data acquisition, AI and analytics. Suppliers capable of combining proprietary data, scalable software and domain-specific analytical workflows are increasingly differentiated from providers offering visualization alone.
Recent Developments
July 2026: Esri introduced geospatial foundation models within ArcGIS, expanding AI capabilities for imagery understanding, feature extraction, similarity analysis and other GIS workflows.
July 2026: Esri released ArcGIS Velocity for ArcGIS Enterprise, enabling real-time ingestion and spatial analysis of IoT, sensor and operational data within self-hosted environments.
July 2026: NGA awarded Esri a USD 37.1 million Enterprise Geographic Information System task order covering twelve months.
June 2026: Hexagon acquired ITRES Research, adding hyperspectral and thermal airborne sensors to its existing LiDAR, optical-imagery and geospatial-processing portfolio.
June 2026: Planet demonstrated agentic geospatial AI and onboard satellite object detection as part of its strategy to automate.
May 2026: NGA announced an AI-focused Industry Day covering future contracts for imagery exploitation, analytic systems, AI/ML model development and AI-enabled geospatial tools.
Market Outlook
Software remains the largest component and reaches approximately USD 321.1 billion by the end of the forecast period as GeoAI, real-time analytics and cloud-based spatial services increase the value delivered through software platforms. Network and location analytics remains the largest analytics type, while geo-visualization grows faster as digital twins, 3D environments and AI-driven spatial interfaces become more widely used.
Large enterprises continue to represent the largest customer group, but SMEs gain share as cloud and AI reduce the technical and infrastructure requirements associated with spatial analysis. Military intelligence remains the largest application and reaches approximately USD 138.3 billion by 2031, while climate adaptation, disaster management and public-safety applications also expand strongly as higher-frequency Earth-observation data becomes easier to interpret.
North America remains the largest regional market at approximately USD 172.9 billion in 2031, while Asia Pacific reaches around USD 163.0 billion and grows considerably faster. The defining change through 2031 is expected to be the movement from geospatial analytics as a specialist mapping discipline toward location intelligence embedded directly within enterprise, defense and operational decision systems. AI will increasingly automate data extraction and spatial analysis, but the commercial value will depend on combining these capabilities with reliable data, domain expertise and workflows that translate geographic information into operational decisions.
Geospatial Analytics Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 176.4 billion |
| Total Market Size in 2031 | USD 494.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 22.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Type, Enterprise Size, Application |
| Companies |
|
Market Segmentation
By Component
Software
Services
By Type
Surface and Field Analytics
Network and Location Analytics
Geo-visualization
Others
By Enterprise Size
Small and Medium Enterprises
Large Enterprises
By Application
Surveying
Medicine and Public Safety
Military Intelligence
Disaster Risk Reduction and Management
Climate Change Adaptation
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Taiwan
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Market Estimation
2.4. Segment Modelling
2.5. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Geospatial Analytics Market Size, 2026-2031
3.3. Component Outlook
3.4. Analytics Type Outlook
3.5. Enterprise Size Outlook
3.6. Application Outlook
3.7. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Commercial Earth Observation and Geospatial Data
4.1.2. Defense Investment in Commercial GEOINT and AI
4.1.3. Infrastructure and Digital-Twin Adoption
4.2. Market Restraints
4.2.1. Fragmented Data and Interoperability
4.2.2. Specialized Skills and Data-Governance Requirements
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
4.5. Data Governance and Regulatory Environment
5. TECHNOLOGICAL OUTLOOK
5.1. Geospatial Artificial Intelligence
5.2. Geospatial Foundation Models
5.3. Agentic Geospatial AI
5.4. Real-Time GIS and IoT Integration
5.5. Digital Twins and 3D Geospatial Analytics
5.6. Hyperspectral and Multisensor Analytics
6. GEOSPATIAL ANALYTICS MARKET BY COMPONENT
6.1. Software
6.2. Services
7. GEOSPATIAL ANALYTICS MARKET BY TYPE
7.1. Surface and Field Analytics
7.2. Network and Location Analytics
7.3. Geo-visualization
7.4. Others
8. GEOSPATIAL ANALYTICS MARKET BY ENTERPRISE SIZE
8.1. Small and Medium Enterprises
8.2. Large Enterprises
9. GEOSPATIAL ANALYTICS MARKET BY APPLICATION
9.1. Surveying
9.2. Medicine and Public Safety
9.3. Military Intelligence
9.4. Disaster Risk Reduction and Management
9.5. Climate Change Adaptation
9.6. Others
10. GEOSPATIAL ANALYTICS MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.1.3. Mexico
10.2. South America
10.2.1. Brazil
10.2.2. Argentina
10.2.3. Others
10.3. Europe
10.3.1. Germany
10.3.2. France
10.3.3. United Kingdom
10.3.4. Spain
10.3.5. Others
10.4. Middle East and Africa
10.4.1. Saudi Arabia
10.4.2. UAE
10.4.3. South Africa
10.4.4. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. Japan
10.5.3. India
10.5.4. South Korea
10.5.5. Indonesia
10.5.6. Taiwan
10.5.7. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Esri
12.2. Hexagon AB
12.3. Google LLC
12.4. Trimble Inc.
12.5. Bentley Systems, Incorporated
12.6. TomTom International B.V.
12.7. Planet Labs PBC
12.8. Maxar Technologies
12.9. Fugro N.V.
12.10. CARTO
12.11. RMSI
12.12. Alteryx, Inc.
12.13. Precisely
12.14. HERE Technologies
12.15. BlackSky Technology Inc.
13. APPENDIX
Navigate
Trusted by the world's leading organizations











