
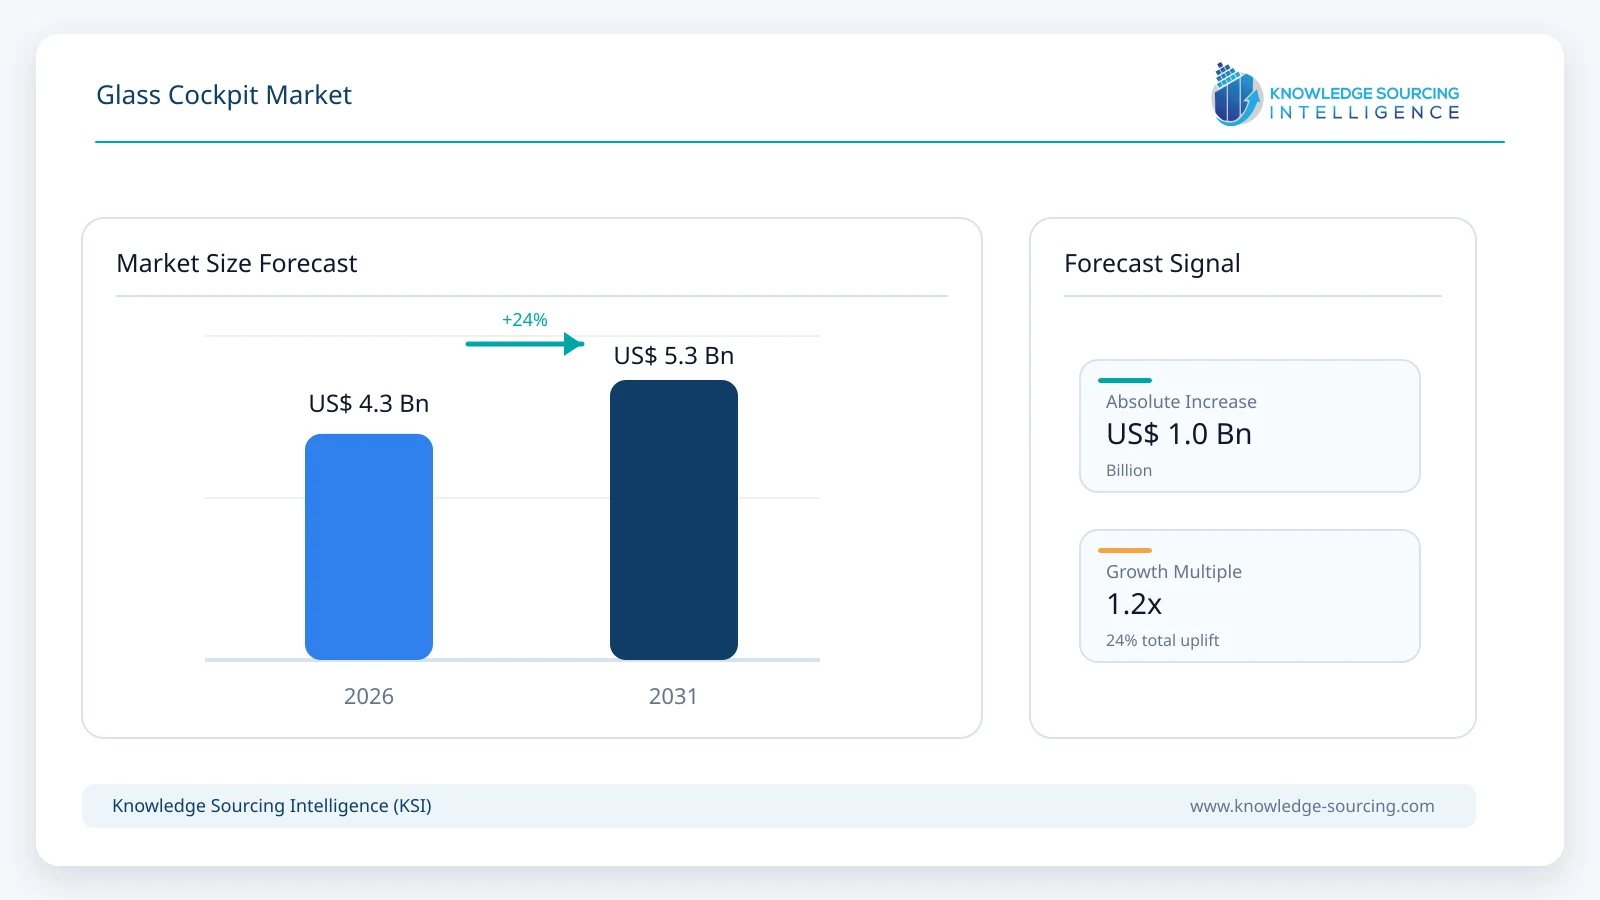
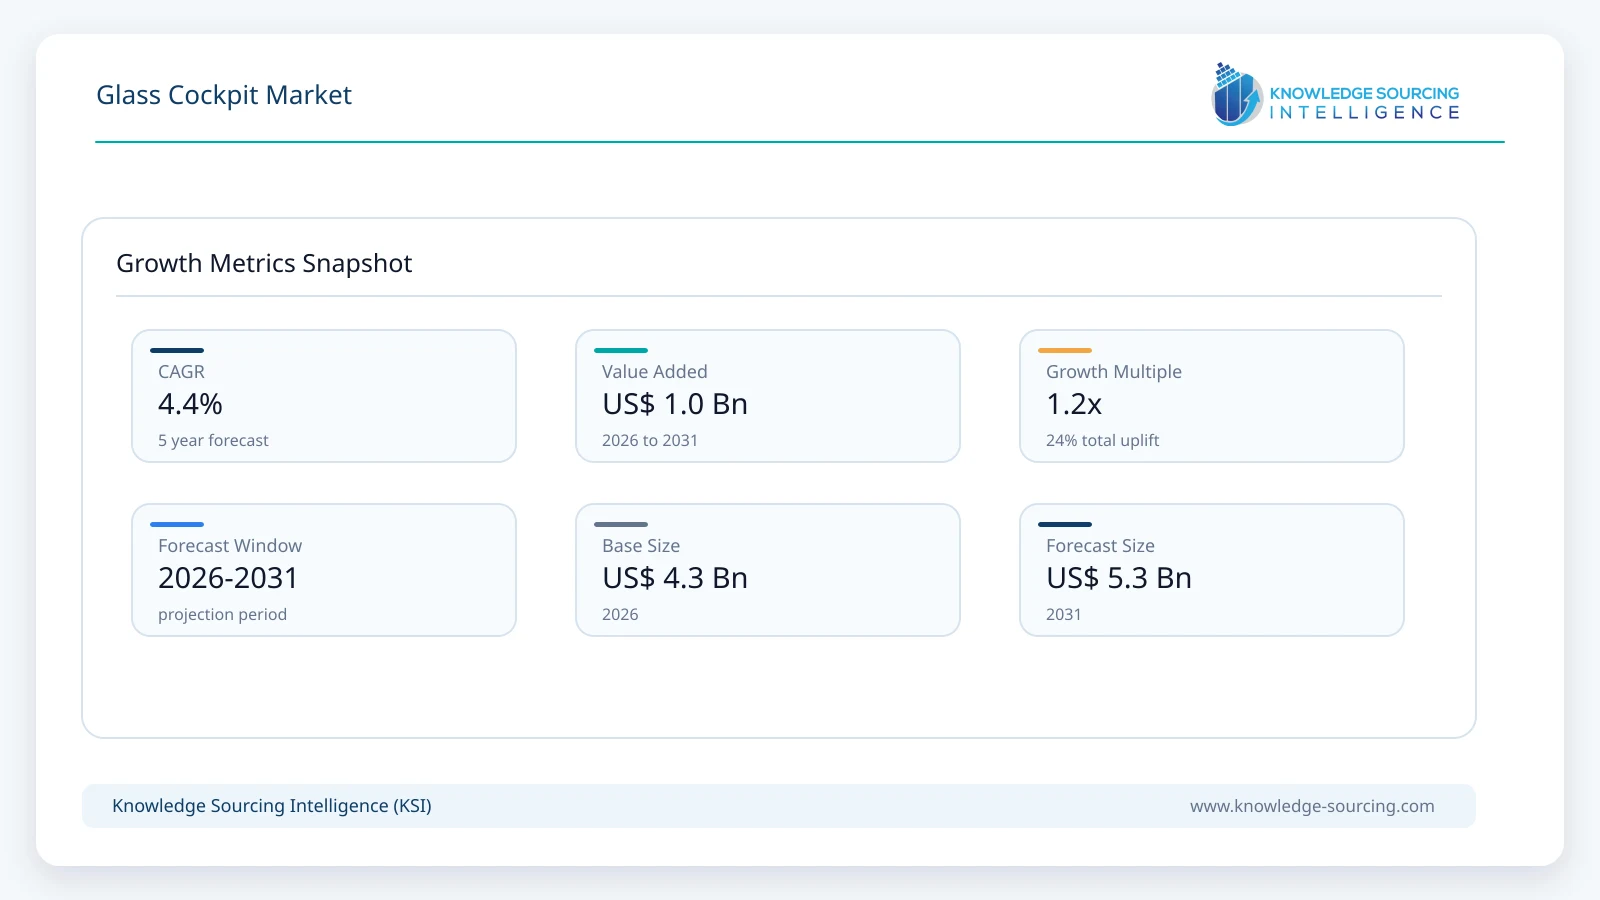
The global glass cockpit market is forecast to grow at a CAGR of 4.4%, reaching USD 5.30 billion in 2031 from USD 4.28 billion in 2026.
Highlights:
- 1Commercial and cargo transport aircraft account for approximately 39% of global glass cockpit revenue in 2026.
- 2Business and general aviation glass cockpits are projected to grow at approximately 5.5% annually through 2031.
- 3Multi-function displays generate about USD 1.54 billion of global glass cockpit market value in 2026.
- 4North America accounts for approximately 37% of global glass cockpit revenue in 2026.
- 5Touch interfaces, synthetic vision and automated workflows are shifting value from standalone displays toward integrated flight-deck platforms.
- 6Retrofit programs remain commercially important as operators address display obsolescence and extend the life of installed aircraft fleets.
Market Overview
Modern glass cockpits combine multiple data sources into a small number of high-resolution electronic displays rather than presenting each flight parameter through a dedicated gauge. Primary flight displays consolidate attitude, altitude, airspeed and navigation information; multi-function displays can present maps, weather, traffic, system synoptics and flight-planning information; and engine-indicating or crew-alerting functions communicate aircraft status and abnormalities. The commercial product is therefore increasingly an integrated avionics architecture rather than a display panel alone. Collins Aerospace positions Pro Line Fusion around integrated flight planning, synthetic vision, connectivity and open architecture, while Garmin flight decks combine flight, weather, terrain, traffic, charts and system data within a common interface.
Market boundaries are important because many avionics products interact with a glass cockpit but are not themselves counted as glass-cockpit revenue. This estimate includes integrated cockpit displays, display-processing electronics, cockpit interface controls and software or integration directly supplied as part of the flight-deck display system. Standalone radar, radio, navigation sensors, autopilots, head-up displays and cabin displays are excluded unless supplied as an inseparable part of the integrated cockpit package. Forward-fit systems installed by aircraft manufacturers and certified retrofit packages installed on in-service aircraft are both included.
Market Trends
Flight decks are moving toward software-defined, open and connected architectures
The next generation of glass cockpits is being designed around computing capacity and upgradeability rather than fixed-function display hardware. Honeywell describes Anthem as a modular, cloud-connected and AI-capable integrated cockpit that supports third-party applications and OEM customization. Collins Aerospace similarly emphasizes open architecture in Pro Line Fusion, allowing new functions to be integrated without replacing the entire flight deck. Garmin has followed the same direction with G3000 PRIME and G2000 PRIME, using higher-performance processors, gigabit connectivity and configurable display windows. This architecture matters commercially because aircraft remain in service for decades while navigation standards, cybersecurity requirements, datalink services and pilot-assistance functions continue to change. Suppliers able to insert software and computing upgrades over the aircraft life cycle can capture aftermarket value beyond the initial display sale.
Large touch displays and workload-reduction functions are becoming standard design priorities
Cockpit interfaces are increasingly designed around larger displays, fewer dedicated controls and context-sensitive workflows. Garmin G2000 PRIME uses 14-inch primary display units and multi-touch interaction, while G3000 PRIME combines large primary displays with secondary touchscreen control units. Collins Pro Line Fusion uses touch-interactive maps, customizable layouts and synthetic vision to reduce the number of discrete tasks required during flight planning and approach. At the same time, manufacturers are retaining physical controls for functions where tactile feedback is valuable, particularly in turbulence or military operations. The result is not simply a shift from buttons to touchscreens; it is a broader redesign of the human-machine interface around information prioritization, automation and reduced crew workload.
Market Drivers
Aircraft production backlogs sustain forward-fit cockpit demand
Aircraft production is the most direct source of new-build glass cockpit demand because each delivered aircraft requires a certified flight-deck configuration. Airbus delivered 793 commercial aircraft in 2025 and ended the year with an 8,754-aircraft backlog. By June 2026, its commercial backlog had increased to 9,222 aircraft, while first-half deliveries rose to 351 aircraft from 306 a year earlier. Boeing projects 43,600 new commercial aircraft deliveries over 2025-2044 as the active fleet approaches 50,000 aircraft. These figures do not translate directly into glass cockpit revenue because avionics content varies by aircraft class and supplier, but they provide long-duration visibility for cockpit display demand. Military transport, trainer, rotorcraft and business-aviation programs add a separate production base outside large commercial aircraft.
Retrofit and fleet-life extension create a second recurring demand pool
A large installed aircraft fleet creates demand for display replacement even when new-aircraft production slows. Older cathode-ray-tube displays and early-generation LCD systems face component obsolescence, limited processing capability and increasing difficulty supporting modern datalink, navigation and airspace requirements. Collins Aerospace markets large-format display retrofits for Boeing 757 and 767 aircraft that replace multiple legacy displays while reducing flight-deck weight, and it continues to offer Pro Line Fusion upgrade paths across business aircraft. Garmin serves a wide range of retrofit aircraft through G1000 NXi, G5000 and newer AXIS displays. Retrofit economics are especially attractive where a digital cockpit upgrade can extend aircraft service life without requiring replacement of the full airframe, creating demand that is less closely tied to annual aircraft deliveries.
Market Restraint
Certification cost and platform-specific integration limit rapid supplier substitution
Glass cockpits are safety-critical systems, and each display architecture must be integrated with aircraft sensors, flight controls, power systems, navigation sources, warning logic and human-factors requirements. Certification therefore involves extensive software assurance, hardware qualification, electromagnetic compatibility, environmental testing and aircraft-specific verification. A display system certified on one platform cannot simply be transferred to another aircraft without additional engineering and regulatory work. This favors established suppliers with long aircraft-OEM relationships and makes switching expensive even when a competing display offers superior computing performance. Long certification cycles also slow the introduction of consumer-style electronics, while cybersecurity and software configuration control add new lifecycle obligations as flight decks become more connected.
Segment Analysis
By Aircraft Type - Commercial and Cargo Transport Aircraft
Commercial and cargo transport aircraft remain the largest aircraft category because large airliners use multiple high-value displays with extensive system integration, redundancy and certification requirements. The segment is projected to approach USD 2.04 billion by 2031. Demand is supported by narrowbody production ramp-ups, widebody replacement and the continuing need to modernize in-service fleets. Business and general aviation is smaller in absolute value but grows faster as integrated flight decks move into high-performance piston, turboprop, light-jet and electric-aircraft categories. Garmin's July 2026 launch of G2000 PRIME for high-performance piston and electric aircraft illustrates how functionality once concentrated in turbine aircraft is moving down into smaller platforms.
By Display Type - Multi-Function Display
Multi-function displays remain the largest display category because they aggregate navigation, weather, traffic, system synoptics, checklists and mission information that would otherwise require multiple dedicated instruments. The segment is projected to reach approximately USD 1.91 billion by 2031. Primary flight displays remain indispensable and account for a similar but slightly smaller revenue pool, while engine-indicating and crew-alerting displays are concentrated in larger and more complex aircraft. Standby and mission displays form a smaller segment but can carry high unit values in military and special-mission applications where redundant or mission-specific information must remain available independently of the main flight deck.
By Screen Size - Large Displays
Large cockpit displays, generally above 15 inches, are projected to grow at approximately 5.3% annually through 2031 as commercial, business and military flight decks consolidate information onto fewer high-resolution screens. Larger display areas support split-screen views, synthetic vision, system synoptics and interactive charts without forcing crews to move repeatedly between separate pages. Medium-size displays remain important in business aviation, helicopters and retrofit installations where panel dimensions constrain screen area, while small displays continue to serve standby and general-aviation applications. The trend toward larger screens increases the value of processing, graphics and thermal-management capability even when the number of physical display units in a cockpit decreases.
By Geography - Asia Pacific
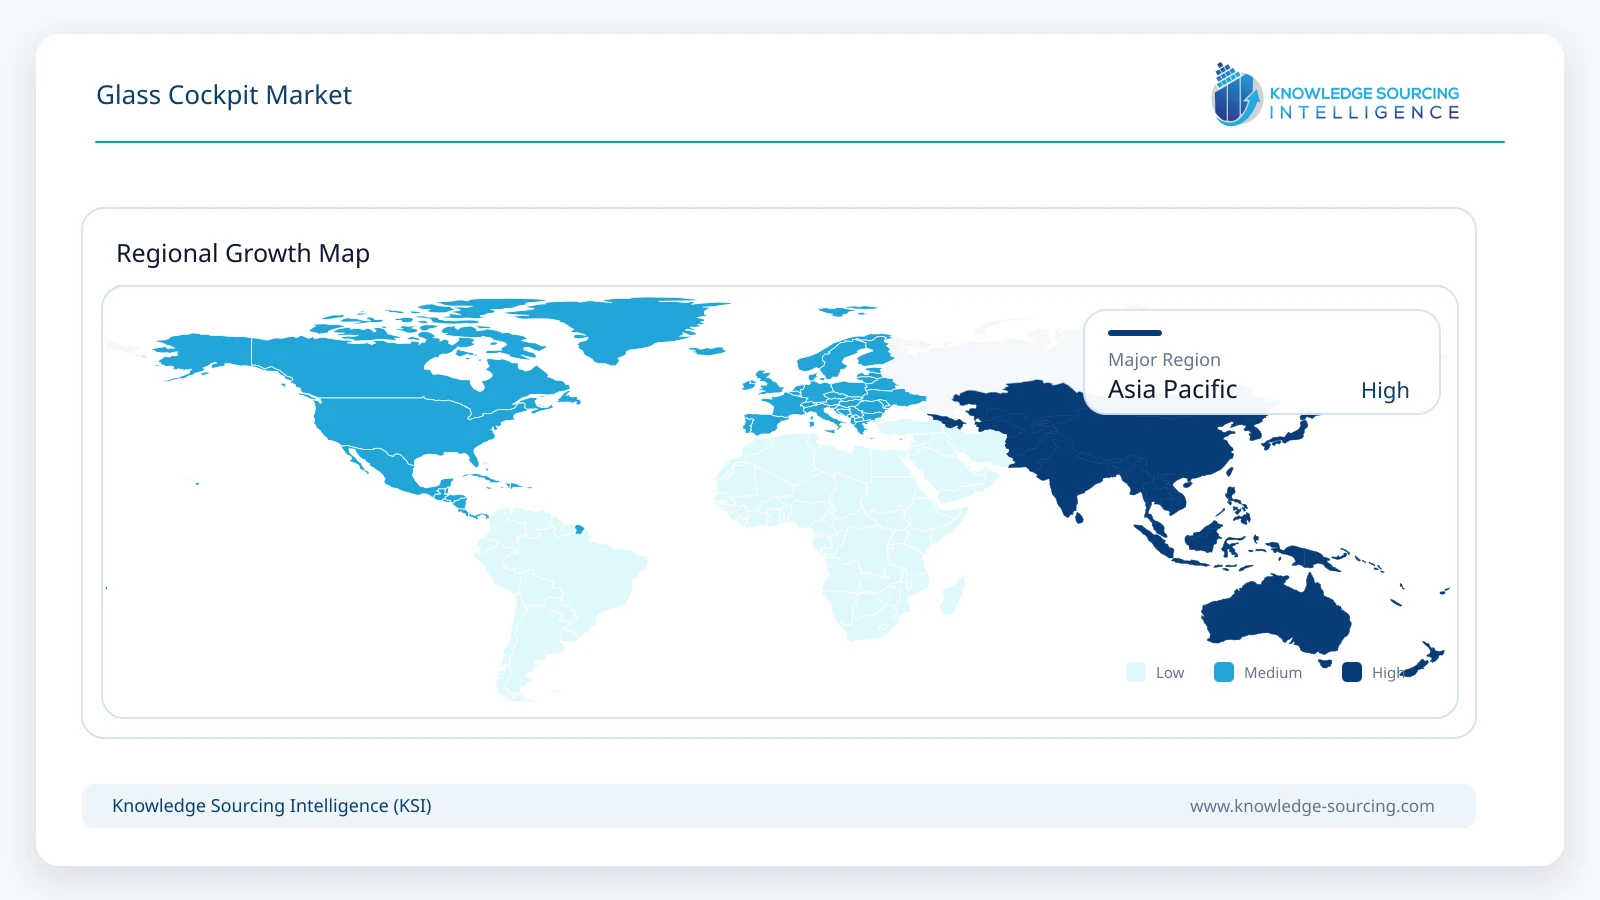
Asia Pacific is projected to reach approximately USD 1.62 billion in glass cockpit revenue by 2031. The region combines commercial fleet growth, new-aircraft manufacturing, military modernization and an expanding business-aviation and helicopter base. China and India are adding aircraft capacity and aviation infrastructure, while Japan, South Korea and Australia maintain significant commercial and defense avionics demand. North America remains the largest current market because it combines major aircraft OEMs, a large installed general-aviation fleet, defense procurement and the headquarters or major operations of Honeywell, Collins Aerospace and Garmin. Europe remains important through Airbus, Thales, Safran, Leonardo and a dense base of commercial and rotorcraft operators.
Competitive Environment
Competition is concentrated among integrated avionics suppliers with the certification experience, software capability and aircraft-OEM relationships required to win long-duration flight-deck programs. Honeywell, Collins Aerospace, Garmin and Thales hold broad positions across multiple aircraft classes, while Safran, Elbit Systems, Leonardo, L3Harris and specialist suppliers compete in military, rotorcraft, general-aviation and retrofit niches. Program awards are commercially significant because the selected architecture can remain on an aircraft platform for many years and generate recurring revenue from spares, repairs, software updates and modernization packages.
The competitive basis is moving beyond display brightness or resolution. Open architectures, multicore processing, touchscreen design, synthetic and enhanced vision, cybersecurity, datalink integration and the ability to host new applications increasingly influence platform selection. Honeywell reported in June 2026 that Anthem had five platform wins representing more than USD 10 billion in lifetime value, demonstrating the economic importance of winning next-generation flight-deck positions. Retrofit capability is another differentiator because installed fleets can support recurring demand long after new-aircraft production ends.
Recent Developments
August 2026: Collins Aerospace received a U.S. Army contract worth up to USD 472 million to support CH-47 Chinook avionics modernization and sustainment, including upgrades to a flexible cockpit architecture.
July 2026: Garmin introduced the G2000 PRIME integrated flight deck for high-performance piston and electric aircraft, extending PRIME touchscreen architecture into a new aircraft class.
July 2026: Garmin launched the AXIS family of integrated flight displays, combining display, IFR GPS, NAV/COMM and optional audio-panel functions in selected configurations for certified and experimental aircraft.
March 2025: Pilatus Aircraft and Garmin announced the Pilatus PC-12 PRO as the first certified aircraft featuring the G3000 PRIME integrated flight deck, with initial deliveries scheduled to begin in the third quarter of 2025.
Glass Cockpit Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.28 billion |
| Total Market Size in 2031 | USD 5.30 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Aircraft Type, Display Type, Screen Size, Geography |
| Companies |
|
Market Segmentation
By Aircraft Type
Commercial and Cargo Transport Aircraft
Business and General Aviation
Military Fixed-Wing Aircraft
Helicopters
Trainer and Special-Mission Aircraft
By Display Type
Primary Flight Display (PFD)
Multi-Function Display (MFD)
Engine-Indicating and Crew-Alerting System (EICAS) Display
Standby, Backup and Mission Displays
By Screen Size
Small
Medium
Large
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Aircraft Production Backlogs Sustain Forward-Fit Cockpit Demand
3.1.2. Retrofit and Fleet-Life Extension Create a Second Recurring Demand Pool
3.2. Market Restraint
3.2.1. Certification Cost and Platform-Specific Integration Limit Rapid Supplier Substitution
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Touchscreen and Multi-Touch Flight Decks
4.2. Open and Software-Defined Avionics Architectures
4.3. Synthetic and Enhanced Vision Integration
4.4. Connected Cockpits, Automation and AI-Assisted Workflows
5. GLASS COCKPIT MARKET BY AIRCRAFT TYPE
5.1. Introduction
5.2. Commercial and Cargo Transport Aircraft
5.3. Business and General Aviation
5.4. Military Fixed-Wing Aircraft
5.5. Helicopters
5.6. Trainer and Special-Mission Aircraft
6. GLASS COCKPIT MARKET BY DISPLAY TYPE
6.1. Introduction
6.2. Primary Flight Display (PFD)
6.3. Multi-Function Display (MFD)
6.4. Engine-Indicating and Crew-Alerting System (EICAS) Display
6.5. Standby, Backup and Mission Displays
7. GLASS COCKPIT MARKET BY SCREEN SIZE
7.1. Introduction
7.2. Small
7.3. Medium
7.4. Large
8. GLASS COCKPIT MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Honeywell Aerospace Technologies
10.2. Collins Aerospace (RTX)
10.3. Garmin Ltd.
10.4. Thales Group
10.5. Safran Electronics & Defense
10.6. Elbit Systems Ltd.
10.7. L3Harris Technologies, Inc.
10.8. Leonardo S.p.A.
10.9. Astronautics Corporation of America
10.10. BAE Systems plc
10.11. CMC Electronics
10.12. Innovative Solutions & Support, Inc.
10.13. Avidyne Corporation
10.14. Dynon Avionics
10.15. Aspen Avionics, Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











