
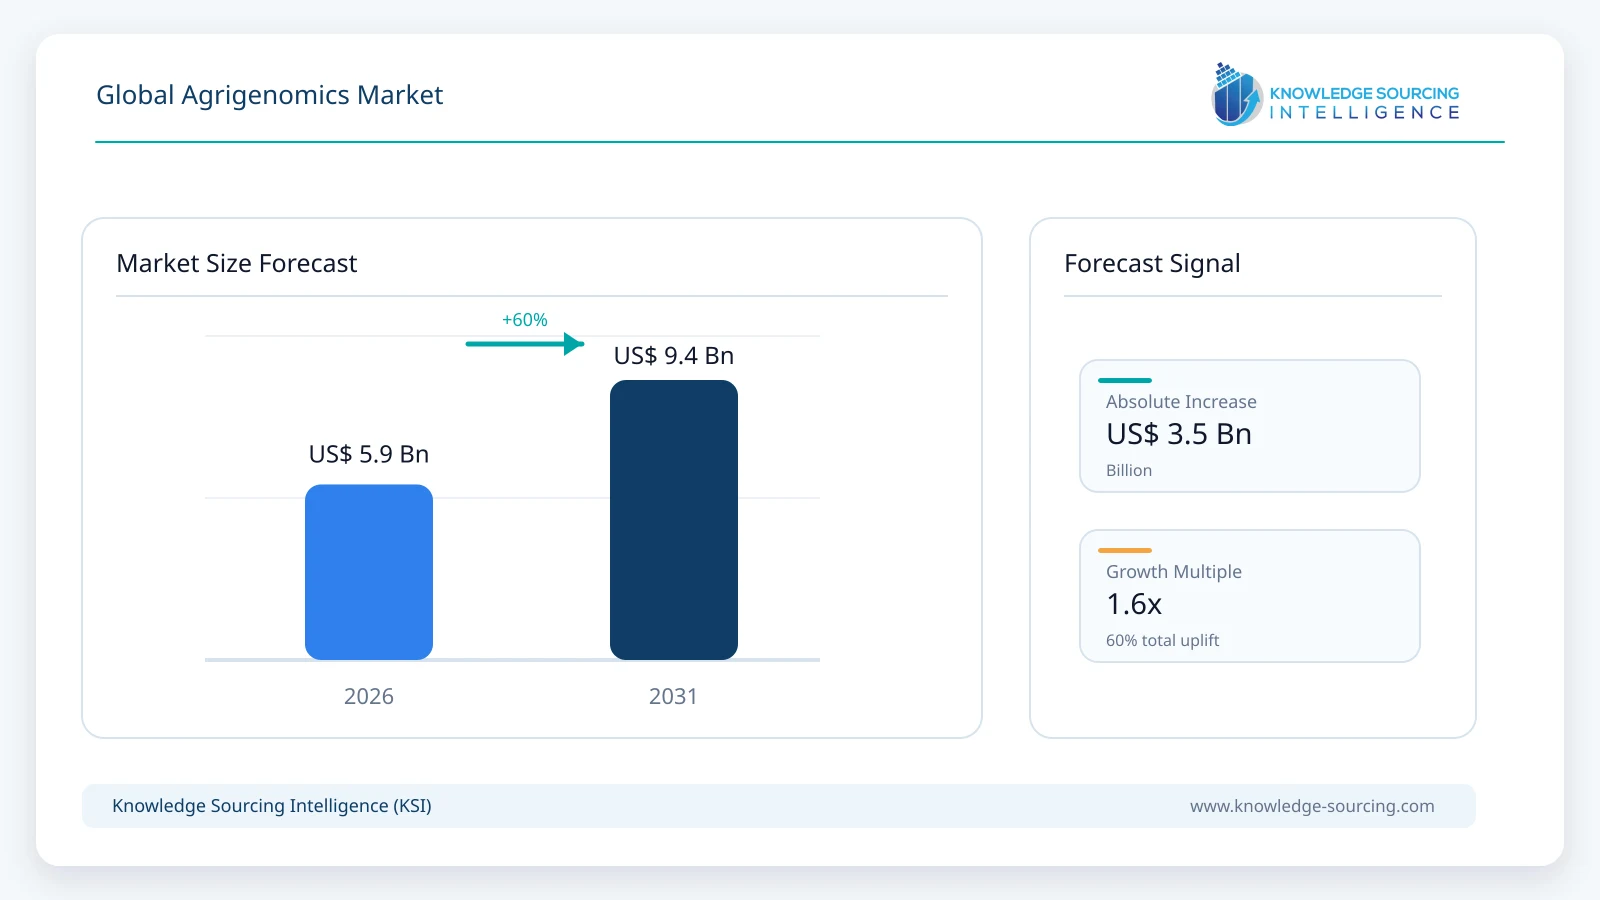
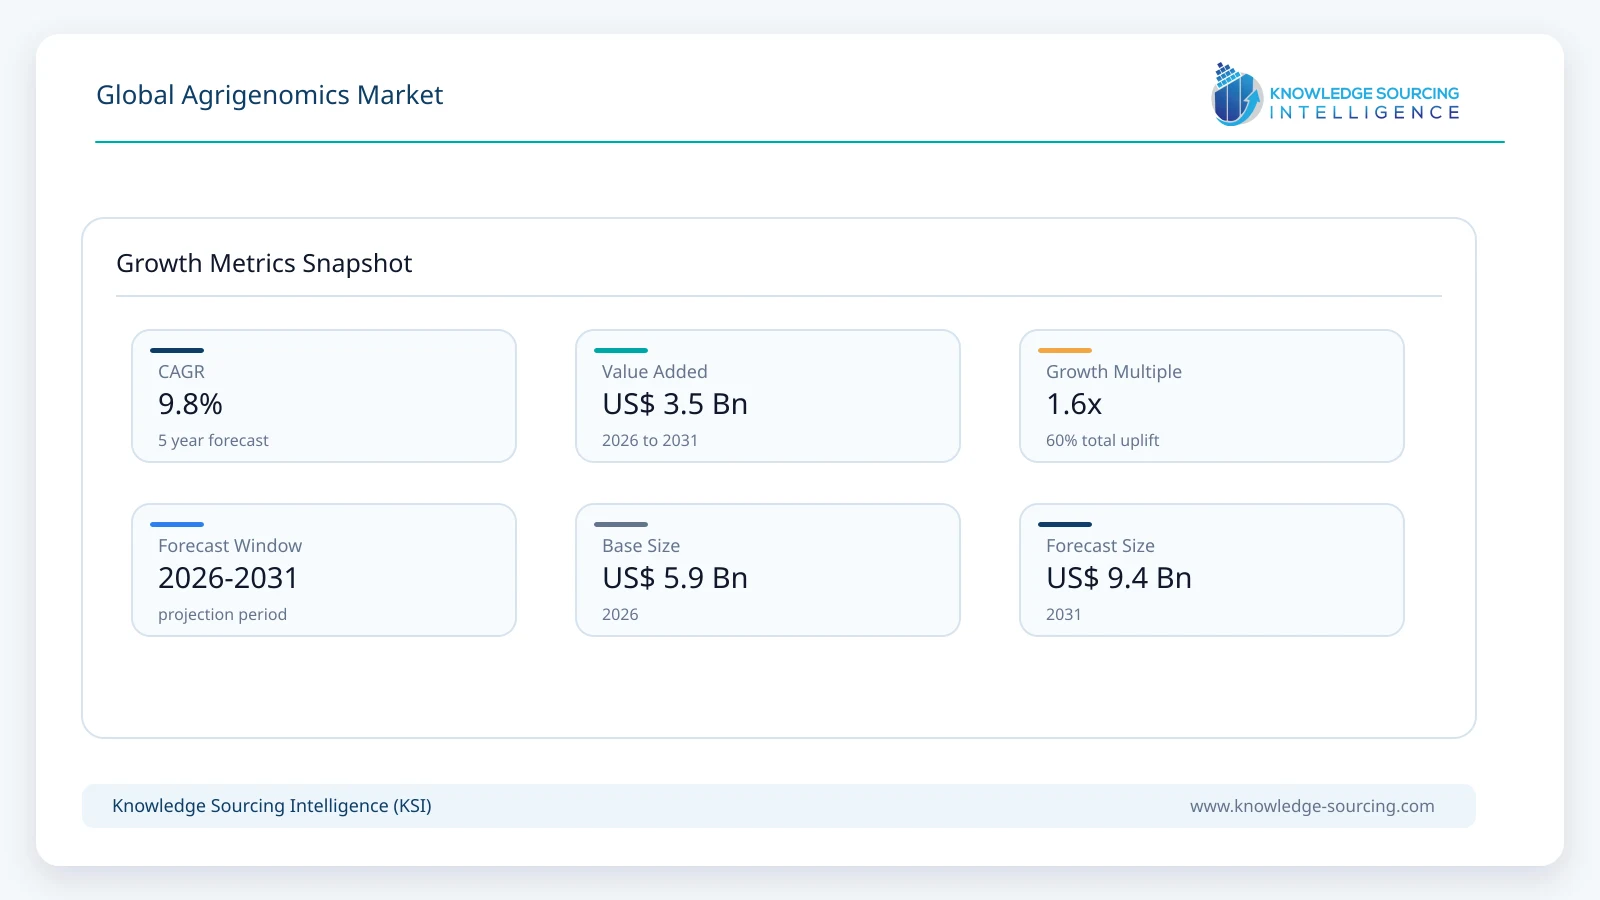
The Global Agrigenomics Market is growing at a CAGR of 9.79%, from USD 5.88 billion in 2026 to USD 9.38 billion by 2031.
Highlights:
- 1North America accounts for approximately one-third of global agrigenomics market value in 2026.
- 2Next-generation sequencing is the largest technology segment as whole-genome and low-pass workflows scale commercially.
- 3Crop genomics remains the largest application, while livestock genomics is increasingly embedded in routine breeding decisions.
- 4Long-read sequencing is gaining share where polyploid genomes, structural variants and phased haplotypes limit short-read analysis.
- 5Neogen's genomics business generated about USD 90 million in FY2025 and is under an agreed USD 160 million sale to Zoetis.
- 6Public genome-to-phenome and germplasm programs continue to support recurring agricultural sequencing and genotyping demand.
Agrigenomics is moving from project-based research into routine breeding infrastructure. Seed developers, livestock genetics companies and agricultural research organizations increasingly use genomic information to select parent lines, predict breeding values, validate varietal purity, characterize germplasm and identify disease- or climate-resilience traits before full field or progeny evaluation. The commercial value therefore spans instruments, reagents, arrays, library preparation, sequencing, genotyping, laboratory automation and bioinformatics. Large technology companies such as Illumina and Thermo Fisher Scientific compete alongside specialized agricultural testing providers including LGC Biosearch Technologies, Eurofins Genomics and AgriGenome Labs.
The technology mix is broadening. Short-read NGS remains central to high-throughput whole-genome, low-pass and targeted sequencing, while microarrays and PCR remain highly competitive for routine marker-assisted selection because they deliver predictable cost at very high sample volumes. Thermo Fisher continues to support large Axiom array portfolios across crops, livestock and aquaculture, while LGC Biosearch Technologies combines KASP chemistry with targeted GBS and high-throughput automation. Long-read platforms from PacBio and Oxford Nanopore are becoming more important for complex crop genomes, structural variants, pangenomes, haplotype phasing and functional genomics.
The livestock side is also becoming more commercially consolidated. Neogen agreed in March 2026 to sell its global GeneSeek genomics business to Zoetis for USD 160 million. The business generated approximately USD 90 million in fiscal 2025 and operates laboratories across the United States, Brazil, Australia, China and the United Kingdom. As of July 2026, Neogen continued to guide for the transaction to close by the end of the first half of fiscal 2027, meaning the businesses should still be treated separately during the 2026 market year. Zoetis is simultaneously expanding its own precision-animal-health portfolio through CLARIFIDE Plus traits linked to heat resilience and environmental stewardship.
Market Trends
Low-Pass Whole-Genome Sequencing Is Challenging Fixed Arrays in High-Throughput Breeding
Low-pass whole-genome sequencing is becoming more commercially practical as library preparation, multiplexing and imputation improve. seqWell launched AgriPrep in January 2026 specifically for applied agrigenomics, supporting up to 3,072 built-in indexes and low-coverage whole-genome or SKIM-sequencing workflows for genomic selection, parentage, trait mapping and variant discovery. The approach competes with fixed arrays by generating genome-wide information while retaining scalable per-sample economics. Arrays remain attractive for standardized breeding pipelines, but flexible sequencing-based genotyping becomes more valuable when breeding programs require novel markers, structural variants or changing panels.
Long-Read Sequencing Is Expanding Beyond Reference-Genome Assembly
Long-read sequencing has moved beyond one-time de novo assembly toward recurring breeding and trait-discovery workflows. PacBio positions HiFi sequencing for haplotype-resolved pangenomes, structural-variant discovery, genomic selection and genome editing validation, while its 2026 Fiber-seq resources extend agricultural genomics into chromatin accessibility and regulatory architecture. Oxford Nanopore is similarly expanding plant research workflows around unrestricted read length, methylation and full-length transcript analysis. These capabilities are especially relevant in polyploid crops, repetitive plant genomes and populations where short-read mapping can obscure important structural variation.
Epigenomics Is Becoming a New Layer of Livestock Selection
Agrigenomics is beginning to incorporate epigenetic information alongside sequence variation. Illumina introduced the Infinium Bovine Methylation Array in 2026, targeting roughly 42,000 CpG sites associated with fertility, age, breed, nutrition, inflammation, milk somatic-cell count, heat stress and metabolic stress. The commercial implication is important because livestock breeding programs can increasingly examine regulatory biology and environmental response rather than relying only on inherited SNP markers. Epigenomic tools remain a small part of market revenue but expand the analytical value of established microarray infrastructure.
Agricultural Genomics Is Becoming More Software- and Bioinformatics-Intensive
Sequencing output is rising faster than the availability of specialist bioinformatics capacity. Breeding organizations increasingly require variant calling, imputation, genomic prediction, pangenome analysis, GWAS, data integration and decision-support tools rather than raw sequence files. Neogen's Encompass platform, Illumina's DRAGEN and GenomeStudio environments, Eurofins' agrigenomics bioinformatics services and LGC's integrated genotyping workflows illustrate the shift. This increases recurring service value and favors suppliers that combine wet-lab technology with interpretation and breeding-program support.
Market Drivers
Genomic Selection Shortens Breeding Cycles and Improves Selection Accuracy
Genomic selection allows breeders to estimate genetic merit earlier than conventional phenotype-only approaches. In livestock, genomic breeding values can be calculated before mature production traits become visible, while crop breeders can screen large populations for desirable markers before multi-season field testing. The result is higher selection intensity and faster genetic gain. This economic benefit is strongest when sample volumes are large enough for genotyping cost to be outweighed by fewer breeding cycles, reduced field-testing burden and improved selection confidence.
Climate Resilience and Food Security Expand Public and Commercial Genomics Programs
Climate variability is increasing the value of traits linked to drought tolerance, heat resilience, disease resistance, yield stability and nutrient-use efficiency. USDA's 2026 research priorities continue to support genome science, AI and the Agricultural Genome to Phenome Initiative across agriculturally significant crops, livestock, poultry and aquaculture. Similar programs operate through CGIAR, national breeding institutes and agricultural universities. These programs sustain demand for sequencing, germplasm characterization and marker development even where commercial seed markets alone would not justify the full research cost.
Falling Cost per Data Point Expands Commercial Adoption
Agrigenomics adoption is highly sensitive to the cost of processing thousands or millions of breeding samples. New library-preparation workflows, higher sequencer throughput, targeted GBS, automated PCR and improved multiplexing reduce cost per genotype and make genomic selection economical for more crops and species. LGC reports genotyping systems capable of millions of samples annually, while newer sequencing platforms from Element Biosciences, Complete Genomics and other suppliers target lower run cost and higher sample density. As cost falls, genomics moves from elite research populations into routine quality control and production breeding.
Market Restraints
Bioinformatics Complexity, Capital Cost and Validation Requirements Limit Smaller Programs
Generating data has become easier, but interpreting it remains resource intensive. Complex agricultural genomes can be polyploid, highly repetitive or poorly represented by reference assemblies. Breeding programs also need high-quality phenotypes to train genomic prediction models, and poorly standardized samples can reduce data quality. Smaller seed companies and public institutes may therefore depend on external laboratories rather than owning high-throughput sequencers. Commercialization can also require multi-season validation, seed certification, animal-breeding validation or regulatory documentation, extending the time between genomic discovery and economic return.
Segment Analysis
By Technology - Next-Generation Sequencing
Next-generation sequencing is estimated at approximately USD 2.4 billion in 2026 and represents the largest technology segment. Short-read sequencing supports whole-genome sequencing, low-pass genotyping, targeted sequencing, RNA sequencing and high-throughput variant discovery, while long-read sequencing is growing faster from a smaller base. PCR/qPCR and microarrays remain essential for routine marker validation and high-volume screening, so NGS growth should be interpreted as an expansion of analytical depth rather than a complete replacement of established genotyping technologies.
By Application - Crop Genomics
Crop genomics is estimated at approximately USD 3.4 billion in 2026 and remains the largest application segment. Major use cases include marker-assisted selection, genomic selection, trait discovery, hybrid purity, germplasm characterization, disease resistance, stress tolerance and seed quality assurance. Cereals and grains represent the largest crop group because of the scale of maize, wheat and rice breeding programs, while fruits, vegetables, oilseeds and pulses provide high-value specialized demand. Livestock genomics is smaller but commercially mature in dairy and beef cattle and increasingly important in swine, poultry and aquaculture.
By Workflow / Service - Genotyping and Marker-Assisted Selection
Genotyping and marker-assisted selection are estimated at approximately USD 2.1 billion in 2026 and form the largest workflow segment. Routine breeding programs often process very large sample populations using fixed arrays, KASP, qPCR or targeted sequencing rather than deep whole-genome sequencing. Sequencing and genome assembly grow faster as breeders adopt low-pass WGS and long reads, while bioinformatics and data analysis capture increasing value because genomic prediction depends on integrating markers with phenotype, pedigree and environmental data.
By End User - Seed and Breeding Companies
Seed and breeding companies are estimated at approximately USD 2.3 billion in 2026 and represent the largest end-user group. These organizations purchase instruments, reagents and outsourced services to accelerate variety development and quality control. Livestock genetics and animal-health companies form another major commercial group, while universities, government research institutes and contract laboratories provide a large research and service base. Outsourcing remains particularly important for smaller breeding organizations that cannot justify dedicated sequencing infrastructure.
By Geography - North America
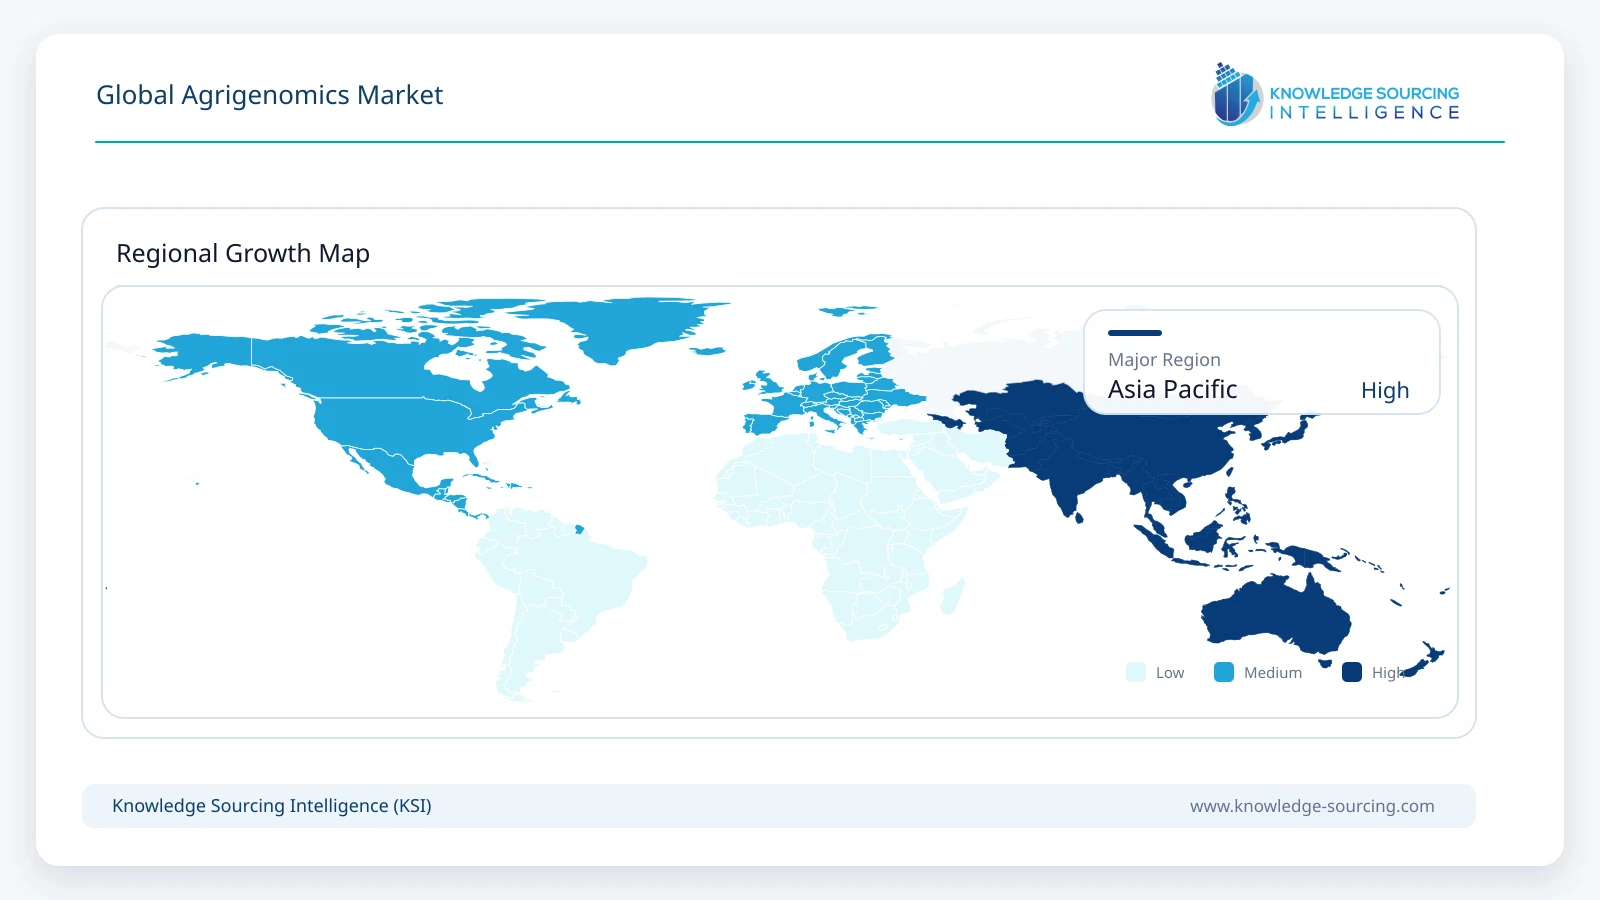
North America is estimated at approximately USD 2.0 billion in 2026 and remains the largest regional market. The United States combines major seed and livestock breeding companies, USDA genomics programs, agricultural universities and leading sequencing suppliers. Europe has strong plant breeding, livestock genetics and genomics-service capability, while Asia Pacific grows faster through food-security programs, expanding biotech research and larger commercial breeding systems in China, India, Japan, South Korea and Australia. South America is strategically important through soybean, maize and cattle breeding in Brazil and Argentina.
Competitive Environment
The agrigenomics competitive landscape spans sequencing-platform companies, array and PCR suppliers, automation vendors, laboratory-service providers and livestock-genomics specialists. Illumina, Thermo Fisher Scientific, PacBio, Oxford Nanopore, Complete Genomics and Element Biosciences compete primarily through sequencing and genotyping platforms. LGC Biosearch Technologies, Eurofins Genomics and AgriGenome Labs provide agricultural testing and genotyping services, while Daicel Arbor Biosciences and seqWell provide specialized target-enrichment and library-preparation workflows. Tecan and Agilent participate through NGS automation, genotyping, fragment analysis and plant/animal microarray solutions.
Recent Developments
July 2026: Neogen confirmed that the USD 160 million sale of its global Genomics business to Zoetis remained pending regulatory approval and was targeted to close by the end of the first half of fiscal 2027.
June 2026: Element Biosciences raised an expanded Series E round including USD 175 million from Samsung Electronics to accelerate commercialization of its genomic and multiomic platforms.
April 2026: Illumina highlighted TruPath whole-genome and species-specific methylation technologies at the AGBT Agricultural meeting for crop, livestock and aquaculture research.
March 2026: Illumina introduced the Infinium Bovine Methylation Array, targeting approximately 42,000 CpG sites linked to cattle fertility, stress, nutrition and other phenotypes.
March 2026: Zoetis agreed to acquire Neogen's animal genomics business, including the GeneSeek testing network, for USD 160 million.
January 2026: seqWell launched AgriPrep, a library-preparation kit designed for high-throughput low-pass whole-genome sequencing and SKIM sequencing in agrigenomics.
Agrigenomics Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.88 billion |
| Total Market Size in 2031 | USD 9.38 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.79% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Application, Workflow / Service, End User, Geography |
| Companies |
|
Market Segmentation
By Technology
PCR / qPCR
Microarrays
Short-Read Next-Generation Sequencing
Long-Read Sequencing
Other Genomic and Multiomic Technologies
By Application
Crop Genomics
Cereals and Grains
Oilseeds and Pulses
Fruits and Vegetables
Other Crops
Livestock Genomics
Cattle
Swine
Poultry
Other Livestock
Aquaculture and Other Agricultural Species
By Workflow / Service
Genotyping and Marker-Assisted Selection
Sequencing and Genome Assembly
Trait Purity and Quality Control
Gene Expression and Functional Genomics
Bioinformatics and Data Analysis
By End User
Seed and Plant Breeding Companies
Livestock Genetics and Animal Health Companies
Research Institutes and Universities
Contract Laboratories and CROs
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Netherlands
Spain
Others
Middle East & Africa
South Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Genomic Selection Shortens Breeding Cycles and Improves Selection Accuracy
3.1.2. Climate Resilience and Food Security Expand Public and Commercial Genomics Programs
3.1.3. Falling Cost per Data Point Expands Commercial Adoption
3.2. Market Restraints
3.2.1. Bioinformatics Complexity, Capital Cost and Validation Requirements Limit Smaller Programs
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Regulatory and Policy Environment
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. PCR and qPCR Genotyping
4.2. Microarray Genotyping
4.3. Short-Read Next-Generation Sequencing
4.4. Long-Read Sequencing
4.5. Low-Pass Whole-Genome and Genotyping-by-Sequencing
4.6. Epigenomics, Transcriptomics and Multiomics
4.7. Bioinformatics and Genomic Prediction
5. GLOBAL AGRIGENOMICS MARKET BY TECHNOLOGY
5.1. Introduction
5.2. PCR / qPCR
5.3. Microarrays
5.4. Short-Read Next-Generation Sequencing
5.5. Long-Read Sequencing
5.6. Other Genomic and Multiomic Technologies
6. GLOBAL AGRIGENOMICS MARKET BY APPLICATION
6.1. Introduction
6.2. Crop Genomics
6.2.1. Cereals and Grains
6.2.2. Oilseeds and Pulses
6.2.3. Fruits and Vegetables
6.2.4. Other Crops
6.3. Livestock Genomics
6.3.1. Cattle
6.3.2. Swine
6.3.3. Poultry
6.3.4. Other Livestock
6.4. Aquaculture and Other Agricultural Species
7. GLOBAL AGRIGENOMICS MARKET BY WORKFLOW / SERVICE
7.1. Introduction
7.2. Genotyping and Marker-Assisted Selection
7.3. Sequencing and Genome Assembly
7.4. Trait Purity and Quality Control
7.5. Gene Expression and Functional Genomics
7.6. Bioinformatics and Data Analysis
8. GLOBAL AGRIGENOMICS MARKET BY END USER
8.1. Introduction
8.2. Seed and Plant Breeding Companies
8.3. Livestock Genetics and Animal Health Companies
8.4. Research Institutes and Universities
8.5. Contract Laboratories and CROs
9. GLOBAL AGRIGENOMICS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Netherlands
9.4.5. Spain
9.4.6. Others
9.5. Middle East & Africa
9.5.1. South Africa
9.5.2. Saudi Arabia
9.5.3. UAE
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Australia
9.6.6. Indonesia
9.6.7. Thailand
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Sequencing and Genotyping Platform Providers
10.2. Agricultural Genomics Service Providers
10.3. Livestock Genomics and Precision Breeding Providers
10.4. M&A, Partnerships and Technology Development
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. Illumina, Inc.
11.2. Thermo Fisher Scientific Inc.
11.3. Pacific Biosciences of California, Inc. (PacBio)
11.4. Oxford Nanopore Technologies plc
11.5. Complete Genomics, Inc.
11.6. Element Biosciences, Inc.
11.7. LGC Biosearch Technologies
11.8. Eurofins Genomics
11.9. Neogen Corporation (GeneSeek)
11.10. Zoetis Inc.
11.11. seqWell, Inc.
11.12. Daicel Arbor Biosciences
11.13. Tecan Group Ltd.
11.14. Agilent Technologies, Inc.
11.15. AgriGenome Labs Pvt. Ltd.
11.16. STgenetics
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











