
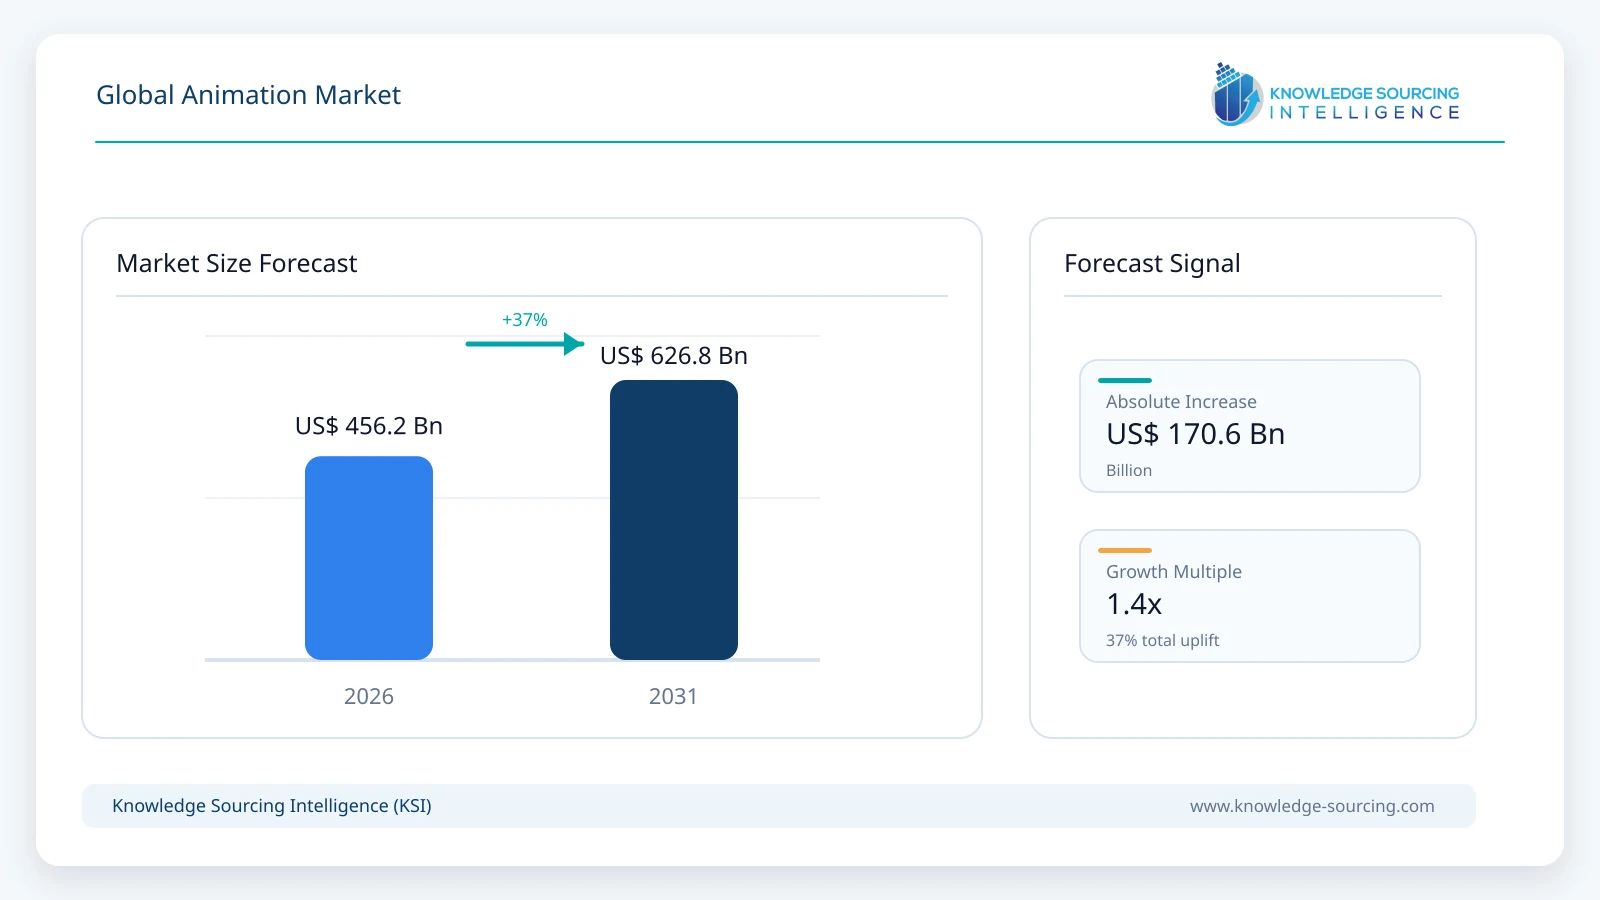
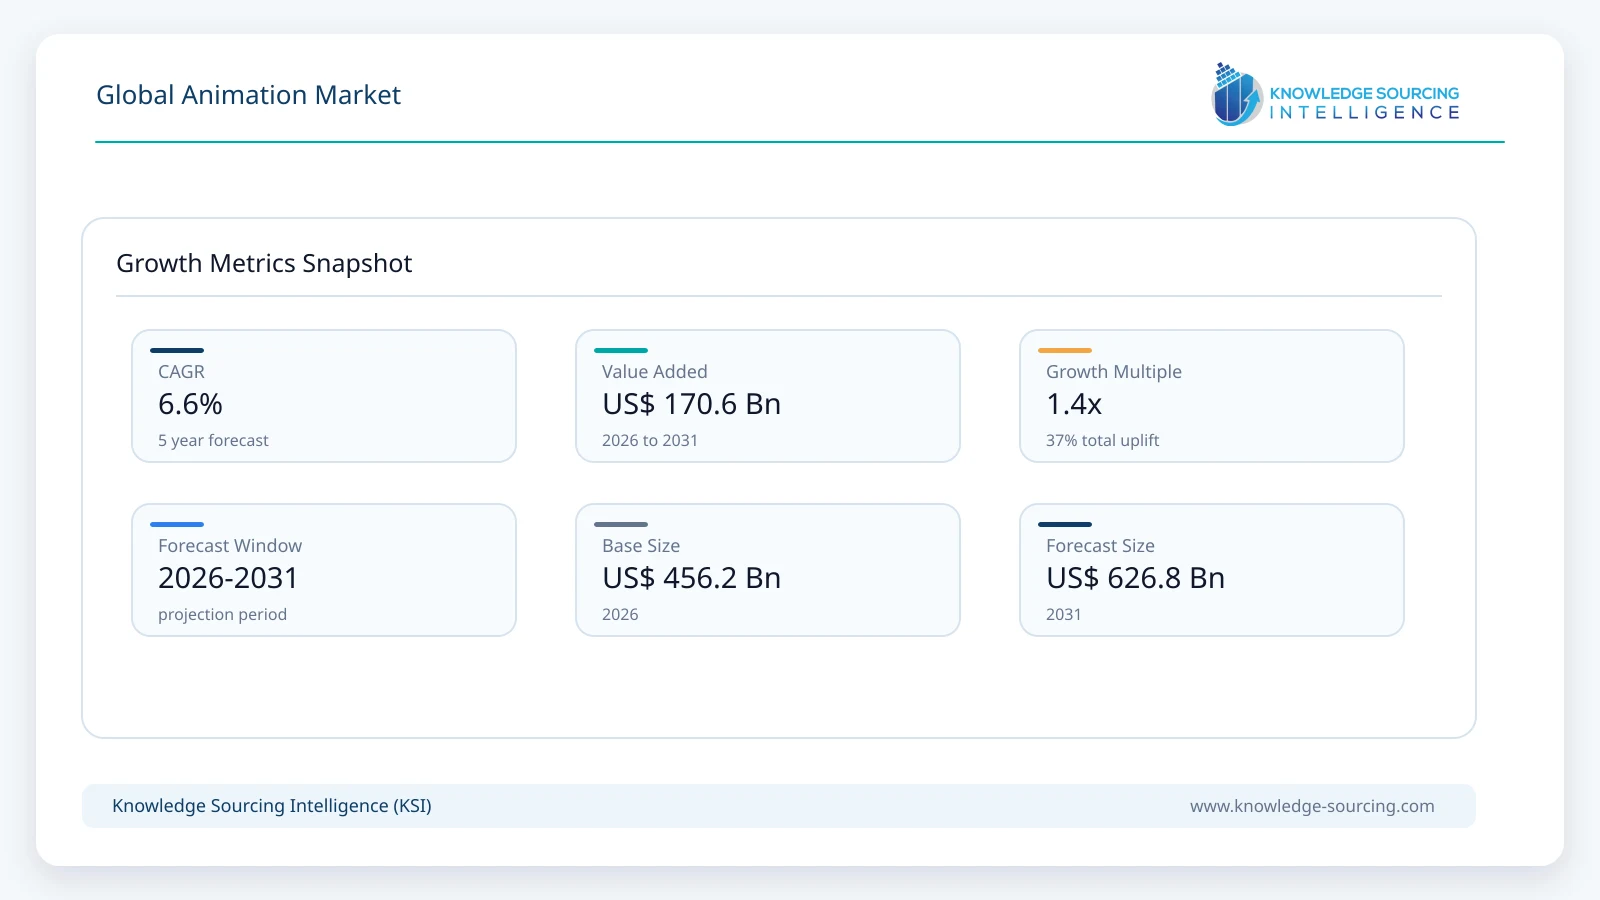
The global animation market is forecast to grow from USD 456.2 billion in 2026 to USD 626.8 billion by 2031, representing a CAGR of approximately 6.6% during the forecast period.
Highlights:
- 13D and CGI animation accounts for approximately 43% of market value in 2026.
- 2Media and entertainment represents approximately 62% of animation demand in 2026.
- 3Asia Pacific accounts for approximately 32% of global animation revenue in 2026.
- 4Gaming and interactive animation is projected to gain market share through 2031.
- 5More than 130 million Netflix members watch animated titles globally each month.
- 6Japan’s anime industry market reached JPY 3.84 trillion ($25.35 billion) in 2024.
Market Overview
The animation market encompasses commercial activity generated through the creation, production, distribution, licensing, and exploitation of animated content and animation services across film, television, streaming, gaming, advertising, education and enterprise applications. The industry includes 2D animation, 3D and computer-generated imagery, motion graphics, stop motion and hybrid production techniques. Animated intellectual property also generates value through licensing and merchandise where the underlying commercial value is directly associated with animated franchises.
The global animation market is being accelerated by growth in streaming animation, anime, gaming, global IP licensing and the use of animation beyond entertainment. Animation is increasingly deployed in advertising, product visualization, education, healthcare communication and corporate content, while production technologies are reducing barriers for smaller studios and independent creators.
Streaming has materially expanded the addressable audience for animated content. Netflix reported in June 2026 that more than 130 million members globally watch animated titles every month, while anime programming generated more than 1.5 billion views during 2025. The company has consequently expanded its animation production infrastructure and partnerships, including Netflix Animation Studios and relationships with external studios such as MAPPA.
Japanese animation provides another indication of the industry’s international expansion. The Association of Japanese Animations reported that Japan’s broad anime industry market reached JPY 3.84 trillion ($25.35 billion) in 2024, increasing 14.8% year over year to a record level. International revenue reached JPY 2.17 trillion ($14.33 billion), increasing 26%, and exceeded the JPY 1.67 trillion ($11.03 billion) domestic market.
The commercial model is also extending beyond theatrical and television distribution. Successful animated franchises generate revenue through streaming, consumer products, games, music, licensing and location-based entertainment. At the same time, independent production companies increasingly work within co-production and outsourcing structures that distribute production across multiple countries and specialized studios.
Major Market Drivers
Streaming, Global Franchises and International Anime Consumption
Streaming platforms have expanded animation from a predominantly television and theatrical format into an always-available global content category. Animated productions can travel internationally with fewer location-specific production constraints than live-action content, while dubbing and localization enable the same intellectual property to reach multiple markets.
Netflix’s 2026 animation slate spans CG animation, hand-drawn productions, anime, adult animation and family content. The company reported more than 130 million monthly members watching animation and more than 1.5 billion views of anime programming during 2025. Netflix also opened a dedicated Animation Studios location in Vancouver in April 2026 and continues operating its animation production network across multiple international locations.
Anime is becoming particularly important to global growth. Japan’s international anime market increased 26% during 2024, significantly faster than its domestic market. Netflix strengthened its partnership with MAPPA in January 2026 to jointly develop globally oriented projects and exclusively stream a new slate of MAPPA productions worldwide.
Animation franchises are consequently being evaluated as long-duration intellectual property rather than one-time film or television releases. Studios increasingly plan theatrical, streaming, gaming, licensing and merchandise strategies together, increasing the total commercial value generated by successful animated properties.
3D Production, Real-Time Workflows and AI-Assisted Animation
Animation production is being reshaped by improvements in rendering, motion capture, cloud collaboration and artificial intelligence. These technologies can reduce time spent on technically repetitive activities while allowing artists to iterate more rapidly on character movement, environments, lighting and shot composition.
Autodesk expanded Flow Studio during 2026 with AI-based character rigging, markerless motion capture and neural rendering capabilities. AI Rigging allows generated 3D characters to be prepared for animation with substantially less manual setup, while the company’s newer workflows integrate AI-generated assets with editable scenes, cameras and animation controls.
These capabilities do not eliminate the need for skilled animators but alter the economics of production. Previsualization, background generation, asset creation and repetitive rigging tasks can be accelerated, allowing production teams to direct resources toward creative decisions and high-value character work.
Real-time rendering also creates stronger links between film, television and game-production pipelines. Assets built for one environment can increasingly be adapted across linear entertainment, interactive content and immersive experiences, supporting growth in 3D and CGI animation through 2031.
Major Market Restraints
High Production Costs and Long Development Cycles
High-quality animated films and series remain expensive despite improvements in production technology. Feature animation requires extensive work across story development, design, modeling, rigging, animation, lighting, rendering, effects, editing and sound. Production schedules can extend across several years, increasing exposure to labor costs and creative changes.
Large studios can distribute these risks across established franchises and global distribution networks, while independent studios face greater financing constraints. High-end animation also requires specialized artists and technical infrastructure, particularly for complex 3D productions.
AI and real-time tools are reducing selected production costs, but savings are not uniform. Premium animated content increasingly competes on visual quality, distinctive artistic style and increasingly sophisticated environments, which can offset productivity gains by raising audience expectations.
Talent Availability, Copyright and Generative-AI Governance
The animation industry requires specialized creative and technical skills covering character animation, rigging, modeling, storyboarding, visual development, effects and production technology. Demand for artists with experience in real-time engines and AI-assisted workflows adds another layer to existing talent requirements.
Generative AI also introduces copyright and ownership questions concerning training data, character likenesses, production assets and creative attribution. Studios need workflows that protect proprietary intellectual property and allow commercially produced assets to be traced and controlled.
This is particularly important for animation because characters and visual worlds can become long-term franchise assets. Technology adoption therefore depends not only on production efficiency but also on rights management, creative control and contractual clarity.
Market Trends
Anime Is Becoming a Global Mainstream Content Category
International anime consumption is expanding faster than its domestic Japanese market. The Association of Japanese Animations reported that overseas anime activity reached JPY 2.17 trillion ($14.33 billion) in 2024, exceeding the domestic anime industry market.
Streaming has accelerated this internationalization by giving Japanese studios immediate access to audiences across North America, Europe, Latin America and Asia. Netflix’s partnership with MAPPA and continuing investment in anime demonstrate how global platforms increasingly participate directly in development rather than only acquiring completed programming.
The result is greater international financing, licensing and co-production around Japanese animation intellectual property.
AI Is Moving From Asset Generation Into Production Workflows
AI adoption in animation is moving beyond image generation toward controllable production functions. Autodesk introduced AI Rigging and Neural Layer capabilities in Flow Studio in April 2026, followed by an integrated 3D Editor and Canvas environment in August. These tools allow creators to generate and rig characters, assemble scenes and control cameras while retaining editable 3D structures.
The distinction is commercially important because professional studios require control and consistency across shots rather than isolated generated images. AI tools that integrate with established animation pipelines are therefore more relevant to professional production than standalone generation applications.
Hybrid Visual Styles Are Increasing
Animation studios increasingly combine 2D, 3D, hand-drawn and stylized computer graphics rather than adhering to one visual technique. This allows productions to differentiate themselves visually while benefiting from digital production efficiencies.
Sony Pictures Animation’s Spider-Verse productions helped establish greater commercial acceptance of stylized CGI, while newer productions continue combining digital techniques with hand-drawn visual languages. Sony Pictures Classics’ May 2026 acquisition of Iron Boy, a hand-painted animated feature, also demonstrates continued commercial interest in distinctive non-standard animation aesthetics.
Hybrid production is consequently included alongside traditional 2D and 3D formats as a meaningful area of creative development.
Animation Production Is Becoming More International
Production capacity is expanding beyond the traditional U.S. studio centres. Canada, India, France, Japan, South Korea, Australia and other markets increasingly participate in animation production, outsourcing and visual-effects pipelines.
Netflix opened its new Animation Studios location in Vancouver on April 9, 2026 and its Eyeline Studios production and innovation facility in Hyderabad on March 12, 2026. The Hyderabad investment specifically supports India’s growing animation, visual-effects, gaming and comics ecosystem.
International production enables studios to access specialized talent, tax incentives and cost structures while supporting round-the-clock production workflows.
Segment Analysis:
By Type
3D and CGI Animation
3D and CGI animation accounts for approximately 43% of global animation market value in 2026, making it the largest animation type. Its position reflects extensive use across feature films, television, gaming, advertising, product visualization and hybrid visual-effects environments.
3D animation benefits from reusable digital assets, sophisticated simulation and increasingly integrated production pipelines. Real-time rendering and AI-assisted rigging further improve production flexibility by allowing creators to iterate on characters and scenes more quickly.
The segment is projected to account for approximately 47% of global market value by 2031, supported particularly by gaming, theatrical animation and streaming productions. 2D animation remains commercially significant, especially across television, anime and stylized productions, but grows more gradually.
By Revenue Stream
Content Distribution and Licensing
Content distribution and licensing represents the largest animation revenue stream in 2026. It includes theatrical distribution, television licensing, streaming rights and other commercial exploitation of animated film and episodic content.
Streaming has materially increased the international reach of animation. Netflix’s 2026 slate includes original animated films, series and anime, while Disney, Universal, Sony and other major studios continue combining theatrical and streaming distribution across their animation portfolios.
The revenue model increasingly extends beyond an initial release window. Successful properties can generate repeated licensing value across territories and platforms, while long-running franchises create opportunities for sequels, series, games and merchandise.
By End User
Media and Entertainment
Media and entertainment accounts for approximately 62% of global animation market value in 2026, making it the largest end-user category. Film, television and streaming remain the industry’s principal commercial applications and support the majority of large-scale animation production.
Disney continues to operate Walt Disney Animation Studios and Pixar as major animation businesses. During fiscal 2025, Moana 2 generated approximately USD 1.1 billion in global box-office revenue, demonstrating the continuing theatrical potential of animated franchises.
Netflix, Universal, Sony and other entertainment groups are also maintaining substantial animation slates. Gaming records faster growth through 2031 as character animation, cinematics and real-time interactive environments require increasingly sophisticated animation pipelines.
By Geography
North America
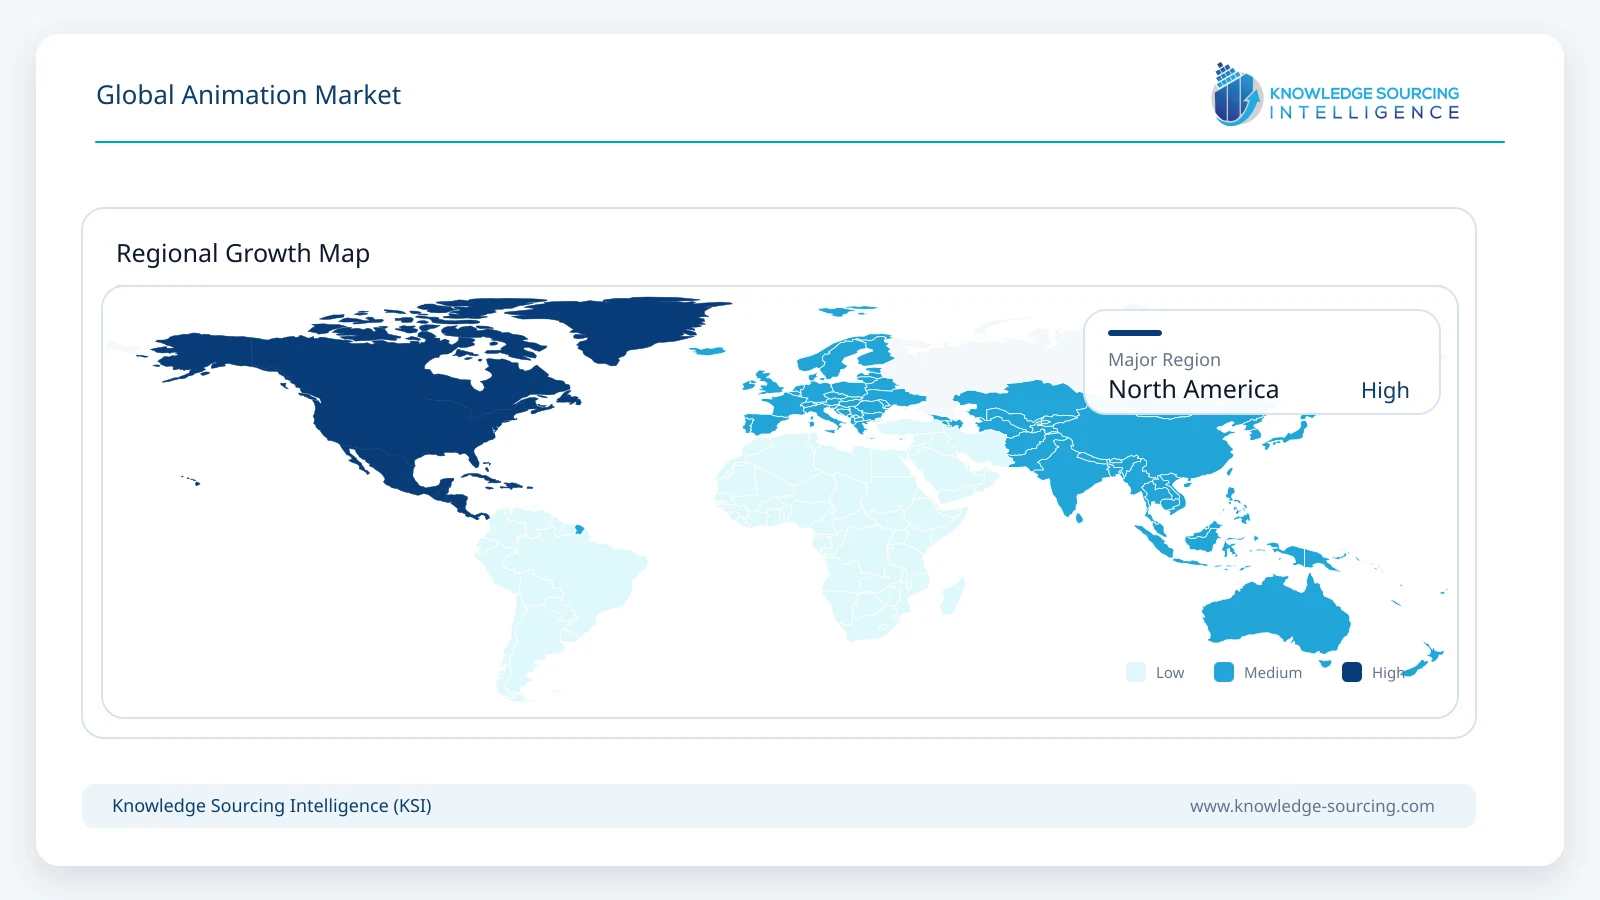
North America accounts for approximately 34% of global animation market value in 2026, making it the largest regional market. The United States hosts several of the world’s largest animation studios and media companies, including Disney, Pixar, DreamWorks Animation, Illumination, Sony Pictures Animation, Warner Bros. Animation and Netflix Animation Studios.
The region benefits from established theatrical and streaming distribution, global intellectual-property ownership and a mature production-services ecosystem. Major animated properties can generate revenue through multiple channels including films, episodic programming, licensing, gaming and consumer products.
North America remains the largest regional market through 2031, although its share declines modestly as Asia Pacific expands faster. Asia Pacific benefits from rapid international growth of Japanese anime, increasing Chinese and Korean content production and expanding animation capabilities in India and Southeast Asia.
Competitive Landscape
The global animation market combines large vertically integrated entertainment groups, independent animation studios and specialized production houses. Competitive advantage increasingly depends on ownership of recognizable intellectual property, access to global distribution and the ability to maintain a continuous pipeline of high-quality content.
Walt Disney Animation Studios and Pixar operate within The Walt Disney Company, while DreamWorks Animation and Illumination are part of NBCUniversal. Sony Pictures Animation combines theatrical production with Sony’s wider entertainment and distribution capabilities, and Netflix increasingly combines commissioning with its own animation-studio infrastructure.
Japanese studios represent an increasingly important competitive group. Toei Animation, Studio Ghibli and MAPPA have internationally recognizable franchises and creative identities, while international streaming has widened access to Japanese animated content.
Independent studios including Aardman and LAIKA continue to differentiate through distinctive production techniques and creative styles. Production-service companies such as Cinesite and DNEG Animation also play an important role in large-scale outsourced and co-production workflows.
Recent Developments
June 26, 2026: The Walt Disney Company presented new projects from Walt Disney Animation Studios, Pixar, 20th Television Animation and Disney Kids & Family at Annecy International Animation Film Festival.
June 24, 2026: Netflix announced its animation slate for 2026 and beyond and reported that more than 130 million members globally watch animation each month.
May 21, 2026: Sony Pictures Classics acquired rights across multiple territories to Louis Clichy’s hand-painted animated feature Iron Boy.
April 28, 2026: Autodesk added AI Rigging and Neural Layer capabilities to Flow Studio, expanding AI-assisted character preparation and animation workflows.
April 9, 2026: Netflix Animation Studios officially opened its new animation production facility in Vancouver, Canada.
January 20, 2026: Netflix and MAPPA expanded their strategic partnership to co-develop new animation projects for worldwide distribution.
Market Outlook
The global animation market growth is supported by the continued internationalization of streaming content, expansion of anime, greater commercial exploitation of animated intellectual property and increasing use of animation in gaming and non-entertainment applications.
3D and CGI remains the largest animation type and increases its share through 2031. Hybrid production techniques also become increasingly important as studios combine traditional artistic approaches with computer-generated environments and effects.
Media and entertainment remains the largest end-user segment, while gaming records stronger growth as real-time animation and interactive environments become more sophisticated.
North America remains the largest regional market, but Asia Pacific gains share through Japanese anime, expanding regional intellectual property and increasing production capacity across India, China, South Korea and Southeast Asia.
Animation Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 456.2 billion |
| Total Market Size in 2031 | USD 626.8 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Revenue Stream, End User, Geography |
| Companies |
|
Market Segmentation
By Type
· 2D Animation
· 3D and CGI Animation
· Motion Graphics
· Stop Motion
· Hybrid and Others
By Revenue Stream
· Content Distribution and Licensing
· Animation Production and Post-Production Services
· IP Licensing and Merchandising
· Gaming and Interactive Animation
· Commercial and Enterprise Animation Services
By End User
· Media and Entertainment
· Gaming
· Advertising and Retail
· Education
· Healthcare
· Architecture, Engineering and Manufacturing
· Others
By Geography
North America
· United States
· Canada
· Mexico
South America
· Brazil
· Argentina
· Others
Europe
· United Kingdom
· France
· Germany
· Spain
· Italy
· Ireland
· Others
Middle East and Africa
· Saudi Arabia
· UAE
· South Africa
· Others
Asia Pacific
· Japan
· China
· India
· South Korea
· Australia
· Indonesia
· Thailand
· Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Primary Research Framework
2.4. Secondary Research Framework
2.5. Data Triangulation
2.6. Forecast Methodology
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of Streaming Animation and Global Anime Consumption
4.1.2. Growth of Animation Franchises Across Multiple Monetization Channels
4.1.3. Increasing Gaming and Interactive-Content Production
4.1.4. AI, Real-Time Rendering and Cloud-Based Production Workflows
4.2. Market Restraints
4.2.1. High Production Costs and Long Development Cycles
4.2.2. Shortage of Specialized Creative and Technical Talent
4.2.3. Copyright and Generative-AI Governance Challenges
4.2.4. Commercial Risk Associated With Original Animated IP
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Intellectual Property and Copyright Environment
4.7. Strategic Recommendations
5. TECHNOLOGICAL OUTLOOK
5.1. 3D and CGI Production
5.2. Real-Time Rendering
5.3. AI-Assisted Animation
5.4. AI Motion Capture and Automated Rigging
5.5. Virtual Production
5.6. Cloud Rendering and Distributed Production
5.7. Procedural Animation
5.8. Stylized and Hybrid 2D/3D Production
5.9. AR, VR and Immersive Animation
6. GLOBAL ANIMATION MARKET BY TYPE
6.1. Introduction
6.2. 2D Animation
6.3. 3D and CGI Animation
6.4. Motion Graphics
6.5. Stop Motion
6.6. Hybrid and Others
7. GLOBAL ANIMATION MARKET BY REVENUE STREAM
7.1. Introduction
7.2. Content Distribution and Licensing
7.3. Animation Production and Post-Production Services
7.4. IP Licensing and Merchandising
7.5. Gaming and Interactive Animation
7.6. Commercial and Enterprise Animation Services
8. GLOBAL ANIMATION MARKET BY END USER
8.1. Introduction
8.2. Media and Entertainment
8.3. Gaming
8.4. Advertising and Retail
8.5. Education
8.6. Healthcare
8.7. Architecture, Engineering and Manufacturing
8.8. Others
9. GLOBAL ANIMATION MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. United Kingdom
9.3.2. France
9.3.3. Germany
9.3.4. Spain
9.3.5. Italy
9.3.6. Ireland
9.3.7. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. Japan
9.5.2. China
9.5.3. India
9.5.4. South Korea
9.5.5. Australia
9.5.6. Indonesia
9.5.7. Thailand
9.5.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Walt Disney Animation Studios
11.2. Pixar Animation Studios
11.3. DreamWorks Animation
11.4. Illumination
11.5. Sony Pictures Animation
11.6. Netflix Animation Studios
11.7. Warner Bros. Animation
11.8. Toei Animation Co., Ltd.
11.9. Studio Ghibli, Inc.
11.10. MAPPA Co., Ltd.
11.11. Aardman Animations Ltd.
11.12. LAIKA, LLC
12. APPENDIX
Navigate
Trusted by the world's leading organizations











