
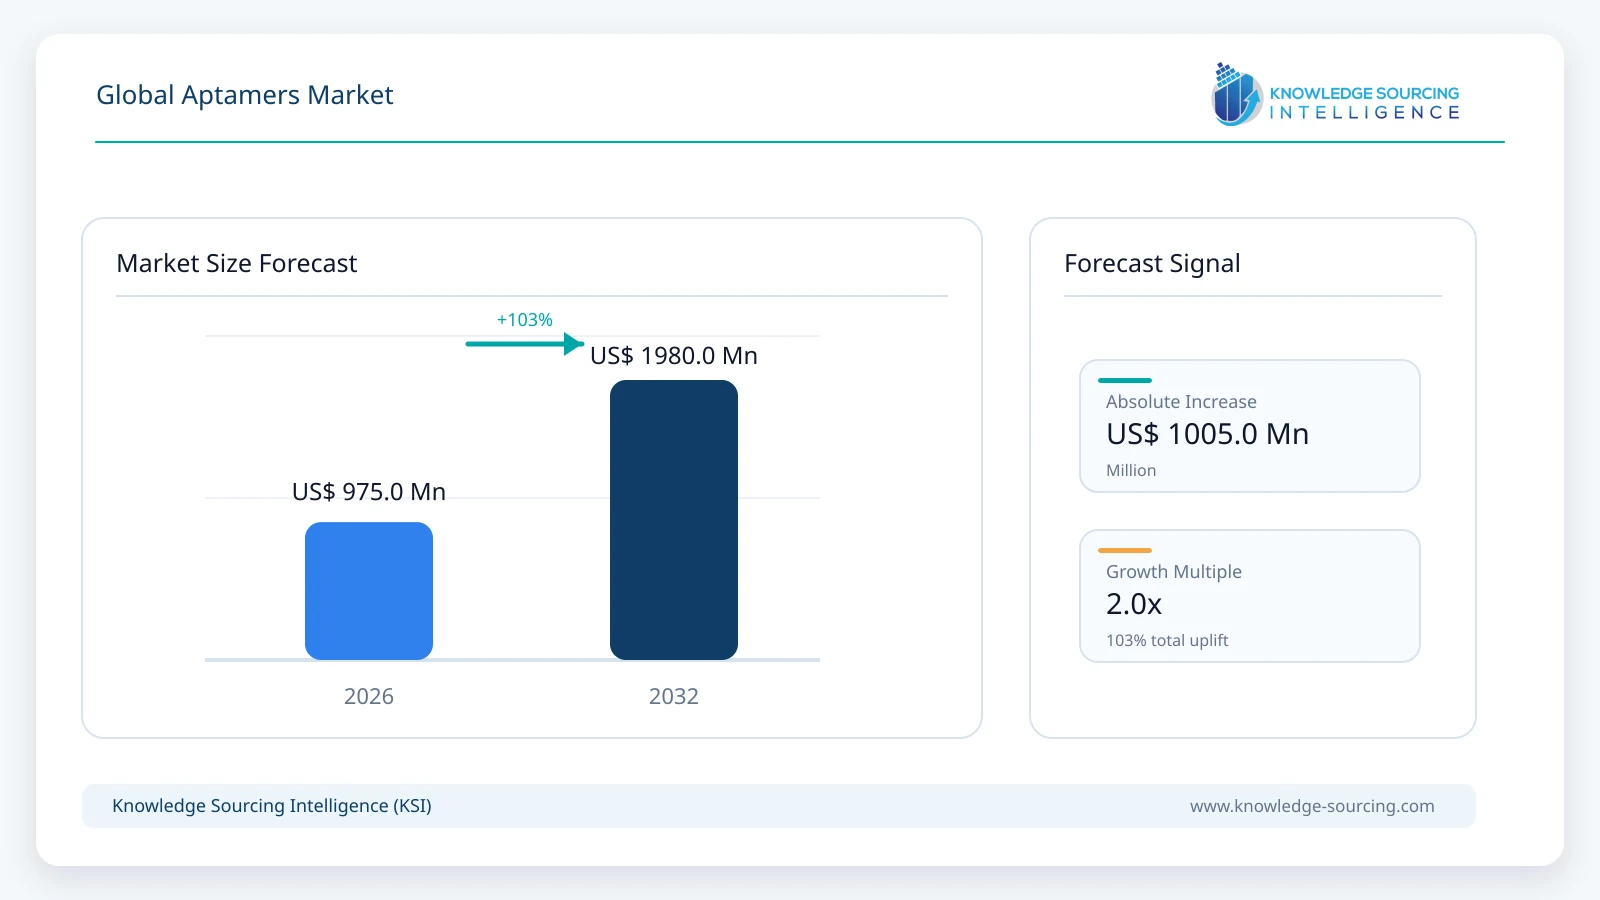
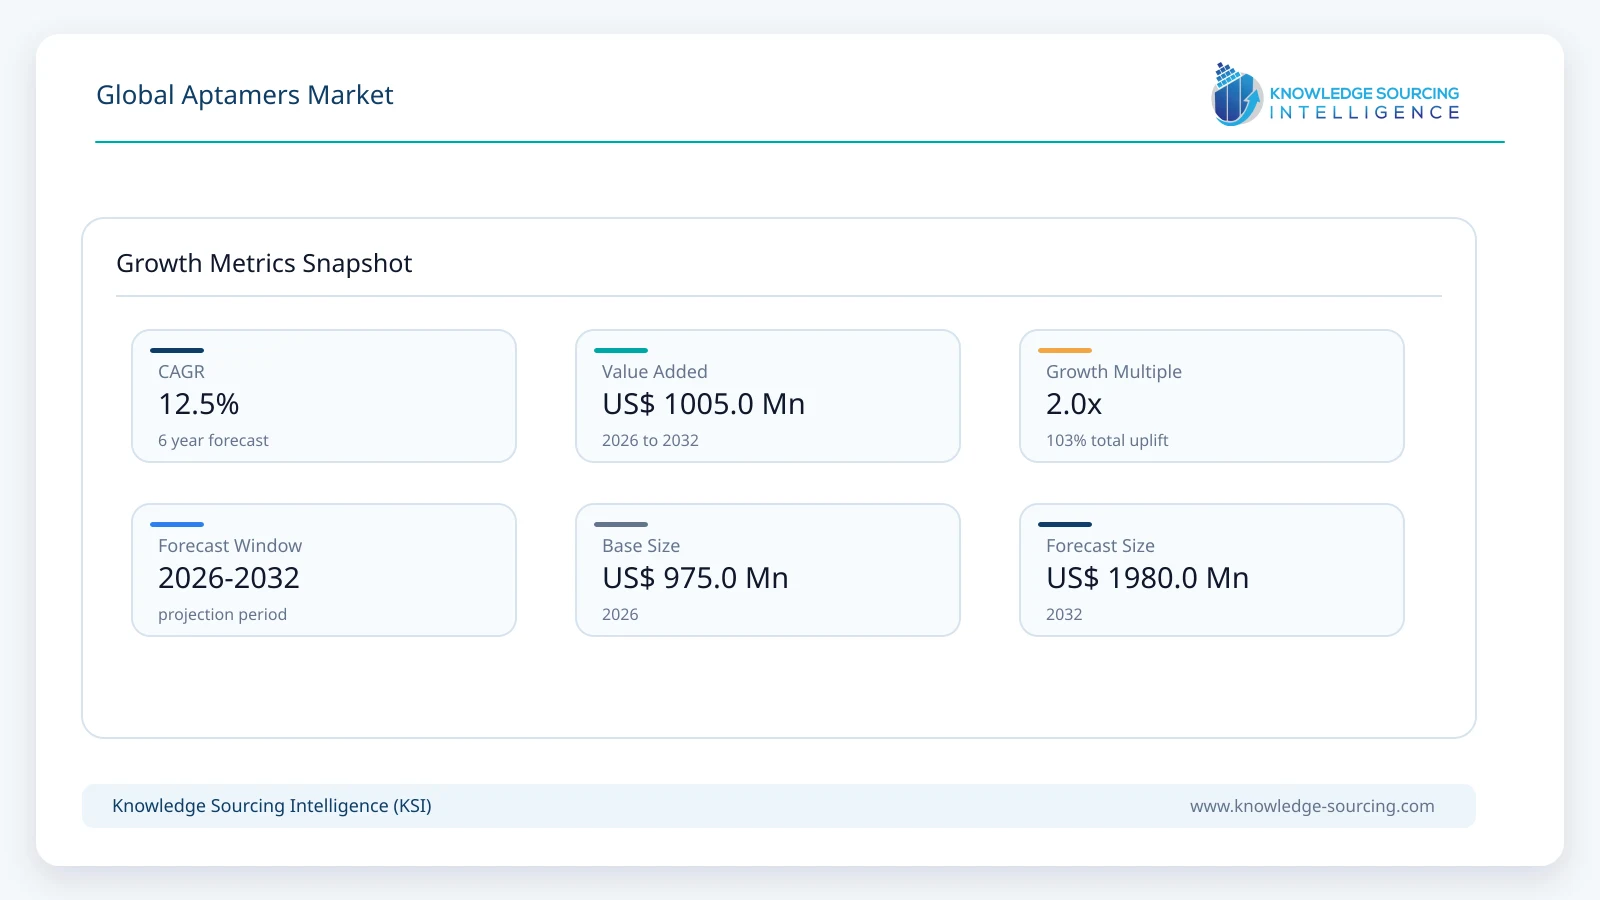
The global aptamers market is estimated at USD 975.0 million in 2026 and is projected to reach USD 1,980.0 million by 2032, representing a compound annual growth rate of 12.5% during the forecast period.
Highlights:
- 1Therapeutic applications represent an estimated US$705.0 million, or 72.3% of the 2026 market, and are projected to reach US$1,375.0 million by 2032, a CAGR of 11.78%.
- 2Astellas reported ¥77.6 billion of fiscal 2025 IZERVAY sales and ¥27.2 billion in the first quarter of fiscal 2026, demonstrating the commercial scale achieved by an approved aptamer medicine.
- 3Illumina completed its acquisition of SomaLogic in January 2026, bringing aptamer-based protein affinity capture into a larger next-generation sequencing ecosystem.
- 4Commercial differentiation is shifting toward reproducible assays, validated clinical use, scalable manufacturing and platform integration rather than binding affinity alone.
- 5North America remains the principal near-term revenue market, while European and Asian suppliers expand aptamer discovery, diagnostics and clinical-development activity.
Demand increasingly reflects two distinct commercial activities: approved aptamer therapeutics and the use of synthetic affinity reagents in high-throughput protein analysis, diagnostics, and drug development. The distinction matters because pharmaceutical net sales, laboratory assay revenues, custom binder discovery fees, and platform licensing are not interchangeable measures of demand. The commercialization of avacincaptad pegol for geographic atrophy has established a substantial recurring pharmaceutical revenue base, while sequencing-linked proteomics is extending aptamer applications beyond individual biomarker assays. Astellas reported ¥77.6 billion in fiscal 2025 IZERVAY sales, followed by ¥27.2 billion during the first quarter of fiscal 2026. These disclosed sales illustrate the magnitude of commercial therapeutic demand, rather than an estimate of every downstream aptamer application. The remaining opportunity is more fragmented, with purchasing decisions determined by assay validation, reproducibility, integration costs, and research budgets.
Aptamers are affinity-binding molecules selected or engineered to recognize particular biological or chemical targets. DNA and RNA aptamers can be chemically synthesized, modified, and incorporated into sensors, assays, therapeutic products, and targeted-delivery platforms. Their commercial value rests on repeatable manufacturing, target specificity, and the ability to bind molecules for which conventional antibody development may be difficult. However, synthetic production does not remove the need for stringent analytical validation. Affinity under laboratory selection conditions may differ from performance in plasma, tissue, complex food samples, or other operating environments. Clinical programs face additional barriers involving stability, biodistribution, safety, and reimbursement, while diagnostic systems require acceptable sensitivity and specificity at viable cost per test. These constraints explain why commercially established drug sales and proteomic testing services currently dominate recognized revenue, even as research publications and emerging applications broaden. The market therefore reflects a progression from discovery services toward scalable, clinically validated and licensed products, not an automatic monetization of every newly reported aptamer sequence.
Market Dynamics
Demand Drivers: Commercial Therapeutics and High-Content Proteomics
The clearest demand driver is the establishment of a regulated therapeutic revenue stream. IZERVAY is indicated for geographic atrophy secondary to age-related macular degeneration and is administered by intravitreal injection, linking revenues to treatment starts, persistence, physician adoption, and payer coverage. Competitive effectiveness, safety monitoring, and retinal-specialist capacity therefore influence its contribution more directly than laboratory aptamer synthesis costs. A second driver is broadening protein measurement in pharmaceutical discovery, translational research, and large population studies. SomaScan-based assays and Illumina’s SomaSeq Discovery workflow use modified aptamer affinity capture to quantify thousands of proteins in a single sample. The ability to integrate proteomic signals with genomic datasets is commercially relevant because it can improve biomarker selection and target validation across drug-development programs. Nevertheless, customers assess complete workflow economics, including reagent consumption, sequencing capacity, software, data quality, and sample throughput. Contracts are consequently more likely to scale when the technology demonstrates repeatability across laboratories and delivers actionable results that justify total processing expenditure.
Market Restraints: Validation, Competition and Clinical Translation
Aptamer innovation faces two different sets of adoption barriers. In research and diagnostics, laboratories must establish binding specificity, reproducibility across reagent lots, resistance to matrix effects, and comparability with existing antibodies or mass-spectrometry methods. Procurement teams are cautious when a custom aptamer requires significant assay redevelopment or creates single-supplier dependence. Therapeutic products face a stricter sequence of chemistry optimization, toxicology, clinical trials, regulatory review, and payer negotiations. Pegaptanib established the original regulatory precedent, but subsequent competition from anti-VEGF therapies demonstrated that early market entry does not guarantee durable share. Newer aptamer delivery systems must also prove reliable pharmacokinetics and meaningful clinical outcomes, not only target engagement. These issues limit the conversion of preclinical candidates into recognized revenue and create a substantial difference between pipeline activity and market sales. For suppliers, the commercial implication is that validated performance data, quality systems, clinical partnerships, and defensible intellectual property can be more valuable than the sheer number of sequences selected.
Market Opportunities: Licensing and Targeted Delivery
Synthetic binder licensing creates a path to recurring revenue without requiring every supplier to operate a full pharmaceutical commercialization organization. Aptamer Group reported approximately £1.5 million in revenue for its fiscal year ended June 2026 and highlighted licensing arrangements involving enzyme-modulating Optimer technology. These collaborations show how a specialized discovery platform can commercialize through upfront fees, reagent supply, and potential royalty streams. Similar commercial logic applies to aptamer-guided delivery, imaging, and selective biomarker capture, although each application requires different performance standards. The transfer of the investigational ApTOLL program to Merck and continued clinical investigation of TME Pharma’s NOX-A12 illustrate the importance of larger partners and clinical development capacity. In industrial testing, portable biosensors and assays for contaminants or food safety could expand addressable demand when they provide sufficient accuracy at acceptable sample-preparation cost. Across these opportunities, downstream adoption is contingent on evidence of analytical or therapeutic utility. The largest economic gains will accrue to platforms that convert qualified binders into repeatable products rather than isolated research results.
Major Segment Analysis
Therapeutic Applications
Therapeutic applications account for an estimated US$705.0 million in 2026, equivalent to 72.3% of global aptamers market revenue. This segment is projected to expand to US$1,375.0 million in 2032, growing at a CAGR of 11.78%. The segment is dominated commercially by approved ophthalmic treatment rather than by the number of compounds in clinical development. Astellas’s fiscal 2025 and early fiscal 2026 sales of IZERVAY provide a direct observable commercial anchor. Its C5-targeting RNA aptamer is used in geographic atrophy, where revenues depend on diagnosed patient access, repeat treatment rates, and competition with other complement inhibitors. Pegaptanib remains historically important as the first FDA-approved aptamer drug but is not a comparable contemporary growth engine. Other programs, including NOX-A12 and ApTOLL, are investigational and do not justify assigning them approved-drug sales. The segment’s commercial trajectory therefore combines continued uptake of existing therapy with a more uncertain pipeline contribution. For developers, clinically meaningful differentiation and partner-funded development remain central to commercialization success.
The economic structure of aptamer therapeutics differs from that of research affinity reagents. Approved treatment revenue is recognized when the drug reaches commercial distribution, while contract development fees and early-stage milestone payments support companies well before clinical launch. Counting the value of a licensing agreement, the developer’s service fees, and subsequent drug sales together without identifying the associated transaction would overstate market activity. Equally, the acquisition price of an aptamer company is not the revenue generated by its products. The ability to chemically modify nucleic-acid structures offers scope to tune stability and target binding, but developers still need to demonstrate safety, delivery, manufacturing consistency, and clinical benefit. Research programs in stroke, oncology, kidney-targeted delivery and ophthalmology may broaden the therapeutic base during the forecast period. Their contribution is likely to be uneven because clinical timelines, capital needs and regulatory outcomes differ substantially. As a result, the established ophthalmic franchise remains the clearest near-term economic benchmark, while additional approvals represent meaningful but less certain upside.
Other Applications and End-User Demand
Outside therapeutics, aptamer-based proteomics represents the strongest established commercial platform category. The SomaScan business generated US$101.3 million in reported 2025 revenue before its acquisition by Illumina, demonstrating a recurring revenue base associated with assay products and services. Integration into sequencing infrastructure may strengthen cross-selling opportunities, but reagent and assay-service revenues must be distinguished from the broader sales of sequencing instruments used for many applications. Diagnostics represent a narrower but strategically significant category, including Aptamer Sciences’ AptoDetect-Lung test in South Korea and other targeted assay formats. Customized selection, synthesis, and licensing support pharmaceutical and biotechnology research customers, while environmental and food testing create additional applications for specialized binders. These activities are grouped rather than presented as competing product-market totals because procurement, regulatory requirements and selling prices vary materially. Research institutes tend to prioritize performance and grant-funded budgets; pharmaceutical companies emphasize validated discovery workflows; and clinical laboratories require standardized, reproducible results. Commercial scale depends on translating a novel binding reagent into a repeatable testing or discovery process.
Regional Analysis
North America
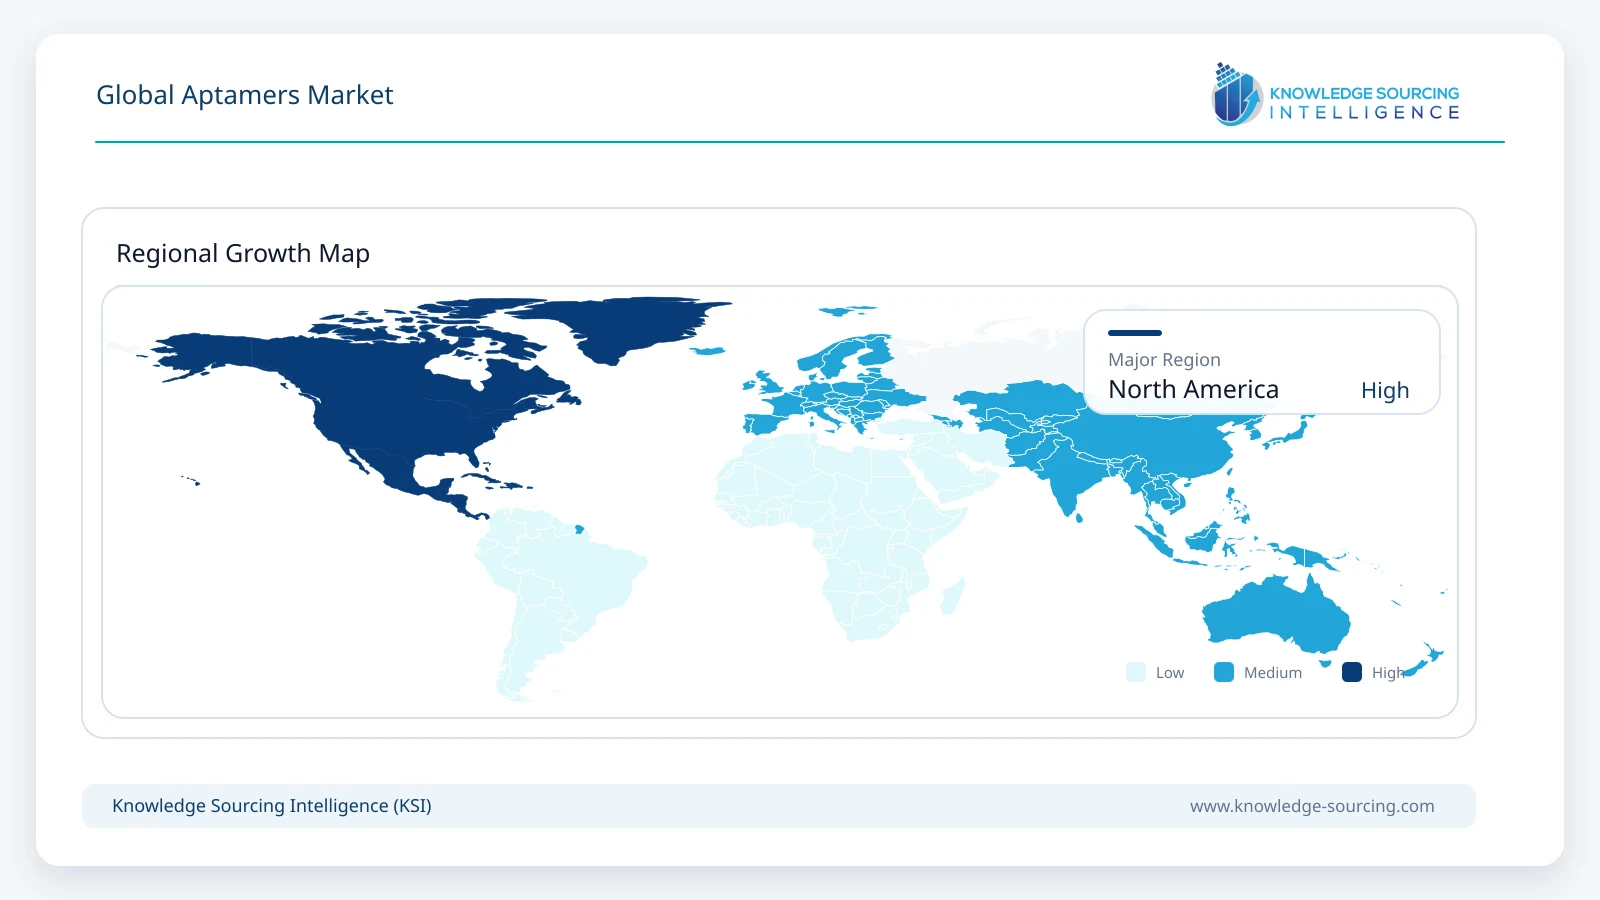
North America leads aptamer-related commercialization through the concentration of biopharmaceutical development, proteomics purchasers, and the United States market for approved ophthalmic therapy. Astellas’s IZERVAY commercial uptake is particularly influential because the drug’s regulatory status and documented sales provide a direct revenue contribution absent in most other regions. The region also hosts Aptagen and Base Pair Biotechnologies, whose custom selection services support research and commercial assay development. Following Illumina’s acquisition of SomaLogic, integration with a broad sequencing installed base could make aptamer-based protein analysis more accessible to laboratories already using genomic workflows. Nevertheless, this transition depends on sample throughput, software compatibility, reproducibility, and competitive pricing against antibody-based assays and mass spectrometry. For North American customers, the key purchasing question is whether aptamer methods deliver clinically relevant or scientifically differentiated information at a lower total workflow cost. Reimbursement and regulatory approval remain decisive for therapeutic growth, while grant allocations and pharmaceutical research budgets shape demand for discovery and proteomic services.
South America
South America is an emerging market for aptamer applications, with most near-term commercial activity concentrated in university research, molecular diagnostics development, and imported life-science reagents. Brazil offers a comparatively substantial biomedical research base, supported by national research institutions, biotechnology programs, and a growing network of clinical laboratories. However, academic adoption of aptamer selection does not imply local manufacture of commercial diagnostic kits or the availability of approved aptamer medicines. Imported affinity reagents face exchange-rate exposure, customs costs and procurement delays, which can make a low-cost synthetic binder comparatively expensive by the time it reaches the laboratory. Suppliers seeking regional growth are therefore more likely to succeed through distributor relationships, technical support, and validated assays requiring limited workflow redesign. Argentina and smaller regional markets may provide specialized research demand, but broad commercial penetration remains sensitive to funding stability. The most feasible near-term opportunities concern targeted diagnostic research, food and environmental testing, and research collaborations rather than assuming rapid uptake of investigational therapeutics.
Europe
Europe combines aptamer discovery expertise with pharmaceutical partnerships and highly regulated diagnostic markets. Aptamer Group in the United Kingdom, Novaptech in France, and TME Pharma’s clinical programs provide distinct examples of fee-for-service development, diagnostic-binder engineering, and therapeutic translation. Their commercial models are not directly comparable: one earns discovery and licensing income, another supplies custom assays, and a third develops clinical assets whose future value is tied to trial outcomes. European pharmaceutical and diagnostic clients increasingly assess whether aptamer platforms offer validated alternatives to established antibody reagents for difficult targets. For clinical diagnostics, product claims, performance evaluation, and regulatory compliance are critical commercial requirements, and differences between research-use-only and clinical assays must be explicit. The region also benefits from cross-border collaborations with hospitals and biotechnology companies, although reimbursement and purchasing decisions remain country-specific. Growth will therefore follow successful technical validation and partner adoption more closely than the publication volume of new selection methods.
Middle East and Africa
The Middle East and Africa market is developing from a smaller commercial base, with demand centered on academic research, diagnostic laboratories, and specialist life-science distributors. High-income Gulf healthcare systems can provide pathways for advanced molecular testing when evidence supports patient benefit and when assays integrate with existing laboratory infrastructure. Research activity in the region also creates opportunities for aptamer reagents in pathogen detection, environmental monitoring, and biotechnology education. However, most complex aptamer selection platforms and approved therapeutics are sourced internationally, making procurement and distribution relationships central to market access. In many African countries, laboratory budget constraints, trained personnel availability, and inconsistent sample logistics limit near-term uptake of sophisticated multiplex proteomic workflows. A useful commercial strategy is therefore to distinguish accessible point-of-care assays from high-throughput discovery platforms rather than treating the region as one homogeneous market. Growth depends on targeted clinical validation, local technical support, and the ability to demonstrate economically meaningful advantages over incumbent diagnostic technologies.
Asia Pacific
Asia Pacific is an important source of aptamer innovation and a growing market for specialized diagnostic and research applications. South Korea’s Aptamer Sciences offers a marketed aptamer-based lung cancer risk-assessment product, providing an example of commercialization beyond US ophthalmic therapeutics. Japan’s TAGCyx applies its Xenoligo platform to artificial-nucleotide aptamer discovery and pharmaceutical collaborations, while research organizations in China, India and other economies continue to investigate targeted delivery and molecular biosensors. Regional demand is shaped by pharmaceutical research investment, domestic diagnostic regulation, access to clinical validation sites, and manufacturing partnerships. Platform developers must establish repeatable performance against local clinical or industrial requirements before broad procurement. Asia Pacific is also a substantial prospective market for proteomics, particularly where academic medical centers and biotechnology companies seek integrated analysis of proteins and genomic datasets. Yet different countries have distinct purchasing and reimbursement systems. Consequently, emerging research capabilities should be evaluated separately from near-term product sales, with particular attention to domestic assay approval and commercialization partnerships.
Competitive Environment
The aptamers market does not have a single homogeneous competitor set. Astellas participates through approved pharmaceutical sales; Illumina participates through acquired aptamer-based proteomic assays and platform integration; Aptamer Group, Aptagen, Base Pair Biotechnologies and Novaptech compete more directly in synthetic-binder discovery and development services. TAGCyx, TME Pharma and aptaTargets or their commercialization partners focus on therapeutic technology and clinical programs, while Aptamer Sciences combines discovery capabilities with a regulated diagnostic product. These distinct positions require separate evaluation of revenues, development stage, customer relationships and intellectual property. Illumina’s acquisition of SomaLogic, completed in January 2026, is strategically important because it brings aptamer affinity chemistry into an established sequencing ecosystem. Conversely, Aptamer Group’s smaller revenue base and licensing arrangements demonstrate the economics of a specialist provider. For customers, vendor choice increasingly hinges on established performance in the intended biological matrix, speed of optimization, regulatory readiness, and supply continuity. Broad market share comparisons based solely on corporate size would obscure these differences.
Recent Developments
July 2026: Aptamer Group reported approximately £1.5 million in expected revenue for fiscal 2026 and confirmed early licensing income from Optimer agreements involving Twist Bioscience and Alphazyme.
April 2026: TME Pharma reported publication of findings from its Phase 1/2 GLORIA expansion study involving NOX-A12 with radiotherapy and bevacizumab in glioblastoma. The program remains investigational.
January 2026: Illumina completed the acquisition of SomaLogic, adding the SomaScan affinity-proteomics platform to its multiomics portfolio and strengthening the route to sequencing-linked protein analysis.
Aptamers Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 975.0 million |
| Total Market Size in 2032 | USD 1,980.0 million |
| Forecast Unit | Million |
| Growth Rate | 12.5% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Type, Application, End-User, Geography |
| Companies |
|
Market Segmentation
By Type
DNA Aptamers
RNA Aptamers
Other Nucleic-Acid Aptamer Constructs
By Application
Therapeutics
Diagnostics and Proteomic Analysis
Research and Discovery Tools
Industrial and Environmental Testing
By End User
Healthcare Providers and Treatment Channels
Pharmaceutical and Biotechnology Companies
Academic and Research Institutes
Clinical and Reference Laboratories
Industrial and Other Users
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
UK
Germany
France
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
Japan
China
India
South Korea
Thailand
Taiwan
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Definition and Revenue Boundary
1.2. Market Segmentation
1.3. Historical and Forecast Period
2. RESEARCH METHODOLOGY
2.1. Primary and Secondary Research
2.2. Market Estimation and Validation
3. EXECUTIVE SUMMARY
3.1. Research Highlights
3.2. Global Market Outlook
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.4.1. Bargaining Power of Suppliers
4.4.2. Bargaining Power of Buyers
4.4.3. Threat of New Entrants
4.4.4. Threat of Substitutes
4.4.5. Competitive Rivalry
4.5. Industry Value Chain Analysis
4.6. Technology and Regulatory Landscape
5. GLOBAL APTAMERS MARKET ANALYSIS, BY TYPE
5.1. Introduction
5.2. DNA Aptamers
5.3. RNA Aptamers
5.4. Other Nucleic-Acid Aptamer Constructs
6. GLOBAL APTAMERS MARKET ANALYSIS, BY APPLICATION
6.1. Introduction
6.2. Therapeutics
6.3. Diagnostics and Proteomic Analysis
6.4. Research and Discovery Tools
6.5. Industrial and Environmental Testing
7. GLOBAL APTAMERS MARKET ANALYSIS, BY END USER
7.1. Introduction
7.2. Healthcare Providers and Treatment Channels
7.3. Pharmaceutical and Biotechnology Companies
7.4. Academic and Research Institutes
7.5. Clinical and Reference Laboratories
7.6. Industrial and Other Users
8. GLOBAL APTAMERS MARKET ANALYSIS, BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. UK
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Israel
8.5.4. Others
8.6. Asia Pacific
8.6.1. Japan
8.6.2. China
8.6.3. India
8.6.4. South Korea
8.6.5. Thailand
8.6.6. Taiwan
8.6.7. Indonesia
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Product Commercialization and Clinical Pipeline
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Astellas Pharma Inc.
10.2. Illumina, Inc. (including SomaLogic)
10.3. Aptamer Group plc
10.4. Aptagen, LLC
10.5. Base Pair Biotechnologies, Inc.
10.6. Aptamer Sciences Inc.
10.7. Novaptech
10.8. TAGCyx Biotechnologies, Inc.
10.9. TME Pharma N.V. (formerly NOXXON Pharma)
10.10. aptaTargets S.L.
10.11. Merck KGaA
10.12. Twist Bioscience Corporation
10.13. Alphazyme (Maravai LifeSciences)
11. RESEARCH METHODOLOGY APPENDIX
12. LIST OF FIGURES
13. LIST OF TABLES
Navigate
Trusted by the world's leading organizations











