
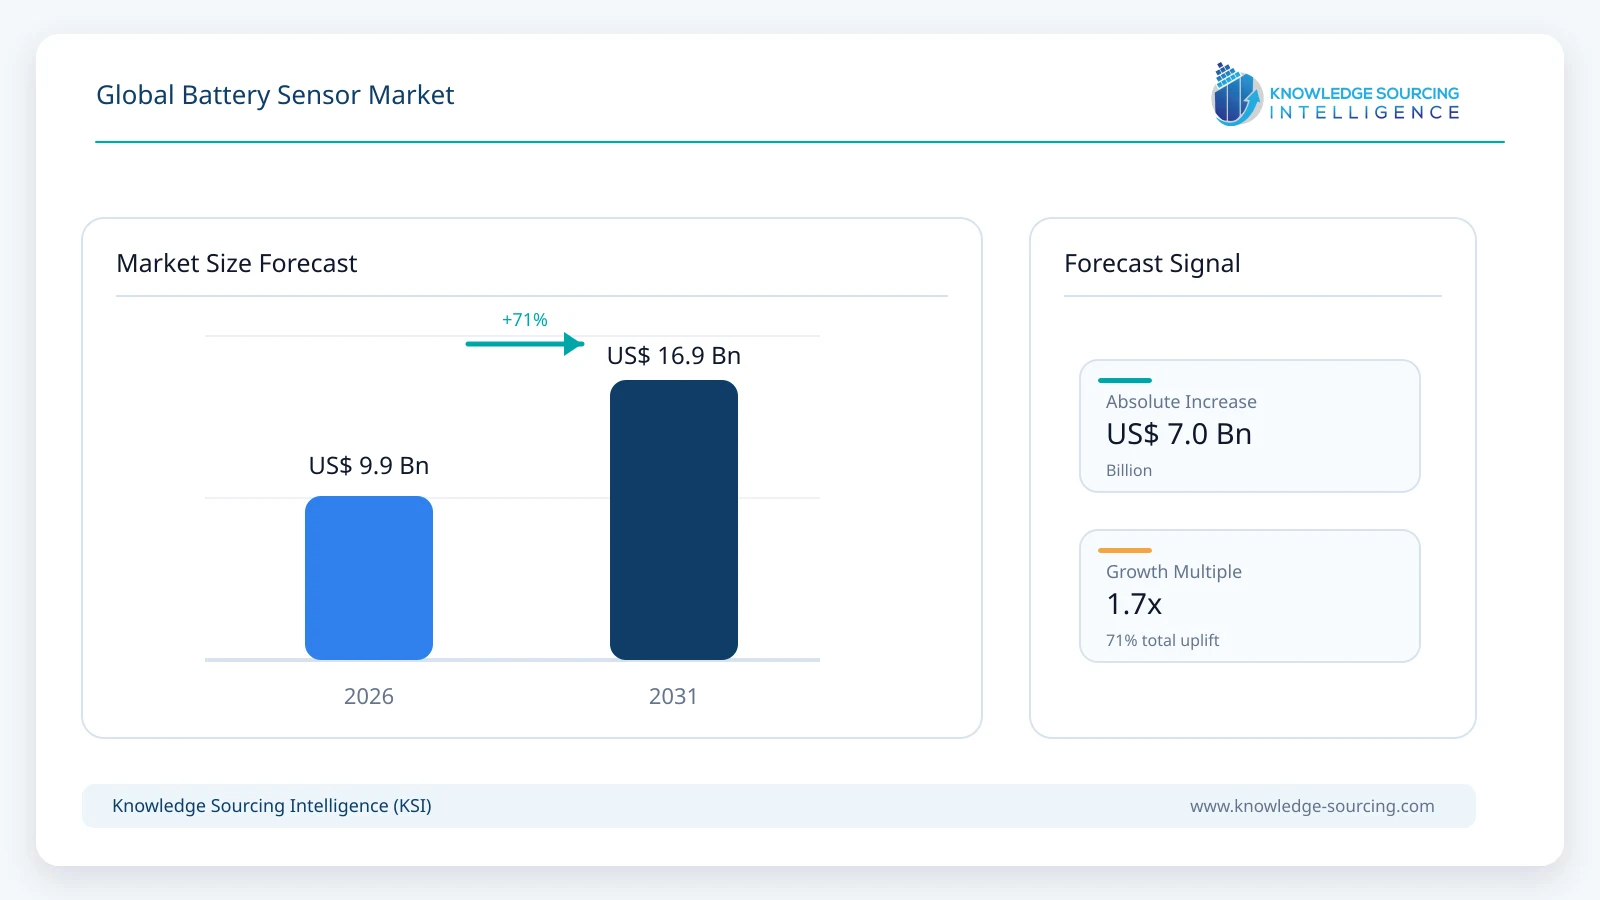
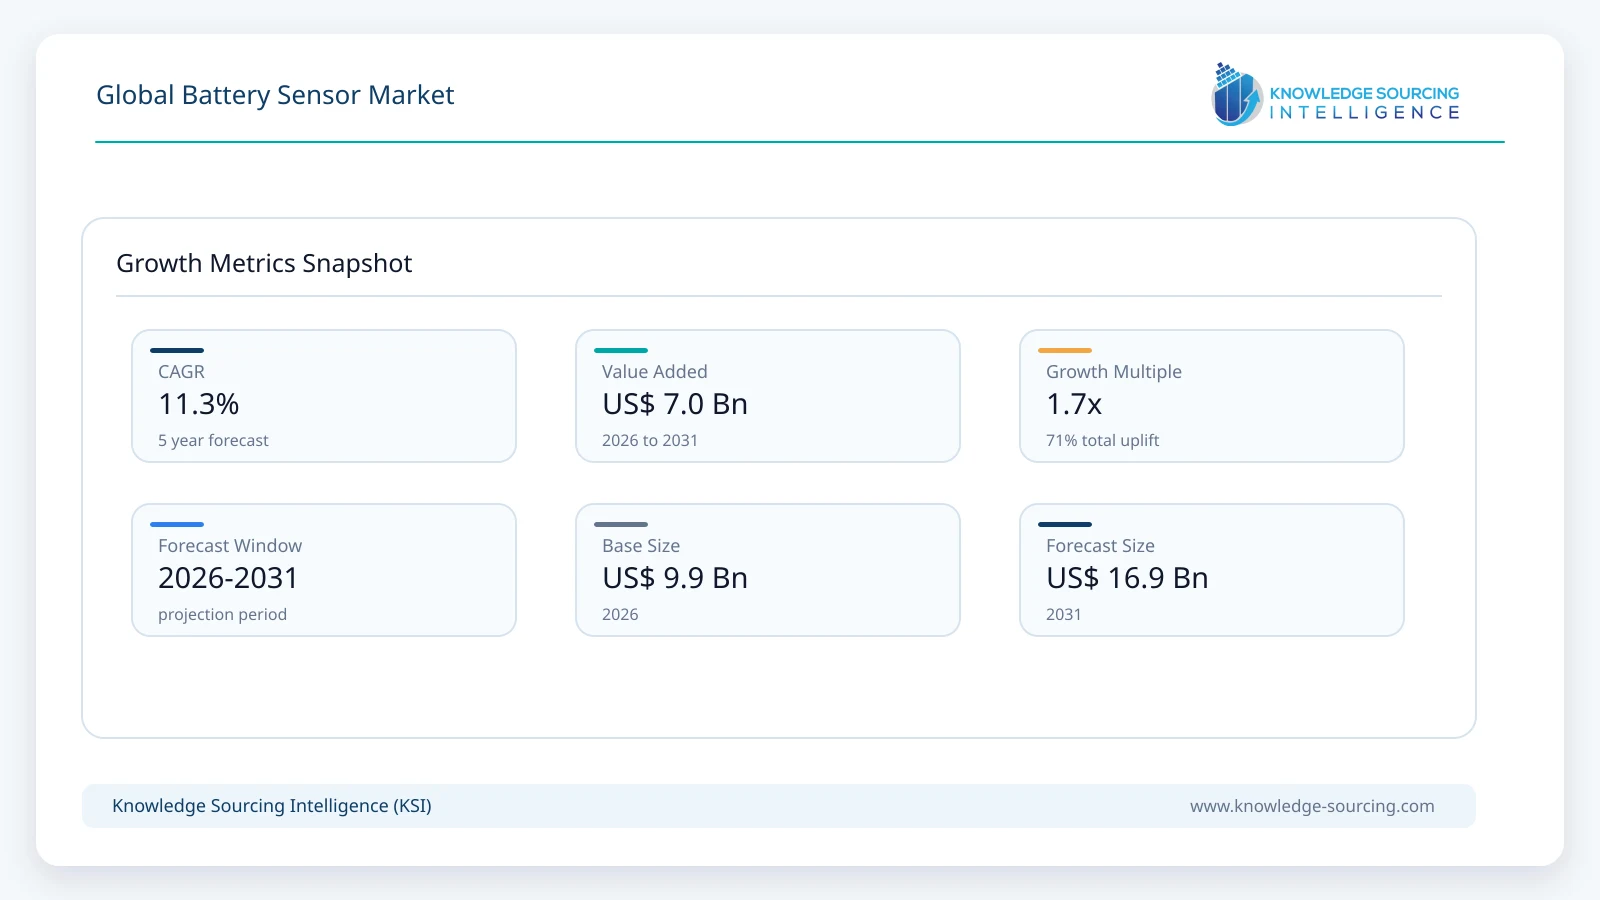
The Global Battery Sensor Market is forecast to grow at a CAGR of 11.3%, reaching USD 16.90 billion in 2031 from USD 9.91 billion in 2026.
Highlights:
- 1Battery sensors are becoming integral to battery management, predictive maintenance, and functional safety across electrified systems.
- 2Automotive electrification continues to account for the largest share of commercial demand for battery sensing solutions.
- 3High-voltage battery packs require increasingly accurate current, voltage, and temperature monitoring to improve battery life.
- 4Battery sensor suppliers are expanding software capabilities alongside sensing hardware to improve state estimation accuracy.
- 5Asia Pacific remains the manufacturing center for battery sensors, while North America and Europe are driven by electrification policies and advanced vehicle production.
Market Overview
Modern sensors continuously measure voltage, current, and temperature while estimating state of charge (SOC), state of health (SOH), and state of function (SOF). These capabilities have become increasingly important as battery systems grow larger, operate at higher voltages, and require longer operating lives with improved safety.
Commercial demand is strongest where battery reliability directly affects operational continuity or safety. Automotive manufacturers increasingly specify integrated battery sensing solutions to improve energy management, support start-stop systems, optimize regenerative braking, and extend battery service life. Similar purchasing priorities are emerging across utility-scale energy storage, telecom backup power, and industrial automation, where predictive maintenance and remote diagnostics reduce operating costs and unplanned downtime. Official product disclosures from battery sensor manufacturers increasingly emphasize embedded diagnostics, programmable algorithms, and communication compatibility rather than measurement accuracy alone, reflecting changing customer procurement priorities.
Competition extends beyond sensor hardware. Suppliers increasingly differentiate through software algorithms, communication interfaces, functional safety certification, calibration capability, and compatibility with battery management platforms. Vehicle manufacturers and battery pack integrators are also placing greater importance on long-term software support, cybersecurity, and system interoperability as battery architectures migrate toward centralized electronic control systems.
Growing deployment of battery energy storage systems and electrified transportation continues to broaden the addressable market. However, purchasing decisions increasingly depend on total lifecycle performance rather than initial component cost. Buyers evaluate sensing accuracy, diagnostic capability, long-term stability, functional safety compliance, communication reliability, and integration effort before supplier selection.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Bosch Mobility battery sensor capability | Measures current, voltage and temperature while calculating SOC, SOH and SOF | Demonstrates the shift from basic sensing toward intelligent battery diagnostics. |
Communication interface | LIN 2.2 with programmable output | Standardized communication reduces integration complexity for automotive OEMs. |
Operating temperature | -40°C to +115°C | Wide operating range supports deployment across demanding automotive and industrial environments. |
Functional safety | ASIL-B capable battery sensing | Safety certification has become an important purchasing criterion for electrified vehicle platforms. |
Bosch R&D investment | ~€7.9 billion (2025) | Sustained investment supports development of sensing technologies used in electrification and mobility solutions. |
Market Drivers
Expansion of electrified vehicle platforms requiring continuous battery diagnostics. Modern battery-electric, hybrid, and plug-in hybrid vehicles require continuous monitoring of battery operating conditions to maximize usable capacity while maintaining safety. Battery sensors now provide far more than voltage measurement by supplying real-time information on current flow, battery temperature, charge status, and battery ageing. Bosch identifies electronic battery sensors as a core component supporting energy management, predictive maintenance, automated driving functions, and fuel-saving technologies. Vehicle manufacturers increasingly specify intelligent sensing because battery replacement costs make lifecycle optimization economically attractive.
Higher battery system complexity is increasing demand for intelligent sensing architectures. Battery packs are becoming larger, operate at higher voltages, and contain more monitoring points than previous generations. These changes require improved measurement precision together with reliable communication between sensing devices and battery management controllers. Communication protocols such as CAN and LIN remain widely deployed because they simplify integration with vehicle electronic architectures while supporting diagnostic functions. Suppliers including NXP Semiconductors, Infineon Technologies, Melexis, Allegro MicroSystems, Continental AG, and Robert Bosch GmbH continue expanding semiconductor and sensing portfolios that support increasingly sophisticated battery management systems for automotive and industrial applications.
Predictive maintenance is becoming a purchasing requirement across industrial battery applications. Battery failures can interrupt telecommunications networks, industrial automation systems, marine operations, and stationary energy storage facilities. End users therefore seek continuous battery health monitoring instead of periodic inspection. Modern battery sensors estimate remaining battery life and detect abnormal operating conditions before failure occurs, allowing maintenance schedules to become condition-based rather than calendar-based. This operating model reduces service costs while improving system availability, making intelligent battery sensing commercially attractive beyond passenger vehicles. Research activity also indicates increasing emphasis on combining multiple sensing techniques with software algorithms to improve battery state estimation accuracy.
Market Restraints and Challenges
Functional safety qualification and long automotive validation cycles increase commercialization costs. Battery sensors used in electrified vehicles must operate reliably throughout the vehicle's service life under demanding thermal, electrical, and vibration conditions. Automotive OEMs require compliance with standards such as ISO 26262, extensive environmental validation, electromagnetic compatibility testing, and software verification before production approval. These qualification requirements lengthen product development cycles and raise engineering costs, particularly for suppliers introducing new sensing technologies. Companies including Infineon Technologies, NXP Semiconductors, and Robert Bosch GmbH continue investing in functional safety capabilities and automotive-grade semiconductor development to meet these customer requirements. While these investments strengthen long-term competitiveness, they also increase barriers to market entry and delay revenue generation from new product platforms.
Semiconductor supply-chain risks and raw material dependencies continue to affect production planning. Battery sensors rely on mixed-signal integrated circuits, microcontrollers, magnetic sensing elements, and communication components that remain exposed to semiconductor supply fluctuations and geopolitical trade risks. Although component availability has improved compared with the peak shortages experienced during 2021 and 2022, several semiconductor manufacturers continue to identify supply-chain resilience, manufacturing capacity, and geopolitical uncertainty as operational priorities in their annual reports. Automotive customers increasingly expect multi-source supply strategies and regional manufacturing capability, requiring suppliers to diversify production networks and maintain higher inventory levels. These measures improve supply security but increase operating costs and place additional pressure on pricing, particularly in cost-sensitive vehicle programs.
Higher software complexity raises integration costs for battery management systems. Modern battery sensors no longer function as standalone measurement devices. They must communicate with battery management systems, vehicle domain controllers, cloud-based diagnostics platforms, and predictive maintenance software while maintaining cybersecurity and functional safety compliance. Integrating sensing hardware with proprietary battery management algorithms often requires substantial engineering resources and extended validation. Industrial and energy storage customers also seek compatibility with existing control systems rather than replacing complete battery management architectures. As a result, suppliers increasingly compete on software support, firmware updates, and integration services in addition to hardware performance, expanding development costs and extending implementation timelines for both manufacturers and end users.
Major Segment Analysis
Automotive
The automotive segment represents the most commercially important application for battery sensors because electrified vehicles require continuous monitoring of battery performance throughout their operating life. Passenger cars, commercial vehicles, and hybrid platforms increasingly depend on battery sensors to measure current, voltage, and temperature while supporting calculations for state of charge, state of health, and remaining battery life. These functions influence vehicle range estimation, charging efficiency, thermal management, and overall battery durability, making sensor reliability a critical purchasing criterion for vehicle manufacturers.
Procurement decisions within this segment extend beyond measurement accuracy. Automotive OEMs increasingly evaluate functional safety compliance, communication compatibility through CAN and LIN protocols, software support, diagnostic capability, cybersecurity, and long-term supply assurance before approving suppliers. Companies such as Robert Bosch GmbH, Continental AG, NXP Semiconductors, Infineon Technologies AG, Melexis, Allegro MicroSystems, and Hella GmbH & Co. KGaA (Forvia SE) continue expanding sensing and semiconductor portfolios designed for next-generation battery management systems. Although industrial and stationary energy storage applications are increasing their use of intelligent battery monitoring, automotive programs continue to establish the highest qualification standards and remain the primary source of technology development and supplier investment across the battery sensor market.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | EV manufacturing expansion, battery production investments, grid-scale energy storage | Higher production costs and supply-chain localization requirements |
Europe | Vehicle emission regulations, battery safety standards, regional battery manufacturing | Regulatory compliance costs and competitive pricing pressure |
Asia Pacific | Large-scale battery manufacturing, electronics production, expanding EV supply chain | Intense supplier competition and pricing pressure |
Middle East and Africa | Grid modernization, telecom infrastructure, renewable energy storage | Limited domestic manufacturing and import dependence |
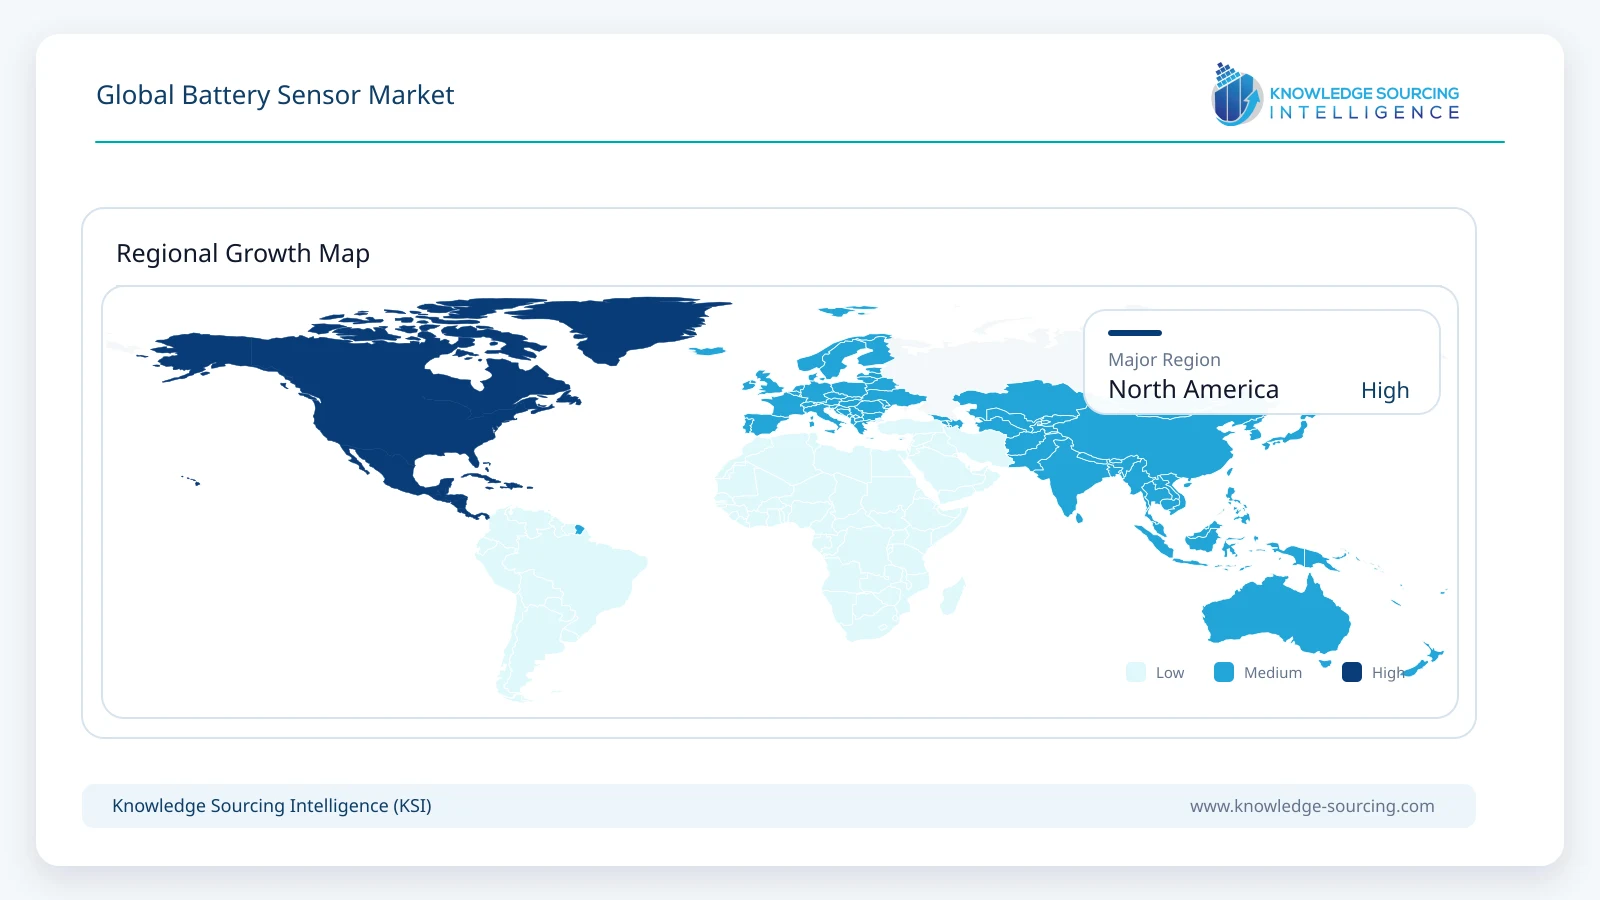
North America continues to benefit from expanding domestic battery manufacturing, electric vehicle assembly, and grid-scale energy storage deployment. Government incentives supporting battery production and clean transportation have encouraged investment across the United States and Canada, while automotive manufacturers increasingly seek regional supply chains for critical electronic components. These developments strengthen demand for battery sensors capable of supporting high-voltage battery systems, predictive diagnostics, and functional safety. Buyers in this region place considerable emphasis on software integration, cybersecurity, and long-term supplier support alongside component performance.
European demand remains closely linked to vehicle electrification policies, battery sustainability requirements, and strict functional safety standards. The European Union's Battery Regulation, together with increasingly stringent vehicle emission targets, continues to encourage battery manufacturers and automotive OEMs to improve battery efficiency, durability, and lifecycle monitoring. These conditions support adoption of intelligent battery sensing technologies that provide accurate health estimation and support predictive maintenance. Germany, France, and the United Kingdom remain important centers for automotive engineering, semiconductor development, and battery system integration, while suppliers continue expanding research partnerships and software capabilities to meet evolving customer requirements.
Asia Pacific remains the global manufacturing center for batteries, electronics, and electric vehicles, making it the largest production base for battery sensing components. China, Japan, South Korea, and Taiwan host extensive semiconductor fabrication capacity, battery manufacturing facilities, and automotive supply chains that support large-scale production of sensing solutions. India and Southeast Asian economies are also increasing investment in electric mobility and battery manufacturing through industrial policies and localized production initiatives. High production volumes strengthen economies of scale but also intensify price competition, encouraging suppliers to differentiate through software capability, sensing precision, and integrated battery management solutions.
The Middle East and Africa represent an emerging market where battery sensors are increasingly adopted in renewable energy storage, telecommunications backup systems, marine applications, and critical infrastructure projects. Several countries are investing in utility-scale solar installations supported by battery storage, creating additional demand for battery monitoring technologies that improve operational reliability and maintenance planning. However, limited local manufacturing capacity and continued dependence on imported electronic components constrain supply chain development and increase procurement costs for system integrators.
Competitive Landscape
Competition in the global battery sensor market is technology-driven and closely linked to the broader automotive and power electronics supply chain. Established automotive suppliers and semiconductor manufacturers compete by combining sensing hardware with software algorithms, communication interfaces, and functional safety capabilities rather than through component pricing alone. Robert Bosch GmbH, Continental AG, Hella GmbH & Co. KGaA (Forvia SE), NXP Semiconductors, Infineon Technologies AG, Allegro MicroSystems, Melexis, and Furukawa Electric Co., Ltd. continue expanding products that support battery management systems for electrified vehicles and industrial battery applications.
Product qualification remains a major competitive barrier because automotive customers require long validation cycles, compliance with ISO 26262 functional safety requirements, and proven field reliability before approving new suppliers. Semiconductor companies increasingly differentiate through mixed-signal integration, Hall-effect sensing technologies, low-power designs, and support for CAN and LIN communication protocols. Automotive system suppliers complement these capabilities with battery management software, calibration expertise, and integration services. Competition is therefore shaped by engineering capability, manufacturing quality, long-term supply assurance, and the ability to support evolving battery architectures rather than by component cost alone.
Recent Developments
July 2026 – Nordic Semiconductor released Fuel Gauge v2.0 Beta for battery-powered devices. The updated battery-monitoring software introduced adaptive state-of-health algorithms that improve battery lifetime estimation and degradation management, enhancing battery sensing accuracy in connected consumer electronics.
July 2026 – Infineon Technologies completed the acquisition of ams OSRAM’s non-optical analog/mixed-signal sensor portfolio. The transaction strengthened Infineon’s automotive sensor capabilities, including technologies supporting battery management and battery sensing, while adding approximately 230 employees and complementary sensor intellectual property.
March 2026 – Infineon Technologies unveiled the TLE4978 hybrid Hall-coil current sensor. The new sensor detects lithium plating by measuring high-frequency current harmonics, enabling more precise battery diagnostics, improved battery management systems, and enhanced electric-vehicle battery safety.
January 2026 – FORVIA HELLA announced its next-generation Intelligent Battery Sensor for mass production in China. The localized solution provides real-time battery monitoring, predictive maintenance, and improved battery performance, safety, and lifecycle management for electric vehicles.
Regulatory and Policy Environment
Battery sensor demand is increasingly influenced by regulations governing battery safety, vehicle emissions, product traceability, and battery lifecycle management rather than by sensor-specific legislation. The European Union Battery Regulation (EU 2023/1542) establishes requirements covering battery sustainability, carbon footprint reporting, recycled material content, due diligence, and battery information throughout the product lifecycle. These requirements encourage manufacturers to deploy more sophisticated battery monitoring systems that support lifecycle management and performance assessment.
Vehicle safety standards also continue to influence battery sensor specifications. Functional safety requirements defined under ISO 26262 have become standard practice for automotive electronic systems, including battery management architectures. Compliance requires highly reliable sensing, diagnostics, fault detection, and communication performance throughout the operating life of the vehicle.
In North America, government support for electric vehicle manufacturing, domestic battery production, and grid modernization continues to stimulate investment across the battery value chain. Similar industrial policies in China, Japan, South Korea, and India encourage localized battery manufacturing, semiconductor production, and electrified transportation, indirectly supporting long-term demand for battery sensing technologies.
As battery systems become larger and more complex, regulatory attention is shifting toward battery durability, transport safety, recycling, cybersecurity, and lifecycle traceability. Suppliers capable of aligning sensing technologies with evolving regulatory requirements are expected to strengthen their position in automotive and industrial procurement programs.
Outlook and Strategic Implications
Commercial demand for battery sensors is expected to broaden as battery systems become more intelligent, connected, and software-defined across transportation, energy storage, telecommunications, and industrial applications. Higher-voltage battery architectures, longer battery warranties, and increased emphasis on predictive maintenance will continue raising customer expectations for sensing accuracy, reliability, and diagnostic capability. Battery sensors are increasingly viewed as strategic components that influence battery utilization, operational safety, maintenance planning, and lifecycle cost rather than as standalone electronic devices.
Several structural trends are likely to influence supplier strategies during the 2026-2031 forecast period:
Increasing adoption of high-voltage battery systems requiring more precise current, voltage, and temperature monitoring.
Greater use of software-based battery analytics to improve state-of-charge and state-of-health estimation.
Expansion of battery energy storage systems (BESS) for renewable energy integration, creating additional demand beyond automotive applications.
Continued localization of semiconductor and battery supply chains to improve resilience against geopolitical and logistics risks.
Higher customer emphasis on functional safety, cybersecurity, interoperability, and remote diagnostics when selecting battery management solutions.
Suppliers that combine precision sensing hardware with embedded software, automotive-grade functional safety, and scalable communication capabilities are likely to remain well positioned as battery management systems evolve. Investments in semiconductor manufacturing, application-specific integrated circuits, calibration expertise, and system-level integration will continue shaping competitive differentiation. At the same time, buyers are expected to evaluate suppliers on lifecycle performance, engineering support, regulatory compliance, and supply reliability as carefully as they assess component specifications, reinforcing the transition of battery sensors from supporting electronics to essential elements of modern battery management systems.
Global Battery Sensor Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 9.9 billion |
| Total Market Size in 2031 | USD 16.9 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 11.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Communication Protocol, Voltage Type, Industry Vertical, Geography |
| Companies |
|
Market Segmentation
By Communication Protocol
CAN
LIN
Other Protocols (FlexRay, Ethernet, UART, SPI, etc.)
By Voltage Type
12V
24V
48V
High Voltage (>48V)
By Industry Vertical
Automotive
Energy and Power
Industrial
Telecommunications
Marine
Aerospace and Defense
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
UAE
Saudi Arabia
Israel
Others
Asia Pacific
China
India
South Korea
Taiwan
Thailand
Indonesia
Japan
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to the stakeholder
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Processes
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. CXO Perspective
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. GLOBAL BATTERY SENSOR MARKET, BY COMMUNICATION PROTOCOL
5.1. Introduction
5.2. CAN
5.3. LIN
5.4. Other Protocols (FlexRay, Ethernet, UART, SPI, etc.)
6. GLOBAL BATTERY SENSOR MARKET, BY VOLTAGE TYPE
6.1. Introduction
6.2. 12V
6.3. 24V
6.4. 48V
6.5. High Voltage (>48V)
7. GLOBAL BATTERY SENSOR MARKET, BY INDUSTRY VERTICAL
7.1. Introduction
7.2. Automotive
7.3. Energy and Power
7.4. Industrial
7.5. Telecommunications
7.6. Marine
7.7. Aerospace and Defense
7.8. Others
8. GLOBAL BATTERY SENSOR MARKET, BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Communication Protocol
8.2.2. By Voltage Type
8.2.3. By Industry Vertical
8.2.4. By Country
8.2.4.1. USA
8.2.4.1.1. Market Trends and Opportunities
8.2.4.1.2. Growth Prospects
8.2.4.2. Canada
8.2.4.2.1. Market Trends and Opportunities
8.2.4.2.2. Growth Prospects
8.2.4.3. Mexico
8.2.4.3.1. Market Trends and Opportunities
8.2.4.3.2. Growth Prospects
8.3. South America
8.3.1. By Communication Protocol
8.3.2. By Voltage Type
8.3.3. By Industry Vertical
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.1.1. Market Trends and Opportunities
8.3.4.1.2. Growth Prospects
8.3.4.2. Others
8.3.4.2.1. Market Trends and Opportunities
8.3.4.2.2. Growth Prospects
8.4. Europe
8.4.1. By Communication Protocol
8.4.2. By Voltage Type
8.4.3. By Industry Vertical
8.4.4. By Country
8.4.4.1. Germany
8.4.4.1.1. Market Trends and Opportunities
8.4.4.1.2. Growth Prospects
8.4.4.2. France
8.4.4.2.1. Market Trends and Opportunities
8.4.4.2.2. Growth Prospects
8.4.4.3. United Kingdom
8.4.4.3.1. Market Trends and Opportunities
8.4.4.3.2. Growth Prospects
8.4.4.4. Spain
8.4.4.4.1. Market Trends and Opportunities
8.4.4.4.2. Growth Prospects
8.4.4.5. Others
8.4.4.5.1. Market Trends and Opportunities
8.4.4.5.2. Growth Prospects
8.5. Middle East and Africa
8.5.1. By Communication Protocol
8.5.2. By Voltage Type
8.5.3. By Industry Vertical
8.5.4. By Country
8.5.4.1. UAE
8.5.4.1.1. Market Trends and Opportunities
8.5.4.1.2. Growth Prospects
8.5.4.2. Saudi Arabia
8.5.4.2.1. Market Trends and Opportunities
8.5.4.2.2. Growth Prospects
8.5.4.3. Israel
8.5.4.3.1. Market Trends and Opportunities
8.5.4.3.2. Growth Prospects
8.5.4.4. Others
8.5.4.4.1. Market Trends and Opportunities
8.5.4.4.2. Growth Prospects
8.6. Asia Pacific
8.6.1. By Communication Protocol
8.6.2. By Voltage Type
8.6.3. By Industry Vertical
8.6.4. By Country
8.6.4.1. China
8.6.4.1.1. Market Trends and Opportunities
8.6.4.1.2. Growth Prospects
8.6.4.2. India
8.6.4.2.1. Market Trends and Opportunities
8.6.4.2.2. Growth Prospects
8.6.4.3. South Korea
8.6.4.3.1. Market Trends and Opportunities
8.6.4.3.2. Growth Prospects
8.6.4.4. Taiwan
8.6.4.4.1. Market Trends and Opportunities
8.6.4.4.2. Growth Prospects
8.6.4.5. Thailand
8.6.4.5.1. Market Trends and Opportunities
8.6.4.5.2. Growth Prospects
8.6.4.6. Indonesia
8.6.4.6.1. Market Trends and Opportunities
8.6.4.6.2. Growth Prospects
8.6.4.7. Japan
8.6.4.7.1. Market Trends and Opportunities
8.6.4.7.2. Growth Prospects
8.6.4.8. Others
8.6.4.8.1. Market Trends and Opportunities
8.6.4.8.2. Growth Prospects
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. FURUKAWA ELECTRIC CO., LTD
10.2. NXP Semiconductors
10.3. Robert Bosch GmbH
10.4. Hella GmbH & Co. KGaA (Forvia SE)
10.5. Continental AG
10.6. Allegro MicroSystems
10.7. Melexis
10.8. Infineon Technologies AG
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











