
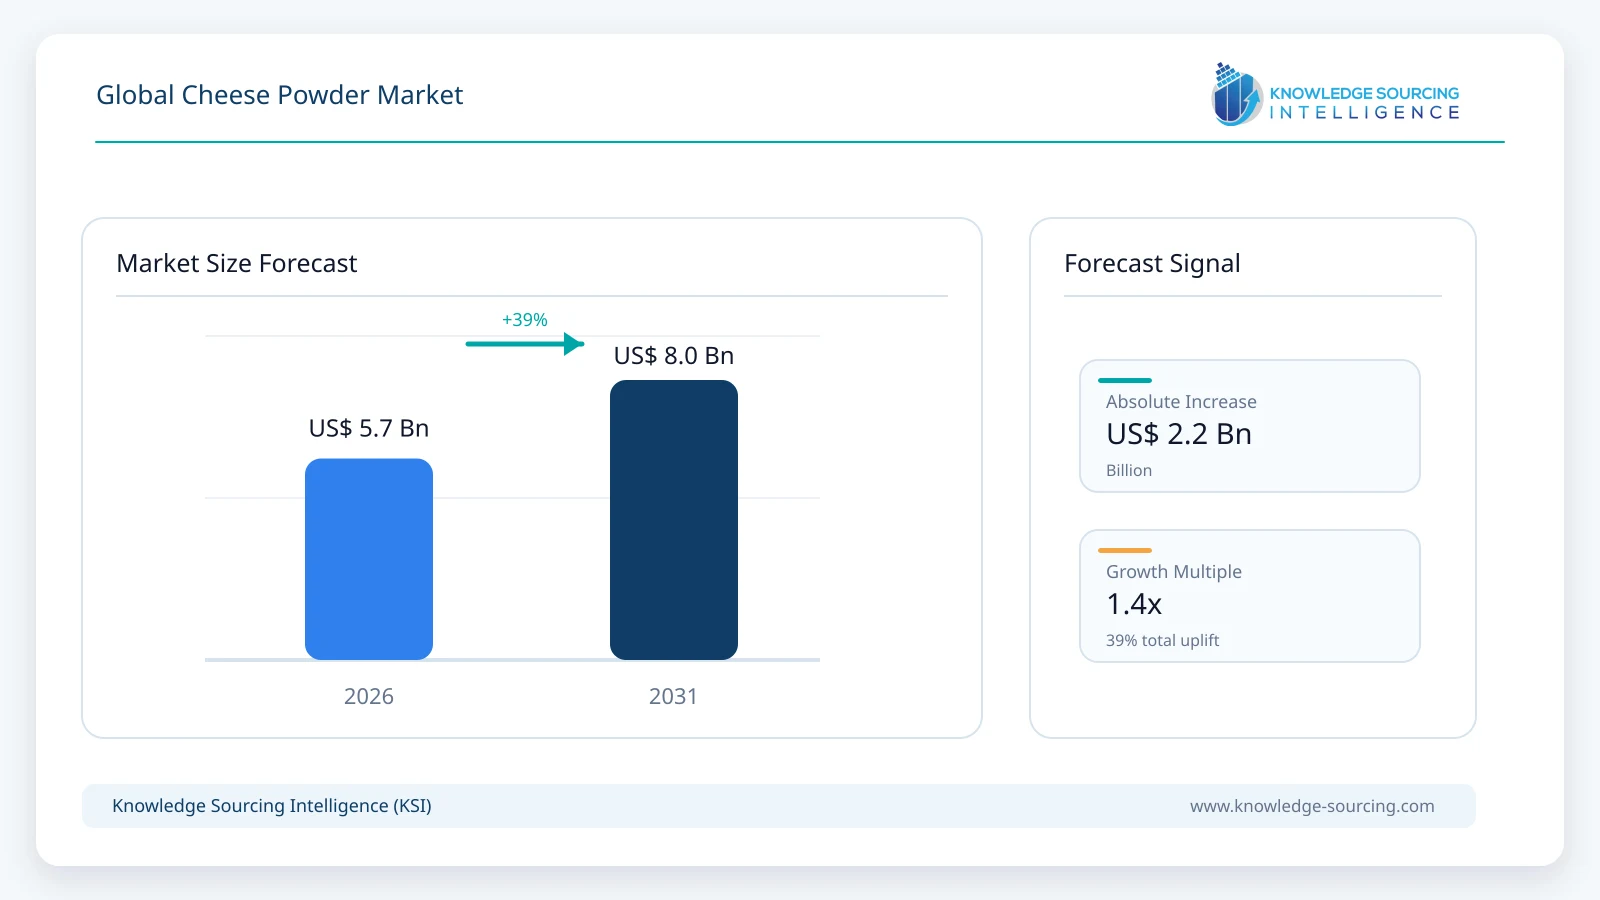
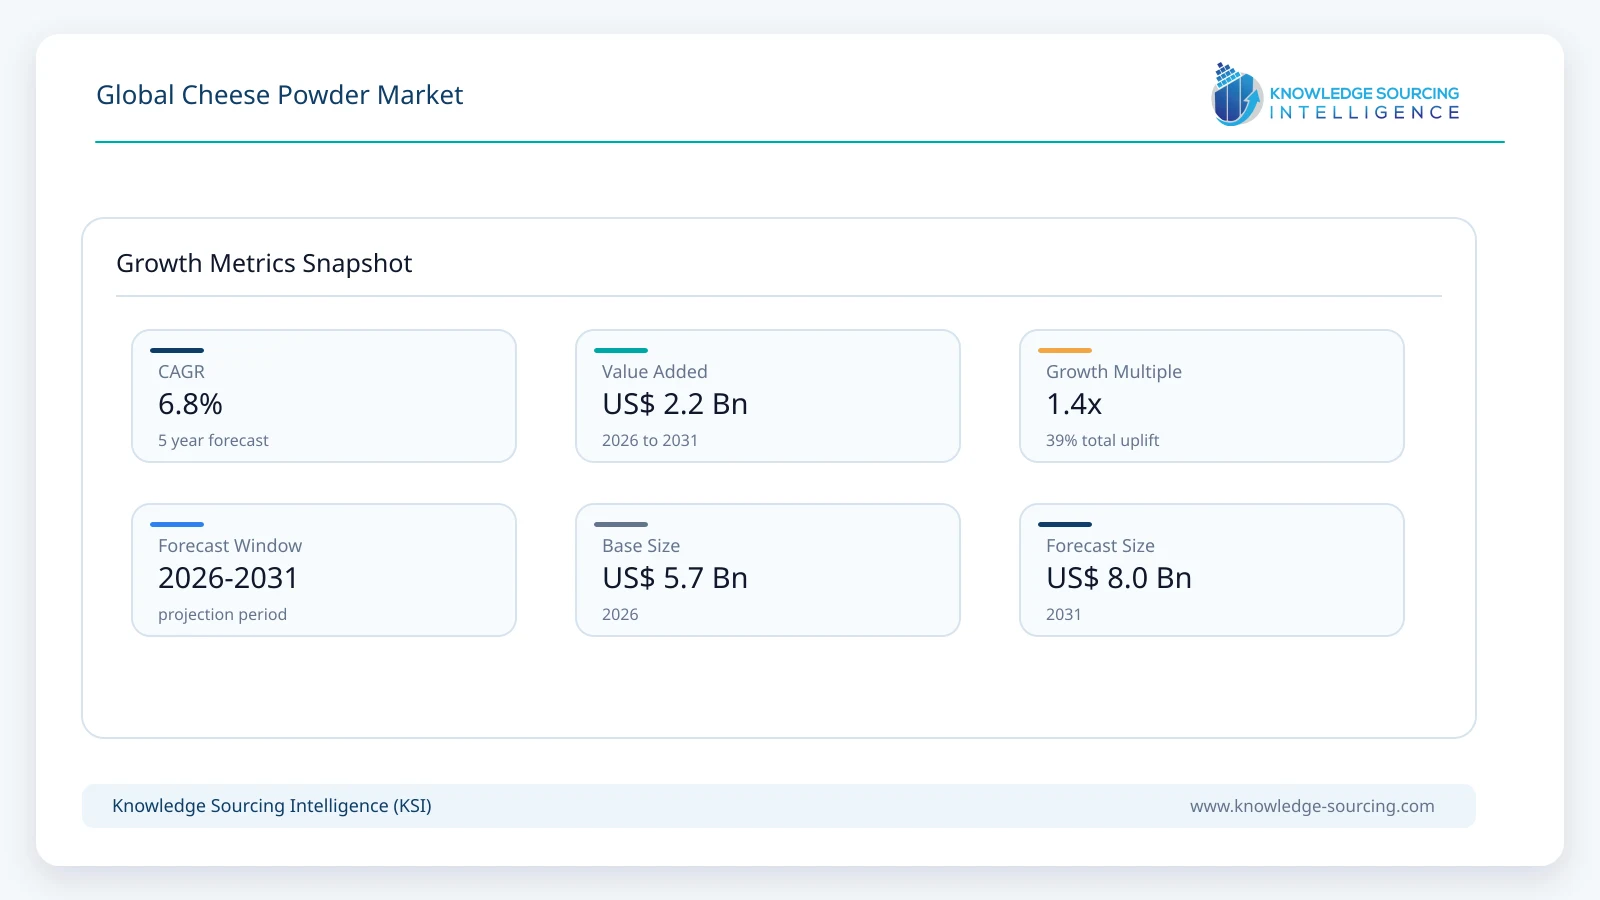
The global cheese powder market is estimated at USD 5.72 billion in 2026 and is forecast to reach USD 7.95 billion in 2031, representing an implied CAGR of 6.8% during the period.
Highlights:
- 1August 2026Lactosan published updated cheese-powder guidance emphasizing real-cheese content, clean-label potential and applications across snacks, seasonings, sauces, bakery, ready meals and hybrid or plant-forward concepts.
- 2June 2026:Lactosan highlighted 2026 ready-meal and seasoning concepts using cheese powder, including multi-sensory snack coatings and formulation approaches intended to improve flavor impact and process convenience.
- 3May 2026:Fonterra reported higher mozzarella production at its Clandeboye site in New Zealand to meet growing global demand, strengthening the broader cheese supply base that supports value-added cheese ingredients and foodservice products.
- 4March 2026Lactosan and the University of Copenhagen presented research showing that small doses of cheese powder can enhance umami and kokumi in plant-forward dips, dressings, pesto and sauces.
- 5February 2026Bluegrass Ingredients released an updated technical guide for product developers covering real-cheese powders, cheese-powder blends, processing, fat and protein functionality, and application-specific formulation.
- 62025-2026:Lactosan continued expansion of its Danish production and warehousing infrastructure, with new warehouse facilities scheduled for completion by the end of 2026 to support growing global cheese-powder demand.
Key Highlights
• Cheddar cheese powder accounts for approximately 40.0% of global 2026 revenue, equivalent to about USD 2.29 billion, supported by its broad use in snacks, sauces, pasta meals and seasoning systems.
• Snack, seasoning and savory coating applications represent approximately 36.0% of 2026 revenue, or about USD 2.06 billion, making them the largest application group.
• Sauces, soups, dips and dressings account for approximately 23.0% of 2026 revenue, supported by ambient-stable convenience foods and demand for consistent cheese flavor without refrigerated cheese handling.
• Europe accounts for approximately 32.0% of global 2026 revenue, equivalent to about USD 1.83 billion, reflecting its large cheese-processing base and concentration of specialist powder manufacturers.
• North America represents approximately 31.0% of 2026 revenue, or about USD 1.77 billion, supported by large snack, ready-meal and foodservice ingredient markets and substantial domestic cheese production.
• Clean-label products, high-cheese-content powders, provenance-led varieties and application-specific formulations are increasingly differentiating suppliers beyond commodity cheddar powder.
Market Overview
Cheese powder is a dehydrated cheese ingredient produced by converting natural or processed cheese into a pumpable cheese base and removing water, typically through spray drying. Depending on the specification, the finished product may contain a very high proportion of natural cheese or may be blended with dairy solids, emulsifying salts, carriers, colors, seasonings or other functional ingredients. The market covered in this report includes commercial cheese powders and cheese-powder blends in which cheese is the principal dairy-flavor component and the product is sold as an ingredient to food manufacturers, foodservice processors or bulk users. Retail grated cheese, fresh shredded cheese, ordinary milk and whey powders, and flavor systems with no meaningful cheese-powder content are excluded.
This scope differs from the older KSI page, which treated online and offline retail channels as a core market segmentation. The commercial market is primarily business-to-business: major suppliers sell bulk bags, super sacks or custom formulations for snacks, ready meals, sauces, bakery, processed cheese and foodservice applications. DFA Ingredient Solutions, Bluegrass Ingredients, Lactosan, All American Foods and Aarkay all position cheese powder as a formulation ingredient rather than primarily as a retail packaged food. Retail and wholesale products remain part of the addressable market where they represent bulk ingredient demand, but channel format is not an analytically useful primary segmentation.
The 2026 estimate is triangulated from cheese-production availability, international trade in the nearest customs category, supplier portfolios, application demand and observed commercial pricing. USDA reports 23.12 million metric tons of cheese production across its tracked global markets in 2025/26, up about 2% year over year. Separately, UN Comtrade data reported through the World Bank show multi-billion-dollar 2024 trade in HS 040620, which covers grated or powdered cheese. That customs code is not used as a direct market-size figure because it includes grated cheese and can include cross-border re-exports, but it provides a useful boundary check on the scale of internationally traded cheese in dry or grated form.
The market forecast is intentionally non-uniform rather than a simple CAGR fill. The modeled path is approximately USD 5.72 billion in 2026, USD 6.08 billion in 2027, USD 6.47 billion in 2028, USD 6.91 billion in 2029, USD 7.41 billion in 2030 and USD 7.95 billion in 2031. Growth strengthens modestly as foodservice and convenience-food volumes expand, global cheese availability rises, and suppliers capture greater value through application-specific powders, clean-label formulations and specialty cheese profiles. The path also allows for volatility in milk and cheese prices, which can materially influence nominal ingredient revenue from year to year.
Value creation comes from more than drying cheese. Suppliers compete on flavor intensity, cheese content, fat and protein contribution, color, solubility, heat stability, adhesion to snack surfaces, emulsification and label declaration. Lactosan markets cheese powders ranging from high-cheese-content products to clean-label powders without emulsifying salts, while Bluegrass differentiates between cheese powders and broader seasoning blends. This makes the market structurally diverse: two products both sold as cheddar cheese powder can differ significantly in cheese content, concentration, carrier system, cost-in-use and suitability for a particular manufacturing process.
Global Cheese Powder Market Trends
Clean-Label and Real-Cheese Declaration Become Stronger Purchase Criteria
Food manufacturers increasingly want a recognizable ingredient declaration alongside authentic dairy flavor. Lactosan offers clean-label cheese powders without emulsifying salts and states that selected products can be declared as dried cheese, while DFA and Bluegrass offer organic and other label-oriented options. This pushes suppliers to increase cheese content, simplify carrier systems and document provenance rather than competing only on flavor strength and price.
Application-Specific Powders Replace One-Size-Fits-All Formulations
Cheese powder is increasingly engineered around the end product. Snack coatings require adhesion, strong top-note impact and tolerance to surface oils; sauces and dips need emulsification and smooth dispersibility; bakery applications require flavor persistence through heat; and ready meals need stability across processing and storage. Supplier portfolios therefore increasingly separate cheddar, Parmesan, Romano, blue, mozzarella and cream-cheese profiles by fat level, color, intensity and process performance.
Cheese Powder Moves into Plant-Forward and Hybrid Foods
Cheese powder is being used as a small-dose taste amplifier in plant-forward foods rather than only in conventional dairy-heavy products. Research presented by Lactosan and the University of Copenhagen in March 2026 found that low inclusion rates could add umami and kokumi to dips, dressings, pesto and sauces. This creates a niche where dairy cheese powder improves palatability in hybrid formulations while allowing the bulk of the product to remain plant-based.
Premium Provenance and Specialty Cheese Profiles Gain Value
The market is moving beyond generic orange cheddar. Suppliers now offer Parmesan, Romano, blue, Gouda, Camembert, Swiss, Monterey Jack, Asiago, feta and other regionally recognizable profiles, including organic and provenance-led variants. Premium powders enable snack, sauce and ready-meal brands to make a more distinctive flavor proposition without handling short-shelf-life specialty cheese in every manufacturing location.
Sustainability Shifts Toward Upcycling and Efficient Dairy Utilization
Cheese powder can convert offcuts, downgraded cheese or surplus cheese streams into stable ingredients when food-safety and quality requirements are met. Kerry has previously documented lower greenhouse-gas emissions for upcycled cheese powder compared with standard powder, while current supplier messaging increasingly emphasizes resource efficiency, longer shelf life and reduced cold-chain burden. Sustainability is therefore becoming a sourcing and product-development criterion alongside cost and flavor.
Segment Analysis
By Type - Cheddar Cheese Powder
Cheddar cheese powder is estimated at approximately USD 2.29 billion in 2026, representing about 40.0% of global market revenue. Cheddar has the broadest commercial application set because its flavor can be tuned from mild and creamy to sharp and aged, and because both white and colored products are widely accepted in snacks, pasta meals, sauces, bakery and seasoning systems. All American Foods, Bluegrass Ingredients, DFA Ingredient Solutions, Lactosan and Aarkay all maintain cheddar-based products or blends, supporting the segment’s leadership across multiple regions.
Parmesan and Romano-style powders together are estimated at approximately USD 1.03 billion in 2026, or roughly 18.0% of the market, while mozzarella is estimated near USD 0.86 billion, or about 15.0%. Cream cheese, blue cheese, Gouda, Swiss, feta, Monterey Jack, Asiago and blended specialty profiles account for the balance. Specialty varieties grow faster than commodity cheddar because they allow manufacturers to create premium flavor identities at relatively low inclusion rates.
By Application - Snack Foods, Seasonings and Savory Coatings
Snack foods, seasonings and savory coatings are estimated at approximately USD 2.06 billion in 2026, representing about 36.0% of global cheese powder revenue. Cheese remains a major flavor platform across potato chips, extruded snacks, popcorn, crackers, nuts and savory seasonings. Powder format provides low moisture, controlled particle size and consistent dosing, and can be blended with salt, spices, acids and colors into complete seasoning systems. Lactosan’s 2026 application material identifies cheese as the leading flavor in corn-based snack launches in its cited 2025 dataset, illustrating the continuing importance of the flavor family.
Sauces, soups, dips and dressings are estimated at approximately USD 1.32 billion in 2026, or about 23.0%. This segment uses powder for ambient-stable dry mixes, shelf-stable sauces, foodservice bases and wet formulations where natural cheese handling is inconvenient. Ready meals and pasta applications represent approximately USD 0.97 billion, while bakery and prepared-food applications account for about USD 0.57 billion. Processed cheese and other specialty applications make up the remaining market.
By Formulation - High-Cheese-Content and Clean-Label Powders
High-cheese-content and clean-label products are estimated to represent approximately 44.0% of 2026 revenue, equivalent to about USD 2.52 billion. This category includes powders in which natural cheese is the dominant formulation and products designed for simple declarations such as dried cheese. The segment carries above-average value because raw cheese input is higher and the supplier must control flavor, fat, protein, emulsion stability and spray-drying performance without relying heavily on low-cost carriers.
Blended cheese powders and cost-optimized flavor systems account for the remainder and remain important in high-volume snacks, sauces and ready meals. Their commercial advantage is cost-in-use: a blend can deliver required cheese notes, color and process functionality at a lower dosage or lower unit cost. The balance between pure powder and blends varies substantially by application and geography, so formulation mix is more useful as a value-chain distinction than as a rigid regulatory classification.
By Geography - Europe
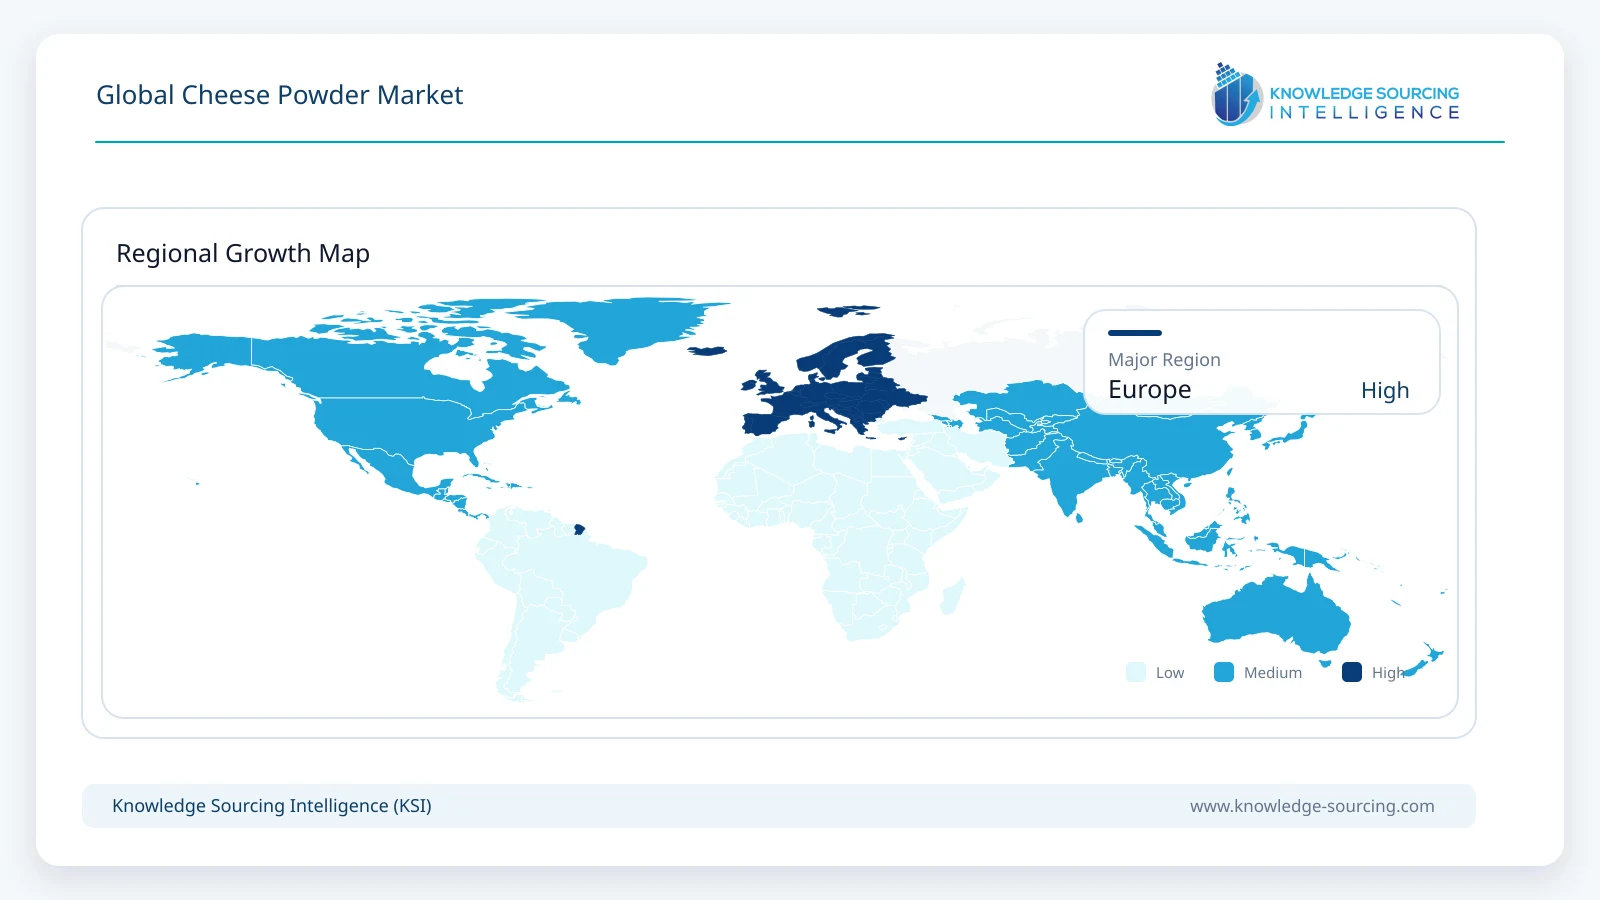
Europe is estimated at approximately USD 1.83 billion in 2026, representing about 32.0% of global revenue. The region combines a large natural-cheese production base, strong processed-food and foodservice industries, and specialist powder companies such as Lactosan, Grozette and Kanegrade. WITS data for HS 040620 also show Italy and the Netherlands among the largest exporters of grated or powdered cheese in 2024, reinforcing Europe’s importance in the underlying tradable cheese ecosystem.
North America is estimated at approximately USD 1.77 billion in 2026, or 31.0% of global revenue, supported by the United States’ large cheese-production base and extensive snack, seasoning, boxed-meal and foodservice industries. Asia Pacific represents approximately USD 1.54 billion, or 27.0%, and is the fastest-growing major region as Western-style snacks, quick-service restaurants, bakery and convenience foods expand. South America and the Middle East & Africa collectively account for the remaining 10.0%.
Market Drivers
Growth of Packaged Savory Snacks
Cheese powder delivers high-impact dairy flavor in a dry, stable format suited to chips, popcorn, extruded snacks, crackers and nuts. Continued innovation in globally inspired and premium cheese flavors increases the number of formulations that use powder rather than natural cheese.
Expansion of Convenience and Ready-Meal Formats
Boxed pasta, frozen and chilled meals, dry soup bases, sauces and shelf-stable meal kits require repeatable flavor and long ingredient shelf life. Cheese powder simplifies storage, dosing and process control compared with handling natural cheese at every manufacturing site.
Foodservice and Quick-Service Restaurant Growth
Restaurants and centralized foodservice kitchens use powdered or dry cheese systems in sauces, seasonings, coatings and prepared dishes because they reduce preparation steps and improve consistency across locations. Growth in global quick-service formats expands ingredient demand.
Demand for Clean Labels and Authentic Dairy Flavor
Manufacturers increasingly want real-cheese declaration rather than purely artificial cheese flavor. High-cheese-content and clean-label powders allow brands to retain shelf stability while simplifying ingredient lists and supporting premium positioning.
Product Development in Emerging Markets
Rising consumption of cheese-flavored snacks, bakery and convenience foods in Asia, the Middle East and Latin America expands demand for locally adapted cheese profiles. Powder format is particularly useful where refrigerated cheese distribution or local specialty-cheese availability is limited.
Market Restraints
Milk and Cheese Price Volatility
Natural cheese is the principal cost input for high-cheese-content powder. Changes in milk availability, cheese inventories, energy costs and regional dairy pricing can quickly affect powder cost and customer purchasing behavior.
High Energy Requirement of Spray Drying
Cheese bases must be heated, emulsified and dried while maintaining flavor and powder functionality. Energy-intensive drying raises production cost and creates a sustainability challenge, particularly for smaller plants or markets with high electricity and gas prices.
Competition from Natural Cheese, Flavors and Enzyme-Modified Ingredients
Food developers can obtain cheese character through grated cheese, concentrates, enzyme-modified cheese and natural or artificial flavors. Powder must therefore demonstrate a superior combination of shelf life, label declaration, process convenience and cost-in-use.
Dairy Allergen and Dietary Exclusion
Conventional cheese powder contains milk and is unsuitable for vegan consumers and people who must avoid milk allergens. Plant-based cheese flavors create a competing solution in selected snack and prepared-food applications.
Sodium, Fat and Label-Declaration Constraints
Depending on formulation, cheese powder can contribute sodium and saturated fat and may contain emulsifying salts, colors or carriers. Customers seeking aggressive nutrition claims or very short ingredient lists can require reformulation, lower dosage or cleaner-label alternatives.
Competitive Environment
The cheese powder market is fragmented between global taste-and-nutrition groups, dairy cooperatives, specialist cheese-powder manufacturers, ingredient blenders and contract spray-drying companies. Kerry competes through broad taste systems and global customer reach; Fonterra/NZMP brings upstream dairy scale; DFA Ingredient Solutions, Bluegrass Ingredients and All American Foods combine cheese powders with dairy-seasoning and formulation capabilities; and Lactosan specializes deeply in cheese-powder technology and high-cheese-content products.
Competition is shaped by application rather than only by cheese variety. Snack manufacturers value coating adhesion, color and cost per finished kilogram, while sauce and ready-meal customers focus on dispersibility, emulsification, heat stability and authentic flavor after processing. Suppliers with pilot plants, application laboratories and custom blending can therefore defend higher-value positions even when underlying cheese inputs are widely available.
Scale and sourcing remain important because cheese availability and price fluctuate. Companies with direct dairy access, multiple manufacturing sites or broad supplier networks can offer more reliable supply. At the same time, specialist regional companies remain competitive by offering custom batches, organic or clean-label variants, unusual cheese profiles and faster product-development support. The market is therefore unlikely to consolidate into a small number of commodity producers despite the importance of global dairy groups.
Recent Developments
Market Outlook
The cheese powder market is expected to maintain mid-single-digit to high-single-digit annual value growth through 2031. Volume growth will be supported by packaged snacks, sauces, convenience meals and foodservice, while value growth will receive an additional contribution from specialty profiles, cleaner labels and higher-cheese-content formulations.
Cheddar will remain the largest type, but Parmesan/Romano, mozzarella and specialty profiles should gain value share as manufacturers pursue premium and geographically distinctive flavors. Snack and seasoning use will remain the largest application, while sauces, dips, dressings and ready meals provide steady recurring demand and attractive opportunities for customized powders.
Europe and North America will remain the two largest regional markets, but Asia Pacific is expected to grow faster as cheese flavor becomes more deeply embedded in snacks, bakery, quick-service restaurants and convenience foods. Suppliers best positioned for growth will combine secure dairy sourcing with application laboratories, spray-drying expertise, clean-label capability and rapid customization rather than competing only on commodity powder price.
Global Cheese Powder Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 5.72 billion |
| Total Market Size in 2031 | USD 7.95 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 6.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Formulation, Application, Geography |
| Companies |
|
Market Segmentation
By Type
Cheddar
Parmesan and Romano
Mozzarella
Cream Cheese
Blue, Gouda, Swiss and Other Specialty Profiles
Blended Cheese Powders
By Formulation
High-Cheese-Content / Real-Cheese Powder
Clean-Label Cheese Powder
Cheese Powder Blends and Cost-Optimized Systems
By Application
Snacks, Seasonings and Savory Coatings
Sauces, Soups, Dips and Dressings
Ready Meals and Pasta
Bakery and Prepared Foods
Processed Cheese and Dairy Applications
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Netherlands
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Australia and New Zealand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Growth of Packaged Savory Snacks
4.1.2. Expansion of Convenience and Ready-Meal Formats
4.1.3. Foodservice and Quick-Service Restaurant Growth
4.1.4. Demand for Clean Labels and Authentic Dairy Flavor
4.1.5. Product Development in Emerging Markets
4.2. Market Restraints
4.2.1. Milk and Cheese Price Volatility
4.2.2. High Energy Requirement of Spray Drying
4.2.3. Competition from Natural Cheese, Flavors and Enzyme-Modified Ingredients
4.2.4. Dairy Allergen and Dietary Exclusion
4.2.5. Sodium, Fat and Label-Declaration Constraints
5. GLOBAL CHEESE POWDER MARKET BY TYPE
5.1. Cheddar
5.2. Parmesan and Romano
5.3. Mozzarella
5.4. Cream Cheese
5.5. Blue, Gouda, Swiss and Other Specialty Profiles
5.6. Blended Cheese Powders
6. GLOBAL CHEESE POWDER MARKET BY FORMULATION
6.1. High-Cheese-Content / Real-Cheese Powder
6.2. Clean-Label Cheese Powder
6.3. Cheese Powder Blends and Cost-Optimized Systems
7. GLOBAL CHEESE POWDER MARKET BY APPLICATION
7.1. Snacks, Seasonings and Savory Coatings
7.2. Sauces, Soups, Dips and Dressings
7.3. Ready Meals and Pasta
7.4. Bakery and Prepared Foods
7.5. Processed Cheese and Dairy Applications
7.6. Others
8. GLOBAL CHEESE POWDER MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. United Kingdom
8.3.3. France
8.3.4. Italy
8.3.5. Netherlands
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. South Africa
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. Japan
8.5.3. India
8.5.4. South Korea
8.5.5. Southeast Asia
8.5.6. Australia and New Zealand
8.5.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Real-Cheese and Blended Product Positioning
9.3. Clean-Label and Specialty Cheese Portfolios
9.4. Application Development and Customization
9.5. Recent Developments
9.6. Competitive Dashboard
10. COMPANY PROFILES
10.1. Kerry Group plc
10.2. Lactosan A/S
10.3. DFA Ingredient Solutions
10.4. Bluegrass Ingredients
10.5. Fonterra Co-operative Group Limited / NZMP
10.6. All American Foods, Inc.
10.7. Aarkay Food Products Ltd.
10.8. Ballantyne Foods Pty Ltd.
10.9. Grozette B.V.
10.10. CoreFX Ingredients LLC
10.11. Quality Ingredients Corporation
10.12. Kanegrade Ltd.
10.13. Hoosier Hill Farm LLC
10.14. Hoogwegt Group B.V.
10.15. Clofine Dairy & Food Products, Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Abbreviations
Navigate
Trusted by the world's leading organizations











